
 India Food Hydrocolloids Market | 2026-2036
India Food Hydrocolloids Market Size, Share, and Industry Trends Forecast 2026-2036
India Food Hydrocolloids Market Foresight
FSSAI's tightened food additive purity standards is restructuring the cost-of-entry calculus for domestic hydrocolloid suppliers. Cargill leverages its integrated supply chain to secure consistent guar gum sourcing from Rajasthan's processing belt. Ingredion sustains competitive positioning through specialized starch-hydrocolloid hybrid formulations tailored to Indian dairy applications. LUCID Colloids anchors regional distribution networks across Maharashtra and Karnataka, giving it channel control in high-volume bakery and confectionery segments.
Food hydrocolloids comprise high-molecular-weight polysaccharides and proteins that hydrate in aqueous systems to form viscous solutions or gels, with typical usage concentrations ranging from 0.1% to 2.0% by weight depending on desired rheology. These functional ingredients primarily serve to stabilize emulsions, control syneresis, and modify texture in processed foods. Xanthan gum dominates industrial procurement for beverages and sauces due to its pseudoplastic flow behavior and acid stability under Indian tropical storage conditions. Plant-based hydrocolloids from guar and tamarind seed sources represent the fastest-expanding source category, displacing animal-derived gelatin in vegetarian-majority formulations. Powder formulations occupy the largest share of commercial transactions, though liquid dispersions gain traction in automated dairy processing lines around Coimbatore and Pune.
BIS certification requirements for food-grade hydrocolloids and FSSAI's additive maximum-limit notifications shape product specifications and import documentation burdens. The country's national food regulator maintains stringent heavy-metal thresholds that filter out unqualified regional traders and elevate compliance costs for SME formulators. CDSCO oversight of hydrocolloid applications in nutraceutical delivery systems creates an adjacent compliance pathway for suppliers diversifying beyond conventional food uses. Stakeholders must monitor evolving PLI scheme eligibility for specialty food ingredient manufacturing as policy signals determine where capacity investments flow.
Market Dynamics
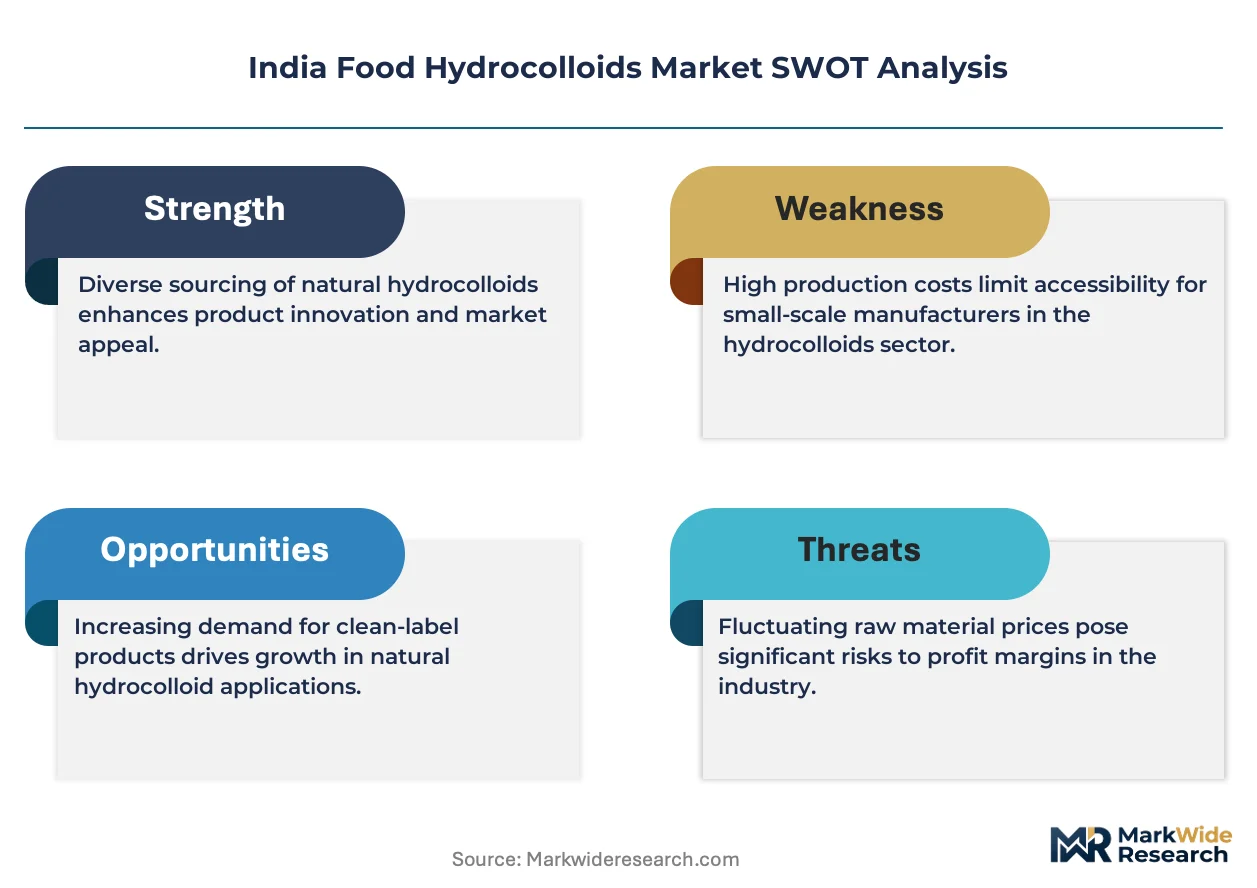
FSSAI's tightened additive purity standards are compressing the supplier base by elevating compliance costs, while simultaneously pulling procurement toward BIS-certified domestic processors capable of documenting heavy-metal thresholds and traceability.
Growth Catalysts
- Clean-label mandate:Vegetarian formulation requirements in processed dairy and bakery segments accelerate plant-based hydrocolloid substitution for animal-derived gelatin.
- PLI scheme tailwinds:Specialty food ingredient manufacturing incentives redirect capital toward guar gum and tamarind seed processing capacity in Rajasthan and Karnataka.
- Idli-dosa batter commercialization:South India's ready-to-cook breakfast segment drives concentrated agar and xanthan gum uptake in Tamil Nadu and Karnataka.
Market Restraints
- Guar seed price volatility:Monsoon-dependent Rajasthan harvests create input cost instability for domestic gum processors.
- Import documentation burdens:FSSAI additive maximum-limit notifications and BIS certification requirements filter out unqualified regional traders.
- Technical substitution ceiling:Starch-hydrocolloid hybrids face performance gaps in high-acid sauce applications under tropical storage conditions.
Strategic Opportunities
- Untapped Northeast penetration:Assam and Manipur processed food manufacturing remains underpenetrated for hydrocolloid distribution networks.
- Nutraceutical delivery convergence:CDSCO oversight of hydrocolloid applications in controlled-release formulations opens adjacent revenue streams beyond conventional food uses.
- Automated dairy integration:Liquid dispersion formats gain traction in Coimbatore and Pune processing lines requiring pumpable ingredient systems.
Industry Challenges
- Rheology expertise scarcity:Formulation chemists capable of optimizing pseudoplastic flow behavior in high-shear dairy applications command premium compensation.
- Dual certification timelines:BIS food-grade approval and FSSAI additive registration create sequential bottlenecks for new product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Food Hydrocolloids Market |
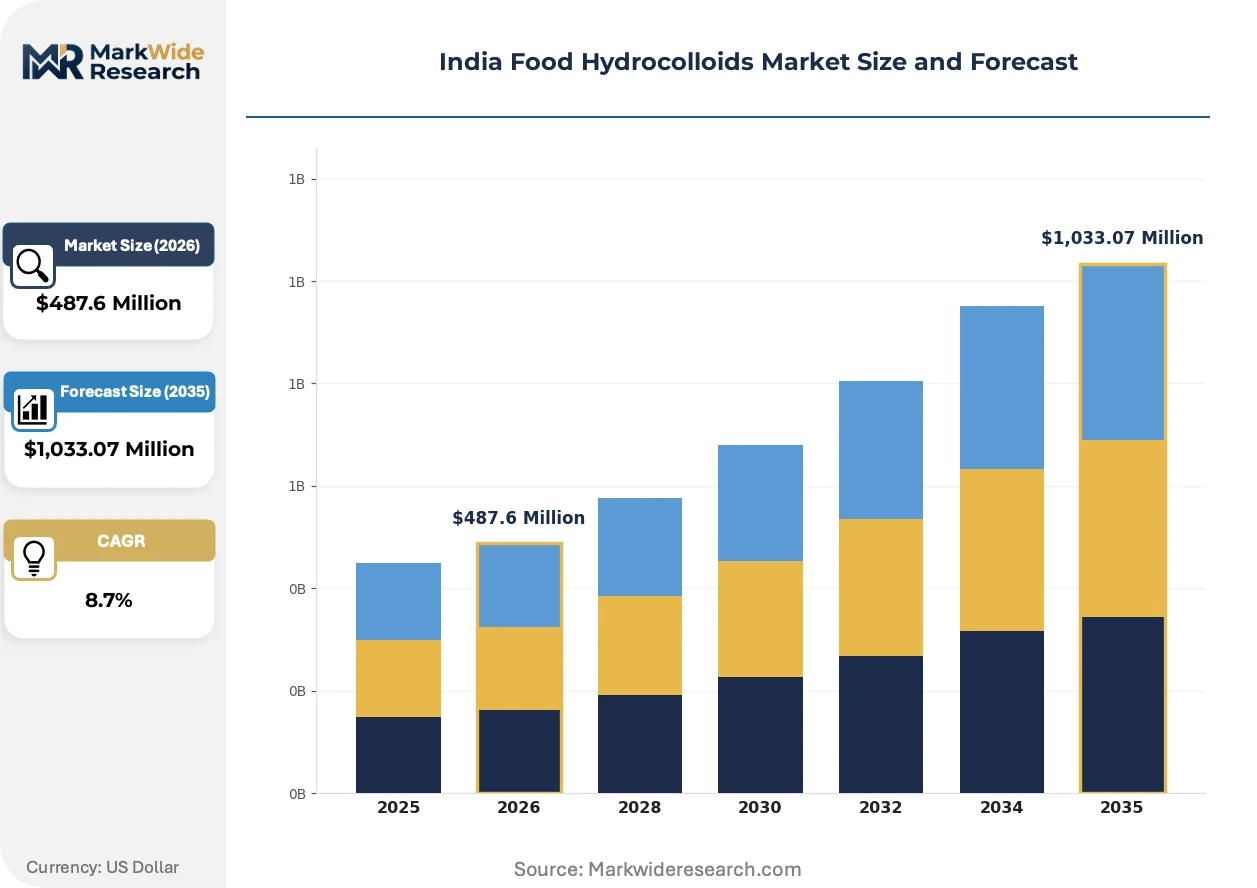
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Pectin, Agar, Xanthan Gum Application: Dairy Products, Bakery, Beverages, Sauces Source: Plant-based, Animal-based, Microbial, Synthetic Form: Powder, Liquid, Granules, Sheets |
| Companies Covered | Koninklijke DSM, Ingredion, Cargill, LUCID Colloids, Tate & Lyle, CP Kelco, Hawkins Watts, Ashland, DuPont, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Food Hydrocolloids Market Shifts & Advancements
Clean-label ingredient substitution and processing automation are compressing traditional supply relationships while opening formulation white space for plant-derived stabilizers with documented traceability.
Enzyme-modified tamarind seed polysaccharide is rewriting viscosity-building economics in cost-sensitive sauce applications. Mid-tier condiment manufacturers in Maharashtra and Gujarat are adopting this modified gum at accelerating rates. The technology is rewriting procurement benchmarks by delivering acid-stable thickening at 40% lower inclusion rates versus conventional alternatives.
FSSAI's 2023 heavy-metal threshold notifications for food-grade gums are restructuring import documentation and domestic testing protocols. Industrial buyers now demand batch-level certificates of analysis from Rajasthan and Gujarat processing facilities. Powder-grade guar suppliers face the steepest compliance recalibration as lead and arsenic limits tighten.
Direct-procurement relationships between dairy cooperatives and hydrocolloid processors are displacing layered distributor networks in Karnataka and Tamil Nadu. Bulk buyers in the Mysuru and Erode clusters now negotiate annual contracts with BIS-certified gum processors. This channel compression concentrates volume with processors maintaining in-house application laboratories and technical service capabilities.
India Food Hydrocolloids Market Segmentation
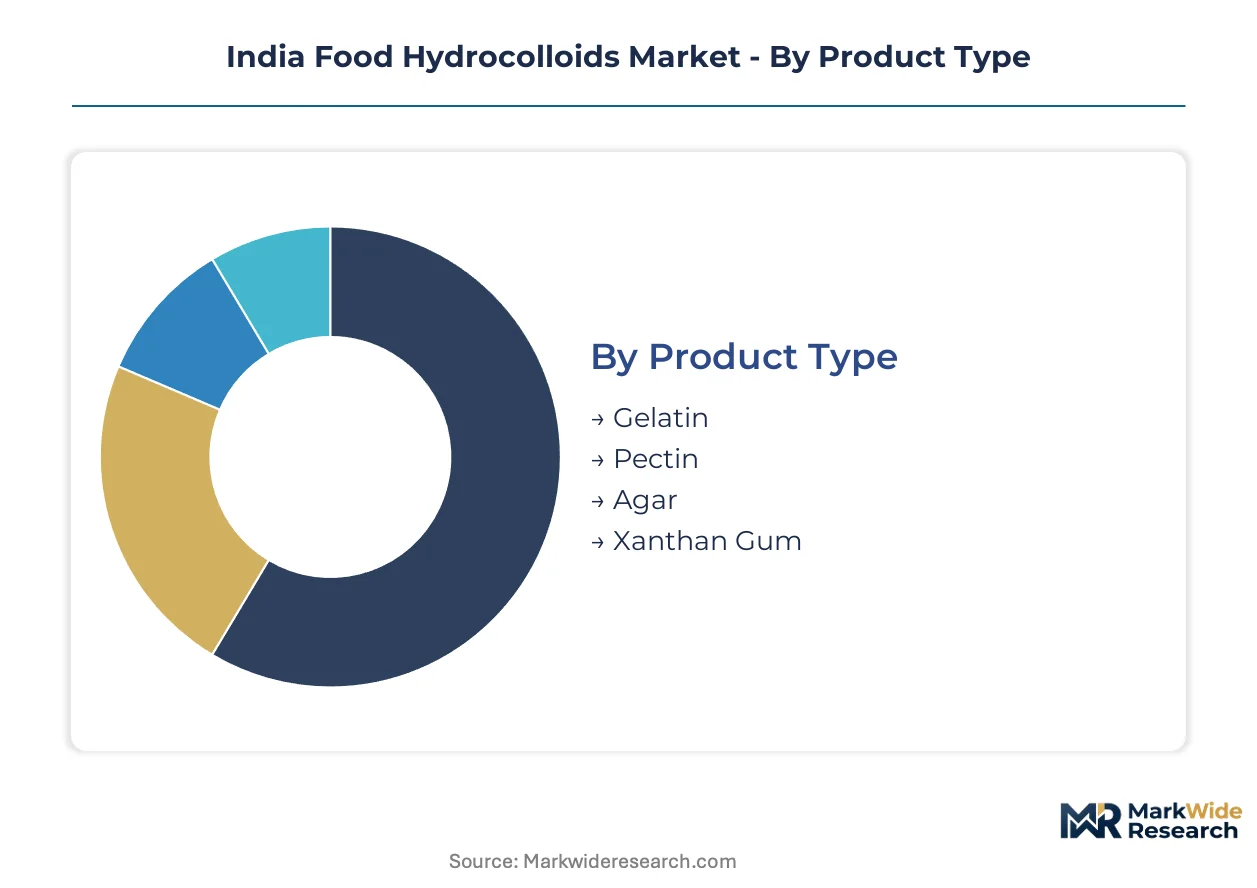
Hydrocolloid procurement patterns in India diverge sharply across formulation requirements, with dairy processors prioritizing acid-stable microbial gums while South Indian batter manufacturers demand plant-derived gelling agents with clean-label credentials. Segment boundaries are hardening as FSSAI purity standards and vegetarian formulation mandates reshape supplier qualification criteria.
Product Type:
Buyers in this category separate by thermal stability needs and religious dietary compliance, with Hindu-majority food processors avoiding animal-derived options regardless of functional performance.
- Xanthan Gum:Extracellular polysaccharide produced by Xanthomonas campestris fermentation delivers pseudoplastic viscosity that recovers after high-shear pumping. Maharashtra and Gujarat dairy processors specify this grade for ambient-stable yogurt drinks facing tropical distribution stress.
- Agar:Seaweed-extracted galactose polymer forms thermoreversible gels with sharp melting profiles distinct from animal gelatin. Tamil Nadu and Karnataka idli-dosa batter commercializers source agar for vegetarian gelling applications where FSSAI-mandated documentation proves plant origin.
- Pectin:Citrus and apple peel-derived polyuronide requiring precise calcium concentration for gelation, constraining formulation flexibility in mineral-variable water sources.
- Gelatin:Collagen hydrolysate from bovine and porcine sources faces shrinking food-grade demand as vegetarian labels dominate premium positioning, though confectionery applications in non-vegetarian product lines sustain residual volumes.
Xanthan gum leads volumes today; agar is gaining share fastest.
Application:
Volume concentration tracks regional food manufacturing clusters, with procurement scale determined by automation level and export orientation rather than domestic consumption alone.
- Dairy Products:Paneer and yogurt stabilization demands hydrocolloids controlling syneresis under refrigerated and ambient storage cycles. Rajasthan and Punjab dairy cooperatives specify guar gum and xanthan blends for processed cheese spreads facing FSSAI texture benchmarks.
- Beverages:Pulp suspension and mouthfeel modification in mango and guava drinks requires pseudoplastic thickeners stable at pH 3.5-4.2. Pune and Coimbatore bottling lines favor liquid dispersion formats compatible with automated dosing systems.
- Bakery:Shelf-life extension and crumb moisture retention in industrial bread production, with Maharashtra facilities specifying hydrocolloid-starch hybrids for cost-sensitive applications.
- Sauces:Tomato and chili ketchup viscosity building confronts acid stability requirements and clean-label pressure, driving tamarind seed polysaccharide substitution in Gujarat and Maharashtra condiment manufacturing.
Dairy applications command the largest procurement tonnage; beverages show the steepest expansion trajectory.
Source:
Raw material origin determines certification pathway complexity and price volatility exposure, with monsoon-dependent agricultural supplies contrasting against controlled fermentation outputs.
- Plant-based:Guar seed from Rajasthan and tamarind kernel from Karnataka supply chains dominate cost-sensitive thickening applications. BIS certification for food-grade guar gum tightened following FSSAI heavy-metal threshold revisions, elevating documentation burdens for unprocessed seed exporters.
- Microbial:Xanthan and gellan gum fermentation delivers batch-to-batch consistency independent of agricultural harvest cycles. Strain optimization and downstream processing investments concentrate with integrated suppliers capable of CDSCO-compliant documentation for nutraceutical crossover applications.
- Animal-based:Gelatin sourcing confronts religious dietary restrictions and import documentation for bovine-derived materials, compressing addressable market scope despite superior melt characteristics.
- Synthetic:Cellulose derivatives including CMC and methylcellulose serve niche applications requiring precise viscosity control, with pharmaceutical-grade specifications spilling into premium food segments.
Plant-based sources supply the majority of tonnage; microbial fermentation is climbing the fastest.
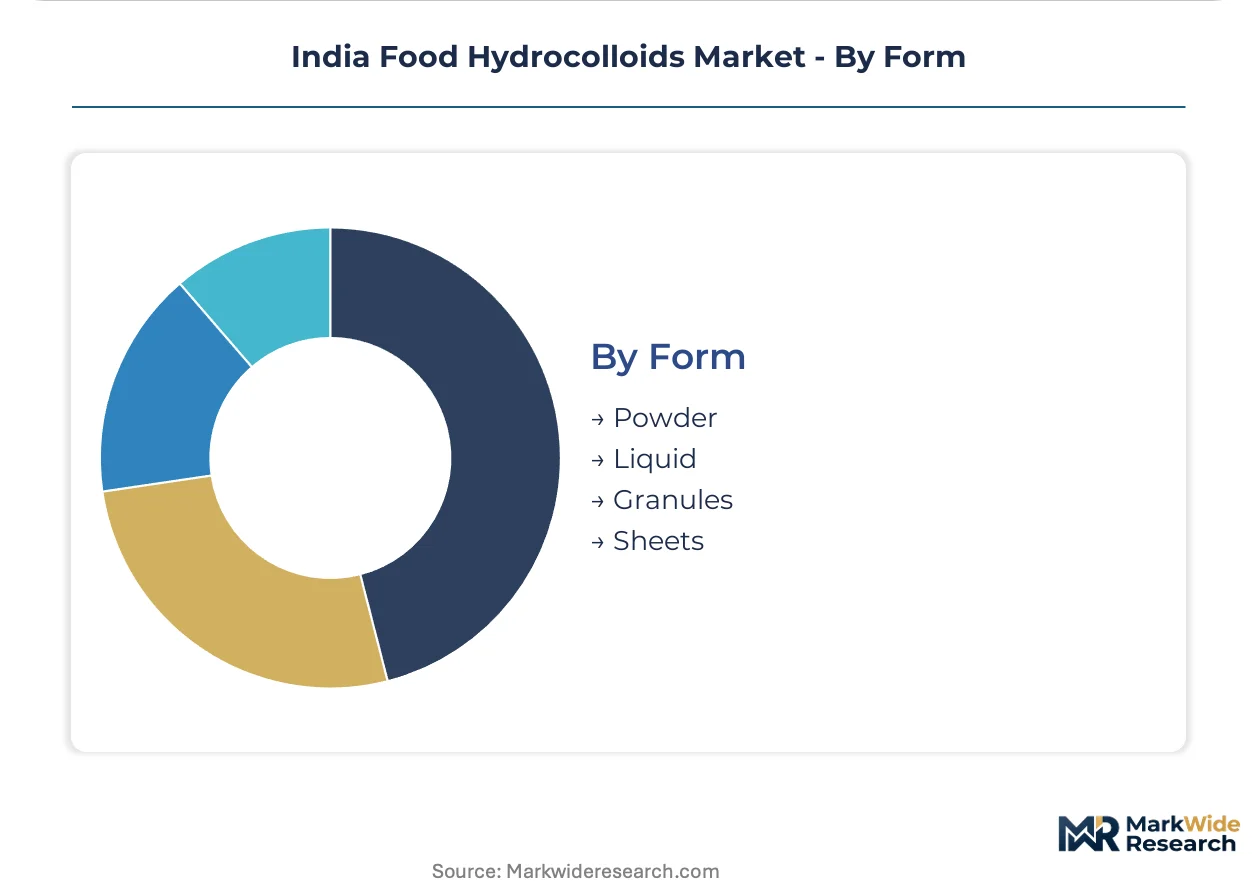
Form:
Physical presentation dictates handling infrastructure requirements and dissolution efficiency, with powder dominance eroding only where automated processing lines justify liquid system investments.
- Powder:Spray-dried and milled grades dominate commercial transactions, offering extended shelf stability and flexible dosing across formulation scales. Rajasthan guar gum processors supply bulk powder to pan-India distributor networks serving SME formulators lacking liquid handling equipment.
- Liquid:Pre-hydrated dispersions eliminate dust exposure and dissolution time, penetrating Coimbatore and Pune dairy automation lines where pumpable ingredient systems reduce batch cycle variability.
- Granules:Intermediate particle size reducing dust generation versus fine powder while maintaining rapid hydration, finding preference in mid-scale bakery operations.
- Sheets:Agar in dried strip format serves traditional confectionery and laboratory applications, with limited penetration in industrial food processing due to weighing and dissolution inefficiency.
Powder formulations retain volume leadership; liquid dispersions are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial hydrocolloid manufacturing in India traces its modern lineage to the 1960s establishment of guar gum processing cooperatives in Rajasthan's arid belt, which subsequently scaled through export-oriented infrastructure investments during the 1990s economic liberalization era.
Gujarat
Dairy processors in Ahmedabad and Vadodara drive concentrated demand for xanthan gum and guar blends to stabilize paneer and yogurt textures under FSSAI-mandated quality benchmarks. The state's food safety administration enforces batch-level heavy-metal documentation that filters out unqualified regional traders. Anand's dairy cooperative cluster negotiates direct annual contracts with BIS-certified gum processors, displacing traditional distributor networks.
Maharashtra
Mid-tier condiment manufacturers in Mumbai and Pune adopt enzyme-modified tamarind seed polysaccharide for acid-stable sauce thickening at reduced inclusion rates. CDSCO oversight of hydrocolloid applications in nutraceutical delivery systems creates adjacent compliance pathways for Mumbai-based suppliers diversifying beyond conventional food uses. Nashik's beverage bottling lines favor liquid dispersion formats compatible with automated dosing infrastructure.
Karnataka
Idli and dosa batter commercialization across Bengaluru and Mysuru drives concentrated agar uptake for vegetarian gelling applications requiring FSSAI-mandated plant-origin documentation. The state's PLI scheme eligibility for specialty food ingredient manufacturing redirects capital toward tamarind seed processing capacity expansion. Coimbatore's dairy automation lines accelerate adoption of pumpable liquid hydrocolloid systems.
Tamil Nadu
Ready-to-cook breakfast segment scale-up in Chennai and Erode clusters sustains bulk procurement of agar and xanthan gum from BIS-certified processors. FSSAI's 2023 heavy-metal threshold notifications restructure import documentation and domestic testing protocols for seaweed-extracted galactose polymers. Bulk buyers in the Erode cluster now demand in-house application laboratory capabilities from contracted suppliers.
Rajasthan
Monsoon-dependent guar seed harvests in Jodhpur and Bikaner processing belts create input cost volatility that compresses margins for domestic gum processors. BIS certification requirements for food-grade guar gum tightened following FSSAI heavy-metal threshold revisions, elevating documentation burdens for unprocessed seed exporters. Rajasthan's integrated supply chain anchors secure captive sourcing relationships with pan-India dairy cooperatives.
India Food Hydrocolloids Market Competitive Landscape
The competitive structure tilts toward integrated multinational suppliers with captive raw material sourcing and regional specialists controlling distribution networks in high-volume segments. Three archetypes dominate: fermentation-based microbial gum producers with strain optimization capabilities, plant-derived hydrocolloid processors with backward integration into agricultural supply chains, and hybrid formulation specialists blending starch-hydrocolloid systems for cost-sensitive applications. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with players securing BIS certification and FSSAI additive registration to compress commercialization timelines.
Among multinational ingredient suppliers, Koninklijke DSM and Cargill exemplify the integrated archetype with upstream control over fermentation and agricultural sourcing infrastructure. Tate & Lyle occupies a position within the hybrid formulation tier, while LUCID Colloids anchors the regional specialist category through channel control in Maharashtra and Karnataka bakery and confectionery segments. These named entities represent strategic positioning patterns rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Koninklijke DSM |
| Ingredion |
| Cargill |
| LUCID Colloids |
| Tate & Lyle |
| CP Kelco |
| Hawkins Watts |
| Ashland |
| DuPont |
| Others |
Supply & Pricing Matrix
BIS-certified guar gum processors command a 15-20% premium over unqualified Rajasthan traders, and this certification ladder simultaneously concentrates procurement with documented heavy-metal compliance and fragments spot-market liquidity for cost-sensitive SME formulators. The divergence manifests in annual contract negotiations where Anand dairy cooperatives lock in volume commitments with technical service guarantees, while Maharashtra condiment manufacturers chase enzyme-modified tamarind seed polysaccharide on shorter procurement cycles.
Pricing Analysis
Bundled technical service contracts dominate premium tier transactions, where BIS-certified processors include in-house application laboratory support and batch-level certificates of analysis. Price differentiation rests on heavy-metal documentation grade and FSSAI additive registration status, with unqualified regional traders facing compression from tightened purity standards. Pricing pressure intensifies in commodity guar gum as monsoon-dependent Rajasthan harvests amplify input cost volatility. SME dairy processors in Gujarat exhibit highest price sensitivity, while export-oriented beverage bottlers in Pune prioritize acid-stable performance over per-kilogram rates.
Supply Chain Analysis
Dual-sourcing mandates from FSSAI-registered dairy cooperatives force qualification of at least two BIS-certified processors per hydrocolloid category, compressing single-source relationships despite Rajasthan's guar gum concentration. Geographic supply anchors in India, with microbial fermentation capacity concentrated in Maharashtra and Karnataka tamarind seed processing scaling under PLI incentives. Raw material dependencies include monsoon-sensitive guar seed, seaweed-derived agar from Tamil Nadu coastlines, and fermentation feedstocks for xanthan gum. Supply chain risk centers on single-source vulnerability for acid-stable thickeners in high-shear dairy applications. Distribution runs through direct-procurement annual contracts displacing layered distributor networks in Mysuru and Erode clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India food hydrocolloids market reads as a late-cycle quality story where FSSAI's tightened heavy-metal thresholds are redirecting procurement toward documented traceability and away from cost-optimized spot buying. This specification shift elevates processors with captive laboratory capabilities and compresses margins for undifferentiated commodity suppliers.
For Market Incumbents: Lock in captive guar seed sourcing through backward integration into Rajasthan processing cooperatives before PLI scheme eligibility windows narrow. Defend channel position by embedding technical service teams directly into Anand and Erode dairy clusters, as emerging enzyme-modified gum specialists threaten displacement in cost-sensitive sauce applications. Prioritize dual BIS-FSSAI certification maintenance to compress new entrant commercialization timelines.
For New Entrants and Emerging Players: Direct-to-batter-manufacturer digital platforms offer the most penetrable route into Tamil Nadu and Karnataka ready-to-cook breakfast segments underserved by incumbent distributor networks. Target Assam and Manipur processed food manufacturing with liquid dispersion formats compatible with emerging automation infrastructure. Lead with documented vegetarian-origin credentials and FSSAI-mandated plant-source traceability to capture clean-label substitution demand.
For Investors and Strategic Acquirers: Consolidation pressure builds where BIS certification timelines exceed 18 months and FSSAI additive registration creates sequential bottlenecks for new product commercialization. Mid-cap processors with established Rajasthan agricultural relationships and in-house application laboratories represent priority acquisition archetypes over pure fermentation plays. Monitor CDSCO nutraceutical delivery pathway approvals as the inflection signal for revenue diversification beyond conventional food uses.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Guar Seed Processing | Captive Rajasthan supply secures margin stability against monsoon-driven input volatility. |
| In-House Application Laboratory Buildout | Technical service capabilities lock in annual contracts with FSSAI-registered dairy cooperatives. |
| Dual BIS-FSSAI Certification Investment | Accelerated registration timelines compress commercialization windows for competing entrants. |
| Liquid Dispersion Format Expansion | Pumpable systems penetrate Coimbatore and Pune automated dairy processing lines. |
| Nutraceutical Delivery Pathway Diversification | CDSCO-compliant documentation opens adjacent revenue streams beyond food-grade applications. |
Research Methodology
Multiple input streams — primary interviews with hydrocolloid procurement managers at dairy cooperatives, technical directors at BIS-certified processing facilities, and regulatory affairs leads navigating FSSAI additive registration — were reconciled against secondary validation from FSSAI notification databases, BIS certification registries, and PLI scheme eligibility disclosures. Customs records tracking guar seed and tamarind kernel import-export flows, alongside SEC filings from listed multinational ingredient suppliers, provided volume anchor points. Bottom-up segmentation modeling across product type, application, source, and form dimensions was cross-checked against top-down market sizing from identified manufacturer capacity declarations.
Data-stream reconciliation enabled construction of an analytical framework projecting value and volume trajectories across the analysis window. Segmentation dimensions modeled include hydrocolloid source category, end-use application intensity, certification grade tier, and regional manufacturing cluster concentration. CAGRs were derived from fitted growth curves calibrated to historical procurement patterns and forward-looking capacity investment announcements. Industry-specific forecast inputs incorporated monsoon-indexed guar seed yield projections and PLI scheme capital flow tracking.
Monsoon failure severity, FSSAI regulatory timeline delays, and CDSCO nutraceutical pathway approval bottlenecks are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding certification compliance rates and cooperative procurement contract renewal velocities. Deviation in Rajasthan agricultural output would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Asia-Pacific Food Anti Caking Agents Market
Food Components and Additives
Polydextrose Market
Food Components and Additives
Food Can Coatings Market
Food Components and Additives
Soybean by-Products Market
Food Components and Additives
United Kingdom Food Hydrocolloids Market
Food Components and Additives
Food Grade Calcium Carbonate Market
Food Components and Additives
Horseradish Peroxidase Market
Food Components and Additives
Polyphenols Market
Food Components and Additives
Europe Food Stabilizers Market
Food Components and Additives
Global Zeaxanthin Market
Food Components and Additives
Europe and MEA Food Phosphate Market
Food Components and Additives
South America Food Hydrocolloids Market
Food Components and Additives
Edible Oil Co-Products and by-Products Market
Food Components and Additives
Polyphenol Antioxidant Market
Food Components and Additives
Europe Food Anti Caking Agents Market
Food Components and Additives
Food Grade Activated Carbon Market