
 South America Food Acidulants Market | 2026-2036
South America Food Acidulants Market Size, Share, and Industry Trends Forecast 2026-2036
South America Food Acidulants Market Analytics
Market Context
The direct-to-manufacturer supply channel is narrowing as multinational acidulant suppliers consolidate distributor relationships across the Andean and Southern Cone regions. Cargill Incorporated leverages its Brazilian crushing and fermentation infrastructure to anchor citric acid supply contracts with major beverage bottlers. Jungbunzlauer Suisse AG competes through specialized lactic acid grades tailored to clean-label dairy applications in Argentina and Uruguay.
Technical Definition and Segments
Food acidulants comprise organic acids and their salts added to food matrices to regulate pH, enhance microbial stability, modify flavor profiles, and control gelation or protein functionality in processed foods. Citric acid dominates volume flows due to its GRAS status, compatibility across pH ranges, and established fermentation manufacturing base using Aspergillus niger on sucrose or dextrose substrates. Lactic acid captures expanding share in dairy and plant-based beverage applications where milder acidity and preservative synergy matter. Malic acid occupies premium positioning within confectionery and sports drink formulations where prolonged sourness release differentiates sensory profiles.
Regulatory Framework
ANVISA governs acidulant purity specifications and maximum usage levels under Brazilian food additive regulations, while Argentina's national food safety authority enforces Mercosur-aligned CODEX standards for acidulant labeling and identity. Compliance with these frameworks determines market access, as non-conforming shipments face port detention and reformulation costs that erode contract viability. Stakeholders must monitor pending harmonization between Chile's updated food code and Mercosur technical regulations, as divergence would fragment procurement and testing protocols across the region's largest economies.
Market Dynamics
ANVISA's updated additive purity standards are compressing supplier margins while simultaneously locking in market share for acidulant producers with captive Brazilian fermentation infrastructure. This regulatory tightening coincides with tax incentive programs that favor domestic manufacturing, creating a bifurcated competitive landscape where local production assets determine contract viability.
Growth Catalysts
- PLI-style tax incentives:Brazil's processed food ingredient manufacturing subsidies are accelerating acidulant capacity expansion in São Paulo and Minas Gerais industrial corridors.
- Functional beverage proliferation:Carbonated and fortified drink portfolios across Brazil, Argentina, and Colombia are expanding acidulant procurement volumes for pH stabilization and flavor modulation.
- Clean-label dairy demand:Consumer preference for recognizable ingredients is elevating lactic acid grades in Argentine and Uruguayan yogurt and fresh cheese applications.
Market Restraints
- Sucrose input volatility:Citric acid fermentation economics remain exposed to Brazilian sugarcane harvest fluctuations and ethanol market competition for feedstock allocation.
- Supplier concentration risk:Multinational acidulant suppliers dominate distributor relationships across Andean and Southern Cone regions, limiting pricing leverage for mid-tier processors.
- Port detention exposure:Non-conforming acidulant shipments face Brazilian customs holds under ANVISA enforcement protocols, eroding just-in-time supply reliability.
Strategic Opportunities
- Colombian beverage processing:Bogotá and Medellín industrial zones show underpenetrated acidulant sourcing relative to installed bottling capacity.
- Chile-Mercosur harmonization:Pending regulatory alignment between Chile's updated food code and Mercosur technical standards could streamline cross-border procurement protocols.
- Direct-to-manufacturer channels:Bypassing consolidated distributor networks offers margin recovery for acidulant producers with established Brazilian logistics infrastructure.
Industry Challenges
- Reformulation timeline compression:ANVISA compliance deadlines force accelerated product redevelopment cycles that strain R&D bandwidth at regional dairy and beverage processors.
- Testing protocol fragmentation:Divergent purity verification requirements between Brazilian, Argentine, and Chilean laboratories multiply certification costs for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Food Acidulants Market |
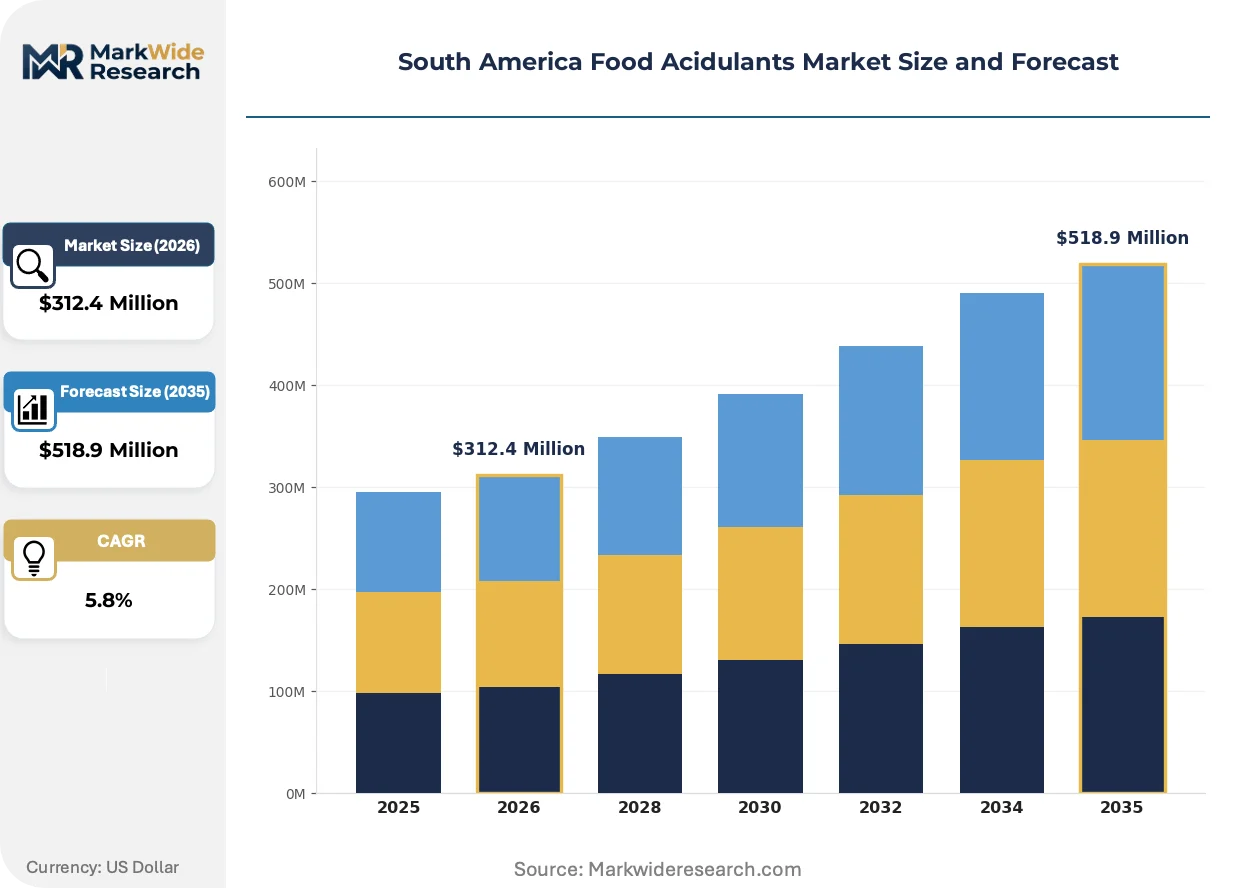
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Acetic Acid, Lactic Acid, Malic Acid Application: Dairy Products, Beverages, Bakery, Confectionery End User: Food Manufacturers, Beverage Producers, Retailers, Food Service Packaging Type: Bottles, Bags, Drums, Bulk Containers |
| Companies Covered | Tate & Lyle, ICL, Cargill Incorporated, Jungbunzlauer Suisse AG, Innova Corporate, Archer Daniels Midland Company, SUCROAL, Brenntag SE, Corbion NV, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Food Acidulants Market Evolving Landscape
Fermentation-based acidulant production is converging with precision biotechnology to reshape cost structures and functional performance specifications across South American supply chains.
Bioprocess engineering is hybridizing traditional Aspergillus niger citric acid fermentation with enzymatic conversion pathways. Argentine dairy processors are piloting these hybrid systems to reduce sucrose feedstock intensity by 15-20%. The technology is compressing capital requirements for mid-scale acidulant production while enabling customized acidulant salt formulations previously requiring separate synthesis steps.
Mercosur-aligned CODEX standard revisions are tightening maximum usage level definitions for malic acid in confectionery applications. Argentine and Brazilian regulators are coordinating enforcement protocols that will require reformulated sour candy portfolios by 2026. Sports drink manufacturers in São Paulo industrial parks are accelerating sensory testing to identify alternative acidulant blends that maintain prolonged sourness release within revised limits.
Consolidated beverage bottlers are compressing supplier rosters to single-source acidulant contracts with integrated technical service support. Direct procurement agreements are displacing traditional distributor intermediaries in Brazil's Southeast corridor. This concentration is most visible among multinational soft drink producers operating captive blending facilities in Guarulhos and Contagem industrial zones.
South America Food Acidulants Market Segmentation
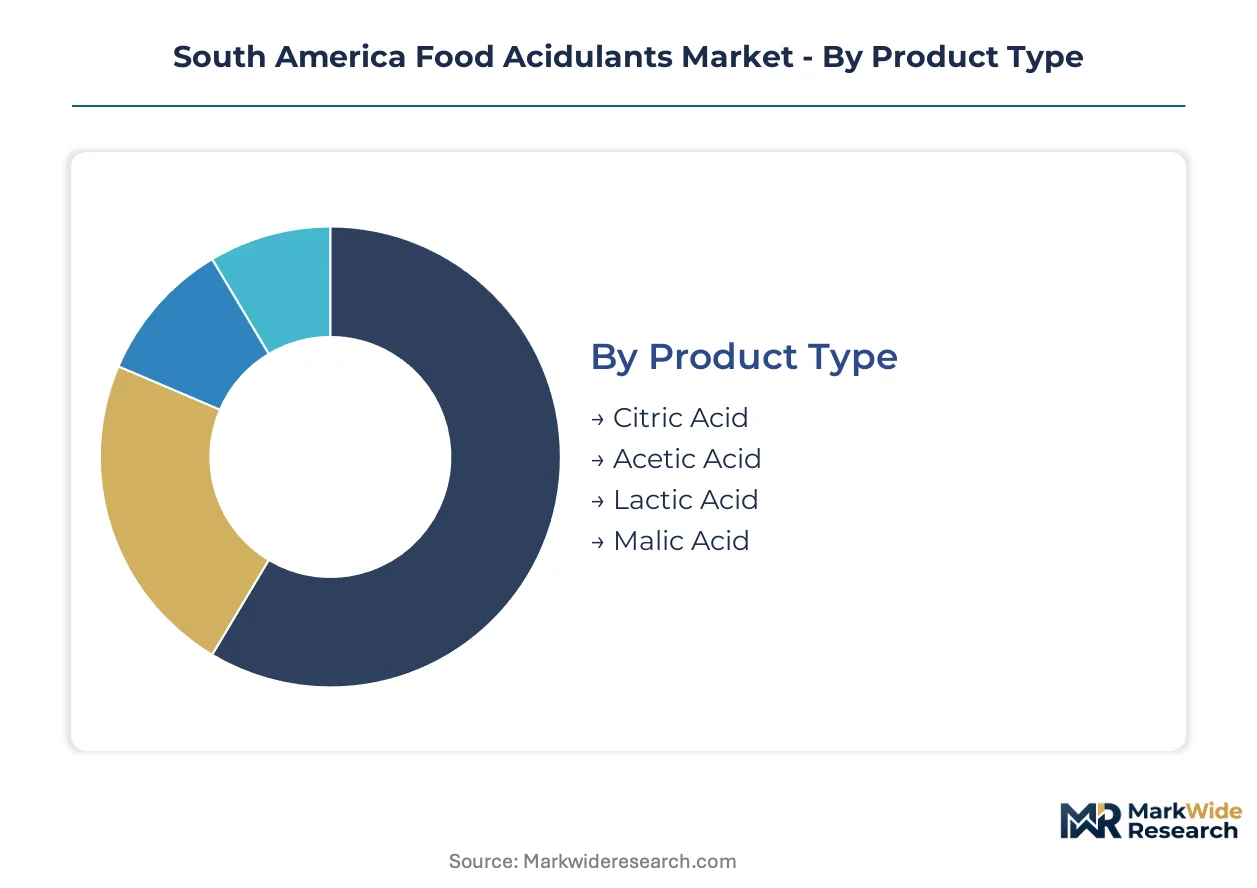
Acidulant procurement patterns across South America diverge sharply by product chemistry, end-use application, and customer scale. Understanding these fault lines reveals where margin pools concentrate and which supply configurations command pricing leverage in Brazil's industrial corridor versus Andean markets.
Product Type:
Cost tier stratification in acidulant chemistry determines feedstock exposure and fermentation economics across Brazilian supplier networks.
- Citric Acid:Fermentation-derived from Aspergillus niger on sucrose substrates, this acidulant delivers broad pH compatibility and GRAS regulatory acceptance. Demand concentrates in São Paulo beverage bottling clusters where carbonated drink volumes require consistent acidification at scale. Sucrose price volatility from Brazilian sugarcane harvests compresses margins during ethanol feedstock competition.
- Lactic Acid:Milder acidity profiles suit clean-label dairy applications in Argentine yogurt and fresh cheese production. Uruguayan processors are expanding procurement of specialized grades that preserve protein functionality while meeting Mercosur labeling requirements for recognizable ingredients.
- Acetic Acid:Synthetic and fermentation routes supply vinegar-based preservation in Brazilian condiment manufacturing. Minas Gerais sauce producers represent the primary demand concentration.
- Malic Acid:Prolonged sourness release differentiates confectionery and sports drink formulations in premium positioning. Argentine sour candy reformulation under pending CODEX limits is compressing allowable usage levels.
Citric acid holds installed capacity. Lactic acid is rotating up the share rankings.
Application:
Application focus determines acidulant specification requirements and technical service intensity in customer relationships.
- Beverages:Carbonated and functional drink portfolios across Brazil, Argentina, and Colombia require precise pH stabilization for microbial safety and flavor modulation. Guarulhos and Contagem industrial zones host captive blending facilities that source acidulants through direct manufacturer contracts rather than distributor channels.
- Dairy Products:Yogurt, cheese, and fermented milk applications in Argentina and Uruguay demand lactic acid grades with specific optical purity and preservative synergy. Clean-label positioning elevates fermentation-derived over synthetic sources.
- Confectionery:Sour candy and gummy formulations utilize malic acid for extended flavor release. ANVISA and Argentine regulator coordination on maximum usage levels is forcing reformulation timelines.
- Bakery:Chemical leavening and mold inhibition in Brazilian industrial bakeries consume citric acid and sodium acid pyrophosphate blends. São Paulo metropolitan area processors represent the volume concentration.
Beverages anchor procurement volumes. Dairy is climbing the fastest on clean-label substitution.
End User:
Customer type dictates channel configuration and contract structure from acidulant producers.
- Beverage Producers:Multinational soft drink bottlers in Brazil's Southeast corridor are consolidating supplier rosters to single-source contracts with integrated technical support. Direct procurement agreements displace traditional distributor intermediaries.
- Food Manufacturers:Mid-tier dairy and processed food processors in Argentina and Colombia rely on distributor networks for smaller volume acidulant procurement. Pricing leverage remains constrained by supplier concentration.
- Food Service:Restaurant chains and institutional kitchens in Brazilian urban centers source pre-diluted acidulant solutions through specialized foodservice distributors.
- Retailers:Private-label condiment and beverage brands in Chile and Peru contract toll manufacturers who manage acidulant sourcing.
Beverage producers command contract scale. Food manufacturers are expanding fastest on processed ingredient demand.
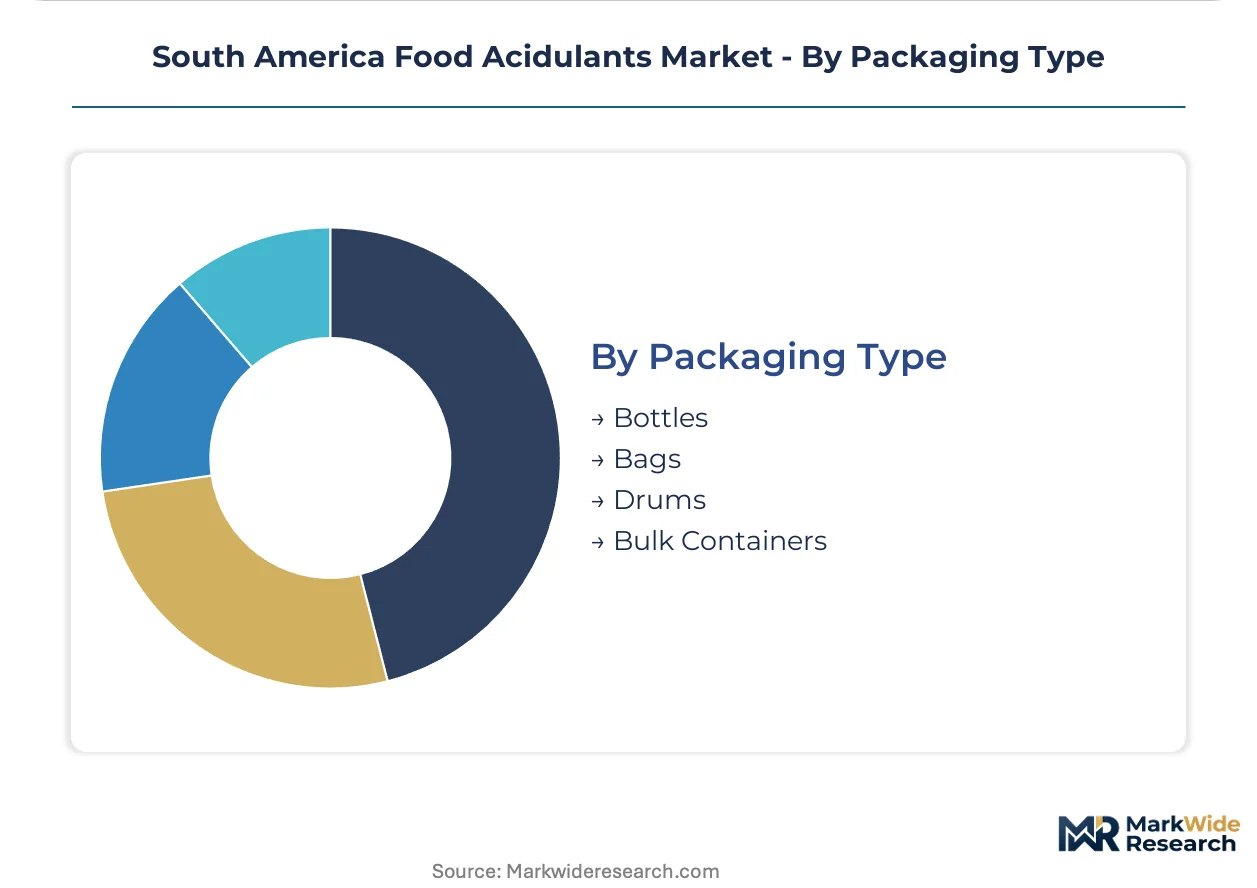
Packaging Type:
Volume and handling requirements segment logistics infrastructure and inventory carrying costs.
- Bulk Containers:Tanker and ISO-tank deliveries serve high-volume beverage and dairy processors in São Paulo and Minas Gerais with dedicated unloading infrastructure. ANVISA customs clearance protocols favor established Brazilian logistics networks.
- Drums:200-liter steel and plastic drums supply mid-scale food manufacturers across Argentina and Colombia with flexible order quantities.
- Bags:Multi-wall paper and woven polypropylene bags suit dry acidulant salts for bakery and confectionery processors with powder handling systems.
- Bottles:Retail-ready liquid acidulants in foodservice and small manufacturer segments complete the packaging hierarchy.
Bulk containers dominate value flows. Bags are gaining share fastest on dry acidulant salt demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA governs acidulant purity standards across Brazil, the region's dominant market, while Mercosur-aligned regulations coordinate enforcement with Argentina and Uruguay. Tax incentives and industrial clustering are reshaping procurement geography.
Brazil
Beverage bottlers in São Paulo and Minas Gerais are scaling acidulant procurement for carbonated and functional drink portfolios. ANVISA's updated food additive purity standards are compressing supplier margins while favoring domestic fermentation infrastructure. The Southeast industrial corridor hosts captive blending facilities in Guarulhos and Contagem that source through direct manufacturer contracts.
Argentina
Clean-label dairy demand is elevating lactic acid grades in yogurt and fresh cheese applications across Buenos Aires and Córdoba provinces. The national food safety authority enforces Mercosur-aligned CODEX standards for acidulant labeling and identity. Argentine regulators are coordinating with Brazilian counterparts on malic acid maximum usage levels for confectionery reformulation.
Colombia
Bogotá and Medellín industrial zones show underpenetrated acidulant sourcing relative to installed bottling capacity. Beverage producers are expanding procurement volumes for pH stabilization in carbonated portfolios. The Andean nation's processing clusters lack the dedicated acidulant logistics infrastructure present in Brazil's Southeast corridor.
Chile
Pending harmonization between Chile's updated food code and Mercosur technical regulations could streamline cross-border procurement protocols. Santiago metropolitan area processors currently face divergent testing requirements that multiply certification costs. Regulatory alignment would reduce fragmentation for suppliers serving both Chilean and Mercosur markets.
Uruguay
Uruguayan dairy processors are expanding procurement of specialized lactic acid grades that preserve protein functionality while meeting Mercosur labeling requirements. Montevideo-based operations represent a secondary demand concentration relative to Argentine scale. The market favors fermentation-derived acidulants over synthetic sources for clean-label positioning.
South America Food Acidulants Market Competitive Landscape
Integrated fermentation operators and specialized acidulant distributors split the market between captive supply relationships and flexible procurement channels. Supplier rosters are consolidating around multinational producers with Brazilian manufacturing assets. Three archetypes dominate: domestic-integrated fermentation houses, European-headquartered specialty acidulant suppliers, and global agribusiness processors with downstream acidulant units. Competitive positioning hinges on backward integration into sucrose feedstock and direct-to-manufacturer channel bypass of distributor networks.
Among European-headquartered specialists, Jungbunzlauer Suisse AG occupies a position exemplifying clean-label dairy acidulant supply, while Tate & Lyle represents the diversified ingredient conglomerate archetype with broad acidulant portfolios. Cargill Incorporated anchors the agribusiness-integrated tier, leveraging Brazilian crushing and fermentation infrastructure to secure beverage bottler contracts. These three entities illustrate how geographic asset placement and regulatory compliance capabilities determine contract viability in ANVISA-governed markets.
| Leading Market Players |
|---|
| Tate & Lyle |
| ICL |
| Cargill Incorporated |
| Jungbunzlauer Suisse AG |
| Innova Corporate |
| Archer Daniels Midland Company |
| SUCROAL |
| Brenntag SE |
| Corbion NV |
| Others |
Value Network & Pricing Analysis
Idle fermentation capacity in Brazil's Southeast corridor compresses supplier pricing power while simultaneously accelerating contract consolidation toward domestic-integrated producers. This utilization dynamic rewards acidulant manufacturers with captive sucrose feedstock and direct-to-beverage-bottler channel access, squeezing distributor-dependent competitors on both cost structure and procurement reliability.
Pricing Analysis
Brazil-Argentina price spreads widen during sugarcane harvest volatility, with São Paulo-based citric acid commanding premiums over Andean-sourced alternatives during ethanol feedstock competition. Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade acidulants reflects certification burden and optical purity specifications. Pricing pressure stems from ANVISA compliance cost absorption as suppliers internalize reformulation support for dairy processors. Mid-tier Argentine food manufacturers exhibit highest price sensitivity, while multinational beverage bottlers prioritize supply security over unit cost negotiation.
Supply Chain Analysis
Cargill Incorporated and Jungbunzlauer Suisse AG anchor contract manufacturing concentration through Brazilian fermentation assets and Swiss-specialized lactic acid production respectively. Supply concentrates in Brazil, Argentina, and Uruguay, with Colombian and Chilean markets drawing from established Mercosur distribution corridors. Raw material dependencies center on Brazilian sugarcane sucrose, Argentine corn dextrose, and imported malic acid precursors. Single-source vulnerability pervades the citric acid tier where Aspergillus niger fermentation expertise concentrates among three multinational operators. Distribution runs through direct manufacturer contracts for beverage bottlers and regional distributor networks for mid-scale food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where ANVISA regulatory entrenchment creates substantial switching costs for qualified suppliers, locking in incumbent advantage through multi-year certification timelines and captive technical service relationships.
For Market Incumbents: Harden ANVISA compliance capabilities as primary defensive perimeter against European specialty acidulant entrants seeking Mercosur expansion. Deepen backward integration into Minas Gerais sugarcane processing to neutralize ethanol market feedstock competition. Expand dedicated technical service teams for Argentine dairy reformulation cycles to cement clean-label lactic acid positioning before CODEX maximum usage revisions finalize. For New Entrants and Emerging Players: Colombian beverage processing clusters in Bogotá and Medellín represent the most penetrable entry point given underdeveloped dedicated acidulant logistics infrastructure relative to installed bottling capacity. Uruguayan clean-label dairy supply chains offer secondary white-space targeting through Mercosur-aligned regulatory equivalence. Go-to-market execution should emphasize pre-certified acidulant salt formulations that compress customer R&D bandwidth during ANVISA-mandated product redevelopment cycles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Brazilian-integrated fermentation houses with direct-to-manufacturer beverage contracts and captive sucrose supply arrangements. Long-term viability over the projection horizon rests on regulatory compliance infrastructure rather than commodity cost position alone. Acquisition target archetype: mid-scale Argentine lactic acid specialists with established Mercosur dairy processor relationships and fermentation-derived clean-label positioning. Signal to monitor: ANVISA enforcement protocol harmonization with Chilean food code revisions as inflection indicator for cross-border procurement consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sucrose Feedstock | Captive Brazilian sugarcane supply neutralizes ethanol market competition for fermentation inputs. |
| Direct-to-Manufacturer Channel Development | Bypassing distributor networks recovers margin compression from ANVISA compliance cost absorption. |
| Clean-Label Lactic Acid Capacity Expansion | Fermentation-derived grades capture Argentine and Uruguayan dairy processor preference shifts. |
| Malic Acid Reformulation Technical Service | Pre-compliant sourness-release alternatives secure confectionery contracts before CODEX limits enforce. |
| Colombian Logistics Infrastructure Buildout | Dedicated acidulant distribution captures Bogotá and Medellín beverage processing procurement gaps. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ANVISA regulatory filings, Mercosur technical standards, and Brazilian customs trade data. Primary interviews engaged acidulant procurement managers at São Paulo beverage bottlers, Argentine dairy R&D directors, and Colombian food manufacturer supply chain leads. Secondary validation drew from ANVISA food additive registers, CODEX Alimentarius draft revisions, and Brazilian sugarcane industry production statistics. Bottom-up acidulant volume estimates triangulated against top-down processed food industry consumption models.
Forecast inputs incorporate fermentation capacity utilization rates, sucrose-ethanol price arbitrage dynamics, and regulatory harmonization probability between Chile and Mercosur. Segmentation modeling spans acidulant chemistry tier, end-use application intensity, customer scale archetype, and packaging format logistics. CAGRs derive from installed capacity expansion timelines and penetration rate assumptions across underdeveloped Colombian and Chilean processing clusters. Industry-specific forecast inputs include Brazilian PLI-style tax incentive qualification thresholds and ANVISA purity standard compliance cost curves.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates, Argentine inflation volatility, or sugarcane harvest yields would shift the trajectory. Forecasts reflect assumptions regarding regulatory enforcement consistency and feedstock allocation stability. Quarterly review of ANVISA customs detention rates, Mercosur standard revision drafts, and Colombian beverage production indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
South America Food Emulsifiers Market
Food Additives and Ingredients
Aluminum-Free Natural Food Color Market
Food Additives and Ingredients
Japan Food Emulsifiers Market
Food Additives and Ingredients
Cocoglycerides Market
Food Additives and Ingredients
South America Food Additives Market
Food Additives and Ingredients
Japan Anti-Caking Market
Food Additives and Ingredients
Beverage Clarifier and Stabilizer Market
Food Additives and Ingredients
Germany Feed Additives Market
Food Additives and Ingredients
Asia-Pacific Food Additives Market
Food Additives and Ingredients
Brazil Food Ingredient Market
Food Additives and Ingredients
Allulose for Food Market
Food Additives and Ingredients
Flavophospholipol Market
Food Additives and Ingredients
North America Food Starch Market
Food Additives and Ingredients
Global Sodium Starch Glycolate Market
Food Additives and Ingredients
Dairy Enzymes Market
Food Additives and Ingredients
Ammonia Caramel Market