
 Starch-Based Edible Coatings Market | 2026-2036
Starch-Based Edible Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Starch-Based Edible Coatings Market Analytics
Fresh produce packaging is broadening its share of starch-based edible coating consumption as retailers and exporters confront post-harvest losses. Cargill Incorporated leverages its grain-processing infrastructure to anchor supply security for native and modified starch inputs. Ingredion Incorporated differentiates through R&D intensity in amylopectin-based barrier formulations. Roquette Frères specializes in pea-derived starch alternatives that compete on clean-label positioning against conventional corn and potato sources.
Starch-based edible coatings comprise polysaccharide films derived from amylose, amylopectin, native starch, or chemically modified starch variants, typically applied through dipping, spraying, or brushing to create oxygen and moisture barriers between 20 and 200 micrometers thick. Their primary commercial purpose is extending perishable food shelf life while replacing petroleum-derived synthetic films. Modified starch formulations command margin pools due to superior mechanical properties and controlled release functionality, while native starch maintains volume leadership in cost-sensitive applications. Powder and liquid forms dominate processing flexibility, though film formats are gaining traction in ready-to-use retail configurations for fruits and vegetables.
The FDA governs food-contact substance notifications under 21 CFR, while the EPA regulates agricultural chemical residues that affect coating ingredient approval pathways. The EU's REACH framework and F-Gas Regulation indirectly shape demand by restricting synthetic barrier alternatives. EFSA evaluations of novel food-contact materials determine market access timelines for innovative starch modifications. Stakeholders must monitor evolving compostability certifications and single-use plastic bans, as these regulatory trajectories will determine which coating chemistries secure preferential procurement contracts.
Market Dynamics
EU Packaging and Packaging Waste Regulation enforcement is compressing synthetic film procurement timelines while Mediterranean fruit exporters accelerate starch coating qualification programs to maintain retail access.
Growth Catalysts
- EU Green Deal packaging mandates:Biodegradable material quotas under the EU Green Deal are compelling food-contact material suppliers to reformulate barrier solutions around edible polysaccharides.
- Post-harvest loss economics:Fresh produce exporters in Spain and Italy face retailer penalties for spoilage, driving coating adoption as an insurance mechanism against rejected shipments.
- Modified starch functionality:Amylopectin cross-linking advances enable moisture barriers competitive with synthetic alternatives at 20-50 micrometer thicknesses.
Market Restraints
- Native starch price volatility:Corn and potato starch feedstock costs fluctuate with grain commodity cycles, squeezing margin pools for unmodified formulations.
- Pea protein diversion:Roquette Frères and competitors face input competition from plant-based meat sectors for pea starch streams, tightening specialty supply.
- REACH registration timelines:Novel modified starch chemistries require ECHA substance evaluation periods that delay commercial launch by 18-36 months.
Strategic Opportunities
- India FSSAI clean-label pathway:India's food safety regulator is developing expedited approval frameworks for edible coatings on tropical fruit exports to Gulf markets.
- Ready-to-use film formats:Pre-formed starch sheets for retail vegetable packaging bypass on-site dipping infrastructure requirements, opening convenience-oriented channels.
- Carbon accounting integration:EU CSRD disclosure rules position compostable coatings as Scope 3 reduction instruments for supermarket private-label programs.
Industry Challenges
- Compostability certification fragmentation:Divergent industrial composting standards between TÜV Austria, BPI, and OK Compost create multi-jurisdiction testing burdens.
- Application equipment retrofit costs:Converting synthetic film coating lines to handle aqueous starch slurries requires spray nozzle and drying tunnel modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Starch-Based Edible Coatings Market |
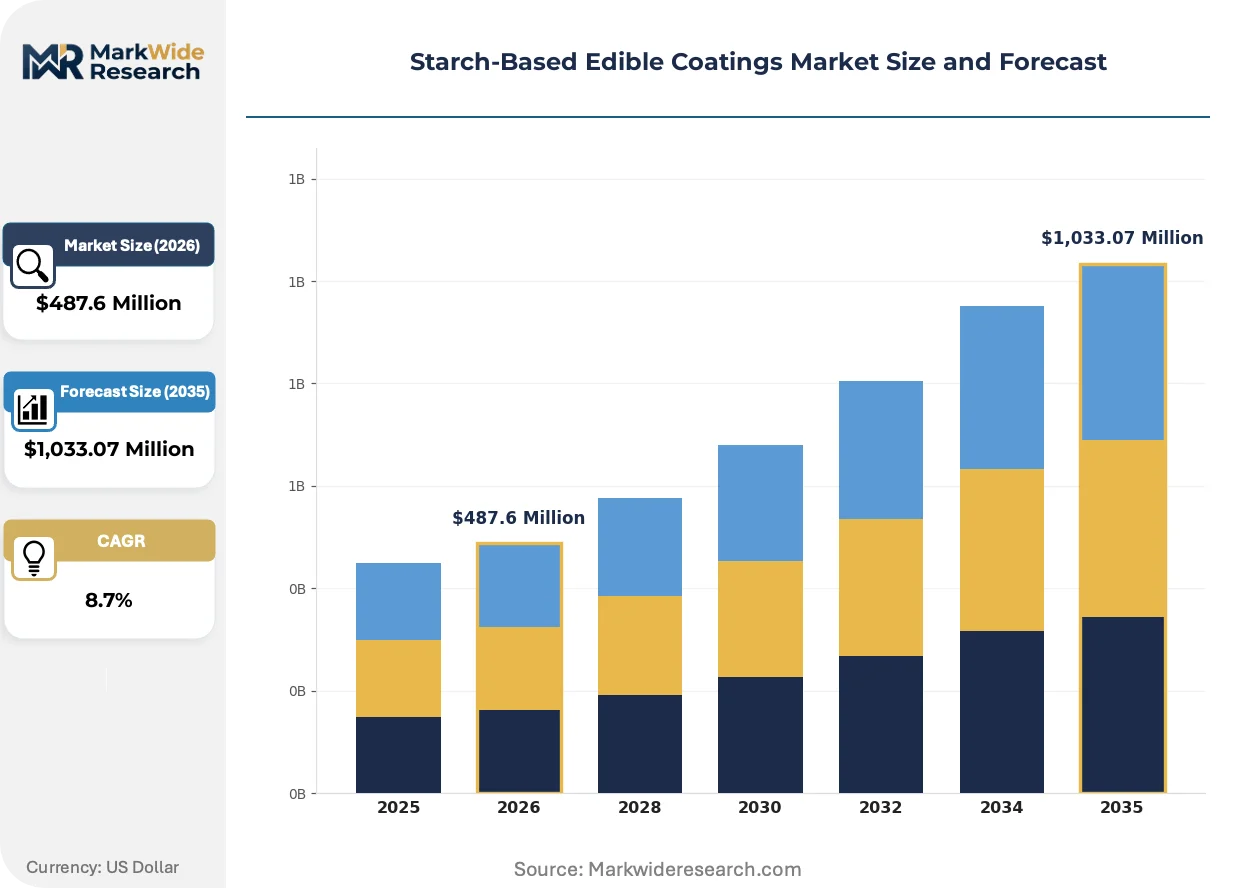
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amylose, Amylopectin, Modified Starch, Native Starch Application: Fruits, Vegetables, Dairy Products, Meat Products Form: Liquid, Powder, Film, Gel Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, Tate & Lyle PLC, Roquette Frères, BASF SE, DuPont de Nemours, Inc., Kerry Group plc, Apeel Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Starch-Based Edible Coatings Market Evolving Landscape
Active barrier functionality is displacing passive oxygen and moisture blocking as the primary R&D target, with antimicrobial and antioxidant release properties now standard in premium coating specifications.
Nano-cellulose reinforcement is rewriting mechanical property benchmarks for starch-based edible coatings. Food packaging engineers at Mediterranean export cooperatives are piloting 5-15% cellulose nanofiber loadings to achieve synthetic-comparable tensile strength. This hybrid approach is compressing the performance gap that previously confined starch films to short-shelf-life applications.
REACH F-Gas Regulation restrictions on fluorinated barrier chemicals are redirecting coating R&D budgets toward polysaccharide alternatives. Synthetic film manufacturers face phase-out deadlines for perfluorinated moisture barriers, accelerating partnership discussions with starch formulation specialists. Spanish citrus exporters report active supplier audits to qualify edible coating replacements before F-Gas prohibitions take full effect.
Retailer sustainability scorecards now weight packaging circularity at 15-25% of supplier evaluation criteria. German and French supermarket chains are delisting produce SKUs without certified compostable packaging by 2027, forcing coating adoption upstream. This procurement filter is most visible in berry and leafy green categories where film replacement delivers maximum visual sustainability signaling.
Starch-Based Edible Coatings Market Segmentation
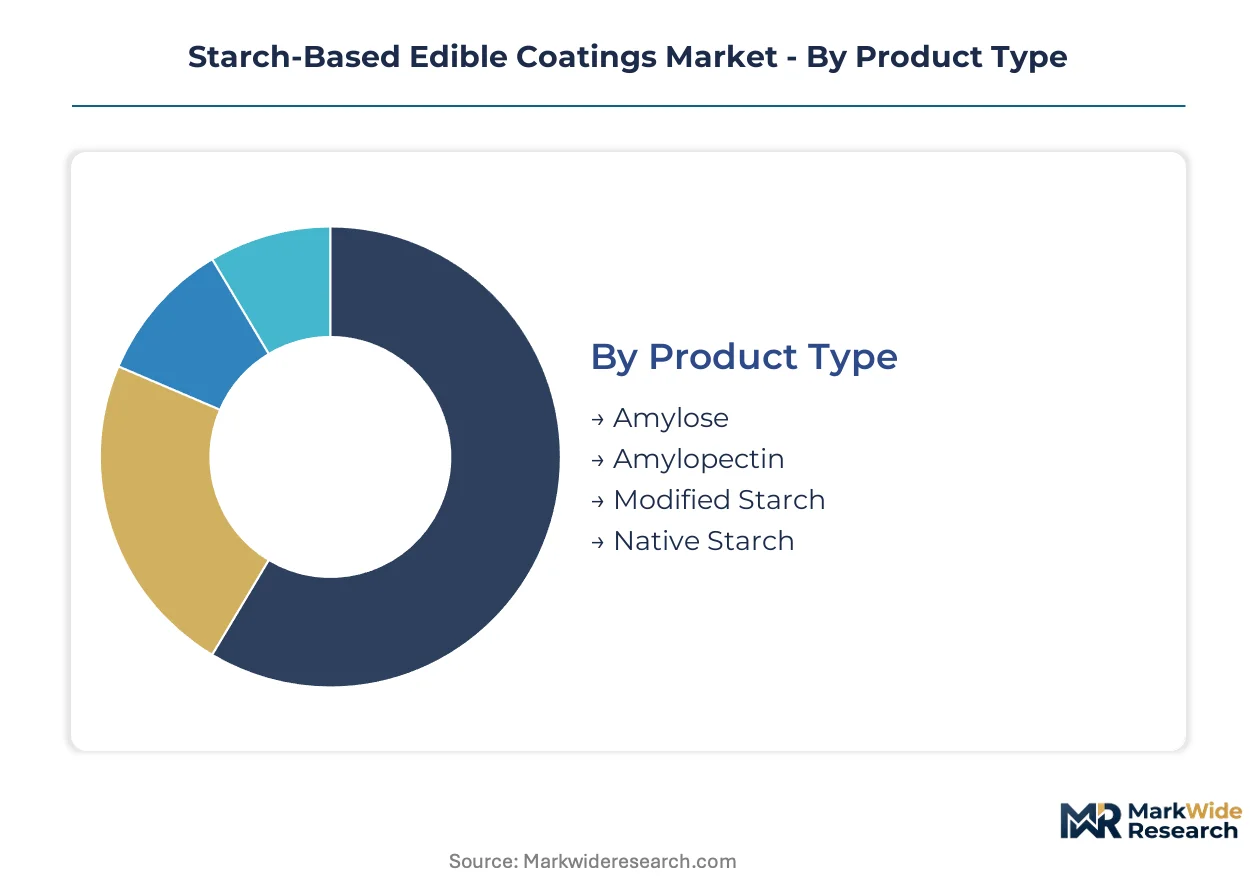
Formulation chemistry and application method determine procurement priorities for starch-based edible coatings. Buyers segment choices by barrier performance requirements, processing infrastructure compatibility, and end-product shelf-life targets.
Product Type:
Barrier specificity and cost thresholds drive formulation selection across fresh produce and protein applications.
- Modified Starch:Chemical or physical alterations enhance mechanical strength and controlled-release functionality for high-value exports. Spanish citrus cooperatives specify cross-linked amylopectin variants to meet German retailer compostability mandates.
- Native Starch:Unmodified corn and potato starches serve cost-sensitive volume applications through simpler dipping operations. Italian tomato processors favor native formulations for short domestic distribution cycles where barrier demands remain modest.
- Amylose:Linear polymer structures create dense, crystalline films with superior oxygen barrier properties. French berry exporters specify high-amylose coatings for refrigerated supply chains.
- Amylopectin:Branched architectures enable flexible, transparent films suitable for visual produce presentation. Greek stone fruit packers select amylopectin-dominant formulations for cling-film replacement.
Native starch leads on scale; modified starch leads on momentum.
Application:
Perishability windows and surface morphology dictate coating specification intensity across food categories.
- Fruits:High-moisture, respiring surfaces demand breathable barriers that balance gas exchange with dehydration control. Mediterranean exporters deploy starch coatings on citrus, stone fruit, and berries to reduce refrigeration energy intensity.
- Vegetables:Leafy greens and brassicas present large surface-area-to-mass ratios requiring uniform spray application. Dutch greenhouse operators trial nano-cellulose reinforced starch films on packaged herbs.
- Dairy Products:Fat-protein matrices challenge adhesion and flavor neutrality. Italian cheese producers experiment with starch-based edible wraps for aged pecorino wheels.
- Meat Products:Myoglobin oxidation and microbial proliferation require antimicrobial-active formulations. Spanish cured ham processors evaluate starch barriers as synthetic vacuum-bag replacements.
Fruits dominate current procurement volumes; vegetables are gaining share fastest.
Form:
Processing infrastructure and labor automation requirements determine format selection at coating application points.
- Liquid:Aqueous suspensions enable continuous spray lines with standard nozzle equipment. Portuguese apple packers prefer liquid systems for high-throughput waxing line retrofits.
- Powder:Dry blends offer extended shelf stability and reduced transport costs. Greek olive oil cooperatives specify powder formats for remote facility reconstitution.
- Film:Pre-formed sheets eliminate on-site dipping infrastructure for small-scale operations. Italian organic vegetable distributors adopt ready-to-use starch films for retail-ready packaging.
- Gel:Thixotropic formulations enable brush application on irregular surfaces. Spanish artichoke processors utilize gel consistency for hand-application on specialty export grades.
Liquid formulations lead on scale; film formats lead on momentum.
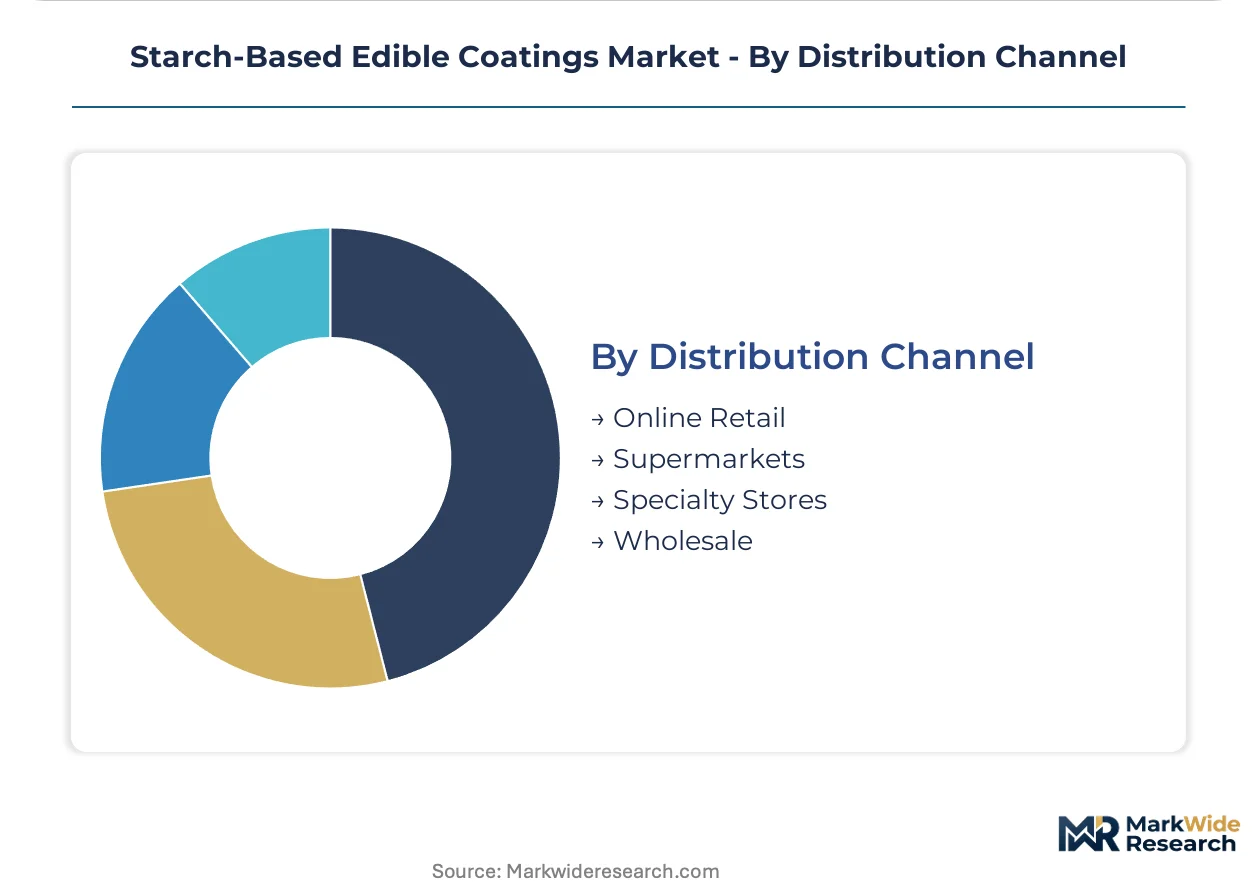
Distribution Channel:
Volume concentration and technical service intensity shape channel economics for coating procurement.
- Wholesale:Bulk supply relationships dominate ingredient procurement for large-scale fruit cooperatives and processing facilities. Cargill Incorporated and Ingredion Incorporated anchor supply security through direct wholesale contracts with Mediterranean exporters.
- Supermarkets:Private-label sustainability commitments drive specification of certified compostable coatings. French retail chains mandate coating compliance in supplier scorecards.
- Specialty Stores:Niche organic and biodynamic producers seek clean-label starch alternatives through regional distributors. Italian agritourism cooperatives source pea-derived coatings for direct-market differentiation.
- Online Retail:E-procurement platforms serve small-scale operators and research institutions with sample quantities and technical documentation. Roquette Frères maintains digital channels for specialty pea starch inquiries.
Wholesale channels lead on scale; supermarket direct specifications lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting coating formulation investments toward jurisdictions with expedited food-contact approval pathways and proximity to high-value agricultural export corridors.
Spain
Mediterranean citrus and stone fruit exporters drive coating demand through German and French retail procurement channels. The EU's Packaging and Packaging Waste Regulation compresses synthetic film transition timelines, forcing Valencia and Murcia packing cooperatives to accelerate starch-based qualification programs.
Italy
Tomato processors and cheese producers in Emilia-Romagna and Lombardy seek barrier solutions for short domestic distribution and aged product export. EFSA evaluations of novel starch modifications determine market access timelines for regional formulation specialists.
France
Berry exporters in Provence-Alpes-Côte d'Azur and greenhouse operators in Brittany specify high-amylose coatings for refrigerated supply chains. Supermarket sustainability scorecards weight packaging circularity at 15-25% of supplier evaluation criteria, forcing coating adoption upstream.
Germany
Retail chains in Bavaria and North Rhine-Westphalia mandate certified compostable packaging compliance by 2027, delisting produce SKUs without compliant barriers. Industrial composting standards from TÜV Austria create multi-jurisdiction testing burdens for coating suppliers.
India
Tropical fruit exporters to Gulf markets leverage FSSAI clean-label pathway development for edible coating approvals. Maharashtra and Gujarat processing facilities trial starch formulations as insurance mechanisms against retailer spoilage penalties.
Starch-Based Edible Coatings Market Competitive Landscape
Capacity expansion dominates the current landscape as grain processors and specialty ingredient suppliers retrofit existing infrastructure for food-contact starch production. The vendor base clusters around three strategic archetypes: agricultural commodity traders with captive starch supply, dedicated ingredient formulators with R&D intensity, and clean-label specialists with alternative feedstock positioning. M&A activity concentrates on mid-scale coating technology acquisitions, while strategic partnerships between starch suppliers and produce packagers accelerate application-specific formulation development.
Among North American agricultural conglomerates, Cargill Incorporated and Archer Daniels Midland Company exemplify the commodity-anchored archetype with grain-processing infrastructure supporting native and modified starch supply security. Ingredion Incorporated represents the R&D-intensive formulation specialist, while Roquette Frères occupies the clean-label alternative position with pea-derived starch sourcing. These three anchors illustrate divergent competitive vectors: scale-driven supply assurance, technology-driven barrier performance, and sustainability-driven feedstock differentiation.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Roquette Frères |
| BASF SE |
| DuPont de Nemours, Inc. |
| Kerry Group plc |
| Apeel Sciences |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap starch processors in Italy and Spain anchor regional supply networks through generational financing structures that resist private-equity rollup pressure, creating pricing discipline through captive grain-milling assets and long-term produce-packer contracts.
Pricing Analysis
Distributor margins on modified starch formulations absorb 12-18 points before reaching Mediterranean fruit cooperatives, compressing as ingredient suppliers consolidate wholesale relationships. Three-tier pricing structure across modified, native, and amylose-rich formulations separates premium barrier performance from cost-sensitive dipping applications. Pricing pressure stems from corn and potato feedstock commodity cycles that squeeze unmodified formulation margins. Small-scale organic distributors exhibit highest price sensitivity; large export cooperatives prioritize certification compliance over unit cost.
Supply Chain Analysis
Compostability certification returns and re-qualification flows create reverse-logistics burdens as German and French retailers reject non-compliant batches, forcing reformulation cycles back to starch suppliers. Supply concentrates in the United States, France, and India for corn, pea, and tapioca starch feedstocks respectively. Input dependencies include grain commodity markets, chemical modification reagents, and nano-cellulose reinforcement streams. Single-source vulnerability runs through Cargill's North American grain-processing infrastructure. Distribution runs through wholesale ingredient contracts with Mediterranean packing cooperatives, bypassing distributor layers for volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Starch-based edible coatings represent a late-cycle quality story as EU retailer sustainability scorecards shift procurement weight toward certified compostable barriers, elevating specification intensity above commodity-grade competition.
For Market Incumbents: Deploy amylopectin cross-linking R&D to defend formulation premium against nano-cellulose hybrid entrants. Cargill and Ingredion should consolidate regional distributor relationships in Spain and Italy before FSSAI pathway expansion invites Indian competition. Backward integration into pea starch streams counters Roquette's clean-label positioning. For New Entrants and Emerging Players: Regional organic distributors in France and Germany present the most penetrable channel layer, as these buyers lack technical qualification resources for direct supplier relationships. Target ready-to-use film formats for small-scale vegetable packers lacking dipping infrastructure. Pursue carbon accounting integration as the go-to-market wedge for EU CSRD-compliant supermarket private-label programs. For Investors and Strategic Acquirers: Valuations sit cheapest among native starch commodity processors lacking modification capabilities or certification assets. Five-to-ten year viability hinges on REACH F-Gas substitution timelines and compostability standard convergence. Monitor TÜV Austria and BPI certification harmonization progress as the inflection signal for margin expansion in premium modified formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pea Starch Streams | Roquette Frères' captive supply model forces competitors to secure alternative legume feedstock sources. |
| REACH F-Gas Substitution Partnership | Spanish citrus exporters accelerate supplier audits to qualify edible coatings before fluorinated barrier phase-outs. |
| Nano-Cellulose Reinforcement Licensing | Mediterranean cooperatives pilot hybrid formulations achieving synthetic-comparable tensile strength benchmarks. |
| Ready-to-Use Film Format Launch | Italian organic distributors adopt pre-formed sheets eliminating on-site dipping infrastructure requirements. |
| India FSSAI Clean-Label Pathway Investment | Maharashtra and Gujarat processors trial starch formulations for Gulf-market tropical fruit exports. |
Research Methodology
Multiple input streams — regulatory filing analysis, grain commodity trade data, and produce export documentation — were reconciled across primary interviews with starch formulation R&D directors, Mediterranean fruit cooperative procurement managers, EU packaging compliance officers, and Indian FSSAI regulatory consultants, validated against secondary sources including EFSA novel food-contact evaluations, EU Packaging and Packaging Waste Regulation impact assessments, and SEC filings from publicly traded ingredient suppliers, with bottom-up volume modeling triangulated against top-down market sizing.
Data-stream reconciliation applied segmentation dimensions across formulation chemistry, application method, and regional regulatory cluster throughout the projection horizon, with CAGRs derived from trend extrapolation of historical adoption curves and scenario-weighted regulatory enforcement timelines, incorporating nano-cellulose reinforcement adoption rates and compostability certification penetration as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH registration delays, F-Gas phase-out acceleration, and divergent industrial composting standard adoption between TÜV Austria, BPI, and OK Compost frameworks. Practitioners should monitor EU retailer delisting deadline compliance rates and India FSSAI pathway finalization for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Acidulants Market
Food Additives and Ingredients
Brazil Feed Additives Market
Food Additives and Ingredients
Spain Food Preservatives Market
Food Additives and Ingredients
Isodecanol Market
Food Additives and Ingredients
Meat Tenderizing Agents Market
Food Additives and Ingredients
Australia Food Preservatives Market
Food Additives and Ingredients
Canada Food Emulsifiers Market
Food Additives and Ingredients
Africa Food Preservatives Market
Food Additives and Ingredients
Vietnam Food Additives Market
Food Additives and Ingredients
Phosphated Distarch Phosphate Market
Food Additives and Ingredients
Africa Food Emulsifiers Market
Food Additives and Ingredients
Plant-Based Emulsifiers Market
Food Additives and Ingredients
Flour Whiteners Market
Food Additives and Ingredients
Chocolate Wax Market
Food Additives and Ingredients
Agar Agar Gum Market
Food Additives and Ingredients
Global Flaked Shortenings Market