
 Egypt Food Emulsifiers Market | 2026-2036
Egypt Food Emulsifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Food Emulsifiers Market Foresight
Egypt is reconfiguring its food ingredient manufacturing base through localized emulsifier blending facilities and import-substitution programs. Cargill, Incorporated leverages its Red Sea logistics corridor to sustain bulk lecithin distribution into Egyptian dairy processors. BASF SE anchors technical service capabilities for bakery stabilizer formulations in the Nile Delta industrial zone. Kerry Group competes through flavor-emulsifier hybrid systems tailored to Egyptian flatbread applications.
Food emulsifiers are surface-active compounds that reduce interfacial tension between immiscible phases such as oil and water, typically possessing hydrophilic-lipophilic balance values between 3 and 16 depending on molecular structure. These agents stabilize dispersions, control crystallization, and extend shelf life in processed foods ranging from margarine to ice cream. Natural emulsifiers command premium positioning as Egyptian food manufacturers reformulate to meet Gulf export standards and domestic clean-label preferences. Modified starches represent a mature, cost-driven category where margin pools have compressed amid regional oversupply. The functionality dimension shows texture modifiers gaining share as ready-meal producers seek freeze-thaw stability in ambient distribution chains.
Egypt's National Food Safety Authority enforces additive maximum limits under harmonized standards with the GCC Standardization Organization, while the Egyptian Organization for Standardization and Quality (EOS) mandates labeling disclosure for synthetic emulsifiers. These frameworks compel reformulation investments and create compliance barriers for unregistered imports. Stakeholders must monitor NFSA's pending positive-list revisions and align R&D pipelines with anticipated natural-source certification requirements.
Market Dynamics
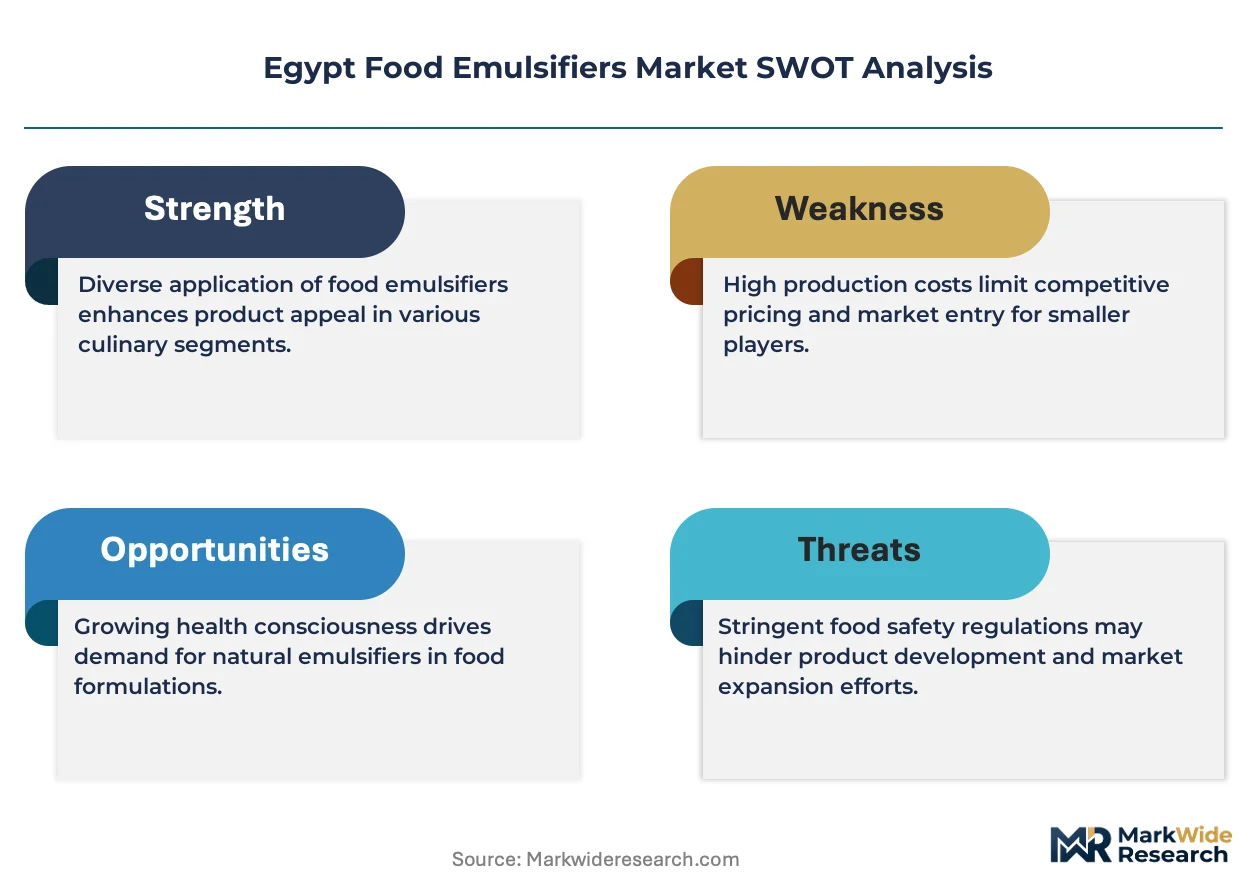
Clean-label reformulation mandates from the National Food Safety Authority are restructuring Egypt's food emulsifier procurement, forcing manufacturers to replace synthetic additives with certified natural alternatives ahead of GCC export harmonization deadlines.
Growth Catalysts
- GCC Standardization Alignment:NFSA's harmonization with Gulf standards is opening export pathways for Egyptian dairy and bakery processors, expanding addressable demand for certified emulsifiers.
- Greater Cairo Processing Clusters:Concentrated food manufacturing in the capital region generates procurement economies of scale that attract technical service investments from multinational ingredient suppliers.
- Enzymatic Modification:Advanced enzymatic processes for lecithin refinement are enabling cleaner-label positioning without sacrificing functional performance in margarine and chocolate applications.
Market Restraints
- Sunflower Lecithin Supply Concentration:Dependence on Black Sea-origin sunflower inputs exposes Egyptian blenders to volatility from the ongoing conflict zone and sanctions complexity.
- NFSA Positive-List Uncertainty:Pending revisions to Egypt's additive approval catalog create formulation risk for manufacturers holding inventory of emulsifiers awaiting re-registration.
- Modified Starch Substitution:Mature starch-based stabilizers in cost-sensitive confectionery segments limit premium penetration for functional emulsifier systems.
Strategic Opportunities
- Red Sea Logistics Corridors:Port infrastructure expansion at Ain Sokhna and Safaga enables direct bulk import of lecithin and specialty esters, reducing reliance on Alexandria congestion.
- Freeze-Thaw Stability Demand:Ready-meal producers distributing through ambient Egyptian retail chains require emulsifier systems that maintain texture through temperature abuse.
- Natural-Source Certification Tailwind:Anticipated NFSA mandates for plant-origin documentation will advantage early movers with established supply chain traceability systems.
Industry Challenges
- Food Technologist Shortage:Limited local expertise in emulsion science and HLB balancing restricts in-house reformulation capability at mid-tier Egyptian manufacturers.
- Dual Registration Burden:Separate NFSA and EOS compliance pathways for new emulsifier introductions extend time-to-market by 8-14 months versus regional competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Food Emulsifiers Market |
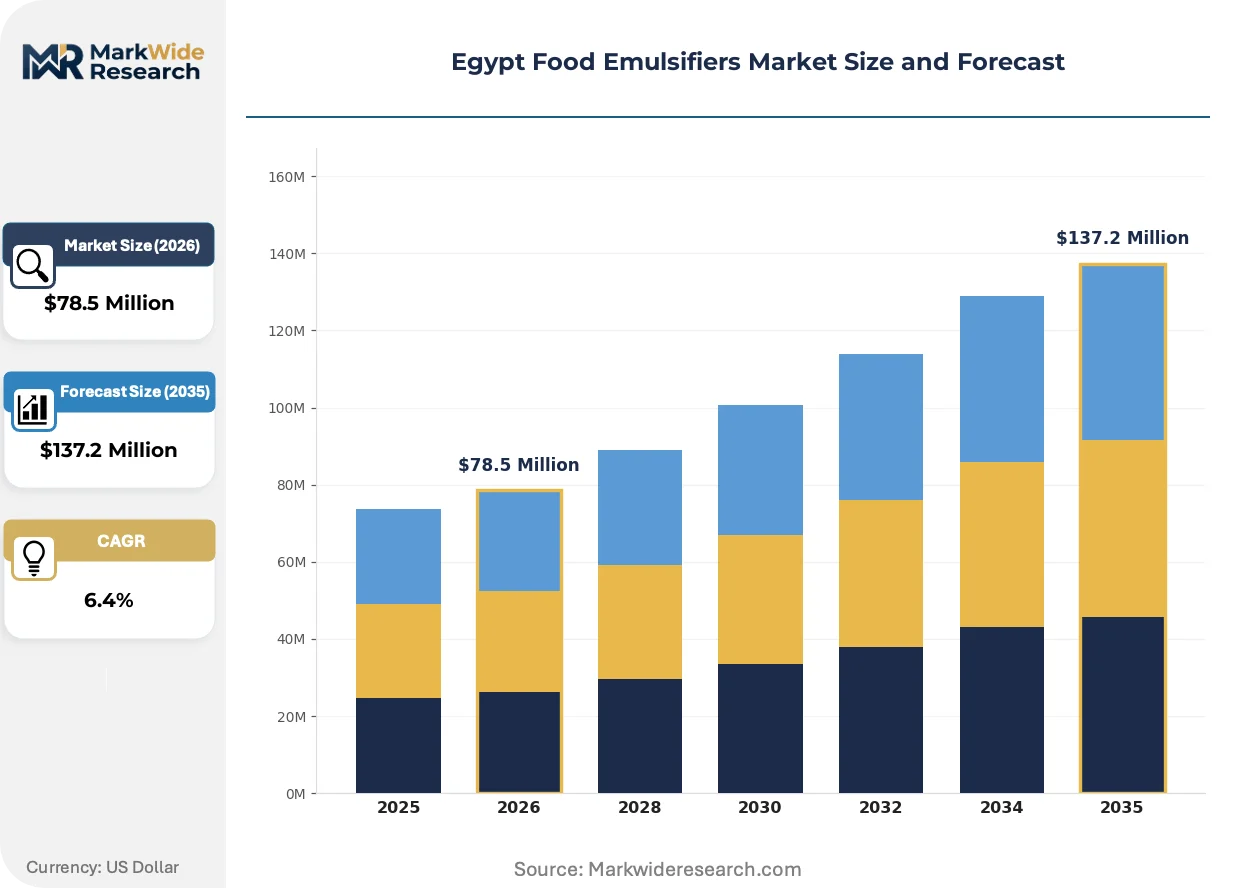
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $137.2 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Emulsifiers, Artificial Emulsifiers, Modified Starches, Lecithin Application: Baked Goods, Dairy Products, Salad Dressings, Sauces End User: Food Manufacturers, Restaurants, Catering Services, Home Cooks Functionality: Stabilizers, Thickeners, Texture Modifiers, Flavor Enhancers |
| Companies Covered | BASF SE, Ingredion Incorporated, Cargill, Incorporated, Palsgaard A/S, Puratos, Kerry Group, Archer Daniels Midland Company, Lonza Group AG, DuPont de Nemours, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Food Emulsifiers Market Shifts & Advancements
Reformulation chemistry is pivoting toward multifunctional systems that combine emulsification with extended shelf-life protection, reducing ingredient list complexity for Egyptian clean-label positioning.
Phospholipid-protein hybrid emulsifiers are hybridizing in Nile Delta dairy applications, where processors seek single-ingredient solutions for both fat stabilization and foaming control. Medium-scale cheese and yogurt manufacturers in Alexandria industrial zones are piloting these systems at commercial scale. The convergence is compressing demand for standalone hydrocolloid stabilizers in cultured dairy segments.
NFSA's pending positive-list revision is tightening maximum limits on synthetic esters while fast-tracking plant-derived alternatives through expedited review tracks. Egyptian margarine producers face reformulation timelines of 12-18 months to maintain compliance. Bakery stabilizer suppliers are responding by pre-positioning enzymatically modified lecithin stocks ahead of anticipated enforcement windows.
Direct procurement from Red Sea bulk terminals is displacing traditional distributor-mediated supply for Greater Cairo compounders. Large flatbread and confectionery manufacturers now negotiate annual contracts with logistics-integrated suppliers rather than spot purchasing through Cairo trading houses. This channel consolidation is most pronounced among exporters seeking lot-traceability documentation for Saudi and UAE retail chains.
Egypt Food Emulsifiers Market Segmentation
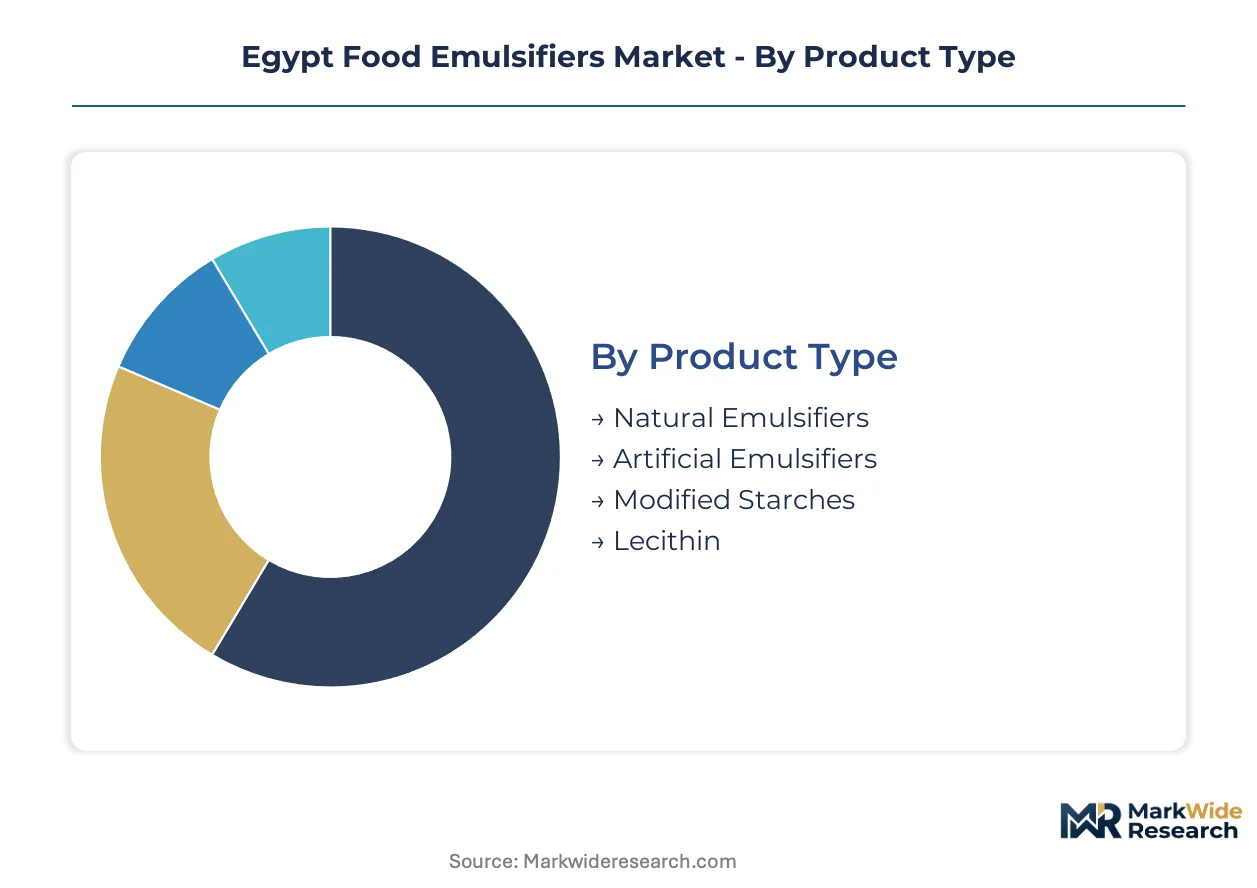
Segmentation reveals how procurement cycles and reformulation pressures fragment demand across Egypt's food emulsifier landscape. Manufacturers must align inventory strategies with divergent technical requirements and compliance timelines.
Product Type:
Cycle times vary sharply: lecithin turns monthly through dairy processors, while modified starches sit for quarters in confectionery stockpiles.
- Natural Emulsifiers:Plant-derived phospholipids and protein-lipid complexes with HLB values optimized for clean-label positioning. Egyptian margarine producers in the Nile Delta are converting formulations ahead of NFSA's anticipated plant-origin mandates, compressing approval-to-procurement windows.
- Lecithin:Soy and sunflower phospholipid fractions refined through enzymatic or solvent processes. Greater Cairo compounders are securing six-month forward contracts through Red Sea bulk terminals to hedge Black Sea supply disruption.
- Artificial Emulsifiers:Synthetic esters including mono- and diglycerides and polysorbates subject to tightening maximum limits under NFSA-Codex harmonization.
- Modified Starches:Acetylated and hydroxypropylated starches with emulsifying properties in cost-sensitive applications where functional performance tolerates lower HLB precision.
Modified starches dominate installed base. Natural emulsifiers are where expansion concentrates.
Application:
Application segmentation tracks how thermal processing demands and distribution cold-chain reliability dictate emulsifier selection.
- Baked Goods:Flatbread and biscuit manufacturers require emulsifiers that withstand high-temperature oven stress while maintaining crumb structure through ambient retail distribution. Alexandria industrial clusters are piloting phospholipid-protein hybrids to reduce ingredient list complexity.
- Dairy Products:Cultured milk applications demand emulsifiers with dual foaming and fat-stabilization functionality. Medium-scale yogurt processors are displacing standalone hydrocolloids with integrated systems.
- Salad Dressings:Oil-in-water emulsions requiring shear stability through homogenization and bottle-filling lines.
- Sauces:Viscosity-controlled emulsions where freeze-thaw stability matters less than thermal reversibility in hot-climate distribution.
Dairy commands premium formulation spend. Baked goods are climbing the fastest.
End User:
Customer-type segmentation exposes divergent technical capabilities and compliance documentation requirements.
- Food Manufacturers:Large-scale processors with in-house emulsion science expertise and direct NFSA registration pathways. These buyers negotiate annual contracts with lot-traceability documentation for GCC export.
- Restaurants:Commercial kitchens sourcing pre-blended emulsifier systems through distributor networks with limited reformulation autonomy.
- Catering Services:Volume buyers prioritizing cost stability over functional optimization in buffet and institutional applications.
- Home Cooks:Retail-packaged emulsifier blends sold through supermarket channels with minimal technical specification demands.
Food manufacturers anchor procurement volumes. Restaurants are gaining share fastest.
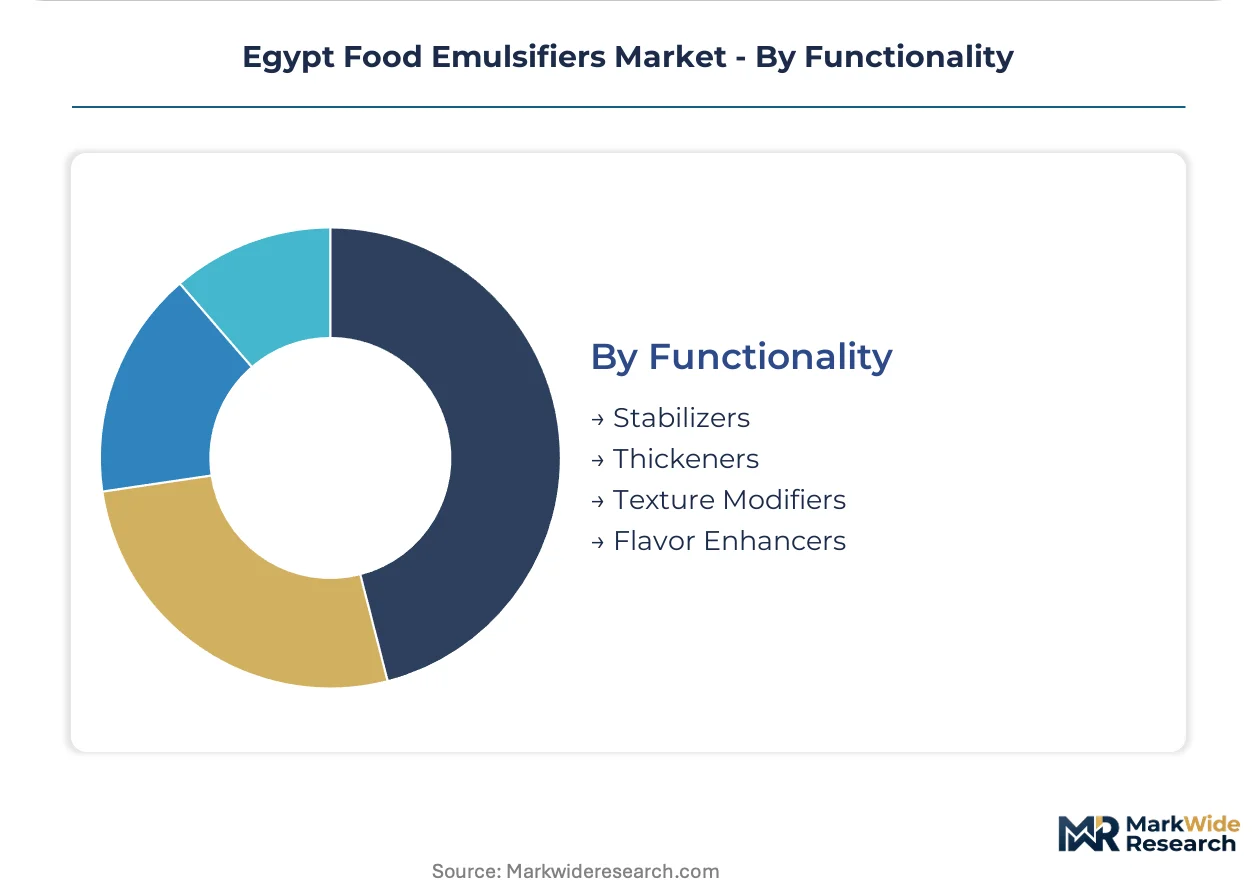
Functionality:
Functional segmentation maps how single-purpose ingredients are consolidating into multifunctional systems.
- Stabilizers:Agents preventing phase separation in extended shelf-life products. Egyptian ice cream producers are demanding systems that maintain integrity through ambient distribution temperature abuse.
- Texture Modifiers:Ingredients controlling mouthfeel and structural recovery in ready-meal applications. Freeze-thaw stability is the critical specification for Greater Cairo processors supplying supermarket chains.
- Thickeners:Viscosity-building agents often overlapping with hydrocolloid categories in sauce and dressing formulations.
- Flavor Enhancers:Emulsifiers with secondary taste-modulation properties in reduced-fat dairy and confectionery.
Stabilizers dominate technical service investments. Texture modifiers are where R&D pipelines concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Suez Canal Economic Zone underwrites Egypt's food ingredient logistics, anchoring Red Sea bulk import corridors that bypass Mediterranean port congestion and accelerate lecithin distribution into Nile Delta processing clusters.
Greater Cairo
Flatbread manufacturers and compound dairy processors concentrate procurement volumes in the capital region, driving technical service investments from multinational suppliers. NFSA registration pathways run through Cairo headquarters, creating compliance gravity for emulsifier distributors. The 10th of Ramadan industrial city hosts the largest emulsifier blending capacity outside Alexandria.
Alexandria
Ice cream and cultured dairy producers in Alexandria's free zones demand freeze-thaw stable emulsifier systems for ambient retail distribution. The port's bulk liquid handling infrastructure receives sunflower lecithin shipments from Black Sea origins. Medium-scale yogurt processors here pilot phospholipid-protein hybrid stabilizers to displace standalone hydrocolloids.
Nile Delta
Margarine producers in Damietta and Mansoura industrial zones face 12-18 month reformulation timelines ahead of NFSA's pending plant-origin mandates. Enzymatically modified lecithin stocks are pre-positioning in regional warehouses. Local food technologist scarcity restricts in-house emulsion science capability at mid-tier manufacturers.
Red Sea Coast
Ain Sokhna and Safaga port expansions enable direct bulk lecithin and specialty ester imports, reducing reliance on Alexandria congestion. Exporters to Saudi and UAE retail chains negotiate annual contracts with lot-traceability documentation here. Logistics-integrated suppliers are displacing traditional Cairo trading house intermediation.
Egypt Food Emulsifiers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower functional portfolios. Egypt's food emulsifier structure concentrates around multinational ingredient houses with Red Sea logistics integration and regional technical service arms. Three archetypes dominate: Gulf-export-integrated formulators, clean-label certification specialists, and Red Sea logistics-integrated distributors. Competitive moves center on pre-positioning enzymatically modified lecithin stocks ahead of NFSA enforcement windows and securing six-month forward contracts through bulk terminal direct procurement.
Among European-based chemical conglomerates, BASF SE anchors technical service capabilities for bakery stabilizer formulations. Cargill, Incorporated leverages its Red Sea logistics corridor to sustain bulk lecithin distribution. Kerry Group occupies a position in flavor-emulsifier hybrid systems tailored to Egyptian flatbread applications. These three exemplify the platform-integrator archetype that dominates procurement relationships with large-scale food manufacturers seeking GCC export compliance.
| Leading Market Players |
|---|
| BASF SE |
| Ingredion Incorporated |
| Cargill, Incorporated |
| Palsgaard A/S |
| Puratos |
| Kerry Group |
| Archer Daniels Midland Company |
| Lonza Group AG |
| DuPont de Nemours, Inc. |
| Others |
Supply & Pricing Matrix
The Red Sea logistics corridor's bulk terminal economics compress procurement costs for Greater Cairo compounders while amplifying price spreads between certified natural emulsifiers and synthetic alternatives. This freight-cost asymmetry rewards logistics-integrated suppliers with pricing power in premium tiers, forcing distributor-dependent competitors toward economy positioning.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Egyptian emulsifier procurement. Premium tiers capture plant-origin certification and GCC export documentation; standard tiers serve domestic dairy processors with enzymatically modified lecithin; economy tiers compete on modified starches for cost-sensitive confectionery. Pricing pressure stems from Black Sea sunflower lecithin supply disruption and NFSA's pending positive-list revisions. Mid-tier manufacturers exhibit highest price sensitivity due to limited reformulation budgets and inventory risk from re-registration delays.
Supply Chain Analysis
Upstream sunflower and soy phospholipid feedstock draws from Ukraine, Russia, and Argentina, with Egyptian blenders exposed to Black Sea conflict-zone volatility and sanctions complexity. Refined lecithin fractions, specialty esters, and enzymatic processing enzymes constitute critical input dependencies. Single-source vulnerability concentrates in sunflower lecithin origins. Distribution runs through Red Sea bulk terminals at Ain Sokhna and Safaga, displacing Alexandria port congestion and Cairo trading house intermediation for large-scale manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's food emulsifier market sits at a platform-economics inflection where logistics-integrated suppliers with GCC export documentation capabilities are consolidating procurement relationships and marginalizing distributor-mediated channels.
For Market Incumbents: Harden Red Sea logistics integration through captive bulk terminal access and multi-year forward contracting with Black Sea sunflower suppliers to buffer re-registration inventory risk from NFSA's pending positive-list revisions. Deepen technical service capabilities in enzymatic lecithin refinement to defend margin position against modified starch substitution in cost-sensitive segments. For New Entrants and Emerging Players: Pursue white-space positioning in phospholipid-protein hybrid systems for medium-scale Alexandria yogurt processors seeking single-ingredient alternatives to standalone hydrocolloids. Target Nile Delta margarine manufacturers facing 12-18 month reformulation mandates with pre-positioned natural-source certification and expedited NFSA registration support as the primary go-to-market wedge. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors logistics-integrated ingredient platforms with GCC export compliance infrastructure over standalone formulation specialists. Long-term viability hinges on traceability system deployment ahead of anticipated NFSA plant-origin mandates. The signal to watch is NFSA's positive-list publication timeline, which will compress approval-to-procurement windows and strand non-compliant inventory.| Strategic Initiative | Industry Significance |
|---|---|
| Red Sea Bulk Terminal Integration | Cuts lecithin landed costs for Greater Cairo compounders versus Alexandria routing. |
| Enzymatic Lecithin Refinement Investment | Enables clean-label positioning ahead of NFSA's anticipated plant-origin mandates. |
| GCC Export Documentation Systems | Unlocks Saudi and UAE retail chain procurement with lot-traceability compliance. |
| Phospholipid-Protein Hybrid Development | Consolidates foaming and fat-stabilization functions for Alexandria dairy processors. |
| Natural-Source Certification Pre-Positioning | Accelerates NFSA approval timelines when positive-list revisions take effect. |
Research Methodology
Desk research of trade flow databases, NFSA regulatory filings, and GCC Standardization Organization harmonization protocols preceded structured interviews with procurement directors at Greater Cairo dairy processors, technical service managers at multinational ingredient suppliers, Red Sea port logistics coordinators, and Nile Delta margarine plant managers. Secondary validation drew from Egyptian Organization for Standardization and Quality labeling directives, Codex Alimentarius additive specifications, and customs import records. Bottom-up demand modeling triangulated against top-down market sizing across product type and application segments.
Assumptions held fixed include NFSA's alignment trajectory with GCC standards, continued Red Sea port expansion timelines, and enzymatic modification technology cost curves. Segmentation dimensions modeled encompass product type, application, end-user category, and functionality requirements across the projection horizon. CAGRs derived from volume-weighted segment growth rates applied against base-year estimates. Industry-specific forecast inputs included Black Sea sunflower supply disruption scenarios and clean-label reformulation adoption curves among Egyptian exporters.
Macroeconomic conditions sit as an overlay; deviation in Egyptian pound exchange rates, Suez Canal transit fees, or regional conflict escalation would shift the trajectory. Forecasts reflect these assumptions and acknowledge regulatory revision timing, feedstock supply disruption, and food technologist labor scarcity as specific revision risks. Cross-checking against GCC import data and NFSA registration queue lengths is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Sustained Release Excipients Market
Food Additives and Ingredients
United Kingdom Anti Caking Market
Food Additives and Ingredients
Global Crystalline Maltitol Market
Food Additives and Ingredients
North America Food Micronized Salt Market
Food Additives and Ingredients
United Kingdom Food Acidulants Market
Food Additives and Ingredients
Low-Sodium Salt Substitute Market
Food Additives and Ingredients
Egypt Food Enzymes Market
Food Additives and Ingredients
DATEM Replacement Market
Food Additives and Ingredients
Citrus Fruit Coatings Market
Food Additives and Ingredients
Asia-Pacific Food Emulsifier Market
Food Additives and Ingredients
Feed Anti-Caking Agents Market
Food Additives and Ingredients
Beverage Stabilizer Market
Food Additives and Ingredients
China Food Acidulants Market
Food Additives and Ingredients
Natural Food Color Ingredients Market
Food Additives and Ingredients
Australia Food Enzymes Market
Food Additives and Ingredients
Brazil Food Acidulants Market