
 Australia Food Emulsifiers Market | 2026-2036
Australia Food Emulsifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Food Emulsifiers Market Outlook
FSANZ Standard 1.2.4 is expanding the compliance burden for imported emulsifier formulations, forcing reformulation investments from both domestic blenders and multinational suppliers. Cargill leverages its Australian oilseed crushing network to secure local lecithin feedstock. Kerry Group anchors its emulsifier portfolio through bakery application labs in Melbourne. DuPont Australia competes on enzyme-emulsifier hybrid systems for clean-label bread applications.
Food emulsifiers are surface-active agents with hydrophilic-lipophilic balance values typically between 3 and 8, designed to reduce interfacial tension between immiscible phases such as oil and water in processed foods. Lecithin dominates volume flows due to its label-friendly status and established supply chains through Australian oilseed processors. Monoglycerides and diglycerides sustain premium pricing in industrial bakery segments where dough conditioning and shelf-life extension justify higher ingredient costs. Powder forms lead institutional procurement channels, while liquid emulsifiers concentrate in high-throughput dairy and sauce manufacturing plants.
FSANZ maintains primary authority over food additive permissions and labeling disclosures, while the Department of Agriculture enforces biosecurity protocols on imported emulsifier raw materials. The ACCC monitors competition and anti-competitive conduct among ingredient suppliers. Stakeholders must track pending FSANZ proposals on novel emulsifier sources and assess how biosecurity inspection backlogs at Port Melbourne affect just-in-time manufacturing schedules.
Market Dynamics
Clean-label reformulation pressure from FSANZ Standard 1.2.4 is restructuring procurement patterns across Australian food manufacturing, forcing domestic blenders and importers to rebuild emulsifier portfolios around declaration-friendly ingredients.
Growth Catalysts
- Bakery industry reformulation:Industrial bakers in Victoria and New South Wales are accelerating clean-label transitions to meet FSANZ disclosure mandates, creating sustained demand for lecithin and enzyme-hybrid systems.
- Oilseed processing infrastructure:Australian canola and soybean crushing capacity expansion secures captive lecithin feedstock, shortening supply chains for domestic emulsifier manufacturers.
- Import gateway concentration:Port Melbourne and Port Botany biosecurity clearances favor established suppliers with compliance track records, consolidating procurement relationships around verified importers.
Market Restraints
- Specialty monoglyceride import dependency:Distilled monoglycerides for premium bakery applications rely on Southeast Asian chemical processors, exposing buyers to freight cost volatility and biosecurity inspection delays.
- FSANZ novel source approval timelines:Emerging plant-based emulsifier candidates face extended safety assessment protocols, delaying commercialization of oat and fava bean-derived alternatives.
- Enzyme stability limitations:Transglutaminase and lipase emulsifier hybrids require cold-chain integrity that exceeds regional distribution capabilities in Western Australia and Queensland.
Strategic Opportunities
- Tasmanian dairy expansion:Specialty cheese and functional dairy processing growth creates demand for tailored emulsifier systems with proven melt and texture control.
- Plant-based meat analogues:Extruded protein applications require novel emulsifier architectures to stabilize fat-water matrices in emerging alternative protein manufacturing.
- FSANZ code revision windows:Pending amendments to additive permissions present pathways for petitioning expanded uses of enzymatically modified lecithins in infant nutrition.
Industry Challenges
- Food technologist specialization gap:Reformulation expertise combining emulsion science with FSANZ label compliance remains scarce outside Melbourne and Sydney technical service hubs.
- Legacy dairy equipment retrofit costs:High-throughput plants in Gippsland and Murray-Darling regions face capital barriers to adopting liquid emulsifier dosing systems optimized for clean-label sauces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Food Emulsifiers Market |
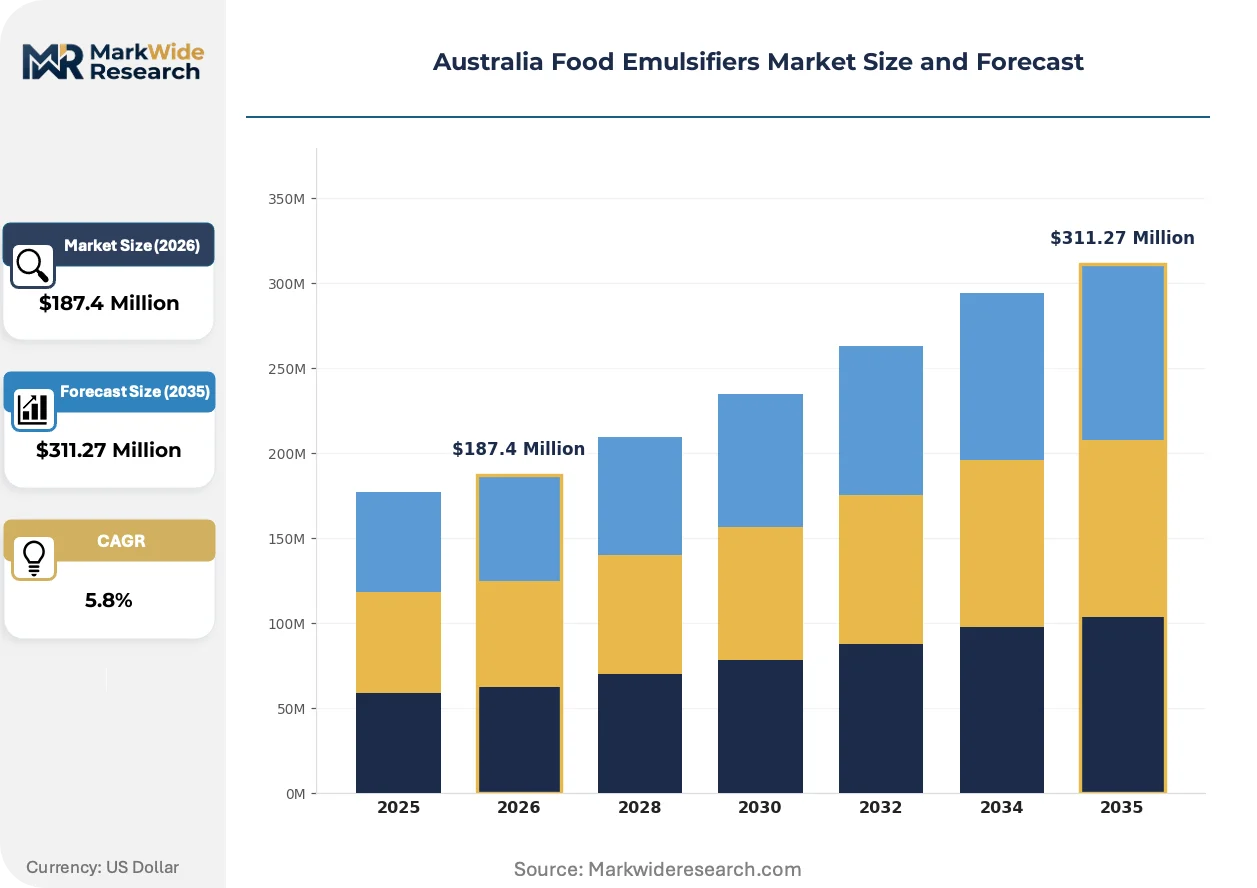
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lecithin, Monoglycerides, Diglycerides, Polyglycerol Esters Application: Baked Goods, Dairy Products, Sauces, Dressings Form: Powder, Liquid, Granulated, Paste End User: Food Manufacturers, Bakery Industry, Beverage Producers, Catering Services |
| Companies Covered | Archer Daniels Midland Company, Ingredion Incorporated, BASF SE, Cargill, Kerry Group, AAK, Corbion NV, DuPont Australia, Tate & Lyle Australia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Food Emulsifiers Market Strategic Shifts
Enzymatic processing and plant-protein hybridization are actively restructuring emulsifier functionality benchmarks across Australian food manufacturing, compressing the performance gap between synthetic and clean-label alternatives.
Enzyme-modified lecithin is rewriting emulsifier performance standards in industrial bread production. Major bakery groups in metropolitan Melbourne have adopted phospholipase-treated lecithin for dough conditioning, displacing synthetic DATEM in premium product lines. This enzymatic intervention enables equivalent volume and shelf-life extension while satisfying FSANZ clean-label declarations.
FSANZ consultation papers on novel food sources are tightening pre-market approval pathways for fermented emulsifier outputs. Bioprocess-derived glycolipids and rhamnolipids face extended toxicological review timelines, compressing investment horizons for domestic biotechnology ventures. Early-stage developers are redirecting R&D expenditure toward GRAS-recognized modifications rather than novel molecular architectures.
Direct supplier relationships are displacing traditional ingredient distributor networks in high-volume manufacturing segments. National bakery and dairy processors in Victoria and New South Wales now contract emulsifier formulators for application-specific technical service, bypassing merchant intermediaries. This disintermediation concentrates procurement leverage with technical buyers capable of specifying hydrophilic-lipophilic balance values and interfacial tension targets.
Australia Food Emulsifiers Market Segmentation
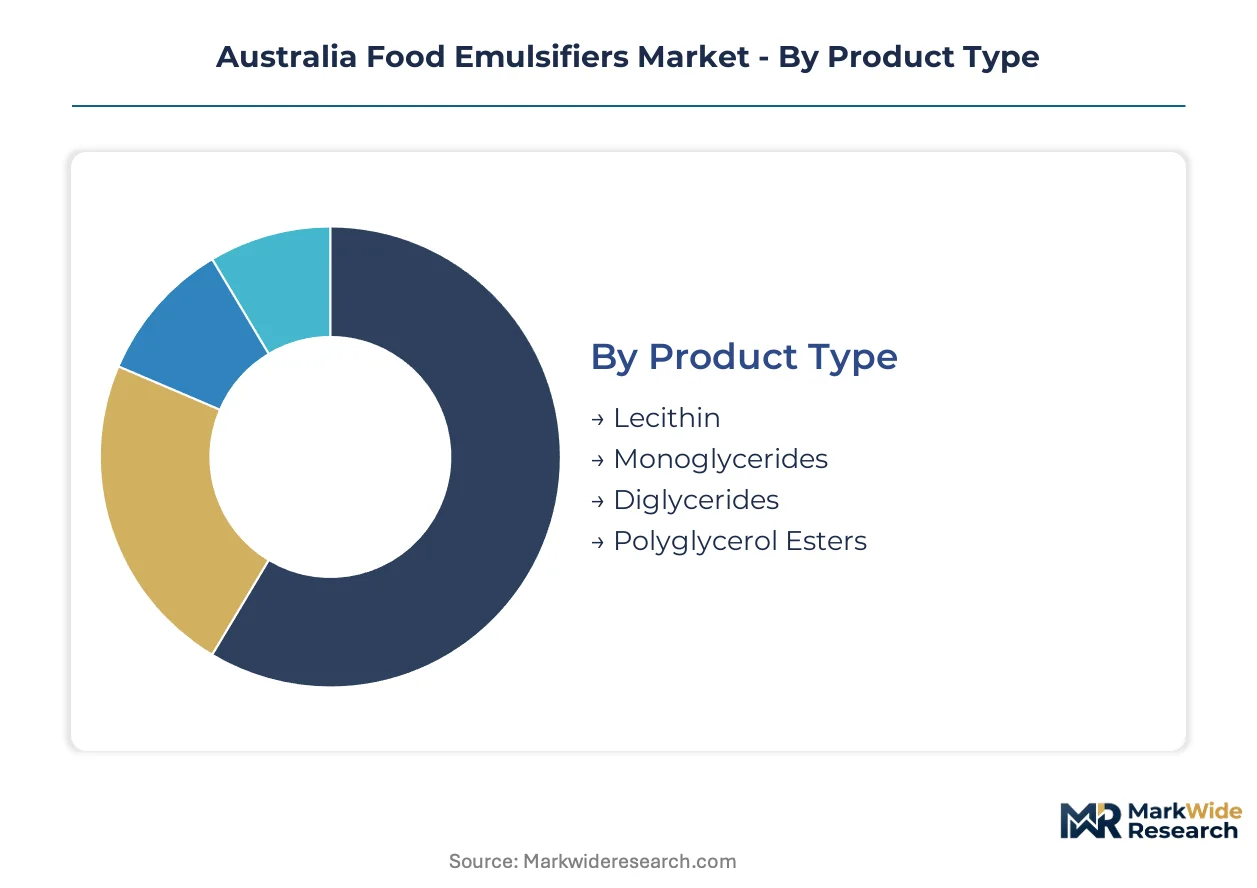
Emulsifier procurement decisions across Australian food manufacturing hinge on FSANZ additive permissions, biosecurity clearance pathways, and application-specific performance thresholds. Segment boundaries reflect divergent compliance burdens and supply chain reliability requirements.
Product Type:
FSANZ Standard 1.2.4 disclosure mandates create tiered certification pressures across molecular categories, with novel sources facing extended safety assessment timelines compared to established additives.
- Lecithin:Phospholipid mixtures extracted from canola and soybean oilseeds dominate volume flows through Australian crushing infrastructure. Victorian and New South Wales oilseed processors supply captive feedstock to domestic blenders, insulating procurement from import biosecurity bottlenecks at Port Melbourne.
- Monoglycerides:Distilled glycerol monoesters deliver superior dough conditioning and shelf-life extension in industrial bakery applications. Premium positioning in Melbourne metropolitan bakeries justifies higher ingredient costs against synthetic alternatives, though Southeast Asian chemical processors remain the primary import source.
- Diglycerides:Glycerol diesters function as cost-effective emulsifier extenders in margarine and shortening formulations.
- Polyglycerol Esters:Multifunctional surfactants stabilize high-water-activity sauces and dressings requiring extended freeze-thaw tolerance.
Lecithin sits at the top of the volume ranking, with enzyme-modified variants climbing the fastest.
Application:
End-use concentration in Victoria and New South Wales processing corridors shapes regional procurement patterns and technical service availability.
- Baked Goods:Industrial bread and pastry manufacturing consumes emulsifier systems optimized for dough rheology and crumb structure. Melbourne-based bakery groups drive reformulation toward phospholipase-treated lecithin, displacing DATEM in premium product lines to satisfy clean-label mandates.
- Dairy Products:Functional dairy processing in Gippsland and Tasmanian specialty cheese operations demands emulsifiers with proven melt stability and texture control. Liquid dosing systems predominate in high-throughput plants, though legacy equipment retrofit costs constrain adoption.
- Sauces:Viscosity maintenance and oil-in-water stability requirements concentrate demand in Port Botany-imported polyglycerol esters.
- Dressings:Cold-process mayonnaise and vinaigrette applications favor cold-soluble lecithin grades with rapid hydration kinetics.
Baked Goods commands the largest procurement volume, while Dairy Products gains share fastest on Tasmanian expansion and functional ingredient growth.
Form:
Physical state selection correlates with manufacturing scale, equipment infrastructure, and cold-chain distribution capabilities across Australian states.
- Powder:Free-flowing granular forms dominate institutional procurement channels and small-batch food manufacturers. Shelf stability and precise dosing accuracy support widespread adoption in bakery premix operations lacking liquid handling infrastructure.
- Liquid:Pumpable emulsifier concentrates optimize high-throughput dairy and sauce manufacturing with automated dosing integration. Queensland and Western Australia distribution faces cold-chain integrity constraints for enzyme-hybrid systems.
- Granulated:Dust-reduced particle engineering serves intermediate-scale processors seeking handling efficiency without liquid system investment.
- Paste:High-viscosity semisolids target artisan bakery segments requiring manual incorporation and extended workability windows.
Powder leads procurement volume, with Liquid expanding most quickly on dairy automation upgrades.
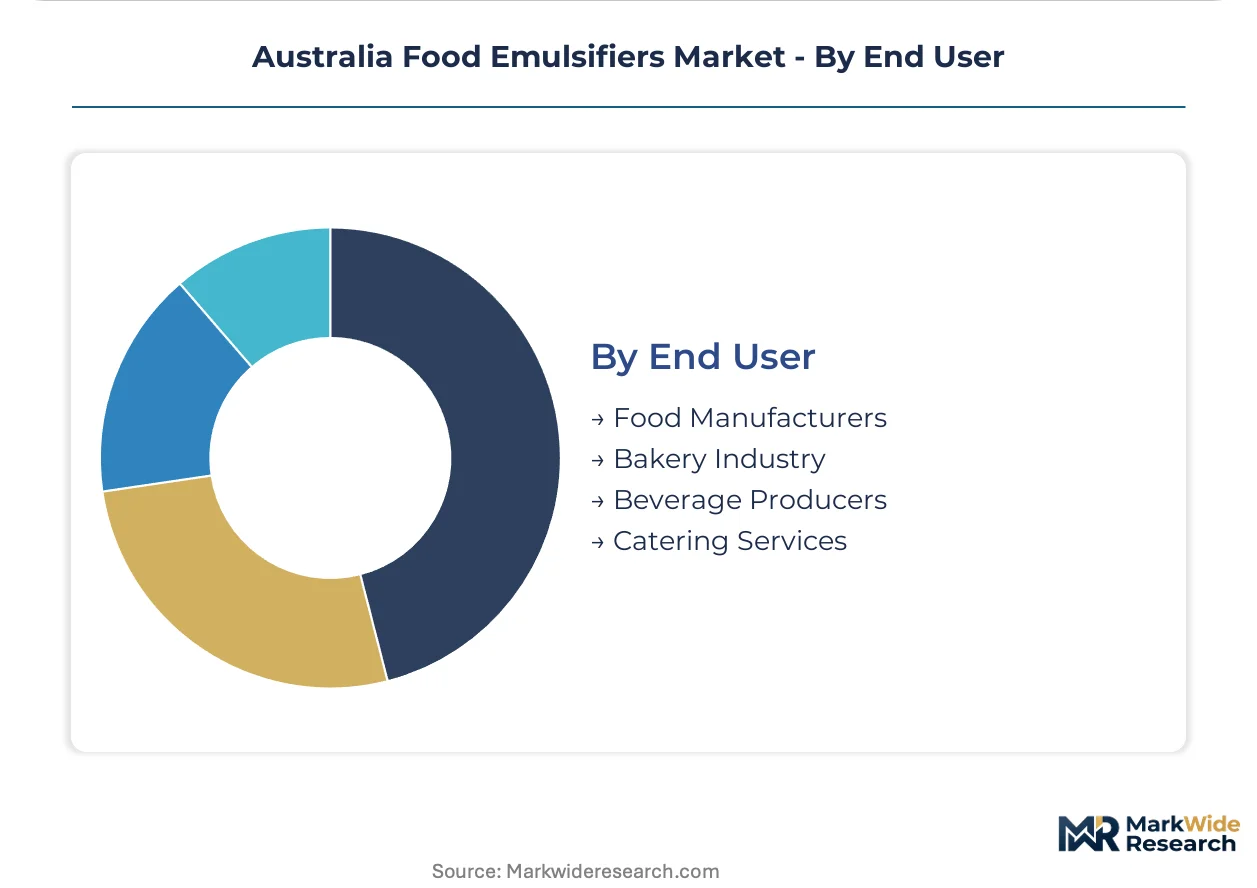
End User:
Buyer sophistication and technical specification capability determine direct supplier relationship formation versus distributor channel dependence.
- Food Manufacturers:National processors with in-house food technology capabilities contract directly with emulsifier formulators for application-specific systems. Technical buyers specify hydrophilic-lipophilic balance values and interfacial tension targets, bypassing traditional merchant intermediaries.
- Bakery Industry:Victoria and New South Wales industrial bakers anchor clean-label reformulation demand, concentrating procurement leverage among established suppliers with FSANZ compliance track records.
- Beverage Producers:Flavor emulsion stability requirements in functional drinks and plant-based milks create niche demand for tailored lecithin grades.
- Catering Services:Volume-scale foodservice operations prioritize cost-optimized monoglyceride-diglyceride blends for shortening and margarine applications.
Food Manufacturers represent the deepest procurement volume, with Beverage Producers on the steepest expansion trajectory from plant-based milk growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Australian food emulsifiers industry traces its modern scale to post-war industrialization of Victoria's food processing corridor, where oilseed crushing infrastructure established captive lecithin feedstock for domestic bakery and dairy manufacturing.
New South Wales
Port Botany biosecurity clearances anchor import flows for specialty monoglycerides and polyglycerol esters. FSANZ labeling mandates drive Sydney metropolitan bakers toward enzyme-modified lecithin systems. The Parramatta food technology hub concentrates reformulation expertise for clean-label sauce applications.
Victoria
Melbourne-based industrial bakeries consume the nation's largest emulsifier volumes for bread and pastry production. Victorian oilseed processors supply captive canola lecithin to domestic blenders, insulating procurement from import bottlenecks. Gippsland dairy plants retrofit liquid dosing systems for functional cheese manufacturing.
Queensland
Brisbane food manufacturers face cold-chain integrity constraints for enzyme-hybrid emulsifier distribution. The state's beverage sector drives niche demand for lecithin-stabilized flavor emulsions in functional drinks. Sunshine Coast plant-based meat startups trial novel fat-water matrix stabilizers.
Western Australia
Perth's isolation from eastern supply chains elevates inventory carrying costs for distilled monoglyceride imports. Local food technologists rely on Melbourne technical service hubs for FSANZ compliance guidance. Fremantle port biosecurity backlogs disrupt just-in-time manufacturing schedules for sauce processors.
Tasmania
Specialty cheese operations in the north-west create demand for tailored emulsifier systems with proven melt control. Tasmanian dairy expansion outpaces local technical service capacity, forcing reliance on Victorian supplier relationships. Hobart's small-scale food manufacturers favor powder lecithin for shelf-stable bakery premixes.
Australia Food Emulsifiers Market Competitive Environment
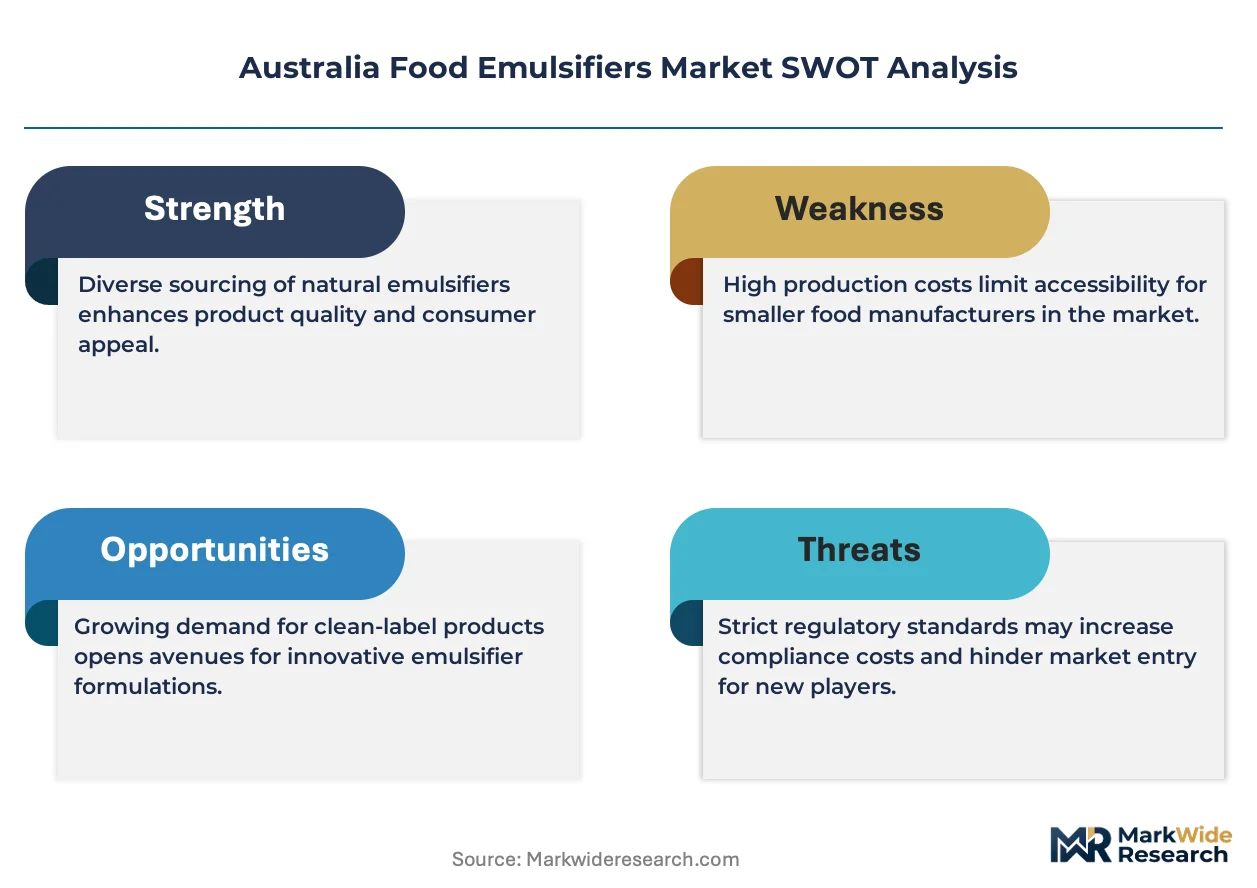
The competitive structure tilts toward multinational ingredient conglomerates with integrated oilseed processing and established FSANZ compliance track records. Domestic blenders compete on application-specific technical service, while import-reliant distributors face margin compression from biosecurity inspection delays. Two strategic archetypes dominate: vertically integrated agricultural processors and specialty lipid formulators with bakery application laboratories. Competitive moves concentrate on backward integration into oilseed crushing and direct contracting relationships with national food manufacturers.
Among North American agricultural conglomerates, Archer Daniels Midland Company and Cargill occupy positions anchored by oilseed processing infrastructure. European chemical and ingredient specialists BASF SE and Kerry Group exemplify the technical service archetype through Melbourne-based application laboratories. DuPont Australia represents the enzyme-hybrid system specialist tier, competing on clean-label bread applications. These named entities serve as anchors for understanding how procurement leverage concentrates with suppliers possessing verified biosecurity clearance pathways and in-house food technology capabilities.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| BASF SE |
| Cargill |
| Kerry Group |
| AAK |
| Corbion NV |
| DuPont Australia |
| Tate & Lyle Australia |
| Others |
Value Chain & Pricing Dynamics
Captive oilseed crushing infrastructure in Victoria anchors both supply security and pricing leverage for domestic lecithin processors, insulating Cargill and local blenders from import cost volatility while compressing margins for distributors reliant on Southeast Asian monoglyceride sources. This backward integration into canola and soybean feedstock creates tiered procurement power that reshapes how buyers negotiate across clean-label and synthetic emulsifier categories.
Pricing Analysis
The bundled-vs-unbundled service split separates technical service-inclusive contracts from commodity spot transactions. Three-tier pricing structure across premium, standard, and economy levels reflects FSANZ compliance certification, volume scale, and application complexity. Cost compression in distilled monoglycerides is intensifying because freight volatility from Southeast Asian chemical processors disrupts just-in-time bakery schedules. National food manufacturers with in-house food technology capabilities show least price sensitivity, while small-batch catering services and Hobart artisan bakeries face acute margin pressure.
Supply Chain Analysis
Direct-to-manufacturer channels handle national bakery and dairy processor demand, bypassing traditional ingredient distributors. Geographic supply concentrates in Australia for lecithin through Victorian oilseed crushing, Malaysia and Indonesia for distilled monoglycerides, and China for polyglycerol esters. Raw material dependencies center on canola and soybean phospholipids, glycerol feedstock, and enzymatic processing reagents. Single-source vulnerability runs through Port Melbourne biosecurity inspection backlogs, which disrupt just-in-time manufacturing for Gippsland dairy plants and Sydney sauce processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FSANZ Standard 1.2.4 functions as a regulatory compounder, accelerating clean-label reformulation investments as disclosure mandates force bakery and dairy manufacturers to rebuild emulsifier portfolios around declaration-friendly ingredients.
For Market Incumbents: To counter enzyme-hybrid system displacement of synthetic DATEM in Melbourne metropolitan bakeries, incumbents must deepen captive lecithin supply through oilseed crushing capacity expansion and anchor technical service relationships through Melbourne-based application laboratories. Certification investment in FSANZ novel source approval pathways secures first-mover positioning for oat and fava bean-derived alternatives.
For New Entrants and Emerging Players: Enzyme-modified lecithin with phospholipase treatment protocols offers a technology-first wedge against established synthetic emulsifier portfolios. Tasmanian specialty cheese operations and Queensland plant-based meat startups represent the most penetrable white-space targets, with direct technical service contracts replacing distributor-dependent go-to-market models.
For Investors and Strategic Acquirers: Roll-up economics work for domestic blenders with FSANZ compliance track records because biosecurity clearance bottlenecks at Port Melbourne and Port Botany consolidate procurement leverage around verified importers. Long-term viability hinges on backward integration into oilseed crushing or enzyme processing capabilities. Watch for FSANZ code revision windows on novel emulsifier sources as the inflection signal for expanded infant nutrition permissions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Cargill's Australian oilseed network secures captive lecithin feedstock against import biosecurity delays. |
| Enzyme Processing Capability Buildout | DuPont Australia leverages phospholipase-treated systems to displace synthetic DATEM in clean-label bread. |
| Melbourne Application Laboratory Expansion | Kerry Group anchors technical service relationships with direct contracting from national bakery processors. |
| FSANZ Novel Source Approval Petition | Early-stage developers redirect R&D toward GRAS-recognized modifications to compress toxicological review timelines. |
| Tasmanian Dairy Technical Service Partnership | Victorian supplier relationships fill local capability gaps as specialty cheese operations expand emulsifier demand. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with oilseed processing plant managers, bakery procurement leads, dairy technical directors, and FSANZ regulatory affairs specialists with secondary validation through customs trade data, FSANZ consultation papers, ACCC competition filings, and oilseed crushing capacity disclosures. Bottom-up emulsifier volume estimates from end-use consumption patterns triangulated against top-down oilseed processing output figures.
Comparable-period anchoring linked projection models to historical reference periods spanning pre- and post-FSANZ Standard 1.2.4 implementation phases across the analysis window. Segmentation dimensions modeled include molecular category, application end-use, physical form, and buyer sophistication tier. CAGRs derived from compound growth trajectory analysis incorporating oilseed crushing capacity expansion rates, bakery reformulation investment cycles, and biosecurity clearance throughput trends.
The model holds under stable FSANZ regulatory interpretation and intact Port Melbourne biosecurity processing capacity; deviation in novel source approval timelines or inspection backlog accumulation would shift volume and value trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Egg Wash Substitute Market
Food Additives and Ingredients
Australia Feed Additives Market
Food Additives and Ingredients
Argentina Food Additives Market
Food Additives and Ingredients
Food Glazing Agents Market
Food Additives and Ingredients
South Africa Food Colorants Market
Food Additives and Ingredients
South America Anti Caking Market
Food Additives and Ingredients
Japan Food Emulsifiers Market
Food Additives and Ingredients
Canada Food Acidulants Market
Food Additives and Ingredients
Phosphated Distarch Phosphate Market
Food Additives and Ingredients
Excipients Market
Food Additives and Ingredients
Lime Oil Market
Food Additives and Ingredients
Food Encapsulation Market
Food Additives and Ingredients
Mexico Food Emulsifiers Market
Food Additives and Ingredients
Food Grade Ammonium Carbonate Market
Food Additives and Ingredients
North America Food Coating Ingredients Market
Food Additives and Ingredients
South Africa Food Enzymes Market