
 Africa Feed Additives Market | 2026-2036
Africa Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Feed Additives Market Outlook
Pharmaceutical-grade amino acid specifications are rotating through the Africa Feed Additives Market as commercial livestock operations replace commodity premixes with precision-formulated diets. DSM Nutritional Products leverages its premix network to supply fortified lysine complexes to Nigerian and South African integrators. Cargill anchors supply security through its oilseed processing footprint that generates captive vitamin E and lecithin streams. Evonik Industries specializes in methionine chemistry, positioning its Biolys product line for ruminant and poultry applications across East and West Africa.
Feed additives comprise biologically active compounds including amino acids, organic acids, microbial cultures, and antioxidant molecules that are incorporated into compound feed at inclusion rates typically ranging from 0.01% to 2.0% by weight to enhance nutrient digestibility, preserve feed stability, or modulate gut microbiota. Amino acids command the deepest margin pools among product type segments because lysine and methionine carry irreplaceable roles in poultry and swine diet formulation. Probiotics represent the fastest-expanding category as antibiotic growth promoter bans in South Africa and Egypt push producers toward Bacillus-based direct-fed microbials. Poultry dominates end user demand structure due to short production cycles and high feed conversion ratios that magnify additive efficacy.
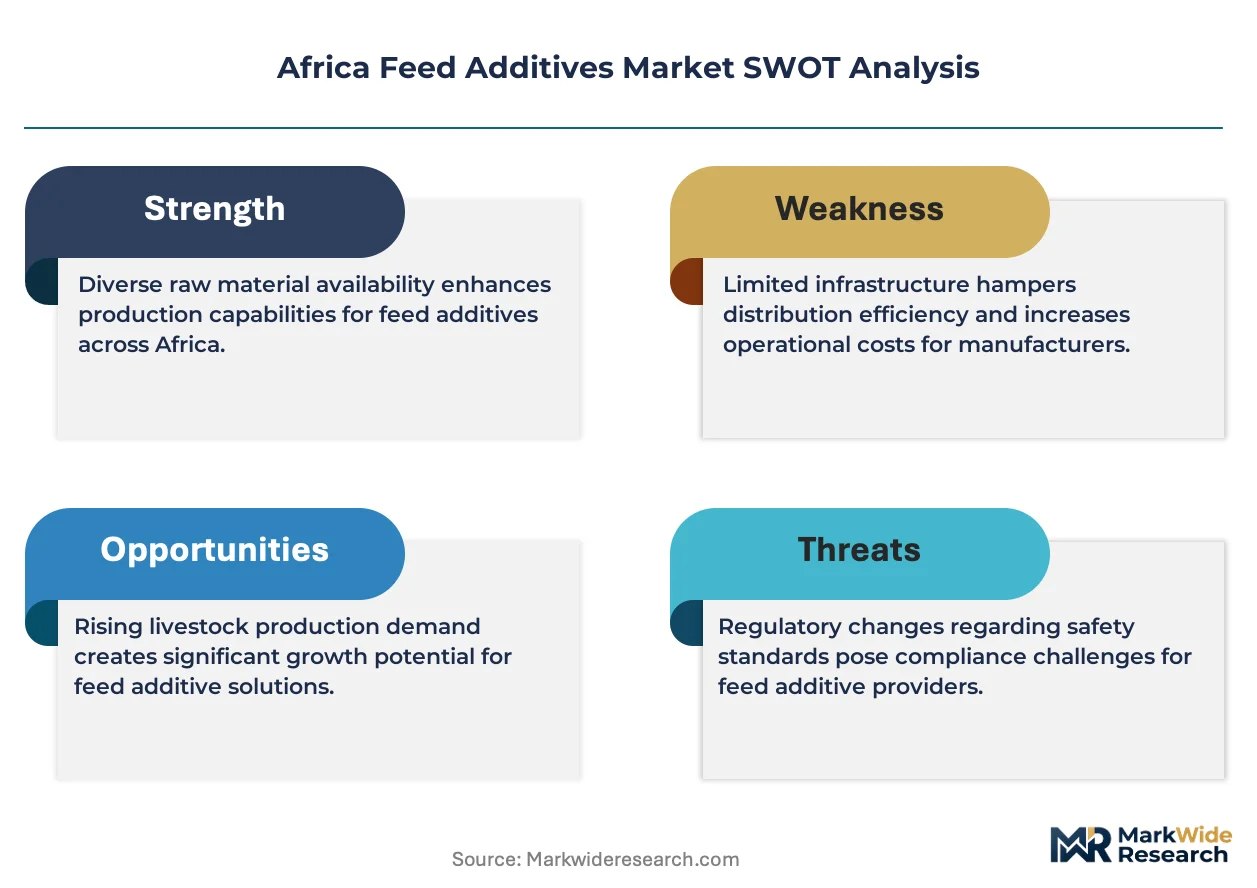
South Africa's Department of Agriculture enforces compulsory registration under Act 36 of 1947 for all feed additives sold domestically, while Egypt's National Food Safety Authority implements EU-aligned import protocols that restrict unapproved microbial strains. Nigeria's National Agency for Food and Drug Administration and Control operates a parallel veterinary product registration track that creates compliance friction for multinational suppliers. Stakeholders must monitor divergence between national feed additive approval lists and decide whether to pursue country-specific registrations or prioritize harmonized portfolio designs that satisfy the strictest jurisdiction.
Market Dynamics
The Africa Feed Additives Market is being fundamentally restructured by the antibiotic growth promoter bans cascading across South Africa and Egypt, which are forcing commercial livestock operations to rebuild their entire nutritional protocols around direct-fed microbials and precision amino acid dosing.
Growth Catalysts
- Regulatory Phase-Out of AGPs:South Africa's Department of Agriculture, Land Reform and Rural Development has enforced stricter maximum residue limits for veterinary substances, compelling integrators to adopt probiotic and organic acid alternatives.
- Integrated Poultry Expansion:Nigeria's Lagos-Ibadan corridor hosts rapidly scaling commercial feed milling operations that demand pharmaceutical-grade lysine and methionine complexes.
- Oilseed Processing Captive Supply:Local crushing capacity expansion generates downstream vitamin E and lecithin streams, reducing import dependency for critical antioxidant inputs.
Market Restraints
- Import-Derived Input Volatility:Synthetic amino acid and vitamin premix supplies concentrate through European and Asian manufacturing hubs, exposing African compounders to currency fluctuation and shipping cost spikes.
- Registration Asymmetry:Nigeria's NAFDAC operates a parallel veterinary product registration track that creates compliance friction against South Africa's Act 36 of 1947 framework, fragmenting approval pathways.
- Technical Efficacy Gaps:Bacillus-based direct-fed microbials show variable colonization rates in ruminant applications compared to monogastric systems, limiting cross-species portfolio leverage.
Strategic Opportunities
- East African Ruminant Underpenetration:Ethiopia and Kenya maintain minimal commercial feed additive penetration in dairy and beef operations, presenting first-mover positioning for methionine hydroxy analog suppliers.
- EU-Aligned Export Certification:Egypt's National Food Safety Authority import protocols already mirror European standards, enabling qualified Egyptian processors to serve as re-export hubs for EU-compliant additive formulations.
- Precision Nutrition Convergence:Near-infrared spectroscopy for real-time feed analysis is converging with cloud-based formulation software, allowing millers to dynamically adjust amino acid inclusion rates.
Industry Challenges
- Formulation Chemistry Talent Scarcity:Commercial feed mills across West Africa lack sufficient nutritional biochemists capable of balancing multi-enzyme and organic acid interactions in high-temperature pelleting conditions.
- Cold Chain Infrastructure Deficits:Probiotic viability requirements demand refrigerated storage and transport networks that remain underdeveloped outside South Africa's major urban corridors.
- Harmonization Timeline Compression:Stakeholders must simultaneously track divergent national approval lists while building portfolios that satisfy the strictest jurisdiction without duplicative registration costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Feed Additives Market |
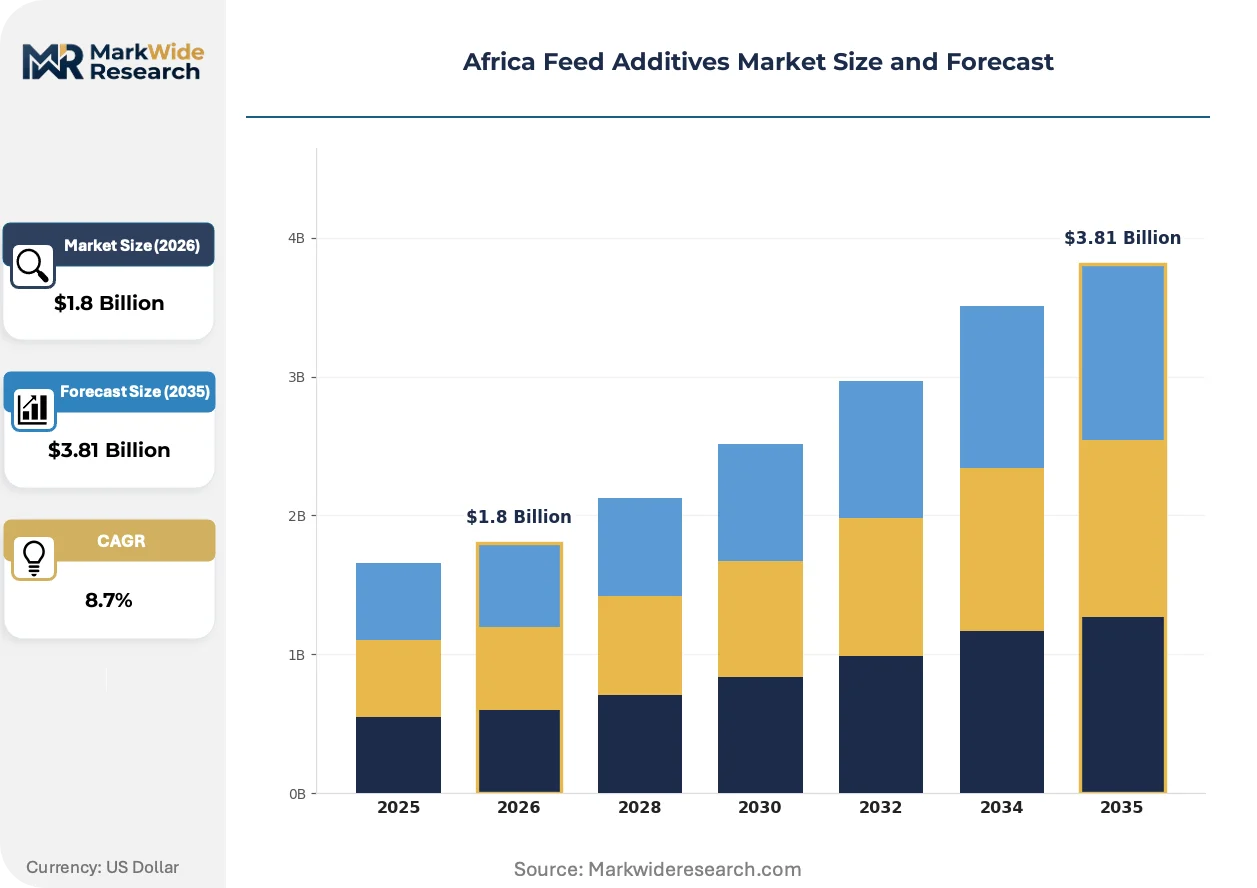
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antioxidants, Acidifiers, Amino Acids, Probiotics End User: Poultry, Swine, Ruminants, Aquaculture Form: Powder, Liquid, Granular, Pelleted Distribution Channel: Direct Sales, Online, Distributors, Retailers |
| Companies Covered | Adisseo, Archer Daniels Midland, DSM Nutritional Products, Evonik Industries, BASF, Nutreco, Cargill, Kemin Industries, Brenntag, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Feed Additives Market Strategic Shifts
Precision fermentation and enzymatic processing technologies are rewriting cost structures for amino acid production, while regulatory alignment pressures and buyer consolidation are compressing traditional distribution hierarchies across the continent.
Precision fermentation for amino acid manufacturing is bifurcating the Africa Feed Additives Market into premium pharmaceutical-grade supply and commodity chemical-grade alternatives. Nigerian and South African integrators with captive breeding operations are adopting the higher-specification lysine complexes at accelerated procurement cycles. This technological divide is compressing margin pools for intermediate-grade suppliers while rewarding fermentation-scale specialists with dedicated African distribution infrastructure.
South Africa's Act 36 of 1947 compulsory registration framework is tightening enforcement timelines for feed additive importers, with the Department of Agriculture now requiring enhanced stability documentation for heat-labile vitamins. Industrial consequence includes extended product launch cycles and elevated compliance costs for microbial strain introductions. Poultry-focused compounders are responding by consolidating supplier relationships toward premix partners with established local regulatory affairs capabilities.
Buyer concentration among integrated poultry operations is consolidating procurement authority away from independent feed distributors toward direct manufacturer relationships. Large-scale millers in Nigeria's Southwest and South Africa's Mpumalanga region now negotiate amino acid and vitamin premix contracts through centralized technical teams rather than decentralized purchasing. This channel compression is most visible in methionine sourcing, where volume commitments increasingly determine pricing tiers and technical service allocation.
Africa Feed Additives Market Segmentation
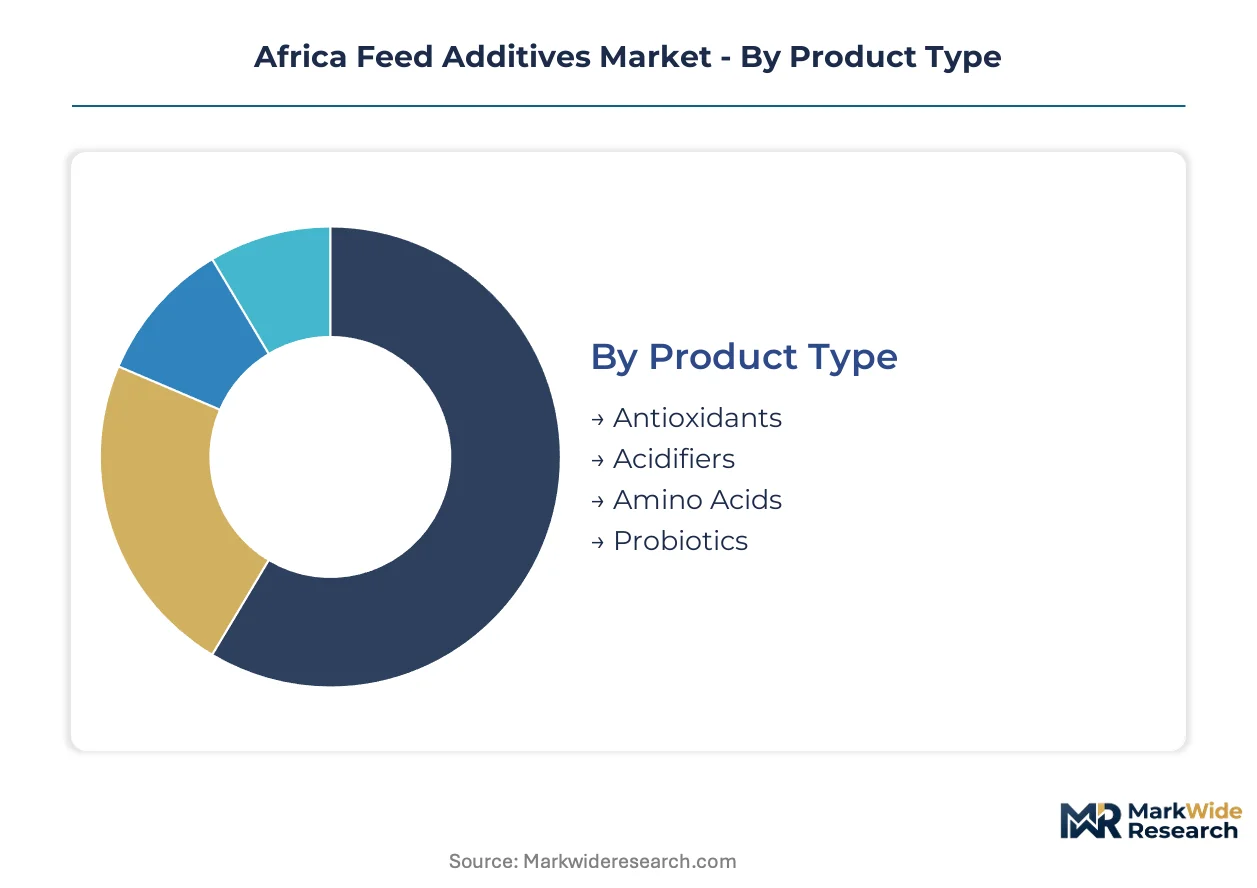
Feed additive segmentation across Africa reflects divergent margin economics between commodity-grade inputs and precision-formulated compounds. Understanding where value concentrates by product chemistry, species application, and physical form enables suppliers to align technical service investments with profit pool depth.
Product Type:
Amino acids and probiotics capture the deepest margin pools, while antioxidants and acidifiers compete on volume throughput with thinner unit economics.
- Amino Acids:Lysine and methionine carry irreplaceable roles in poultry and swine diet formulation, with pharmaceutical-grade specifications commanding premium positioning. Nigerian and South African integrators are accelerating procurement cycles for fortified lysine complexes as they replace commodity premixes.
- Probiotics:Bacillus-based direct-fed microbials represent the category expanding most quickly as antibiotic growth promoter bans in South Africa and Egypt force nutritional protocol rebuilding. Variable colonization rates in ruminant applications limit cross-species portfolio leverage.
- Antioxidants:Vitamin E and lecithin streams from local oilseed crushing reduce import dependency for critical preservation inputs.
- Acidifiers:Organic acids function as AGP alternatives in monogastric systems, though thermal stability challenges persist in high-temperature pelleting conditions.
The dominant share belongs to amino acids, while probiotics is closing the gap fastest.
End User:
Species-specific feed conversion efficiency dictates additive ROI and determines customer willingness to pay for premium formulations.
- Poultry:Short production cycles and high feed conversion ratios magnify additive efficacy, concentrating demand among integrated operations in Nigeria's Lagos-Ibadan corridor and South Africa's Mpumalanga region.
- Swine:Precision amino acid dosing delivers measurable margin improvement for commercial producers, though penetration remains below poultry levels across West Africa.
- Ruminants:Minimal commercial feed additive penetration in Ethiopia and Kenya dairy and beef operations creates first-mover positioning for methionine hydroxy analog suppliers.
- Aquaculture:Emerging demand from Egyptian and Nigerian aquafeed producers requires specialized formulation expertise distinct from terrestrial livestock applications.
Poultry commands the largest volume position, though ruminants shows the steepest expansion trajectory as commercial feed systems penetrate East African markets.
Form:
Physical presentation determines handling economics, inclusion precision, and compatibility with existing mill infrastructure.
- Powder:Dominant format for amino acids and vitamin premixes, enabling precise micro-dosing in automated batching systems at large-scale Nigerian and South African mills.
- Liquid:Preferred for acidifiers and certain probiotic applications where homogeneous distribution in mash feeds is critical.
- Granular:Reduced dust generation improves mill operator safety and reduces cross-contamination risk in multi-species facilities.
- Pelleted:Heat-stable formulations required for post-pelleting application of thermolabile additives, extending product launch cycles due to enhanced stability documentation requirements.
Powder maintains the highest share, while liquid is gaining ground fastest in antibiotic-free formulation transitions.
Distribution Channel:
Channel selection reflects buyer scale concentration and technical service requirements for complex additive implementation.
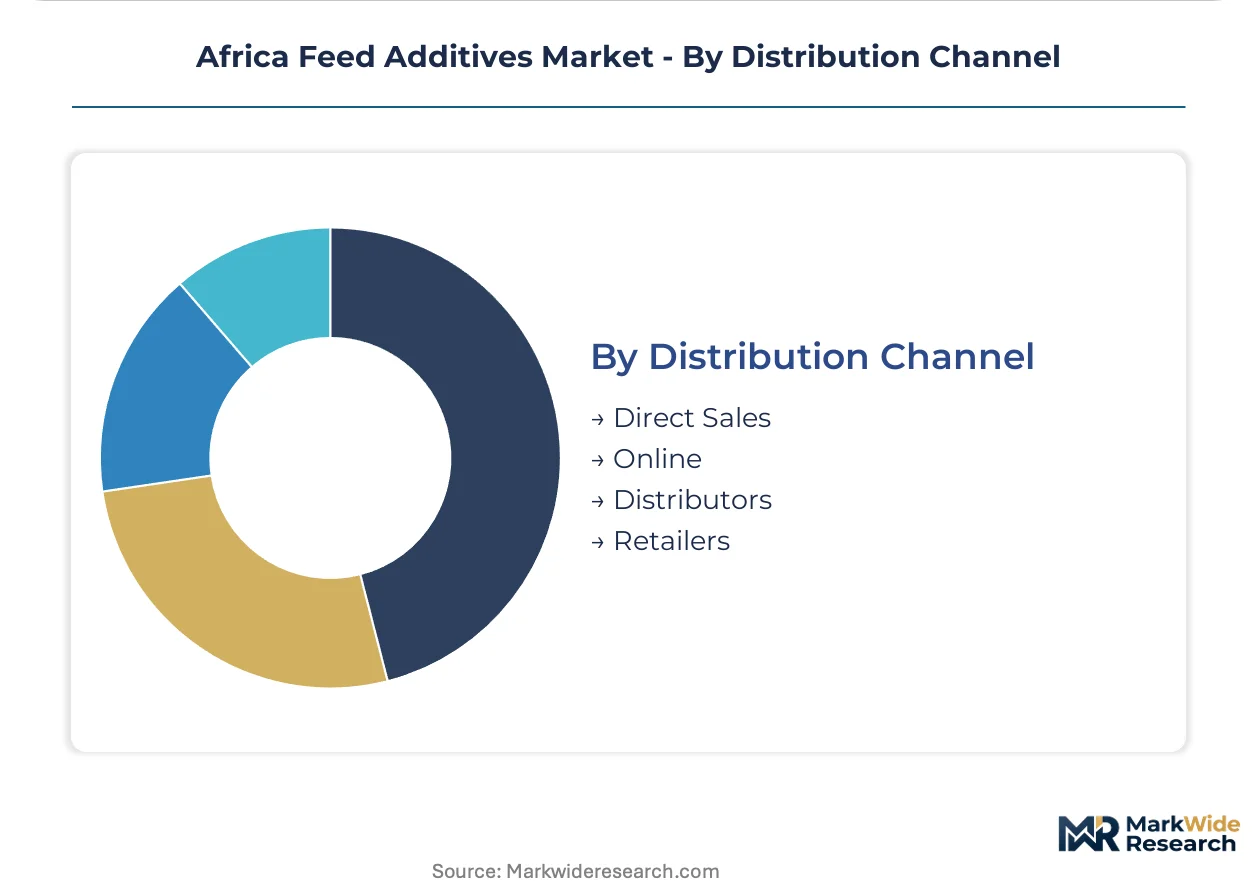
- Direct Sales:Large-scale millers in Nigeria's Southwest and South Africa's Mpumalanga region negotiate amino acid and vitamin premix contracts through centralized technical teams, consolidating procurement authority away from independent distributors.
- Distributors:Remains critical for mid-tier compounders lacking in-house nutritional biochemistry capabilities, particularly across West African markets.
- Online:Emerging channel for standardized vitamin and mineral premixes, constrained by cold chain requirements for probiotic viability.
- Retailers:Serves smallholder and backyard producer segments with pre-formulated concentrates, though volume contribution remains marginal.
Direct sales holds the leading position, while online channels are climbing the fastest as digital procurement platforms penetrate commercial feed operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Amino acid manufacturing capacity concentrates in South Africa and Nigeria, where oilseed crushing infrastructure generates captive vitamin streams and integrated poultry operations drive pharmaceutical-grade lysine procurement. Regulatory divergence between national approval frameworks fragments import pathways and elevates compliance costs for cross-border suppliers.
South Africa
Integrated poultry operations in Mpumalanga and KwaZulu-Natal drive methionine and lysine consumption at commercial feed mills. The Department of Agriculture, Land Reform and Rural Development enforces Act 36 of 1947 compulsory registration with enhanced stability documentation for heat-labile vitamins. Cape Town and Durban serve as import gateways for European and Asian premix supplies, with cold chain infrastructure concentrated in these coastal corridors.
Nigeria
The Lagos-Ibadan corridor hosts rapidly scaling compound feed operations demanding precision-formulated amino acid complexes. NAFDAC operates a parallel veterinary product registration track that creates compliance friction against South African standards. Ogun State industrial zones concentrate commercial milling capacity where large-scale integrators negotiate direct manufacturer contracts for lysine and methionine.
Egypt
Aquafeed and poultry producers along the Nile Delta generate demand for specialized additive formulations distinct from terrestrial livestock applications. The National Food Safety Authority implements EU-aligned import protocols that restrict unapproved microbial strains. Alexandria and Damietta function as re-export hubs for EU-compliant additive formulations serving North African markets.
Ethiopia
Commercial dairy and beef operations in the Central Highlands remain minimally penetrated by feed additives, presenting first-mover positioning for methionine hydroxy analog suppliers. The Ethiopian Agricultural Transformation Agency promotes commercial feed system adoption through subsidized extension services. Addis Ababa and Bishoftu concentrate emerging feed milling capacity serving peri-urban livestock operations.
Kenya
Dairy cooperatives in the Rift Valley and Central Province drive nascent demand for rumen-protected amino acids and probiotic supplements. The Kenya Bureau of Standards enforces feed safety regulations aligned with Codex Alimentarius guidelines. Nairobi and Nakuru host the dominant commercial feed manufacturers expanding precision nutrition services to medium-scale producers.
Africa Feed Additives Market Competitive Environment
Concentration sits with multinational nutrition specialists that combine fermentation-scale amino acid production with established African distribution infrastructure. The market structure tiers between premium pharmaceutical-grade suppliers and commodity chemical-grade alternatives, with regulatory affairs capabilities determining competitive positioning. Three archetypes dominate: integrated nutrition platforms with captive premix networks, fermentation specialists with dedicated African technical service teams, and regional distributors bridging multinational supply with local mill relationships. Dominant competitive moves include backward integration into oilseed crushing for captive vitamin streams and strategic partnerships with large-scale integrators for direct amino acid supply contracts.
Among the nutrition-specialist tier, DSM Nutritional Products and Evonik Industries occupy positions exemplifying pharmaceutical-grade amino acid supply with dedicated African distribution infrastructure. Cargill anchors the integrated platform archetype through oilseed processing footprints that generate downstream vitamin E and lecithin streams. These three companies represent distinct strategic approaches to serving Nigerian and South African integrators transitioning from commodity premixes toward precision-formulated diets.
| Leading Market Players |
|---|
| Adisseo |
| Archer Daniels Midland |
| DSM Nutritional Products |
| Evonik Industries |
| BASF |
| Nutreco |
| Cargill |
| Kemin Industries |
| Brenntag |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical-grade amino acid substitution for commodity premixes redraws supply geography toward fermentation-scale manufacturing hubs in Europe and Asia while compressing margin pools for intermediate-grade suppliers serving Nigerian and South African integrators. This input replacement dynamic simultaneously elevates pricing power for certified-grade suppliers and exposes compounders to currency-driven cost volatility.
Pricing Analysis
South Africa's Act 36 of 1947 dictates the pricing tier structure by mandating enhanced stability documentation that fragments approval pathways and elevates compliance costs. Three-tier pricing structure across pharmaceutical-grade, feed-grade, and commodity-grade levels separates DSM Nutritional Products and Evonik Industries from regional distributors. Cost compression in the commodity tier is intensifying because local oilseed crushing generates captive vitamin E streams. Mid-tier compounders across West Africa show highest price sensitivity, while integrated poultry operations in Nigeria's Lagos-Ibadan corridor prioritize formulation precision over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Africa trade lanes elevate inbound logistics costs for synthetic amino acid and vitamin premix shipments through Durban and Lagos ports. Supply concentration rests on manufacturing hubs in China, the Netherlands, and Singapore for critical lysine and methionine inputs. Raw material dependencies center on corn-derived fermentation feedstocks, petroleum-based chemical precursors, and oilseed crush streams. Single-source vulnerability runs through European microbial strain suppliers facing Egypt's EU-aligned import restrictions. Distribution runs through Cargill's oilseed processing footprint and DSM's premix network serving direct manufacturer contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as antibiotic growth promoter bans across South Africa and Egypt force nutritional protocol rebuilding that penetrates previously additive-naive livestock operations. Commercial feed system adoption in East African dairy and beef sectors extends the penetration runway.
For Market Incumbents: Shield formulation chemistry expertise and regulatory affairs capabilities against emerging regional distributors building local mill relationships. Prioritize backward integration into oilseed crushing for captive vitamin E and lecithin streams that reduce import dependency. Consolidate supplier relationships with large-scale Nigerian integrators through centralized technical service teams rather than decentralized purchasing channels. For New Entrants and Emerging Players: Differentiate on cold chain logistics capabilities for probiotic viability in markets outside South Africa's coastal corridors. Target Ethiopia's Central Highlands and Kenya's Rift Valley dairy cooperatives with methionine hydroxy analog formulations for underpenetrated ruminant applications. Establish go-to-market partnerships with the Ethiopian Agricultural Transformation Agency's subsidized extension services. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional distributors bridging multinational supply with West African mill relationships. Long-term viability hinges on regulatory harmonization trajectory across NAFDAC, Act 36 of 1947, and EU-aligned Egyptian protocols. Watch for inflection signals in near-infrared spectroscopy adoption enabling real-time amino acid inclusion adjustments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Cargill's captive vitamin E streams reduce import exposure for Nigerian compounders. |
| Regulatory Affairs Capability Investment | DSM's premix network navigates NAFDAC and Act 36 of 1947 divergence for faster product launches. |
| Precision Fermentation Scale-Up | Evonik's Biolys manufacturing bifurcates supply into pharmaceutical-grade and commodity-grade tiers. |
| Cold Chain Infrastructure Partnership | Probiotic viability requirements demand refrigerated networks beyond South Africa's urban corridors. |
| Direct Manufacturer Contract Consolidation | Large-scale millers in Ogun State and Mpumalanga centralize amino acid procurement authority. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interviews with feed mill technical directors, poultry integration nutritionists, regulatory affairs managers at additive suppliers, and distribution channel partners. Secondary validation drew from South Africa's Department of Agriculture registration databases, NAFDAC veterinary product filings, Egyptian National Food Safety Authority import protocols, customs and trade flow records, and SEC filings of listed nutrition companies. Bottom-up volume modeling triangulated against top-down market sizing across the projection horizon.
Across the analysis window, forecasts segmented by amino acid grade tier, species application, physical form, and national regulatory cluster. CAGRs were derived from growth driver elasticity modeling against livestock production forecasts and feed conversion ratio improvements. Industry-specific inputs included antibiotic growth promoter ban implementation timelines, oilseed crush capacity expansion schedules, and precision fermentation cost curve trajectories.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of residue limits, stable currency conditions for import-dependent inputs, and cold chain infrastructure development would require recalibration. Forecasts reflect documented assumptions about commercial feed system penetration rates and integrator consolidation trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Lactose Monohydrate Market
Food Additives and Ingredients
AKD Emulsifier Market
Food Additives and Ingredients
North America Food Preservatives Market
Food Additives and Ingredients
Pea Starch Concentrate Market
Food Additives and Ingredients
Global Edible Films and Coatings for Fruits and Vegetables Market
Food Additives and Ingredients
Africa Food Additives Market
Food Additives and Ingredients
United States Food Acidulants Market
Food Additives and Ingredients
France Anti Caking Market
Food Additives and Ingredients
France Food Emulsifiers Market
Food Additives and Ingredients
Russia Food Enzymes Market
Food Additives and Ingredients
India Food Color Industry Market
Food Additives and Ingredients
Beverages Additives Market
Food Additives and Ingredients
Food Inclusions Market
Food Additives and Ingredients
India Food Additives Market
Food Additives and Ingredients
Africa Food Stabilizers Market
Food Additives and Ingredients
Global Canthaxanthin Market