
 South Africa Food Enzymes Market | 2026-2036
South Africa Food Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Food Enzymes Market Analytics
South African enzyme production capacity is consolidating around Gauteng-based bioprocessing facilities and coastal fermentation plants. Novozymes A/S leverages its regional technical service network to anchor industrial baking accounts. DuPont de Nemours, Inc competes through specialized protease blends for meat tenderization. Kerry Group plc sustains formulation partnerships with mid-tier dairy processors across the Western Cape.
Food enzymes constitute protein-based biocatalysts, typically operating at 30–70°C and pH 4.0–8.0, that accelerate hydrolysis, oxidation, or isomerization reactions in raw and processed food matrices. Lipase dominates dairy fat modification applications where cold-active variants reduce energy inputs during cheese ripening. Powder formulations lead the form segment due to superior shelf stability under South Africa's variable ambient storage conditions, while liquid enzymes gain share in automated beverage dosing systems.
South Africa's Department of Health enforces food additive labeling under Regulation R638, compelling enzyme suppliers to declare processing aids on finished product specifications. The country's national standards body, the South African Bureau of Standards, certifies enzyme purity grades through SANS codes aligned with Codex Alimentarius frameworks. Stakeholders must monitor impending amendments to Regulation R638 that could reclassify certain enzyme preparations as additives rather than processing aids, altering compliance pathways and reformulation costs.
Market Dynamics
Regulatory reclassification pressure under South Africa's Department of Health is compressing formulation timelines and forcing enzyme suppliers to rebuild compliance dossiers ahead of anticipated amendments to Regulation R638.
Growth Catalysts
- Clean-label bakery expansion:Johannesburg and Cape Town manufacturers are reformulating bread and pastry lines to eliminate chemical conditioners, creating pull for label-friendly protease and amylase systems.
- Regulation R638 alignment:The Department of Health's processing aid disclosure mandates are standardizing supplier documentation, reducing buyer due diligence friction for certified enzyme preparations.
- Gauteng industrial corridor concentration:Powder-form protease demand clusters around Pretoria-Witwatersrand-Vereeniging manufacturing zones, enabling localized technical service and faster batch customization.
Market Restraints
- Import dependency for specialty lipases:Cold-active variants for dairy applications arrive primarily through European supply chains, exposing buyers to currency volatility and extended lead times.
- Fermentation capacity concentration:Coastal fermentation plants and Gauteng bioprocessing facilities represent limited domestic production nodes, constraining surge capacity during demand spikes.
- Regulatory reclassification risk:Pending amendments to Regulation R638 could shift certain enzyme preparations from processing aid to additive status, triggering reformulation costs and label redesign cycles.
Strategic Opportunities
- Western Cape dairy processor partnerships:Mid-tier cheese and yogurt manufacturers remain undersupplied with customized lipase blends, opening formulation service contracts for technical suppliers.
- Automated beverage dosing systems:Liquid enzyme formats gain traction in Cape Town's fruit juice and brewing sectors, creating channel expansion beyond traditional powder distribution.
- SANS certification premium tier:South African Bureau of Standards purity grades aligned with Codex Alimentarius frameworks enable suppliers to command price differentiation against uncertified imports.
Industry Challenges
- Bioprocessing technician scarcity:Gauteng-based facilities report acute shortages of fermentation specialists capable of optimizing enzyme yield under variable ambient temperature conditions.
- Legacy equipment integration:Powder-to-liquid conversion in automated dosing systems requires retrofitting dosing pumps and calibration protocols, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Food Enzymes Market |
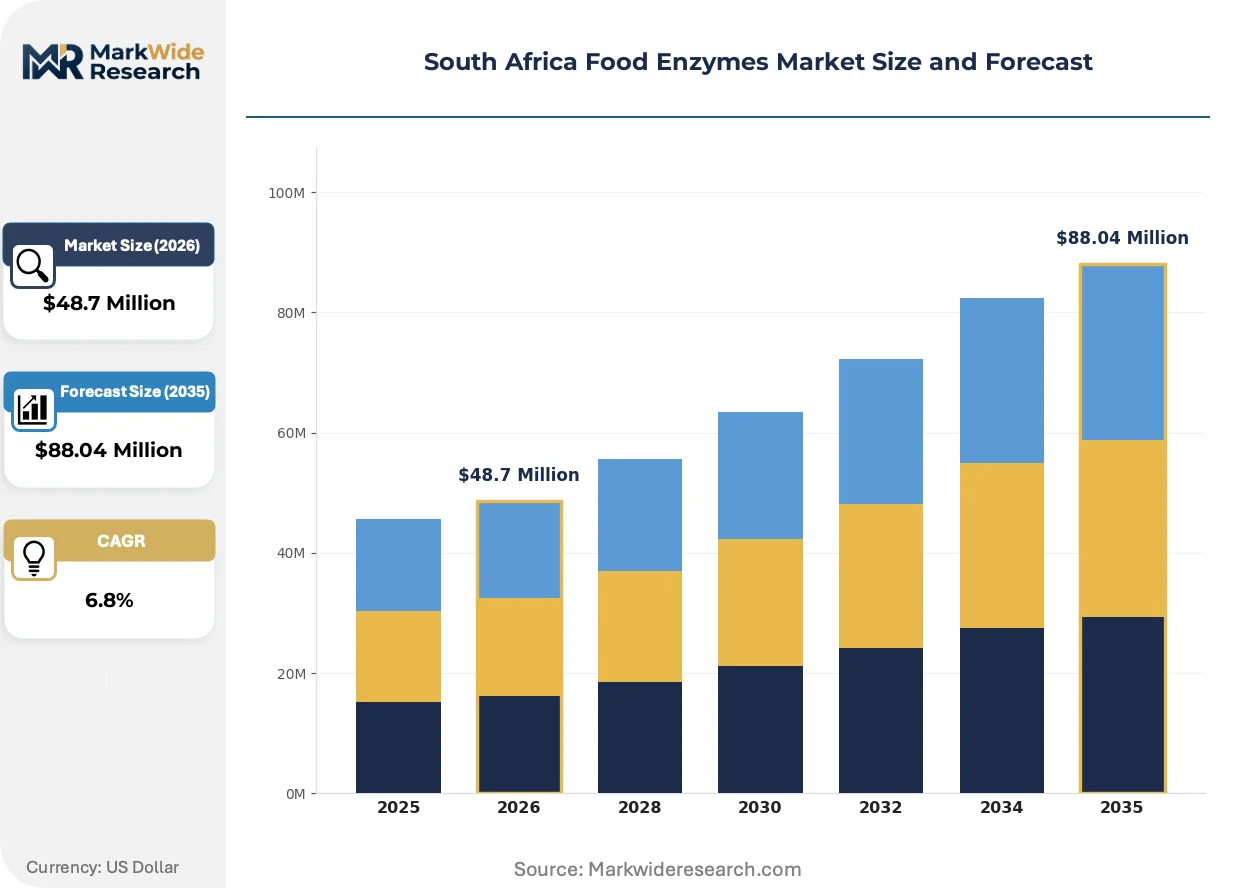
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Enzyme Type: Amylase, Protease, Lipase, Cellulase Application: Baking, Dairy, Beverages, Meat Processing Form: Liquid, Powder, Granular, Tablets Customer Type: Food Manufacturers, Beverage Producers, Retailers, Restaurants |
| Companies Covered | Novozymes A/S, DuPont de Nemours, Inc, Koninklijke DSM N.V., Associated British Foods plc, Kerry Group plc, Chr. Hansen Holding A/S, AB Enzymes GmbH, BASF SE, Amano Enzyme Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Food Enzymes Market Evolving Landscape
Enzyme stabilization and delivery formats are undergoing rapid revision as South African manufacturers balance shelf-life requirements against automated processing needs in variable climate conditions.
Cold-active lipase variants optimized for cheese ripening at reduced temperatures are overtaking standard mesophilic formulations in Western Cape dairy operations. Artisan and mid-scale cheese producers in Stellenbosch and Paarl are adopting these enzymes to cut energy inputs during aging. The shift is overtaking conventional lipase procurement patterns and compressing payback periods for energy efficiency investments.
South Africa's Department of Health is tightening enforcement of Regulation R638 disclosure requirements for processing aids used in baked goods and meat products. Industrial bakers in Johannesburg now face mandatory enzyme declaration on finished product specifications, compelling suppliers to standardize purity documentation. The Western Cape's export-oriented meat processors are responding fastest, pre-emptively aligning with Codex Alimentarius frameworks to maintain EU market access.
Direct supplier relationships are displacing traditional distribution intermediaries among Gauteng's large-scale bakery groups. Technical service agreements now bundle enzyme supply with application support, replacing arm's-length chemical trading. This pattern is most visible in Johannesburg's industrial corridor, where three major bread manufacturers have consolidated procurement under single-source enzyme partnerships with embedded formulation laboratories.
South Africa Food Enzymes Market Segmentation
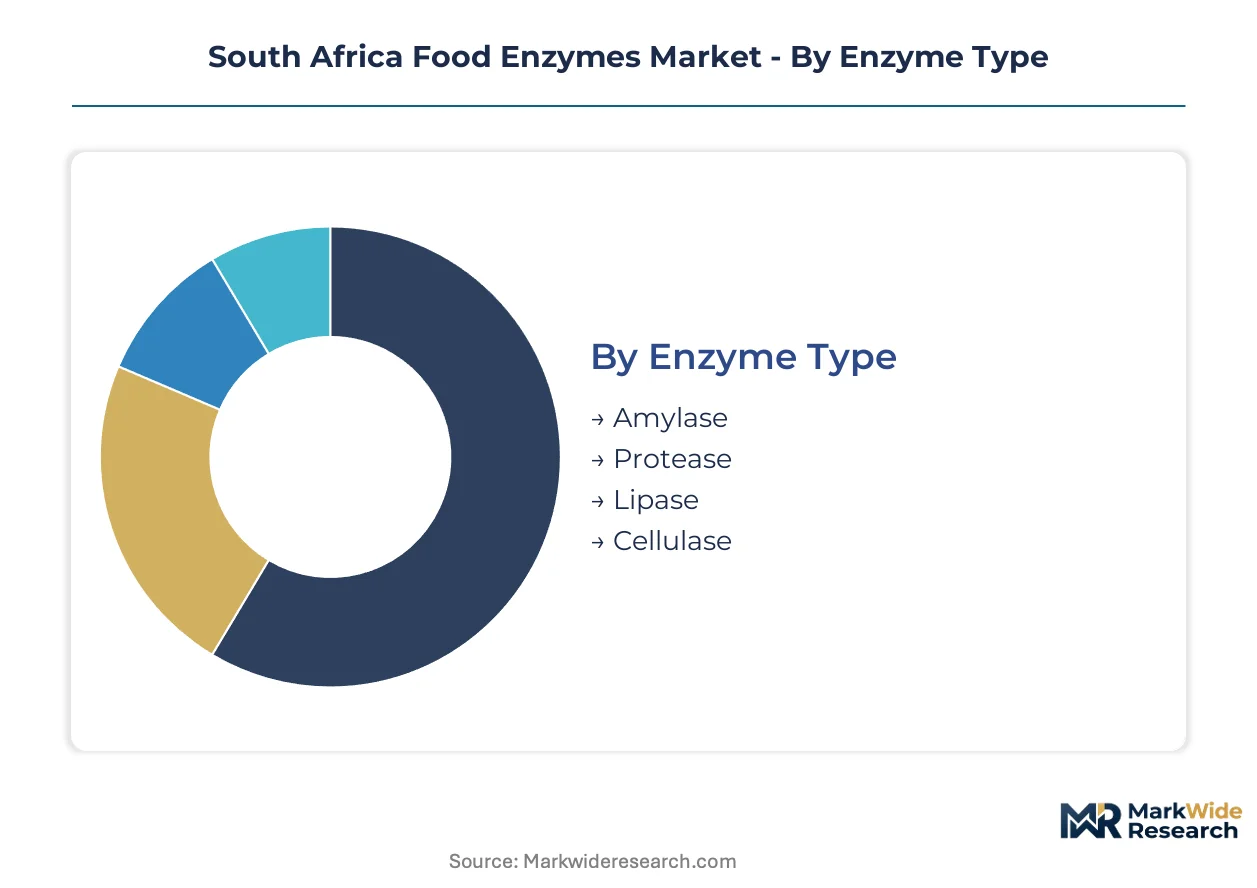
Enzyme procurement patterns in South Africa diverge sharply across application requirements, storage infrastructure, and technical service intensity. Each segmentation dimension reveals distinct capital deployment priorities and margin structures for suppliers operating within the country's regulatory framework.
Enzyme Type:
Capital intensity peaks with lipase production due to cold-active variant development and fermentation optimization under variable ambient conditions.
- Amylase:Starch-hydrolyzing enzymes catalyze dextrinization in bread and brewing applications. Johannesburg industrial bakers drive concentrated demand amid clean-label reformulation mandates from the Department of Health.
- Protease:Protein-cleaving biocatalysts operate across meat tenderization and dough conditioning. Gauteng's Pretoria-Witwatersrand-Vereeniging corridor anchors powder-form procurement for large-scale bakery groups.
- Lipase:Fat-modifying enzymes with cold-active specifications reduce energy inputs during Western Cape cheese ripening. Stellenbosch and Paarl artisan producers are overtaking standard mesophilic procurement patterns.
- Cellulase:Cellulose-degrading catalysts support fruit juice clarification and fiber modification. Cape Town beverage processors represent the primary installation base for automated dosing integration.
Most installed capacity flows through protease systems. Expansion is steepest in lipase variants optimized for dairy energy efficiency.
Application:
Customer technical sophistication and batch scale determine service intensity and pricing architecture across end-use verticals.
- Baking:Dough conditioning and crumb softening applications dominate enzyme volumes in South Africa. Johannesburg and Cape Town manufacturers are eliminating chemical conditioners under Regulation R638 disclosure pressure.
- Dairy:Cheese ripening and fat modification applications command premium formulations. Western Cape processors from mid-tier yogurt plants to artisan cheese operations sustain formulation partnership demand.
- Beverages:Juice clarification and brewing efficiency applications favor liquid enzyme formats. Cape Town's fruit juice sector is retrofitting automated dosing systems for cold-active catalyst integration.
- Meat Processing:Tenderization and flavor development applications concentrate in export-oriented Western Cape facilities. Pre-emptive alignment with Codex Alimentarius frameworks is accelerating ahead of anticipated regulatory amendments.
Revenue concentration sits with baking applications. Climbing the fastest is beverage sector automation-driven procurement.
Form:
Storage infrastructure investment and climate control requirements create divergent cost-to-serve economics across delivery formats.
- Liquid:Aqueous enzyme suspensions enable precision dosing in automated processing lines. Cape Town brewing and juice operations are retrofitting pump systems to capture formulation consistency advantages.
- Powder:Dried enzyme preparations offer superior shelf stability under South Africa's variable ambient storage conditions. Gauteng industrial corridor demand clusters around this format for bread manufacturing scale.
- Granular:Free-flowing particulate formats balance dispersibility with handling characteristics. Mid-tier dairy processors in the Western Cape are evaluating granular lipase against powder alternatives for aging room logistics.
- Tablets:Compressed enzyme units target small-scale artisan producers with limited dosing equipment. Specialty cheese makers in Paarl represent the primary addressable base for this format.
Volume leadership belongs to powder formulations. Gaining share fastest is liquid format adoption in automated beverage lines.
Customer Type:
Procurement scale and technical support requirements segment the buyer base into distinct service tiers.
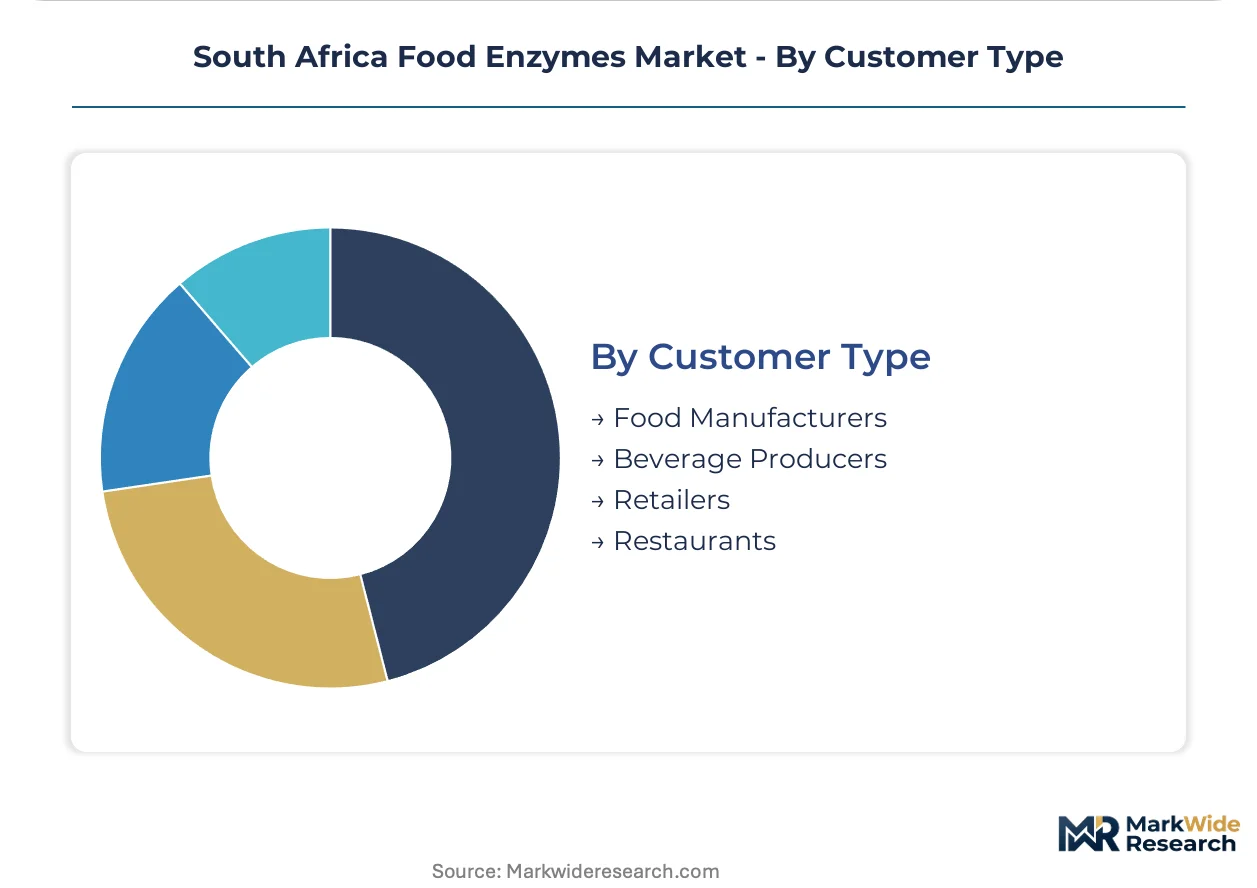
- Food Manufacturers:Industrial-scale bakeries and dairy processors command embedded formulation laboratory partnerships. Three major Johannesburg bread groups have consolidated procurement under single-source technical service agreements.
- Beverage Producers:Fruit juice and brewing operations prioritize dosing precision and batch consistency. Cape Town facilities are displacing traditional distribution intermediaries through direct supplier relationships.
- Retailers:Private-label food product developers represent emerging enzyme demand for consistent ingredient specifications. Compliance documentation standardization under Regulation R638 is reducing buyer due diligence friction.
- Restaurants:Commercial kitchen and catering operations constitute minimal enzyme volume due to pre-processed ingredient sourcing. This segment accesses enzymes indirectly through prepared food suppliers.
Procurement value concentrates with food manufacturers. Steepest expansion trajectory is emerging among beverage producers automating production lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping enzyme procurement patterns as Western Cape exporters front-run stricter Codex alignment costs while Gauteng manufacturers exploit localized technical service density. Production gravity tilts toward provinces with dual fermentation capacity and favorable Department of Health inspection protocols.
Gauteng
Industrial baking clusters in Johannesburg and Pretoria drive concentrated demand for powder-form protease and amylase systems. The Department of Health's Regulation R638 enforcement has standardized purity documentation across the Pretoria-Witwatersrand-Vereeniging corridor. Large-scale bread manufacturers have consolidated procurement under single-source technical service agreements with embedded formulation laboratories.
Western Cape
Mid-tier dairy processors and artisan cheese operations in Stellenbosch and Paarl sustain formulation partnership demand for cold-active lipase variants. Pre-emptive alignment with Codex Alimentarius frameworks is accelerating among export-oriented meat processors. Cape Town's fruit juice sector is retrofitting automated dosing systems for liquid enzyme integration.
KwaZulu-Natal
Sugar refining and beverage concentration facilities generate steady cellulase demand for clarification and fiber modification applications. The South African Bureau of Standards maintains regional certification capacity for SANS-aligned enzyme purity grades. Durban's port logistics infrastructure supports import-dependent specialty lipase distribution to inland dairy processors.
Eastern Cape
Emerging citrus processing and dairy cooperatives represent underserved enzyme demand for juice clarification and cheese ripening applications. Provincial agricultural extension services are building technical familiarity with enzyme dosing protocols. Gqeberha's industrial development zone is attracting fermentation facility investment targeting regional supply security.
South Africa Food Enzymes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized cold-active formulations and automated dosing integration partnerships. The market exhibits moderate concentration with three to four suppliers commanding industrial baking accounts through embedded technical service networks. Strategic archetypes span global fermentation specialists with regional technical laboratories, diversified ingredient conglomerates leveraging formulation bundling, and niche enzyme developers targeting energy-efficient dairy applications. Competitive moves center on direct supplier relationships displacing distribution intermediaries and SANS certification investments enabling price differentiation against uncertified imports.
Among European-origin specialists, Novozymes A/S and Chr. Hansen Holding A/S exemplify the technical service-intensive archetype, anchoring industrial accounts through localized application support. DuPont de Nemours, Inc and Kerry Group plc represent diversified ingredient conglomerates that bundle enzyme supply with broader formulation partnerships. These groupings illustrate how competitive positioning stratifies between pure-play biocatalyst developers and integrated ingredient platforms.
| Leading Market Players |
|---|
| Novozymes A/S |
| DuPont de Nemours, Inc |
| Koninklijke DSM N.V. |
| Associated British Foods plc |
| Kerry Group plc |
| Chr. Hansen Holding A/S |
| AB Enzymes GmbH |
| BASF SE |
| Amano Enzyme Inc. |
| Others |
Value Network & Pricing Analysis
Cold-active lipase fermentation technology is compressing production economics for Western Cape dairy processors while simultaneously concentrating supply leverage among Gauteng-based bioprocessing facilities with temperature-controlled capacity. This dual shift is redrawing margin capture across enzyme tiers as buyers face divergent cost structures between standardized powder protease and customized cold-active formulations.
Pricing Analysis
Distributor margins in the traditional chemical trading channel are compressing as direct supplier relationships displace intermediaries among Johannesburg's industrial baking groups. Pricing stratifies across SANS-certified premium tiers, volume-scale contract tiers, and uncertified import economy tiers, with certification level and technical service bundling as the primary differentiation drivers. Cost compression in the standard protease tier is intensifying because of localized Gauteng production capacity expansion. Mid-tier dairy processors in the Western Cape exhibit the highest price sensitivity due to energy cost pressures, while large-scale bread manufacturers with embedded formulation laboratories show the least.
Supply Chain Analysis
Specialty lipase supply rests on European fermentation producers in Denmark and the Netherlands, with cold-active variants arriving through extended supply chains. Raw material dependencies include fermentation feedstocks, chromatography resins for purification, and stabilizing carriers for powder formulations. Single-source vulnerability concentrates in cold-active lipase variants where domestic substitution remains underdeveloped. Distribution runs through direct technical service agreements for large accounts and regional chemical distributors for mid-tier processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's food enzymes market functions as a regulatory compounder where anticipated amendments to Regulation R638 are accelerating compliance-driven procurement cycles among manufacturers.
For Market Incumbents: Extend technical service laboratory networks into the Western Cape to capture formulation partnership demand from mid-tier dairy processors facing Codex alignment pressure. Deepen backward integration into fermentation capacity within the Gauteng industrial corridor to defend against emerging regional competitors. Certification investment in SANS purity grades offers channel control leverage against uncertified import alternatives. For New Entrants and Emerging Players: Regulation R638 in South Africa opens a window for specialized compliance documentation services that reduce buyer due diligence friction. Target the Eastern Cape's emerging citrus processing and dairy cooperative base, which remains undersupplied with technical enzyme support. A go-to-market angle anchored in automated dosing system integration for Cape Town beverage processors bypasses established powder distribution channels. For Investors and Strategic Acquirers: Roll-up economics work for regional fermentation specialists with SANS certification infrastructure because regulatory compliance barriers are consolidating procurement among certified suppliers. The acquisition target archetype is mid-cap bioprocessing facilities with dormant capacity and existing Department of Health inspection protocols. The signal to watch is amendment timing for Regulation R638 reclassification, which would trigger reformulation spending waves.| Strategic Initiative | Industry Significance |
|---|---|
| Technical Service Laboratory Expansion | Embedded formulation support locks in Johannesburg bread manufacturer procurement under single-source agreements. |
| SANS Certification Investment | Price differentiation against uncertified imports commands premium positioning in Western Cape dairy partnerships. |
| Cold-Active Lipase Development | Energy efficiency positioning captures Stellenbosch and Paarl artisan cheese producer adoption. |
| Automated Dosing System Partnerships | Cape Town fruit juice sector retrofit demand creates channel expansion beyond traditional powder distribution. |
| Fermentation Capacity Addition | Gauteng bioprocessing facility investment addresses surge capacity constraints during demand spikes. |
Research Methodology
Coverage spans Gauteng, Western Cape, KwaZulu-Natal, and Eastern Cape provinces, with primary inputs from each region triangulated against secondary validation. Interviews with fermentation plant managers, bakery procurement leads, dairy technical directors, and Department of Health regulatory officers combined with customs trade data, SANS certification records, and SEC filings from multinational enzyme suppliers. Bottom-up volume modeling and top-down value reconciliation anchored the analysis.
Granularity-level modeling operated at enzyme type, application vertical, form specification, and customer tier dimensions across the projection horizon. CAGRs were derived from trend extrapolation of clean-label reformulation adoption, energy efficiency investment cycles, and regulatory compliance spending patterns. Industry-specific forecast inputs included cold-active lipase penetration rates in Western Cape dairy and powder-to-liquid format conversion timelines in automated beverage lines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under currency volatility affecting European import dependency and pending Regulation R638 reclassification timing. Assumptions reflect current SANS certification frameworks and Department of Health inspection protocols. A small set of triggers—amendment finalization dates, fermentation facility commissioning, and cold-active variant domestic production milestones—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Sucroglycerides Market
Food Additives and Ingredients
Carrageenan Market
Food Additives and Ingredients
Asia-Pacific Food Enzymes Market
Food Additives and Ingredients
Food Grade Calcium Lactate Market
Food Additives and Ingredients
Liquid Caramel Color Market
Food Additives and Ingredients
Sugar Reduction Technology Market
Food Additives and Ingredients
Food Additives Market
Food Additives and Ingredients
Mexico Food Enzymes Market
Food Additives and Ingredients
Yeast Extract and Beta Glucan Market
Food Additives and Ingredients
Microencapsulation Market
Food Additives and Ingredients
Fruit Ripening Agents Market
Food Additives and Ingredients
Food Grade Butyric Acid Market
Food Additives and Ingredients
Bread Emulsifier Market
Food Additives and Ingredients
Japan Food Additives Market
Food Additives and Ingredients
India Food Colorants Market
Food Additives and Ingredients
China Food Enzymes Market