
 Chocolate Wax Market | 2026-2036
Chocolate Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Chocolate Wax Market Insights
Single-use sachet packaging is decoupling from bulk professional formats, giving home buyers entry points previously reserved for salon procurement. GiGi leverages its professional heritage to sustain credibility across both channels. Starpil Wax anchors its position through specialized hard wax formulations. Parissa Laboratories differentiates via natural ingredient positioning that commands shelf space in clean beauty retail.
Chocolate wax denotes a depilatory formulation incorporating cocoa-derived compounds, typically achieving melting points between 40°C and 55°C depending on base resin ratios, designed to adhere to hair rather than skin for reduced irritation during removal. The product serves commercial hair removal services and at-home grooming routines where skin sensitivity and post-treatment comfort determine repurchase behavior. Hard wax currently occupies the dominant margin pool due to lower application skill requirements and reduced strip material costs. Soft wax competes on speed and throughput in high-volume salon environments. Film wax represents the fastest-growing configuration as technicians seek peelable layers that eliminate linen dependency entirely.
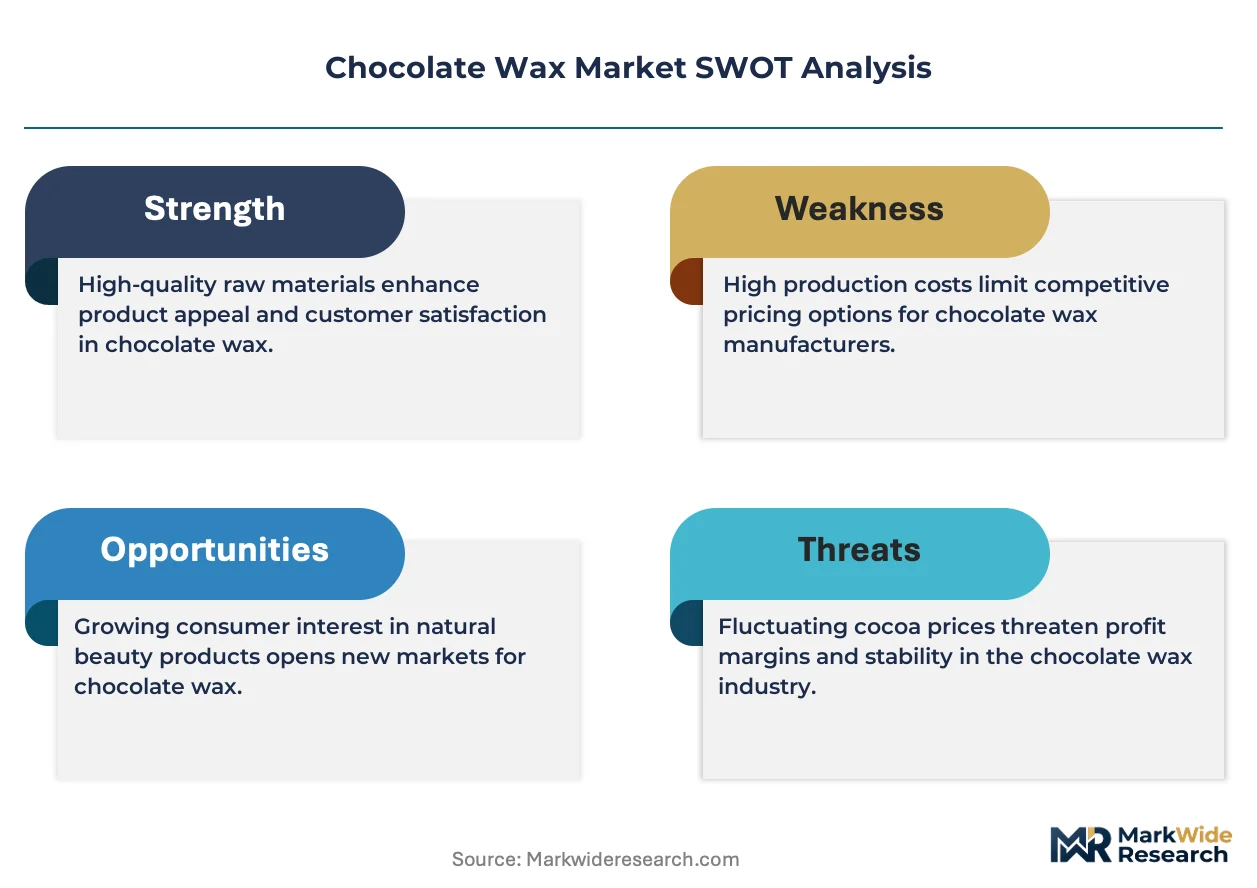
FDA cosmetic labeling requirements and the EU Cosmetics Regulation govern ingredient transparency and allergen disclosure, pushing manufacturers toward standardized cocoa butter sourcing documentation. REACH compliance in Europe adds pressure on synthetic additive portfolios, while state-level board of cosmetology rules in California and Texas shape technician certification requirements that indirectly filter product distribution. Stakeholders must monitor whether clean beauty certification schemes evolve from marketing differentiation into de facto market access gates.
Market Dynamics
The chocolate wax market is being fundamentally restructured by the divergence between professional salon procurement and direct-to-consumer retail channels, with single-use sachet formats eroding the historical dominance of bulk professional containers and forcing reformulation economics at every tier.
Growth Catalysts
- REACH disclosure mandates:European ECHA requirements for synthetic additive transparency are accelerating cocoa butter documentation standards, advantaging suppliers with vertically controlled sourcing.
- Hard wax skill democratization:Lower technician certification barriers in Texas and California state cosmetology boards are expanding addressable technician pools for peelable formulations.
- Brazilian salon chain expansion:National waxing service menu extensions by integrated beauty groups are standardizing chocolate wax as a premium tier offering across metropolitan São Paulo and Rio de Janeiro.
Market Restraints
- Cocoa butter price volatility:Concentrated West African supply exposes formulation costs to commodity swings without hedgeable futures markets.
- Synthetic resin substitution:Petroleum-derived hard wax alternatives achieve comparable adhesion at 30-40% lower raw material cost, pressuring natural-positioned brands.
- REACH compliance friction:ECHA's tightening portfolio assessment timelines extend product registration cycles, delaying new variant commercialization.
Strategic Opportunities
- Film wax peelable layers:Linen-independent removal configurations eliminate consumable costs for mobile technicians and home users.
- Clean beauty certification gates:EWG Verified and COSMOS standards are evolving from marketing differentiation into retail access requirements for premium shelf placement.
- Indian metropolitan penetration:Underdeveloped organized salon networks in Mumbai and Delhi present first-mover positioning for professional-format distributors.
Industry Challenges
- Thermostability formulation expertise:Narrow 40°C-55°C melting point windows demand precise resin-cocoa butter ratios that few compounders master at scale.
- Cross-border documentation complexity:Divergent FDA cosmetic labeling and EU Cosmetics Regulation allergen disclosure formats multiply SKU management overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chocolate Wax Market |
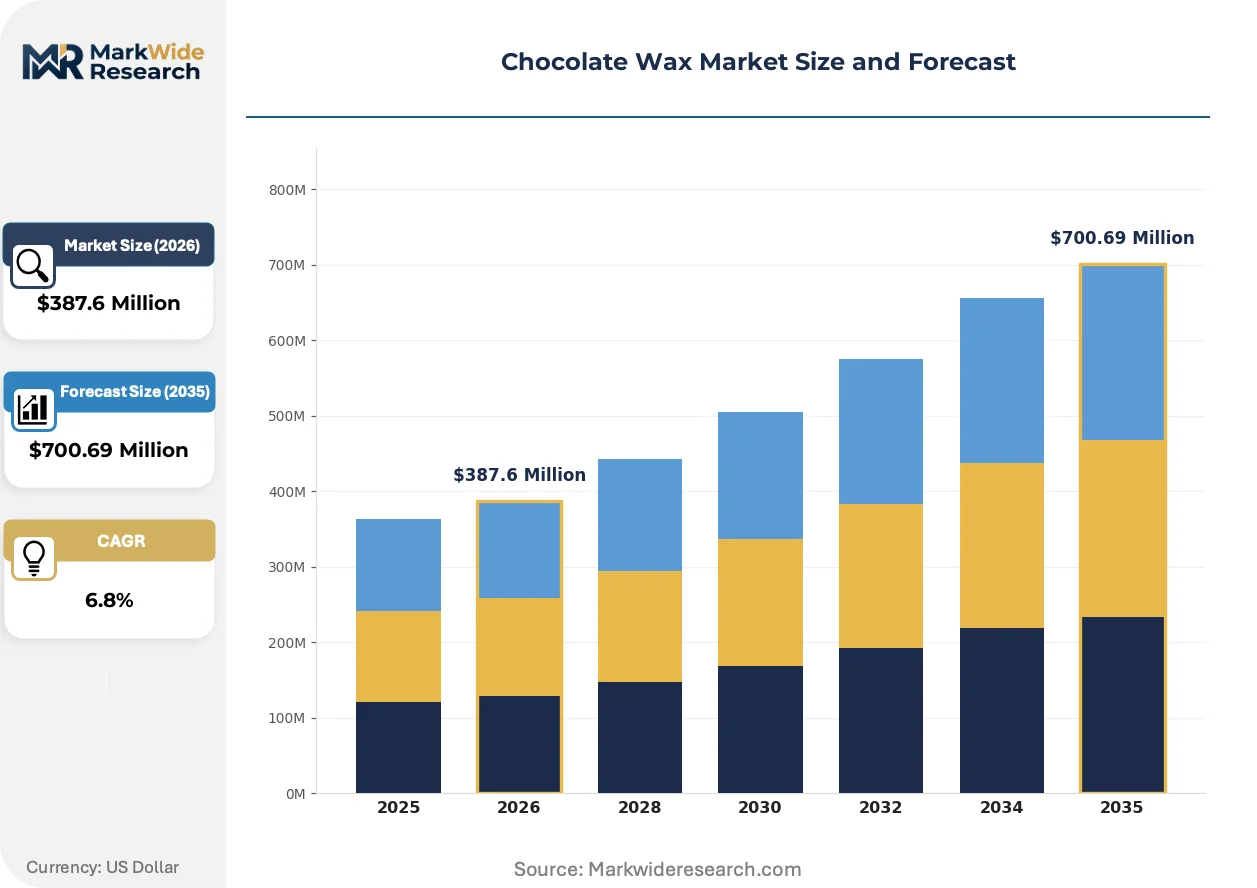
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
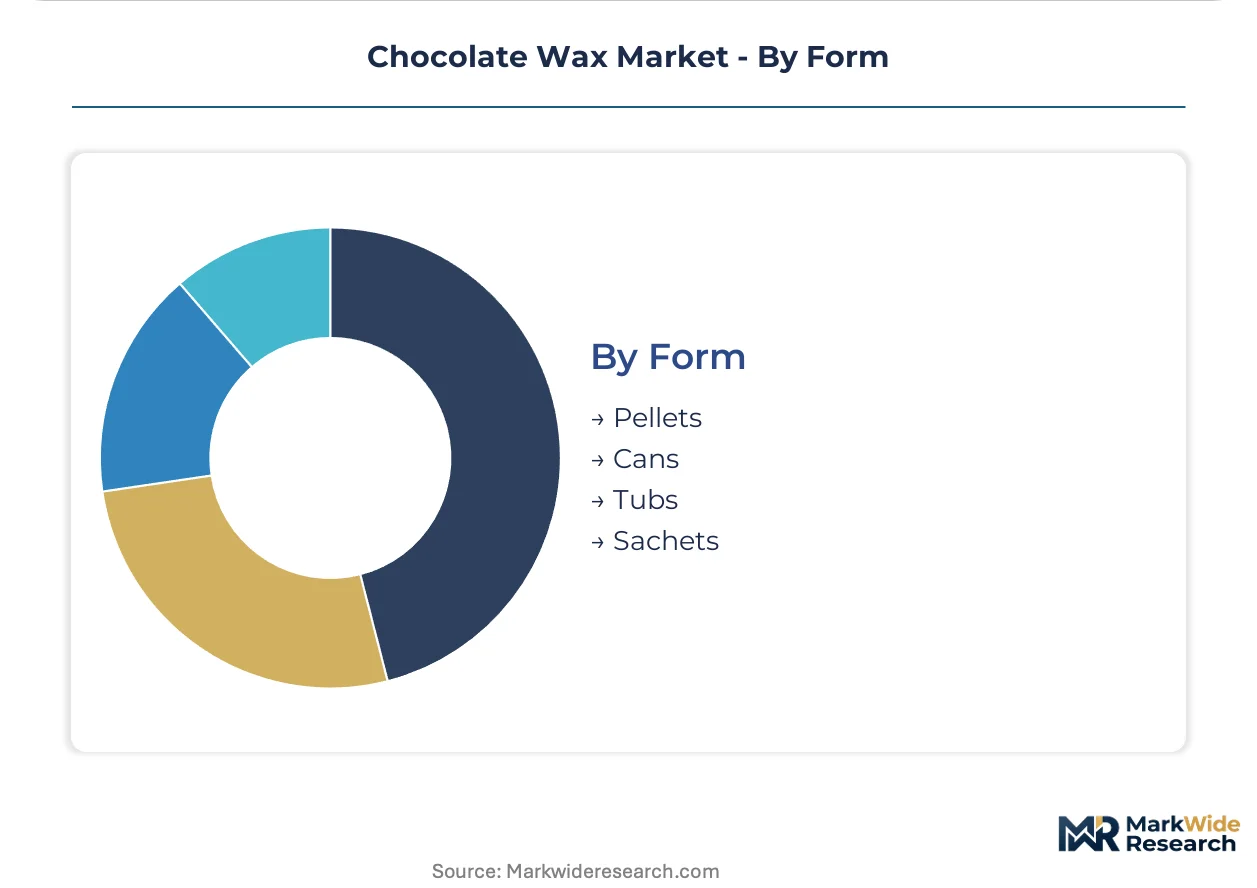
| Segmentation | Product Type: Soft Wax, Hard Wax, Gel Wax, Film Wax End User: Salons, Home Users, Spas, Professionals Application: Body Hair Removal, Facial Hair Removal, Sensitive Areas, Male Grooming Form: Pellets, Cans, Tubs, Sachets |
| Companies Covered | GiGi, Starpil Wax, Parissa Laboratories, American International Industries, Church & Dwight Co., Rica Wax, Harley Waxing, Marzena Body Care, Coloris Sp. Zo.o., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chocolate Wax Market Trends and Innovations
Formulation science and channel economics are colliding to reshape how chocolate wax reaches end users, with three distinct vectors redefining competitive requirements.
Film wax polymer-cocoa butter hybrids are rewriting application protocols by enabling peelable removal without fabric strips. Premium spa networks in California and Florida are standardizing these configurations for back and facial services. The technology is compressing linen logistics costs and enabling mobile service models previously uneconomical.
REACH authorization requirements for synthetic additives are forcing portfolio rationalization across European compounders. Manufacturers with captive cocoa butter supply chains are accelerating documentation investments to maintain formulation continuity. Hard wax variants with reduced synthetic resin content are capturing disproportionate attention from ECHA-compliant distributors.
Direct-to-consumer sachet formats are fragmenting historical professional-channel concentration. Home buyers now access cocoa butter-enriched formulations previously restricted to salon procurement accounts. This channel rotation is most visible in United States premium beauty retail, where clean beauty positioning commands shelf space independent of professional heritage credibility.
Chocolate Wax Market Segmentation
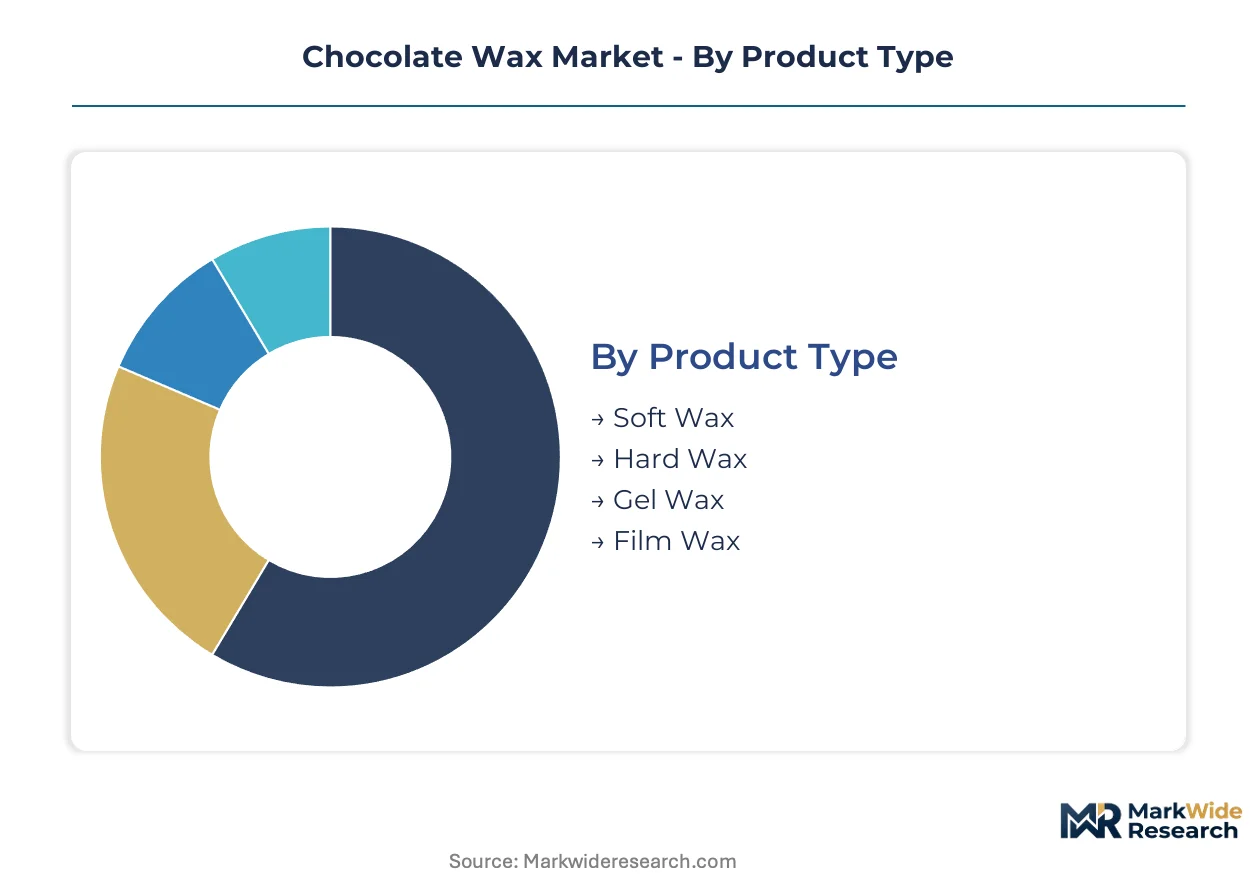
Chocolate wax segmentation reflects divergent channel economics between professional procurement and direct-to-consumer retail. Formulation requirements differ sharply across technician-supervised versus self-application contexts, while packaging formats determine margin capture and logistics costs.
Product Type:
Buyers in this category prioritize application skill requirements and consumable elimination over raw material composition alone.
- Hard Wax:Peelable formulations with elevated melting points around 50°C-55°C that solidify into strippable layers without fabric dependency. Demand concentrates in United States metropolitan salon chains where reduced technician training costs and eliminated linen expenses drive procurement decisions. Cocoa butter enrichment commands premium positioning in California and Florida spa networks.
- Film Wax:Polymer-cocoa butter hybrids enabling complete peelable removal with zero strip material. Growth tilts toward mobile service technicians and home users in premium United States beauty retail where linen independence justifies higher per-gram pricing.
- Soft Wax:Lower viscosity formulations requiring fabric strip removal, competing on speed in high-throughput Brazilian salon environments.
- Gel Wax:Transparent variants with reduced tack for facial and sensitive area applications, finding niche positioning in European professional channels.
Volume sits with Hard Wax; growth tilts toward Film Wax.
End User:
Channel concentration determines packaging scale and formulation documentation requirements.
- Salons:Bulk procurement accounts driving standardized hard wax adoption across Brazilian integrated beauty groups extending service menus in São Paulo and Rio de Janeiro. REACH-compliant documentation requirements from ECHA filter supplier eligibility for European salon distributors.
- Home Users:Sachet-format demand fragmenting historical professional-channel concentration, with cocoa butter-enriched variants previously restricted to salon accounts now penetrating United States premium retail through clean beauty positioning.
- Spas:Premium service tier requiring thermostable formulations with precise 40°C-55°C melting windows for back and facial protocols.
- Professionals:Mobile technicians prioritizing film wax configurations that eliminate linen logistics entirely.
Procurement scale favors Salons; margin expansion concentrates in Home Users.
Application:
Sensitivity tolerance and hair density dictate formulation selection across body zones.
- Body Hair Removal:High-volume leg and arm services in Brazilian salon chains standardizing chocolate wax as premium tier offering.
- Facial Hair Removal:Precision requirements driving film wax adoption in California and Florida premium spa networks where peelable layers reduce skin trauma.
- Sensitive Areas:Low-temperature hard wax variants with enhanced cocoa butter content for bikini and underarm protocols.
- Male Grooming:Emerging segment with coarser hair requirements pressuring adhesion formulation adjustments.
Revenue concentration remains in Body Hair Removal; steepest expansion trajectory appears in Male Grooming.
Form:
Packaging configuration directly determines channel accessibility and per-use economics.
- Sachets:Single-use formats decoupling home buyers from bulk professional procurement, penetrating United States premium beauty retail independent of salon heritage credibility.
- Pellets:Bulk professional formats with precise portion control for high-volume Brazilian salon operations.
- Cans:Standard salon containers with microwave-compatible warming protocols.
- Tubs:Larger-capacity professional formats for integrated beauty group central kitchens.
Unit volume concentrates in Pellets; value capture shifts toward Sachets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
West African cocoa butter production feeds formulation facilities in Europe and North America, while consumption concentrates in premium salon networks across Brazil and the United States. Regulatory divergence between ECHA's REACH mandates and FDA cosmetic labeling requirements fragments supplier compliance strategies. Demand from mobile technicians and home users is accelerating sachet-format penetration in metropolitan clusters.
United States
Premium spa networks in California and Florida drive cocoa butter-enriched hard wax procurement, with film wax configurations capturing mobile technician demand. FDA cosmetic labeling requirements govern ingredient transparency and allergen disclosure for all formulations. Los Angeles and Miami metropolitan clusters anchor professional-format distribution, while sachet formats penetrate premium beauty retail through clean beauty positioning.
Brazil
Integrated beauty groups in São Paulo and Rio de Janeiro standardize chocolate wax as premium-tier service menu extensions. ANVISA regulates cosmetic ingredient disclosure and salon product registration timelines. Metropolitan salon chains in southeastern states concentrate bulk procurement volume, with technician training programs accelerating hard wax adoption across franchise networks.
Germany
ECHA REACH compliance mandates filter supplier eligibility for European salon distributors, advantaging vertically controlled cocoa butter sourcing. The EU Cosmetics Regulation governs allergen disclosure formats distinct from FDA requirements. Industrial compounding clusters in North Rhine-Westphalia and Bavaria maintain formulation continuity through captive supply chain documentation investments.
India
Underdeveloped organized salon networks in Mumbai and Delhi present first-mover positioning for professional-format distributors entering premium service tiers. BIS standards govern cosmetic product quality and labeling requirements for domestic market access. Metropolitan beauty service expansion in Maharashtra and Karnataka concentrates demand for thermostable formulations with precise melting point control.
United Kingdom
Premium spa procurement in London and southeast England prioritizes peelable film wax configurations for back and facial protocols. The UK's post-EU regulatory framework maintains REACH-aligned disclosure requirements through retained EU law. Greater London salon clusters drive standardization of cocoa butter-enriched variants across integrated beauty group service menus.
Chocolate Wax Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the chocolate wax market, creating a tiered structure where professional heritage credibility battles clean beauty retail positioning. The vendor base spans legacy salon supply houses, natural ingredient specialists, and polymer formulation innovators. Three archetypes dominate: vertically integrated cocoa butter compounders, professional-channel heritage brands, and clean beauty retail entrants. Capacity expansion in West African sourcing corridors and strategic partnerships with Brazilian salon chains represent the dominant competitive moves reshaping supply security.
Among heritage professional specialists, GiGi leverages its salon supply legacy to sustain credibility across both bulk professional and emerging sachet retail channels. Starpil Wax anchors the specialized hard wax formulation tier through polymer-cocoa butter hybrid expertise. Parissa Laboratories occupies the natural ingredient positioning vector, commanding shelf space in clean beauty retail independent of professional heritage credentials. These three exemplify how channel diversification and formulation specialization determine competitive viability against petroleum-derived alternatives.
| Leading Market Players |
|---|
| GiGi |
| Starpil Wax |
| Parissa Laboratories |
| American International Industries |
| Church & Dwight Co. |
| Rica Wax |
| Harley Waxing |
| Marzena Body Care |
| Coloris Sp. Zo.o. |
| Others |
Pricing and Supply Chain Analysis
Captive cocoa butter sourcing from West African cooperatives anchors both supply security and premium pricing power for compounders serving ECHA-compliant European distributors. This backward integration into raw material procurement insulates formulation costs from commodity volatility while enabling documentation investments that satisfy REACH disclosure mandates.
Pricing Analysis
Margin tightening in standard-grade formulations reflects petroleum-derived hard wax substitution achieving comparable adhesion at substantially lower input costs. Three-tier pricing structure across premium cocoa butter-enriched, standard natural-positioned, and economy synthetic-blend levels separates GiGi's salon heritage brands from Parissa's clean beauty retail positioning. Pricing pressure stems from Brazilian salon chains consolidating procurement volumes across franchise networks. Home users in United States premium beauty retail exhibit lowest price sensitivity due to clean beauty certification premiums.
Supply Chain Analysis
Cocoa butter supply rests on concentrated West African production corridors in Ivory Coast and Ghana, with secondary processing capacity in Germany and United States. Formulation inputs include cocoa butter, synthetic resins, and polymer additives for film wax hybrids. Single-source vulnerability concentrates in West African harvest cycles exposed to climate disruption. Distribution runs through professional salon supply houses in Brazil and United States, with direct-to-consumer e-commerce channels fragmenting historical wholesale concentration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chocolate wax market is becoming a vertical-integration race where captive cocoa butter sourcing and ECHA-compliant documentation investments determine supplier viability against petroleum-derived substitutes.
For Market Incumbents: Deploy certification investments to defend shelf space as EWG Verified and COSMOS standards evolve into retail access requirements. GiGi and Starpil Wax should deepen backward integration into West African cocoa butter cooperatives to secure formulation continuity against REACH authorization delays. Channel control through Brazilian salon chain partnerships insulates volume against sachet-format fragmentation. For New Entrants and Emerging Players: ANVISA regulatory harmonization in Brazil opens a window for professional-format distributors to establish first-mover positioning in São Paulo and Rio de Janeiro metropolitan clusters. Target underpenetrated Indian organized salon networks in Mumbai and Delhi with thermostable hard wax configurations. Clean beauty retail positioning in United States premium beauty channels offers the most penetrable go-to-market angle independent of professional heritage credibility. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified personal care conglomerates seeking salon-channel credibility. Long-term viability favors compounders with captive cocoa butter supply chains and multi-format packaging capabilities spanning bulk professional and sachet retail. Watch ECHA's synthetic additive authorization timelines as the critical inflection signal for natural-positioned formulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cocoa Butter Sourcing | Captive supply from Ivory Coast cooperatives insulates formulation costs against commodity volatility and satisfies ECHA documentation requirements. |
| Clean Beauty Certification Investment | EWG Verified and COSMOS standards are becoming retail access gates for premium shelf placement in United States beauty retail. |
| Film Wax Polymer Formulation Development | Peelable layer technology eliminates linen logistics costs and enables mobile technician service models in California and Florida. |
| Brazilian Salon Chain Partnership | Integrated beauty group menu extensions in São Paulo standardize chocolate wax as premium-tier offering across franchise networks. |
| Direct-to-Consumer Sachet Launch | Single-use formats decouple home buyers from bulk professional procurement, penetrating premium retail through clean beauty positioning. |
Research Methodology
Multi-period observation of cocoa butter price volatility, REACH authorization timelines, and salon chain procurement patterns anchored the trend analysis, supplemented by interviews with formulation chemists at European compounders, procurement directors at Brazilian integrated beauty groups, regulatory affairs specialists navigating ECHA disclosure requirements, and category buyers at United States premium beauty retailers. Secondary validation drew from ECHA substance registration databases, ANVISA cosmetic product filings, FDA cosmetic labeling guidance, and customs trade data for cocoa butter derivatives. Bottom-up volume estimates from salon and retail channel audits were triangulated against top-down market sizing from raw material consumption patterns.
Segment-weighting across product type, end user, application, and form dimensions shaped the analytical framework throughout the forecast period. Hard wax, film wax, soft wax, and gel wax categories were modeled separately with distinct growth assumptions reflecting technician skill requirements and consumable elimination trends. CAGRs were derived from regression analysis against cocoa butter price indices and salon service menu expansion rates. End-user segmentation incorporated divergent packaging economics between bulk professional procurement and sachet retail penetration.
The model assumes a particular technology adoption path; alternative pathways for synthetic resin substitution achieving cost parity with natural formulations would alter the outlook substantially. Forecasts reflect documented assumptions regarding REACH compliance timelines, Brazilian salon chain consolidation rates, and clean beauty certification evolution. A small set of triggers—ECHA synthetic additive authorization decisions, West African cocoa harvest disruptions, and ANVISA regulatory harmonization progress—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Russia Food Acidulants Market
Food Additives and Ingredients
Italy Food Preservatives Market
Food Additives and Ingredients
Lycopene Food Colors Market
Food Additives and Ingredients
Fat-Replacing Starch Market
Food Additives and Ingredients
Feed Anti-Caking Agents Market
Food Additives and Ingredients
Anti-Caking Agents Market
Food Additives and Ingredients
North America Fermented Ingredient Market
Food Additives and Ingredients
Africa Anti Caking Agent Market
Food Additives and Ingredients
Food Starch Market
Food Additives and Ingredients
Food Protein Ingredient Market
Food Additives and Ingredients
Olestra Market
Food Additives and Ingredients
Acrylamide Reduction Market
Food Additives and Ingredients
Hydrocolloids Market
Food Additives and Ingredients
DATEM Replacement Market
Food Additives and Ingredients
Australia Food Colorants Market
Food Additives and Ingredients
Lactose Monohydrate Market