
 Germany Food Acidulants Market | 2026-2036
Germany Food Acidulants Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Food Acidulants Market Foresight
Precision fermentation and enzymatic acid synthesis is reshaping how acidulants are manufactured for German food processors. Jungbunzlauer Ladenburg GmbH leverages its Ladenburg production base to dominate citric acid supply for Central European beverage clients. BASF anchors industrial-scale malic acid output through its Ludwigshafen chemical complex. Corbion NV specializes in fermentation-derived lactic acid for dairy alternative applications.
Food acidulants are organic and inorganic acids added to food matrices to regulate pH, enhance flavor profiles, inhibit microbial spoilage, and control gelation in processed products; citric acid typically comprises 50-60% of total acidulant consumption by volume in Western European formulations. The citric acid segment sustains the largest revenue pool due to its universal application across beverages and confectionery. Lactic acid competes as the fastest-expanding category, propelled by plant-based dairy alternative growth in German retail channels. The beverage application segment occupies the dominant end-use position, though sauces and dressings are extending share through clean-label reformulation trends.
Bundesamt für Verbraucherschutz und Lebensmittelsicherheit enforces acidulant purity standards under EU Regulation 1333/2008 on food additives, while the European Food Safety Authority conducts re-evaluations of phosphoric acid safety in carbonated beverages. ECHA's REACH framework governs chemical registration and hazard communication for acidulant imports into German manufacturing facilities. Stakeholders must monitor EFSA's ongoing phosphoric acid assessments and the EU's tightening clean-label disclosure mandates to anticipate reformulation requirements.
Market Dynamics
Precision fermentation is virtualizing acidulant production economics across Germany's southern processing corridor, compressing capital requirements while enabling localized supply security for beverage and dairy alternative manufacturers.
Growth Catalysts
- EU Farm to Fork Strategy:The European Green Deal's additive transparency mandates are accelerating clean-label reformulation across Bavarian beverage plants, expanding acidulant procurement volumes for natural-origin suppliers.
- Plant-based dairy alternatives:German retail channels are driving lactic acid demand as oat, almond, and soy-based milk substitutes require pH stabilization and flavor modulation identical to conventional dairy.
- Enzymatic acid synthesis:Biocatalytic production methods are reducing energy intensity and substrate costs for malic and citric acid output in the Ludwigshafen chemical cluster.
Market Restraints
- Phosphoric acid safety re-evaluations:EFSA's ongoing assessments of carbonated beverage applications are creating formulation uncertainty and potential displacement costs for German soft drink bottlers.
- Feedstock concentration:Molasses and starch substrate supply for fermentation-derived acidulants concentrates in Central European agricultural zones, exposing processors to harvest volatility and trade flow disruptions.
- Technical substitution limits:Citric acid's universal functionality in gelation control and microbial inhibition prevents complete replacement by alternative acidulants in confectionery and preserves applications.
Strategic Opportunities
- Baden-Württemberg sauce segment:Clean-label reformulation in Stuttgart-area dressing manufacturers is extending acidulant share beyond traditional beverage dominance into condiment applications.
- REACH registration optimization:ECHA's streamlined hazard communication frameworks for existing chemical substances are reducing compliance friction for acidulant imports into German manufacturing facilities.
- Fermentation-lactic acid convergence:Integration of precision fermentation with dairy alternative processing is enabling captive acidulant production within plant-based food manufacturing sites.
Industry Challenges
- Bioprocess engineering talent scarcity:German fermentation facilities face recruitment gaps in metabolic pathway optimization and scale-up engineering for acidulant strains.
- Legacy equipment retrofit costs:Existing citric acid crystallization infrastructure in the Ladenburg production base requires substantial capital outlay to accommodate enzymatic synthesis feedstocks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Food Acidulants Market |
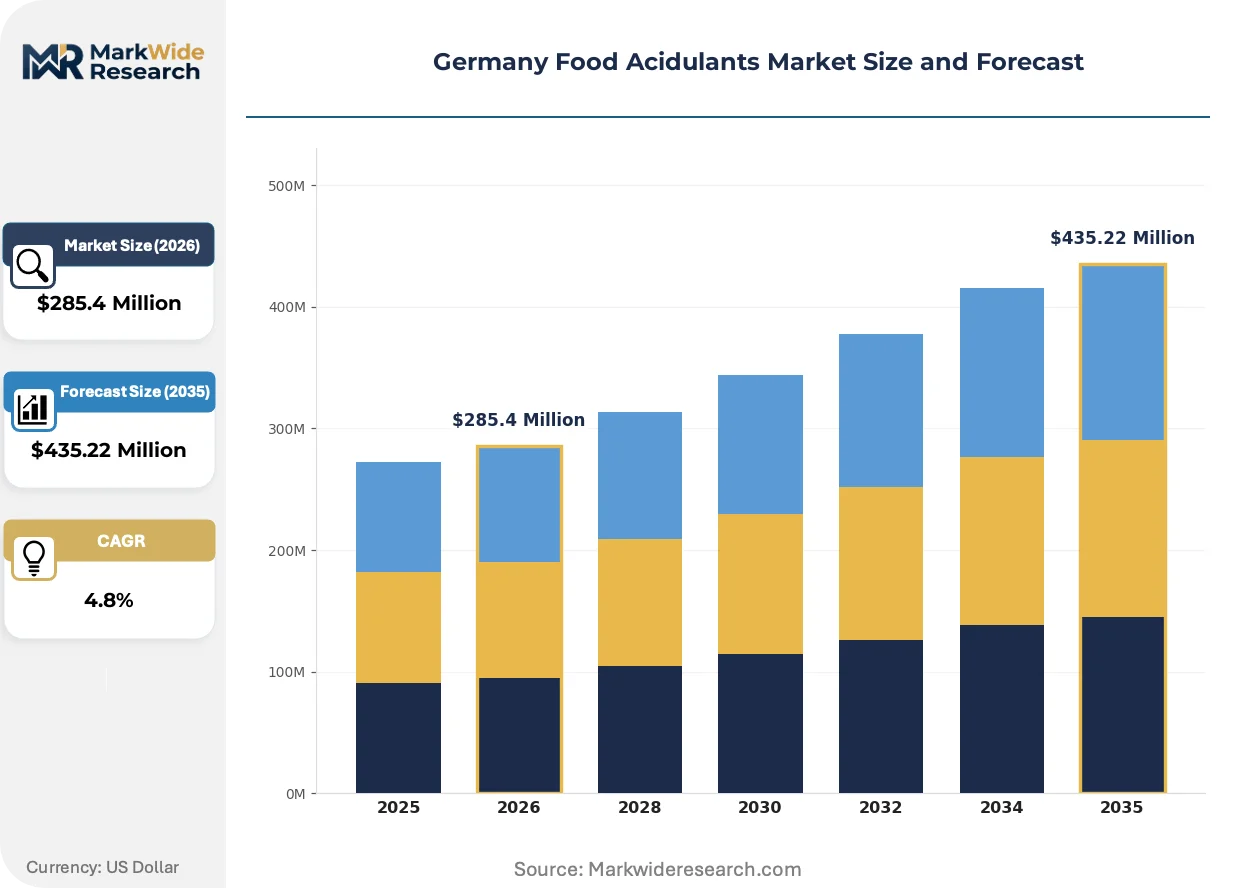
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $435.22 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Lactic Acid, Malic Acid, Tartaric Acid, Acetic Acid, Phosphoric Acid Application: Beverages, Baked Goods, Dairy Alternatives, Confectionery, Snack Foods, Sauces & Dressings Packaging Type: Powder Packs, Liquid Containers, Bulk Bags, Sachets, Drums End User Industry: Food Processing Units, Beverage Manufacturers, Bakery Units, Confectionery Producers |
| Companies Covered | Cargill Inc., Tate & Lyle plc, Archer Daniels Midland Company, Jungbunzlauer Ladenburg GmbH, Corbion NV, Brenntag, BASF, Jungbunzlauer Suisse AG, Hawkins Watts Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Food Acidulants Market Shifts & Advancements
Digital process control and biosynthetic pathway engineering are compressing production timelines while enabling mass-customized acidulant blends for regional food processors.
Continuous fermentation monitoring via in-line spectroscopy is virtualizing quality assurance for citric acid batches. Bavarian beverage manufacturers are adopting these sensor arrays at pilot scale. The technology is virtualizing traditional laboratory testing workflows and accelerating batch release cycles for just-in-time supply contracts.
EU Regulation 1333/2008 purity standard revisions are tightening heavy metal thresholds for food additives. German acidulant importers must recertify supply chains against updated specifications. The Bundesamt für Verbraucherschutz und Lebensmittelsicherheit enforcement focus is concentrating compliance investment on phosphoric acid and synthetic malic acid categories.
Direct procurement relationships between acidulant producers and mid-sized sauce manufacturers are displacing traditional distributor intermediaries in the Munich-Stuttgart corridor. Regional dressing formulators are negotiating volume commitments in exchange for formulation technical support. This channel restructuring is most visible among clean-label specialists in Baden-Württemberg seeking supply security and customization services unavailable through conventional chemical distributors.
Germany Food Acidulants Market Segmentation
Acidulant procurement cycles vary dramatically across segment dimensions, with beverage applications turning inventory weekly while bulk industrial packaging locks capital for quarters. German formulators in Bavaria and Baden-Württemberg structure procurement portfolios around these velocity mismatches to optimize working capital against supply security.
Product Type:
Inventory velocity separates fermentation-derived acids with predictable crop-cycle inputs from mineral acids facing regulatory re-evaluation delays.
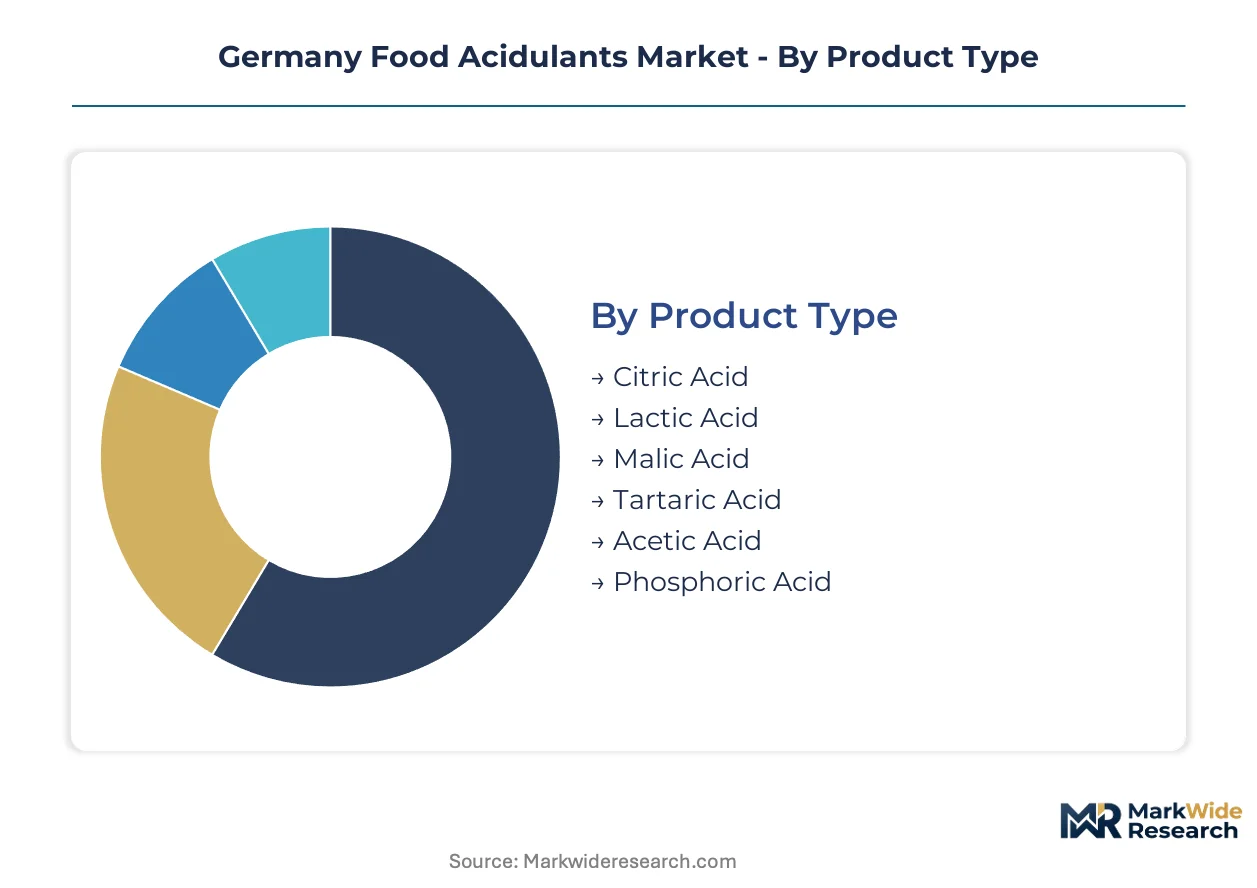
- Citric Acid:Dominates German formulation volumes through universal functionality in pH control, flavor enhancement, and microbial inhibition across beverage and confectionery matrices. Bavarian bottlers in the Munich corridor sustain the densest procurement concentration, though crystallization infrastructure at legacy production sites constrains feedstock flexibility.
- Lactic Acid:Fermentation-derived specification with fastest-expanding demand trajectory as oat, almond, and soy-based dairy alternatives require identical pH stabilization to conventional dairy. Stuttgart-area plant-based manufacturers are negotiating direct supply relationships to secure fermentation-lot traceability for clean-label positioning.
- Malic Acid:Industrial-scale output from the Ludwigshafen chemical cluster supplies tartness modulation for sugar-free confectionery and enhanced beverage profiles.
- Tartaric Acid:Wine industry byproduct acid with specialized application in baking powder formulations and grape-derived flavor systems.
- Acetic Acid:Vinegar-derived and synthetic grades serving pickle preservation and sauce acidification with distinct purity specifications.
- Phosphoric Acid:Mineral acid facing EFSA safety re-evaluation uncertainty for carbonated beverage applications, creating formulation displacement risk for German soft drink bottlers.
Citric acid anchors the volume base while lactic acid gains share at the steepest rate.
Application:
Margin structure inverses across application segments, with commodity beverage volumes funding specialized sauce and dressing technical service investments.
- Beverages:Dominant end-use position spanning carbonated soft drinks, fruit juices, and functional waters with just-in-time delivery requirements. Munich-Stuttgart corridor bottlers are deploying in-line spectroscopy for batch release acceleration.
- Sauces & Dressings:Clean-label reformulation in Baden-Württemberg dressing manufacturers is extending acidulant procurement beyond traditional beverage dominance, with direct producer relationships displacing distributor intermediaries.
- Baked Goods:Leavening activation and preservation applications requiring acid-base reaction control in industrial bakery units.
- Dairy Alternatives:pH stabilization and flavor modulation for oat, almond, and soy-based milk substitutes with fermentation-derived acid preferences.
- Confectionery:Gelation control and sour flavor delivery with citric acid functionality preventing complete substitution by alternative acidulants.
- Snack Foods:Flavor enhancement and preservation in seasoned and processed snack matrices.
Beverages command the procurement volume leadership while sauces and dressings expand most quickly through clean-label technical service demands.
Packaging Type:
Customer scale determines packaging selection, with mid-sized formulators in the Munich-Stuttgart corridor driving hybrid procurement strategies across multiple formats.
- Bulk Bags:Industrial-scale procurement for high-volume beverage and bakery units with dedicated handling infrastructure.
- Liquid Containers:Ready-to-dose format preferred by sauce manufacturers requiring formulation flexibility and reduced handling labor.
- Drums:Intermediate volume solution for regional processors without bulk handling capabilities.
- Powder Packs:Standardized unit weights for mid-scale confectionery and snack food producers.
- Sachets:Precision-dose packaging for artisanal and specialty food manufacturers with batch-scale requirements.
Bulk bags dominate tonnage movement while liquid containers capture margin expansion through formulation technical support bundling.
End User Industry:
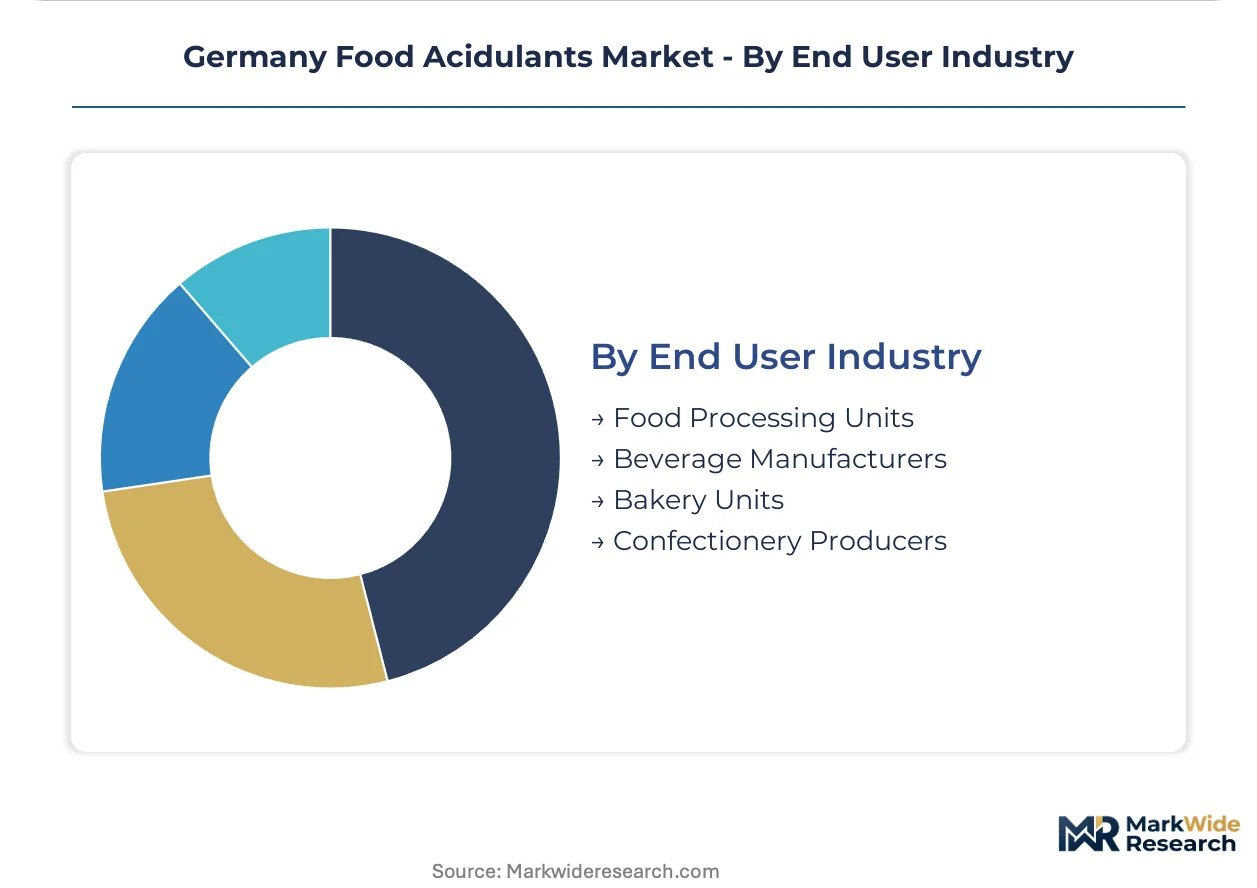
Procurement sophistication varies sharply, with beverage manufacturers demanding supply chain virtualization while bakery units prioritize cost minimization.
- Beverage Manufacturers:Most advanced procurement function with just-in-time contracts, in-line quality monitoring, and direct producer technical partnerships. EFSA phosphoric acid assessments are forcing contingency formulation investments.
- Food Processing Units:Diverse acidulant requirements spanning preservation, pH control, and flavor across multiple product categories.
- Confectionery Producers:Specialized gelation and sour flavor demands with limited acidulant substitution flexibility.
- Bakery Units:Cost-sensitive procurement with standardized citric and tartaric acid specifications for leavening systems.
Beverage manufacturers anchor the value pool while food processing units diversify fastest across acidulant categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mid-sized sauce manufacturers and beverage bottlers concentrate acidulant procurement in Germany's southern processing corridor, with direct producer relationships displacing traditional distributor channels across Bavaria and Baden-Württemberg.
Bavaria
Munich-area beverage bottlers deploy just-in-time acidulant contracts with in-line spectroscopy for batch release acceleration. The Bundesamt für Verbraucherschutz und Lebensmittelsicherheit enforces EU Regulation 1333/2008 purity standards with particular scrutiny on phosphoric acid imports. The Munich-Stuttgart corridor anchors Central Europe's densest citric acid procurement concentration.
Baden-Württemberg
Stuttgart-area dressing manufacturers drive clean-label reformulation demand for fermentation-derived lactic acid in plant-based condiments. ECHA's REACH framework governs hazard communication for acidulant imports into regional manufacturing facilities. The state extends acidulant procurement beyond beverage dominance into technical service-intensive sauce applications.
North Rhine-Westphalia
Cologne-Düsseldorf food processing units diversify acidulant portfolios across preservation and pH control applications. The EU Green Deal's Farm to Fork Strategy tightens additive transparency requirements for regional retail-channel suppliers. The Lower Rhine industrial zone concentrates bulk acidulant distribution infrastructure serving Benelux export markets.
Lower Saxony
Hanover-area bakery units maintain cost-sensitive procurement of standardized citric and tartaric acids for leavening systems. EFSA's ongoing phosphoric acid safety re-evaluations create formulation contingency planning requirements for regional soft drink bottlers. The state harbors specialized tartaric acid byproduct recovery from wine industry operations.
Hesse
Frankfurt-Rhine-Main logistics hubs coordinate acidulant inventory velocity mismatches between weekly beverage turns and quarterly bulk industrial packaging. The European Food Safety Authority's clean-label disclosure mandates accelerate natural-origin supplier qualification. The region's chemical distribution infrastructure bridges Ladenburg production output with southern processing corridor demand.
Germany Food Acidulants Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Germany's acidulant procurement landscape, creating a tiered structure where fermentation-derived acid producers face mineral acid incumbents with entrenched beverage relationships. The vendor base clusters around three strategic archetypes: integrated chemical conglomerates with Ludwigshafen-scale production assets, precision fermentation specialists leveraging enzymatic synthesis, and regional distribution intermediaries losing share to direct procurement. Dominant competitive moves include backward integration into captive fermentation capacity and geographic densification along the Munich-Stuttgart corridor.
Within the fermentation-specialist tier, Jungbunzlauer Ladenburg GmbH and Jungbunzlauer Suisse AG exemplify Swiss-German integrated acidulant production, while Corbion NV represents Dutch fermentation expertise positioned for dairy alternative applications. BASF anchors the industrial-scale chemical archetype through its Ludwigshafen complex malic acid output. These three entities occupy distinct competitive positions: the Jungbunzlauer entities exemplify citric acid concentration with crystallization infrastructure, Corbion NV exemplifies lactic acid specialization for plant-based formulations, and BASF represents mineral acid and synthetic organic acid scale production.
| Leading Market Players |
|---|
| Cargill Inc. |
| Tate & Lyle plc |
| Archer Daniels Midland Company |
| Jungbunzlauer Ladenburg GmbH |
| Corbion NV |
| Brenntag |
| BASF |
| Jungbunzlauer Suisse AG |
| Hawkins Watts Ltd. |
| Others |
Supply & Pricing Matrix
Molasses and starch substrate concentration in Central European agricultural zones anchors cost-plus contract structures for German acidulant processors, with margin pools accumulating at fermentation-derived specification tiers where clean-label premiums command formulation technical support bundling.
Pricing Analysis
Cost-plus contracts with molasses price indexation dominate procurement agreements between Bavarian beverage bottlers and citric acid suppliers. Three-tier pricing structure across fermentation-derived premium, synthetic standard, and mineral economy levels reflects purity grade and EFSA compliance certification. Pricing pressure stems from EFSA phosphoric acid safety re-evaluations forcing contingency formulation investments. Bakery units exhibit highest price sensitivity due to standardized leavening specifications, while dairy alternative manufacturers accept premium positioning for fermentation-lot traceability.
Supply Chain Analysis
Tariff exposure between EU member states and third-country molasses suppliers dominates supply chain risk assessment for German acidulant manufacturers. Production gravity centers on Germany, Switzerland, and the Netherlands for fermentation-derived acids, with Ludwigshafen-scale chemical complexes anchoring synthetic output. Raw material dependencies include sugar beet molasses, corn starch, and enzymatic catalyst feedstocks. Single-source vulnerability concentrates in precision fermentation strain supply. Distribution runs through direct producer relationships displacing traditional chemical distributors across the Munich-Stuttgart corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate substitution defense against enzymatic acid synthesis technologies that compress capital requirements for new fermentation entrants, threatening crystallization infrastructure returns at legacy production sites.
For Market Incumbents: Insulate citric acid revenue pools through backward integration into captive molasses supply contracts with Central European agricultural cooperatives. Deepen technical service capabilities for Baden-Württemberg sauce manufacturers to defend against enzymatic synthesis entrants offering formulation support. Prioritize crystallization infrastructure retrofit for enzymatic feedstock compatibility to neutralize precision fermentation cost advantages. For New Entrants and Emerging Players: Pursue white-space capture in Stuttgart-area plant-based dairy alternative acidulant supply, where fermentation-lot traceability demands exceed incumbent service capacity. Target direct procurement relationships with mid-sized dressing manufacturers seeking clean-label positioning unavailable through distributor channels. Deploy enzymatic synthesis pilot facilities to demonstrate cost compression against legacy fermentation economics. For Investors and Strategic Acquirers: Capital is best deployed toward precision fermentation specialists with demonstrated metabolic pathway optimization capabilities and existing relationships with Bavarian beverage bottlers. The five-to-ten year viability window favors assets with enzymatic synthesis scale-up engineering talent and REACH registration completion. Monitor EFSA phosphoric acid assessment outcomes as inflection indicator for formulation displacement velocity and lactic acid demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Molasses Supply | Captive substrate sourcing neutralizes harvest volatility exposure for Jungbunzlauer-scale producers. |
| Enzymatic Synthesis Scale-Up | Biocatalytic production compression threatens crystallization infrastructure returns at Ladenburg legacy sites. |
| Direct Producer Relationships | Channel restructuring displaces Brenntag intermediaries in Munich-Stuttgart corridor sauce procurement. |
| Fermentation-Lot Traceability Certification | Clean-label positioning commands premium positioning with Baden-Württemberg plant-based manufacturers. |
| REACH Registration Optimization | Streamlined hazard communication reduces compliance friction for acidulant imports into German facilities. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fermentation plant managers, beverage procurement leads, Baden-Württemberg sauce formulators, and ECHA compliance officers; and secondary validation through Bundesamt filings, EU Regulation 1333/2008 purity standard revisions, customs trade data, and SEC disclosures from listed chemical conglomerates. Bottom-up acidulant volume estimates triangulated against top-down food processing sector demand models.
Forecast inputs incorporated product type segmentation by fermentation versus synthetic origin, application segmentation spanning beverage through dairy alternatives, and packaging format velocity mismatches. CAGRs derived from regression analysis against food processing output indices and clean-label reformulation penetration rates across the analysis window. Industry-specific inputs included EFSA phosphoric acid assessment timelines and EU Farm to Fork Strategy implementation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by enzymatic synthesis specialists or accelerated EFSA regulatory displacement would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Protein Ingredient Market
Food Additives and Ingredients
Food Grade Glycerin Market
Food Additives and Ingredients
United Kingdom Food Acidulants Market
Food Additives and Ingredients
Tara Gum Market
Food Additives and Ingredients
Baking Enzymes Market
Food Additives and Ingredients
Asia Pacific Food Acidulants Market
Food Additives and Ingredients
Japan Food Emulsifiers Market
Food Additives and Ingredients
Monostarch Phosphate Market
Food Additives and Ingredients
Global Flaked Shortenings Market
Food Additives and Ingredients
Chocolate Wax Market
Food Additives and Ingredients
Global Calcium Propionate Market
Food Additives and Ingredients
Meat Stabilizers Blends Market
Food Additives and Ingredients
Africa Food Acidulants Market
Food Additives and Ingredients
Argentina Food Preservatives Market
Food Additives and Ingredients
Food Supplement Ingredients Market
Food Additives and Ingredients
Japan Food Enzymes Market