
 Lactylated Monoglyceride Market | 2026-2036
Lactylated Monoglyceride Market Size, Share, and Industry Trends Forecast 2026-2036
Lactylated Monoglyceride Market Foresight
Plant-derived lecithin is expanding as a partial substitute for synthetic emulsifiers in premium baked goods, altering cost structures for lactylated monoglyceride formulators. DuPont leverages its integrated food ingredient platform to sustain supply continuity across North American bakery chains. Corbion anchors European demand through specialized fermentation-derived emulsifier portfolios. Stepan Company competes on manufacturing scale in industrial-grade monoglyceride derivatives for mass-market applications.
Lactylated monoglycerides are fatty acid esters produced by reacting monoglycerides with lactic acid, yielding emulsifiers with HLB values typically ranging from 3 to 5 and superior alpha-crystalline stability in dough conditioning. These compounds function primarily as dough strengtheners, crumb softeners, and anti-staling agents in yeast-leavened bakery systems. Monolaurin dominates pharmaceutical and nutraceutical applications due to its established antimicrobial properties against Gram-positive pathogens. Powder form leads industrial procurement volumes for dry-blend convenience, though liquid variants capture margin in automated continuous-mixing bakery operations. The food and beverage vertical channels the majority of volume consumption, with cosmetics emerging as a concentrated margin pool for high-purity grades.
FDA food additive regulations under CFR 172.850 govern lactylated monoglyceride usage limits and labeling requirements in the United States, while EFSA evaluates novel emulsifier safety profiles under the EU food improvement agent framework. BIS certification requirements in India and GB standards administered by SAMR in China create divergent compliance pathways that fragment formulation strategies. Stakeholders must monitor evolving clean-label definitions across FDA, EFSA, and China's SAMR to anticipate reformulation mandates before they disrupt existing product registrations.
Market Dynamics
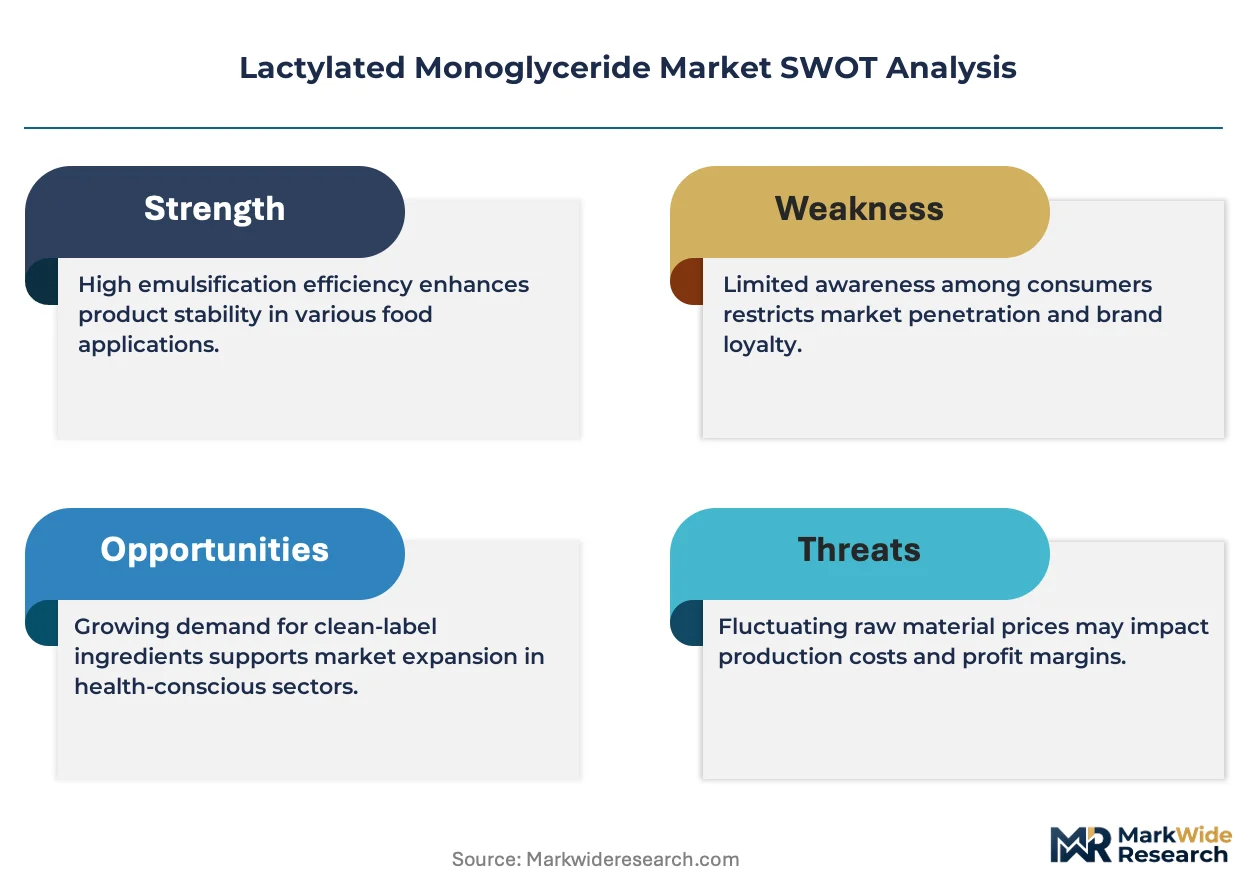
Bakery manufacturers face intensifying reformulation pressure as FDA and EFSA simultaneously tighten scrutiny of synthetic emulsifiers while clean-label definitions expand beyond ingredient lists into processing disclosures. This regulatory compression forces simultaneous compliance with divergent regional standards.
Growth Catalysts
- FDA CFR 172.850 expansion:Clarified usage limits for lactylated monoglycerides in yeast-leavened products reduce formulation uncertainty for US bakery chains. This accelerates standardization of dough conditioning protocols.
- India's PLI scheme for food processing:Domestic manufacturing incentives attract emulsifier production capacity to Maharashtra and Gujarat. Localized supply cuts import dependency for processed bread and biscuit manufacturers.
- Alpha-crystalline stability technology:Improved HLB tuning in lactylated monoglyceride variants extends shelf life in par-baked frozen dough systems. Industrial bakeries adopt these grades for distribution network expansion.
Market Restraints
- Palm oil price volatility:Feedstock cost swings compress margins for monoglyceride producers without backward integration into oleochemicals. Formulators pass through costs unevenly across contract structures.
- Plant-derived lecithin substitution:Premium baked goods manufacturers partial-replace synthetic emulsifiers with soy and sunflower lecithin. This erodes addressable volume in high-margin clean-label segments.
- EFSA novel food assessment timelines:Extended safety evaluation periods delay approval of modified lactylated ester variants. European innovation pipelines stall against faster-moving regulatory jurisdictions.
Strategic Opportunities
- Cosmetics-grade high-purity channels:Personal care formulators seek emulsifiers with pharmaceutical-grade monolaurin content. This application commands pricing multiples above food-grade equivalents.
- China's SAMR clean-label acceleration:Domestic processed food producers preempt regulatory tightening by adopting fermentation-derived emulsifiers. Early positioning captures formulation relationships ahead of mandate timelines.
- Continuous-mixing automation compatibility:Liquid lactylated monoglyceride variants integrate with industrial bakery equipment retrofits. Equipment OEMs specify these grades for new line installations.
Industry Challenges
- Cross-regional formulation divergence:BIS certification requirements in India, GB standards in China, and FDA labeling rules create incompatible product specifications. R&D teams maintain parallel formulation libraries.
- Fermentation scale-up capex intensity:Biological production routes for emulsifier alternatives require dedicated bioreactor infrastructure. Capital allocation debates split between chemical and biotech process investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lactylated Monoglyceride Market |
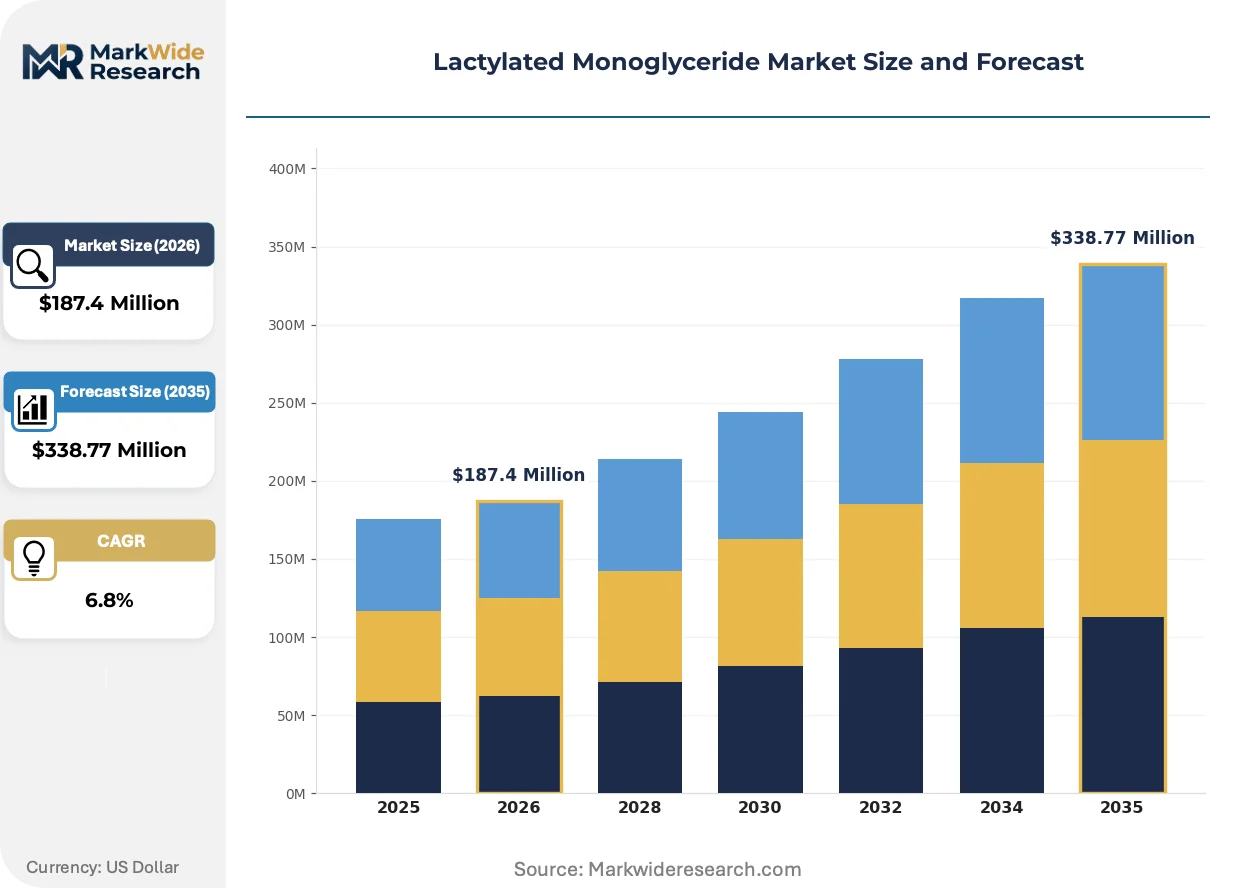
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monolaurin, Monostearin, Monopalmitin, Others Application: Baked Goods, Dairy Products, Confectionery, Sauces Industry Vertical: Food & Beverage, Pharmaceuticals, Cosmetics, Nutraceuticals Form: Liquid, Powder, Granular, Paste |
| Companies Covered | DuPont, Corbion, Riken Vitamin Co., Ltd., Palsgaard, Stepan Company, Galactic, Guangzhou Cardlo Biotechnology Co., Ltd., Zhengzhou Yizeli Industrial Co., Ltd., Fine Organics Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lactylated Monoglyceride Market Shifts & Advancements
Emulsifier technology is converging with bioprocessing advances and automated manufacturing, compressing development cycles while fragmenting competitive positioning between chemical and fermentation-derived supply bases.
Enzymatic interesterification for tailored monoglyceride structures is unifying functionality previously achieved through chemical modification with cleaner processing credentials. European specialty ingredient houses deploy these biocatalytic routes for premium bakery accounts. The technology is unifying performance specifications across organic and conventional product lines, collapsing historical quality tier distinctions.
REACH substance evaluation under the EU's chemicals strategy for sustainability is extending disclosure requirements to food-contact emulsifier precursors. Industrial bakery suppliers must now document full oleochemical supply chain origins. German and Dutch manufacturers lead compliance investments, creating specification gaps with southern European competitors.
Buyer consolidation among North American retail bakery chains compresses supplier qualification timelines while extending contract durations. Procurement teams demand multi-year price locks in exchange for volume commitments. This pattern concentrates purchasing power with three national distributors, marginalizing regional emulsifier blenders.
Lactylated Monoglyceride Market Segmentation
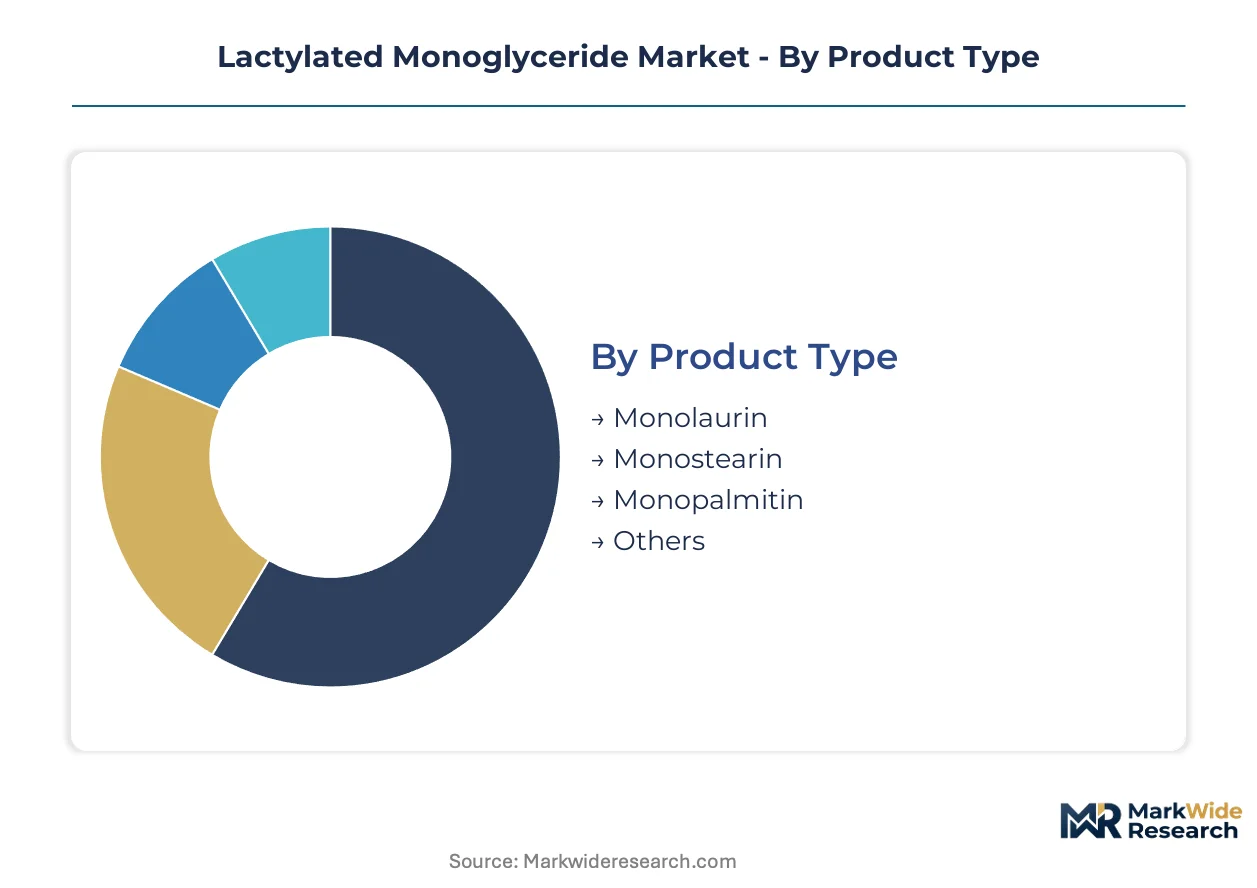
Lactylated monoglyceride procurement splits across technical specifications, regulatory pathways, and processing requirements. Manufacturers optimize formulations by matching HLB values, crystalline stability needs, and clean-label positioning to specific end-use certifications.
Product Type:
FDA CFR 172.850 governs monolaurin and monostearin usage limits in yeast-leavened products, while EFSA's food improvement agent framework evaluates novel ester variants. Pharmaceutical-grade monolaurin requires additional USP or EP certification for antimicrobial applications.
- Monolaurin:Glycerol ester of lauric acid with established antimicrobial efficacy against Gram-positive pathogens. Pharmaceutical and nutraceutical formulators in the United States concentrate demand for USP-certified grades, constrained by EFSA's extended novel food assessment timelines for modified variants.
- Monostearin:Saturated C18 fatty acid ester delivering superior alpha-crystalline stability in dough conditioning. Industrial bakeries across Germany and the Netherlands specify this grade for par-baked frozen dough distribution networks, driven by REACH supply chain disclosure mandates for oleochemical precursors.
- Monopalmitin:C16 saturated ester valued for emulsion stability in confectionery fat systems. European specialty ingredient houses favor this variant for premium chocolate applications.
- Others:Mixed-chain and custom-esterified monoglycerides including monoolein and monomyristin. Niche applications in aerosol food sprays and pharmaceutical solubilization.
Leading the category by volume: Monostearin. Growing fastest: Monolaurin.
Application:
Cost tier stratification separates commodity baked goods from premium confectionery and clean-label dairy segments. Reformulation investments scale inversely with per-unit ingredient sensitivity.
- Baked Goods:Dough strengthening and crumb softening in yeast-leavened systems. North American retail bakery chains demand multi-year supply contracts with price locks, compressing regional blender margins while concentrating procurement with national distributors.
- Dairy Products:Emulsion stabilization in creamers and processed cheese. Clean-label positioning drives partial substitution with plant-derived lecithin in premium segments.
- Confectionery:Fat bloom inhibition and texture control in chocolate and coatings. German manufacturers lead compliance investments for REACH substance evaluation disclosures.
- Sauces:Viscosity modification and emulsion stability in pourable dressings. Automated continuous-mixing equipment retrofits favor liquid emulsifier integration.
Volume concentrates in baked goods. Margin accrues fastest to confectionery.
Industry Vertical:
Customer type fragmentation separates mass-market food processors from pharmaceutical-grade purity requirements and cosmetics formulators seeking pharmaceutical-grade monolaurin content.
- Food & Beverage:Channels majority volume through industrial bakery and dairy processing. India's PLI scheme for food processing attracts emulsifier production capacity to Maharashtra and Gujarat, cutting import dependency.
- Pharmaceuticals:Antimicrobial and solubilization applications require documented full oleochemical supply chain origins under REACH. Pricing multiples exceed food-grade equivalents significantly.
- Cosmetics:Personal care formulators seek high-purity grades for emulsion stability. This vertical commands concentrated margin pools for fermentation-derived alternatives.
- Nutraceuticals:Dietary supplement encapsulation and delivery systems. Growth correlates with antimicrobial positioning in immune-support formulations.
Food & Beverage dominates procurement tonnage. Cosmetics generates steepest expansion trajectory.
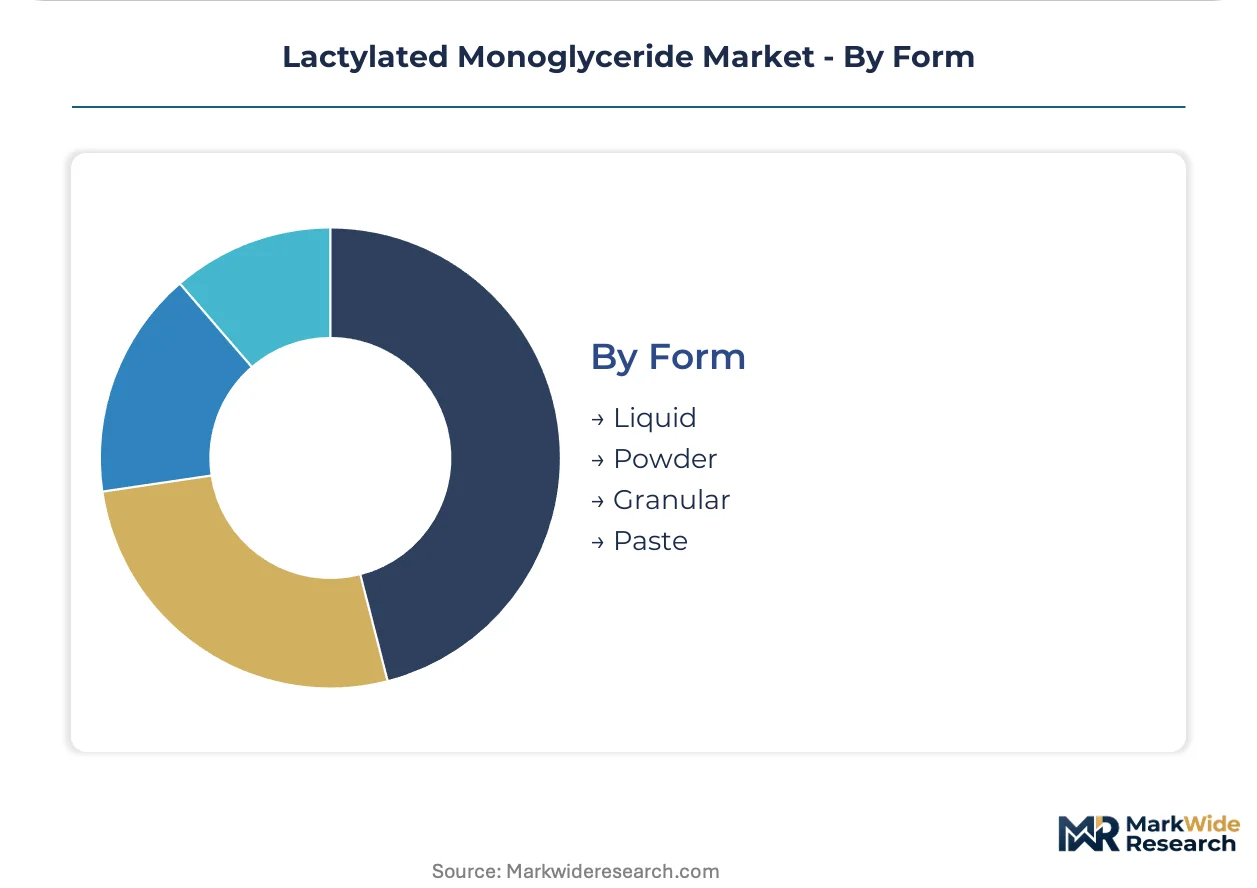
Form:
Supply concentration in powder production serves dry-blend convenience, while liquid variants capture automation-aligned demand from equipment OEM specifications.
- Liquid:Pumpable emulsifier for automated continuous-mixing bakery operations. Equipment OEMs specify these grades for new line installations in North American industrial bakeries.
- Powder:Free-flowing form for dry premix and flour fortification. Leads industrial procurement volumes through distribution efficiency and extended shelf stability.
- Granular:Intermediate flow characteristics for semi-automated dosing systems. Preferred in mid-scale European bakery operations.
- Paste:High-concentration semi-solid for specialized confectionery fat systems. Limited to artisan and premium chocolate applications.
Powder leads by procurement volume. Liquid gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's food processing special economic zones attract emulsifier manufacturing investments through India's PLI scheme incentives. Domestic production capacity cuts import dependency for processed bread and biscuit manufacturers across western India.
United States
Industrial bakery chains concentrate procurement power through multi-year supply contracts with price locks. FDA CFR 172.850 governs lactylated monoglyceride usage limits in yeast-leavened products. Chicago and Minneapolis anchor North American distribution networks for dough conditioning emulsifiers.
Germany
REACH substance evaluation mandates full oleochemical supply chain disclosure for food-contact emulsifier precursors. German manufacturers lead compliance investments ahead of southern European competitors. The Rhine-Ruhr industrial corridor concentrates fermentation-derived emulsifier production capacity.
China
GB standards administered by SAMR create divergent compliance pathways that fragment formulation strategies. Domestic processed food producers preempt regulatory tightening by adopting fermentation-derived emulsifiers. Yangtze River Delta clusters scale manufacturing for both domestic consumption and export markets.
India
Maharashtra and Gujarat attract emulsifier production capacity through the PLI scheme for food processing. BIS certification requirements create formulation specifications distinct from FDA and EFSA standards. Ahmedabad and Mumbai industrial zones localize supply for bread and biscuit manufacturers.
Netherlands
Rotterdam's oleochemical hub supplies feedstock for European monoglyceride derivatives. EFSA's extended novel food assessment timelines delay approval of modified lactylated ester variants. Dutch manufacturers integrate enzymatic interesterification for premium bakery accounts seeking cleaner processing credentials.
Lactylated Monoglyceride Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with fermentation-derived portfolios commanding premium positioning against chemical-process alternatives. The vendor base organizes around three strategic archetypes: integrated food ingredient platforms, specialized fermentation houses, and scale-driven industrial chemical producers. Consolidation pressure intensifies as buyer concentration among North American retail bakery chains compresses supplier qualification timelines. Dominant competitive moves include backward integration into oleochemical feedstocks and geographic expansion through localized production incentives.
Within the integrated platform tier, DuPont leverages supply continuity across North American bakery chains. Corbion anchors European demand through specialized fermentation-derived portfolios. Stepan Company occupies a position at the scale-driven end for industrial-grade monoglyceride derivatives. These three exemplify how competitive positioning fragments between biotechnology credentials and chemical manufacturing efficiency.
| Leading Market Players |
|---|
| DuPont |
| Corbion |
| Riken Vitamin Co., Ltd. |
| Palsgaard |
| Stepan Company |
| Galactic |
| Guangzhou Cardlo Biotechnology Co., Ltd. |
| Zhengzhou Yizeli Industrial Co., Ltd. |
| Fine Organics Industries Ltd. |
| Others |
Supply & Pricing Matrix
North American retail bakery chain procurement teams concentrate purchasing power through multi-year supply contracts with price locks, anchoring a contract-based long-term offtake pricing model that marginalizes regional emulsifier blenders. This buyer concentration compresses supplier margins while extending contract durations across industrial-grade monoglyceride derivatives.
Pricing Analysis
Short lead-time premiums command substantial markups over standard delivery windows, particularly for liquid lactylated monoglyceride variants specified by equipment OEMs for automated continuous-mixing retrofits. Pricing stratifies across pharmaceutical-grade, food-grade, and industrial-grade tiers, with USP-certified monolaurin capturing multiples above standard bakery grades. Cost compression in industrial-grade segments is intensifying because palm oil feedstock volatility passes through unevenly across contract structures. Mass-market baked goods manufacturers exhibit highest price sensitivity, while cosmetics formulators seeking high-purity grades demonstrate lowest sensitivity.
Supply Chain Analysis
Dual-sourcing requirements mandated by North American industrial bakery chains force qualification of at least two suppliers per emulsifier grade, fragmenting procurement across integrated platforms and specialized fermentation houses. Manufacturing concentrates in the United States, Germany, and China, with Rotterdam's oleochemical hub feeding European derivative production. Raw material dependencies center on palm oil, lactic acid, and glycerol feedstocks. Single-source vulnerability in Malaysian and Indonesian palm oil supply creates exposure to commodity price swings. Distribution runs through national distributors serving retail bakery chains, bypassing regional blenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation scale-up capex intensity constrains biological production route expansion, propping pricing for fermentation-derived emulsifier portfolios as chemical-process alternatives face margin compression from feedstock volatility.
For Market Incumbents: Deepen backward integration into oleochemical feedstocks to insulate margins from palm oil price swings. Anchor supply continuity through captive production of lactic acid precursors. Plant-derived lecithin substitution in premium segments threatens addressable volume; defend positioning through USP and EP certification investments for pharmaceutical-grade monolaurin channels. For New Entrants and Emerging Players: Equipment OEMs represent the most accessible channel partner type for liquid variant penetration, specifying grades for new line installations without incumbent contract lock-in. Target cosmetics-grade high-purity segments where fermentation credentials command pricing multiples absent in commodity food-grade competition. White-space exists in India's Maharashtra and Gujarat production zones under PLI scheme incentives, cutting import dependency for domestic bread and biscuit manufacturers. For Investors and Strategic Acquirers: The window for entry favors fermentation-derived specialists with existing bioreactor infrastructure and clean-label positioning ahead of SAMR regulatory acceleration in China. Long-term viability hinges on biotechnology credentials displacing chemical-process efficiency as regulatory scrutiny tightens across FDA, EFSA, and SAMR jurisdictions. Watch EFSA novel food assessment timeline compression as inflection signal for European innovation pipeline reactivation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oleochemicals | Captive palm oil and glycerol supply insulates margins from feedstock volatility in Malaysia and Indonesia. |
| Fermentation Capacity Expansion | Bioreactor infrastructure in the Rhine-Ruhr corridor captures cosmetics-grade premium pricing from personal care formulators. |
| USP Certification Investment | Pharmaceutical-grade monolaurin documentation unlocks antimicrobial application pricing multiples above food-grade equivalents. |
| Continuous-Mixing Liquid Variant Development | Equipment OEM specifications for automated bakery lines displace powder-form incumbents in retrofit cycles. |
| India PLI Scheme Localization | Maharashtra and Gujarat production capacity cuts import dependency for domestic processed bread manufacturers. |
Research Methodology
Trade databases, SEC filings, and customs records formed the secondary backbone, supplemented by EFSA food improvement agent framework documentation and FDA CFR 172.850 regulatory filings. Primary interviews with bakery procurement directors, emulsifier plant managers, and cosmetics formulators validated supply chain configurations and pricing structures. Bottom-up and top-down triangulation cross-checked volume estimates against oleochemical feedstock consumption patterns and end-use application disclosures.
Bottom-up modeling anchored projections in segment-level demand drivers across product type, application, industry vertical, and form dimensions, while top-down validation checked aggregate figures against macro food processing trends. CAGRs derived from fitted growth curves across the analysis window, incorporating alpha-crystalline stability technology adoption rates and clean-label regulatory acceleration timelines as industry-specific inputs.
Caveats apply where EFSA novel food assessment timeline compression, palm oil supply disruptions, or SAMR clean-label mandate acceleration could materially shift the outlook. Deviation in fermentation scale-up investment levels would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
United States Food Acidulants Market
Food Additives and Ingredients
China Monosodium Glutamate (MSG) Market
Food Additives and Ingredients
Natural Food Color Ingredients Market
Food Additives and Ingredients
Potassium Polymetaphosphate Food Additives Market
Food Additives and Ingredients
Australia Feed Additives Market
Food Additives and Ingredients
Seitan Powder Market
Food Additives and Ingredients
Africa Food Emulsifiers Market
Food Additives and Ingredients
Italy Food Acidulants Market
Food Additives and Ingredients
Global Gamma Linolenic Acid Market
Food Additives and Ingredients
Food Antifoaming Agents Market
Food Additives and Ingredients
Octadecanedioic Acid (ODDA) Market
Food Additives and Ingredients
Europe Feed Anti-Caking Agents Market
Food Additives and Ingredients
Cream Emulsifier Market
Food Additives and Ingredients
Acetylated Distarch Adipate Market
Food Additives and Ingredients
Brazil Food Ingredient Market
Food Additives and Ingredients
Japan Feed Additives Market