
 Alpha-Amylase Baking Enzyme Market | 2026-2036
Alpha-Amylase Baking Enzyme Market Size, Share, and Industry Trends Forecast 2026-2036
Alpha-Amylase Baking Enzyme Market Analysis
Artisan and clean-label commercial bakeries is collapsing the historical dominance of mass industrial bread producers as the primary enzyme buyer archetype. Novozymes A/S leverages its microbial fermentation expertise to supply thermostable amylase variants for premium sourdough applications. DSM-Firmenich anchors its position through enzyme blends that reduce acrylamide formation while extending shelf life in par-baked goods. DuPont de Nemours, Inc. competes with granulated formats optimized for dusty-free handling in mid-scale bakery operations.
Alpha-amylase baking enzymes are glycoside hydrolases that catalyze the hydrolysis of internal alpha-1,4-glycosidic bonds in starch, typically operating at pH 4.5 to 7.0 and temperatures between 20°C and 95°C depending on fungal, bacterial, or maltogenic origin; their primary industrial purpose is to modify dough rheology, accelerate fermentation, and improve crumb structure in wheat-based baked goods. Powder formulations dominate high-volume industrial channels where dosing precision and shelf stability outweigh hydration concerns, while liquid concentrates gain traction in continuous-process bread plants seeking automated metering integration. The gluten-free formulation segment represents the fastest-growing margin pool as enzyme suppliers develop tailored amylase systems that compensate for the structural deficiencies of rice, tapioca, and sorghum flours.
The FDA's GRAS self-affirmation pathway and the EPA's biotechnology oversight under TSCA shape product registration timelines for novel microbial strains entering the US market, while EFSA evaluates enzyme preparations under the EU Food Improvement Agent regulation with escalating purity requirements. BIS certification and FSSAI food additive approvals govern import and domestic sale in India, where local enzyme producers navigate dual compliance burdens. Stakeholders must monitor evolving enzyme labeling thresholds in major jurisdictions as clean-label scrutiny tightens and bioengineered strain disclosure mandates expand beyond current voluntary frameworks.
Market Dynamics
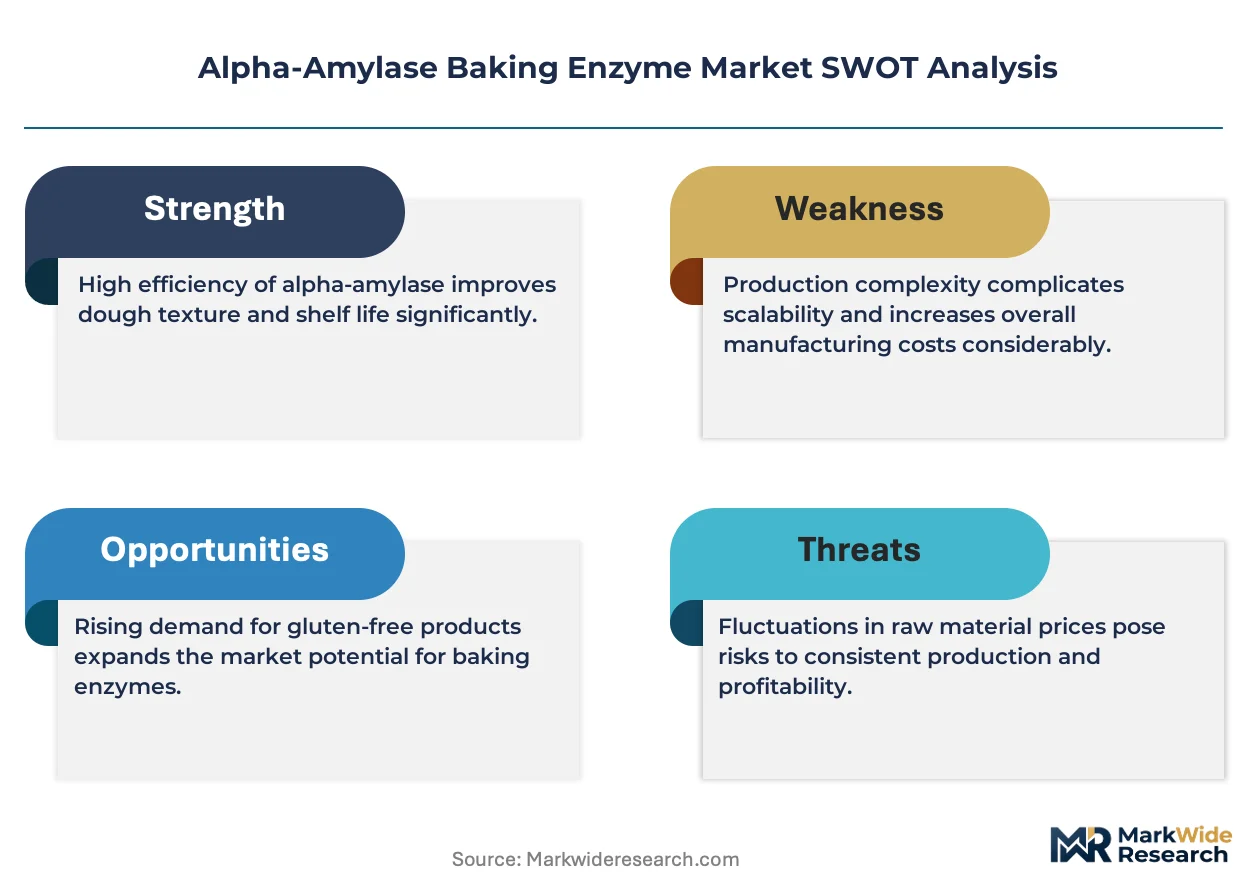
Clean-label mandates from the EU Green Deal and REACH are collapsing demand for chemical dough conditioners, forcing industrial bakeries to rebuild formulation pipelines around bio-based enzyme systems. This regulatory compression is redistributing purchasing power toward suppliers with microbial fermentation capabilities and thermostable variant portfolios.
Growth Catalysts
- REACH chemical substitution deadlines:European industrial bakeries face phased reduction of bromate and azodicarbonamide, redirecting capital toward amylase-based conditioning systems. German craft bakeries lead this transition.
- Thermostable bacterial amylases:Enzyme variants operating above 85°C enable continuous-process bread plants to reduce fermentation cycle times without gelatinization failure. Par-baked goods manufacturers adopt these formats fastest.
- Gluten-free flour structural compensation:Rice and sorghum formulations lack native gluten networks, creating enzyme-dependent demand for tailored amylase systems that restore crumb elasticity in allergen-free products.
Market Restraints
- Feedstock concentration in Danish fermentation capacity:Major enzyme suppliers rely on captive microbial production clustered near Copenhagen, creating single-source vulnerability for thermostable variants.
- Fungal amylase temperature ceiling:Fungal-derived enzymes denature above 60°C, excluding them from high-temperature industrial processes and limiting application breadth.
- GRAS self-affirmation timeline uncertainty:FDA's voluntary notification pathway for novel bacterial strains creates unpredictable commercialization delays without formal approval guarantees.
Strategic Opportunities
- India FSSAI enzyme additive expansion:India's food safety regulator is expanding permitted enzyme categories in packaged bread, opening formulation partnerships with domestic millers and quick-service bakery chains.
- Acrylamide-reduction enzyme blends:DSM-Firmenich's asparaginase-amylase combinations address EU acrylamide monitoring obligations while extending shelf life, creating dual-value positioning.
- Liquid concentrate automated metering:Continuous-process plants seek pump-integrated dosing systems that eliminate powder handling labor and cross-contamination risk in high-output facilities.
Industry Challenges
- Enzymologist talent scarcity:Industrial microbiology programs produce insufficient specialists in fungal strain optimization and fermentation scale-up, constraining R&D throughput at mid-tier suppliers.
- Cross-border BIS certification delays:Indian import requirements for enzyme preparations create 8-14 month approval windows, disrupting just-in-time supply to domestic biscuit manufacturers.
- Legacy powder-handling infrastructure:Retrofitting dusty-free granulated formats into existing dosing equipment requires capital expenditure that smaller artisan cooperatives defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alpha-Amylase Baking Enzyme Market |
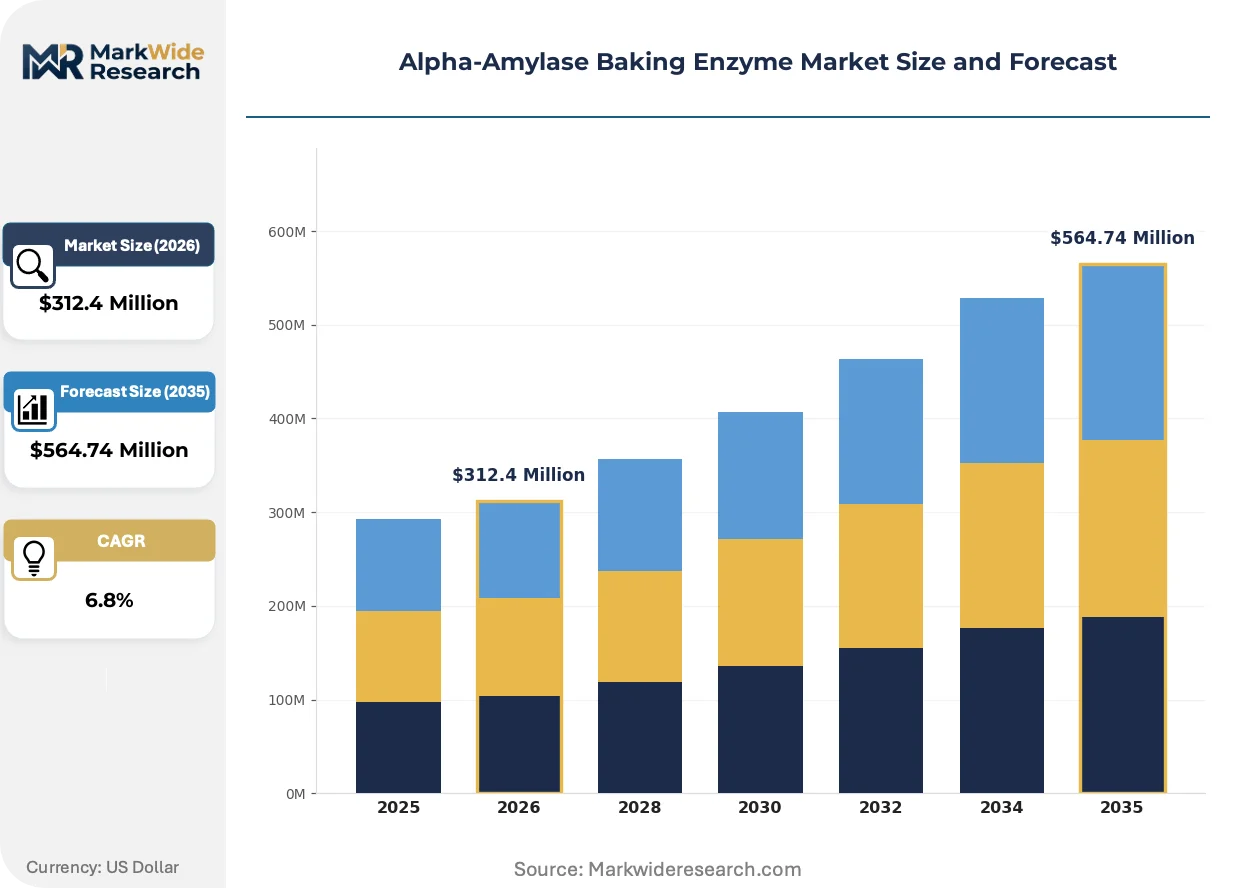
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granulated, Tablet Application: Bread, Pastry, Cookies, Tortillas End User: Bakeries, Food Manufacturers, Restaurants, Home Bakers Formulation Type: Organic, Conventional, Gluten-Free, High-Amylose |
| Companies Covered | Novozymes A/S, DuPont de Nemours, Inc., DSM-Firmenich, AB Enzymes GmbH, International Flavors & Fragrances Inc., Amano Enzyme Inc., Puratos N.V., Mianyang Habio Bioengineering Co., Ltd., Chr. Hansen Holding A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alpha-Amylase Baking Enzyme Market Emerging Trajectories
Formulation science is converging with regulatory compliance engineering, producing enzyme systems that simultaneously modify dough rheology and satisfy contaminant thresholds. This dual-function imperative is compressing supplier R&D cycles and reshaping buyer evaluation criteria.
Encapsulated enzyme delivery systems are miniaturizing. Microencapsulation technology using lipid or protein matrices protects amylase activity through high-shear mixing and freezing stages. Premium frozen dough manufacturers adopt these formats to preserve enzyme function across extended cold-chain distribution. This miniaturization is enabling just-in-time enzyme activation that reduces pre-fermentation variability.
EFSA's escalating purity requirements under the Food Improvement Agent regulation are forcing enzyme suppliers to invest in downstream processing capacity. Residual DNA and allergen thresholds have tightened twice since 2020. European industrial bakeries now demand certificate-of-analysis documentation for every batch, shifting procurement toward vertically integrated suppliers with in-house quality laboratories.
Clean-label scrutiny is compressing ingredient declaration thresholds. German and French retailers now require enzyme disclosure on front-of-pack labels, eliminating "processing aid" exemptions that previously hid amylase presence. Artisan bakeries respond by marketing enzyme sourcing transparency, while industrial producers seek single-enzyme solutions that simplify label architecture and reduce consumer skepticism.
Alpha-Amylase Baking Enzyme Market Segmentation
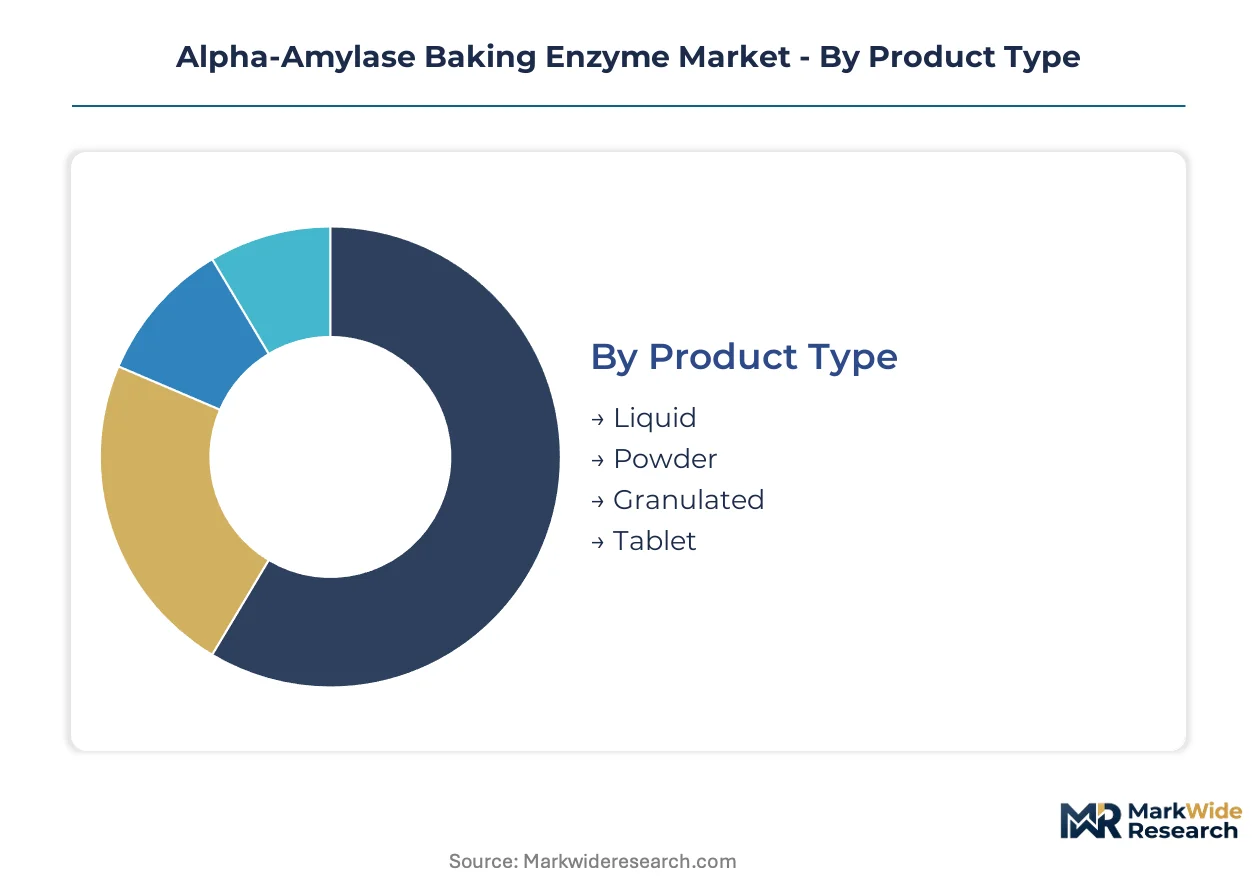
Alpha-amylase enzymes reach end-users through distinct channel architectures that shape formulation requirements and packaging formats. Industrial buyers prioritize automated dosing compatibility, while artisan channels demand flexible minimum order quantities and handling safety.
Product Type:
Powder and liquid formats dominate high-throughput industrial channels where dosing precision and automation integration determine procurement decisions, while granulated and tablet variants serve smaller-scale operations with legacy equipment constraints.
- Liquid:Concentrated aqueous suspensions enable pump-integrated metering in continuous-process bread plants. German industrial bakeries favor liquid formats for sourdough fermentation control where temperature ramping demands rapid enzyme dispersion.
- Powder:Spray-dried preparations offer extended shelf stability and precise gravimetric dosing in high-volume facilities. Dust exposure concerns are driving powder users toward granulated upgrades despite capital retrofit costs.
- Granulated:Agglomerated particles reduce airborne dust during manual handling, appealing to mid-scale artisan cooperatives with limited ventilation infrastructure.
- Tablet:Unit-dose compressed formats serve home bakers and small restaurant kitchens where measurement simplicity outweighs per-unit cost premiums.
By volume, Powder leads. By growth pace, Liquid is ahead.
Application:
Cost-tier stratification separates commodity bread applications from premium pastry segments, with enzyme specifications tightening as product margins expand.
- Bread:Wheat-based loaves consume the largest enzyme volumes, with fungal amylases preferred for sponge-and-dough methods and bacterial variants dominating no-time processes. Clean-label reformulation in French and German retail chains is accelerating thermostable enzyme adoption.
- Pastry:Laminated doughs require controlled amylolysis to manage extensibility without compromising butter layer integrity. Danish and croissant manufacturers specify low-protease fungal preparations to prevent gluten weakening.
- Cookies:Crisp texture specifications demand limited starch modification, restricting amylase use to conditioning-focused applications rather than structural modification.
- Tortillas:Corn and flour tortilla producers use amylases to improve rollability and reduce staling, with Mexican and US Southwest operations representing concentrated demand pockets.
Bread commands the volume base. Pastry applications are climbing the fastest as premiumization extends enzyme specifications.
End User:
Customer-type segmentation reveals divergent procurement patterns, with food manufacturers consolidating supply contracts while bakeries fragment across regional distributors.
- Bakeries:Artisan and industrial bakery operations constitute the core demand pool, with enzyme selection driven by fermentation schedule, flour variability, and clean-label positioning requirements.
- Food Manufacturers:Packaged goods producers integrate amylases into frozen dough and par-baked systems, prioritizing batch consistency and extended distribution stability over artisan flexibility.
- Restaurants:Foodservice operations with in-house baking programs source through broadline distributors, accepting limited formulation customization in exchange for logistical simplicity.
- Home Bakers:Consumer-facing enzyme preparations remain niche, concentrated in specialty retail and direct-to-online channels serving sourdough enthusiasts.
Food Manufacturers lead by volume commitment. Bakeries are gaining share fastest as artisan segment fragmentation creates new supplier entry points.
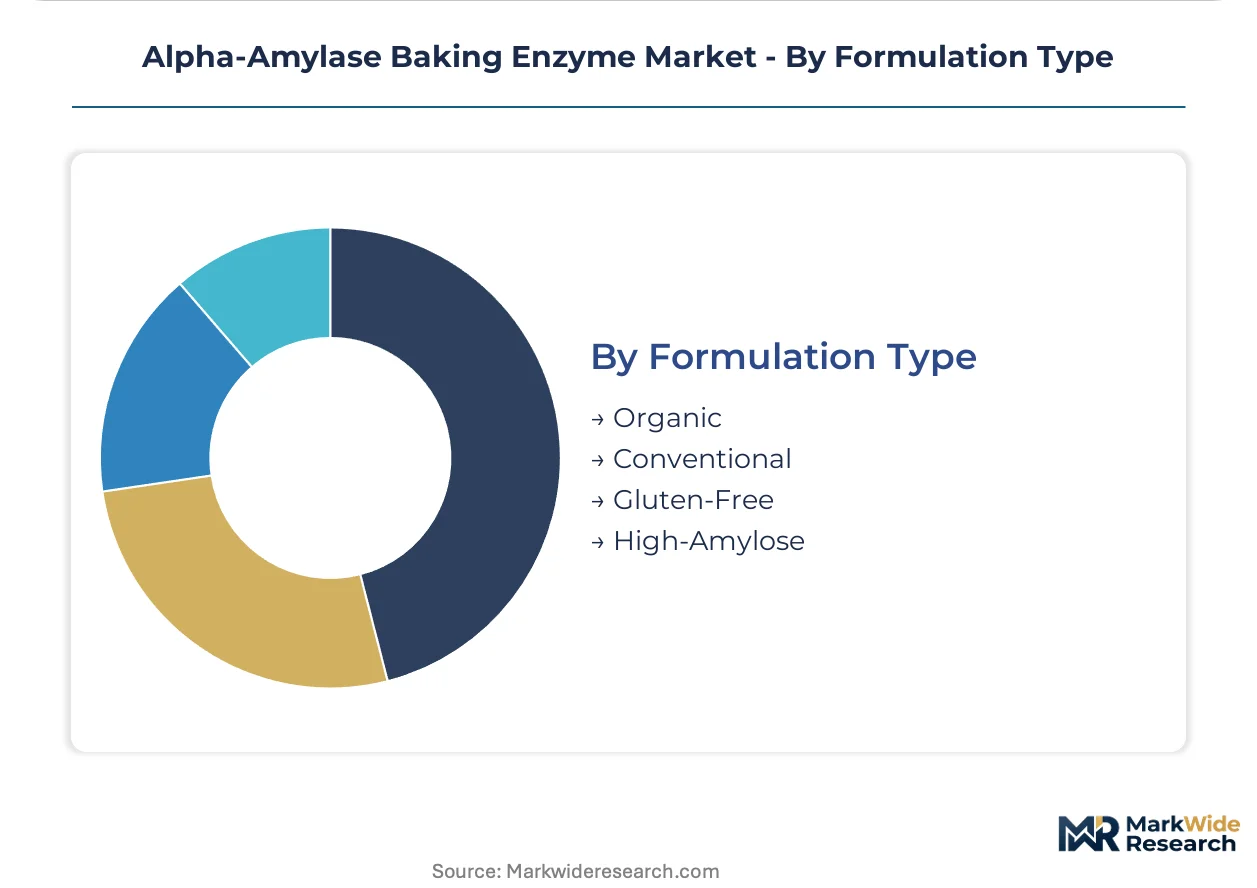
Formulation Type:
Margin concentration follows certification tier, with organic and gluten-free formulations commanding price premiums that justify specialized enzyme development investment.
- Gluten-Free:Rice, tapioca, and sorghum flour systems lack native gluten networks, creating enzyme-dependent demand for tailored amylase blends that restore crumb elasticity and shelf life. This segment commands the steepest expansion trajectory among all formulation categories.
- Organic:Certified organic enzymes require fermentation substrates and processing aids meeting USDA Organic or EU Organic standards, constraining supplier pools and extending lead times.
- Conventional:Standard-grade enzymes serve cost-sensitive industrial applications where certification premiums are not recoverable through product positioning.
- High-Amylose:Specialty wheat varieties with elevated amylose content demand adjusted enzyme dosing protocols, serving resistant starch and low-glycemic product development pipelines.
Conventional formulations dominate volume. Gluten-Free is expanding most quickly as allergen-free product lines proliferate across retail and foodservice channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Artisan and industrial bakery buyers concentrate in Germany, the United States, and India, with regulatory pressure from the EU Green Deal and FDA GRAS pathways reshaping procurement patterns across these markets. Enzyme suppliers are calibrating regional strategies around clean-label mandates and fermentation infrastructure availability.
Germany
Clean-label reformulation in retail chains and craft baking cooperatives drives enzyme adoption, with the EU Green Deal and REACH compliance deadlines forcing bromate substitution. Bavaria's industrial baking corridor around Munich anchors thermostable amylase demand for par-baked systems.
United States
Continuous-process bread plants and frozen dough manufacturers seek automated liquid dosing integration, with FDA GRAS self-affirmation timelines creating commercialization uncertainty for novel bacterial strains. The Midwest baking belt spanning Illinois and Ohio concentrates industrial enzyme procurement.
India
Packaged bread expansion and quick-service bakery chains create formulation partnership opportunities, with FSSAI enzyme additive category expansion opening regulatory pathways. Maharashtra's Mumbai-Pune industrial corridor hosts domestic millers integrating amylase conditioning systems.
China
Industrial bakery scale-up and Western-style bread penetration drive enzyme volume, with SAMR food additive standards and GB compliance requirements governing import and domestic production. The Yangtze River Delta around Shanghai anchors foreign supplier distribution networks.
Brazil
Tortilla and pan bread producers adopt amylases for rollability and shelf-life extension, with ANVISA food additive regulations shaping product registration. São Paulo state's baking industrial park concentrates demand from both packaged goods manufacturers and foodservice distributors.
Alpha-Amylase Baking Enzyme Market Vendor Landscape
Player mix skews toward microbial fermentation specialists with captive biotech capacity, creating a tiered structure where vertically integrated multinationals occupy premium formulation segments and regional enzyme houses compete on price-accessible standard grades. Two strategic archetypes dominate: thermostable variant developers serving continuous-process industrial bakeries, and clean-label positioning specialists targeting artisan cooperatives with transparency-focused sourcing narratives. Competitive moves concentrate on downstream processing capacity expansion for EFSA-compliant purity thresholds, and geographic licensing partnerships to circumvent BIS certification delays in India.
Within the fermentation-anchored tier, Novozymes A/S and DSM-Firmenich exemplify vertically integrated positions with in-house quality laboratories and microbial strain optimization capabilities. DuPont de Nemours, Inc. occupies a position emphasizing granulated format development for dusty-free handling requirements. AB Enzymes GmbH represents the regional specialist archetype with European market concentration. These three anchors illustrate how supplier strategies diverge between thermostable innovation pipelines and clean-label compliance engineering.
| Leading Market Players |
|---|
| Novozymes A/S |
| DuPont de Nemours, Inc. |
| DSM-Firmenich |
| AB Enzymes GmbH |
| International Flavors & Fragrances Inc. |
| Amano Enzyme Inc. |
| Puratos N.V. |
| Mianyang Habio Bioengineering Co., Ltd. |
| Chr. Hansen Holding A/S |
| Others |
Supply Flow & Price Mechanics
Chemical conditioner substitution by bio-based amylase systems is simultaneously redistributing supply geography toward Danish fermentation clusters and compressing pricing premiums for thermostable bacterial variants as REACH compliance deadlines accelerate industrial buyer procurement.
Pricing Analysis
Thermostable bacterial amylase variants command substantial premiums over fungal-derived alternatives and next-generation encapsulation formats. Three-tier pricing structure across premium thermostable, standard fungal, and economy maltogenic grades reflects EFSA purity certification levels and volume scale commitments from industrial bakeries. Cost compression in the economy tier is intensifying because Indian domestic producers are expanding FSSAI-approved capacity. Artisan cooperatives exhibit highest price sensitivity due to legacy equipment retrofit costs, while par-baked goods manufacturers show lowest sensitivity given fermentation cycle time savings.
Supply Chain Analysis
Strategic stockpile preferences dominate among industrial bakeries facing REACH substitution deadlines, while just-in-time inventory governs artisan channels with flexible flour sourcing. Captive microbial production concentrates in Denmark, China, and India, with fermentation substrate supply drawing from agricultural processing residues and specialized nutrient media. Single-source vulnerability around Copenhagen-based thermostable variant capacity represents the primary structural risk. Distribution runs through regional enzyme distributors serving millers and bakery ingredient blenders, with direct supply contracts consolidating among multinational food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation is accelerating as clean-label mandates splinter demand across artisan transparency-seekers, industrial efficiency-optimizers, and gluten-free formulation specialists, creating distinct service and certification niches.
For Market Incumbents: Shield market position by deepening captive fermentation capacity in India to circumvent BIS certification delays, while accelerating downstream processing investments to meet EFSA's escalating purity thresholds. Novozymes A/S and DSM-Firmenich exemplify this defensive posture through in-house quality laboratory expansion. The priority lever centers on thermostable variant R&D pipelines that maintain performance differentiation against emerging bacterial strain developers.
For New Entrants and Emerging Players: Technical service gaps in artisan cooperative enzyme selection and dosing optimization represent the most penetrable white-space opportunity, as incumbent technical teams prioritize multinational food manufacturer accounts. Target India's quick-service bakery chains through FSSAI formulation partnership models, leveraging domestic regulatory navigation capabilities that foreign suppliers lack. The most viable go-to-market angle combines granulated format supply with hands-on fermentation training for mid-scale operations.
For Investors and Strategic Acquirers: The market sits at a substitution-acceleration phase that favors vertically integrated fermentation specialists with regulatory approval portfolios over pure-play formulation houses. Long-term viability hinges on backward integration into microbial strain optimization capabilities rather than reliance on licensed production. Acquisition targets should demonstrate EFSA-compliant downstream processing and established BIS certification pathways. The signal to watch is FSSAI enzyme additive category expansion velocity, which would indicate regulatory pathway widening for domestic Indian production investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Fermentation Capacity Expansion | Reduces single-source dependency on Danish thermostable variant supply. |
| EFSA-Compliant Downstream Processing Investment | Enables batch certificate-of-analysis documentation for European industrial bakeries. |
| BIS Certification Partnership Structuring | Accelerates 8-14 month Indian import approval windows for enzyme preparations. |
| Gluten-Free Formulation R&D Pipeline | Captures fastest-growing margin pool in rice and sorghum flour structural compensation. |
| Liquid Concentrate Automated Metering Integration | Eliminates powder handling labor and cross-contamination risk in continuous-process plants. |
Methodological Framework
Cross-validation between primary interviews with industrial bakery procurement directors, artisan cooperative technical managers, and enzyme supplier fermentation scientists anchors the qualitative findings against secondary validation from EFSA Food Improvement Agent regulatory filings, FSSAI additive category notifications, and customs trade data. Bottom-up triangulation incorporates granular production capacity estimates from fermentation facility disclosures, while top-down approaches benchmark against packaged bread and par-baked goods volume trends.
Sensitivity analysis across formulation type, end-user scale, and regional regulatory cluster dimensions shapes the analytical framework over the projection horizon. Segmentation modeling spans product format, application, customer type, and certification tier. CAGRs derive from volume-demand elasticity estimates tied to clean-label reformulation pace and substitution timeline assumptions for chemical conditioners. Industry-specific forecast inputs include REACH compliance deadline phasing and FSSAI enzyme category expansion trajectories.
Forecasts assume regulatory continuity in EU REACH, FDA GRAS, and FSSAI additive regimes; material policy shifts would require re-modeling. Specific risk factors include EFSA purity threshold escalation, BIS certification timeline volatility, and microbial strain disclosure mandate expansion. Revision becomes warranted when thermostable variant supply concentration crosses critical redundancy thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
South Africa Food Colorants Market
Food Additives and Ingredients
India Food Emulsifiers Market
Food Additives and Ingredients
Asia-Pacific Food Emulsifier Market
Food Additives and Ingredients
United Kingdom Anti Caking Market
Food Additives and Ingredients
Erythorbic Acid Market
Food Additives and Ingredients
Feed Anti-Caking Agents Market
Food Additives and Ingredients
Mexico Food Additives Market
Food Additives and Ingredients
Protein Films Market
Food Additives and Ingredients
Egypt Food Preservatives Market
Food Additives and Ingredients
Australia Food Preservatives Market
Food Additives and Ingredients
North America Food Emulsifiers Market
Food Additives and Ingredients
Beverage Encapsulants Market
Food Additives and Ingredients
Sri Lanka Starch and Starch Derivative Market
Food Additives and Ingredients
Food Bleaching Agents Market
Food Additives and Ingredients
Africa Food Emulsifiers Market
Food Additives and Ingredients
Wheat & Rice Flour Substitute-Resistant Starch Market