
 Natural Solubilizers Market | 2026-2036
Natural Solubilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Solubilizers Market Foresight
Technical service contracts for formulation support is expanding what suppliers actually deliver beyond raw material tonnage. BASF SE leverages its global technical centers to embed application scientists directly at customer R&D labs. Croda International Plc sustains premium positioning through lipid-specialized manufacturing assets in the United Kingdom and Singapore. SEPPIC differentiates via marine biotechnology expertise that anchors its portfolio of bio-derived emulsifiers.
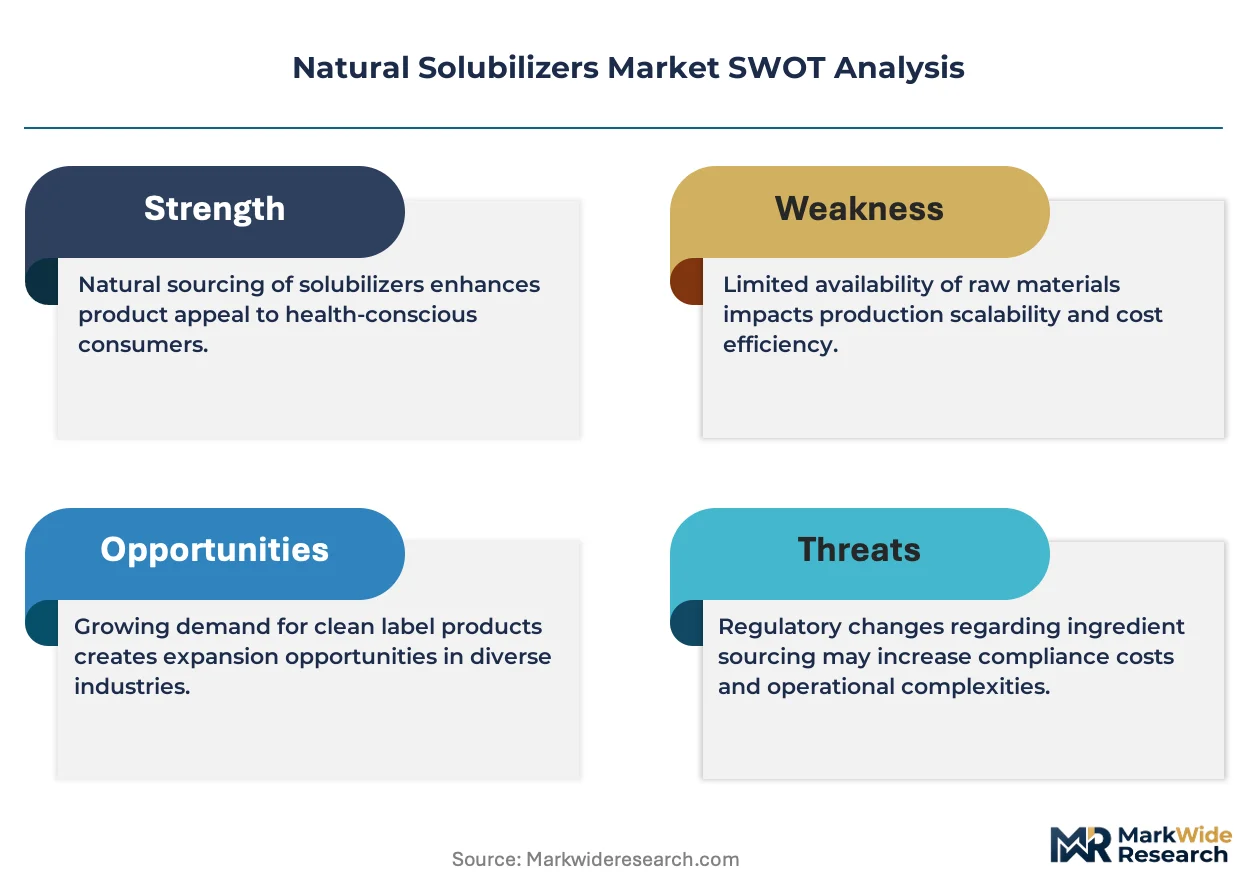
Natural solubilizers are amphiphilic compounds derived from plant, microbial, or marine biomass that reduce interfacial tension between immiscible phases, typically achieving hydrophilic-lipophilic balance values between 8 and 16 for stable oil-in-water dispersion. Their primary commercial purpose is to replace synthetic ethoxylated surfactants in applications where consumer perception, dermal tolerance, or environmental biodegradability constrains formulation choices. Lecithin and phospholipid fractions dominate current volume owing to decades of supply infrastructure and GRAS regulatory status across multiple jurisdictions. Quillaja saponin extracts represent the fastest-expanding product class as cosmetic and beverage applications exploit their foaming and emulsifying dual functionality. Essential oil-based solubilizers command concentrated margin pools in premium personal care where fragrance houses bundle solubilization with olfactory performance.
EMA guidelines on excipient quality and the EU Green Deal's chemical sustainability criteria are elevating documentation burdens for petrochemical-derived alternatives, indirectly advantaging botanical and fermentation-derived solubilizers with established life-cycle assessments. FDA GRAS notifications and FSSAI clean-label initiatives in India are creating parallel compliance pathways that multinational suppliers must navigate simultaneously. Clariant AG controls regulatory dossier compilation across these jurisdictions, while Sensient Technologies Corporation positions its color-and-flavor integrated offerings to capture formulation simplification demand. Stakeholders must monitor how REACH authorization list expansions and emerging state-level restrictions in California on per- and polyfluoroalkyl substances reshape acceptable performance benchmarks for surfactant replacements.
Market Dynamics
REACH authorization expansions and the EU Green Deal's chemical sustainability criteria are systematically elevating documentation burdens for petrochemical-derived surfactants, forcing formulators toward botanical and fermentation-derived alternatives with established life-cycle assessments.
Growth Catalysts
- REACH Compliance Pressure:ECHA's tightening restrictions on synthetic ethoxylated surfactants create direct substitution demand for quillaja saponin and phospholipid alternatives in cosmetic emulsions.
- Clean-Label Beverage Formulation:FSSAI initiatives in India and FDA GRAS pathways drive procurement of plant-derived foaming agents for functional drinks and plant-based dairy analogues.
- Marine Biotechnology Advances:SEPPIC's bio-derived emulsifier platforms demonstrate how lipid-specialized fermentation processes unlock new performance benchmarks for oil-in-water dispersion stability.
Market Restraints
- Quillaja Supply Concentration:Chilean and Peruvian raw bark harvesting dominates feedstock availability, exposing processors to climate-driven harvest volatility and export licensing friction.
- Phospholipid Input Cost Volatility:Soybean and sunflower oil price swings transmit directly to lecithin fraction costs, compressing margin predictability for standard-grade solubilizer suppliers.
- Performance Gap in High-Stress Applications:Natural alternatives fail to match synthetic ethoxylates in extreme pH or temperature conditions, limiting penetration into industrial cleaning and agrochemical formulations.
Strategic Opportunities
- Underpenetrated Indian Personal Care:FSSAI clean-label momentum and domestic ayurvedic brand expansion create white space for saponin-based solubilizers in mass-market hair and skin products.
- Carbon Accounting Integration:EU Green Deal lifecycle assessment mandates position suppliers with verified Scope 3 data to capture premium positioning against petrochemical incumbents lacking equivalent documentation.
- Technical Service Contracting:Formulation support partnerships let suppliers embed application scientists at customer R&D facilities, converting raw material sales into recurring service revenue streams.
Industry Challenges
- Multijurisdictional Dossier Compilation:Simultaneous EMA excipient quality, FDA GRAS notification, and FSSAI compliance pathways strain regulatory affairs capacity at mid-scale suppliers.
- Biomass Preprocessing Capital Intensity:Supercritical CO2 extraction and membrane filtration systems for phospholipid purification require seven-figure equipment commitments that constrain new entrant scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Solubilizers Market |
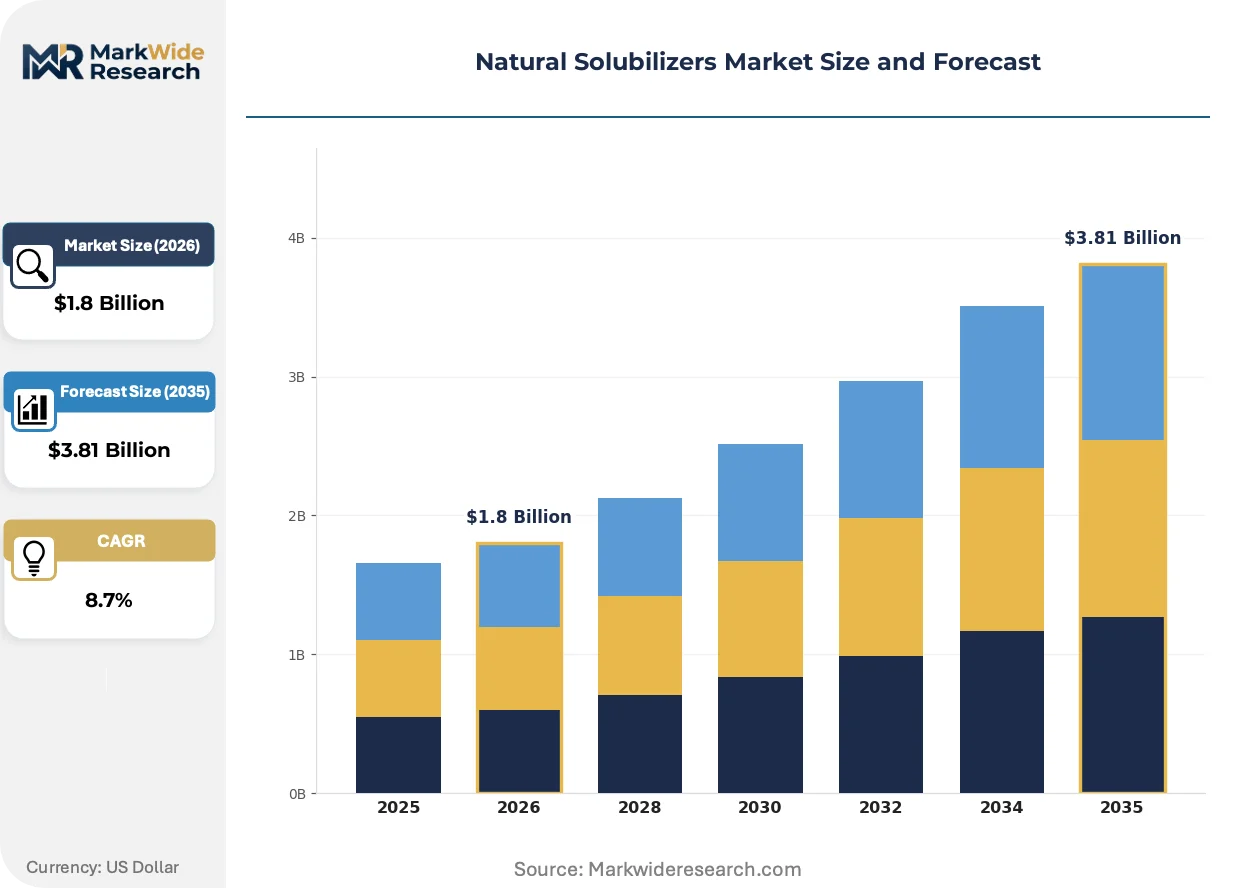
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lecithin, Saponins, Quillaja Extract, Essential Oils Application: Cosmetics, Pharmaceuticals, Food & Beverages, Nutraceuticals Delivery Mode: Liquid, Powder, Granule, Emulsion End User: Cosmetic Manufacturers, Pharmaceutical Companies, Food Processors, Dietary Supplement Firms |
| Companies Covered | BASF SE, Cargill Inc, Archer Daniels Midland Company, Croda International Plc, Evonik Industries AG, SEPPIC, Dow Inc, Clariant AG, Sensient Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Solubilizers Market Shifts & Advancements
Formulation science is converging with biotechnology and carbon accounting to redefine how solubilizer performance gets measured, priced, and procured across cosmetic, food, and pharmaceutical applications.
Enzymatic modification of phospholipids is integrating targeted headgroup engineering that tailors hydrophilic-lipophilic balance values for specific oil-phase compositions. Premium fragrance houses and clean-label cosmetic formulators in Germany and France are adopting these precision-tailored lecithin fractions at accelerated procurement cycles. The technology is integrating performance customization previously achievable only through synthetic ethoxylate chemistry, compressing the premium positioning window for conventional plant-derived alternatives.
EMA's 2023 excipient quality guidelines and the EU Green Deal's chemical sustainability criteria are mandating comprehensive lifecycle documentation for all surfactant inputs entering pharmaceutical and cosmetic supply chains. Suppliers must now maintain verified carbon footprints, biodegradability data, and supply chain transparency records to maintain formulation approval status. Western European cosmetic manufacturing clusters in the Rhine-Ruhr and Île-de-France regions are most affected, with procurement teams rejecting petrochemical alternatives lacking equivalent environmental dossiers.
Cosmetic formulators are consolidating supplier relationships around integrated color-flavor-solubilization offerings that simplify procurement workflows and reduce qualification overhead. Sensient Technologies and similar integrated suppliers are capturing this demand by bundling natural solubilizers with complementary excipients under single technical service contracts. This pattern is most visible in premium personal care segments across France, Germany, and the United Kingdom, where brand owners prioritize supply base reduction over unit cost minimization.
Natural Solubilizers Market Segmentation
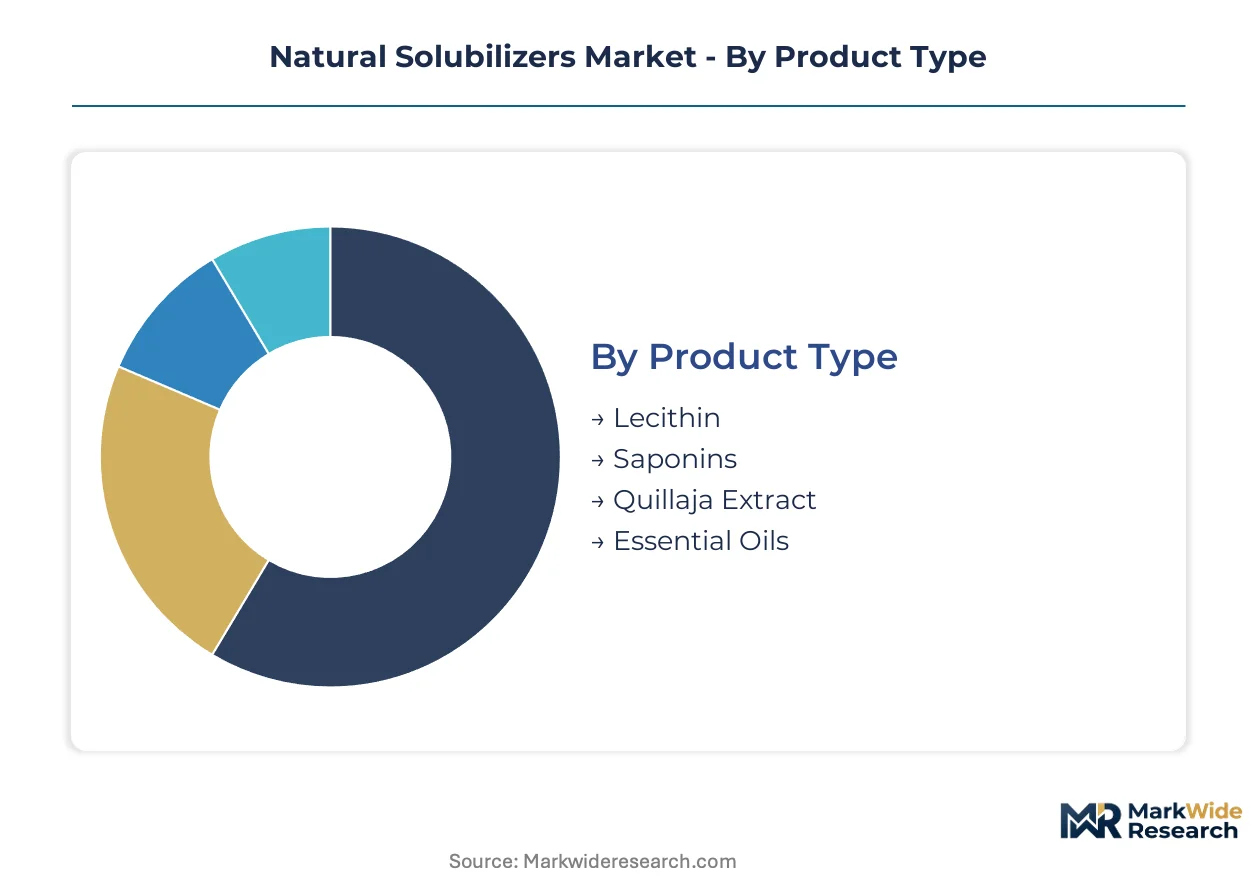
Natural solubilizers fragment across four distinct classification axes, each governing how suppliers configure production assets and how formulators match performance specifications to regulatory constraints. Product chemistry determines processing infrastructure. Application verticals dictate certification requirements and customer technical support intensity.
Product Type:
Standardization dominates at the commodity end, while enzymatic modification and extraction precision enable premium customization for targeted hydrophilic-lipophilic balance values.
- Lecithin:Phospholipid fractions from soybean and sunflower oils constitute the volume backbone, with decades of GRAS regulatory infrastructure supporting food and pharmaceutical applications. Demand concentrates in German and French cosmetic manufacturing clusters where enzymatically modified grades displace synthetic ethoxylates under REACH pressure. Soybean oil price volatility transmits directly to margin predictability.
- Saponins:Plant-derived glycosides with foaming and emulsifying dual functionality anchor clean-label beverage formulations. Procurement from Chilean and Peruvian quillaja bark dominates feedstock availability, exposing processors to climate-driven harvest volatility and export licensing friction.
- Quillaja Extract:Purified saponin concentrates command premium positioning in personal care where fragrance houses bundle solubilization with olfactory performance.
- Essential Oils:Terpene-based solubilizers serve niche premium segments requiring integrated fragrance delivery.
Most installed capacity flows through lecithin. Expansion is steepest in saponins.
Application:
Regulatory documentation intensity varies sharply across verticals, with pharmaceutical and food applications demanding verified lifecycle assessments that cosmetic formulators are only now adopting.
- Cosmetics:Clean-label emulsion demand in Western Europe drives procurement of quillaja-derived and phospholipid solubilizers. EMA excipient quality guidelines and EU Green Deal chemical sustainability criteria elevate documentation burdens, advantaging botanical alternatives with established carbon footprints.
- Pharmaceuticals:Excipient quality mandates require comprehensive biodegradability data and supply chain transparency. Lecithin fractions with decades of regulatory dossiers maintain formulation approval status.
- Food & Beverages:FSSAI clean-label initiatives in India and FDA GRAS pathways drive plant-derived foaming agent procurement for functional drinks and plant-based dairy analogues.
- Nutraceuticals:Dietary supplement manufacturers prioritize GRAS-status ingredients with minimal qualification overhead.
Cosmetics commands the densest supplier concentration. Nutraceuticals offers the most open competitive terrain.
Delivery Mode:
Physical form selection hinges on formulation viscosity requirements, storage stability needs, and downstream processing equipment compatibility.
- Liquid:Standard aqueous and oil-based concentrates dominate high-volume cosmetic and food applications where pumpability and easy incorporation matter.
- Powder:Spray-dried and agglomerated grades serve dry blend beverage and supplement manufacturers requiring extended shelf stability.
- Granule:Low-dust, free-flowing formats target pharmaceutical tableting and capsule filling operations.
- Emulsion:Pre-dispersed systems reduce qualification complexity for formulators lacking high-shear mixing infrastructure.
Liquid absorbs the majority of current volume. Powder formats are climbing fastest as dry-mix beverage applications expand.
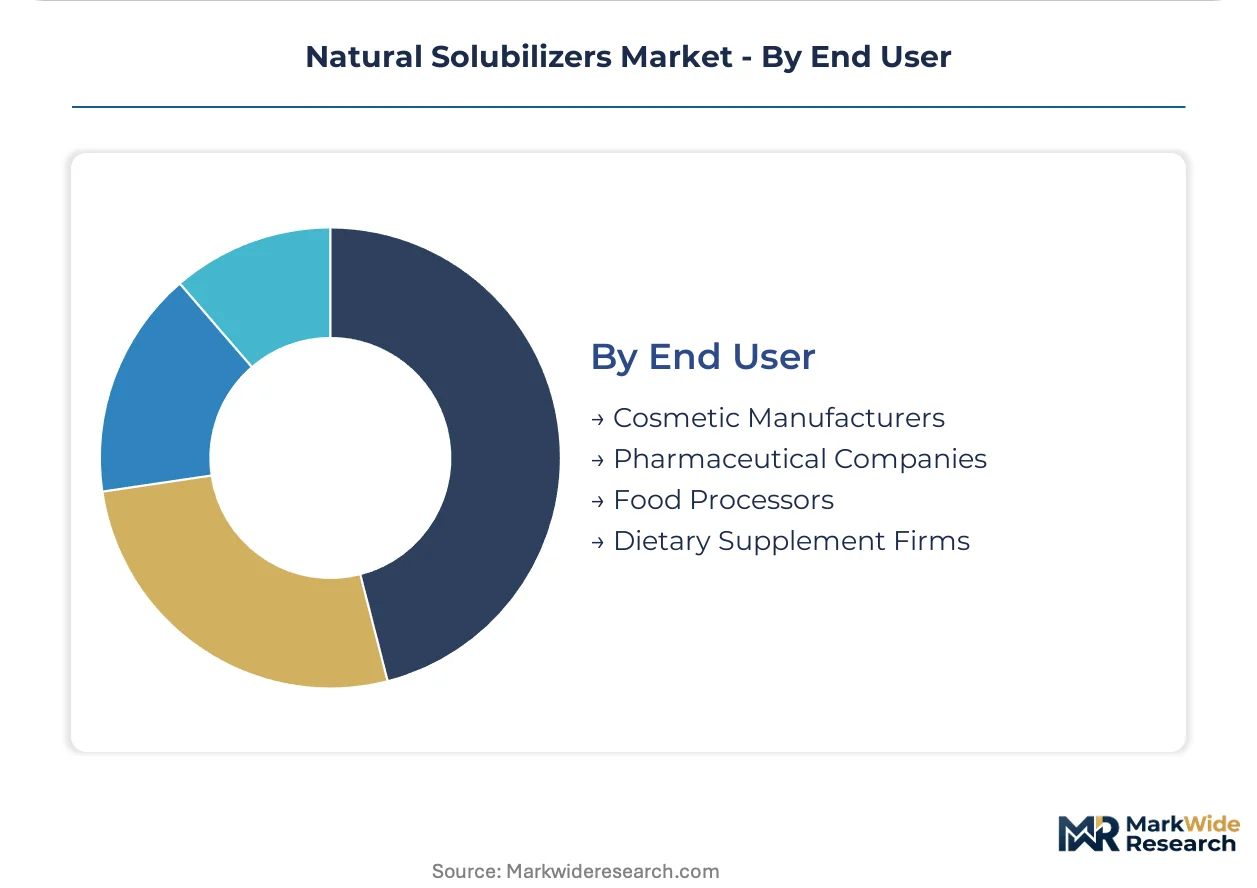
End User:
Customer scale and technical sophistication determine whether suppliers sell raw material tonnage or embed application scientists in recurring service relationships.
- Cosmetic Manufacturers:Rhine-Ruhr and Île-de-France clusters consolidate procurement around integrated color-flavor-solubilization offerings that simplify workflows and reduce qualification overhead.
- Pharmaceutical Companies:Multinational dossier compilation across EMA, FDA, and FSSAI pathways favors suppliers with dedicated regulatory affairs capacity.
- Food Processors:Mass-market beverage and dairy analogue producers prioritize unit cost minimization over technical service intensity.
- Dietary Supplement Firms:Mid-scale operators seek GRAS-status ingredients with minimal supply base complexity.
Cosmetic manufacturers deploy the most technical service contracts. Dietary supplement firms represent the most price-sensitive demand pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands denser procurement networks than France, yet both Rhine-Ruhr and Île-de-France clusters face identical REACH compliance deadlines that accelerate botanical solubilizer substitution.
Germany
Cosmetic manufacturers in the Rhine-Ruhr corridor drive enzymatically modified lecithin procurement as ECHA tightens ethoxylated surfactant restrictions. The EU Green Deal's chemical sustainability criteria mandate verified lifecycle documentation for all excipient inputs. BASF SE embeds application scientists directly at customer R&D facilities in Düsseldorf and Cologne, converting raw material sales into technical service contracts.
France
Fragrance houses in Grasse and Paris bundle quillaja-derived solubilization with olfactory performance for premium personal care lines. ANSM enforces EMA excipient quality guidelines that elevate biodegradability data requirements. SEPPIC leverages marine biotechnology expertise from its Île-de-France base to supply bio-derived emulsifiers to L'Oréal and LVMH formulation labs.
United States
FDA GRAS notifications drive procurement of plant-derived foaming agents for functional beverage applications. EPA scrutiny of per- and polyfluoroalkyl substances in surfactants creates substitution openings for saponin alternatives. Sensient Technologies Corporation positions integrated color-flavor-solubilization offerings from its Midwestern technical centers to capture formulation simplification demand.
India
FSSAI clean-label initiatives accelerate saponin-based solubilizer penetration into mass-market ayurvedic hair and skin products. The PLI scheme for specialty chemicals attracts fermentation-derived solubilizer investments. Maharashtra-based contract manufacturers supply phospholipid fractions to domestic nutraceutical brands seeking minimal qualification overhead.
United Kingdom
Croda International Plc sustains premium positioning through lipid-specialized manufacturing assets in East Yorkshire. The Medicines and Healthcare products Regulatory Agency aligns with EMA excipient quality standards post-Brexit. Cosmetic formulators in Greater Manchester consolidate procurement around suppliers with verified Scope 3 carbon data.
Natural Solubilizers Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational chemical conglomerates controlling regulatory dossier compilation while mid-scale fermentation houses capture clean-label niches. The vendor base organizes around three archetypes: integrated agribusiness traders with oilseed crushing infrastructure, lipid-specialized chemical manufacturers with enzymatic modification capabilities, and marine biotechnology houses with fermentation-derived platforms. Dominant competitive moves include backward integration into quillaja bark sourcing and technical service contracting that embeds supplier scientists at customer facilities.
Within the integrated conglomerate tier, BASF SE and Evonik Industries AG occupy positions defined by global technical center networks and multijurisdictional regulatory capacity. Croda International Plc exemplifies the lipid-specialized archetype through United Kingdom and Singapore manufacturing assets. SEPPIC anchors the marine biotechnology vector with bio-derived emulsifier platforms developed from its French research base.
| Leading Market Players |
|---|
| BASF SE |
| Cargill Inc |
| Archer Daniels Midland Company |
| Croda International Plc |
| Evonik Industries AG |
| SEPPIC |
| Dow Inc |
| Clariant AG |
| Sensient Technologies Corporation |
| Others |
Supply & Pricing Matrix
EU Green Deal lifecycle assessment mandates gate both qualified supply and premium-tier pricing access for natural solubilizers, as formulators lacking verified Scope 3 documentation face exclusion from Western European cosmetic manufacturing clusters while suppliers with carbon-accounted lecithin fractions capture margin premiums against undocumented petrochemical alternatives.
Pricing Analysis
Capacity additions in India are reshaping price floors for standard-grade saponin solubilizers as fermentation-derived alternatives enter the market. Pricing stratifies across enzymatically modified phospholipid premiums, standard lecithin fractions, and commodity saponin grades. Cost compression in standard lecithin is intensifying because soybean oil price volatility transmits directly to margin predictability. Mass-market beverage processors exhibit the highest price sensitivity, while premium fragrance houses in France demonstrate the lowest.
Supply Chain Analysis
Direct-to-formulator channels handle hyperscale cosmetic manufacturer demand in Germany and France, while distributor networks serve mid-scale dietary supplement firms. Raw bark harvesting in Chile and Peru anchors quillaja saponin availability, with phospholipid purification drawing from Argentine and Ukrainian sunflower oil crushing. Single-source vulnerability in Andean feedstock exposes processors to climate-driven harvest volatility and export licensing friction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Natural solubilizers function as a stable compounder, with regulatory substitution mandates across REACH and FDA GRAS pathways delivering predictable demand expansion regardless of macroeconomic cyclicality.
For Market Incumbents: Acquire enzymatic modification capabilities to defend against synthetic ethoxylate displacement in high-performance cosmetic emulsions. Backward integration into Chilean quillaja bark sourcing mitigates climate-driven supply disruption. Certification investment in EMA excipient quality dossiers maintains formulation approval status across pharmaceutical applications. For New Entrants and Emerging Players: Contract manufacturers serving Maharashtra-based ayurvedic brands represent the most accessible channel entry point. White space concentrates in FSSAI-compliant saponin solubilizers for mass-market Indian personal care. Technical service partnerships embedding application scientists at customer R&D facilities differentiate against commodity traders. For Investors and Strategic Acquirers: Roll-up economics work for lipid-specialized fermentation houses because EMA and FDA documentation burdens favor scaled regulatory affairs capacity over fragmented mid-tier suppliers. The five-to-ten-year viability window favors platforms with verified carbon footprints and multijurisdictional dossier libraries. Monitor REACH authorization list expansions as the critical inflection signal for accelerated petrochemical displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quillaja Sourcing | Captive Andean bark supply insulates SEPPIC and similar processors from climate-driven harvest volatility. |
| Enzymatic Modification Capacity Expansion | Precision-tailored phospholipid HLB values displace synthetic ethoxylates in German cosmetic manufacturing clusters. |
| Technical Service Contracting | BASF embeds application scientists at Düsseldorf and Cologne R&D labs, converting tonnage sales into recurring revenue. |
| Carbon Accounting Certification | Verified Scope 3 data positions Croda to capture EU Green Deal premium positioning against petrochemical incumbents. |
| FSSAI Compliance Pathway Investment | Clean-label documentation unlocks mass-market penetration for saponin solubilizers in Indian ayurvedic personal care. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cosmetic formulators, phospholipid plant managers, FSSAI regulatory consultants, and fragrance house procurement leads with secondary validation from ECHA restriction proposals, FDA GRAS notification databases, EU Green Deal implementation guidelines, and customs trade flows for quillaja bark and lecithin fractions. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Segment-weighting applied product chemistry, application vertical, and regional regulatory cluster dimensions across the projection horizon. CAGRs derived from elasticity-adjusted substitution curves modeling REACH-driven synthetic surfactant displacement. Industry-specific inputs included enzymatic modification yield rates and FSSAI clean-label adoption velocity in Indian mass-market personal care.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Andean climate patterns, soybean oil price volatility, and REACH authorization list expansion timing. Forecasts reflect documented assumptions on substitution elasticity and regulatory enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Natural Ferulic Acid Market
Food Additives and Ingredients
Flavor Encapsulation Market
Food Additives and Ingredients
Feed Anti-Caking Agents Market
Food Additives and Ingredients
China Emulsifiers Market
Food Additives and Ingredients
Lactose Monohydrate Market
Food Additives and Ingredients
Alpha-Linolenic Acid Market
Food Additives and Ingredients
Food Grade Carrageenan Market
Food Additives and Ingredients
Global Baking Powder Market
Food Additives and Ingredients
Leavening Acids Market
Food Additives and Ingredients
Firming Agents Market
Food Additives and Ingredients
Fermented Chymosin Market
Food Additives and Ingredients
Middle East and Africa Food Anti Caking Agents Market
Food Additives and Ingredients
Monosodium Glutamate Market
Food Additives and Ingredients
Brazil Food Preservatives Market
Food Additives and Ingredients
Food Antimicrobial Additives Market
Food Additives and Ingredients
North America Feed Additives Market