
 Global Natural Food Colorants Market | 2026-2036
Global Natural Food Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Natural Food Colorants Market Foresight
Asset-light toll manufacturing and third-party extraction partnerships are tilting competitive economics toward mid-sized botanical processors. GNT Group B.V. leverages its vertical farm network in the Netherlands to secure year-round beetroot and spirulina supply. Sensient Technologies Corporation anchors North American beverage accounts through its specialized emulsion technology. Döhler Group SE competes by bundling natural color systems with integrated flavor and texture solutions.
Natural food colorants comprise pigments extracted, fermented, or bioconverted from plant, algal, microbial, or mineral sources, typically standardized to specified color intensity measured in International Color Units and stabilized against pH and light degradation for commercial food systems. Their primary purpose is to restore or enhance visual appeal in processed foods where thermal treatment, storage, or formulation strips native pigmentation. Carotenoids and anthocyanins together command the deepest margin pools due to their heat stability breadth and applicability across acidic and neutral pH matrices. Curcumin and betalains represent faster-expanding niches as beverage and dairy alternative formulators seek turmeric-derived yellows and beetroot reds for clean-label positioning. Liquid formulations dominate volume throughput, though powder and dry extract forms are gaining traction in shelf-stable bakery and snack applications where moisture control dictates ingredient selection.
EFSA maintains the EU's centralized food additive safety evaluations under Regulation (EC) No 1333/2008, while the FDA enforces batch certification for certain coal-tar derived colors and exempts many natural pigments from certification but subjects them to food additive petitions or GRAS self-determinations. REACH and the EU Green Deal's Farm-to-Fork pesticide reduction targets are simultaneously constraining agricultural input residues and expanding the addressable market for fermentation-derived colorants that bypass field cultivation. Stakeholders must monitor how the EU's proposed revision of food contact material rules and emerging state-level natural claims litigation in the US reshape liability exposure and labeling architecture.
Market Dynamics
Clean-label reformulation mandates from European retail chains and US beverage conglomerates are compressing supplier qualification timelines while simultaneously elevating technical performance thresholds for natural color stability across pH and thermal ranges.
Growth Catalysts
- EU Green Deal Farm-to-Fork pesticide reduction targets:These mandates are expanding commercial viability for fermentation-derived colorants that bypass agricultural residue risks entirely, opening new supplier categories.
- Beverage clean-label positioning:Premium and functional drink manufacturers across Germany, the Netherlands, and California are replacing synthetic dyes with turmeric-derived yellows and spirulina-based blues at accelerated reformulation cycles.
- Algal bioconversion platforms:Closed-system photobioreactor operations in coastal Portugal and southern Spain are yielding phycocyanin with batch-to-batch consistency that field-cultivated botanicals cannot match.
Market Restraints
- Beetroot supply geographic concentration:Northern European climatic dependence for betalain sources creates harvest volatility that processors cannot hedge through contract farming alone.
- FDA batch certification requirements for coal-tar derivatives:These parallel compliance obligations create administrative drag for manufacturers maintaining dual natural-synthetic portfolios, elevating overhead disproportionately.
- Carotenoid oxidation sensitivity:Lipid-soluble pigments require antioxidant stabilization systems that add formulation complexity and cost in high-temperature processing environments.
Strategic Opportunities
- Fermentation-derived anthocyanins:Microbial cell factories bypass agricultural land use and pesticide residue monitoring entirely, aligning with REACH chemical registration pathways for novel food additives.
- Shelf-stable bakery and snack segments:Powder-format natural colorants are displacing liquid formulations where moisture control dictates ingredient selection, creating new dry-extraction equipment demand.
- Direct-to-manufacturer digital procurement platforms:Specialty ingredient distributors in the US and Germany are launching specification-matching algorithms that compress technical qualification from months to weeks.
Industry Challenges
- Cross-functional formulation chemists:Scarce talent pools combine natural pigment stabilization expertise with beverage emulsion science and regulatory dossier preparation capabilities.
- EFSA novel food additive petition timelines:Centralized safety evaluations under Regulation (EC) No 1333/2008 extend market entry delays beyond eighteen months for unapproved colorant sources.
- pH-dependent hue shift management:Anthocyanin formulations require application-specific buffering systems that complicate multi-product manufacturing line changeovers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Natural Food Colorants Market |
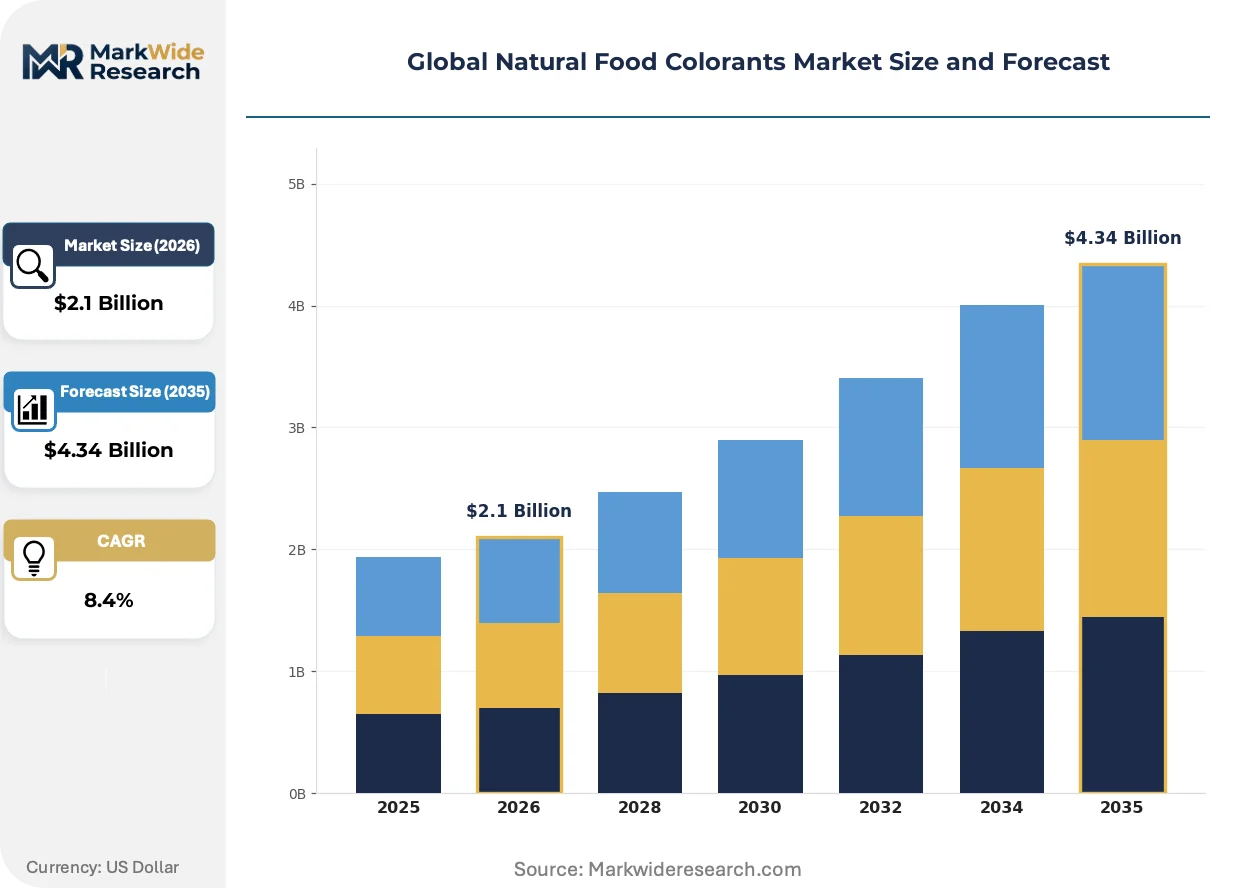
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carotenoids, Anthocyanins, Chlorophyll, Curcumin, Betalains, Flavonoids Application: Beverages, Bakery Products, Dairy Alternatives, Confectionery, Snack Foods, Sauces & Condiments End User: Food & Beverage Manufacturers, Nutraceuticals Producers, Flavor Houses, Specialty Ingredient Suppliers, Contract Manufacturers Formulation: Liquid, Powder, Paste, Granule, Emulsion, Dry Extract |
| Companies Covered | Sensient Technologies Corporation, GNT Group B.V., Givaudan S.A., Döhler Group SE, DIC Corporation, Oterra, DSM-Firmenich, Kalsec Inc., Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Natural Food Colorants Market Shifts & Advancements
Bioprocess engineering and extraction technology advances are collapsing cost differentials between natural and synthetic color systems while regulatory pressure on petroleum-derived additives intensifies commercial substitution economics.
Precision fermentation of anthocyanins using engineered yeast strains is collapsing the cost structure that previously confined natural reds to premium price tiers. North American beverage manufacturers are adopting these bioconverted pigments at commercial scale for acidic fruit-flavored applications. The technology is collapsing traditional supply chain dependencies on seasonal beetroot harvests and grape skin byproduct availability.
EFSA's systematic re-evaluation of existing food additive approvals under the 2020-2025 roadmap is tightening toxicological data requirements for legacy colorants. Manufacturers holding approvals for titanium dioxide and certain azo dyes face renewed safety substantiation costs or reformulation pressure. German and French retail private-label programs are responding by accelerating natural colorant transition timelines ahead of regulatory determination deadlines.
Specification-driven procurement through digital platforms is fragmenting traditional distributor relationships as large beverage and dairy manufacturers build direct technical partnerships with extraction specialists. These platforms enable real-time color matching against International Color Unit standards without intermediary sample logistics. The shift is most visible in California and Bavaria, where conglomerate technical centers maintain dedicated natural colorant application laboratories.
Global Natural Food Colorants Market Segmentation
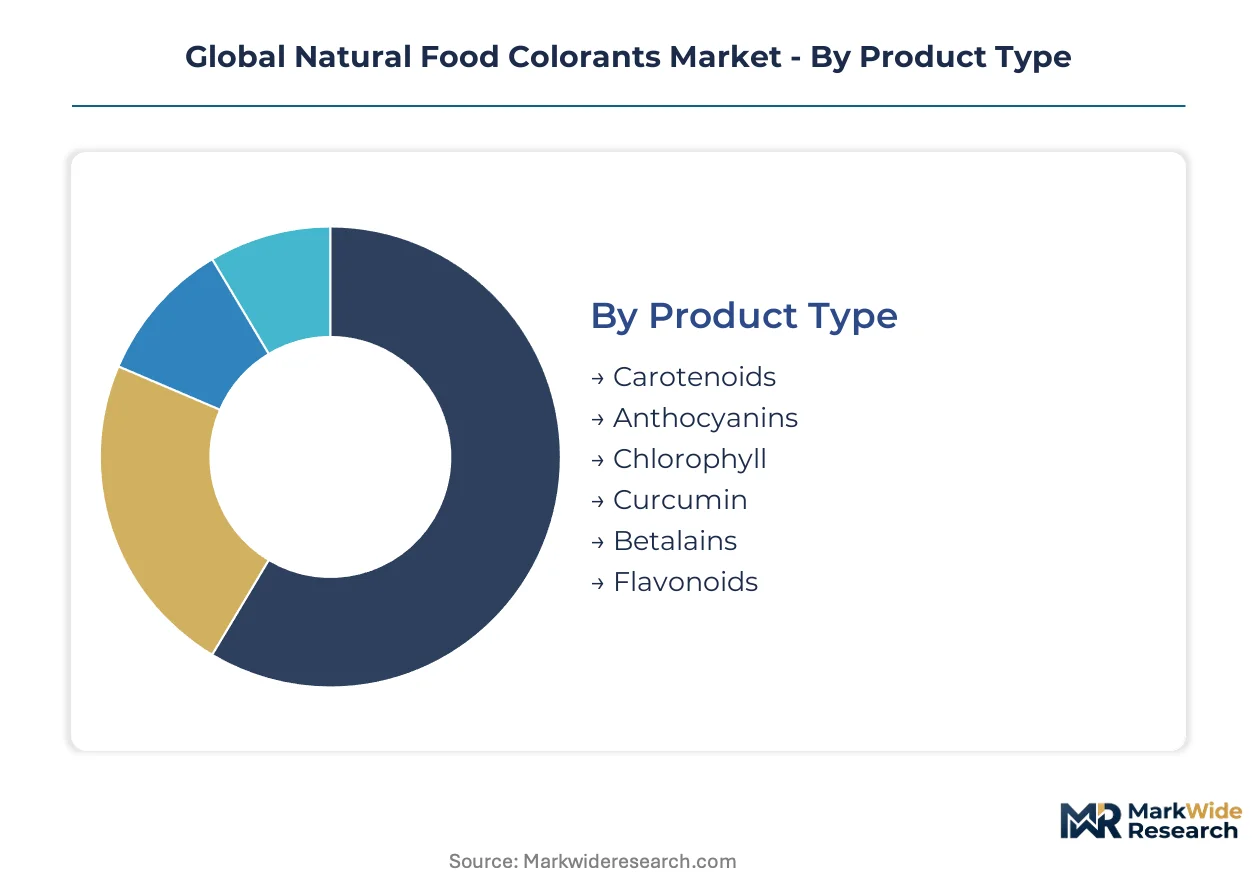
Segmentation in natural food colorants reveals how technical performance requirements and supply chain constraints fragment procurement decisions across pigment chemistries and delivery formats. Formulators select colorant systems based on thermal stability thresholds, pH compatibility matrices, and clean-label positioning mandates that vary sharply by end-use application.
Product Type:
After-sales technical support intensity runs highest for pigment categories requiring application-specific stabilization protocols and regulatory dossier maintenance across multiple jurisdictions.
- Carotenoids:Lipid-soluble pigments including beta-carotene, lycopene, and lutein deliver orange-to-red hues with proven heat stability in high-temperature extrusion processes. Demand concentrates in snack food manufacturing across Germany and the Netherlands, where processors require antioxidant stabilization systems that suppliers must validate through extended shelf-life studies.
- Anthocyanins:Water-soluble flavonoid pigments extracted from grape skins, elderberry, and purple sweet potato provide red-to-purple coloration across acidic pH matrices. Beverage manufacturers in California and Bavaria are expanding procurement of these pigments for clean-label fruit-flavored applications, though pH-dependent hue shifts necessitate technical service partnerships for buffering system optimization.
- Chlorophyll:Magnesium-centered porphyrin compounds deliver green coloration with moderate heat tolerance; copper chlorophyllin variants offer enhanced stability for canned vegetable applications.
- Curcumin:Turmeric-derived diarylheptanoid provides bright yellow hues with limited light stability; dairy alternative formulators value its recognized ingredient identity for label transparency.
- Betalains:Nitrogen-containing pigments from beetroot deliver magenta-red tones with excellent water solubility; harvest volatility in Northern Europe drives qualification of alternative supply regions.
- Flavonoids:Quercetin and catechin derivatives provide subtle yellow-to-brown coloration with antioxidant co-functionality; niche adoption in functional beverage positioning.
Carotenoids holds the largest share; momentum sits with anthocyanins as beverage clean-label reformulation accelerates.
Application:
Cost tier differentiation separates commodity colorant procurement in high-volume processed foods from premium pigment systems in functional and organic-positioned products.
- Beverages:Acidic and neutral pH matrices across carbonated, still, and functional drink categories require colorants with proven emulsion stability and light-fastness validation. German and Dutch beverage conglomerates are driving specification tightening for natural colorants that maintain hue consistency across twelve-month shelf-life targets.
- Bakery Products:Thermal processing above 180°C in ovens and extruders demands heat-stable carotenoid and caramel colorant systems; moisture-sensitive applications favor powder and dry extract formulations.
- Dairy Alternatives:Oat, almond, and soy-based milk and yogurt applications require oil-in-water emulsion colorants with neutral pH compatibility; turmeric-derived yellows dominate clean-label positioning.
- Confectionery:Hard candy and panned coating processes require colorants with thermal stability through sugar inversion temperatures; spirulina-based blues gain traction in premium positioning.
- Snack Foods:Extruded and fried applications leverage paprika oleoresin and annatto for orange-red coloration; oxidation-sensitive formulations drive antioxidant system co-development with suppliers.
- Sauces & Condiments:Acidic tomato and mustard matrices favor anthocyanin and curcumin systems with proven pH stability; retail private-label programs in France are accelerating natural colorant transitions.
Beverages command the deepest technical service relationships; snack foods represent the steepest expansion trajectory as extruded product naturalization accelerates.
End User:
Volume concentration varies sharply between multinational food conglomerates with captive application laboratories and mid-sized processors reliant on distributor technical support.
- Food & Beverage Manufacturers:Multinational conglomerates in California, Bavaria, and the Netherlands maintain direct technical partnerships with extraction specialists and run proprietary color matching against International Color Unit standards.
- Nutraceuticals Producers:Supplement and functional food formulators require colorants with additional bioactive positioning and organic certification compatibility; smaller batch sizes elevate per-unit technical service intensity.
- Flavor Houses:Integrated flavor and color system bundling demands cross-functional formulation expertise; Döhler Group SE and comparable suppliers compete through combined sensory solutions.
- Specialty Ingredient Suppliers:Distributor intermediaries face margin compression as digital procurement platforms enable direct manufacturer-to-processor relationships; technical qualification speed becomes the remaining differentiation lever.
- Contract Manufacturers:Toll processors require rapid line changeover protocols for multi-product natural colorant applications; pH buffering system standardization reduces technical service burdens.
Food and beverage manufacturers hold the largest share; specialty ingredient suppliers are gaining share fastest as digital platform adoption fragments traditional distribution.
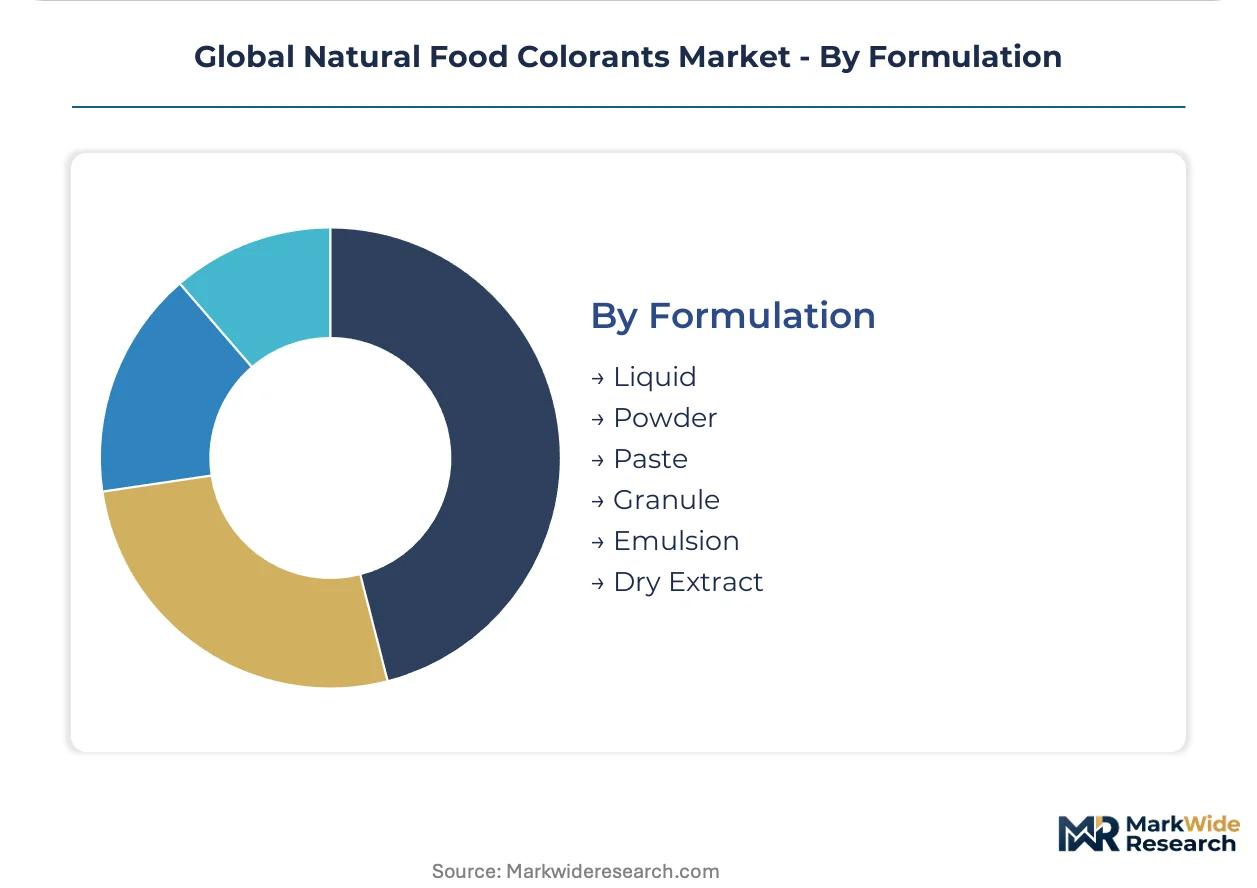
Formulation:
Supply concentration in liquid extraction capacity versus dry processing infrastructure shapes regional availability and minimum order economics across format types.
- Liquid:Aqueous and oil-based solutions dominate volume throughput for beverage and sauce applications; GNT Group B.V.'s vertical farm network secures year-round supply consistency for liquid spirulina and beetroot concentrates.
- Powder:Spray-dried and freeze-dried formats gain traction in shelf-stable bakery and snack applications where moisture control dictates ingredient selection; capital-intensive drying equipment creates supplier concentration.
- Paste:Semi-solid concentrates offer intermediate moisture content for industrial-scale food processing; standardized color strength reduces batch-to-batch formulation adjustment.
- Granule:Free-flowing dry formats facilitate automated dispensing in high-volume manufacturing environments; limited commercial availability restricts adoption.
- Emulsion:Oil-in-water systems enable lipid-soluble carotenoid dispersion in aqueous matrices; Sensient Technologies Corporation anchors North American supply through specialized emulsion technology.
- Dry Extract:Low-moisture botanical concentrates serve organic and clean-label positioning requirements; extraction yield variability elevates procurement qualification complexity.
Liquid formulations hold the largest share; powder formats are expanding most quickly as bakery and snack shelf-stability requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in natural food colorants tilt toward import-dependent markets with stringent additive regulations, while extraction-specialized economies capture upstream value. Germany and the Netherlands run structural surpluses in beetroot and spirulina processing. The United States, France, and Japan rely on cross-border procurement to meet beverage and dairy reformulation timelines.
Germany
Retail chain clean-label mandates and conglomerate reformulation programs drive procurement intensity. EFSA's centralized evaluations under Regulation (EC) No 1333/2008 compress supplier qualification windows. The Hamburg-Bremen port cluster anchors import logistics for beetroot concentrates and spirulina biomass.
United States
Beverage manufacturers in California and Wisconsin accelerate synthetic-to-natural transitions in premium drink lines. FDA batch certification requirements for coal-tar derivatives create compliance overhead for dual-portfolio producers. The Chicago technical corridor hosts application laboratories serving North American dairy and beverage accounts.
Netherlands
Vertical farming infrastructure and controlled-environment agriculture secure year-round botanical supply independent of climatic volatility. REACH registration pathways and EU Green Deal pesticide targets favor fermentation-derived colorant development. The Eindhoven-Rotterdam logistics belt concentrates extraction toll manufacturing capacity.
France
Private-label retail programs advance natural colorant transitions ahead of EFSA re-evaluation deadlines for legacy additives. ANSM and DGCCRF enforcement on food contact materials elevates technical documentation requirements. The Lyon-Grenoble corridor clusters flavor-house integration specialists bundling color and sensory systems.
Japan
Functional beverage positioning and premium confectionery segments sustain demand for heat-stable carotenoid and spirulina-based systems. METI guidelines on food additive labeling and consumer transparency tighten specification protocols. The Osaka-Kobe industrial zone maintains import dependency for anthocyanin and curcumin raw materials.
Global Natural Food Colorants Market Competitive Landscape
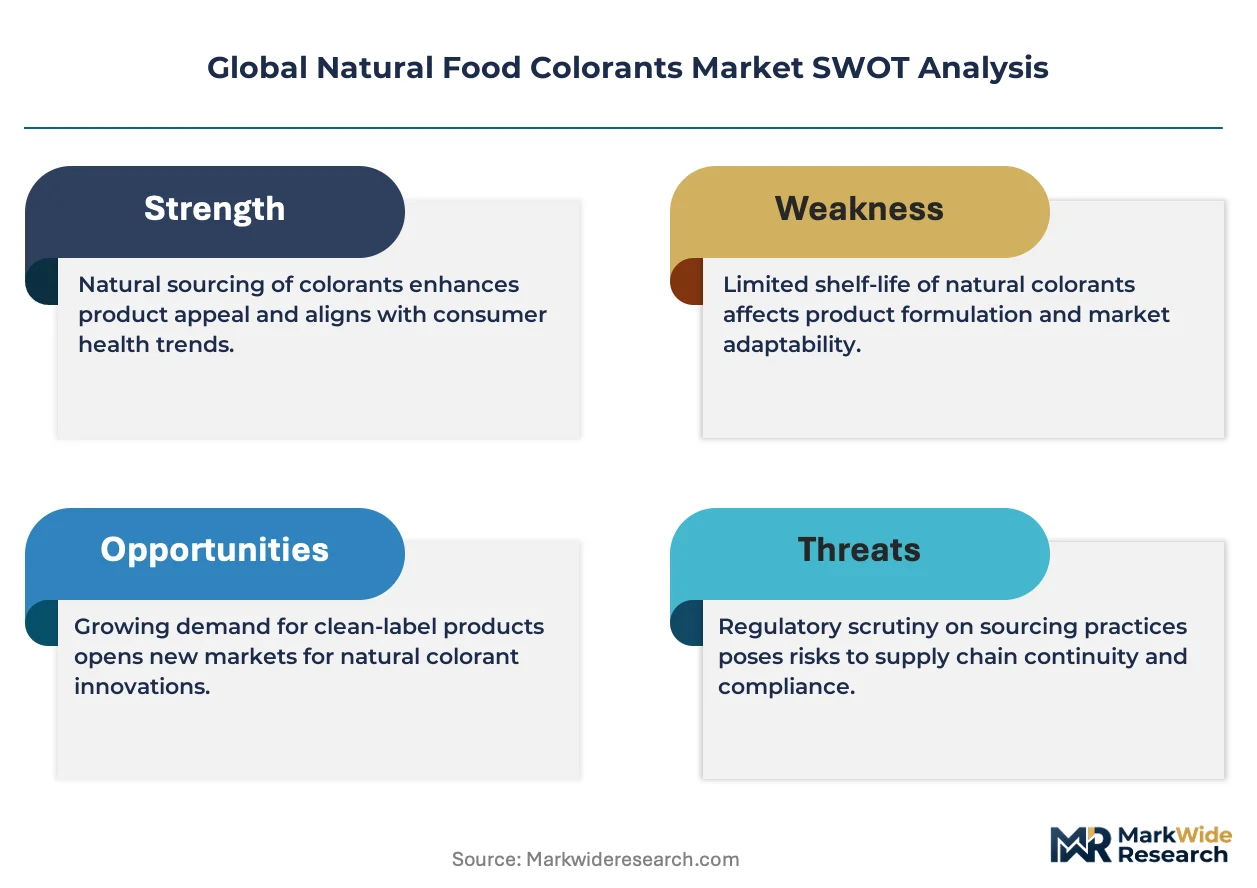
On the supply side, the industry is bifurcating between integrated extraction specialists and toll-dependent processors. Mid-sized botanical processors capture margin through asset-light manufacturing partnerships and third-party fermentation capacity. Three archetypes dominate: vertical farm operators controlling agricultural input, emulsion technology specialists serving beverage matrices, and integrated flavor-color bundlers. Capacity expansion in precision fermentation and direct-to-manufacturer digital procurement represent the dominant competitive vectors.
Among extraction-specialized operators, GNT Group B.V., Sensient Technologies Corporation, and Döhler Group SE occupy distinct positioning archetypes. GNT Group B.V. exemplifies the vertical integration model through controlled-environment agricultural assets. Sensient Technologies Corporation anchors the emulsion-technology tier serving aqueous-matrix applications. Döhler Group SE represents the bundled-solution archetype combining color systems with integrated flavor and texture platforms. These three entities illustrate how geographic concentration in the Netherlands, North America, and Germany respectively maps to divergent capability stacks.
| Leading Market Players |
|---|
| Sensient Technologies Corporation |
| GNT Group B.V. |
| Givaudan S.A. |
| Döhler Group SE |
| DIC Corporation |
| Oterra |
| DSM-Firmenich |
| Kalsec Inc. |
| Archer Daniels Midland Company |
| Others |
Supply & Pricing Matrix
Beetroot supply geographic concentration in Northern Europe determines both premium-to-economy tier spreads and supply chain configuration across the natural food colorants industry. Harvest volatility in this climatic zone compresses margins for standard-grade betalain processors while elevating pricing power for suppliers with controlled-environment agricultural assets or fermentation-derived alternatives.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the natural food colorants market. Price differentiation rests on certification grade—organic and EU Organic-certified pigments command substantial premiums over conventional grades—and volume scale, where multinational beverage conglomerates negotiate long-term offtake agreements. Cost compression in the economy tier is intensifying because spirulina and turmeric extract capacity expansion in India and Vietnam is flooding commodity-grade supply. Small-scale nutraceutical producers exhibit the highest price sensitivity due to limited batch sizes and technical service requirements, while premium-positioned dairy alternative manufacturers absorb higher per-unit costs for label-transparent curcumin systems.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for anthocyanin and curcumin raw material flows. Geographic supply concentration centers on the Netherlands for spirulina biomass, India for turmeric oleoresin, and Germany for beetroot concentrate processing. Raw material dependencies draw from grape skin byproducts, marigold flower petals, and engineered yeast strains for precision fermentation platforms. Single-source vulnerability in Northern European beetroot cultivation creates harvest-driven supply disruptions that processors cannot hedge through contract farming alone. Distribution runs through specialty ingredient distributors in Germany and California, though direct-to-manufacturer digital procurement platforms are fragmenting traditional intermediary relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The natural food colorants market functions as a service-attach opportunity where after-sales technical support for pH buffering system optimization and regulatory dossier maintenance expands faster than commodity pigment sales.
For Market Incumbents: Build captive supply moats through backward integration into controlled-environment agriculture or precision fermentation capacity. GNT Group B.V.'s vertical farm network in the Netherlands exemplifies this defensive positioning against harvest volatility threats. Incumbents should anchor North American beverage accounts through specialized emulsion technology partnerships, mirroring Sensient Technologies Corporation's technical service model. Certification investment in EU Organic and clean-label standards creates switching costs that defend margin position against commodity-grade entrants. For New Entrants and Emerging Players: Build out fermentation-derived anthocyanin capacity to bypass agricultural land use and pesticide residue monitoring entirely. The most penetrable white space sits in shelf-stable bakery and snack segments where powder-format natural colorants displace liquid formulations. A direct-to-manufacturer digital procurement platform with specification-matching algorithms offers the strongest go-to-market angle, compressing technical qualification timelines from months to weeks for mid-sized processors. For Investors and Strategic Acquirers: EFSA's systematic re-evaluation of existing food additive approvals under the 2020-2025 roadmap reshapes the acquisition landscape toward suppliers with novel food dossier capabilities and fermentation platforms. Long-term viability favors precision fermentation specialists and integrated flavor-color bundlers over commodity extraction operators. The acquisition target archetype combines microbial cell factory technology with existing beverage industry technical partnerships. The signal to watch is accelerated private-label natural colorant transitions by German and French retail chains ahead of regulatory determination deadlines.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Microbial cell factories bypass agricultural residue risks and EFSA pesticide monitoring requirements entirely. |
| Vertical Farm Network Expansion | Controlled-environment agriculture secures year-round spirulina and beetroot supply independent of climatic volatility. |
| Direct-to-Manufacturer Digital Platform Launch | Specification-matching algorithms compress technical qualification timelines for mid-sized processors. |
| Integrated Flavor-Color System Bundling | Cross-functional formulation expertise captures beverage accounts seeking combined sensory solutions. |
| EU Organic Certification Investment | Premium-grade positioning creates switching costs and defends margin against commodity-grade competition. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with extraction specialists, beverage formulation chemists, regulatory affairs directors, and specialty ingredient procurement managers; and secondary validation through EFSA food additive safety evaluations, FDA GRAS determinations, EU customs trade data, and REACH chemical registration filings. Bottom-up triangulation across pigment chemistry segments and top-down validation against end-use application demand generated volume and value estimates. Primary fieldwork concentrated in the Netherlands, Germany, California, and India where supplier concentration and procurement intensity are highest.
Forecast inputs considered thermal stability thresholds, pH compatibility matrices, clean-label positioning mandates, and fermentation technology cost curves across the projection horizon. Segmentation dimensions modeled include pigment chemistry, delivery format, application matrix, and end-user procurement archetype. CAGRs were derived from fitted growth curves anchored to observed supplier capacity expansion and beverage manufacturer reformulation cycle data. Industry-specific inputs incorporated EFSA petition timelines, EU Green Deal pesticide reduction targets, and digital procurement platform adoption rates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by precision fermentation specialists or accelerated regulatory determinations by EFSA would shift outcomes beyond modeled ranges. Forecasts reflect assumptions regarding sustained clean-label momentum and stable agricultural input costs. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Lemon Essential Oil Market
Flavorings and Food Additives
Modified Lecithin Market
Flavorings and Food Additives
Beverage Flavoring Agent Market
Flavorings and Food Additives
Blueberry Extract Market
Flavorings and Food Additives
United States Food Flavor and Enhancer Market
Flavorings and Food Additives
Beef Flavors Market
Flavorings and Food Additives
Liquid Flavors Market
Flavorings and Food Additives
Pumpkin Spice Products Market
Flavorings and Food Additives
Egypt Food Flavor and Enhancer Market
Flavorings and Food Additives
Coloring Foodstuffs Market
Flavorings and Food Additives
North America Licorice Extract Market
Flavorings and Food Additives
Flavor Masking Agents Market
Flavorings and Food Additives
Taste Modulators Market
Flavorings and Food Additives
Natural Acerola Cherry Extract Market
Flavorings and Food Additives
France Food Colorants Market
Flavorings and Food Additives
Global Ginger Extract Market