
 Follicular Lymphoma Treatment Market | 2026-2036
Follicular Lymphoma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Follicular Lymphoma Treatment Market Intelligence
The bundling of companion diagnostics with targeted therapies is repositioning treatment selection for follicular lymphoma. This integrated approach allows for more precise patient stratification before initiating treatment. Roche leverages its combined diagnostics and pharmaceuticals portfolio to offer personalized medicine strategies. Bristol Myers Squibb specializes in pioneering cell therapies for relapsed and refractory patient populations.
Follicular lymphoma treatment encompasses medical interventions for a slow-growing, or indolent, B-cell non-Hodgkin lymphoma. This cancer is often characterized by the t(14;18) chromosomal translocation, which results in the overexpression of the anti-apoptotic BCL2 protein. Monoclonal antibodies, particularly anti-CD20 agents, remain a cornerstone of first-line treatment protocols. However, the targeted therapies segment, including PI3K and EZH2 inhibitors, shows significant growth for relapsed or refractory disease.
Regulatory frameworks from the US FDA and the European Medicines Agency (EMA) influence market access through designations like Breakthrough Therapy and PRIME. Approval pathways in jurisdictions such as China, governed by the NMPA, are also critical for therapy developers. Navigating the diverse reimbursement landscapes and demonstrating long-term value to payors will be decisive for market success.
Market Dynamics
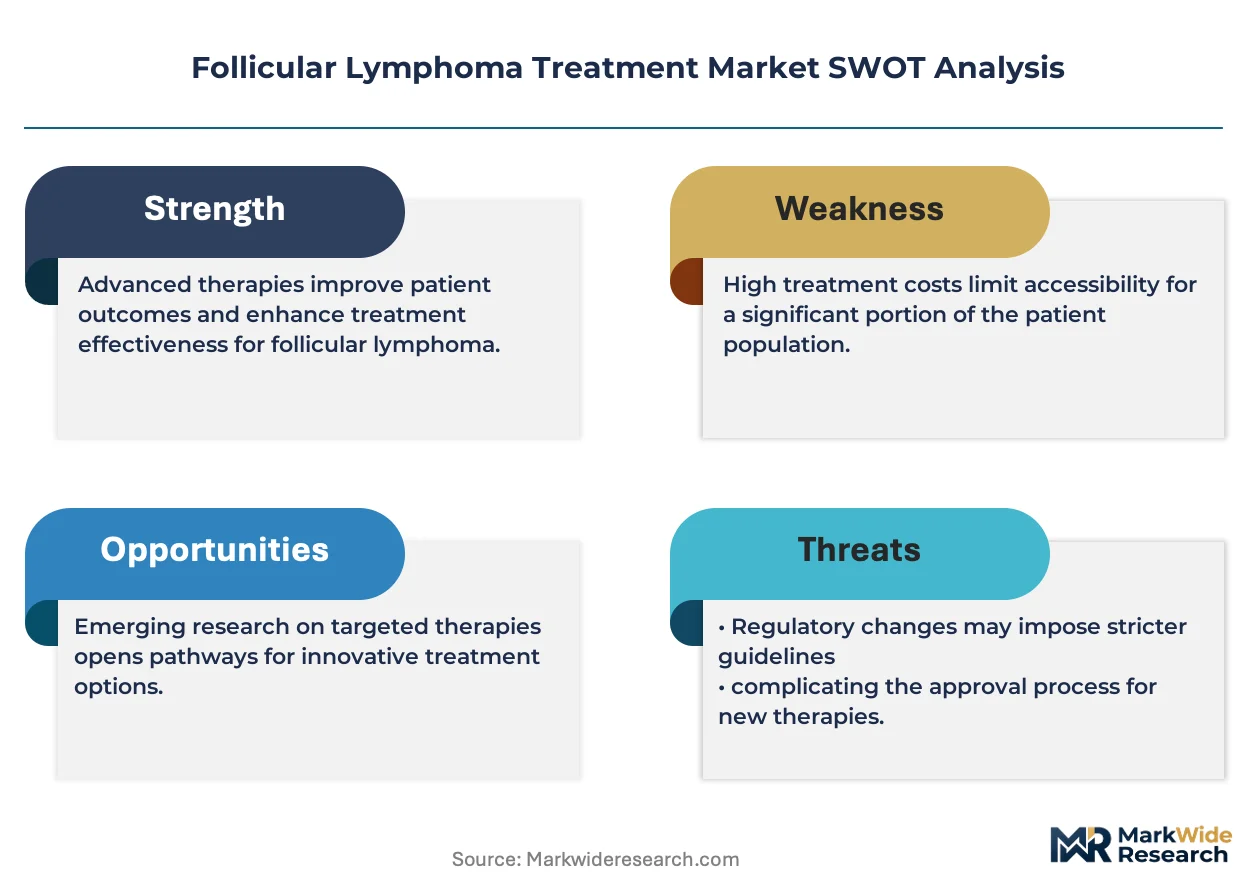
The bifurcation of treatment strategies defines the follicular lymphoma market, creating a clear division between established first-line protocols and highly specialized therapies for relapsed or refractory disease. This dynamic is driven by improved genetic diagnostics that stratify patients early.
Growth Catalysts
- Accelerated Regulatory Pathways:Designations like the FDA's Breakthrough Therapy and the EMA's PRIME scheme expedite the approval process for novel drugs targeting unmet needs in heavily pre-treated patient populations.
- Advancements in Genomic Profiling:The increasing use of next-generation sequencing in clinical practice enables the identification of specific mutations, such as in EZH2, guiding the use of targeted inhibitors.
- Concentrated Clinical Research:A high density of clinical trials and academic research centers in the United States accelerates the development and validation of new therapeutic modalities, including advanced cell therapies.
Market Restraints
- Prohibitive Treatment Costs:The exceptionally high price points for autologous cell therapies, such as CAR-T, create significant access and reimbursement hurdles for health systems and payors globally.
- Complex Treatment Logistics:Advanced cell therapies require specialized, certified treatment centers and carry risks of severe adverse events, limiting their widespread administration outside of major oncology hubs.
- Biosimilar Erosion:The impending patent expirations for foundational anti-CD20 monoclonal antibodies are expected to introduce biosimilar competition, placing downward price pressure on a core segment of the market.
Strategic Opportunities
- Allogeneic Cell Therapy Development:Investing in off-the-shelf allogeneic CAR-T platforms presents an opportunity to overcome the manufacturing bottlenecks and high costs associated with patient-specific autologous therapies.
- Expansion into New Geographies:As regulators like China's NMPA streamline oncology drug approvals, there is an opportunity to expand clinical trial footprints and commercial access into large, previously underpenetrated patient populations.
- AI in Drug Discovery:Applying artificial intelligence and machine learning to analyze large-scale genomic and proteomic datasets can uncover novel biological targets and predictive biomarkers for follicular lymphoma.
Industry Challenges
- Specialized Talent Scarcity:A shortage of healthcare professionals trained in the administration, monitoring, and management of toxicities related to cell therapies constrains the capacity of qualified treatment centers.
- Reimbursement Model Lag:Payor reimbursement frameworks are struggling to adapt to the high upfront costs and unique value proposition of single-administration curative therapies, delaying patient access.
- Manufacturing Scale-Up:The complex, multi-step manufacturing process for autologous cell therapies faces significant challenges in scalability, quality control, and turnaround time, creating supply constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Follicular Lymphoma Treatment Market |
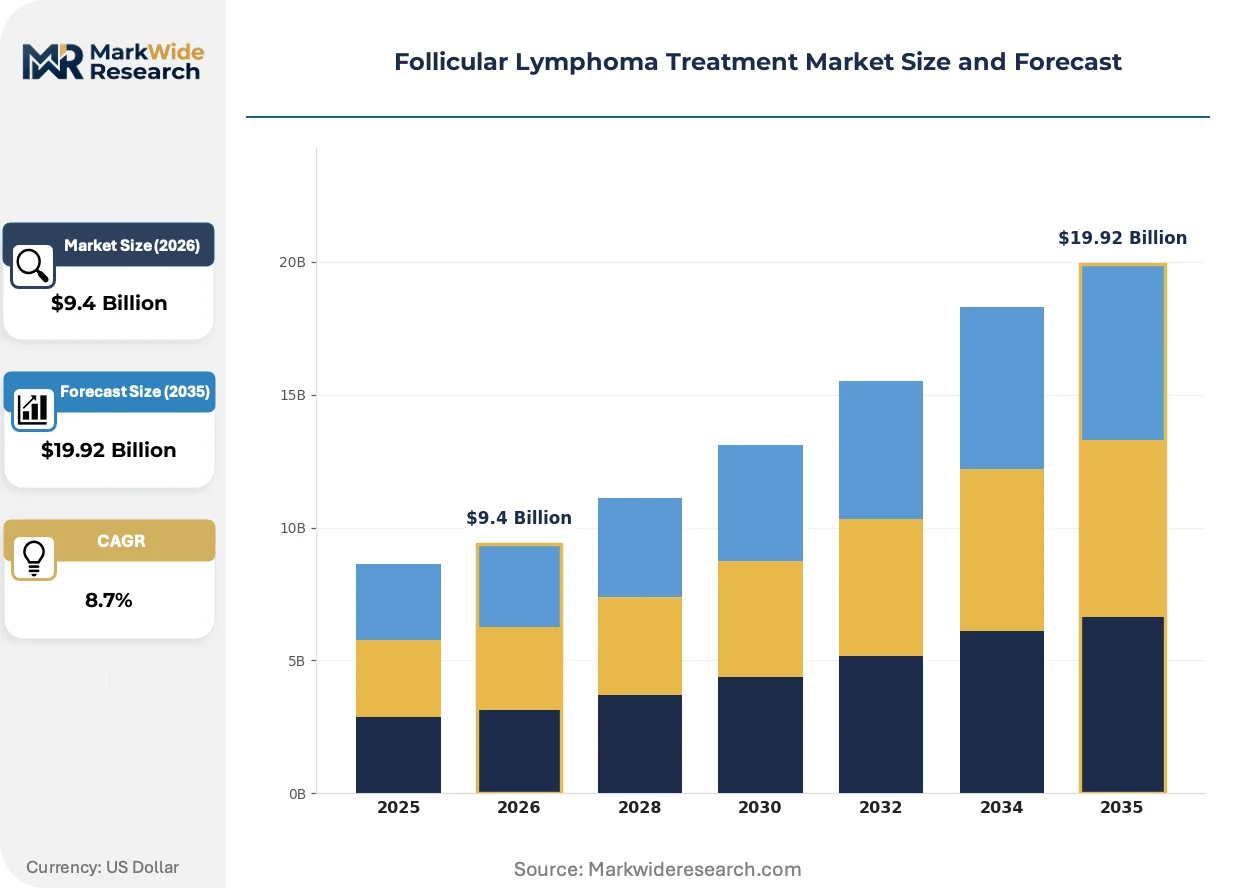
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $19.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Chemotherapy Agents, Targeted Therapies, Immunomodulators, Radiotherapy Therapy Area: First-Line Treatment, Relapsed/Refractory, Maintenance Therapy, Combination Therapy End User: Oncology Clinics, Hematology Centers, Outpatient Facilities, Specialist Hospitals Delivery Mode: Intravenous, Oral, Subcutaneous, Injectable, Infusion |
| Companies Covered | Roche, Novartis, Bristol Myers Squibb, AbbVie, Johnson & Johnson, Amgen, Merck & Co., Gilead Sciences, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Follicular Lymphoma Treatment Market Strategic Shifts & Innovations
Personalization is the central theme, with treatment decisions increasingly guided by a patient's specific genetic markers and prior treatment history. This shift moves the market away from generalized protocols toward precision medicine, particularly in later lines of therapy.
Bispecific antibodies represent a significant evolution in immunotherapy, designed to simultaneously bind to a cancer cell protein like CD20 and an immune cell receptor like CD3. Specialized oncology clinics are adopting these therapies for patients who have relapsed after multiple lines of treatment. This novel antibody engineering platform is absorbing the clinical development focus that was previously centered on single-target agents for refractory patient groups.
The European Medicines Agency's PRIME scheme offers enhanced regulatory and scientific support for medicines addressing significant unmet needs. This framework accelerates data generation and review timelines for promising follicular lymphoma treatments. Developers of innovative cell therapies and targeted agents are most affected, aligning clinical strategies to meet PRIME criteria for expedited assessment and potential market entry.
A demand-side shift toward valuing real-world evidence (RWE) alongside traditional randomized controlled trial data is influencing treatment guidelines and reimbursement. Payors and health technology assessment bodies use data from patient registries to evaluate the long-term effectiveness of novel agents outside the controlled trial setting. This trend is most prominent in the United States and key European markets, where it is becoming critical for demonstrating value for high-cost therapies.
Follicular Lymphoma Treatment Market Segmentation
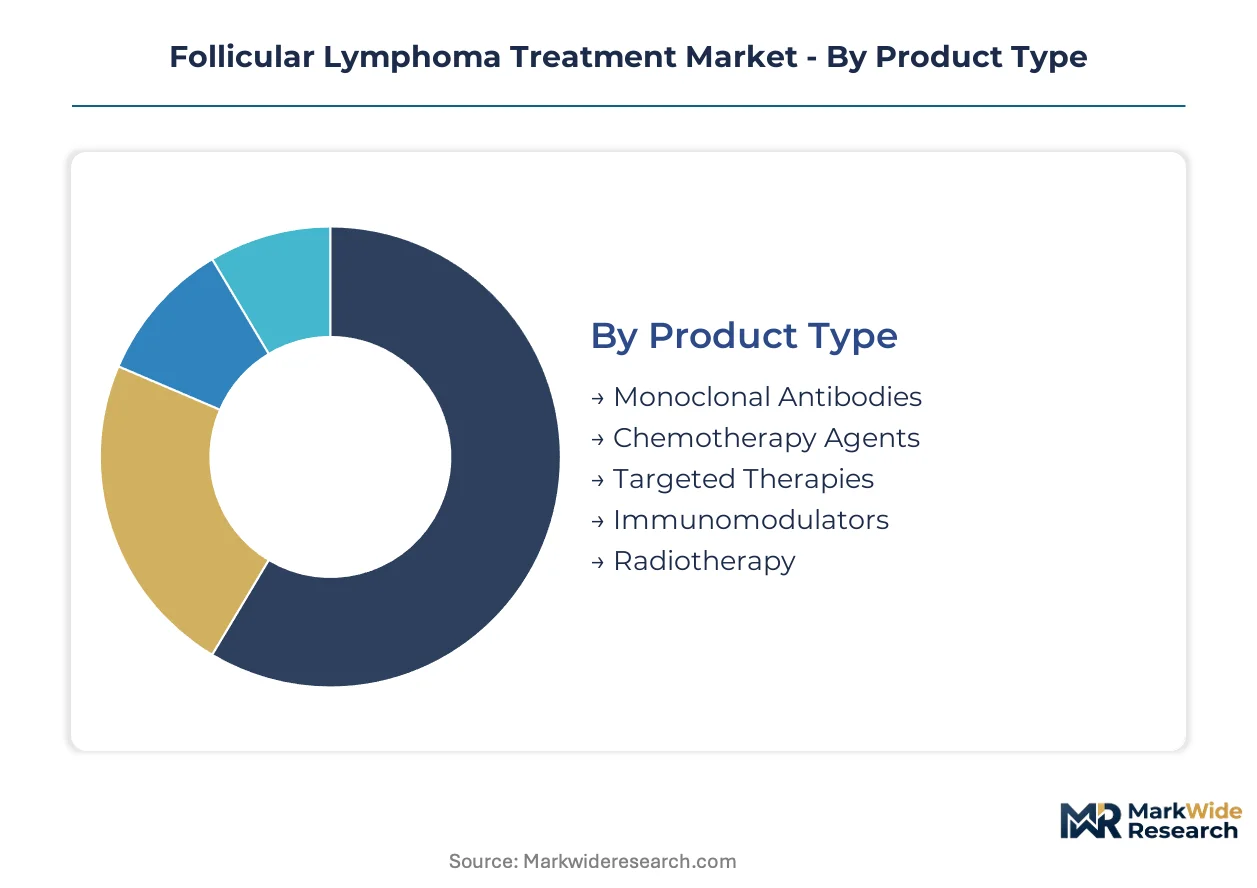
The follicular lymphoma treatment market is a complex ecosystem, with distinct segments emerging based on therapeutic innovation, patient needs, and delivery logistics. Understanding these divisions is crucial for stakeholders to identify growth opportunities and navigate the evolving treatment landscape.
Product Type:
The product type segmentation highlights varying regulatory approval burdens, with novel therapies often requiring accelerated designations from the US FDA and European Medicines Agency, while established agents face biosimilar pathways through China's NMPA.
- Monoclonal Antibodies:These biologic agents, primarily anti-CD20 antibodies, target specific proteins on lymphoma cells, forming the backbone of first-line treatment protocols. Demand concentrates in established markets like the United States and Germany, where their long-standing efficacy and safety profiles are well-understood.
- Targeted Therapies:This category includes small molecule inhibitors like PI3K and EZH2 inhibitors, designed to block specific pathways crucial for cancer cell growth and survival. Their adoption is concentrated in patients with relapsed or refractory disease, particularly in academic research centers in the United States, where genomic profiling guides treatment selection.
- Chemotherapy Agents:Traditional cytotoxic drugs continue to be used, often in combination regimens, for their broad anti-cancer effects.
- Immunomodulators:These agents, such as lenalidomide, modify the immune system's response to cancer, offering alternative mechanisms of action.
- Radiotherapy:Localized radiation therapy is employed for specific disease sites, particularly in early-stage or palliative settings.
Monoclonal Antibodies sits at the top of the volume ranking, with Targeted Therapies climbing the fastest.
Therapy Area:
Treatment approaches for follicular lymphoma bifurcate across the patient journey, addressing distinct disease stages from initial diagnosis to advanced relapse.
- First-Line Treatment:This segment encompasses initial therapies administered upon diagnosis, typically involving anti-CD20 monoclonal antibodies combined with chemotherapy or immunomodulators. Demand remains high across all geographies, driven by the incidence of new follicular lymphoma cases.
- Relapsed/Refractory:This category focuses on patients whose disease has returned or failed to respond to prior treatments, requiring more aggressive and often novel interventions like CAR-T cell therapies or bispecific antibodies. The United States and major European markets exhibit the highest demand for these complex therapies, supported by advanced clinical infrastructure.
- Maintenance Therapy:Ongoing treatment after initial response aims to prolong remission, frequently utilizing monoclonal antibodies at reduced frequency.
- Combination Therapy:This involves the synergistic use of multiple agents, enhancing efficacy and overcoming resistance mechanisms.
First-Line Treatment protocols represent the largest patient population, while Relapsed/Refractory interventions are expanding most quickly due to unmet needs.
End User:
The end-user landscape reflects the specialized nature of follicular lymphoma care, with centers offering advanced treatments requiring specific infrastructure and personnel.
- Oncology Clinics:These facilities provide comprehensive cancer care, including diagnosis, chemotherapy, and targeted therapy administration, serving a broad patient base. These clinics form the primary point of care for most follicular lymphoma patients, particularly in urban centers across Germany and France.
- Specialist Hospitals:Large academic medical centers and highly specialized hospitals manage complex cases, perform advanced procedures like stem cell transplants, and conduct clinical trials. These institutions are critical for the adoption of innovative cell therapies, with a high concentration in major cities like Boston and London.
- Hematology Centers:These centers specialize in blood disorders, including lymphomas, offering expert diagnosis and treatment.
- Outpatient Facilities:These settings provide convenient access for routine treatments and follow-up care, reducing inpatient stays.
Oncology Clinics manage the broadest patient cohort, with Specialist Hospitals driving innovation in complex case management.
Delivery Mode:
Patient convenience and logistical considerations heavily influence the choice of delivery mode, impacting treatment adherence and healthcare resource utilization.
- Intravenous:Many foundational and advanced treatments, including monoclonal antibodies and chemotherapy, are administered directly into the bloodstream via infusion. This mode requires professional healthcare settings and is prevalent across all major markets for initial and complex therapies.
- Oral:Oral medications offer convenience for patients, allowing self-administration at home and reducing the need for frequent clinic visits. The demand for oral targeted therapies is growing in regions with strong outpatient care networks, such as the United States and Japan.
- Subcutaneous:Injections under the skin provide an alternative to intravenous, often allowing for quicker administration and potential home use for certain biologics.
- Injectable:This broad category includes both intravenous and subcutaneous methods, highlighting therapies requiring parenteral administration.
- Infusion:This refers specifically to the slow, controlled administration of fluids or medications, typically intravenously, for extended periods.
Intravenous administration remains foundational for many therapies, while Oral options are gaining traction for their ease of use.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The follicular lymphoma treatment market scaled significantly through the development of advanced therapies, particularly in the United States. This region became a hub for clinical trials and academic research, driving early adoption of innovative treatments. Specialized oncology clinics consistently contribute to market value across developed economies.
United States
The United States exhibits strong demand for innovative follicular lymphoma treatments, driven by a high concentration of clinical trials. The US FDA's Breakthrough Therapy designation expedites approval for novel drugs targeting unmet needs. Major biotech hubs in Boston and New York City foster significant advancements in cell therapies.
Germany
German healthcare providers consistently adopt established monoclonal antibodies and targeted therapies for follicular lymphoma patients. The EMA's PRIME scheme offers enhanced regulatory support for promising treatments addressing unmet needs. Specialized hospitals in Munich and Berlin are crucial for the administration of complex cell therapies.
Japan
Demand in Japan is growing for both established and novel follicular lymphoma treatments, including oral targeted therapies. The PMDA's approval pathways are essential for market access for new pharmaceutical products. Tokyo and Osaka are key regions for clinical research and the deployment of advanced oncology interventions.
China
China presents a significant opportunity for market expansion, particularly as regulators streamline oncology drug approvals. The NMPA's processes are critical for therapy developers seeking to enter this large patient population. Shanghai and Beijing are rapidly developing into major centers for clinical trials and commercial oncology access.
United Kingdom
British health systems show high demand for novel agents, valuing real-world evidence alongside trial data for high-cost therapies. The MHRA reviews new drug applications, while NICE assesses long-term value for reimbursement decisions. London and Cambridge host major medical research institutions and specialized oncology clinics.
Follicular Lymphoma Treatment Market Key Industry Players
Premium-margin players sit above commodity-margin players across therapeutic innovation and R&D intensity in the follicular lymphoma treatment market. The market structure is tiered, encompassing distinct archetypes focusing on novel cell therapies, established biologics, and targeted small molecules. Innovators prioritize advanced research and development to address unmet needs in relapsed or refractory disease. Companies actively pursue strategic partnerships for pipeline development and engage in portfolio diversification through targeted M&A activities.
On the premium-tier vector, companies like Roche, a Swiss pharmaceutical giant, exemplify integrated personalized medicine strategies by combining diagnostics and therapeutics. This approach allows for more precise patient stratification and treatment selection. Bristol Myers Squibb, a US-based biopharmaceutical company, occupies a strong position in pioneering cell therapies for patients with relapsed or refractory disease, addressing critical unmet needs. Gilead Sciences, another US-based firm, sits within the advanced cell therapy segment, focusing on innovative treatments for complex hematological malignancies and expanding therapeutic options. These firms drive significant innovation in the market.
| Leading Market Players |
|---|
| Roche |
| Novartis |
| Bristol Myers Squibb |
| AbbVie |
| Johnson & Johnson |
| Amgen |
| Merck & Co. |
| Gilead Sciences |
| AstraZeneca |
Cost & Logistics Intelligence
Manufacturing complexity for autologous cell therapies drives significant cost differentiation, impacting pricing tiers for these advanced treatments from specialized centers to payors globally.
Pricing Analysis
Value-based pricing models increasingly dominate the follicular lymphoma market, particularly for novel cell therapies and targeted agents. Price differentiation stems from the therapy's clinical efficacy, US FDA Breakthrough Therapy or European Medicines Agency PRIME designations, and the specialized infrastructure required for administration. Pricing pressure intensifies for established monoclonal antibodies due to impending biosimilar erosion. Relapsed/refractory patient populations exhibit lower price sensitivity for life-extending therapies, while first-line treatments face higher scrutiny from payors.
Supply Chain Analysis
Single-source vulnerability sits with specialized manufacturing facilities for advanced cell therapies, concentrated primarily in the United States and select European hubs like Germany. Raw material dependencies include viral vectors for CAR-T production and highly purified reagents for targeted inhibitors. Logistics chokepoints present a structural risk, especially for time-sensitive autologous cell therapies requiring rapid patient-to-manufacturing-to-patient turnaround. Distribution runs through a network of highly specialized oncology clinics and academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The follicular lymphoma treatment market acts as a stable compounder, driven by continuous innovation in targeted therapies addressing unmet patient needs.
For Market Incumbents: Acquire specialized cell therapy platforms to counter the threat of emerging biotech firms displacing established monoclonal antibodies. Deepen vertical integration into advanced diagnostic capabilities to reinforce personalized medicine strategies. Invest in clinical trial expansion within key European markets to leverage PRIME designations and secure market access against biosimilar competition.
For New Entrants and Emerging Players: Capture underserved patient populations in emerging markets like China by aligning with NMPA streamlined approval pathways. Target niche relapsed/refractory segments with novel bispecific antibodies, offering a differentiated go-to-market angle through specialized oncology clinics. Focus on developing allogeneic cell therapies to overcome the manufacturing bottlenecks associated with autologous treatments.
For Investors and Strategic Acquirers: Consolidation pressure builds where manufacturing capabilities for advanced cell therapies remain scarce. This market offers long-term viability over a 5-10 year window due to persistent unmet needs in advanced disease. Target vertically integrated biopharmaceutical companies with strong R&D pipelines in gene editing or novel immunotherapies. The signal to watch is the successful clinical translation of off-the-shelf allogeneic CAR-T platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates regulatory approval for novel agents, particularly in the United States. |
| Manufacturing Scale-Up | Addresses supply constraints for complex autologous cell therapies globally. |
| Regulatory Approval Pathway | Streamlines market entry for innovative treatments in China and Europe. |
| Pipeline Diversification | Mitigates risk from biosimilar erosion of established monoclonal antibodies. |
| Strategic Partnership | Leverages combined diagnostics and pharmaceuticals portfolios for personalized medicine. |
Research Approach
Bottom-up patient population modeling reconciled against top-down pharmaceutical sales tracking forms the analytical core of this study. Primary interviews with oncology specialists, hospital procurement managers, regulatory affairs leads, and payor access specialists provided critical insights. Secondary validation drew from US FDA filings, European Medicines Agency submissions, ClinicalTrials.gov, and peer-reviewed scientific literature. This triangulation ensures a robust understanding of market dynamics.
An input-output matrix framework established interdependencies across market segments over the projection horizon. Segmentation dimensions modeled include product type, therapy area, end-user, delivery mode, and regional regulatory frameworks. Compound annual growth rates were derived from historical data analysis and projected market drivers. Key forecast inputs included anticipated drug approvals and patent expiration timelines.
Regulatory shifts, unexpected clinical trial outcomes, and evolving reimbursement policies are the dominant revision risks for market forecasts. Forecasts reflect documented assumptions regarding these factors. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Febrile Neutropenia Market
Hematology
Multiple Myeloma Treatment Market
Hematology
Global Non-Hodgkin Lymphoma Therapeutics Market
Hematology
Global Hematology Market
Hematology
Small Lymphocytic Lymphoma Market
Hematology
Hematology Analyzers Market
Hematology
Polycythemia Vera Treatment Market
Hematology
Sickle Cell Treatment Market
Hematology
Erythropoietic Protoporphyria (EPP) Treatment Market
Hematology
Global Hematologic Malignancies Treatment Market
Hematology
Polycythemia Vera Market
Hematology
Chemotherapy-Induced Myelosuppression Treatment Market
Hematology
Heparin-Induced Thrombocytopenia (HIT) Treatment Market
Hematology
Rare Hematology Market
Hematology
APAC Acute Myeloid Leukemia Treatment Market
Hematology
Congenital Amegakaryocytic Thrombocytopenia (CAMT) Market