
 Heparin-Induced Thrombocytopenia (HIT) Treatment Market | 2026-2036
Heparin-Induced Thrombocytopenia (HIT) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Heparin-Induced Thrombocytopenia (HIT) Treatment Market Foresight
Hospital procurement consortiums is reshaping how parenteral anticoagulants reach acute-care settings. Pfizer Inc. leverages its critical-care distribution infrastructure to secure formulary placement across integrated delivery networks. Fresenius Kabi AG anchors European hospital supply through its generic injectables portfolio. Eagle Pharmaceuticals Inc. specializes in ready-to-use formulations that reduce pharmacy compounding burden.
Heparin-induced thrombocytopenia denotes an immune-mediated prothrombotic disorder triggered by IgG antibodies against platelet factor 4-heparin complexes, requiring immediate discontinuation of all heparin exposure and initiation of alternative anticoagulation with direct thrombin inhibitors or factor Xa inhibitors. The condition demands continuous platelet count monitoring and carries substantial morbidity from thrombotic complications including limb ischemia and cerebral infarction. Argatroban dominates the product type landscape due to its established intravenous protocol in surgical and percutaneous intervention settings. Home healthcare represents the fastest-growing end user segment as stable patients transition to subcutaneous fondaparinux or oral anticoagulation under remote monitoring protocols.
FDA guidance on heparin-induced thrombocytopenia diagnosis and management shapes clinical trial endpoints for novel anticoagulant development, while EMA pharmacovigilance requirements mandate systematic platelet surveillance reporting across member states. ISO standards for injectable manufacturing govern sterility and stability specifications for hospital-ready formulations. Stakeholders must monitor evolving thrombosis society guidelines that periodically redefine optimal anticoagulant selection based on bleeding-risk stratification and renal function thresholds.
Market Dynamics
Hospital anticoagulation protocols are consolidating around direct thrombin inhibitors as cardiac surgery volumes rise and immunoglobulin-mediated adverse reactions trigger stricter platelet surveillance mandates across tertiary care networks.
Growth Catalysts
- FDA platelet monitoring guidance:Tightened clinical standards for immunoglobulin-mediated adverse reactions are accelerating formulary upgrades to alternative anticoagulants in US cardiac centers.
- Home healthcare transition:Stable HIT patients shifting to subcutaneous fondaparinux under remote monitoring protocols are expanding addressable patient days beyond hospital walls.
- Cardiac surgery volume concentration:Tertiary centers in the United States, Germany, and Japan are generating caseload density that justifies dedicated HIT treatment pathways and specialized pharmacy infrastructure.
Market Restraints
- Argatroban supply concentration:Parenteral direct thrombin inhibitor production clusters among limited sterile injectable manufacturers, creating vulnerability to batch contamination or facility shutdown.
- Reimbursement compression:US Medicare severity-adjusted diagnosis-related group payments for HIT complicating cardiac procedures lag actual pharmacy acquisition costs for branded alternatives.
- Diagnostic specificity limitations:Serotonin release assay availability constraints and false-positive enzyme-linked immunosorbent assay rates delay definitive diagnosis, prolonging unnecessary heparin cessation.
Strategic Opportunities
- Ready-to-use formulation expansion:Premixed argatroban bags eliminating pharmacy compounding are capturing formulary preference in US integrated delivery networks seeking Joint Commission compliance simplification.
- Japan's aging surgical population:Expanding percutaneous coronary intervention volumes among elderly patients with complex heparin exposure histories are elevating HIT recognition and alternative anticoagulant demand.
- Real-world evidence mandates:EMA pharmacovigilance requirements for systematic platelet surveillance reporting are creating data infrastructure partnerships between hospitals and anticoagulant sponsors.
Industry Challenges
- Specialized hematopathology staffing:Interpretation of platelet factor 4 antibody titers and serotonin release assay results requires scarce laboratory medicine expertise concentrated at academic medical centers.
- Cross-reactivity assessment protocols:Determining safe re-exposure to heparin for patients with prior HIT history demands institutional review board oversight and individualized risk stratification that slows surgical scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heparin-Induced Thrombocytopenia (HIT) Treatment Market |
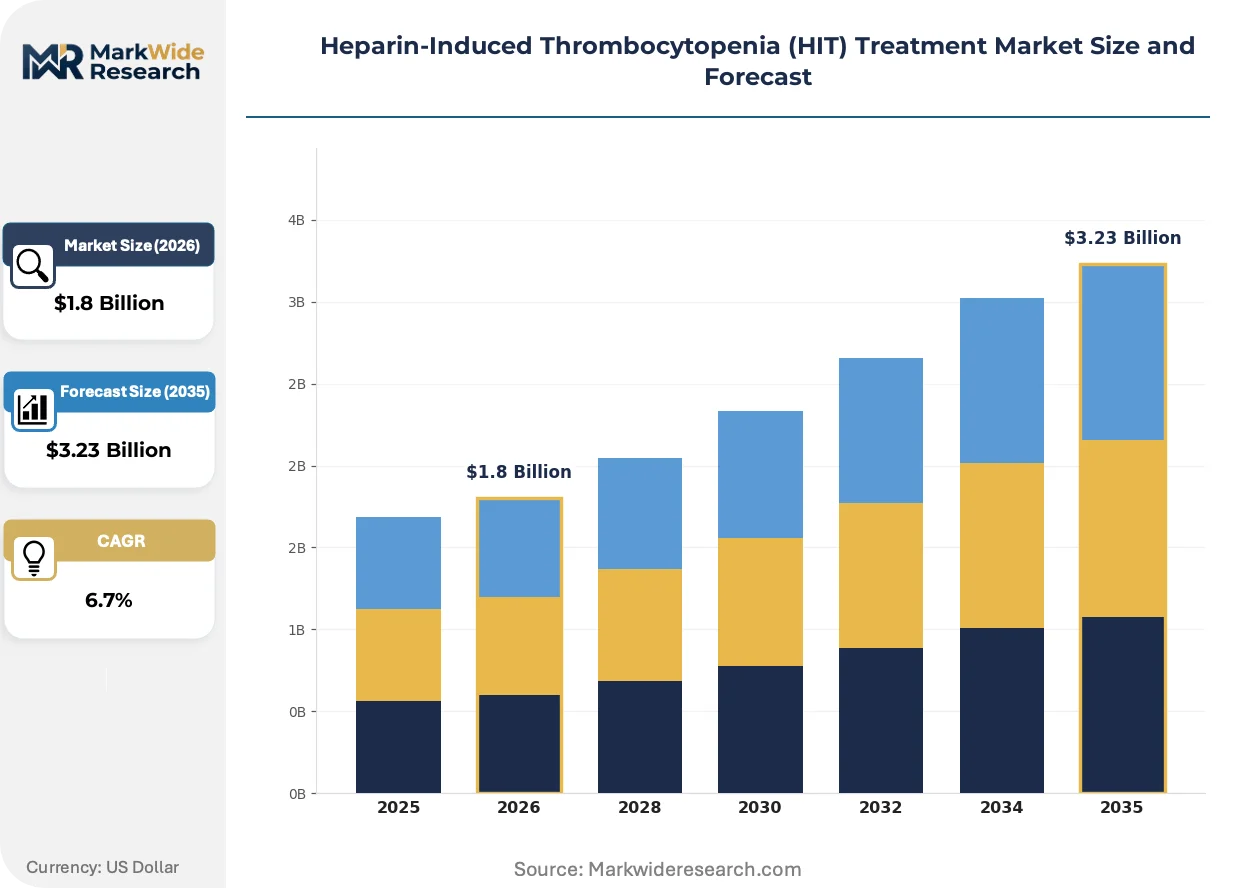
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Argatroban, Bivalirudin, Fondaparinux, Danaparoid End User: Hospitals, Specialty Clinics, Diagnostic Centers, Home Healthcare Administration Route: Intravenous, Subcutaneous, Oral, Intramuscular Distribution Channel: Direct Sales, Online Pharmacies, Retail Pharmacies, Wholesalers |
| Companies Covered | Pfizer Inc., Bayer Healthcare Pharmaceuticals Inc., GlaxoSmithKline Plc., Teva Pharmaceutical Industries Ltd., Sanofi S.A., Eagle Pharmaceuticals Inc., Fresenius Kabi AG, Bristol Myers Squibb Company, Janssen Pharmaceuticals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heparin-Induced Thrombocytopenia (HIT) Treatment Market Shifts & Advancements
Anticoagulant delivery is converging on point-of-care readiness as hospital pharmacies face compounding capacity constraints and regulatory scrutiny intensifies around sterile preparation practices.
Ready-to-use argatroban formulations are virtualizing traditional pharmacy compounding workflows by eliminating admixture steps and reducing contamination risk. Surgical units at high-volume cardiac centers are adopting these premixed presentations fastest, compressing time-to-treatment intervals and reallocating pharmacy technician labor to higher-complexity tasks.
EMA pharmacovigilance requirements now mandate systematic platelet surveillance reporting across all member states, forcing hospitals to deploy integrated laboratory-information-system triggers for automated HIT suspicion alerts. This regulatory architecture is elevating diagnostic consistency but imposing substantial health-information-technology upgrade costs on smaller European facilities.
Integrated delivery networks are consolidating anticoagulant procurement through centralized pharmacy and therapeutics committees that standardize HIT protocols across multiple hospital sites. This buyer concentration is displacing individual physician preference in favor of system-wide contracts with formulary exclusivity provisions, most visible in US multi-hospital systems spanning several states.
Heparin-Induced Thrombocytopenia (HIT) Treatment Market Segmentation
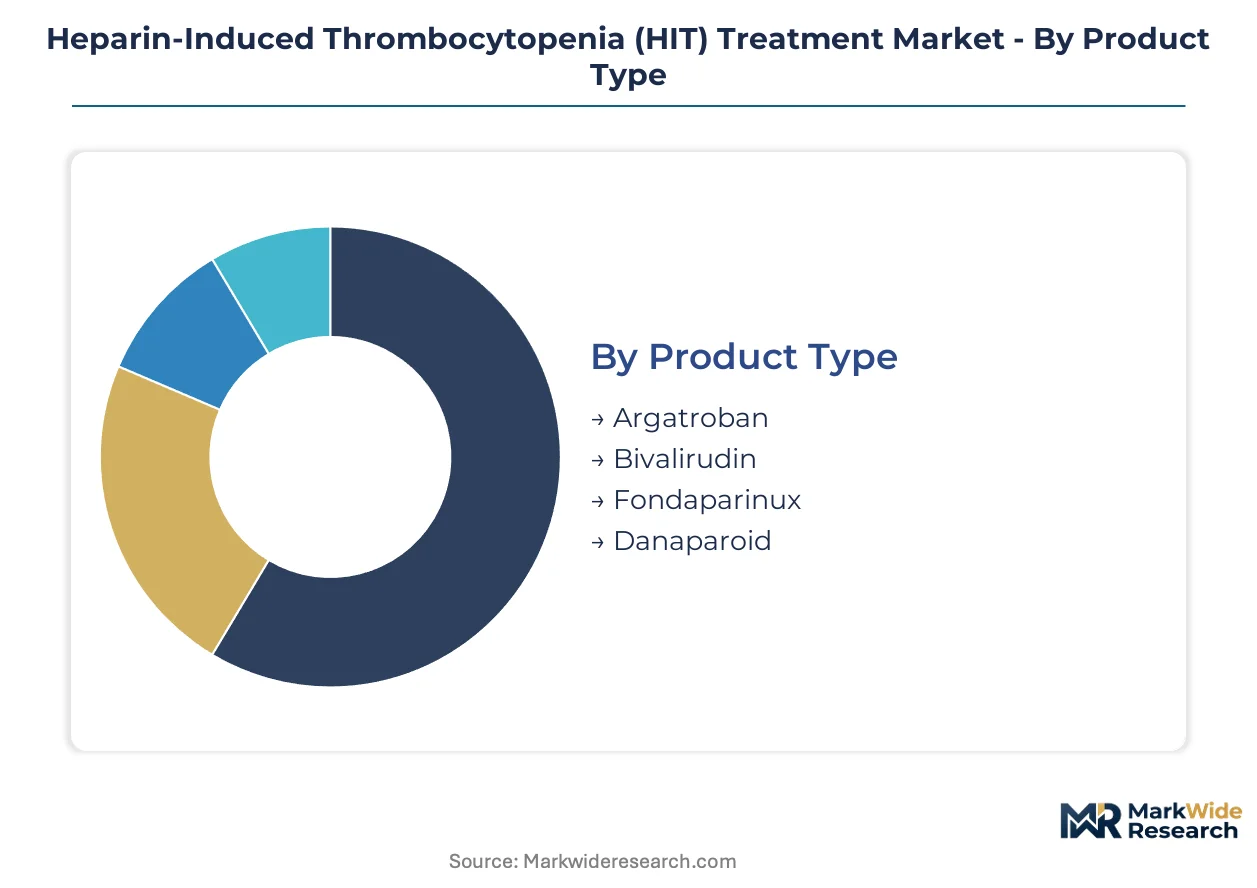
HIT treatment segmentation reflects divergent clinical workflows across acute intervention and chronic management settings. Each category captures distinct procurement patterns, reimbursement pathways, and patient risk profiles that shape commercial strategy.
Product Type:
After-sales service intensity varies sharply across parenteral anticoagulants, with intravenous formulations demanding continuous clinical pharmacy support and therapeutic drug monitoring.
- Argatroban:Synthetic direct thrombin inhibitor administered via continuous intravenous infusion with dose titration based on activated partial thromboplastin time. Demand concentrates in United States cardiac surgery centers where FDA-cleared protocols support percutaneous coronary intervention anticoagulation. Hospital formulary placement depends on intensive care unit nursing familiarity and pharmacy compounding capacity.
- Bivalirudin:Reversible direct thrombin inhibitor with shorter half-life enabling rapid procedural anticoagulation offset. Percutaneous coronary intervention suites in Germany and Japan favor this agent for patients with suspected or confirmed HIT requiring urgent revascularization. Higher acquisition costs limit penetration outside tertiary referral networks.
- Fondaparinux:Synthetic pentasaccharide factor Xa inhibitor enabling subcutaneous outpatient transition.
- Danaparoid:Heparinoid anticoagulant with minimal cross-reactivity reserved for refractory cases.
By volume, Argatroban leads. By growth pace, Fondaparinux is expanding most quickly through home healthcare transition protocols.
End User:
Customer type determines reimbursement complexity and purchasing authority concentration across the care continuum.
- Hospitals:Tertiary cardiac centers generate the highest caseload density with dedicated anticoagulation stewardship programs. United States integrated delivery networks consolidate procurement through centralized pharmacy and therapeutics committees with formulary exclusivity provisions.
- Home Healthcare:Stable HIT patients transitioning to subcutaneous fondaparinux or oral anticoagulation under remote monitoring protocols. Medicare home health benefit coverage and telemedicine reimbursement policies in the United States accelerate segment expansion.
- Specialty Clinics:Outpatient anticoagulation management for post-acute monitoring.
- Diagnostic Centers:Serotonin release assay and platelet factor 4 antibody testing services.
Hospitals dominate current revenue. Home Healthcare shows the steepest expansion trajectory as remote monitoring infrastructure matures.
Administration Route:
Supply concentration in sterile injectable manufacturing shapes route availability and geographic access patterns.
- Intravenous:Continuous infusion delivery for acute thrombosis management in intensive care settings. United States and German cardiac surgery volumes sustain demand for pump-compatible formulations with established therapeutic drug monitoring protocols.
- Subcutaneous:Outpatient self-administration enabling hospital discharge and reduced length of stay. Japan's aging percutaneous coronary intervention population and home healthcare infrastructure support segment growth.
- Oral:Transition agents including vitamin K antagonists and direct oral anticoagulants.
- Intramuscular:Limited applications due to hematoma risk in anticoagulated patients.
Intravenous routes command current volume leadership. Subcutaneous delivery is gaining share fastest through ambulatory care expansion.
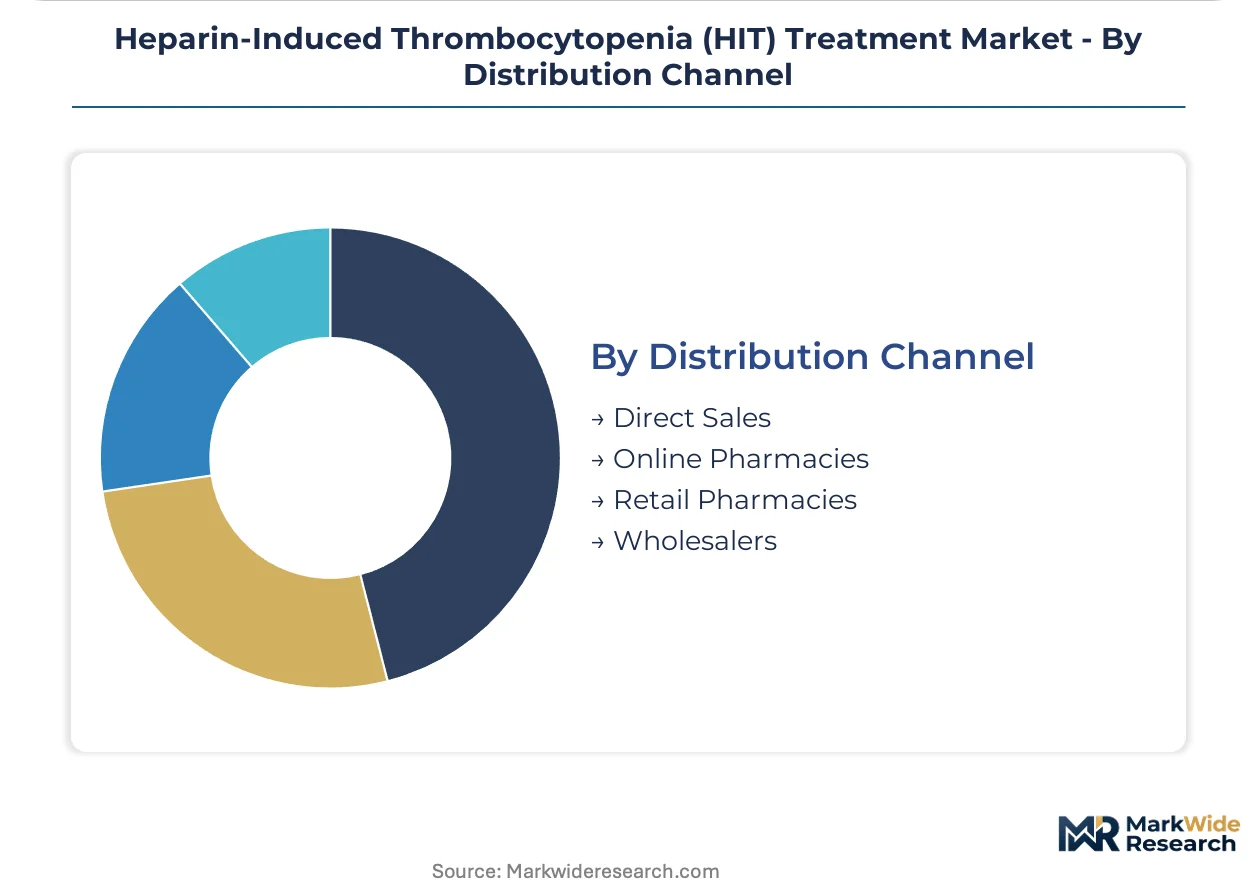
Distribution Channel:
Margin structures diverge across channel types based on cold-chain requirements and contractual service levels.
- Direct Sales:Manufacturer-to-hospital contracts for high-volume parenteral anticoagulants with just-in-time inventory guarantees. Pfizer and Fresenius Kabi anchor European and United States hospital supply through dedicated critical-care distribution infrastructure.
- Wholesalers:Broad-line distribution reaching smaller hospitals and specialty clinics with consolidated purchasing. Three national wholesalers dominate United States hospital pharmaceutical supply, negotiating system-wide contracts with integrated delivery networks.
- Retail Pharmacies:Outpatient prescription fulfillment for oral anticoagulation transition.
- Online Pharmacies:Emerging channel for home healthcare patient support programs.
Direct sales generate highest absolute volume. Wholesalers are climbing the fastest as mid-tier hospitals consolidate procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA platelet monitoring guidance anchors United States clinical practice, while EMA pharmacovigilance mandates reshape European hospital protocols. Tertiary cardiac centers in Germany and Japan concentrate the highest caseload densities.
United States
Medicare severity-adjusted diagnosis-related group payments and integrated delivery network consolidation drive anticoagulant procurement standardization. FDA guidance on heparin-induced thrombocytopenia diagnosis shapes clinical trial endpoints for novel agents. The Cleveland Clinic and Mayo Clinic cardiac surgery centers generate sufficient HIT caseload to justify dedicated pharmacy infrastructure and specialized stewardship programs.
Germany
Percutaneous coronary intervention volumes and aging surgical populations elevate alternative anticoagulant demand in tertiary referral networks. EMA pharmacovigilance requirements mandate systematic platelet surveillance reporting across member states. The Charité-Universitätsmedizin Berlin and Heidelberg University Hospital anchor European HIT treatment pathway development through academic hematopathology expertise concentration.
Japan
Expanding percutaneous coronary intervention volumes among elderly patients with complex heparin exposure histories drive recognition and treatment demand. PMDA regulatory frameworks govern anticoagulant approval pathways and post-market surveillance requirements. The National Cerebral and Cardiovascular Center in Osaka and Tokyo's Juntendo University Hospital concentrate specialized anticoagulation management capacity.
United Kingdom
NHS England specialized commissioning frameworks and thrombosis society guideline adherence shape hospital formulary decisions. MHRA vigilance requirements align with EMA pharmacovigilance standards for immunoglobulin-mediated adverse reaction reporting. The Royal Brompton and Harefield NHS Foundation Trust and Oxford University Hospitals NHS Foundation Trust maintain dedicated anticoagulation stewardship programs.
Canada
Health Canada regulatory standards and provincial health authority procurement consolidation influence parenteral anticoagulant access patterns. CADTH health technology assessment processes evaluate alternative anticoagulant cost-effectiveness for formulary inclusion. The University Health Network in Toronto and McGill University Health Centre in Montreal anchor national HIT treatment protocol development.
Heparin-Induced Thrombocytopenia (HIT) Treatment Market Competitive Landscape
Critical-care distribution specialists and generic injectable manufacturers split the market between branded formulation leadership and cost-driven hospital procurement. Hospital procurement consortiums and integrated delivery network consolidation favor suppliers with just-in-time inventory guarantees and sterile manufacturing scale. Three strategic archetypes dominate: multinational pharmaceutical conglomerates with critical-care infrastructure, specialized generic injectable producers with European hospital anchoring, and ready-to-use formulation innovators reducing pharmacy compounding burden. Competitive moves center on formulary exclusivity negotiations and premixed presentation development.
Among multinational pharmaceutical conglomerates, Pfizer Inc. and GlaxoSmithKline Plc. occupy positions reflecting critical-care distribution infrastructure and hospital relationship depth. Fresenius Kabi AG exemplifies the generic injectable specialist archetype with European hospital supply anchoring. Eagle Pharmaceuticals Inc. represents ready-to-use formulation innovation targeting pharmacy workflow simplification.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Bayer Healthcare Pharmaceuticals Inc. |
| GlaxoSmithKline Plc. |
| Teva Pharmaceutical Industries Ltd. |
| Sanofi S.A. |
| Eagle Pharmaceuticals Inc. |
| Fresenius Kabi AG |
| Bristol Myers Squibb Company |
| Janssen Pharmaceuticals Inc. |
| Others |
Supply & Pricing Matrix
Air freight corridors linking Frankfurt and Chicago carry temperature-sensitive argatroban shipments that cost three to five times standard pharmaceutical freight, compressing margins for European manufacturers serving United States cardiac centers while enabling premium pricing for just-in-time delivery guarantees. This logistics cost structure reinforces pricing power concentration among sterile injectable specialists with dedicated cold-chain infrastructure.
Pricing Analysis
The customization-premium spread separates standard vial presentations from ready-to-use premixed bags, with the latter commanding substantial formulary preference in United States integrated delivery networks. Contract-based long-term offtake agreements dominate hospital procurement, with price differentiation resting on FDA approval tier and pharmacy compounding burden reduction. Cost compression in standard vial formats is intensifying because Medicare severity-adjusted diagnosis-related group payments lag actual acquisition costs. Mid-tier community hospitals exhibit highest price sensitivity, while tertiary cardiac centers prioritize clinical workflow efficiency over unit cost.
Supply Chain Analysis
Extended payment terms from United States group purchasing organizations now stretch to 90-120 days, forcing European manufacturers to access supply-chain finance facilities to maintain working capital. Sterile injectable production clusters in Germany, Italy, and the United States, with active pharmaceutical ingredient synthesis drawing from specialized chemical manufacturers in Switzerland and India. Single-source vulnerability pervades the parenteral anticoagulant segment where facility shutdowns or batch contamination trigger immediate shortage. Distribution runs through direct manufacturer-to-hospital contracts for high-volume accounts, supplemented by wholesaler reach to smaller facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network consolidation in the United States and European hospital procurement consortiums, shifting negotiation leverage toward centralized pharmacy and therapeutics committees with formulary exclusivity authority.
For Market Incumbents: Harden formulary position by securing Joint Commission-compliant ready-to-use formulation exclusivity across multi-hospital systems. Expand backward integration into active pharmaceutical ingredient synthesis to offset European energy cost volatility. Anchor capacity in Germany and United States manufacturing corridors to mitigate tariff exposure on cross-Atlantic sterile injectable shipments. For New Entrants and Emerging Players: Pursue home healthcare transition protocols as the most penetrable segment, where subcutaneous fondaparinux demand outstocks established hospital supply relationships. Target Japan's aging percutaneous coronary intervention population through PMDA regulatory pathway partnerships with local distributors. Lead with remote monitoring platform integration to differentiate from commodity anticoagulant suppliers. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational pharmaceutical conglomerates divesting critical-care injectable portfolios lacking scale synergy with core therapeutic areas. Long-term viability centers on regulatory data exclusivity and real-world evidence generation infrastructure rather than molecule patent protection. Watch FDA guidance revisions on platelet monitoring protocols as inflection indicators for formulary upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Ready-to-Use Formulation Expansion | Premixed argatroban bags capture Joint Commission compliance preference in United States integrated delivery networks. |
| EMA Pharmacovigilance Data Partnership | Systematic platelet surveillance reporting infrastructure creates hospital-sponsor collaboration lock-in across European member states. |
| Home Healthcare Transition Platform | Remote monitoring protocols for subcutaneous fondaparinux extend patient days beyond hospital reimbursement constraints. |
| Sterile Manufacturing Capacity Addition | United States and Germany facility investments reduce batch contamination vulnerability and tariff exposure. |
| Real-World Evidence Generation Program | Post-market surveillance data supports formulary defense against novel oral anticoagulant entrants. |
Research Methodology
A standing panel of hospital pharmacy directors, critical-care nursing supervisors, hematopathology laboratory chiefs, and anticoagulation stewardship program leads provided ongoing calibration against secondary validation from FDA guidance documents, EMA pharmacovigilance reports, ClinicalTrials.gov entries, and hospital procurement database extracts. Bottom-up patient volume modeling triangulated with top-down pharmaceutical manufacturer revenue analysis.
Scenario-bracketing framed demand projections across conservative, baseline, and accelerated adoption pathways without fixed-year anchoring. Segmentation dimensions spanned product type, administration route, end-user setting, and regional regulatory cluster. CAGRs derived from logistic curve fitting to hospital protocol adoption patterns and cardiac surgery volume trajectories. Forecast inputs incorporated Medicare reimbursement trajectory assumptions and EMA pharmacovigilance implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in healthcare expenditure growth rates, pharmaceutical freight costs, or sterile manufacturing energy prices would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory guidance stability and hospital consolidation pace. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Sickle Cell Treatment Market
Hematology
Mantle Cell Lymphoma Treatment Market
Hematology
Hemoglobinopathies Treatment Market
Hematology
Burkitt Lymphoma Treatment Market
Hematology
Sickle Cell Disease Market
Hematology
Hemoglobinopathy Treatment Drug Market
Hematology
Hemocytometer Market
Hematology
Radiation-Induced Myelosuppression Treatment Market
Hematology
Follicular Lymphoma Treatment Market
Hematology
Hypereosinophilic Syndrome Market
Hematology
Marginal Zone Lymphoma Treatment Market
Hematology
AL Amyloidosis Therapeutics Market
Hematology
APAC Acute Myeloid Leukemia Treatment Market
Hematology
Multiple Myeloma Treatment Market
Hematology
Congenital Amegakaryocytic Thrombocytopenia (CAMT) Market
Hematology
Thrombocytopenia Treatment Market