
 Febrile Neutropenia Market | 2026-2036
Febrile Neutropenia Market Size, Share, and Industry Trends Forecast 2026-2036
Febrile Neutropenia Market Analysis
Prophylactic G-CSF administration is reconfiguring how oncology practices allocate spending between inpatient rescue and outpatient prevention. Amgen dominates the pegfilgrastim segment through manufacturing scale and long-acting formulation leadership. Pfizer leverages its broad-spectrum antibiotic portfolio to compete across empiric therapy protocols in hospitalized neutropenic patients. Fresenius Kabi anchors the generic injectables supply chain, sustaining price-accessibility for high-volume institutional purchasers.
Febrile neutropenia denotes a life-threatening oncologic emergency defined by fever exceeding 38.3°C sustained for one hour in patients with absolute neutrophil counts below 500 cells per microliter, requiring immediate empiric broad-spectrum antibiotic initiation. Granulocyte Colony-Stimulating Factor products command the largest revenue share within prophylaxis, while intravenous antibiotics retain dominant administration-route volumes for inpatient rescue settings. The cancer therapy area generates disproportionate case volumes compared with autoimmune or infectious disease origins, though homecare settings are expanding subcutaneous G-CSF self-administration.
The FDA, EMA, and WHO guideline frameworks collectively shape antimicrobial stewardship requirements and G-CSF biosimilar approval pathways across major prescribing markets. FDA-mandated antibacterial susceptibility reporting standards restrict empiric antibiotic selection, while EMA biosimilar comparability protocols accelerate filgrastim alternative entry. Stakeholders must monitor evolving breakpoint revisions and biosimilar interchangeability designations to anticipate shifts in formulary positioning and reimbursement dynamics.
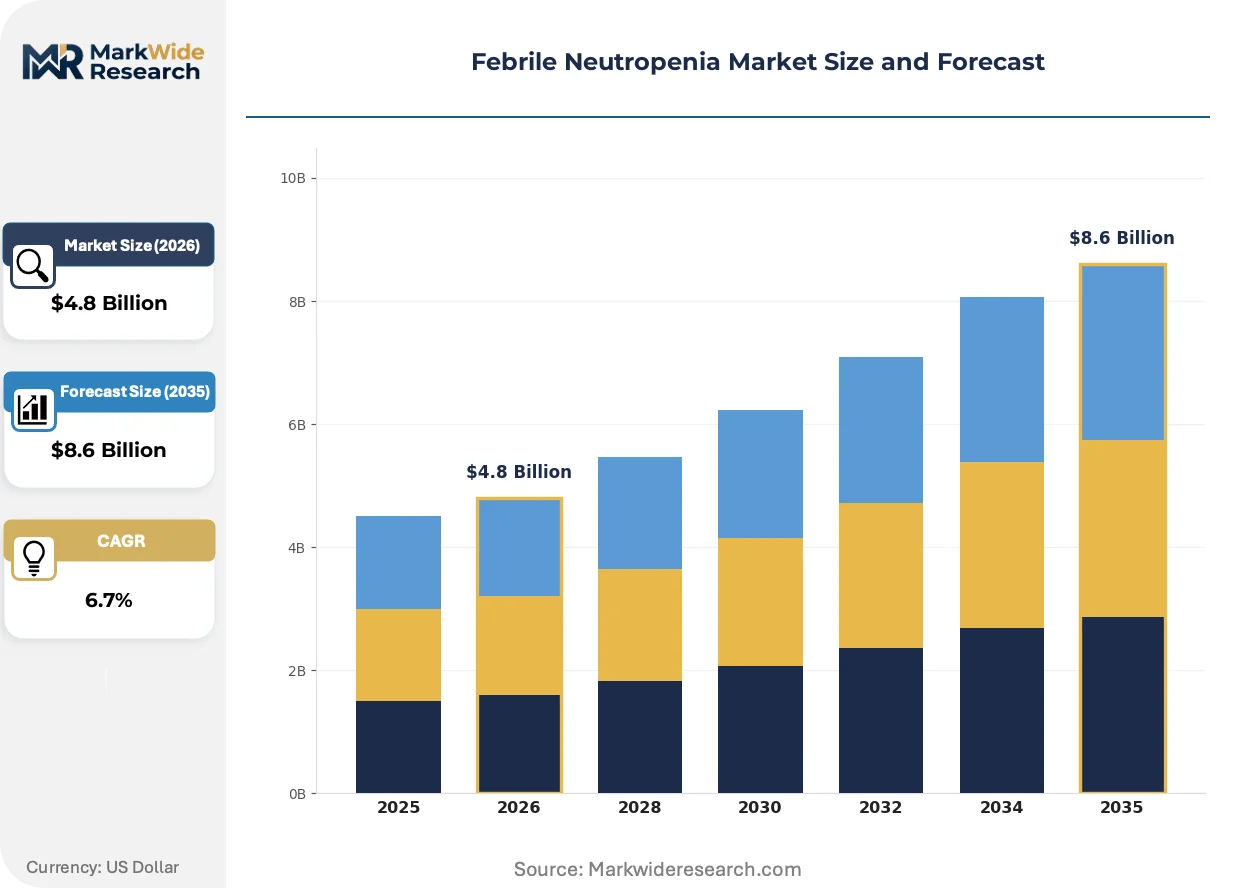
Market Dynamics
The FDA's updated antimicrobial susceptibility testing requirements are compressing empiric antibiotic selection windows, forcing oncology departments to revalidate protocols while biosimilar filgrastim entrants erode prophylaxis pricing power.
Growth Catalysts
- Rising chemotherapy intensity protocols:Aggressive dose-dense regimens in breast and lung oncology are expanding the addressable patient pool for G-CSF prophylaxis.
- EMA biosimilar comparability pathways:Accelerated filgrastim alternative approvals are broadening institutional formulary access across European tertiary hospitals.
- Homecare subcutaneous administration:Self-injection training programs are shifting rescue therapy from infusion centers to outpatient settings.
Market Restraints
- API supply concentration:Penicillin and cephalosporin active pharmaceutical ingredients cluster in Chinese manufacturing zones, exposing formularies to geopolitical disruption.
- Breakpoint revision lag:CLSI and EUCAST discordance on carbapenem susceptibility thresholds creates prescribing uncertainty for multidrug-resistant gram-negative coverage.
- Reimbursement compression:Medicare's hospital outpatient prospective payment system bundles G-CSF costs into episode-based oncology payments.
Strategic Opportunities
- India's expanding oncology infrastructure:CDSCO's streamlined biosimilar approval framework supports pegfilgrastim manufacturing partnerships for domestic and export markets.
- Antimicrobial stewardship integration:WHO's AWaRe classification mandate creates demand for narrow-spectrum empiric alternatives in febrile neutropenia protocols.
- Digital therapeutic adherence tools:Smartphone-based temperature monitoring and symptom reporting are reducing delayed presentation rates in rural patient populations.
Industry Challenges
- Specialized infectious disease pharmacist scarcity:Tertiary hospitals struggle to staff antimicrobial stewardship teams capable of real-time empiric therapy optimization.
- Cold chain integrity for biologics:Pegfilgrastim's temperature excursion sensitivity complicates homecare distribution logistics and waste accounting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Febrile Neutropenia Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granulocyte Colony-Stimulating Factor, Antibiotics, Antivirals, Corticosteroids End User: Hospitals, Specialty Clinics, Homecare, Research Institutions Administration Route: Intravenous, Subcutaneous, Oral, Intramuscular Therapy Area: Cancer, Autoimmune Disorders, Infectious Diseases, Others |
| Companies Covered | AstraZeneca, Teva Pharmaceutical Industries Ltd., Amgen Inc., Roche, Sanofi, Pfizer Inc., Bristol Myers Squibb, Fresenius Kabi, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Febrile Neutropenia Market Emerging Trajectories
Clinical practice patterns are bifurcating between risk-stratified prophylaxis deployment and precision-guided empiric therapy selection, with technology and regulatory frameworks racing to compress decision timelines.
Long-acting G-CSF formulations are migrating from hospital-based infusion to patient-administered subcutaneous delivery. Oncology practices in the United States are adopting on-body injector devices at accelerating rates. This shift is compressing reimbursement differentials between inpatient and outpatient neutropenia management.
REACH's extended authorization requirements for antimicrobial environmental discharge are pressuring hospital pharmacy departments to validate antibiotic deactivation protocols. German oncology centers now audit empiric therapy waste streams as part of ESG compliance reporting. The EMA's green pharmaceuticals initiative is accelerating market access for manufacturers with verified sustainable manufacturing credentials.
Hospital procurement committees are consolidating antibiotic purchasing through sole-source agreements with integrated delivery networks. Group purchasing organizations are displacing individual hospital formulary autonomy in febrile neutropenia drug selection. This concentration is most visible in United States metropolitan markets where IDN consolidation has exceeded sixty percent penetration.
Febrile Neutropenia Market Segmentation
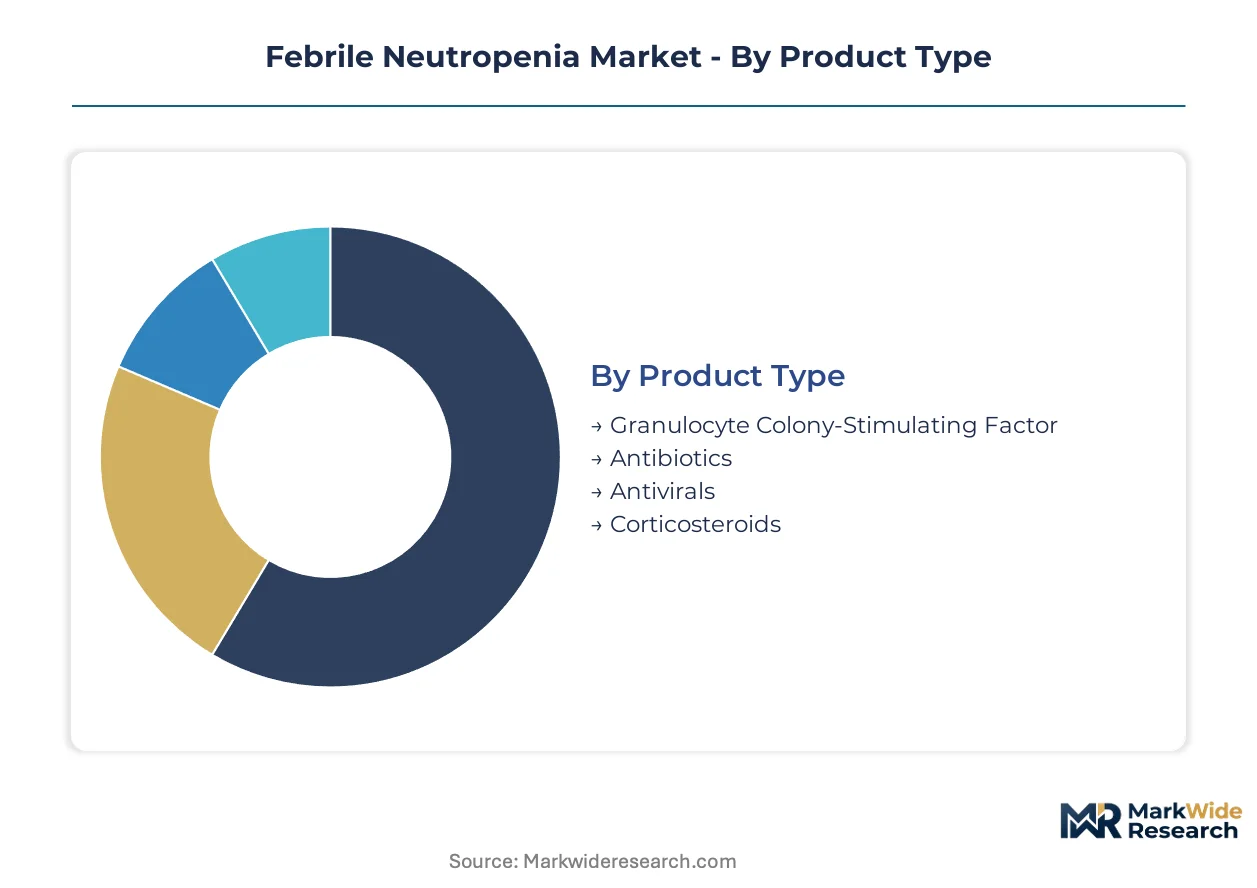
Segmentation in febrile neutropenia reveals divergent clinical workflows across prophylaxis, rescue therapy, and supportive care. Product type and administration route decisions determine reimbursement pathways and site-of-care economics for oncology practices.
Product Type:
Mature biologics dominate revenue concentration while generic small molecules compete on institutional procurement contracts.
- Granulocyte Colony-Stimulating Factor:Recombinant glycoproteins stimulate neutrophil proliferation and maturation through G-CSF receptor activation. Pegylated long-acting formulations concentrate demand in United States outpatient oncology as dose-dense chemotherapy protocols expand. Biosimilar filgrastim entrants are compressing prophylaxis pricing in European hospital formularies.
- Antibiotics:Empiric broad-spectrum agents targeting gram-positive and gram-negative pathogens remain the cornerstone of inpatient febrile neutropenia management. Intravenous cephalosporin and carbapenem utilization concentrates in tertiary hospital oncology wards where multidrug-resistant surveillance is mandatory.
- Antivirals:Acyclovir and related agents address herpes simplex and varicella-zoster reactivation in profoundly immunosuppressed patients.
- Corticosteroids:Adjunctive anti-inflammatory therapy for select autoimmune-related neutropenia presentations.
Granulocyte Colony-Stimulating Factor handles the majority of throughput; Antibiotics is the fastest mover on share as resistance surveillance intensifies.
End User:
Site-of-care migration from inpatient rescue to outpatient prophylaxis is redistributing volume across institutional and ambulatory settings.
- Hospitals:Tertiary medical centers with embedded oncology departments manage high-acuity febrile neutropenia episodes requiring intravenous antibiotic infusion and intensive monitoring. These institutions anchor empiric therapy protocol development and antimicrobial stewardship program implementation.
- Specialty Clinics:Dedicated oncology infusion centers administer G-CSF prophylaxis and monitor post-chemotherapy neutrophil recovery. United States community oncology practices are consolidating into regional networks to negotiate G-CSF purchasing contracts.
- Homecare:Subcutaneous self-injection training programs enable patient-administered pegfilgrastim outside institutional settings.
- Research Institutions:Academic medical centers conduct investigator-initiated trials on novel prophylaxis combinations.
Hospitals retain the dominant share of acute rescue episodes; Homecare is expanding most quickly as on-body injector devices penetrate United States markets.
Administration Route:
Delivery method selection reflects the urgency of neutropenia onset and the pharmacokinetic requirements of specific therapeutic classes.
- Intravenous:Immediate bioavailability for empiric antibiotic initiation in hospitalized patients with hemodynamic instability. This route dominates carbapenem and vancomycin administration in febrile neutropenia protocols.
- Subcutaneous:Sustained G-CSF absorption supporting once-per-cycle prophylaxis with pegfilgrastim. Home nursing services and patient training programs are expanding subcutaneous delivery outside infusion centers.
- Oral:Fluoroquinolone prophylaxis in low-risk outpatient populations with reliable gastrointestinal absorption.
- Intramuscular:Limited utilization for specific antibiotic formulations in settings without intravenous access.
Intravenous commands the largest volume for rescue therapy; Subcutaneous is climbing the fastest as prophylaxis shifts to outpatient administration.
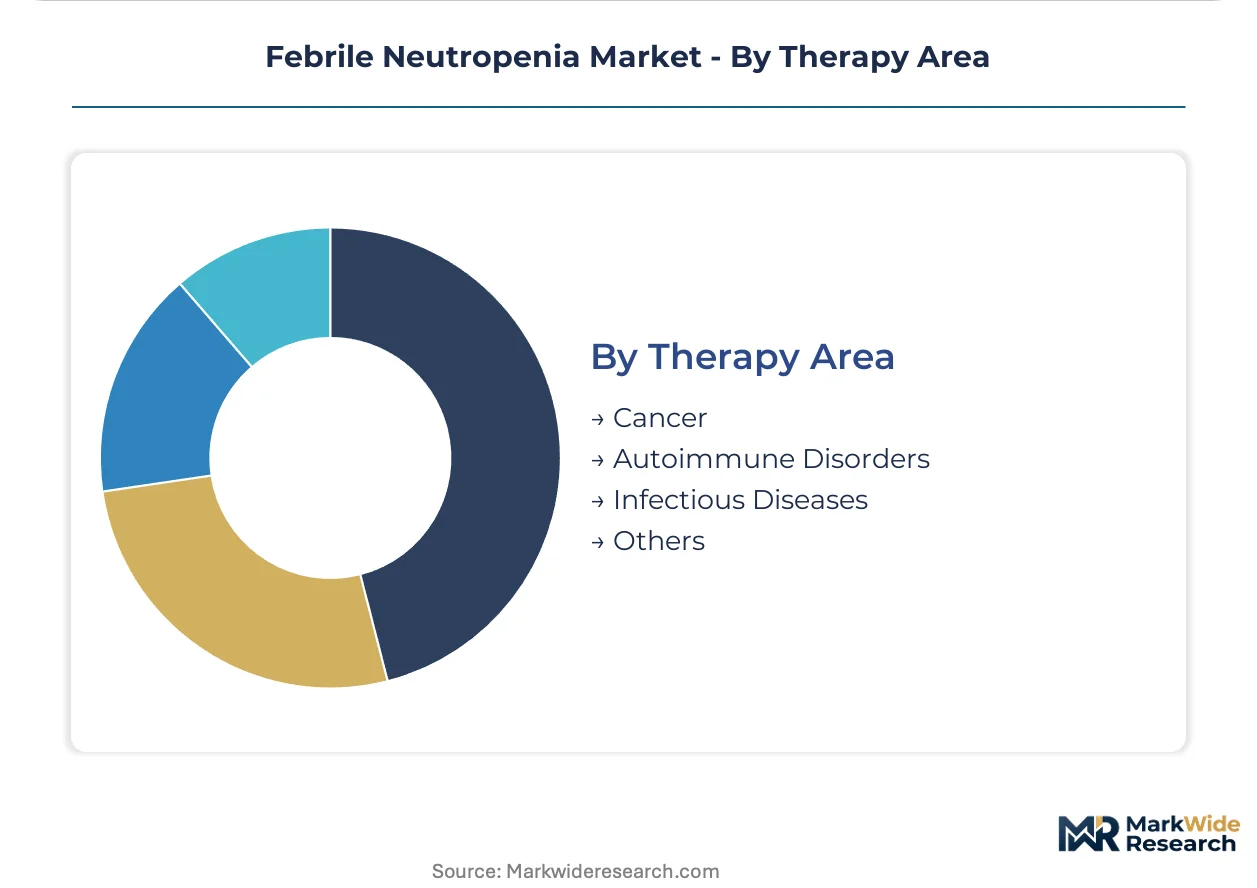
Therapy Area:
Disease-specific neutropenia etiologies generate distinct utilization patterns across prophylaxis and treatment indications.
- Cancer:Chemotherapy-induced myelosuppression generates the preponderance of febrile neutropenia cases requiring G-CSF support. Dose-dense regimens in breast, lung, and hematologic malignancies drive prophylaxis penetration rates.
- Autoimmune Disorders:Felty syndrome and lupus-related neutropenia represent niche indications for immunomodulatory therapy.
- Infectious Diseases:HIV-associated neutropenia and severe sepsis with bone marrow suppression require differentiated management approaches.
- Others:Congenital neutropenia and drug-induced agranulocytosis represent orphan indications with specialized treatment protocols.
Cancer absorbs the dominant share of G-CSF and antibiotic utilization; Autoimmune Disorders is gaining share fastest as biologic therapy expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across prescribing markets: United States buyers absorb premium biologic pricing with limited resistance, while European hospital formularies and Indian institutional purchasers enforce aggressive cost-containment on G-CSF and antibiotic procurement.
United States
Oncology practices in the United States deploy dose-dense chemotherapy protocols at scale, expanding the prophylactic G-CSF patient pool. FDA-mandated antimicrobial susceptibility testing revisions compress empiric antibiotic selection windows, forcing protocol revalidation. The Boston-Cambridge biotech corridor anchors pegfilgrastim manufacturing and biosimilar development activity.
Germany
German tertiary hospitals manage high-acuity febrile neutropenia episodes through embedded hematology-oncology departments with intensive monitoring capacity. EMA biosimilar comparability protocols accelerate filgrastim alternative approvals across hospital formularies. The Rhine-Main cluster around Frankfurt sustains concentrated antibiotic manufacturing and distribution infrastructure for Central European markets.
India
India's expanding oncology infrastructure generates rising case volumes for chemotherapy-induced neutropenia management in tertiary centers. CDSCO's streamlined biosimilar approval framework supports domestic pegfilgrastim manufacturing partnerships for export markets. The Mumbai-Pune pharmaceutical belt concentrates injectable antibiotic production and G-CSF formulation capacity.
Japan
Japanese oncology departments emphasize risk-stratified prophylaxis deployment with systematic neutrophil monitoring protocols. PMDA guidelines shape G-CSF biosimilar interchangeability standards and antimicrobial stewardship requirements. The Kanto region around Tokyo anchors specialized cancer center networks with integrated febrile neutropenia management pathways.
United Kingdom
NHS England's Cancer Drugs Fund influences G-CSF procurement and reimbursement thresholds across regional oncology networks. NICE technology appraisals constrain premium biologic adoption in favor of biosimilar alternatives where available. The London-Oxford-Cambridge golden triangle concentrates academic medical center research on novel prophylaxis combinations.
Febrile Neutropenia Market Vendor Landscape
Capability concentration sits with biologic innovators holding long-acting formulation expertise; scale advantage sits with generic injectable manufacturers and broad-spectrum antibiotic portfolios. The market structures around three tiers: originator biologics with manufacturing scale, biosimilar entrants exploiting regulatory pathways, and institutional generic suppliers competing on procurement contracts. Dominant competitive moves include biosimilar portfolio expansion through regulatory submissions and vertical integration into active pharmaceutical ingredient sourcing.
Within the originator biologic tier, Amgen Inc. and Roche occupy positions anchored by pegylated G-CSF formulation leadership and oncology franchise depth. Among diversified pharmaceutical conglomerates, Pfizer Inc. exemplifies the broad-spectrum antibiotic portfolio archetype competing across empiric therapy protocols. Fresenius Kabi represents the institutional generic supply chain archetype, sustaining price-accessibility for high-volume hospital purchasers through manufacturing scale.
| Leading Market Players |
|---|
| AstraZeneca |
| Teva Pharmaceutical Industries Ltd. |
| Amgen Inc. |
| Roche |
| Sanofi |
| Pfizer Inc. |
| Bristol Myers Squibb |
| Fresenius Kabi |
| Novartis AG |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam maritime corridor carries pegfilgrastim and carbapenem shipments whose freight cost volatility feeds directly into European hospital formulary pricing negotiations and Amgen's regional distributor margin structures.
Pricing Analysis
After-sales service contracts for on-body injector training and homecare nursing support capture disproportionate lifetime value relative to the drug itself. Three-tier pricing structure across premium originator, authorized biosimilar, and institutional generic levels segments buyers by risk tolerance and formulary autonomy. Cost compression in the biosimilar tier is intensifying because EMA interchangeability designations accelerate substitution protocols. Community oncology practices in United States metropolitan markets exhibit the highest price sensitivity, while academic medical centers with dedicated stewardship programs absorb premium pricing for protocol continuity.
Supply Chain Analysis
Contract manufacturing concentration for sterile injectables rests with Lonza, Catalent, and Samsung Biologics facilities across Switzerland, United States, and South Korea. Active pharmaceutical ingredients for cephalosporins and penicillins draw from Chinese and Indian chemical synthesis clusters, while pegfilgrastim biologics production centers on Massachusetts and Puerto Rico. Single-source vulnerability in temperature-controlled distribution creates exposure for homecare delivery networks. Distribution runs through integrated delivery network procurement committees and group purchasing organizations that consolidate hospital antibiotic purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks the chemotherapy treatment cycle, with G-CSF demand recovering in lockstep with oncology patient volumes returning to dose-dense protocols.
For Market Incumbents: Entrench formulary positioning through backward integration into active pharmaceutical ingredient sourcing for carbapenems and cephalosporins, insulating against Chinese supply disruption. Expand pegfilgrastim manufacturing capacity in Puerto Rico to capture Medicare outpatient reimbursement differentials. Biosimilar filgrastim entrants from Fresenius Kabi and Sandoz threaten originator pricing power in European hospital tenders. For New Entrants and Emerging Players: India's CDSCO-streamlined biosimilar approval pathway represents the most penetrable entry point for pegfilgrastim manufacturing partnerships targeting export markets. Homecare subcutaneous administration training programs in United States rural oncology networks offer a second white-space target with limited incumbent penetration. A go-to-market angle anchored on cold-chain logistics partnerships with specialty distributors bypasses hospital procurement committee gatekeeping. For Investors and Strategic Acquirers: FDA's updated antimicrobial susceptibility testing requirements reshape the acquisition landscape by elevating infectious disease pharmacist staffing and real-time protocol optimization capabilities as differentiated assets. Long-term viability centers on platforms integrating G-CSF prophylaxis with digital therapeutic adherence monitoring. The signal to watch is breakpoint revision announcements from CLSI and EUCAST that trigger empiric therapy protocol overhauls and formulary revalidation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Biosimilar Portfolio Expansion | EMA comparability protocols accelerate filgrastim alternative entry across European hospital formularies. |
| Antimicrobial Stewardship Integration | WHO AWaRe classification mandates narrow-spectrum empiric alternatives in febrile neutropenia protocols. |
| Homecare Distribution Partnership | On-body injector device penetration shifts reimbursement from inpatient to outpatient settings. |
| Active Pharmaceutical Ingredient Sourcing | Chinese API concentration exposes formularies to geopolitical disruption and supply interruption. |
| Digital Therapeutic Adherence Platform | Smartphone-based temperature monitoring reduces delayed presentation rates in rural patient populations. |
Methodological Framework
Desk research of FDA filings, EMA submission documents, ClinicalTrials.gov registries, and hospital formulary databases preceded structured interviews with oncology pharmacy directors, antimicrobial stewardship leads, GPO contract managers, and biosimilar regulatory affairs specialists. Primary fieldwork captured protocol validation timelines and procurement committee decision criteria across United States, German, and Indian tertiary hospitals. Secondary validation drew from CMS Medicare reimbursement data, NHS England Cancer Drugs Fund appraisals, and CDSCO approval records. Bottom-up patient-volume modeling and top-down pharmaceutical revenue triangulation anchored market size estimation.
Assumptions held fixed include EMA biosimilar interchangeability standards, FDA breakpoint revision cadence, and Medicare outpatient prospective payment system bundling rules; variables tested include chemotherapy protocol intensity shifts and Chinese API export restriction scenarios. Segmentation dimensions spanned product type, administration route, therapy area, and regional regulatory cluster. CAGRs derived from log-linear trend fitting across modeled patient populations and pricing trajectories. Forecast inputs incorporated G-CSF prophylaxis penetration rates by cancer type and empiric antibiotic resistance surveillance data from tertiary hospital microbiology laboratories.
Macroeconomic conditions sit as an overlay; deviation in oncology patient visit volumes, biologics cold-chain logistics costs, or antimicrobial API trade flows would shift the trajectory. Forecasts reflect documented assumptions about regulatory approval timelines and reimbursement stability. Quarterly review of FDA breakpoint announcements, EMA biosimilar interchangeability designations, and Chinese pharmaceutical export license data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Global Immunohematology Market
Hematology
Polycythemia Vera Market
Hematology
Hypereosinophilic Syndrome Market
Hematology
Patient Blood Management Market
Hematology
Warm Autoimmune Hemolytic Anemia Market
Hematology
Single Blood Drop Analysis Market
Hematology
Hemocytometer Market
Hematology
Rare Hematology Market
Hematology
Radiation-Induced Myelosuppression Treatment Market
Hematology
Apheresis Market
Hematology
Global Sickle Cell Disease Treatment Market
Hematology
Immune Thrombocytopenia (ITP) Market
Hematology
Allogeneic Stem Cell Therapy Market
Hematology
AL Amyloidosis Therapeutics Market
Hematology
Bone Marrow Transplant Market
Hematology
Mantle Cell Lymphoma Treatment Market