
 Small Lymphocytic Lymphoma Market | 2026-2036
Small Lymphocytic Lymphoma Market Size, Share, and Industry Trends Forecast 2026-2036
Small Lymphocytic Lymphoma Market Analytics
ISO 14155 for clinical investigation of medicinal products is rotating toward adaptive trial designs, which is reshaping how hematology sponsors structure Phase II programs. Pharmacyclics leverages its BTK inhibitor franchise to sustain dominance in relapsed settings. AbbVie anchors its position through combination regimens with venetoclax, while Genentech competes via CD20-directed antibody platforms across academic medical centers.
Small lymphocytic lymphoma is a mature B-cell neoplasm characterized by proliferation of small, round lymphocytes in lymph nodes, bone marrow, and peripheral blood, with CD5 and CD23 positivity serving as diagnostic immunophenotypic markers. Its primary purpose in the healthcare system is to guide chronic disease management through intermittent therapy rather than curative intent, given the indolent natural history. Targeted therapy leads the treatment type hierarchy as BTK and BCL-2 inhibitors displace chemoimmunotherapy in frontline settings, while monoclonal antibodies within the drug class segment retain substantial margin pools through rituximab and obinutuzumab utilization. The oral administration route is capturing the fastest growth as fixed-duration venetoclax-based regimens shift care away from infusion centers.
FDA's accelerated approval program and the EMA's conditional marketing authorization framework both shape product entry timelines for hematologic therapies, with post-marketing confirmatory trials becoming a standard access condition. The IRA's Medicare price negotiation provisions are restructuring commercial expectations for small-molecule oncology drugs, compressing the premium pricing window. Stakeholders must monitor how biomarker-defined subpopulations reshape trial eligibility and reimbursement criteria.
Market Dynamics
FDA's accelerated approval pathway for hematologic malignancies is compressing development timelines, forcing sponsors to structure Phase II programs around adaptive designs while post-marketing confirmatory trials become standard access conditions.
Growth Catalysts
- Adaptive Trial Frameworks:ISO 14155 is rotating toward adaptive designs, enabling hematology sponsors to modify Phase II protocols mid-stream based on interim efficacy signals.
- Biomarker-Driven Eligibility:CD5 and CD23 positivity markers are refining patient stratification, expanding addressable populations for targeted B-cell therapies in tertiary cancer centers.
- Oral Administration Shift:Fixed-duration venetoclax-based regimens are pulling care away from infusion centers, capturing fastest-growing route preference among chronic disease management protocols.
Market Restraints
- IRA Price Compression:Medicare price negotiation provisions for small-molecule oncology drugs are restructuring commercial expectations, compressing premium pricing windows for oral targeted therapies.
- Confirmatory Trial Burden:Post-marketing requirements under accelerated approval create sustained R&D cost obligations without guaranteed full conversion, straining mid-cap sponsor balance sheets.
- Infusion Center Dependency:Monoclonal antibody platforms retain substantial utilization through rituximab and obinutuzumab, locking margin pools into high-fixed-cost delivery infrastructure.
Strategic Opportunities
- EMA Conditional Pathway:The conditional marketing authorization framework offers earlier European access for hematologic therapies, creating parallel revenue streams ahead of FDA full approval.
- Combination Regimen Expansion:Venetoclax pairing with BTK inhibitors in frontline settings opens white space beyond relapsed disease, displacing chemoimmunotherapy in earlier treatment lines.
- Academic Medical Center Concentration:Tertiary cancer centers anchor both clinical trial enrollment and commercial uptake, creating concentrated channel access for novel agents.
Industry Challenges
- Biomarker Assay Standardization:CD5 and CD23 testing protocols vary across pathology networks, creating enrollment friction and site qualification delays for biomarker-defined trials.
- Cross-Border Regulatory Divergence:Differences between FDA accelerated approval and EMA conditional authorization timelines force sponsors to maintain dual-track development organizations.
- Care Model Transition Costs:Shifting from intermittent infusion-based therapy to continuous oral administration requires restructuring pharmacy operations and patient monitoring infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Lymphocytic Lymphoma Market |
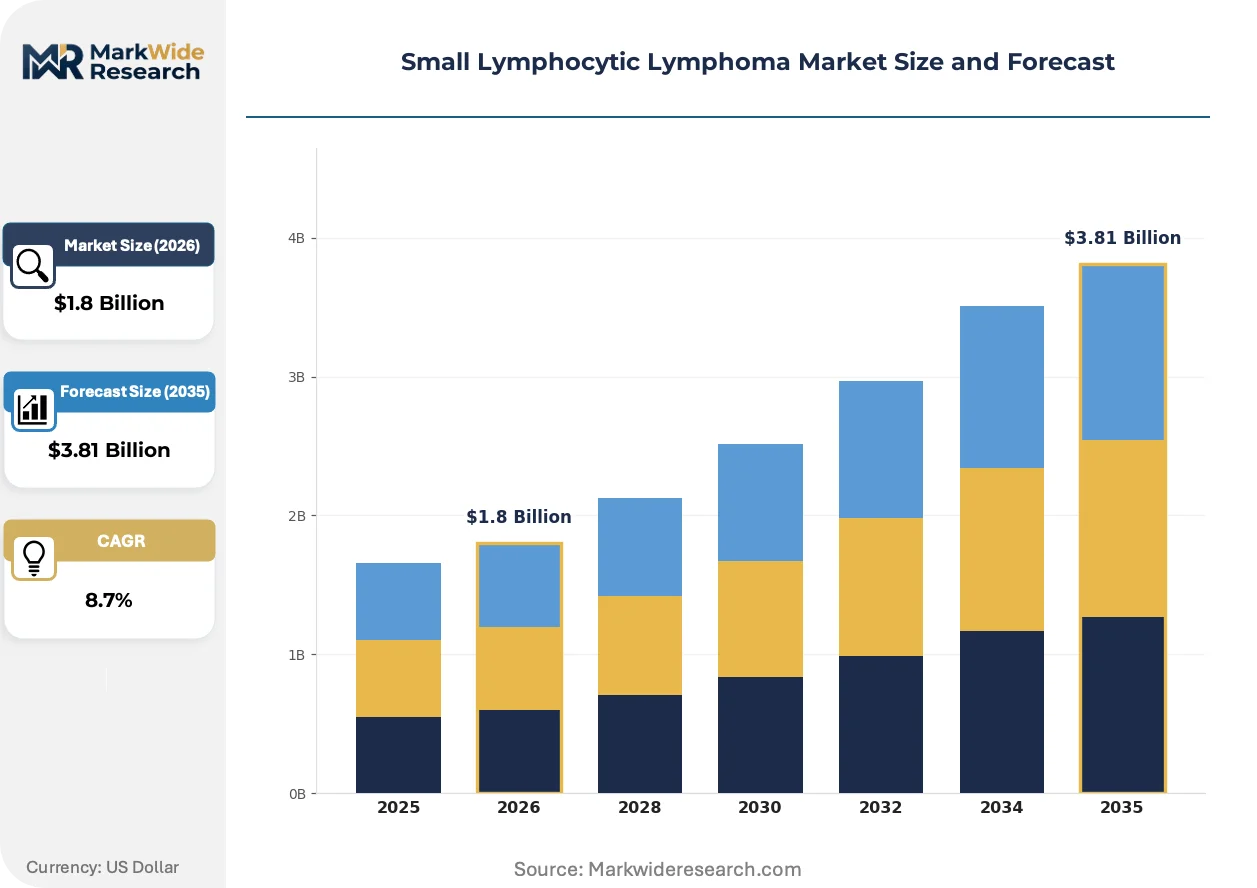
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Chemotherapy, Targeted Therapy, Immunotherapy, Radiation Therapy End User: Oncology Clinics, Hospitals, Research Institutions, Home Care Drug Class: Monoclonal Antibodies, Alkylating Agents, Proteasome Inhibitors, Steroids Administration Route: Intravenous, Subcutaneous, Oral, Topical |
| Companies Covered | Genentech, Pharmacyclics, Loxo Oncology, Bristol Myers Squibb, Pfizer, Eli Lilly and Company, Janssen, Novartis, AbbVie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Lymphocytic Lymphoma Market Evolving Landscape
Targeted B-cell therapy development is fragmenting across mechanistic classes, with BTK inhibitors, BCL-2 antagonists, and CD20-directed antibodies competing for positioning in both frontline and relapsed treatment sequences.
BTK inhibitor technology is bifurcating between covalent and non-covalent binding modalities, with academic medical centers adopting next-generation agents to address resistance mutations emerging in chronic lymphocytic leukemia overlap populations. This mechanistic split is enabling sponsors to segment relapsed settings by prior exposure history, compressing development timelines through narrower initial indications.
REACH registration requirements for chemical substances used in active pharmaceutical ingredient synthesis are tightening impurity profiling obligations, forcing contract manufacturers to upgrade analytical capabilities. European hematology sponsors face the steepest compliance burden, with CDMO networks in Germany and Switzerland investing in mass spectrometry infrastructure to maintain batch release timelines.
Patient assistance programs are unbundling from traditional hub service models, with specialty pharmacies absorbing prior authorization and co-pay support functions previously managed by manufacturer field teams. This channel consolidation is most visible in United States commercial coverage, where pharmacy benefit managers are demanding integrated service guarantees as a condition of formulary placement.
Small Lymphocytic Lymphoma Market Segmentation
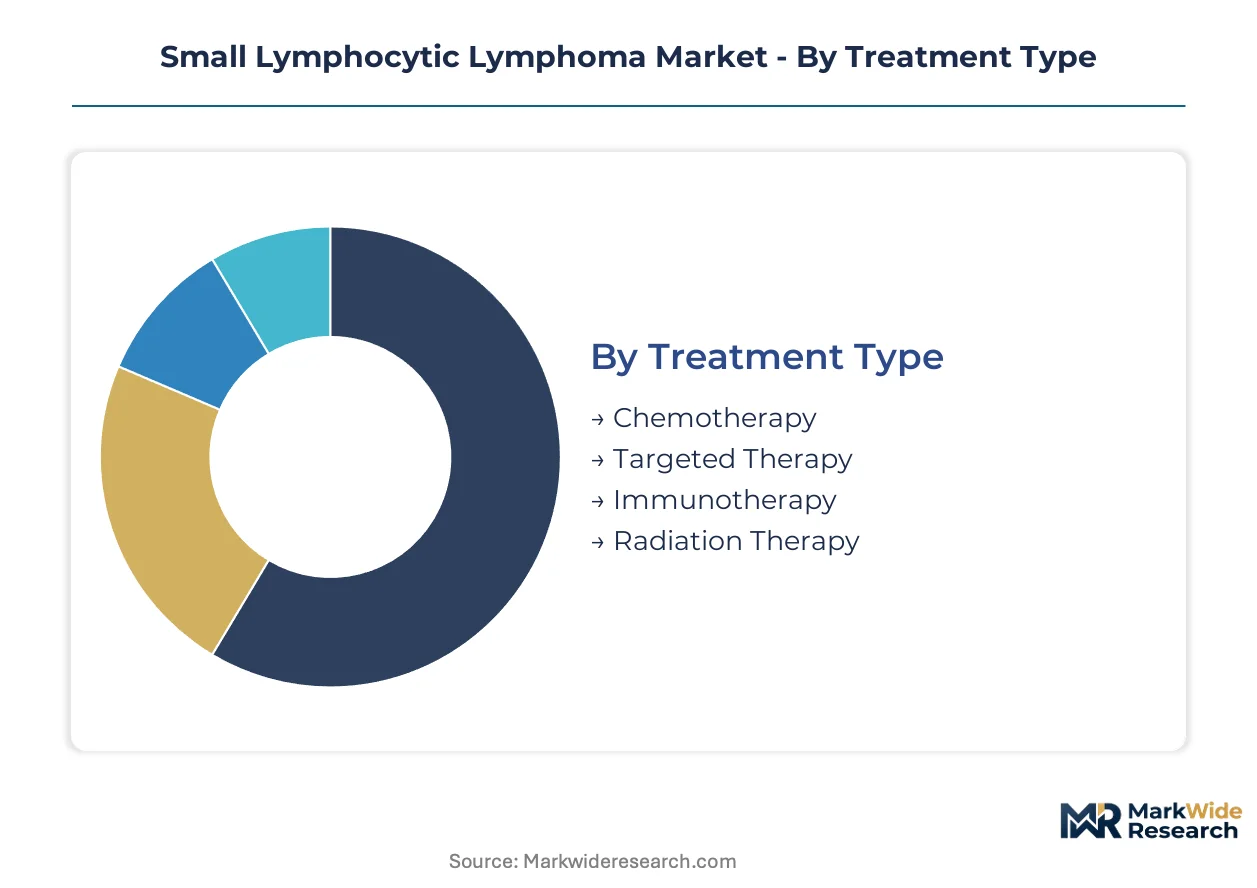
Segmentation in small lymphocytic lymphoma reveals how therapeutic modality preferences are fragmenting across delivery settings and mechanistic classes. Treatment type and administration route divisions capture the most consequential substitution dynamics as oral targeted agents displace infusion-dependent protocols.
Treatment Type:
Targeted therapy faces the most intense substitution pressure from next-generation BTK and BCL-2 inhibitors that compress development timelines through FDA accelerated approval pathways.
- Targeted Therapy:BTK inhibitors and BCL-2 antagonists like venetoclax dominate frontline settings through fixed-duration oral regimens. Tertiary cancer centers in the United States anchor demand concentration as academic medical centers drive protocol adoption away from chemoimmunotherapy.
- Immunotherapy:CD20-directed monoclonal antibodies including rituximab and obinutuzumab retain substantial utilization in combination regimens despite infusion center dependency. Demand concentrates in hospital-based oncology units where infrastructure investments lock in margin pools through high-fixed-cost delivery.
- Chemotherapy:Alkylating agent-based regimens are retreating to later-line salvage settings as B-cell pathway inhibitors capture earlier treatment sequences.
- Radiation Therapy:Localized nodal disease management employs radiation in select symptomatic presentations with limited systemic involvement.
Targeted therapy anchors the volume base while oral administration gains share at the steepest rate.
End User:
Cost tier stratification separates high-complexity academic centers from community oncology practices with divergent formulary access and trial enrollment capabilities.
- Oncology Clinics:Infusion capacity expansion for B-cell therapies concentrates in United States tertiary centers where prior authorization workflows and patient assistance programs integrate through specialty pharmacy networks.
- Hospitals:Inpatient admission requirements for rituximab and obinutuzumab administration sustain revenue capture through facility fees and nursing supervision.
- Research Institutions:Academic medical centers anchor Phase II adaptive trial enrollment under ISO 14155 protocols with biomarker-defined eligibility criteria.
- Home Care:Oral venetoclax regimens enable monitoring transitions away from infusion centers, requiring restructuring of pharmacy operations and remote patient tracking infrastructure.
Hospitals retain the highest revenue per patient while home care expands most quickly as fixed-duration oral protocols proliferate.
Drug Class:
Margin concentration varies sharply across mechanistic categories with monoclonal antibodies commanding premium pricing through biosimilar-protected originator products.
- Monoclonal Antibodies:CD20-directed platforms generate substantial margin pools through rituximab and obinutuzumab utilization despite biosimilar erosion in European markets. United States commercial coverage maintains originator preference through pharmacy benefit manager formulary controls.
- Steroids:Corticosteroid adjunctive therapy retains universal application across treatment sequences with minimal pricing power.
- Alkylating Agents:Bendamustine and cyclophosphamide retreat to combination backbones as targeted agents displace chemoimmunotherapy.
- Proteasome Inhibitors:Limited SLL-specific indications constrain utilization relative to multiple myeloma applications.
Monoclonal antibodies dominate current revenue while targeted small molecules climb the fastest as BTK and BCL-2 inhibitors capture frontline positioning.
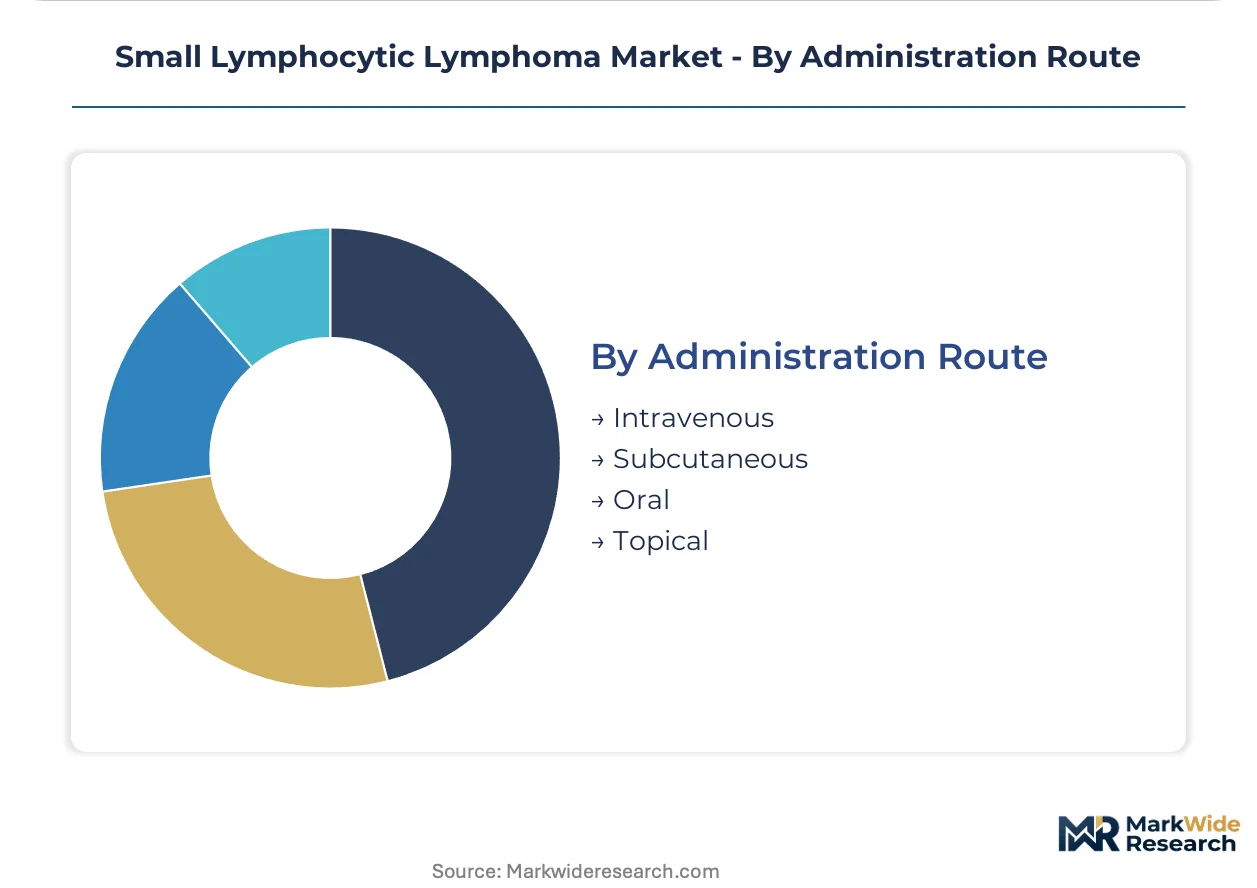
Administration Route:
Supply concentration in infusion center infrastructure creates friction against the shift toward continuous oral administration models.
- Oral:Venetoclax-based fixed-duration regimens pull care away from infusion centers, capturing fastest-growing route preference among chronic disease management protocols in United States commercial and Medicare populations.
- Intravenous:Rituximab and obinutuzumab utilization locks substantial volume into hospital and clinic infusion suites with high-fixed-cost infrastructure.
- Subcutaneous:Rituximab hyaluronidase formulations reduce chair time but retain facility-based administration requirements.
- Topical:Negligible SLL application given systemic disease biology.
Intravenous delivery anchors installed capacity while oral administration achieves the steepest expansion trajectory as IRA price negotiation reshapes commercial expectations for small-molecule oncology drugs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and tertiary cancer hospitals concentrate purchasing power for novel B-cell therapies, with reimbursement frameworks and regulatory pathways determining access velocity across major pharmaceutical markets.
United States
The IRA's Medicare price negotiation provisions restructure commercial expectations for oral small-molecule oncology drugs, compressing premium pricing windows. FDA's accelerated approval pathway enables earlier market entry for hematologic therapies, with post-marketing confirmatory trials becoming standard access conditions. The Greater Boston and New York Metro clusters anchor Phase II adaptive trial enrollment under ISO 14155 protocols.
Germany
REACH registration requirements for chemical substances tighten impurity profiling obligations for active pharmaceutical ingredient synthesis, forcing contract manufacturers to upgrade analytical capabilities. EMA's conditional marketing authorization framework offers parallel European access ahead of FDA full approval. CDMO networks in Baden-Württemberg invest in mass spectrometry infrastructure to maintain batch release timelines.
Switzerland
Swissmedic maintains stringent batch release standards for biologics while offering expedited pathways for breakthrough hematologic therapies. The Basel-Zurich corridor concentrates pharmaceutical manufacturing and clinical research operations. Precision oncology initiatives at University Hospital Zurich drive biomarker-defined trial enrollment for CD5 and CD23 positive populations.
United Kingdom
NICE technology appraisals determine National Health Service access for novel B-cell therapies, creating staged adoption patterns distinct from commercial insurance markets. The MHRA operates under retained EU legislation for medicinal products while developing independent accelerated assessment pathways. The London-Oxford-Cambridge triangle anchors academic medical center concentration for early-phase hematology trials.
Japan
PMDA's sakigake designation system provides priority review for innovative hematologic therapies, compressing regulatory timelines for BTK and BCL-2 inhibitor classes. METI's pharmaceutical industry policies support domestic manufacturing capacity for high-value oncology APIs. The Kanto region's university hospitals concentrate demand for fixed-duration venetoclax-based regimens in chronic disease management protocols.
Small Lymphocytic Lymphoma Market Competitive Landscape
Player mix skews toward large-cap integrated pharmaceutical companies with established oncology franchises and mid-cap biotech specialists focused on hematologic malignancies. The competitive structure tiers across originator biologics, small-molecule targeted therapies, and emerging combination regimens. Strategic archetypes include BTK inhibitor franchise holders, BCL-2 antagonist developers, and CD20-directed antibody platform operators. Dominant competitive moves center on combination regimen expansion and adaptive trial design capabilities.
Within the large-cap integrated tier, AbbVie and Genentech occupy positions anchored by combination portfolio breadth across academic medical center channels. Pharmacyclics exemplifies the targeted therapy specialist archetype with concentrated B-cell pathway expertise. These three entities represent the competitive core around which mid-cap developers including Loxo Oncology and emerging entrants position for frontline treatment sequence access.
| Leading Market Players |
|---|
| Genentech |
| Pharmacyclics |
| Loxo Oncology |
| Bristol Myers Squibb |
| Pfizer |
| Eli Lilly and Company |
| Janssen |
| Novartis |
| AbbVie |
| Others |
Value Network & Pricing Analysis
Ninety-day API inventory buffers at Swiss and German CDMOs concentrate pricing power among mass spectrometry-capable manufacturers, while IRA-induced cost compression in United States oral oncology markets forces sponsors to renegotiate active pharmaceutical ingredient contracts around volume-commitment discounts rather than spot-market premiums.
Pricing Analysis
Cost-plus contracts with quarterly API indexation dominate hematology drug manufacturing agreements, with purity-grade specifications and REACH compliance certification tiers driving price differentiation between European and Asian supply bases. Pricing pressure stems from Medicare price negotiation provisions compressing premium windows for small-molecule oncology drugs. Community oncology practices exhibit highest price sensitivity due to formulary restriction exposure, while academic medical centers maintain lowest sensitivity through trial-subsidy offsets and pharmacy benefit manager carve-outs.
Supply Chain Analysis
Strategic stockpiling of BTK inhibitor intermediates prevails over just-in-time preferences among sponsors facing REACH registration uncertainty, with inventory policies anchored in 180-day coverage targets for critical synthesis steps. API concentration centers on Switzerland, Germany, and India, with contract manufacturers drawing from brominated pyridine and pyrazole derivative feedstocks. Single-source vulnerability in mass spectrometry analytical capacity creates chokepoint exposure for batch release timelines. Distribution runs through specialty pharmacy networks integrating prior authorization and patient assistance functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adaptive trial design expertise and biomarker assay standardization capabilities are scarce relative to sponsor demand, creating asymmetric returns for organizations that anchor Phase II program execution.
For Market Incumbents: Fortify BTK inhibitor franchise positions through backward integration into non-covalent binding chemistry manufacturing, locking in API supply ahead of REACH compliance upgrades. Expand combination regimen patent estates with venetoclax pairing claims to defend against biosimilar CD20 antibody erosion in hospital infusion channels. For New Entrants and Emerging Players: Patient monitoring infrastructure for oral venetoclax home administration represents underserved white space where incumbent field teams have retrenched. Target United States commercial coverage segments with integrated specialty pharmacy service guarantees as the go-to-market wedge, bypassing academic medical center concentration. For Investors and Strategic Acquirers: Long-term, this sits as a chronic disease management infrastructure play because intermittent therapy protocols create recurring revenue visibility absent curative intent endpoints. Acquisition focus should center on mid-cap developers with adaptive trial design capabilities and EMA conditional authorization track records. The signal to watch is biomarker assay standardization progress across CD5 and CD23 testing networks, which would unlock enrollment velocity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Trial Design Implementation | ISO 14155 protocol modifications compress Phase II timelines for hematology sponsors at academic medical centers. |
| EMA Conditional Authorization Pathway | Parallel European market entry generates revenue streams ahead of FDA full approval for B-cell pathway inhibitors. |
| Specialty Pharmacy Network Integration | Prior authorization and co-pay support absorption through pharmacy benefit manager formulary placement requirements. |
| Biomarker Assay Standardization | CD5 and CD23 testing protocol harmonization reduces site qualification delays for biomarker-defined trial enrollment. |
| Fixed-Duration Oral Regimen Development | Venetoclax-based protocols shift care delivery from infusion centers to home administration models. |
Research Methodology
Desk research of FDA accelerated approval filings, EMA conditional authorization decisions, ClinicalTrials.gov protocol registrations, and formulary database entries preceded structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Primary fieldwork combined with secondary validation through SEC oncology segment disclosures and CMS Medicare Part B claims patterns. Bottom-up patient-flow modeling and top-down manufacturer revenue triangulation anchored market size estimation.
Variance decomposition across treatment line, administration route, drug class mechanistic category, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segmented patient population growth rates and therapy substitution dynamics modeled through the analysis window. Forecast inputs incorporated IRA price negotiation implementation timelines and REACH registration compliance cost trajectories for active pharmaceutical ingredient synthesis.
Forecasts assume regulatory continuity in FDA accelerated approval and EMA conditional authorization frameworks; material policy shifts would require re-modeling. Specific risks include biomarker assay standardization delays, cross-border regulatory divergence between United States and European trial requirements, and oral administration care model transition cost overruns. Revision becomes warranted when IRA Medicare price negotiation category assignments for small-molecule oncology drugs cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Chronic Immune Thrombocytopenia Treatment Market
Hematology
Erythropoietic Protoporphyria (EPP) Treatment Market
Hematology
Global Hematopoietic Stem Cell Transplantation Market
Hematology
Blood Plasma Market
Hematology
Febrile Neutropenia Market
Hematology
Hemoglobin Testing Systems Market
Hematology
Blood Screening Market
Hematology
Patient Blood Management Market
Hematology
Alpha Thalassemia Market
Hematology
Mantle Cell Lymphoma Treatment Market
Hematology
Peripheral T-Cell Lymphoma Treatment Market
Hematology
Transfusion Dependent Thalassaemia Management Market
Hematology
Burkitt Lymphoma Treatment Market
Hematology
Global Immunohematology Market
Hematology
Apheresis Market
Hematology
Venous Blood Collection Market