
 Global Hematology Market | 2026-2036
Global Hematology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hematology Market Foresight
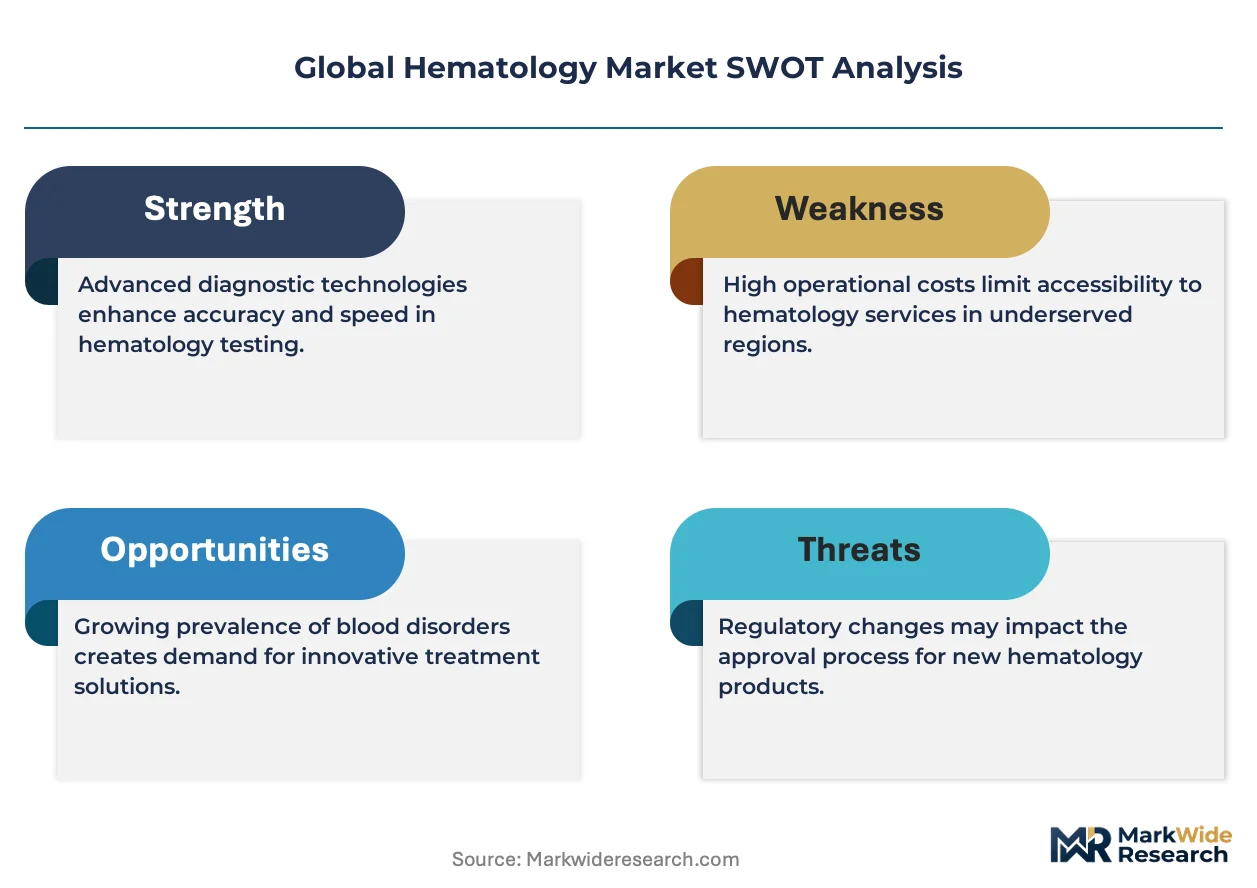
The EU In Vitro Diagnostic Regulation is recalibrating the cost-of-entry calculus for hematology device manufacturers seeking CE marking. Sysmex Corporation leverages its installed base of fluorescence flow cytometry platforms to sustain recurring reagent revenue across Japanese and European hospital networks. Danaher Corporation anchors its position through Beckman Coulter's vertically integrated supply chain for hematology consumables. Abbott Laboratories differentiates via point-of-care hemoglobin testing systems that extend its reach into resource-limited clinical settings.
Hematology encompasses the quantitative and morphological analysis of blood cellular components, employing technologies such as impedance-based counting with thresholds of 1-2 fL for platelet discrimination and fluorescence staining for reticulocyte enumeration. The primary commercial purpose is to generate complete blood count parameters that guide transfusion decisions, chemotherapy monitoring, and infection management. Hematology analyzers dominate capital expenditure budgets in diagnostic laboratories, while flow cytometry segments capture premium pricing for leukemia immunophenotyping applications. Coagulation analyzers occupy a mature but stable position in hospital laboratories, whereas laser-based counting technologies are displacing legacy impedance methods in high-throughput reference settings.
The FDA's quality system regulation and the EU MDR framework impose divergent clinical evidence requirements that shape product development timelines and market access strategies for hematology device manufacturers. The EPA oversees hazardous waste streams from reagent manufacturing, adding compliance layers to production economics. ISO 15189 accreditation standards for medical laboratories drive demand for analyzer calibration traceability and inter-laboratory quality assurance programs. Stakeholders must monitor how evolving reimbursement codes for molecular hematology diagnostics reshape capital allocation between traditional CBC platforms and integrated multi-omics workflows.
Market Dynamics
Automated hematology platforms are consolidating diagnostic workflows as hospital networks standardize on single-vendor ecosystems to reduce training overhead and reagent complexity. This vendor consolidation is compressing replacement cycles and reshaping competitive positioning around consumable lock-in rather than instrument differentiation.
Growth Catalysts
- IVDR Compliance Deadlines:The EU In Vitro Diagnostic Regulation mandates enhanced clinical evidence for CE-marked devices, accelerating hospital laboratory upgrades to analyzers with pre-validated quality systems.
- Oncology Patient Volume:Chemotherapy monitoring protocols in tertiary cancer centers generate recurring CBC demand that sustains high-throughput analyzer utilization rates.
- Laser-Based Platelet Counting:Optical counting technologies with fluorescent staining are replacing impedance methods in reference laboratories seeking improved precision at low platelet concentrations.
Market Restraints
- Reagent Supply Concentration:Proprietary reagent chemistries from single-source manufacturers create captive supply dependencies that limit laboratory negotiating leverage.
- Copper and Rare Earth Input Costs:Laser diode components and specialized optical filters expose production economics to commodity price volatility from Chinese processing facilities.
- ISO 15189 Accreditation Burden:Medical laboratories face recurring costs for inter-laboratory comparison programs and traceable calibrator procurement that constrain mid-tier facility expansion.
Strategic Opportunities
- Point-of-Care Hemoglobin Testing:Resource-limited clinical settings in India and Southeast Asia present deployment opportunities for cartridge-based systems that bypass centralized laboratory infrastructure.
- Multi-Omics Integration:Convergence of hematology analyzers with molecular diagnostic workflows enables single-platform leukemia immunophenotyping and minimal residual disease monitoring.
- US Hospital Consolidation:Integrated delivery networks are standardizing instrument fleets across acquired facilities, creating volume procurement contracts that favor vendors with comprehensive service footprints.
Industry Challenges
- Flow Cytometry Specialist Shortage:Leukemia immunophenotyping applications require trained cytometrists that academic medical centers struggle to recruit and retain against pharmaceutical industry compensation.
- Legacy LIS Integration Complexity:Hospital information systems with decades-old data architectures resist seamless connectivity with modern analyzers, forcing costly middleware deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hematology Market |
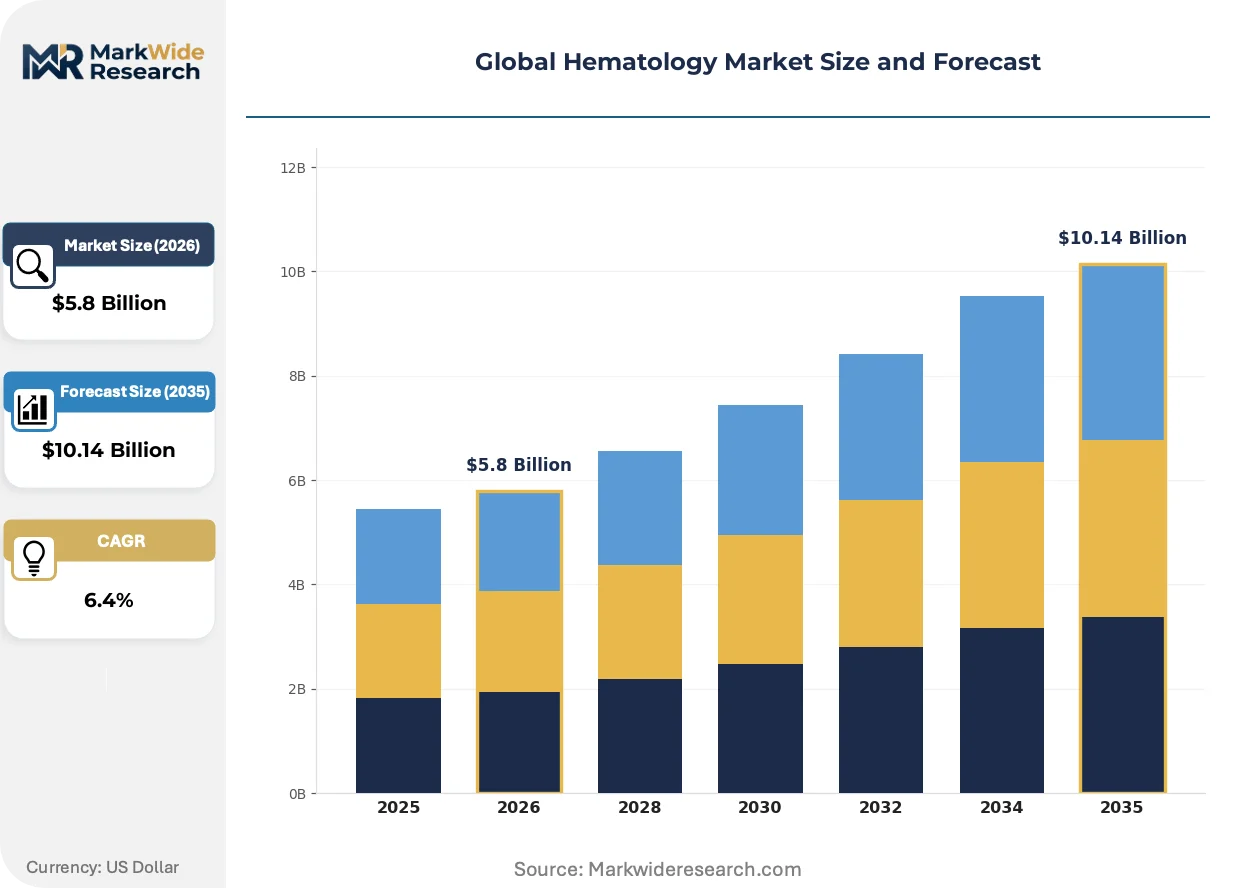
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hematology Analyzers, Coagulation Analyzers, Hemoglobin Analyzers, Cell Counters, Blood Gas Analyzers Application: Blood Disorder Diagnosis, Cancer Detection, Infectious Disease Identification, Monitoring Treatment, Nutritional Deficiency Analysis End User: Diagnostic Laboratories, Blood Banks, Academic Institutions, Pharmaceutical Companies, Research Centers Technology: Flow Cytometry, Spectrophotometry, Impedance Technology, Fluorescence, Laser-Based Counting |
| Companies Covered | Sysmex Corporation, Danaher Corporation, Siemens Healthineers, Abbott Laboratories, Beckman Coulter, F. Hoffmann-La Roche Ltd, Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Bio-Rad Laboratories, Nihon Kohden Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hematology Market Shifts & Advancements
Digital morphology and artificial intelligence classification are converging with traditional cell counting to reshape how laboratories handle smear review workloads. These capabilities are compressing turnaround times while reducing specialist pathologist involvement in routine differential verification.
Fluorescence flow cytometry is unifying reticulocyte enumeration, nucleated red blood cell detection, and immature platelet fraction analysis onto single platforms. High-volume hospital laboratories in Germany and Japan are adopting these systems to eliminate discrete testing modules. This technology consolidation is unifying capital expenditure decisions around vendors with integrated rather than modular architectures.
The EU MDR framework is extending clinical evidence requirements to hematology device renewals and line extensions, forcing manufacturers to maintain post-market surveillance databases that track analyzer performance across diverse patient populations. Small-to-mid device developers lacking regulatory affairs infrastructure are withdrawing legacy products rather than pursuing recertification. The MDR transition is concentrating market access among corporations with dedicated clinical operations teams.
After-sales service contracts are unbundling from instrument purchases as laboratory procurement teams separate capital and operating budgets. Third-party service organizations are capturing maintenance revenue from installed bases of impedance-based analyzers nearing end-of-life. This service fragmentation is most visible in the United States where group purchasing organizations negotiate multi-vendor maintenance agreements independent of original equipment procurement.
Global Hematology Market Segmentation
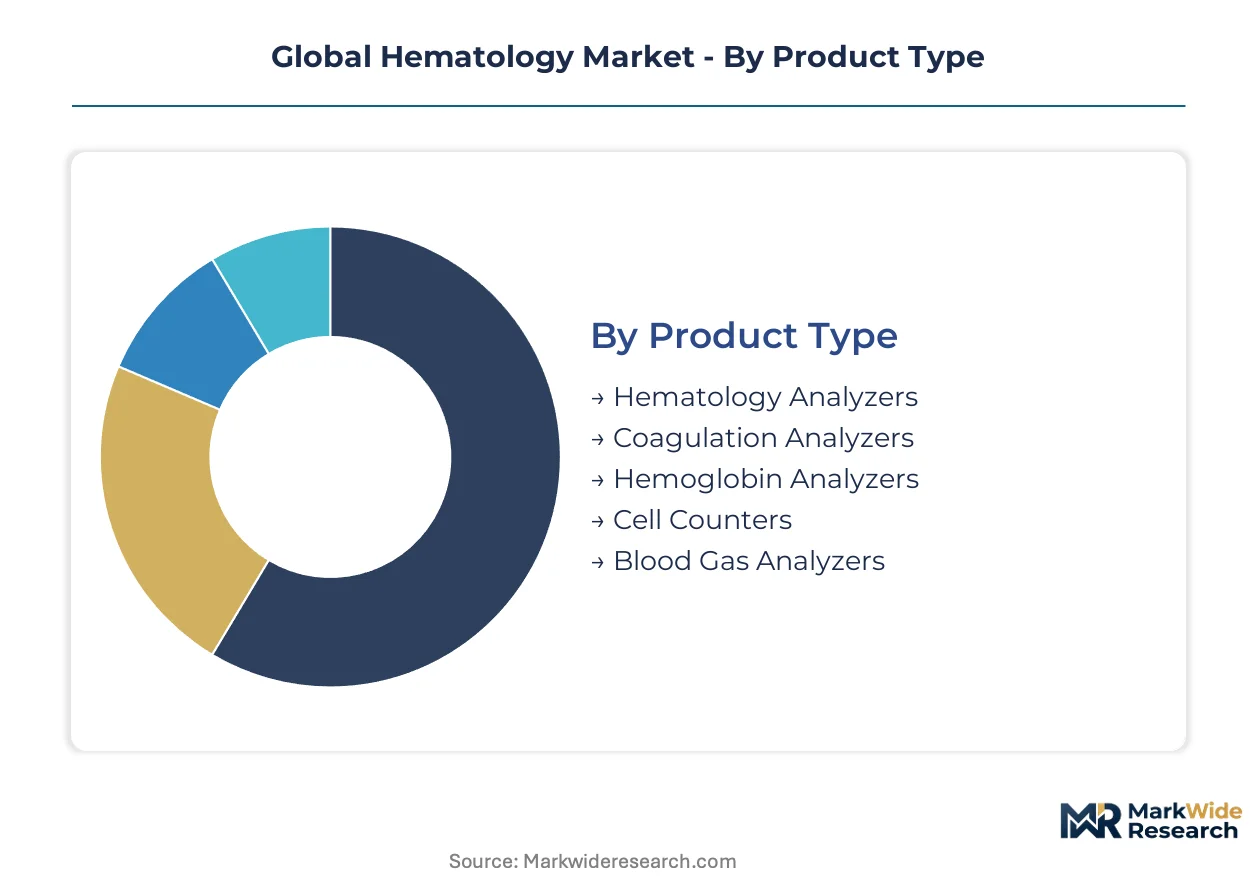
Hematology market segmentation reflects divergent procurement priorities across clinical and research settings. Laboratory buyers prioritize throughput and automation, while academic purchasers emphasize analytical flexibility and publication-grade precision.
Product Type:
Capital allocation patterns separate high-throughput hospital laboratories from resource-constrained point-of-care settings.
- Hematology Analyzers:Multi-parameter platforms generate complete blood count data through impedance-based cell discrimination and optical platelet enumeration. Demand concentrates in tertiary hospital networks across the United States and Germany where chemotherapy monitoring protocols sustain high utilization rates.
- Coagulation Analyzers:Prothrombin time and activated partial thromboplastin time systems employ mechanical clot detection or chromogenic substrates. Blood banks in Japan and Switzerland deploy these for transfusion screening, driven by surgical volume and anticoagulant therapy expansion.
- Hemoglobin Analyzers:Cartridge-based point-of-care devices enable hemoglobin quantification without centrifugation.
- Cell Counters:Manual and semi-automated systems serve research laboratories requiring flexible sample handling.
- Blood Gas Analyzers:Critical care settings deploy these for acid-base status and oxygenation assessment alongside hematologic parameters.
Volume sits with hematology analyzers; growth tilts toward hemoglobin analyzers.
Application:
Clinical workflow integration determines technology selection, with oncology and infectious disease protocols driving platform standardization.
- Blood Disorder Diagnosis:Anemia, thrombocytopenia, and leukocyte abnormality detection employs automated CBC with reflexive smear review. Diagnostic laboratories in France and South Korea prioritize systems with digital morphology capabilities to reduce pathologist review burden.
- Cancer Detection:Leukemia immunophenotyping and chemotherapy monitoring require fluorescence flow cytometry with multi-color antibody panels. Academic medical centers in the United States and Germany sustain demand for high-sensitivity minimal residual disease workflows.
- Infectious Disease Identification:Leukocyte differential shifts guide antibiotic stewardship decisions in emergency departments.
- Monitoring Treatment:Serial CBC tracking supports myelosuppressive therapy management.
- Nutritional Deficiency Analysis:Iron, folate, and B12 deficiency screening employs hemoglobin and red cell indices.
Oncology applications command premium pricing; infectious disease identification is expanding most quickly in emerging health systems.
End User:
Procurement scale and reagent commitment terms differentiate institutional buyers across the value chain.
- Diagnostic Laboratories:High-throughput reference laboratories and hospital-affiliated facilities operate automated platforms with continuous loading capabilities. Consolidated networks in the United States negotiate multi-year reagent contracts tied to analyzer placement.
- Blood Banks:Transfusion services require donor screening and component testing with regulatory traceability. European blood establishments under EU MDR compliance deadlines are upgrading quality management systems.
- Academic Institutions:Research-oriented hematology departments prioritize analytical flexibility over throughput.
- Pharmaceutical Companies:Clinical trial laboratories demand validated platforms with 21 CFR Part 11 compliance.
- Research Centers:Basic science laboratories employ specialized flow cytometry for mechanistic studies.
Diagnostic laboratories dominate installed base; research centers are gaining share fastest through multi-omics integration.
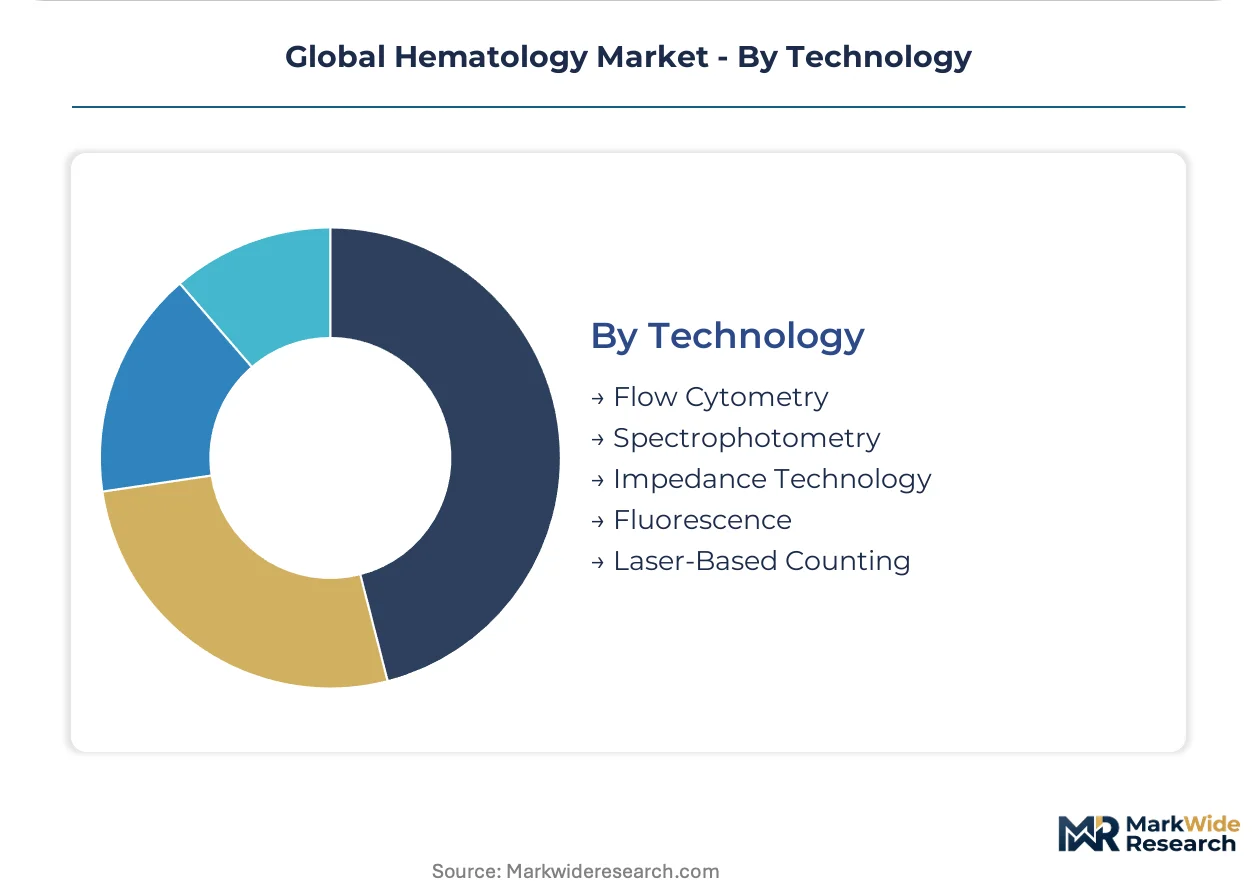
Technology:
Detection methodology determines precision, throughput, and reagent economics for target applications.
- Flow Cytometry:Fluorescence-activated cell sorting enables multi-parameter leukocyte immunophenotyping with single-cell resolution. Leukemia diagnostic laboratories in Japan and Germany adopt 8-10 color panels for minimal residual disease detection.
- Laser-Based Counting:Optical scatter and fluorescence detection improve platelet enumeration precision at low concentrations. Reference laboratories in Switzerland and the United States replace impedance methods for thrombocytopenia assessment.
- Spectrophotometry:Hemoglobin quantification employs cyanmethemoglobin or azide-methemoglobin conversion at specific wavelengths.
- Impedance Technology:Coulter principle cell counting remains cost-effective for routine CBC in mid-tier laboratories.
- Fluorescence:Reticulocyte and nucleated red blood cell detection uses RNA-specific dyes.
Impedance technology retains volume leadership; laser-based counting shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Singapore and Shenzhen concentrate hematology reagent manufacturing and regional distribution hubs. These zones attract multinationals seeking tariff-efficient supply chains into Asian hospital networks. Regulatory harmonization efforts are reshaping market access timelines across major economies.
United States
Integrated delivery networks in Texas and Florida drive analyzer fleet standardization across acquired hospital systems. FDA quality system regulations for in vitro diagnostics mandate enhanced design controls and post-market surveillance. The Research Triangle Park cluster in North Carolina hosts service operations supporting East Coast reference laboratories.
Germany
Tertiary cancer centers in Munich and Heidelberg sustain demand for high-throughput CBC platforms with fluorescence flow cytometry capabilities. EU MDR compliance deadlines force hospital laboratories to upgrade analyzers with pre-validated quality management systems. The Baden-Württemberg industrial corridor concentrates precision optics manufacturing for laser-based counting modules.
Japan
Aging demographics and universal health coverage sustain replacement cycles for automated hematology platforms in Tokyo and Osaka metropolitan hospitals. PMDA regulatory requirements align with international harmonization initiatives while maintaining distinct clinical evidence standards. The Kobe biomedical cluster anchors reagent production serving domestic and Southeast Asian export markets.
China
Tier-three hospital expansion in Chengdu and Wuhan creates procurement volume for mid-range hematology analyzers. NMPA medical device registration pathways are converging toward international standards while retaining domestic testing requirements. The Suzhou Industrial Park hosts joint ventures producing optical components for laser-based platelet enumeration systems.
Switzerland
Reference laboratories in Basel and Zurich adopt laser-based counting technologies for thrombocytopenia assessment precision. Swissmedic medical device oversight maintains alignment with EU MDR while preserving independent market authorization procedures. The Greater Geneva area concentrates hematology research institutions driving early adoption of digital morphology platforms.
Global Hematology Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across instrument and reagent segments. The market structure concentrates among five to seven entities controlling installed base and consumable supply chains. Three archetypes dominate: integrated life science conglomerates with diagnostic divisions, dedicated in vitro diagnostic manufacturers with fluorescence platform expertise, and emerging Asian equipment suppliers with cost-optimized impedance systems. Competitive moves center on multi-year reagent lock-in contracts and third-party service organization acquisitions.
Among diversified life science conglomerates, Danaher Corporation and Siemens Healthineers exemplify the integrated diagnostic platform model. Sysmex Corporation occupies a position as the fluorescence flow cytometry pure-play specialist with deep installed base penetration in Japanese and European hospital networks. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. represents the emerging Asian archetype with cost-competitive analyzer platforms targeting mid-tier laboratory expansion.
| Leading Market Players |
|---|
| Sysmex Corporation |
| Danaher Corporation |
| Siemens Healthineers |
| Abbott Laboratories |
| Beckman Coulter |
| F. Hoffmann-La Roche Ltd |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Bio-Rad Laboratories |
| Nihon Kohden Corporation |
| Others |
Supply & Pricing Matrix
Copper price volatility from Chinese processing facilities cascades through laser diode component costs into three-tier pricing structures across premium fluorescence platforms, standard impedance systems, and economy point-of-care devices. Laboratory procurement teams negotiate multi-year reagent contracts that bundle instrument placement with consumable commitments, compressing margins on hardware while locking in recurring revenue streams.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to emergency analyzer replacements in hospital networks facing IVDR compliance deadlines. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FDA-cleared and CE-marked systems commanding substantial premiums over non-regulated research-use-only alternatives. Cost compression in the economy tier is intensifying because emerging Asian manufacturers are flooding mid-tier laboratory markets with cost-optimized impedance platforms. Academic medical centers exhibit the lowest price sensitivity due to grant-funded procurement, while independent diagnostic laboratories in India and Southeast Asia demonstrate acute price consciousness.
Supply Chain Analysis
Regional distribution centers in Singapore and Shenzhen operate hub-and-spoke patterns serving hospital networks across Southeast Asia and Oceania. Manufacturing concentrates in Japan, Germany, and China, with precision optics production anchored in Baden-Württemberg and reagent chemistry synthesis centered on Kobe and Suzhou. Laser diodes, rare earth optical filters, and proprietary fluorescent dyes constitute critical input dependencies. Single-source vulnerability pervades specialized reagent chemistries from Sysmex and Beckman Coulter, creating captive supply chains that limit laboratory negotiating leverage. Distribution runs through group purchasing organizations in the United States and centralized hospital procurement consortia in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hematology market has become a vertical-integration race where control over reagent chemistry supply determines competitive durability. Incumbents and challengers alike are pursuing backward integration into fluorescent dye manufacturing and laser diode sourcing to defend margin structures.
For Market Incumbents: Anchor market position through captive reagent supply contracts that extend replacement cycles and elevate switching costs for hospital laboratory customers. Pursue ISO 15189 accreditation support services as a defensive moat against emerging Asian competitors lacking regulatory affairs infrastructure. The IVDR compliance burden threatens smaller European competitors, creating acquisition opportunities for consolidated players with dedicated clinical operations teams.
For New Entrants and Emerging Players: Launch via cartridge-based point-of-care hemoglobin testing systems targeting resource-limited clinical settings in India and Southeast Asia that bypass centralized laboratory infrastructure. Target mid-tier hospital expansion in Chengdu and Wuhan where NMPA registration pathways favor cost-competitive impedance platforms. Pursue white-label service contracts for third-party maintenance of end-of-life analyzers as a revenue bridge toward instrument placement.
For Investors and Strategic Acquirers: Distressed-cycle entries favor fluorescence flow cytometry pure-plays in Japan and Germany with deep installed base penetration but constrained R&D budgets. Long-term viability hinges on multi-omics integration capabilities spanning leukemia immunophenotyping and minimal residual disease monitoring. Watch for hospital consolidation announcements in Texas and Florida as inflection indicators for volume procurement contract opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Compliance Pathway Acceleration | Pre-validated quality systems from Beckman Coulter and Sysmex capture European hospital upgrade cycles ahead of regulatory deadlines. |
| Point-of-Care Hemoglobin Platform Launch | Abbott's cartridge-based systems extend reach into Indian primary health centers lacking centrifugation infrastructure. |
| Multi-Omics Workflow Integration | Fluorescence flow cytometry convergence with molecular diagnostics enables single-platform minimal residual disease monitoring. |
| Third-Party Service Organization Acquisition | Independent maintenance providers capture revenue from installed bases of impedance analyzers nearing end-of-life in the United States. |
| Reagent Chemistry Backward Integration | Danaher's vertical control over hematology consumables supply chains sustains margin structures against spot-market input volatility. |
Research Methodology
FDA 510(k) filings, EU MDR technical documentation, and hospital procurement databases formed the secondary backbone, supplemented by trade data from Japanese and German medical device registries. Primary interviews with hematology laboratory directors, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at fluorescence platform manufacturers validated demand assumptions and pricing dynamics. Bottom-up analyzer shipment estimates and top-down reagent revenue triangulation anchored market size calculations.
Historical trendline analysis of replacement cycles across United States integrated delivery networks, German tertiary cancer centers, and Japanese metropolitan hospitals informed penetration rate assumptions across the projection horizon. Segmentation modeling incorporated product type, application workflow, end-user procurement scale, and detection technology dimensions. CAGRs derived from regression analysis of capital expenditure patterns and consumable utilization rates, with chemotherapy monitoring protocol expansion and IVDR compliance deadlines as hematology-specific forecast inputs.
Regulatory timeline slippage, copper and rare earth commodity price spikes, and hospital consolidation pace are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions regarding replacement cycle compression and reagent lock-in contract prevalence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Aplastic Anemia Treatment Market
Hematology
Anemia Drugs Market
Hematology
Polycythemia Vera Treatment Market
Hematology
Graft vs Host Disease Market
Hematology
Peripheral T-Cell Lymphoma Treatment Market
Hematology
Graft Versus Host Disease (Gvhd) Treatment Market
Hematology
Non-Hodgkin Lymphoma Treatment Market
Hematology
Sickle-Cell Anemia Therapeutics Market
Hematology
Lymphopenia Therapeutics Market
Hematology
Venous Blood Collection Market
Hematology
Patient Blood Management Market
Hematology
Acute Myeloid Leukemia Treatment Market
Hematology
Blood Plasma Market
Hematology
Hematologic Malignancies Market
Hematology
Chemotherapy-Induced Myelosuppression Treatment Market
Hematology
Febrile Neutropenia Market