
 Erythropoietic Protoporphyria (EPP) Treatment Market | 2026-2036
Erythropoietic Protoporphyria (EPP) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Erythropoietic Protoporphyria (EPP) Treatment Market Foresight
European biopharma manufacturing capacity is shifting toward rare disease biologics and precision phototherapy platforms. Clinuvel Pharmaceuticals dominates the melanocortin receptor agonist segment with its approved EPP therapy and sustained regulatory exclusivity across major markets. Roche leverages its global diagnostics infrastructure to anchor porphyria screening programs that feed downstream treatment demand. Disc Medicine specializes in novel heme biosynthesis pathway modulators, positioning its pipeline for competitive differentiation in underserved patient populations.
Erythropoietic Protoporphyria treatment encompasses pharmacological and photoprotective interventions targeting the accumulation of protoporphyrin IX in erythrocytes, which causes severe cutaneous photosensitivity upon light exposure in the visible spectrum. The primary purpose is to prevent phototoxic reactions, manage hepatic complications, and improve quality of life for patients with this inherited disorder. Injectable delivery modes command premium pricing due to the biologic nature of leading therapies, while oral formulations represent the fastest-growing category as developers pursue patient convenience and expanded access. Phototherapy devices retain a mature installed base in hospital settings, though homecare applications are gaining traction with portable device innovations.
FDA orphan drug incentives and EMA's priority medicines scheme shape development economics by compressing regulatory timelines and extending market exclusivity for EPP therapies. The EU's MDR and FDA's Good Manufacturing Practice standards enforce stringent quality controls on phototherapy device manufacturing and biologic drug production. REACH compliance in Europe and EPA environmental assessments in the United States govern the chemical safety profiles of porphyrin-related compounds used in research applications. Stakeholders must monitor evolving reimbursement frameworks for rare disease therapies and the competitive entry of gene-silencing platforms that could reshape the therapeutic hierarchy.
Market Dynamics
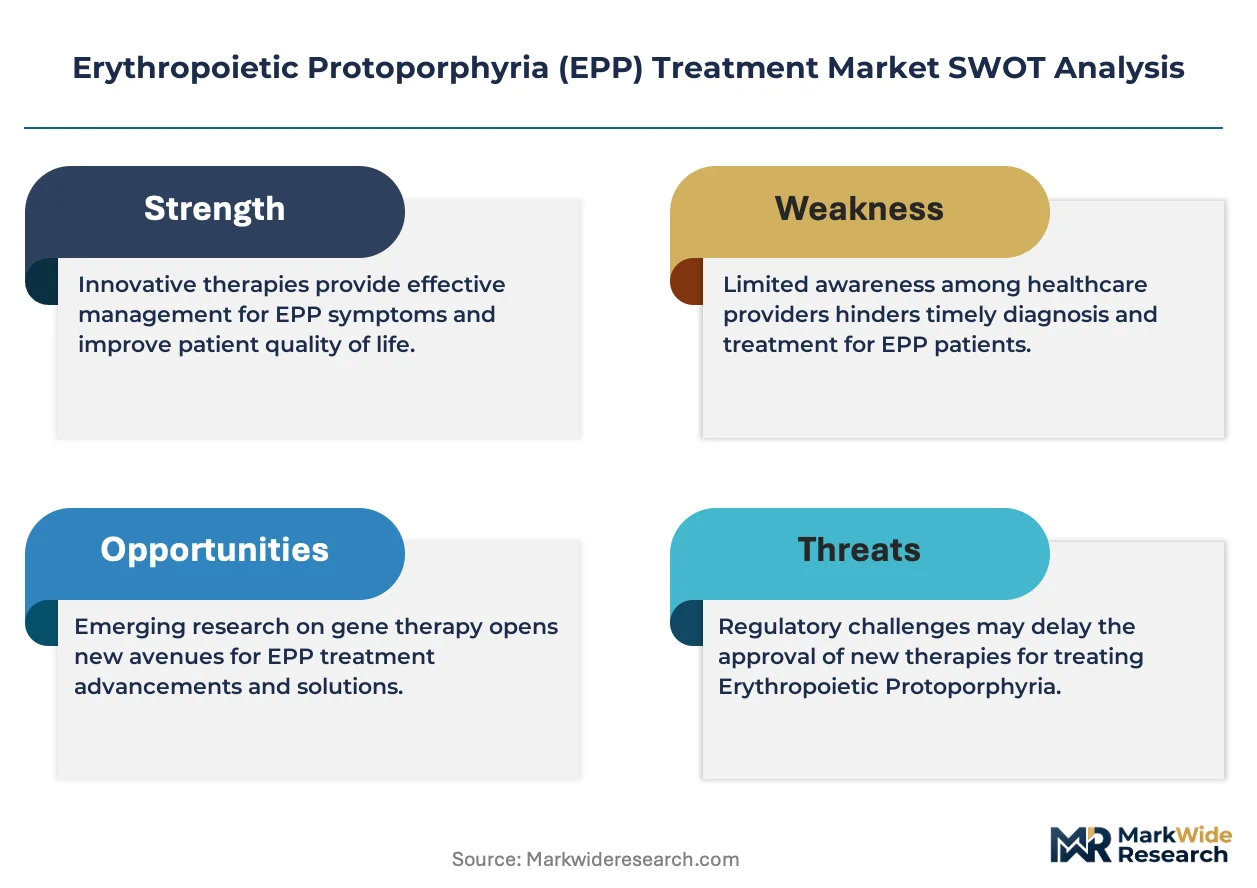
The Erythropoietic Protoporphyria treatment landscape is restructuring around FDA orphan drug exclusivity windows, which compress development timelines and concentrate commercialization rights among holders of melanocortin receptor agonist patents. This regulatory mechanism is accelerating portfolio prioritization decisions across biopharma pipelines.
Growth Catalysts
- EMA Priority Medicines Scheme:The European Medicines Agency's accelerated assessment pathway reduces regulatory review periods for rare disease therapies, incentivizing EPP drug development investment.
- Phototherapy device miniaturization:Portable visible-light filtering technologies are expanding homecare access beyond hospital-based dermatology departments.
- United States porphyria center density:Specialized treatment hubs in Boston, San Francisco, and Houston drive clinical trial recruitment and accelerate patient identification.
Market Restraints
- Biologic manufacturing concentration:Contract development and manufacturing organizations in Switzerland and Germany control critical capacity for peptide-based EPP therapies.
- Protoporphyrin IX assay cost volatility:Fluorometric testing reagents face supply instability due to porphyrin precursor sourcing constraints.
- Gene therapy substitution timeline:CRISPR-based heme pathway editing platforms threaten long-term demand for chronic pharmacological management.
Strategic Opportunities
- Pediatric formulation gap:Weight-based dosing requirements in patients under 12 years create unmet need for oral bioavailability improvements.
- Asia-Pacific diagnostic infrastructure:Japan's PMDA rare disease framework and South Korea's MFDS orphan drug incentives are expanding addressable patient pools.
- Telemedicine integration:Remote phototoxicity monitoring via wearable UV-Visible spectrum sensors is creating direct-to-patient channel possibilities.
Industry Challenges
- Biostatistics talent scarcity:Rare disease trial design requires specialized expertise in small-population efficacy endpoints that outpaces academic program output.
- Phototherapy device MDR certification:EU Medical Device Regulation technical documentation timelines extend commercialization schedules for LED-based platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Erythropoietic Protoporphyria (EPP) Treatment Market |
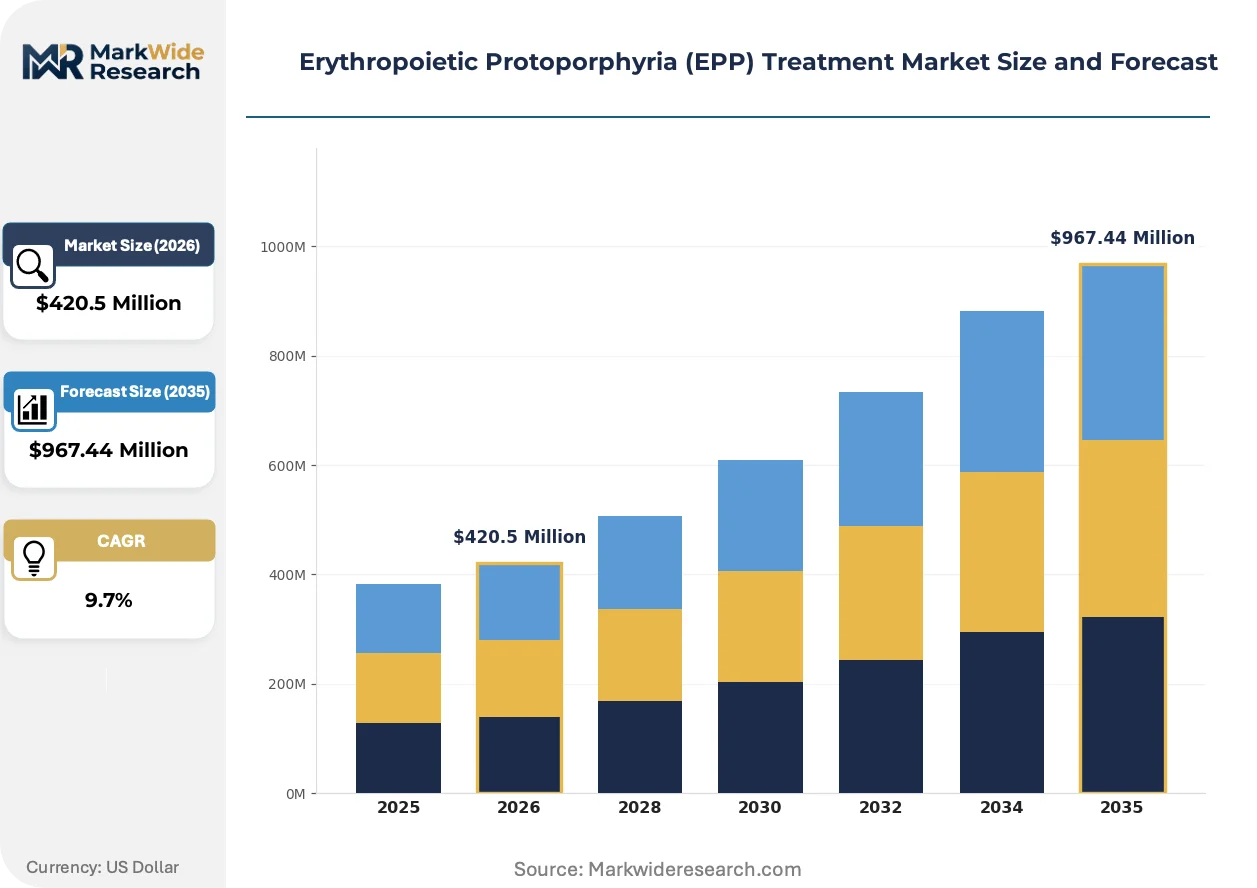
| Market Size in 2026 | $420.5 Million |
| Market Size in 2035 | $967.44 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beta-Carotene, Erythropoietin, Phototherapy Devices, Antioxidants Delivery Mode: Injectable, Oral, Topical, Transdermal End User: Hospitals, Clinics, Homecare, Ambulatory Care Centers Application: Symptomatic Treatment, Preventive Care, Clinical Trials, Research |
| Companies Covered | Clinuvel Pharmaceuticals, Disc Medicine, Roche, Alnylam Pharmaceuticals, Mitsubishi Tanabe Pharma, Pfizer, Johnson & Johnson, Tishcon Corp, L'Oréal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Erythropoietic Protoporphyria (EPP) Treatment Market Shifts & Advancements
Novel heme biosynthesis pathway modulators are converging with patient stratification biomarkers to enable precision dosing. This convergence is compressing the traditional one-size-fits-all therapeutic paradigm and forcing adaptation across clinical development programs.
Gene-silencing platforms targeting ALAS2 expression are converging with established melanocortin receptor agonist protocols in investigator-sponsored trials. Academic medical centers in the United States and Germany are piloting combination regimens that layer transcriptional control over photoprotective pharmacology. This technological convergence is enabling disease-modifying claims that extend beyond symptomatic management.
The FDA's orphan drug exclusivity framework is reshaping competitive positioning by awarding seven-year market protection to novel EPP therapies. This regulatory mechanism accelerates approval pathways but creates bottleneck effects when multiple sponsors target identical molecular targets. Biologics license application holders are responding by securing pediatric exclusivity extensions through mandatory trial commitments.
Hospital procurement committees are consolidating EPP therapy purchasing through integrated delivery networks that span dermatology, hematology, and hepatology service lines. Specialty pharmacy distribution is displacing traditional wholesale channels for injectable biologics. This channel consolidation is most visible in the United States, where pharmacy benefit managers are carving out rare disease tiers with distinct prior authorization workflows.
Erythropoietic Protoporphyria (EPP) Treatment Market Segmentation
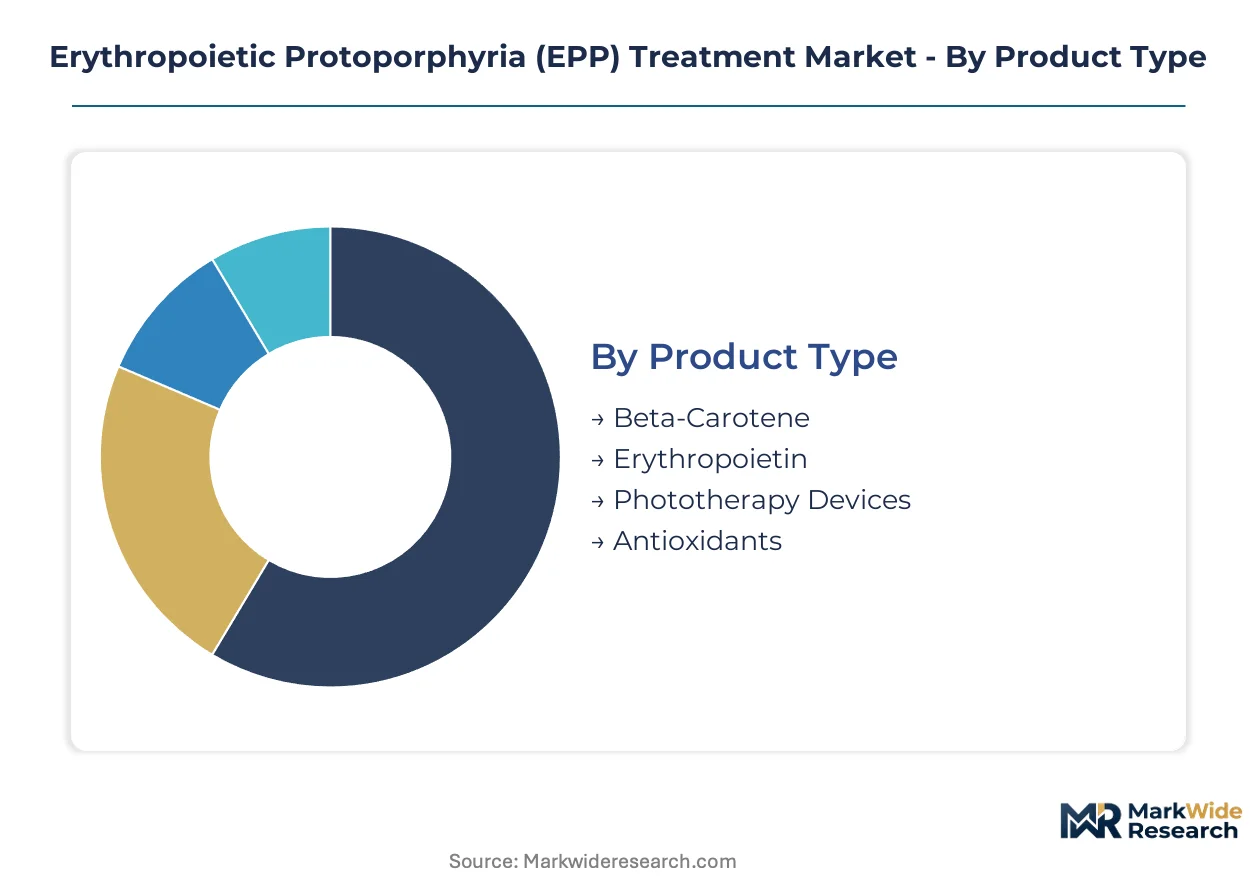
EPP treatment segmentation reveals distinct procurement patterns across pharmacological and device-based interventions. Patient stratification by disease severity and hepatic involvement drives channel preferences and reimbursement negotiations.
Product Type:
Standalone pharmacological therapies command dedicated pharmacy budgets, while phototherapy platforms embed into capital equipment cycles across dermatology departments.
- Phototherapy Devices:Visible-light filtering systems utilizing narrow-band LED arrays or filtered fluorescent sources. Demand concentrates in United States academic medical centers in Boston and Houston, where specialized porphyria clinics anchor device procurement decisions. FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape vendor selection criteria.
- Beta-Carotene:Oral carotenoid supplementation elevates skin tolerance thresholds through systemic photoprotection. European dermatology practices in Germany and Switzerland maintain higher prescription volumes due to established reimbursement codes, though supply volatility in natural-source extraction constrains formulation consistency.
- Erythropoietin:Recombinant hormone therapy modulating erythroid progenitor differentiation.
- Antioxidants:Supplementary compounds targeting oxidative stress from accumulated protoporphyrin IX.
Volume placements concentrate in phototherapy devices; the faster expansion belongs to beta-carotene formulations.
Delivery Mode:
Cost tier stratification separates premium biologic administration from commodity oral and topical channels.
- Injectable:Subcutaneous melanocortin receptor agonist delivery via prefilled syringes or autoinjector systems. Hospital-based infusion centers in San Francisco and New York City generate concentrated demand, with prior authorization workflows through United States pharmacy benefit managers extending fulfillment timelines.
- Oral:Capsule and tablet formulations enabling outpatient self-administration. Japan's PMDA orphan drug framework and South Korea's MFDS incentives are expanding addressable patient pools across Asia-Pacific, driving formulation development investment.
- Topical:Localized barrier creams and photoprotective lotions for immediate symptom management.
- Transdermal:Patch-based delivery systems under early clinical investigation for sustained release.
Injectable modes capture premium value; oral delivery is gaining share fastest among pediatric and adolescent populations.
End User:
Customer type fragmentation reflects divergent clinical workflows across institutional and direct-to-patient channels.
- Hospitals:Integrated delivery networks consolidating dermatology, hematology, and hepatology service lines. United States hospital procurement committees increasingly favor sole-source contracts for biologic therapies, displacing traditional wholesale distribution.
- Homecare:Remote administration and monitoring capabilities expanding through wearable UV-Visible spectrum sensors. Portable phototherapy device innovations are enabling patient-managed photoprotection outside clinical settings.
- Clinics:Outpatient specialty practices with focused porphyria expertise.
- Ambulatory Care Centers:Same-day procedure facilities handling diagnostic workups and infusion services.
Hospital systems dominate current procurement; homecare channels are climbing the fastest as device miniaturization progresses.
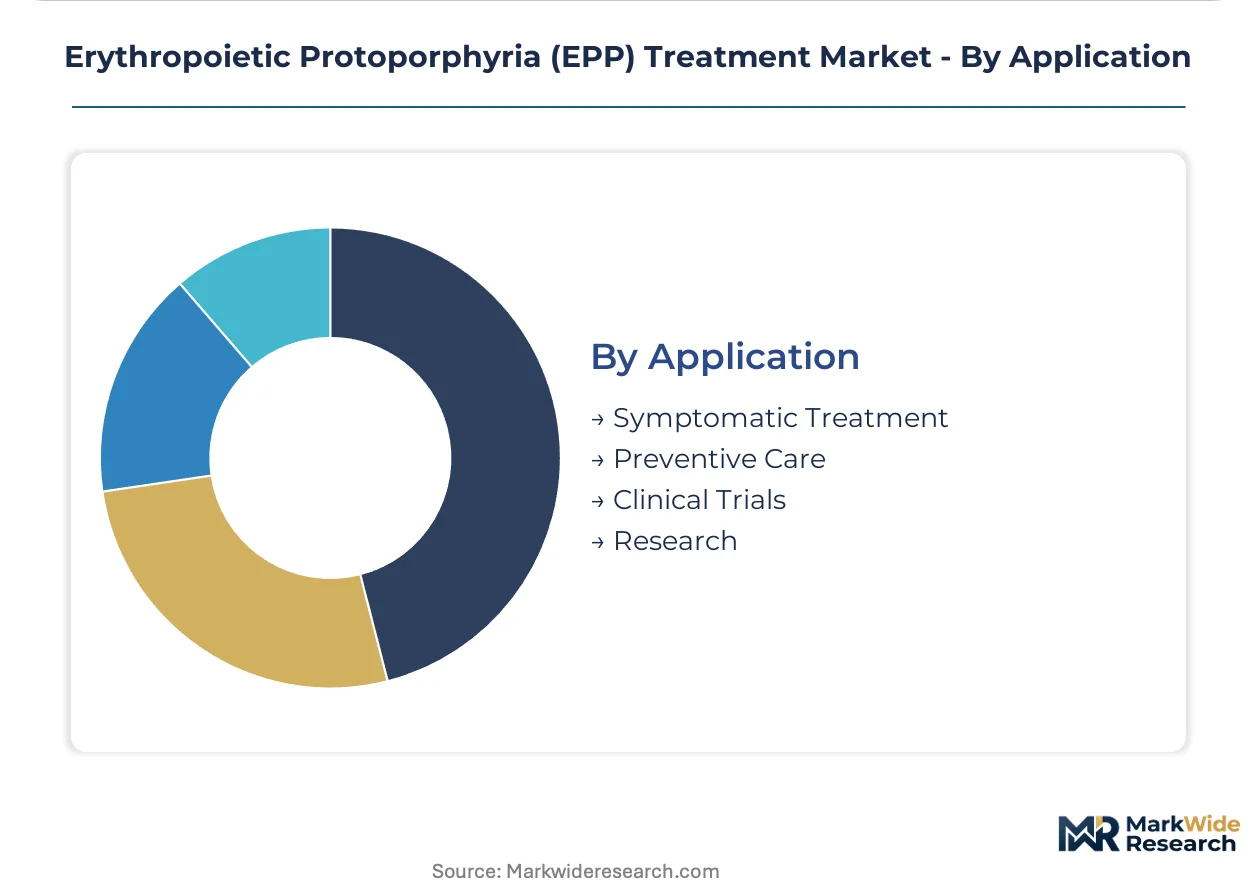
Application:
Maturity gradients separate established symptomatic management from emerging preventive and research-oriented segments.
- Symptomatic Treatment:Acute phototoxicity response and lesion management protocols. Demand anchors in established porphyria treatment centers with dedicated phototherapy suites and emergency consultation pathways.
- Preventive Care:Prophylactic photoprotection and hepatic monitoring regimens. Germany's university hospitals and France's ANSM-registered reference centers are piloting combination protocols layering transcriptional control over pharmacological management.
- Clinical Trials:Investigator-sponsored studies for novel heme biosynthesis pathway modulators.
- Research:Academic exploration of gene-silencing platforms and CRISPR-based heme pathway editing.
Symptomatic treatment retains volume leadership; preventive care applications show the steepest expansion trajectory as biomarker stratification enables precision dosing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Porphyrin precursor sourcing and specialized phototherapy device manufacturing concentrate in Switzerland and Germany, anchoring European supply chains for EPP therapeutics while patient identification programs expand across North American academic medical centers.
United States
Specialized porphyria treatment centers in Boston, San Francisco, and Houston drive clinical trial enrollment and premium therapy access. FDA orphan drug designation pathways compress regulatory timelines for novel melanocortin receptor agonists. Massachusetts General Hospital and University of California San Francisco anchor phototherapy device procurement decisions through integrated dermatology-hematology service lines.
Germany
University hospitals in Munich and Heidelberg pilot combination protocols layering transcriptional control over established pharmacological management. EMA priority medicines scheme accelerates assessment timelines for rare disease biologics manufactured in Swiss-German corridor facilities. Baden-Württemberg's precision medicine clusters concentrate heme biosynthesis pathway research talent.
Switzerland
Contract development and manufacturing organizations in Basel and Zurich control critical peptide-based therapy production capacity. Swissmedic regulatory frameworks align with EMA standards while maintaining distinct national marketing authorization pathways. The country's biopharma manufacturing infrastructure supplies melanocortin receptor agonist formulations to European and North American markets.
Japan
PMDA orphan drug framework and rare disease designation programs expand addressable patient pools for oral formulation developers. Tokyo and Osaka academic medical centers maintain established phototherapy suites with narrow-band LED arrays. METI industrial policy supports precision phototherapy platform miniaturization for homecare applications.
South Korea
MFDS orphan drug incentives attract EPP therapy developers seeking accelerated regulatory pathways in Asia-Pacific. Seoul National University Hospital and Samsung Medical Center anchor specialized porphyria diagnostic and treatment capacity. The country's electronics manufacturing base supplies LED components for portable visible-light filtering devices.
Erythropoietic Protoporphyria (EPP) Treatment Market Competitive Landscape
Global majors compete with regional champions across regulatory exclusivity and precision phototherapy platform development. The EPP treatment landscape concentrates around melanocortin receptor agonist patent holders and heme biosynthesis pathway modulator specialists. Three archetypes dominate: biologics-focused rare disease developers, diversified pharmaceutical conglomerates leveraging diagnostics infrastructure, and precision phototherapy device manufacturers. Competitive moves center on pediatric exclusivity extensions through mandatory trial commitments and sole-source contracting with United States integrated delivery networks.
Within the biologics-focused tier, Clinuvel Pharmaceuticals and Disc Medicine exemplify melanocortin receptor agonist and heme pathway modulation specialization respectively. Roche occupies a position bridging pharmaceutical development with diagnostics anchoring, leveraging global infrastructure to support porphyria screening programs. These three entities represent distinct strategic postures: regulatory exclusivity maintenance, novel mechanism pipeline development, and vertically integrated screening-to-treatment ecosystems.
| Leading Market Players |
|---|
| Clinuvel Pharmaceuticals |
| Disc Medicine |
| Roche |
| Alnylam Pharmaceuticals |
| Mitsubishi Tanabe Pharma |
| Pfizer |
| Johnson & Johnson |
| Tishcon Corp |
| L'Oréal |
| Others |
Supply & Pricing Matrix
Portable phototherapy device miniaturization simultaneously compresses manufacturing cost curves and concentrates component sourcing among South Korean and Japanese LED foundries, reshaping procurement economics across hospital and homecare channels. This technological shift tightens margins on legacy hospital-based systems while enabling premium capture for connected, patient-managed platforms.
Pricing Analysis
Device warranty and calibration service bundling separates premium melanocortin receptor agonist delivery systems from unbundled phototherapy hardware sold through capital equipment cycles. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, EU MDR certification tier, and after-sales service coverage depth. Pricing pressure stems from pharmacy benefit manager prior authorization tightening on injectable biologics. Hospital procurement committees exhibit lowest price sensitivity due to integrated delivery network sole-source contracting, while independent clinics face highest cost compression.
Supply Chain Analysis
Single-source vulnerability sits with Swiss and German contract development and manufacturing organizations controlling peptide-based melanocortin receptor agonist production capacity. Critical inputs include porphyrin precursor compounds, narrow-band LED arrays, and fluorometric assay reagents. Supply chain risk centers on REACH compliance timelines for porphyrin-related research compounds. Distribution runs through specialty pharmacy channels displacing traditional wholesale for biologics, while phototherapy devices flow through hospital procurement committees and integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EPP treatment landscape is transitioning from chronic pharmacological management toward disease-modifying gene-silencing platforms, compressing the addressable window for conventional melanocortin receptor agonists and creating urgency around portfolio repositioning.
For Market Incumbents: Acquire pediatric formulation capabilities and exclusive heme biosynthesis pathway modulator patents to extend regulatory exclusivity windows. Gene therapy substitution timelines threaten long-term demand for injectable biologics, making backward integration into Swiss-German peptide manufacturing capacity essential for cost defense. Channel control through sole-source contracts with United States integrated delivery networks anchors pricing power. For New Entrants and Emerging Players: Direct-to-patient telemedicine channels offer the most penetrable route for wearable UV-Visible spectrum sensors and portable phototherapy devices. Asia-Pacific diagnostic infrastructure expansion in Japan and South Korea presents underserved patient identification opportunities. Target homecare applications through pharmacy benefit manager rare disease tier carve-outs. For Investors and Strategic Acquirers: Exit pathways concentrate in biologics-focused rare disease developers with melanocortin receptor agonist patent estates and established EMA priority medicines scheme approvals. Long-term viability favors platforms combining transcriptional control with photoprotective pharmacology. The signal to watch is FDA pediatric exclusivity extension commitments in biologics license applications.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | EMA priority medicines scheme compresses assessment timelines for rare disease biologics. |
| Regulatory Approval Pathway | FDA orphan drug designation accelerates novel porphyria therapy development timelines. |
| Manufacturing Scale-Up | Swiss-German corridor CDMOs control critical peptide-based EPP therapy production capacity. |
| Pipeline Diversification | Gene-silencing platforms targeting ALAS2 expression reshape therapeutic hierarchy. |
| Strategic Partnership | United States academic medical centers anchor phototherapy device procurement decisions. |
Research Methodology
Independent corroboration across regulatory filings, hospital procurement databases, and clinical trial registries underwrites the qualitative findings. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient population estimates and top-down market sizing triangulate volume and value outputs.
Comparable-period anchoring to historical orphan drug approval timelines and phototherapy device installation cycles structures the projection horizon. The analytical framework segments by product type, delivery mode, end user, and application, with patient severity stratification and hepatic involvement status as cross-cutting dimensions. CAGRs derive from fitted growth curves across the modeling period, incorporating EMA assessment timeline compression, FDA exclusivity window extensions, and Asia-Pacific diagnostic infrastructure buildout as forecast inputs.
The model holds under stable regulatory incentive structures and continued orphan drug designation pathway integrity; deviation in gene therapy substitution timelines or reimbursement framework restructuring would shift trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Allogeneic Stem Cell Therapy Market
Hematology
Paroxysmal Nocturnal Hemoglobinuria (PNH) Treatment Market
Hematology
Global Disposable Hemoperfusion Market
Hematology
Heparin-Induced Thrombocytopenia (HIT) Treatment Market
Hematology
Transfusion Dependent Thalassaemia Management Market
Hematology
Hemoglobinopathies Treatment Market
Hematology
Hypereosinophilic Syndrome Market
Hematology
Polycythemia Vera Market
Hematology
APAC Acute Myeloid Leukemia Treatment Market
Hematology
Myelofibrosis Treatment Market
Hematology
Thrombocytopenia Treatment Market
Hematology
Global Sickle Cell Disease Treatment Market
Hematology
Aplastic Anemia Treatment Market
Hematology
Global Hematologic Malignancies Treatment Market
Hematology
Hairy Cell Leukemia Treatment Market
Hematology
Hemocytometer Market