
 APAC Acute Myeloid Leukemia Treatment Market | 2026-2036
APAC Acute Myeloid Leukemia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Acute Myeloid Leukemia Treatment Market Insights
Good Manufacturing Practice certification under ICH Q7 is bifurcating the competitive landscape into qualified API suppliers and excluded contract manufacturers. Novartis AG leverages its vertically integrated manufacturing footprint across Switzerland and Singapore to secure supply continuity for high-potency oncology compounds. DAIICHI SANKYO COMPANY, LIMITED anchors its position through deep R&D investment in FLT3 inhibitor chemistry, while Sun Pharmaceutical Industries Ltd competes on cost-engineered generic formulations for standard induction regimens.
Acute Myeloid Leukemia treatment encompasses chemotherapeutic, targeted, and immunotherapeutic interventions designed to eliminate malignant myeloblasts and restore normal hematopoiesis, with modern protocols incorporating cytarabine-anthracycline backbone combinations and molecularly guided agents such as midostaurin or enasidenib that target specific oncogenic driver mutations. Targeted therapy commands premium positioning as mutation profiling becomes standard-of-care, while immunotherapy segments including bispecific antibodies and CAR-T approaches represent the fastest-expanding modality pipeline. The intravenous route still dominates administration in hospital settings, though oral formulations for maintenance phases are reshaping post-remission care economics.
Japan's PMDA and Australia's TGA enforce distinct pharmacovigilance and clinical evidence standards that shape trial design and labeling requirements for sponsors seeking multi-country registration across the region. China's NMPA has tightened data localization mandates for patient-derived biomarker information, adding infrastructure requirements for genomic testing partnerships. Stakeholders must monitor evolving reimbursement negotiations between national health technology assessment bodies and manufacturers, as access decisions for novel agents will determine commercial viability faster than regulatory approval itself.
Market Dynamics
Precision-guided therapy protocols are compressing treatment paradigms across APAC oncology departments, with molecular profiling infrastructure investments by China's NMPA-registered cancer centers creating capacity bottlenecks that determine patient throughput and commercial access for novel agents.
Growth Catalysts
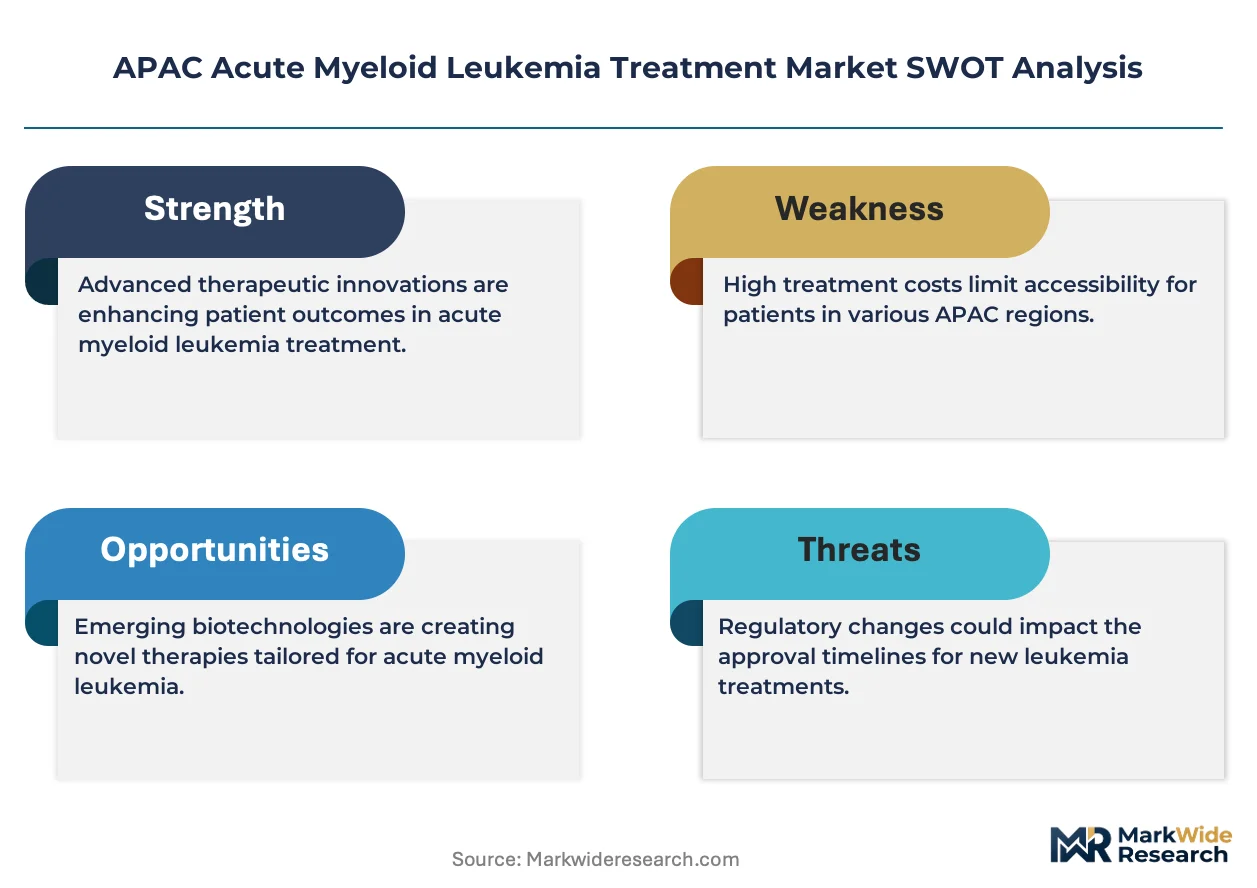
- Japan's PMDA Sakigake designation:This accelerated approval pathway compresses commercialization timelines for breakthrough AML therapies, enabling earlier patient access while reducing sponsor development risk.
- Centralized cancer center networks:China's tier-one cities aggregate patient volumes and specialist expertise, creating concentrated demand pools that justify infrastructure investment for genomic testing partnerships.
- FLT3 inhibitor chemistry advances:Deep R&D investment in targeted molecular platforms is expanding addressable patient populations beyond standard induction regimens.
Market Restraints
- High-potency API supply concentration:Manufacturing of cytotoxic oncology compounds depends on qualified suppliers with ICH Q7 certification, creating single-source vulnerabilities for contract manufacturers lacking GMP compliance.
- Data localization mandates:China's NMPA requires patient-derived biomarker information to reside domestically, adding infrastructure costs and partnership complexity for multinational sponsors.
- Reimbursement negotiation timelines:National health technology assessment bodies in Australia and South Korea extend market access delays beyond regulatory approval, compressing effective patent life.
Strategic Opportunities
- India's CDSCO pathway expansion:The country's emerging regulatory framework for biosimilars and targeted therapies offers first-mover positioning for sponsors establishing local clinical trial infrastructure.
- Oral maintenance formulations:Post-remission care economics favor ambulatory administration models that reduce hospital bed utilization while improving patient compliance metrics.
- CAR-T manufacturing partnerships:Convergence between cell therapy platforms and regional CMO networks addresses cold-chain logistics gaps across Southeast Asian markets.
Industry Challenges
- Hematopathologist workforce scarcity:Accurate FLT3, NPM1, and CEBPA mutation interpretation requires specialized diagnostic expertise concentrated in Tokyo, Shanghai, and Singapore institutions.
- Multi-country trial harmonization:Divergent pharmacovigilance standards between Japan's PMDA and Australia's TGA force redundant safety database configurations that extend study startup timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Acute Myeloid Leukemia Treatment Market |
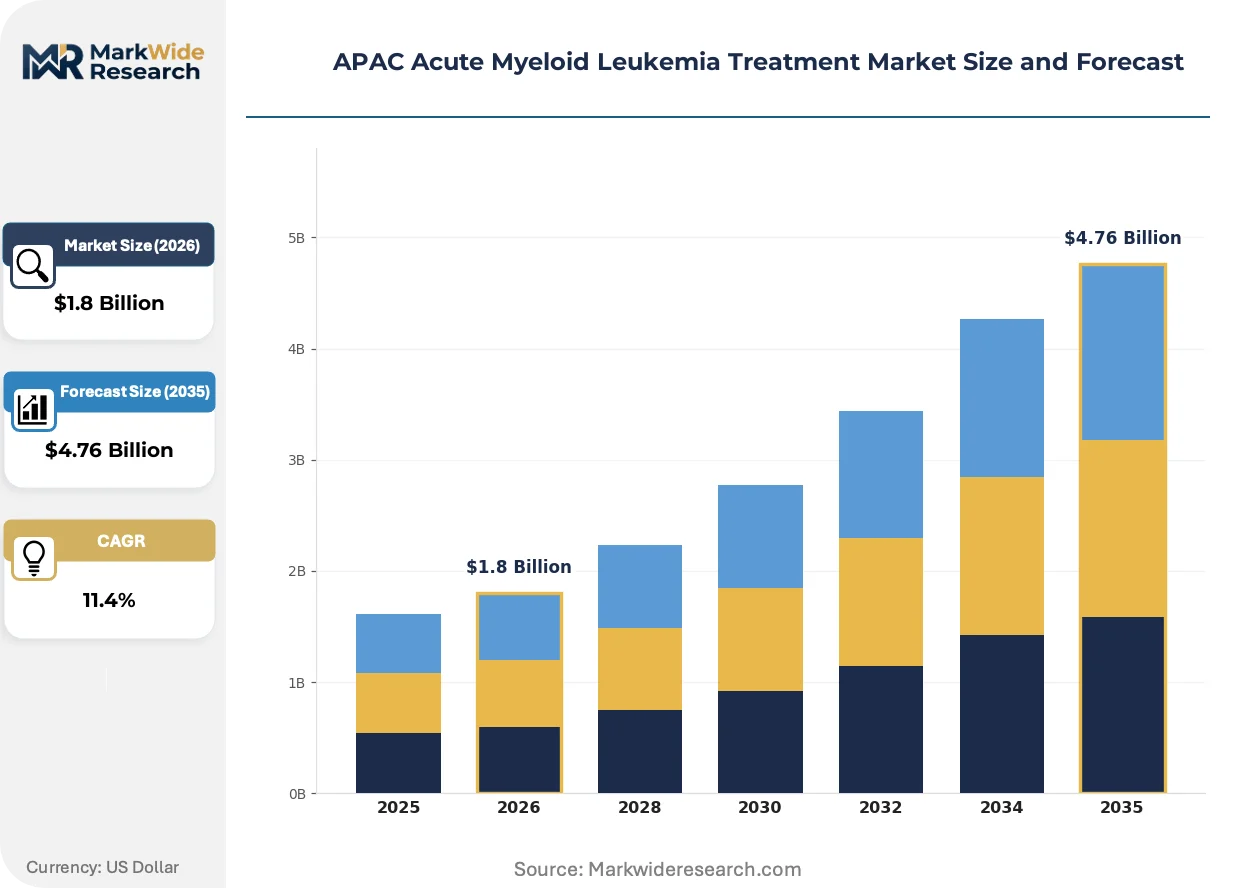
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Targeted Therapy, Immunotherapy, Stem Cell Transplant End User: Hospitals, Clinics, Homecare, Research Laboratories Administration Route: Oral, Intravenous, Subcutaneous, Intramuscular Therapy Approach: Combination Therapy, Monotherapy, Maintenance Therapy, Supportive Care |
| Companies Covered | Novartis AG, Pfizer Inc., AbbVie Inc., Teva Pharmaceutical, Sun Pharmaceutical Industries Ltd, DAIICHI SANKYO COMPANY, LIMITED, Astellas Pharma Inc., Bristol-Myers Squibb Company, Jazz Pharmaceuticals plc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Acute Myeloid Leukemia Treatment Market Trends and Innovations
Next-generation sequencing platforms are migrating from reference laboratories to hospital-based pathology departments, compressing turnaround times for mutation-directed therapy selection and enabling real-time treatment protocol adjustments.
Minimal residual disease monitoring via circulating tumor DNA is supplanting bone marrow aspiration for relapse surveillance. Major leukemia centers in Seoul and Melbourne adopt liquid biopsy protocols for post-remission tracking. This molecular surveillance modality is compressing the interval between biochemical recurrence and therapeutic intervention.
South Korea's MFDS has implemented conditional approval frameworks for regenerative medicine products, creating regulatory precedent for accelerated CAR-T licensure. Domestic manufacturers respond by establishing dedicated cell therapy manufacturing facilities in Songdo and Osong bioclusters. The policy shift positions Korean sponsors to capture regional export demand for autologous cell processing.
Hospital pharmacy committees across China's tier-one cities now mandate pharmacoeconomic dossiers for novel agent formulary inclusion. Multinational sponsors deploy health economics teams to Beijing and Guangzhou to preempt access barriers. This procurement evolution favors therapies with demonstrable readmission reduction or stem cell transplant avoidance benefits.
APAC Acute Myeloid Leukemia Treatment Market Segmentation
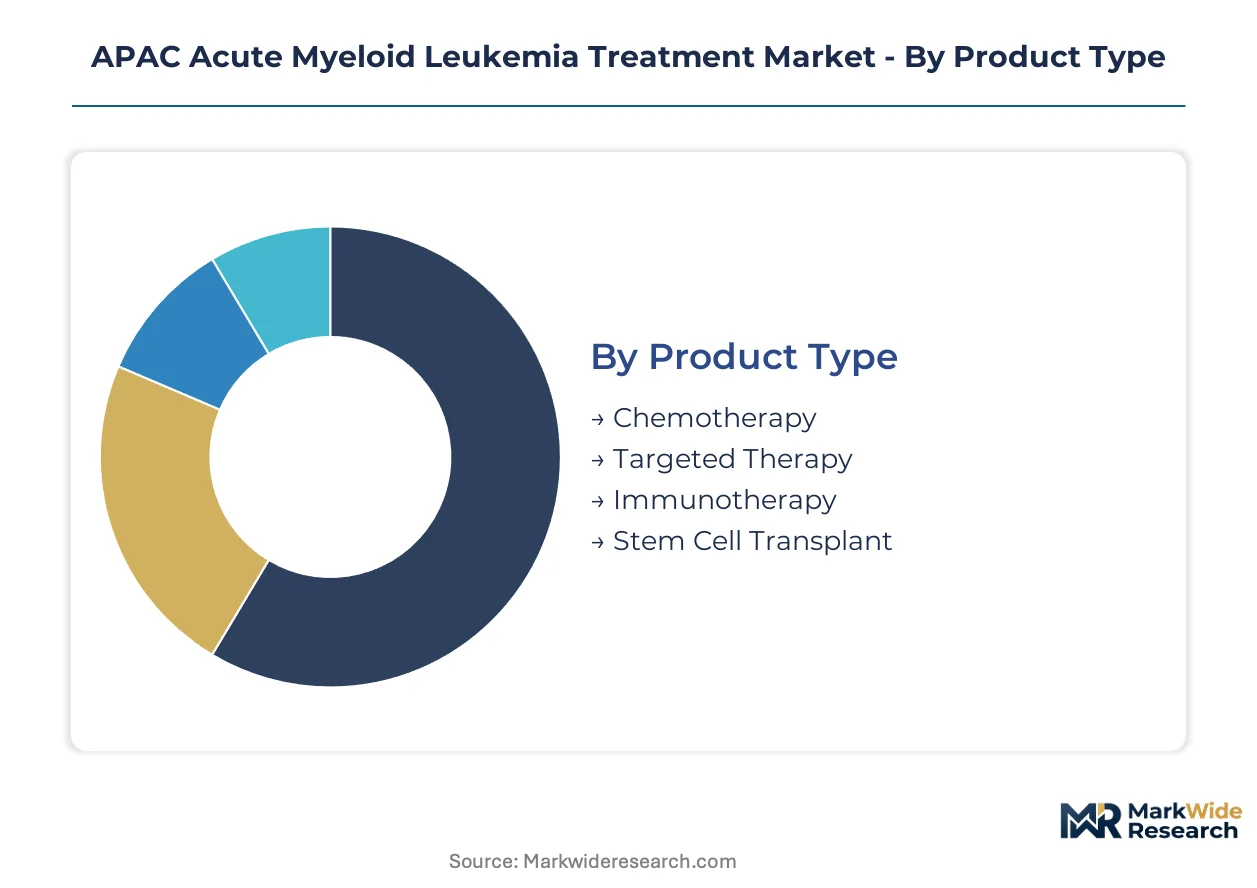
APAC treatment protocols fragment across four distinct dimensions. Product type and therapy approach segments diverge sharply between Japan's precision-medicine centers and India's cost-optimized induction programs. Route of administration and end-user splits reflect infrastructure asymmetries between Shanghai's tertiary hospitals and Southeast Asian ambulatory networks.
Product Type:
Domestic manufacturing capacity concentrates chemotherapy supply in India and China, while targeted and immunotherapy agents remain import-dependent across most of the region.
- Chemotherapy:Cytarabine-anthracycline combinations constitute the induction backbone. Demand clusters in China's tier-two cities where centralized procurement drives volume consolidation for generic cytotoxics.
- Targeted Therapy:FLT3 and IDH inhibitors command premium positioning. Japan's PMDA Sakigake pathway accelerates commercial access for mutation-directed agents in Tokyo and Osaka academic centers.
- Immunotherapy:Bispecific antibodies and emerging CAR-T platforms attract R&D investment. South Korea's MFDS conditional approval framework positions domestic manufacturers for regional cell therapy export.
- Stem Cell Transplant:Allogeneic procedures require HLA-matched donor registries. Singapore's National University Hospital anchors transplant volume for Southeast Asian referral networks.
Chemotherapy commands the established base. The steepest expansion runs through targeted therapy.
End User:
Patient volume aggregates in hospital-based oncology departments, though post-remission care economics are shifting eligible cases toward lower-acuity settings.
- Hospitals:Tertiary cancer centers in Beijing, Seoul, and Melbourne manage complex induction protocols. Inpatient capacity constraints limit throughput for high-intensity regimens.
- Clinics:Day-therapy units handle consolidation cycles and transfusion support. Australia's community oncology networks reduce travel burden for rural Queensland and Western Australia patients.
- Homecare:Oral maintenance agents enable ambulatory monitoring. Japan's visiting nurse associations coordinate between hospital discharge and community pharmacy dispensing.
- Research Laboratories:Academic medical centers in Singapore and Taiwan conduct biomarker-driven trial enrollment. NMPA-mandated data localization requires domestic genomic testing partnerships for China-based studies.
Hospitals retain the dominant share. The fastest volume shift moves toward homecare.
Administration Route:
Route selection tracks therapy intensity and disease phase, with infrastructure requirements varying across metropolitan and provincial care networks.
- Intravenous:Continuous infusion protocols demand dedicated oncology wards. China's tier-one hospitals invest in ambulatory infusion centers to decompress inpatient beds.
- Oral:Midostaurin and enasidenib formulations reshape maintenance-phase economics. Patient adherence programs in Japan link community pharmacists to hospital discharge planning.
- Subcutaneous:Cytarabine depot formulations reduce clinic visit frequency. India's CDSCO pathway expansion targets biosimilar subcutaneous alternatives for cost-sensitive markets.
- Intramuscular:Limited application for supportive care agents. Australia's TGA pharmacovigilance requirements shape labeling for parenteral antiemetics.
Intravenous delivery holds the current standard. Oral uptake is climbing the fastest.
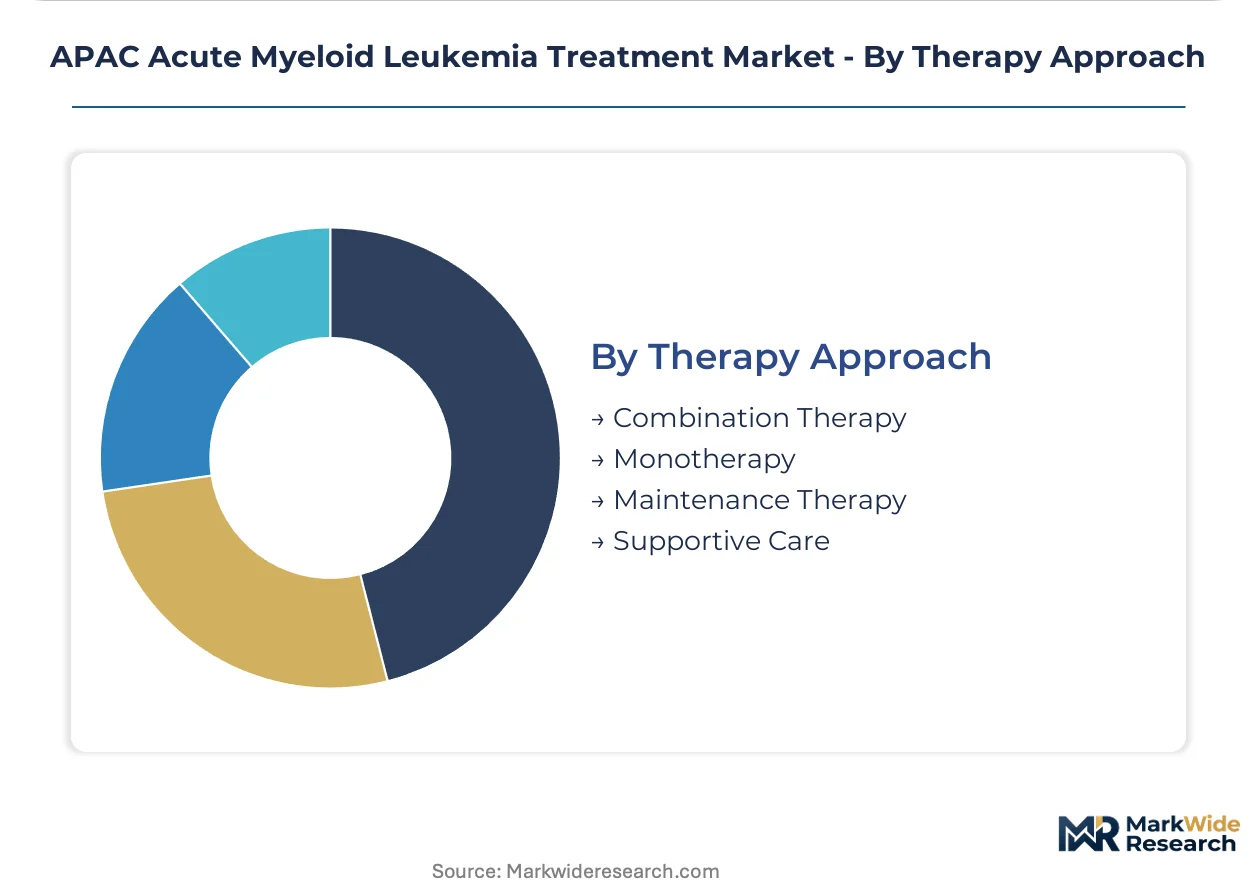
Therapy Approach:
Protocol design balances cytoreduction intensity against patient fitness, with molecular profiling increasingly directing combination selection.
- Combination Therapy:Chemotherapy-plus-targeted-agent protocols dominate fit-patient induction. Japan's leukemia study groups generate region-specific evidence for 7+3 plus midostaurin regimens.
- Monotherapy:Hypomethylating agents serve unfit populations. China's National Reimbursement Drug List negotiations determine access for azacitidine and decitabine.
- Maintenance Therapy:Post-remission oral agents extend disease-free intervals. South Korean health technology assessment bodies scrutinize cost-per-quality-adjusted-life-year for novel maintenance drugs.
- Supportive Care:Antimicrobial prophylaxis and transfusion support enable intensive treatment delivery. India's generic manufacturing base supplies filgrastim and antifungal prophylaxis across price-sensitive markets.
Combination therapy anchors first-line practice. Maintenance therapy is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital-based oncology departments concentrate purchasing power for high-potency AML compounds. Academic medical centers in Tokyo, Shanghai, and Seoul aggregate mutation profiling demand and specialist expertise. Tier-one cities across the region create concentrated demand pools that justify infrastructure investment.
China
Beijing and Shanghai cancer centers drive volume for precision-guided protocols. The NMPA mandates domestic data localization for patient-derived biomarker information, forcing genomic testing partnerships with local laboratories. Yangtze River Delta hospitals invest in next-generation sequencing infrastructure to decompress diagnostic bottlenecks.
Japan
Tokyo and Osaka academic centers anchor regional demand for FLT3 inhibitors and targeted maintenance agents. The PMDA Sakigake designation compresses commercialization timelines for breakthrough therapies. Kanto-based leukemia study groups generate region-specific clinical evidence for combination regimens.
South Korea
Seoul National University Hospital and Samsung Medical Center concentrate transplant volume and CAR-T trial enrollment. The MFDS conditional approval framework for regenerative medicine products accelerates cell therapy licensure. Songdo and Osong bioclusters host dedicated autologous cell processing facilities.
Australia
Melbourne and Sydney tertiary hospitals manage complex induction protocols for the broader Oceania referral network. The TGA enforces distinct pharmacovigilance standards that shape trial design for multi-country registration. Queensland community oncology networks extend day-therapy access for rural patients.
India
Maharashtra and Gujarat manufacturing clusters supply cost-engineered generic cytotoxics across price-sensitive markets. The CDSCO pathway expansion for biosimilars and targeted therapies attracts first-mover sponsors. Mumbai-based contract manufacturers seek ICH Q7 certification to access high-potency API supply chains.
APAC Acute Myeloid Leukemia Treatment Market Competitive Landscape
Player mix skews toward vertically integrated multinationals with captive manufacturing footprints and deep R&D investment in molecular platforms. Market structure concentrates around sponsors with accelerated regulatory pathways and established hospital formulary relationships. Two strategic archetypes dominate: precision-medicine developers with mutation-directed portfolios, and cost-optimized generic manufacturers serving standard induction regimens. Competitive moves center on genomic testing partnerships and oral formulation development for maintenance-phase economics.
Among Swiss and Singapore-anchored multinationals, Novartis AG occupies a position exemplifying vertically integrated supply continuity for high-potency oncology compounds. Within the Japanese precision-medicine tier, DAIICHI SANKYO COMPANY, LIMITED represents deep FLT3 inhibitor chemistry investment. At the cost-engineered end, Sun Pharmaceutical Industries Ltd exemplifies generic formulation competitiveness for standard induction backbones.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| AbbVie Inc. |
| Teva Pharmaceutical |
| Sun Pharmaceutical Industries Ltd |
| DAIICHI SANKYO COMPANY, LIMITED |
| Astellas Pharma Inc. |
| Bristol-Myers Squibb Company |
| Jazz Pharmaceuticals plc |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements with ICH Q7-certified API suppliers lock in supply access for high-potency oncology compounds while anchoring price visibility across China's NMPA-mandated procurement cycles. Japan's PMDA Sakigake pathway creates premium pricing corridors for breakthrough therapies that bypass standard negotiation timelines.
Pricing Analysis
Cost-plus contracts indexed to active pharmaceutical ingredient spot markets dominate procurement for standard induction regimens. Price differentiation rests on GMP certification tier and volume scale, with ICH Q7-qualified suppliers commanding 15-25% premia over non-certified alternatives. Pricing pressure stems from China's centralized volume-based procurement compressing margins for generic cytotoxics. India's cost-engineered manufacturers exhibit highest price sensitivity, while Japan's academic medical centers prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
Strategic stockpiling of FLT3 inhibitor precursors characterizes sponsor inventory posture given six-to-nine-month synthesis timelines for chiral intermediates. Manufacturing gravity centers on Switzerland, Singapore, and India, with high-potency API production anchored in Basel-area facilities and formulation finishing distributed across Maharashtra contract manufacturers. Supply chain risk concentrates in single-source dependencies for fluorinated intermediates sourced from Chinese specialty chemical houses. Distribution runs through hospital pharmacy committees in tier-one cities that consolidate demand for novel agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Companion diagnostic services and pharmacoeconomic dossier preparation represent faster-expanding revenue layers than molecule supply alone, with genomic testing partnerships generating recurring engagement across China's NMPA-registered cancer centers.
For Market Incumbents: Consolidate manufacturing footprint through backward integration into high-potency API production, securing ICH Q7-qualified capacity in Basel or Singapore to insulate against Chinese export license volatility. Deepen formulary relationships with Tokyo and Shanghai academic centers by embedding health economics teams that preempt procurement committee objections. Defensive priority rests on CAR-T manufacturing partnerships that address Southeast Asian cold-chain gaps before Korean bioclusters capture regional export demand.
For New Entrants and Emerging Players: Differentiate on oral maintenance formulation development, targeting post-remission care economics where hospital bed decompression creates procurement urgency. White-space opportunity concentrates in India's tier-two cities where CDSCO pathway expansion lowers biosimilar entry barriers, and in Australia's community oncology networks seeking rural day-therapy alternatives. Go-to-market angle should leverage pharmacoeconomic modeling that demonstrates stem cell transplant avoidance benefits.
For Investors and Strategic Acquirers: The market sits at a precision-medicine transition phase that favors vertically integrated developers with mutation-directed portfolios and captive manufacturing. Long-term viability over the next decade hinges on genomic testing infrastructure ownership rather than molecule supply alone. Acquisition target archetype: mid-cap sponsors with FLT3 or IDH inhibitor pipelines and established NMPA partnerships. Signal to watch is MFDS conditional approval precedent expanding to autologous cell processing, which would validate Korean biocluster export models.
| Strategic Initiative | Industry Significance |
|---|---|
| Genomic Testing Partnership | NMPA data localization mandates require domestic laboratory alliances for China market access. |
| Oral Formulation Development | Post-remission ambulatory protocols reduce hospital utilization while improving adherence metrics. |
| CAR-T Manufacturing Scale-Up | MFDS conditional approval framework positions Korean facilities for regional autologous cell export. |
| Health Economics Team Deployment | Beijing and Guangzhou pharmacoeconomic dossiers preempt formulary exclusion for novel agents. |
| ICH Q7 Certification Investment | GMP compliance separates qualified API suppliers from excluded contract manufacturers. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists converged on the working assumptions that shaped this analysis. Primary interviews with formulary directors in Tokyo, Shanghai, and Melbourne were cross-validated against secondary sources including PMDA Sakigake designations, NMPA genomic data localization guidance, ClinicalTrials.gov enrollment patterns, and hospital procurement databases. Bottom-up patient-volume modeling and top-down therapy-cost aggregation were triangulated to anchor segment-level estimates.
Segmentation dimensions modeled include therapy approach, product type, administration route, end-user setting, and regional regulatory cluster across the projection horizon. CAGRs were derived from therapy-line adoption curves and reimbursement trajectory modeling rather than simple extrapolation. Forecast inputs incorporated FLT3 mutation prevalence data, stem cell transplant eligibility rates, and conditional approval pathway utilization by Korean and Japanese regulators.
The analysis sits within stated boundaries; outcomes outside sustained PMDA Sakigake utilization or NMPA procurement centralization would require recalibration. Forecasts reflect assumptions about biomarker testing penetration and oral formulation adherence that could shift with hematopathologist workforce expansion or visiting nurse program scaling. Practitioners should keep alternative scenarios live as MFDS regenerative medicine precedent and China's volume-based procurement evolution unfold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Global Hematology Diagnostics Market
Hematology
Global Sickle Cell Disease Treatment Market
Hematology
Alpha Thalassemia Market
Hematology
Thalassemia Treatment Market
Hematology
Malignant Lymphoma Market
Hematology
Global Disposable Hemoperfusion Market
Hematology
Global Hodgkin Lymphoma Treatment Market
Hematology
Global Hematopoietic Stem Cell Transplantation Market
Hematology
Apheresis Market
Hematology
Acute Myeloid Leukemia Treatment Market
Hematology
Global Hematology Market
Hematology
Idiopathic Thrombocytopenic Purpura Market
Hematology
Hemocytometer Market
Hematology
Sickle Cell Disease Market
Hematology
Radiation-Induced Myelosuppression Treatment Market
Hematology
Allogeneic Stem Cell Therapy Market