
 Internal Radiation Therapy Market | 2026-2036
Internal Radiation Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Internal Radiation Therapy Market Foresight
CE marking under the EU Medical Device Regulation is redrawing competitive boundaries for radioactive implant suppliers. Elekta AB leverages its integrated oncology software ecosystem to sustain recurring revenue streams across European treatment centers. Siemens Healthineers anchors its position through in-house production of cobalt-60 sources and linear accelerator pairing. Curium competes on radioisotope logistics, controlling cold-chain distribution networks that extend from reactor to bedside.
Internal radiation therapy delivers ionizing radiation directly to tumor sites via implanted sealed sources or liquid radioisotopes, with dose rates typically measured in gray per hour and source strengths calibrated in air-kerma strength for clinical precision. Brachytherapy seeds dominate product-level revenue due to established prostate cancer protocols, while MRI-guided technology commands premium positioning as real-time soft-tissue visualization improves placement accuracy. Radioisotopes for intravesical therapy represent the fastest-growing product category, driven by expanding bladder cancer indications and shorter treatment protocols.
The FDA governs sealed source manufacturing through 10 CFR Part 32 and 10 CFR Part 35, while the EMA's MDR framework imposes post-market surveillance obligations on European importers of radioactive devices. Germany's KBA-equivalent federal radiation protection authority enforces strict handling certifications that limit market access for non-domestic suppliers. Stakeholders must monitor isotope supply security as aging research reactors in Belgium and the Netherlands approach decommissioning timelines.
Market Dynamics
Radioisotope supply concentration in aging European research reactors is forcing manufacturers toward alternative sourcing strategies and regional production partnerships. This structural dependency on Belgium's BR2 and the Netherlands' HFR facilities creates vulnerability as both approach decommissioning windows.
Growth Catalysts
- Prostate cancer protocol expansion:Aging demographics in developed healthcare systems are expanding eligible patient pools for low-dose-rate seed implants. Urology clinics in the United States are adding dedicated brachytherapy suites to capture this demand.
- MDR framework clarity:The EU Medical Device Regulation's post-market surveillance obligations, while stringent, have eliminated regulatory ambiguity that previously delayed product registrations. European importers now operate with predictable compliance timelines.
- MRI-guided placement systems:Real-time soft-tissue visualization technology is improving seed positioning accuracy and reducing rectal toxicity rates. Academic medical centers in Germany are prioritizing capital allocation toward these integrated platforms.
Market Restraints
- Molybdenum-99 supply fragility:The global market depends on five aging research reactors for technetium-99m precursor production. No new large-scale fission facilities have entered operation in two decades.
- Cobalt-60 logistics costs:Radioactive decay during transport from Canadian and Russian irradiation facilities imposes effective loss rates that compress margins for high-volume applicator manufacturers.
- Substitute modality competition:External beam radiation therapy with stereotactic body radiation therapy protocols offers non-invasive alternatives for prostate and gynecological indications, capturing patients averse to implant procedures.
Strategic Opportunities
- Intravesical radioisotope therapy:Bladder cancer applications represent underpenetrated clinical territory with shorter treatment protocols than systemic chemotherapy. French university hospitals are establishing dedicated interventional radiotherapy units for this indication.
- Accelerator-based isotope production:Cyclotron-generated technetium-99m and iodine-131 alternatives are decoupling supply from reactor geopolitics. Canadian health authorities are funding pilot facilities to validate commercial viability.
- Software-integrated service contracts:Treatment planning system subscriptions bundled with source procurement are locking in recurring revenue streams. Elekta's oncology software ecosystem demonstrates this model's traction across Nordic treatment centers.
Industry Challenges
- Medical physicist scarcity:Brachytherapy requires specialized dosimetry expertise that radiation oncology residency programs are de-emphasizing. The American Board of Radiology has documented declining fellowship completion rates.
- Legacy source retrieval liability:Manufacturers face open-ended financial obligations for orphaned implants in deceased patients. The NRC's 10 CFR Part 32.74 imposes strict tracking requirements with penalty structures for non-compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Internal Radiation Therapy Market |
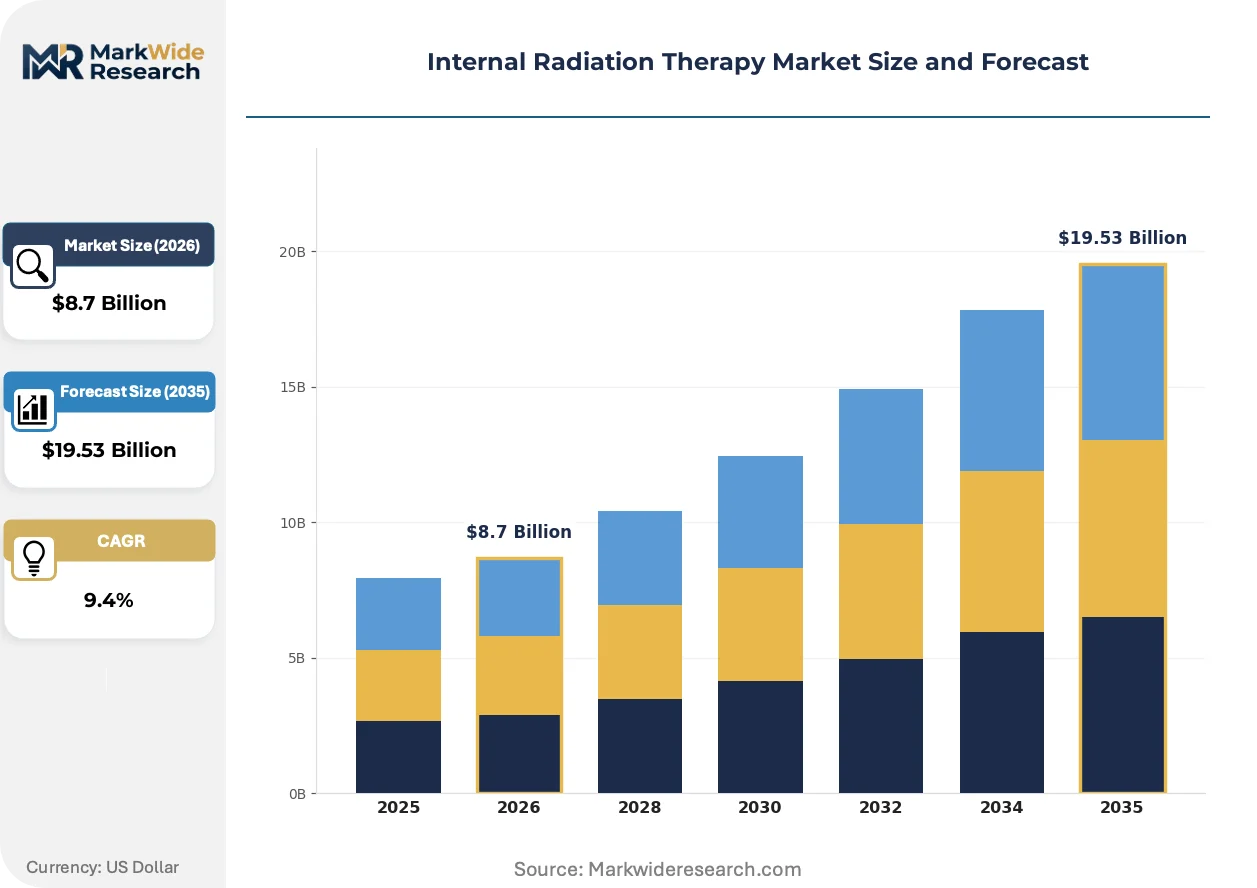
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brachytherapy, Seed Implants, Radioisotopes, Intravesical Therapy End User: Hospitals, Oncology Clinics, Research Institutes, Treatment Centers Technology: X-ray, CT-guided, Ultrasound, MRI-guided Application: Prostate Cancer, Cervical Cancer, Lung Cancer, Endometrial Cancer |
| Companies Covered | Siemens Healthineers, Elekta AB, Accuray Incorporated, IBA (Ion Beam Applications), Curium, Advanced Accelerator Applications, Nordion, ViewRay Technologies, Mevion Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Internal Radiation Therapy Market Shifts & Advancements
Digital integration between imaging, planning, and delivery systems is compressing treatment timelines while raising precision standards. Three concurrent developments are restructuring competitive requirements.
High-dose-rate afterloaders with 3D ultrasound guidance are displacing conventional X-ray based planning systems in cervical and endometrial applications. Gynecological oncology departments at major academic centers are adopting these platforms within 18-month replacement cycles. The technology is displacing film-based dosimetry verification and reducing planning time from hours to minutes.
The FDA's strengthened quality-system requirements under 10 CFR Part 32 are mandating electronic source-tracking databases with real-time location monitoring. Manufacturers must now maintain chain-of-custody records from reactor production through clinical implantation. Smaller sealed-source suppliers lacking enterprise resource planning infrastructure are exiting the United States market rather than absorbing compliance costs.
Hospital procurement departments are consolidating radioisotope purchasing through group purchasing organizations to leverage volume against volatile spot pricing. Independent oncology clinics are losing direct supplier relationships as health system centralization accelerates. This concentration is most visible in Germany, where university hospital networks now negotiate blanket agreements covering multiple isotope categories.
Internal Radiation Therapy Market Segmentation
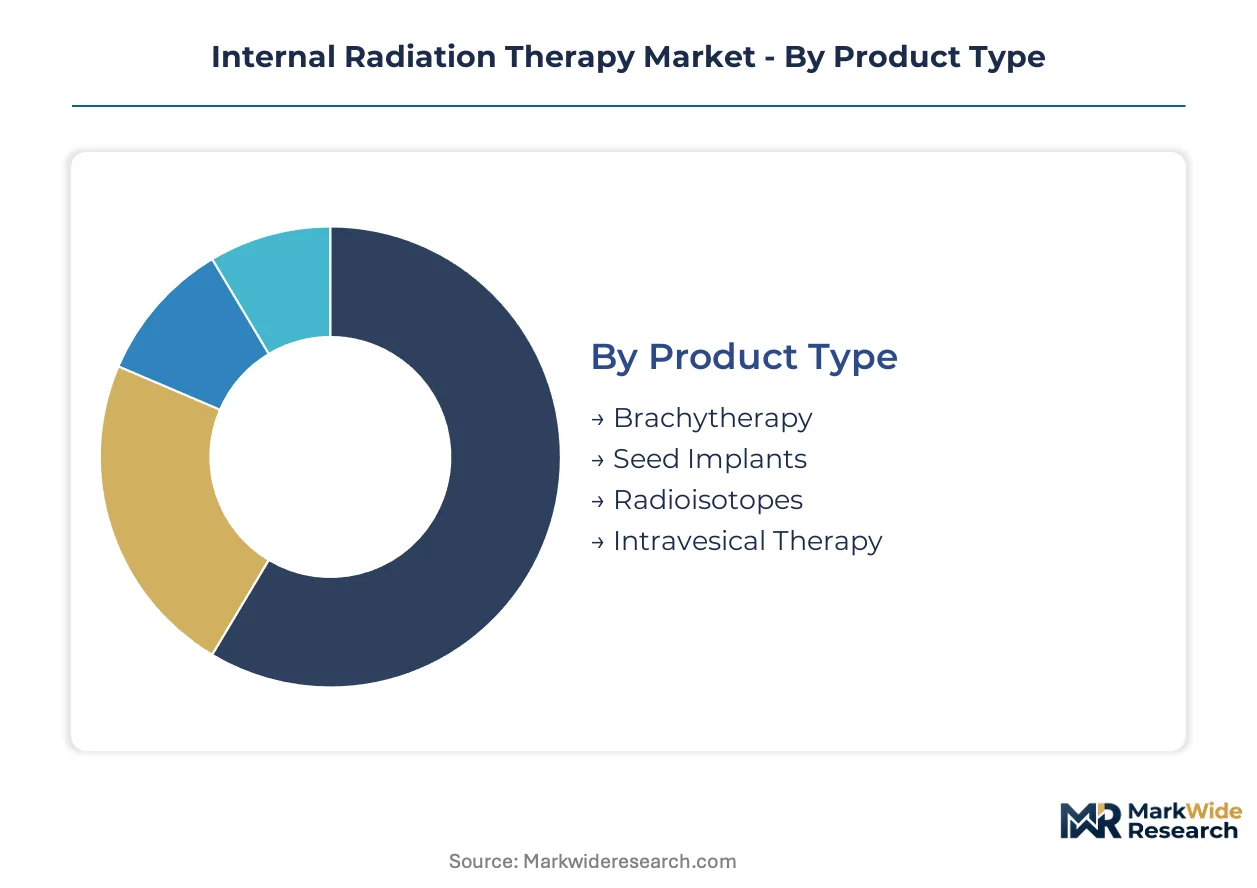
Segmentation in internal radiation therapy reveals how modality selection, clinical setting, and technological sophistication intersect to determine procurement patterns. Each dimension carries distinct regulatory footprints and capital intensity requirements that reshape competitive positioning across treatment ecosystems.
Product Type:
Substitute modality pressure concentrates most intensely on conventional brachytherapy platforms as external beam alternatives capture patient volume in prostate and gynecological indications.
- Brachytherapy:Sealed source placement delivers ionizing radiation directly to tumor beds through temporary or permanent implants. Demand clusters in United States urology clinics expanding dedicated suites for low-dose-rate prostate protocols, though stereotactic body radiation therapy captures patients averse to implant procedures.
- Seed Implants:Low-dose-rate permanent implants using iodine-125 or palladium-103 sources dominate established prostate cancer treatment pathways. German university hospitals are prioritizing capital allocation toward integrated platforms combining seed placement with real-time imaging verification.
- Radioisotopes:Liquid radioisotope formulations for systemic or localized delivery, including technetium-99m and iodine-131 variants.
- Intravesical Therapy:Radioisotope solutions for bladder cancer applications represent underpenetrated clinical territory with shorter treatment protocols than systemic chemotherapy.
Brachytherapy anchors the volume base while intravesical therapy gains share at the steepest rate.
End User:
Procurement authority is shifting toward consolidated health system purchasing departments as independent clinics lose direct supplier relationships under group purchasing organization concentration.
- Hospitals:Academic medical centers and community hospital systems command capital budgets for integrated imaging-delivery platforms. United States health system centralization accelerates blanket agreement negotiations covering multiple isotope categories.
- Oncology Clinics:Specialized radiation oncology practices focus on high-throughput brachytherapy services. German university hospital networks now negotiate centralized procurement covering seed implants and afterloader maintenance contracts.
- Research Institutes:Clinical trial sites and translational research facilities driving protocol development for novel radioisotope applications.
- Treatment Centers:Dedicated cancer centers optimizing patient throughput through dedicated interventional radiotherapy suites.
Hospitals dominate capital expenditure decisions while oncology clinics deliver the highest procedure volume per site.
Technology:
Margin compression in conventional imaging modalities is accelerating displacement as real-time soft-tissue visualization commands premium positioning.
- X-ray:Fluoroscopic guidance remains standard for basic seed placement verification. Cost-sensitive community hospitals in the United States retain these systems for high-throughput prostate procedures where capital constraints limit platform upgrades.
- CT-guided:Computed tomography integration enables three-dimensional dosimetry planning with superior anatomical resolution. Belgian treatment centers leverage CT-guided systems for complex gynecological applications requiring precise organ-at-risk delineation.
- Ultrasound:Transrectal ultrasound dominates prostate brachytherapy for real-time needle guidance.
- MRI-guided:Magnetic resonance imaging delivers unmatched soft-tissue contrast for placement accuracy. Academic medical centers in Germany are establishing dedicated MRI-guided brachytherapy suites as replacement cycles compress toward eighteen-month intervals.
X-ray and CT-guided platforms constitute the installed base majority while MRI-guided systems command the steepest expansion trajectory.
Application:
Protocol maturity varies sharply across oncology indications, with reimbursement pathways and clinical evidence depth determining commercial accessibility.
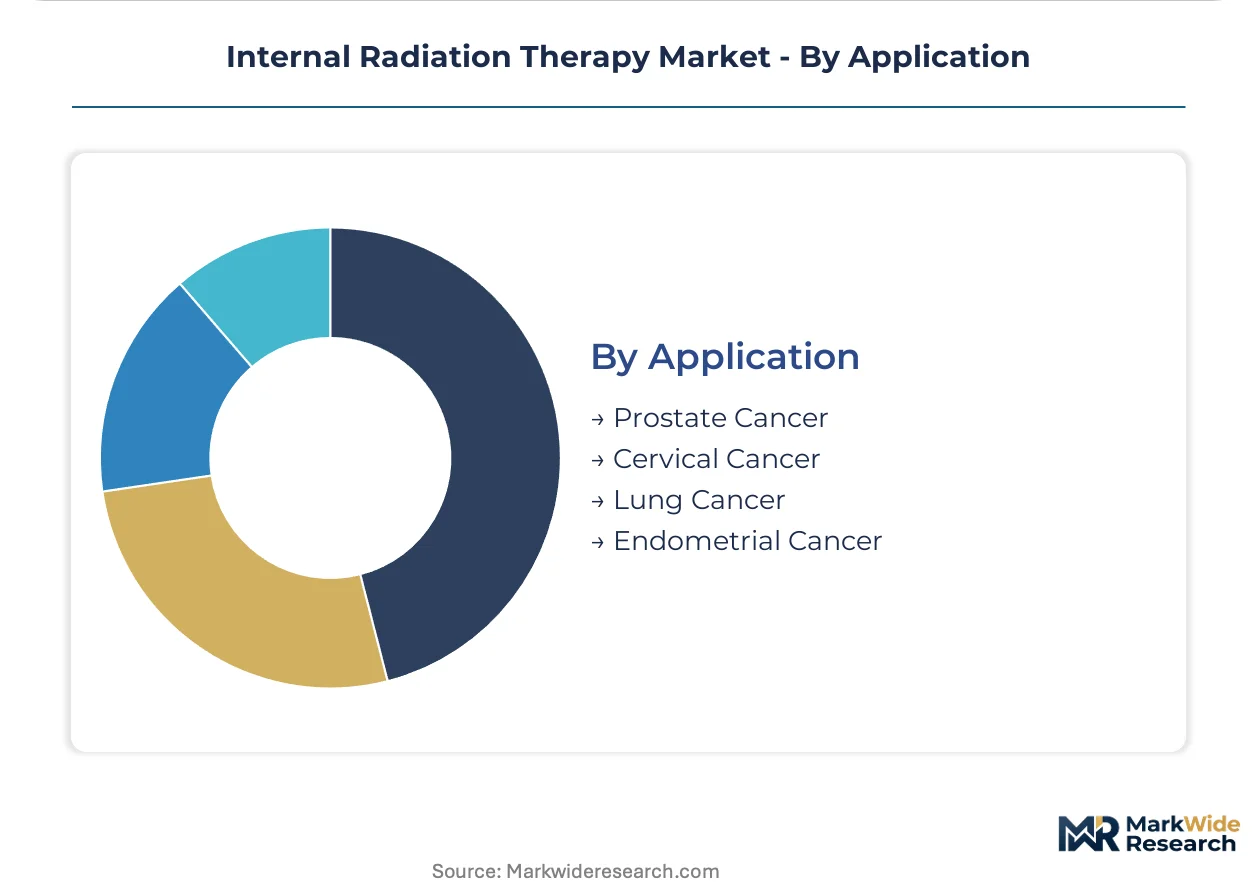
- Prostate Cancer:Low-dose-rate seed implants represent the most established brachytherapy application with decades of outcome data. United States urology clinics are adding dedicated suites as aging demographics expand eligible patient pools.
- Cervical Cancer:High-dose-rate afterloader therapy with tandem and ovoid applicators remains central to definitive treatment. French university hospitals are adopting 3D ultrasound-guided afterloaders within accelerated replacement cycles.
- Lung Cancer:Brachytherapy applications in bronchial obstruction and endobronchial treatment.
- Endometrial Cancer:Vaginal cylinder brachytherapy for postoperative adjuvant treatment.
Prostate cancer anchors the procedure volume base while cervical cancer applications retain the most stable reimbursement profile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal reimbursement incentives in the United States are expanding brachytherapy service coverage while the EMA's MDR framework stabilizes European product registration timelines. Aging demographics across developed healthcare systems are concentrating demand for prostate cancer interventions. Regulatory clarity is reshaping competitive access across major treatment markets.
United States
Urology clinics are adding dedicated brachytherapy suites as Medicare reimbursement codes stabilize for low-dose-rate seed procedures. The FDA enforces 10 CFR Part 32 quality-system requirements that mandate electronic source-tracking databases with real-time location monitoring. Academic medical centers in Boston and Houston are prioritizing capital allocation toward MRI-guided placement platforms.
Germany
University hospital networks are negotiating centralized procurement agreements covering seed implants and afterloader maintenance contracts. The KBA-equivalent federal radiation protection authority enforces strict handling certifications that limit market access for non-domestic suppliers. Treatment centers in Munich and Heidelberg are establishing dedicated interventional radiotherapy suites for intravesical therapy applications.
France
French university hospitals are adopting 3D ultrasound-guided afterloaders within accelerated replacement cycles for cervical cancer protocols. ANSM oversight aligns with EMA MDR post-market surveillance obligations for radioactive device importers. The Paris and Lyon oncology clusters are building dedicated interventional radiotherapy units for bladder cancer indications.
Canada
Health Canada is funding pilot facilities to validate commercial viability of accelerator-based technetium-99m production decoupled from reactor geopolitics. The PMRA framework governs sealed source manufacturing parallel to FDA structures. Toronto and Vancouver treatment centers are integrating cyclotron-generated isotope alternatives into existing brachytherapy workflows.
Japan
PMDA regulatory pathways are streamlining approval timelines for MRI-guided brachytherapy platforms as METI prioritizes precision oncology infrastructure. Aging population demographics are expanding eligible patient pools for prostate seed implants at rates exceeding Western benchmarks. Tokyo and Osaka academic medical centers are compressing replacement cycles toward eighteen-month intervals for integrated imaging-delivery systems.
Internal Radiation Therapy Market Competitive Landscape
Player mix skews toward diversified health technology conglomerates with captive isotope supply chains and specialized radiation oncology pure-plays with software-integrated service models. Consolidation pressure favors enterprises with in-house reactor partnerships or accelerator-based production capabilities. Three archetypes dominate: integrated oncology platform providers controlling treatment planning ecosystems, radioisotope logistics specialists commanding cold-chain distribution networks, and precision imaging manufacturers pairing linear accelerators with source production. Competitive moves center on strategic partnerships securing isotope supply security and portfolio diversification into accelerator-based production alternatives.
Within the integrated platform tier, Elekta AB and Siemens Healthineers exemplify divergent approaches to sustaining recurring revenue. Elekta leverages its oncology software ecosystem to lock in subscription-based service contracts across Nordic and European treatment centers. Siemens Healthineers anchors positioning through in-house production of cobalt-60 sources and linear accelerator pairing, representing backward integration into critical supply inputs. Curium occupies a distinct position as a radioisotope logistics specialist, with its archetype defined by control over cold-chain distribution networks extending from reactor production through clinical implantation.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Elekta AB |
| Accuray Incorporated |
| IBA (Ion Beam Applications) |
| Curium |
| Advanced Accelerator Applications |
| Nordion |
| ViewRay Technologies |
| Mevion Medical Systems |
| Others |
Supply & Pricing Matrix
Reactor-scale economies in radioisotope production concentrate supply among five aging European facilities, compressing price floors for technetium-99m and cobalt-60 while elevating premiums for accelerator-sourced alternatives. This structural concentration grants incumbent logistics specialists outsized pricing power in long-term offtake negotiations with hospital purchasing committees.
Pricing Analysis
Certification level (FDA-grade, CE-marked, or basic ISO) creates the primary spread across brachytherapy seed and afterloader procurement contracts. Subscription-based service bundling dominates integrated platform sales, while per-source transactional pricing persists for standalone radioisotope orders. Price differentiation stems from cold-chain reliability guarantees and real-time tracking capability, with cost compression in standard-grade seeds intensifying as group purchasing organizations consolidate oncology clinic volume. Community hospital systems exhibit highest price sensitivity due to capital constraint pressures, whereas academic medical centers prioritize MRI-guided placement accuracy over unit economics.
Supply Chain Analysis
Radioactive decay during transport imposes strict inventory velocity requirements, with cobalt-60 sources losing effective strength across Canadian and Russian irradiation-to-delivery routes. Supply concentrates in Belgium, the Netherlands, and Canada for reactor-produced isotopes, while Germany and Japan anchor precision applicator manufacturing. Raw material dependencies include enriched uranium targets, high-purity cobalt rods, and specialized polymer encapsulants. Single-source vulnerability from aging BR2 and HFR reactor decommissioning timelines threatens supply continuity. Distribution runs through radioisotope logistics specialists controlling temperature-monitored cold-chain networks from production facilities through clinical implantation suites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized medical physicist expertise and reactor-access credentials constitute scarce capabilities that gate competitive positioning, with residency program decline deepening this bottleneck. The analysis identifies divergent strategic imperatives across stakeholder archetypes.
For Market Incumbents: Secure alternative isotope sourcing through accelerator partnership pilots in Canada and Japan to hedge reactor decommissioning risk. Deepen backward integration into sealed-source manufacturing to defend margin position against emerging software-integrated competitors. Prioritize FDA quality-system compliance investments that smaller suppliers cannot absorb, accelerating market consolidation. For New Entrants and Emerging Players: Differentiate on intravesical therapy applications for bladder cancer, the fastest-growing product category with underpenetrated clinical protocols and shorter treatment timelines than systemic chemotherapy. Target French and German university hospital networks establishing dedicated interventional radiotherapy units. Pursue software companion development partnerships with existing imaging platform vendors to bypass capital-intensive hardware manufacturing barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors radioisotope logistics specialists with captive cold-chain infrastructure over pure-play device manufacturers facing substitute modality pressure from stereotactic body radiation therapy. Long-term viability rests on supply security rather than procedural volume growth. Monitor Health Canada and Japanese METI funding commitments to accelerator-based production pilots as inflection indicators for reactor decoupling timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Accelerator-Based Isotope Production Partnership | Decouples supply from Belgian and Dutch reactor geopolitics as decommissioning windows approach. |
| Software-Integrated Service Contract Expansion | Locks recurring revenue through treatment planning subscriptions bundled with source procurement at Nordic centers. |
| CE Marking Pathway Acceleration | Exploits MDR framework clarity to compress European product registration timelines versus historical ambiguity. |
| Hospital System Partnership Consolidation | Captures procurement authority shifting toward German university network blanket agreements. |
| Reimbursement Strategy Development | Secures Medicare code stability for low-dose-rate prostate procedures in United States urology expansion. |
Research Methodology
Desk research of FDA 10 CFR filings, EMA MDR submission databases, and hospital procurement contract records preceded structured interviews with radiation oncology department heads, medical physicists, GPO contracts managers, and radioisotope logistics specialists. Secondary validation drew from reactor production capacity reports, health system capital expenditure disclosures, and professional society residency training data. Bottom-up procedure volume estimates triangulated against top-down market value reconstructions across product type, technology, and application dimensions.
Variance decomposition across the projection horizon isolates volume, price, and mix effects within segment-level growth trajectories. The analytical framework models modality selection, clinical setting, technological sophistication, and regional regulatory cluster as primary segmentation dimensions. CAGRs derive from logistic diffusion curves fitted to technology adoption patterns and demographic-driven incidence projections. Forecast inputs incorporate reactor decommissioning schedules, accelerator pilot facility validation timelines, and MRI-guided platform replacement cycle compression.
Forecasts assume regulatory continuity in FDA 10 CFR Part 32 enforcement and EMA MDR post-market surveillance obligations; material policy shifts would require re-modeling. Radioisotope supply disruptions, reimbursement code revisions, or substitute modality efficacy breakthroughs represent specific risk factors that could revise trajectory assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Metastatic Breast Cancer Market
Oncology
Cancer Supportive Care Products Market
Oncology
Gynecological Cancers Market
Oncology
US Radiation Oncology Market
Oncology
Glottic Cancer Treatment Market
Oncology
Global Metastatic Melanoma Drugs Market
Oncology
Esophageal Cancer Drugs Market
Oncology
Breast Cancer Liquid Biopsy Market
Oncology
North America Tumor Ablation Market
Oncology
Australia Cancer Treatment Market
Oncology
BRCA Mutation-Positive Ovarian Cancer Market
Oncology
Global Neuroendocrine Tumor Treatment Market
Oncology
Europe Radiotherapy Patient Positioning Market
Oncology
Epithelial Ovarian Cancer Market
Oncology
Triple-Negative Breast Cancer Market
Oncology
Immuno-Oncology Clinical Trials Market