
 Congenital Amegakaryocytic Thrombocytopenia (CAMT) Market | 2026-2036
Congenital Amegakaryocytic Thrombocytopenia (CAMT) Market Size, Share, and Industry Trends Forecast 2026-2036
Congenital Amegakaryocytic Thrombocytopenia (CAMT) Market Outlook
Gene therapy manufacturing capacity in the United States is repositioning toward rare hematologic indications as commercial-scale viral vector suites come online. CRISPR Therapeutics leverages its proprietary editing platform to compete in ex vivo stem cell correction protocols. bluebird bio sustains operational expertise from prior lentiviral programs, while Orchard Therapeutics anchors European manufacturing infrastructure for autologous hematopoietic stem cell gene therapy.
Congenital Amegakaryocytic Thrombocytopenia denotes an autosomal recessive bone marrow failure syndrome arising from MPL gene mutations that abolish thrombopoietin receptor signaling, resulting in absent megakaryopoiesis and progressive aplasia requiring allogeneic stem cell transplantation for curative intent. Biological therapies represent the most technically demanding segment, with lentiviral and gene-edited autologous products commanding development resources and extended manufacturing timelines. Pediatric patients constitute the primary addressable population, though adult presentation cases are expanding the treatable cohort as diagnostic sequencing penetrates non-specialist settings.
FDA orphan drug designation and EMA PRIME eligibility shape clinical trial design and market access trajectories for CAMT developers, while HIPAA and GDPR frameworks govern patient registry data essential for natural history studies and post-authorization surveillance. Stakeholders must monitor manufacturing slot allocation against competing rare disease pipelines and evolving payer policies for single-administration curative modalities.
Market Dynamics
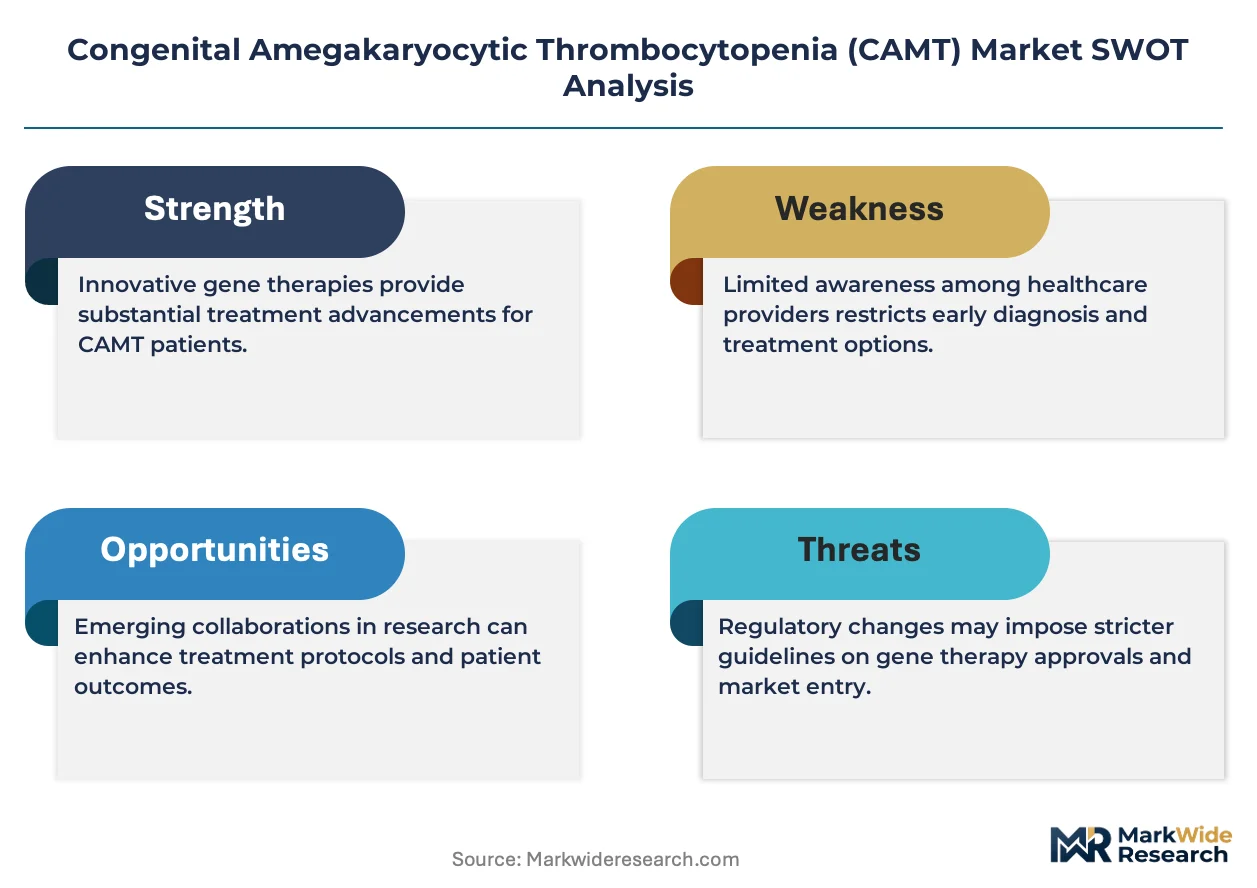
Gene therapy manufacturing capacity constraints are forcing developers to secure viral vector production slots years ahead of clinical milestones, reshaping competitive timelines for autologous hematopoietic stem cell products in ultra-rare indications.
Growth Catalysts
- EMA PRIME Eligibility:Accelerated assessment pathways compress development timelines for bone marrow failure syndromes, enabling earlier patient access to investigational therapies across European pediatric hematology networks.
- Next-Generation Sequencing Penetration:Diagnostic laboratories in the United States and Germany are identifying adult-onset CAMT cases previously misclassified as idiopathic aplastic anemia, expanding the addressable patient base beyond classical pediatric presentation.
- Thrombopoietin Receptor Biology:Advances in understanding MPL signaling pathways enable rational design of gene correction strategies targeting the underlying molecular defect rather than symptomatic management.
Market Restraints
- Plasmid DNA Supply Concentration:Viral vector manufacturing depends on GMP-grade plasmid sourced from a limited supplier base in the United States and Europe, creating input bottlenecks that extend campaign timelines.
- Allogeneic Transplant Competition:Matched sibling donor transplantation remains the established curative standard with decades of outcome data, creating clinical equipoise challenges for gene therapy trial enrollment.
- HIPAA-GDPR Data Friction:Cross-border patient registry harmonization for natural history studies faces compliance complexity, fragmenting longitudinal datasets essential for regulatory submissions.
Strategic Opportunities
- Japan's Sakigake Designation:Priority review incentives for regenerative medicine products create regulatory arbitrage for developers establishing early clinical presence in Asian pediatric hematology centers.
- In-Utero Intervention Models:Preclinical programs exploring fetal hematopoietic stem cell gene delivery could eliminate the need for myeloablative conditioning, opening entirely new therapeutic paradigms.
- Academic Medical Center Partnerships:Vertically integrated gene therapy manufacturing at pediatric transplant centers in Boston, Heidelberg, and Tokyo reduces logistics risk for time-critical autologous products.
Industry Challenges
- Vector Manufacturing Workforce Scarcity:GMP viral vector production requires specialized cell culture expertise that outstrips current training pipeline output in the United States and European Union.
- Post-Authorization Surveillance Infrastructure:Long-term follow-up requirements for integrating vectors demand registry systems capable of tracking patients across decades, straining existing pharmacovigilance frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Congenital Amegakaryocytic Thrombocytopenia (CAMT) Market |
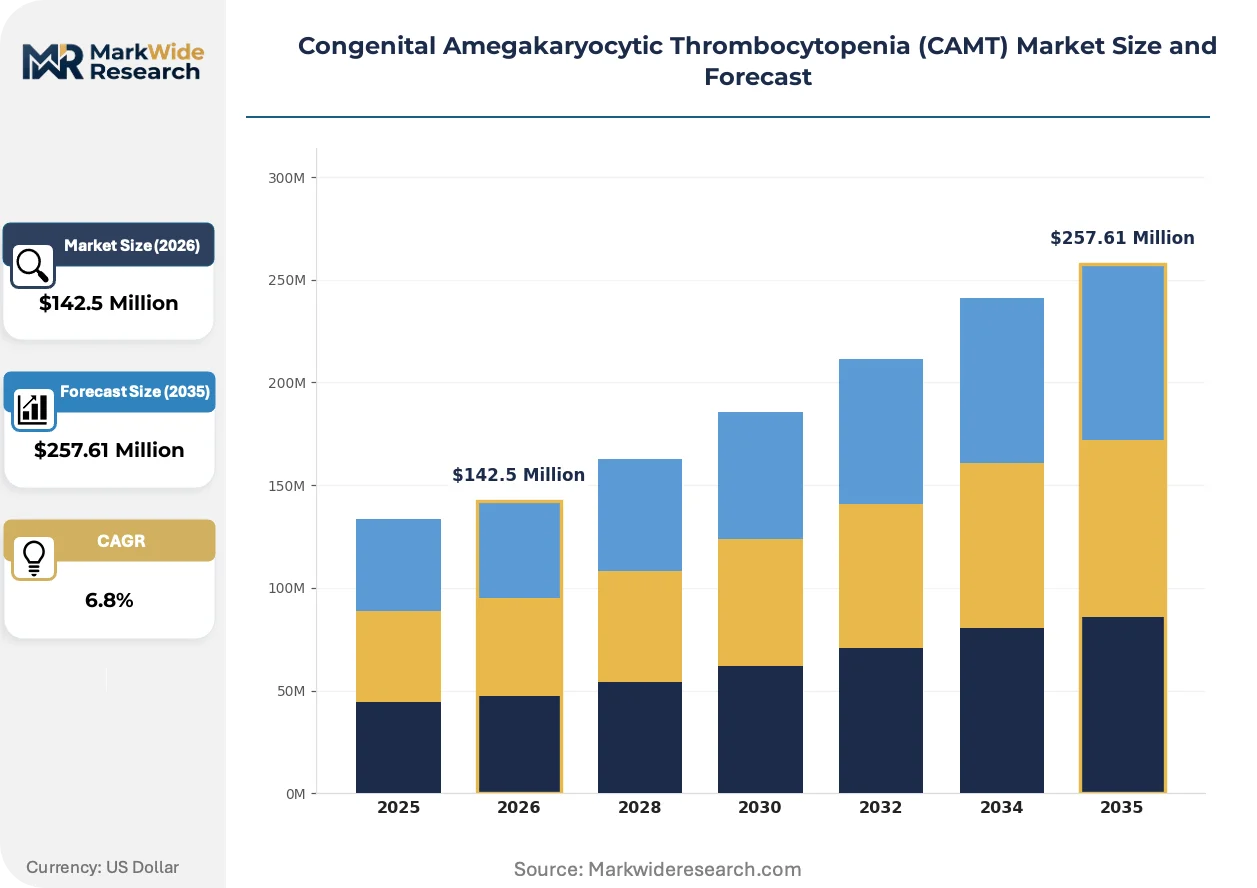
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $257.61 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injections, Infusions, Oral Medications, Biological Therapies Delivery Mode: Subcutaneous, Intravenous, Intramuscular, Oral End User: Pediatric Patients, Adult Patients, Healthcare Providers, Clinics Treatment Strategy: Long-Term Care, Palliative Care, Emergency Treatment, Blood Transfusions |
| Companies Covered | bluebird bio, Orchard Therapeutics, Editas Medicine, CRISPR Therapeutics, Vertex Pharmaceuticals, Sangamo Therapeutics, Novartis, Bristol Myers Squibb, GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Congenital Amegakaryocytic Thrombocytopenia (CAMT) Market Strategic Shifts
Ex vivo stem cell engineering is displacing conventional pharmacologic management in congenital marrow failure, with manufacturing scale-up and regulatory science advancing in parallel across North American and European centers.
CRISPR-based homology-directed repair is converging with optimized electroporation protocols to achieve therapeutic levels of MPL gene correction in hematopoietic stem cells without integrating vector backbone. Academic consortiums in Cambridge and Basel are validating edited cell products through collaborative IND-enabling studies. This convergence is compressing the competitive window for first-generation lentiviral approaches while raising the bar for preclinical proof-of-concept data packages.
FDA's regenerative medicine advanced therapy designation is streamrolling commercial development pathways for curative single-administration products, with breakthrough therapy criteria now routinely applied to ultra-rare hematologic indications. Sponsors are responding by embedding manufacturing quality representatives within clinical operations teams to ensure CMC readiness keeps pace with clinical data generation. Pediatric transplant centers in the United States are restructuring institutional review board processes to accommodate gene therapy trial complexity.
Buyer consolidation among pediatric hematology referral networks is concentrating procurement decisions within a limited number of academic medical centers in the United States, Germany, and Japan. These institutions are establishing dedicated gene therapy pharmacy and therapeutics committees to evaluate single-administration curative modalities against lifetime cost of standard care. The shift is most pronounced in the Northeastern United States, where integrated delivery networks are negotiating outcomes-based arrangements with developers.
Congenital Amegakaryocytic Thrombocytopenia (CAMT) Market Segmentation
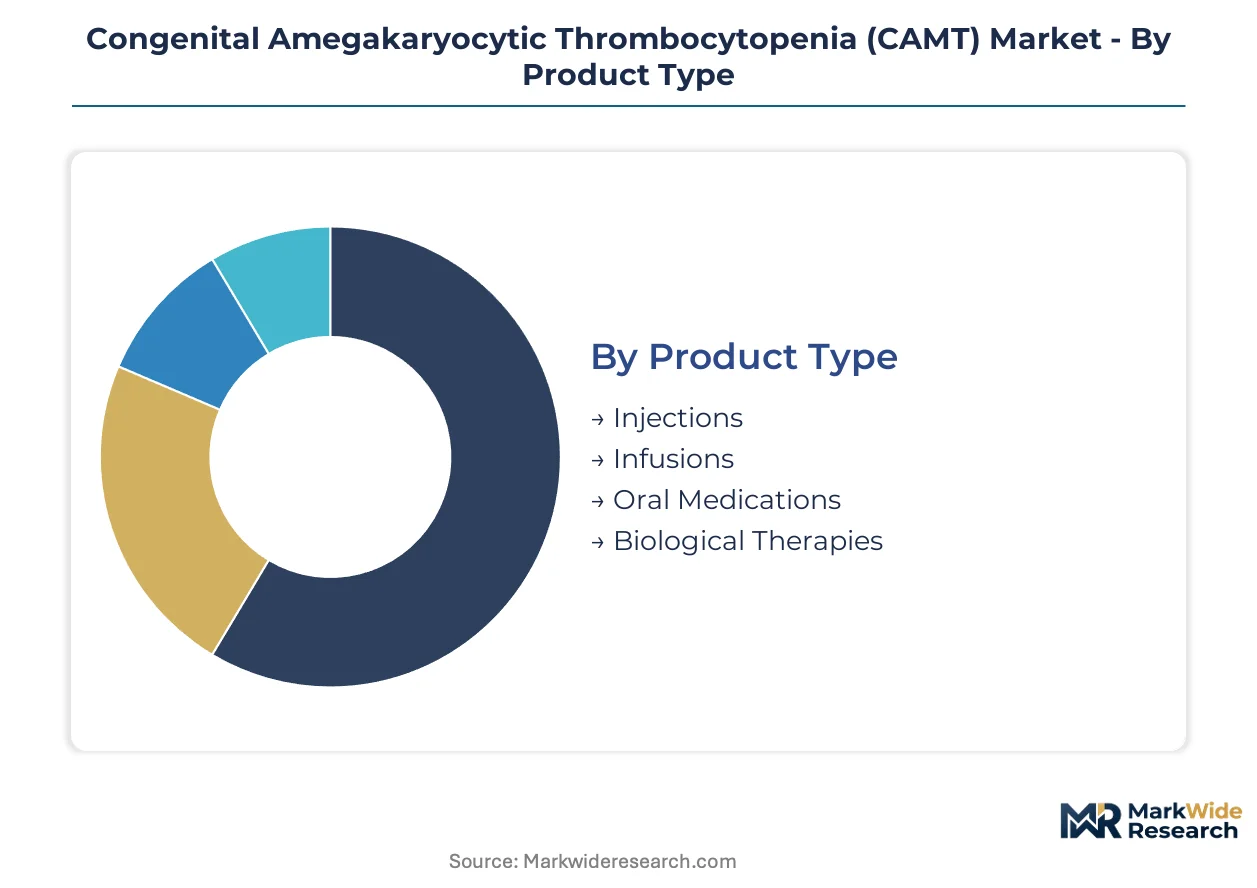
Segmentation in the CAMT market reflects divergent clinical pathways across curative intent versus supportive care. Product architecture and delivery logistics vary sharply between gene-modified cellular therapies and conventional hematologic support.
Product Type:
Customization intensity spans from off-the-shelf pharmacologic agents to patient-specific autologous cellular products requiring GMP manufacturing.
- Biological Therapies:Lentiviral and gene-edited autologous hematopoietic stem cell products demand dedicated viral vector suites and extended manufacturing timelines. Pediatric hematology centers in Boston and Heidelberg anchor demand for these technically demanding modalities.
- Injections:Recombinant thrombopoietin mimetics and supportive hematologic agents provide interim platelet support. Demand concentrates in referral networks managing pre-transplant bridging.
- Infusions:Platelet concentrates and blood products address acute hemorrhagic complications in aplastic crisis.
- Oral Medications:Immunosuppressive protocols and supportive care agents manage complications pending definitive therapy.
Leading the category by volume: Injections. Expanding most quickly: Biological Therapies.
Delivery Mode:
Route selection tracks treatment intent — curative gene therapy requires intravenous stem cell reinfusion, while supportive care leverages accessible administration.
- Intravenous:Essential for autologous stem cell reinfusion following myeloablative conditioning. Academic medical centers in the United States and Germany control capacity for this technically demanding delivery pathway.
- Subcutaneous:Thrombopoietin receptor agonists and supportive hematologic agents enable outpatient management. Adult-onset CAMT cases identified through expanded diagnostic sequencing are deepening demand outside pediatric specialty settings.
- Intramuscular:Immunoglobulin replacement and select supportive agents.
- Oral:Supportive care medications and conditioning regimen components.
Dominant by procedure volume: Subcutaneous. Steepest expansion trajectory: Intravenous.
End User:
Patient population stratification reflects diagnostic timing — classical pediatric presentation versus emerging adult identification.
- Pediatric Patients:Neonatal thrombocytopenia and early marrow failure constitute the historical core addressable population. Specialized transplant centers in the United States, Germany, and Japan concentrate curative intervention capacity.
- Adult Patients:Expanded next-generation sequencing deployment is reclassifying previously idiopathic aplastic anemia cases. Diagnostic laboratories in the United States and Germany are expanding this cohort fastest.
- Healthcare Providers:Pediatric hematologists and transplant specialists coordinate complex care pathways.
- Clinics:Community hematology practices manage stable patients between specialist referrals.
Primary volume concentration: Pediatric Patients. Gaining share fastest: Adult Patients.
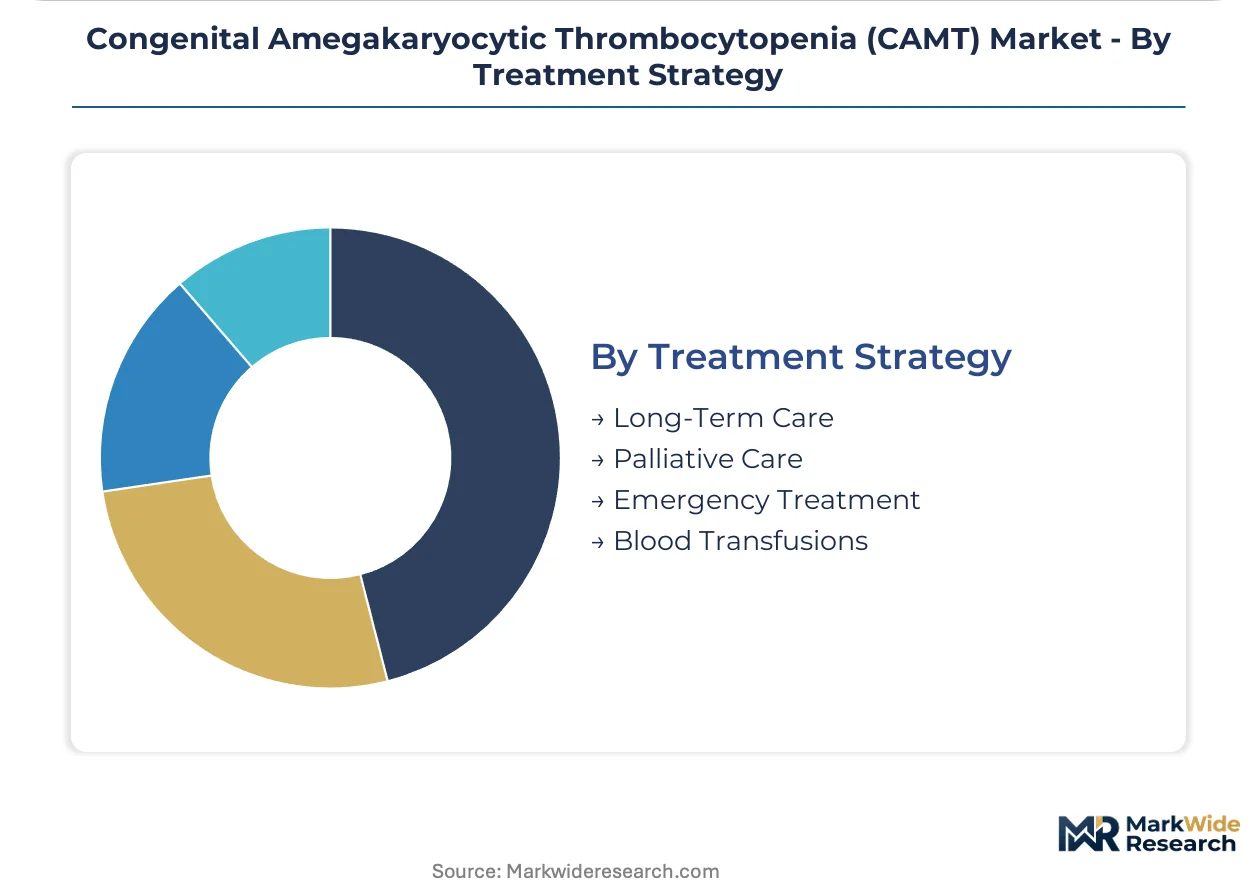
Treatment Strategy:
Strategic allocation spans definitive curative intent through supportive management, with gene therapy repositioning the curative standard.
- Long-Term Care:Comprehensive management spanning diagnosis through transplant or gene therapy. Integrated pediatric hematology networks in the Northeastern United States are restructuring care coordination for these complex pathways.
- Emergency Treatment:Hemorrhage control and aplastic crisis management. Acute presentation in neonatal settings demands immediate platelet support.
- Palliative Care:Symptom management for patients ineligible for curative approaches.
- Blood Transfusions:Platelet and red cell support pending definitive therapy.
Highest resource intensity: Long-Term Care. Fastest protocol evolution: Emergency Treatment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors the viral vector manufacturing corridor that feeds CAMT gene therapy pipelines across North America and Europe. Pediatric hematology centers in this cluster coordinate cross-border patient referral networks and regulatory submissions.
United States
FDA orphan drug designation and breakthrough therapy pathways compress development timelines for MPL-targeted gene therapies. The agency's regenerative medicine advanced therapy framework streamlines commercial readiness reviews. Boston's Longwood Medical Area and the Research Triangle Park concentrate lentiviral vector manufacturing capacity.
Germany
EMA PRIME eligibility accelerates assessment for bone marrow failure syndromes through European pediatric hematology networks. Heidelberg's National Center for Tumor Diseases anchors autologous stem cell processing infrastructure. The country's centralized diagnostic sequencing programs identify adult-onset CAMT cases previously misclassified.
Japan
Sakigake designation for regenerative medicine products creates priority review incentives for developers establishing early clinical presence. Tokyo's National Center for Child Health and Development coordinates pediatric transplant referral networks. PMDA's conditional approval framework enables accelerated patient access to gene-modified cellular therapies.
United Kingdom
Orchard Therapeutics sustains European manufacturing infrastructure for autologous hematopoietic stem cell gene therapy from London and Oxford facilities. The MHRA's innovative licensing pathway supports early access schemes for ultra-rare indications. Cambridge academic consortiums validate CRISPR-edited cell products through collaborative IND-enabling studies.
Switzerland
Swissmedic's expedited access pathway aligns with EMA frameworks while maintaining independent pediatric hematology referral standards. Basel's pharmaceutical research corridor hosts gene editing platform development. The country's centralized health technology assessment coordinates payer negotiations for single-administration curative modalities.
Congenital Amegakaryocytic Thrombocytopenia (CAMT) Market Competitive Environment
Global majors compete with regional champions across gene therapy platform development and viral vector manufacturing capacity. The market structure concentrates around integrated biopharmaceutical groups with lentiviral expertise and specialized gene editing boutiques with platform technologies. Three archetypes dominate: platform technology licensors, integrated vector manufacturers, and transplant medicine incumbents repurposing hematology infrastructure. Competitive moves center on manufacturing slot allocation negotiations and academic medical center partnership structures.
Within the platform technology tier, CRISPR Therapeutics and Editas Medicine exemplify editing-first developers competing in ex vivo stem cell correction protocols. bluebird bio occupies a position reflecting prior lentiviral program expertise, while Orchard Therapeutics anchors European manufacturing infrastructure. Vertex Pharmaceuticals represents the diversified pharmaceutical archetype entering rare hematology through gene therapy acquisitions. These three company types illustrate divergent strategic postures: editing platform specialization, vector manufacturing integration, and therapeutic area diversification.
| Leading Market Players |
|---|
| bluebird bio |
| Orchard Therapeutics |
| Editas Medicine |
| CRISPR Therapeutics |
| Vertex Pharmaceuticals |
| Sangamo Therapeutics |
| Novartis |
| Bristol Myers Squibb |
| GlaxoSmithKline |
| Others |
Value Chain & Pricing Dynamics
Captive manufacturing of lentiviral vectors at academic medical centers in Boston and Heidelberg anchors both supply security and pricing power for gene therapy developers. This backward integration into GMP-grade production insulates slot holders from third-party viral vector price volatility while concentrating procurement leverage among integrated pediatric hematology networks.
Pricing Analysis
Service bundling separates comprehensive manufacturing-plus-clinical-trial packages from unbundled vector-only supply contracts. Three-tier pricing structure across premium, standard, and economy levels tracks GMP certification grade and post-administration monitoring duration. Price differentiation hinges on FDA regenerative medicine advanced therapy designation status and institutional review board coordination services. Cost compression in economy-tier bridging therapies is intensifying because allogeneic transplant centers are consolidating procurement decisions within integrated delivery networks. Pediatric hematology referral networks exhibit lowest price sensitivity due to outcomes-based reimbursement frameworks, while community hematology practices managing adult-onset cases face highest budget constraints.
Supply Chain Analysis
Direct-to-transplant-center channels handle time-critical autologous stem cell reinfusion demand from pediatric hematology networks. GMP-grade plasmid DNA concentrates in the United States and Europe, with viral vector manufacturing drawing from specialized cell culture expertise pools in Germany and Japan. Raw material dependencies center on recombinant thrombopoietin mimetics, myeloablative conditioning agents, and cryopreservation media. Single-source vulnerability in plasmid suppliers creates campaign timeline extension risk. Distribution runs through academic medical center pharmacy and therapeutics committees rather than traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing slot scarcity is forcing consolidation among developers lacking captive viral vector capacity or academic medical center partnerships. Weaker platform technology licensors without integrated GMP infrastructure face acquisition or program abandonment.
For Market Incumbents: To counter CRISPR-edited cell product convergence, bluebird bio and Orchard Therapeutics should deepen backward integration into lentiviral vector production at Boston and Oxford facilities. Capacity addition in Heidelberg anchors European pediatric referral network control. Certification investment in FDA breakthrough therapy coordination services preserves pricing power against emerging editing-platform competitors.
For New Entrants and Emerging Players: The premium-economy price-point gap in supportive thrombopoietin mimetics offers white-space entry before curative gene therapy penetration deepens. Adult-onset CAMT cases identified through expanded diagnostic sequencing in the United States and Germany represent the most penetrable patient segment. Go-to-market execution should target community hematology practices with subcutaneous administration training and payer navigation support.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform technology acquisitions by diversified pharmaceutical groups entering rare hematology. Five-to-ten year viability framing favors developers with EMA PRIME eligibility and Sakigake designation positioning. The signal to watch is manufacturing slot allocation announcements from Boston and Heidelberg GMP facilities as inflection indicators for competitive timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive viral vector capacity at Boston Longwood Medical Area secures pediatric trial enrollment timelines. |
| Regulatory Approval Pathway | FDA regenerative medicine advanced therapy designation streamlines commercial readiness for MPL-targeted products. |
| Licensing Agreement | Platform technology licensors monetize CRISPR editing patents through academic consortium partnerships in Cambridge and Basel. |
| Clinical Trial Advancement | Heidelberg National Center for Tumor Diseases anchors European autologous stem cell processing for IND-enabling studies. |
| Pipeline Diversification | In-utero intervention models at Tokyo National Center for Child Health eliminate myeloablative conditioning requirements. |
Study Parameters
FDA orphan drug designations, EMA PRIME eligibility records, and ClinicalTrials.gov registry entries formed the secondary backbone for pipeline tracking and competitive positioning assessment. Primary interviews with gene therapy manufacturing executives, pediatric hematology transplant specialists, regulatory affairs leads at developers, hospital pharmacy and therapeutics committee chairs, and payer access specialists at integrated delivery networks validated demand assumptions and procurement timeline estimates. Bottom-up patient prevalence modeling and top-down gene therapy revenue projections were triangulated against viral vector manufacturing capacity disclosures.
Bottom-up prevalence estimates across pediatric and adult patient populations were cross-checked against top-down gene therapy addressable market calculations. Segmentation dimensions modeled include product type, delivery mode, end user stratification, and treatment strategy across the analysis window. CAGRs were derived from logistic diffusion curves for curative modalities and linear extrapolation for supportive care segments. Forecast inputs incorporated next-generation sequencing penetration rates and allogeneic transplant waiting list dynamics.
Inputs from FDA and EMA regulatory databases were available through the study window; gaps in long-term post-authorization surveillance registry coverage introduce uncertainty bands around gene therapy adoption curves. Forecasts reflect assumptions regarding manufacturing slot allocation timelines and payer policy evolution for single-administration curative modalities. Periodic stress-testing of base assumptions is recommended against viral vector workforce training pipeline output and cross-border patient registry harmonization progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Warm Autoimmune Hemolytic Anemia Market
Hematology
Multiple Myeloma Market
Hematology
Blood Screening Market
Hematology
Sickle Cell Anemia Market
Hematology
Hematology Analyzers Market
Hematology
Blood Disorder Therapeutics Market
Hematology
Peripheral T-Cell Lymphoma Treatment Market
Hematology
Paroxysmal Nocturnal Hemoglobinuria (PNH) Treatment Market
Hematology
Acute Lymphoblastic Leukemia Market
Hematology
Non-Hodgkin Lymphoma Treatment Market
Hematology
Multiple Myeloma Treatment Market
Hematology
Polycythemia Vera Market
Hematology
Idiopathic Thrombocytopenic Purpura Market
Hematology
Transfusion Dependent Thalassaemia Management Market
Hematology
Global Sickle Cell Disease Treatment Market
Hematology
Global Non-Hodgkin Lymphoma Therapeutics Market