
 Global Non-Hodgkin Lymphoma Therapeutics Market | 2026-2036
Global Non-Hodgkin Lymphoma Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non-Hodgkin Lymphoma Therapeutics Market Analysis
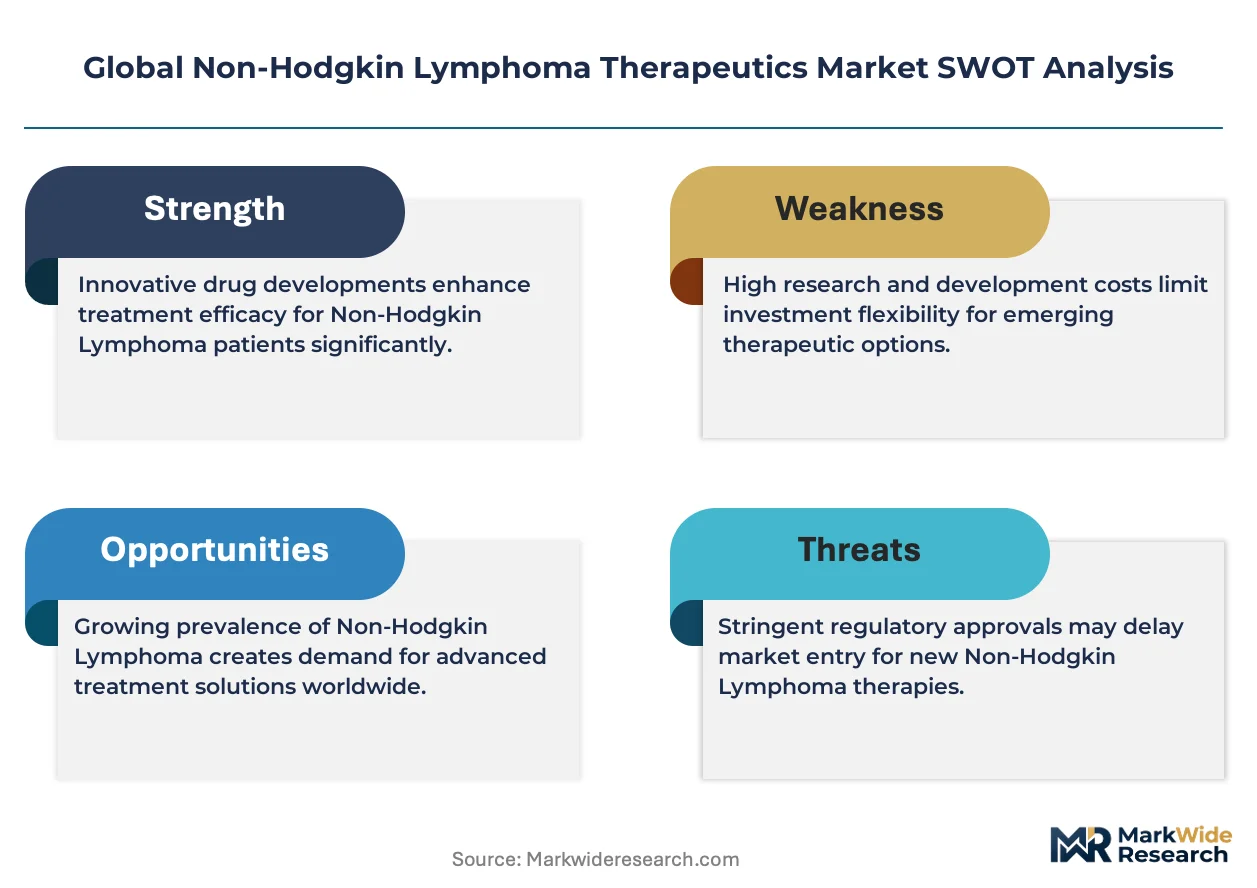
Hospital procurement of chemotherapy regimens is collapsing as specialty clinics expand purchasing of monoclonal antibodies and targeted therapies. Roche dominates biologics manufacturing through its in-house production of rituximab biosimilars. Gilead Sciences anchors its position in CAR-T cell therapy through sustained investment in manufacturing infrastructure. Bristol-Myers Squibb differentiates via checkpoint inhibitor combinations for relapsed refractory cases.
Non-Hodgkin lymphoma therapeutics comprise pharmaceutical agents designed to interrupt malignant B-cell and T-cell proliferation through cytotoxic, immunomodulatory, or targeted mechanisms, typically administered via intravenous infusion in cycles of 21 to 28 days. These agents serve the primary purpose of inducing remission, extending progression-free survival, and enabling stem cell transplantation in aggressive subtypes. Monoclonal antibodies occupy the largest revenue pool due to entrenched rituximab-based protocols across treatment lines. Targeted therapies represent the fastest-expanding segment as Bruton tyrosine kinase inhibitors and PI3K inhibitors displace conventional chemotherapy in indolent forms. Immunotherapy, including CAR-T constructs, commands premium pricing but remains concentrated in tertiary referral centers with apheresis capabilities.
The FDA's breakthrough therapy designation and the EMA's PRIME scheme compress development timelines for novel lymphoma agents, while the EU's MDR tightens post-market surveillance requirements for companion diagnostics used in patient selection. China's NMPA has expanded its priority review pathway for innovative oncology drugs, accelerating market entry for domestic and multinational developers. Stakeholders must monitor evolving reimbursement frameworks for cell therapies across Medicare, NICE, and Japan's Chuikyo as these determine real-world access and commercial viability of next-generation modalities.
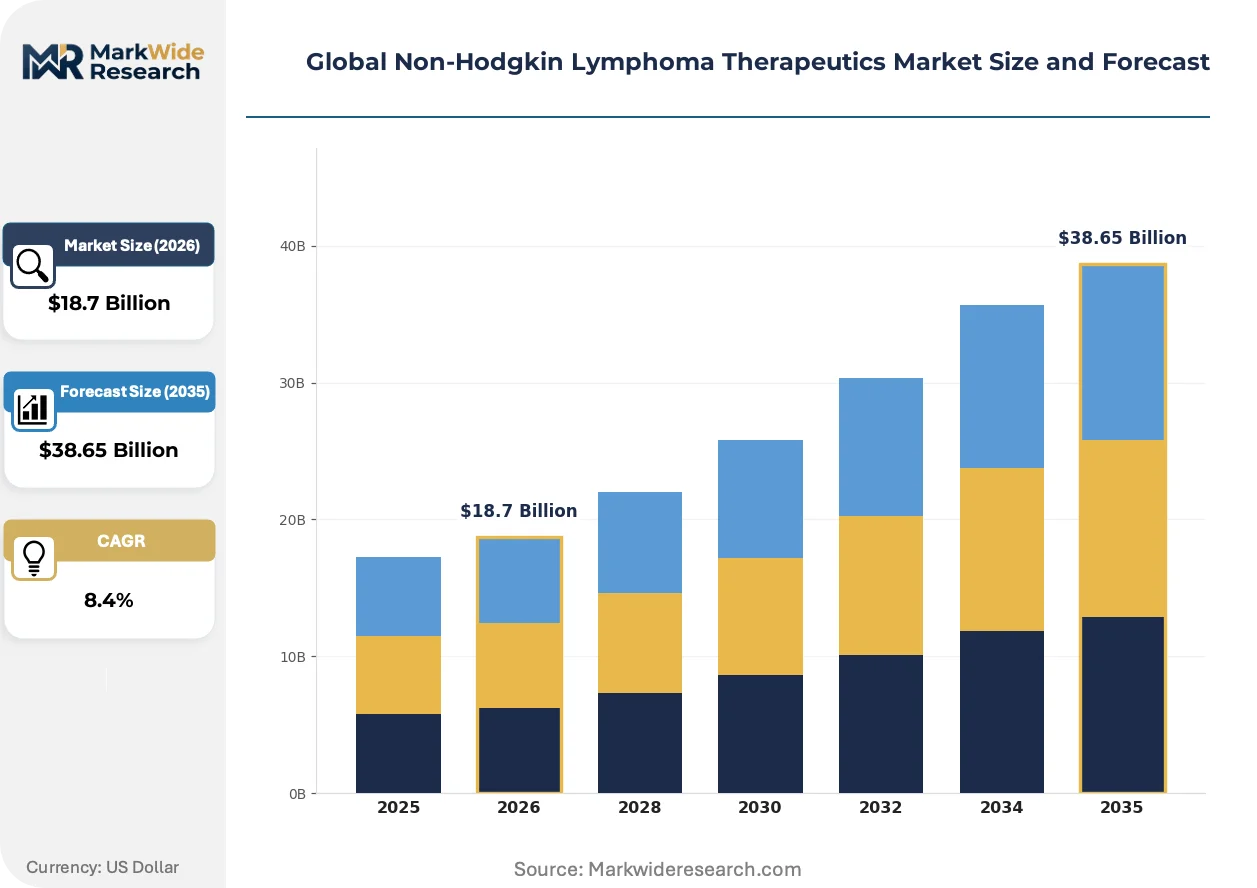
Market Dynamics
FDA breakthrough therapy designations and EMA PRIME schemes are compressing development timelines for novel lymphoma agents while simultaneously fragmenting commercialization strategies across reimbursement jurisdictions.
Growth Catalysts
- Accelerated Regulatory Pathways:The FDA's breakthrough therapy designation compresses Phase II-to-approval timelines for novel mechanisms. Developers leverage this to secure conditional reimbursement ahead of confirmatory trials.
- Specialized Treatment Center Expansion:Tertiary oncology centers in the United States, Germany, and Japan are consolidating CAR-T administration capabilities. These hubs concentrate patient volume sufficient to justify apheresis infrastructure.
- Biomarker-Driven Patient Stratification:Companion diagnostic approvals for CD19, CD20, and BCMA expression levels enable precision enrollment. Pathology laboratories integrate flow cytometry panels into standard diagnostic workups.
Market Restraints
- Plasma Collection Bottlenecks:Leukapheresis capacity constraints in the United States and Europe limit CAR-T manufacturing throughput. Collection center density varies tenfold across metropolitan versus rural catchments.
- Reimbursement Compression:Medicare's new technology add-on payment transitions to standard DRG rates after three years. Hospital margins on cell therapies contract as acquisition costs exceed reimbursement floors.
- Cold Chain Complexity:Cryopreserved cell products require liquid nitrogen logistics from manufacturing through infusion. Temperature excursion events invalidate batches valued at hundreds of thousands per patient dose.
Strategic Opportunities
- Outpatient Administration Models:Community oncology practices in the United States are piloting CAR-T observation protocols outside inpatient settings. Reduced hospitalization days improve total cost of care metrics for payers.
- Allogeneic Platform Development:Off-the-shelf cell therapies eliminate patient-specific manufacturing timelines. Academic medical centers in Japan and South Korea anchor early-phase trials for donor-derived constructs.
- Real-World Evidence Generation:The EU's MDR mandates post-market clinical follow-up for high-risk devices. Developers leverage this requirement to build comparative effectiveness datasets supporting HTA submissions.
Industry Challenges
- Vector Manufacturing Scarcity:Lentiviral and retroviral vector production concentrates at three contract manufacturers globally. Queue times for GMP slots extend to eighteen months for new entrants.
- Interoperability Gaps:Electronic health record systems lack standardized fields for chimeric antigen receptor monitoring. Data fragmentation complicates long-term safety surveillance across treatment centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non-Hodgkin Lymphoma Therapeutics Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Monoclonal Antibodies, Targeted Therapies, Immunotherapy End User: Hospitals, Clinics, Research Institutions, Homecare Settings Administration Route: Intravenous, Subcutaneous, Oral, Intramuscular Drug Class: Corticosteroids, Antimetabolites, Biological Response Modifiers, Others |
| Companies Covered | Roche, Novartis, Gilead Sciences, Bristol-Myers Squibb, AstraZeneca, Takeda Pharmaceutical, Johnson & Johnson, AbbVie, Merck & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non-Hodgkin Lymphoma Therapeutics Market Emerging Trajectories
Next-generation sequencing integration and synthetic biology advances are restructuring how lymphoma therapeutics are discovered, manufactured, and administered across care settings.
Bruton tyrosine kinase inhibitors are decomposing the chemotherapy backbone in mantle cell and marginal zone lymphomas. Community oncologists in the United States now initiate ibrutinib-acalabrutinib sequences before considering cytotoxic regimens. This substitution pattern compresses hospital infusion revenue while expanding oral pharmacy benefit management complexity.
REACH authorization requirements in the European Union impose substance registration obligations on novel small-molecule intermediates. Synthetic route redesign consumes twelve to eighteen months of pre-clinical development. Contract manufacturers in Germany and Switzerland are consolidating active pharmaceutical ingredient production to amortize compliance costs across multiple client programs.
Hospital pharmacy committees now require budget impact models before adding biologics to formularies. United States cancer centers negotiate indication-based pricing contracts that tie reimbursement to progression-free survival thresholds. This value-based purchasing pattern concentrates prescribing authority within institutional review boards at academic medical centers.
Global Non-Hodgkin Lymphoma Therapeutics Market Segmentation
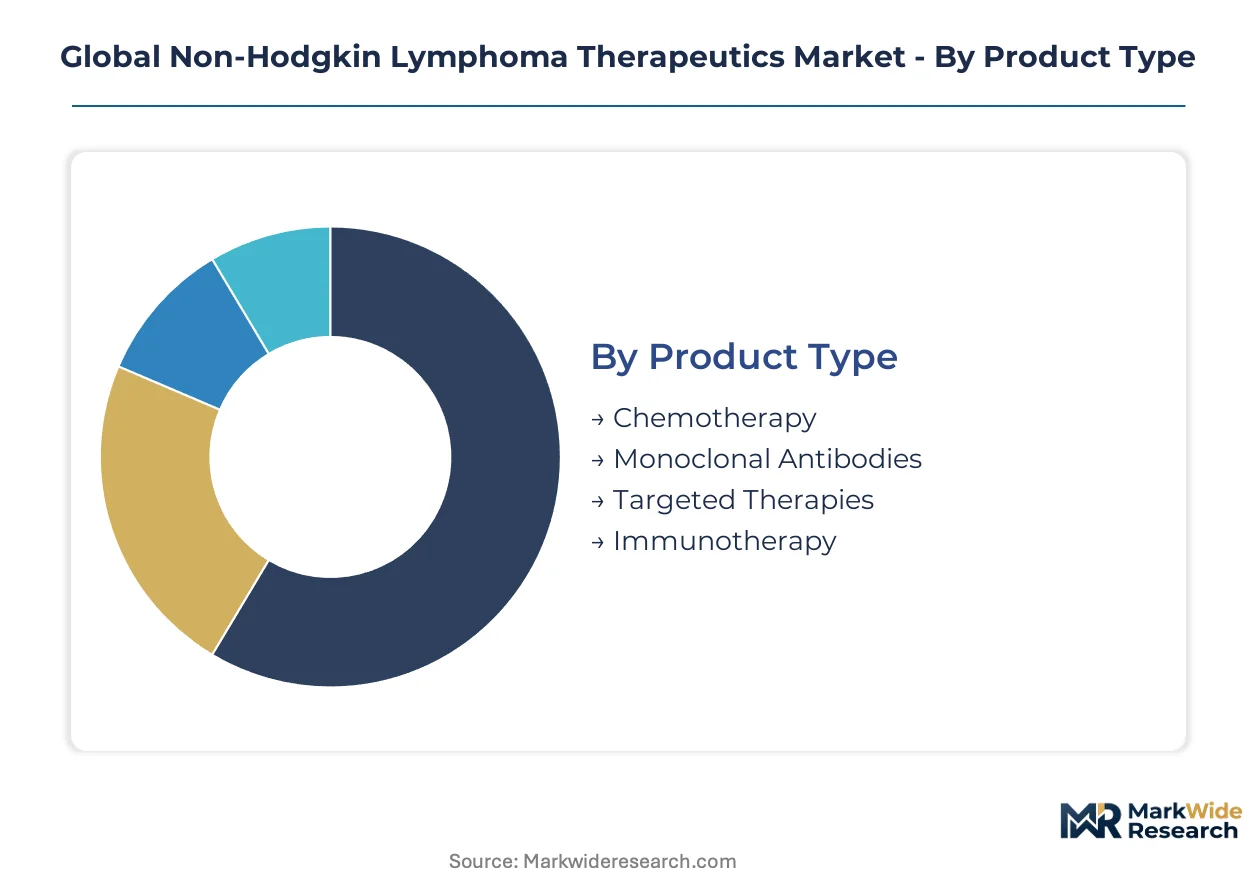
Non-Hodgkin lymphoma therapeutics fragment across four distinct taxonomies that determine pricing power, distribution complexity, and prescriber access. Product type and administration route concentrate margin capture, while end-user configuration shapes logistics requirements and reimbursement pathways.
Product Type:
Margin pools concentrate in biologics manufacturing where process complexity creates natural moats and premium pricing durability.
- Monoclonal Antibodies:Rituximab-based protocols anchor first-line treatment across diffuse large B-cell and follicular subtypes. Hospital formularies in the United States, Germany, and Japan prioritize these agents for their established progression-free survival data and manageable infusion profiles.
- Targeted Therapies:Bruton tyrosine kinase inhibitors and PI3K inhibitors displace chemotherapy in indolent lymphomas through oral administration convenience. Community oncology practices in the United States now initiate ibrutinib-acalabrutinib sequences before cytotoxic regimens, compressing hospital infusion revenue while expanding pharmacy benefit management complexity.
- Immunotherapy:CAR-T constructs command premium pricing contingent on tertiary center apheresis capabilities and cryogenic logistics infrastructure.
- Chemotherapy:Cytotoxic backbones persist in aggressive subtypes and resource-constrained settings where biosimilar rituximab has eroded branded biologic margins.
Monoclonal antibodies hold installed capacity. Targeted therapies are rotating up the share rankings.
End User:
Volume concentration follows CAR-T administration capabilities, which tether high-value procedures to specialized infrastructure.
- Hospitals:Tertiary oncology centers consolidate leukapheresis, cell processing, and inpatient observation for CAR-T therapies. These institutions negotiate indication-based pricing contracts that tie reimbursement to progression-free survival thresholds.
- Clinics:Community oncology practices pilot outpatient CAR-T observation protocols outside inpatient settings. Reduced hospitalization days improve total cost of care metrics for Medicare and commercial payers in the United States.
- Research Institutions:Academic medical centers anchor early-phase trials for allogeneic platform development, particularly in Japan and South Korea.
- Homecare Settings:Oral targeted therapies enable administration outside institutional settings, though cold chain requirements for biologics limit penetration.
Hospitals retain the patient volume concentration. Clinics are climbing the fastest as site-of-care shifts accelerate.
Administration Route:
Supply chain configuration determines cost tier stratification, with cryopreserved cellular products commanding infrastructure investments that oral small molecules bypass entirely.
- Intravenous:Infusion-dependent biologics require hospital-based pharmacy infrastructure and specialized nursing protocols. Medicare DRG reimbursement transitions compress margins as acquisition costs exceed payment floors.
- Oral:Small-molecule inhibitors bypass institutional administration entirely, shifting revenue to specialty pharmacy channels and pharmacy benefit managers.
- Subcutaneous:Fixed-dose formulations reduce infusion chair time and enable administration in lower-acuity settings.
- Intramuscular:Limited application for supportive care agents rather than primary lymphoma therapeutics.
Intravenous holds the reimbursement infrastructure. Oral is gaining share fastest as prescriber preference shifts toward patient convenience.
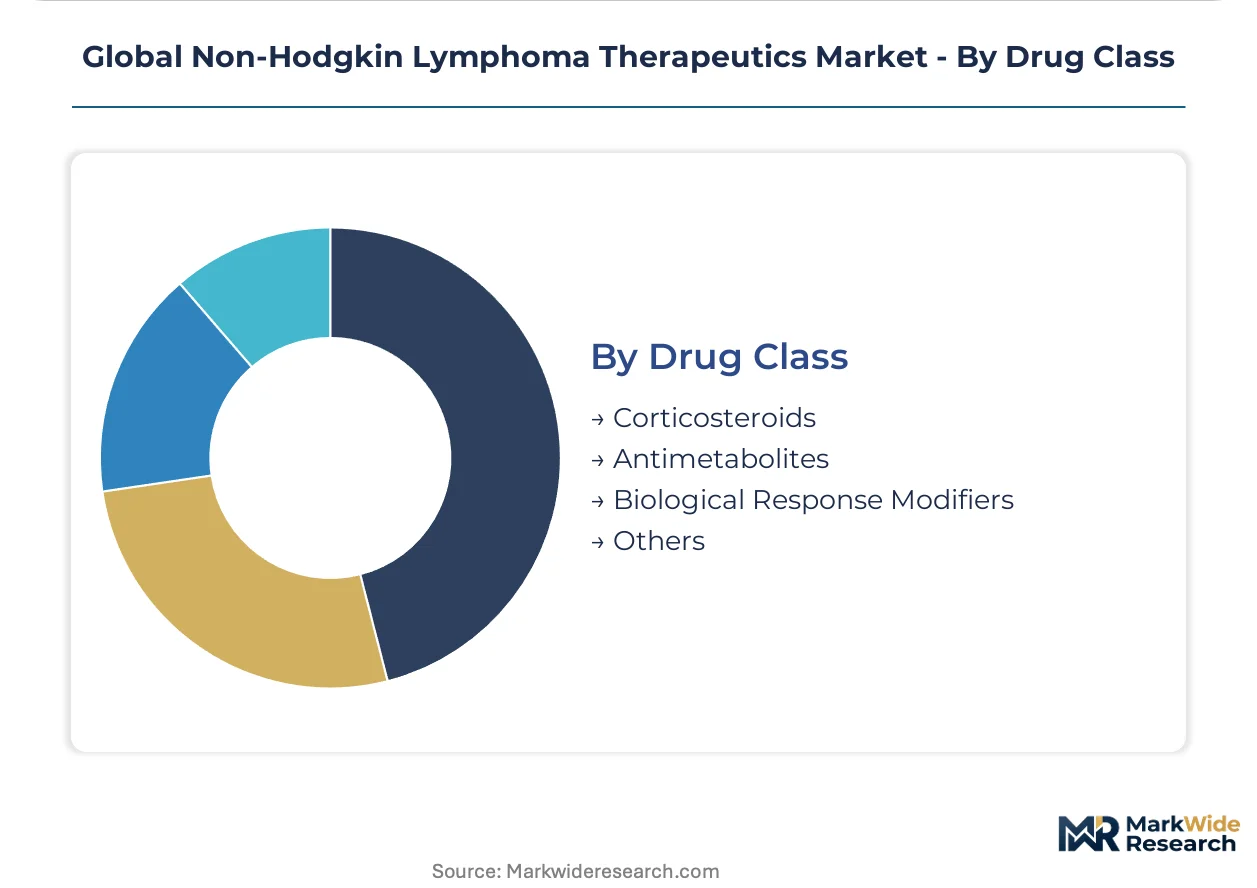
Drug Class:
Development pipelines concentrate on biological response modifiers where mechanism-based differentiation supports premium positioning.
- Biological Response Modifiers:Engineered proteins and cellular constructs command the steepest expansion trajectory as FDA breakthrough therapy designations compress Phase II-to-approval timelines.
- Corticosteroids:Dexamethasone and prednisone remain protocol-mandated components of combination regimens across all lymphoma subtypes.
- Antimetabolites:Purine analogs and folate antagonists persist in specific protocols though biosimilar pressure erodes branded margins.
- Others:Alkylating agents and vinca alkaloids occupy declining share in first-line protocols.
Biological response modifiers anchor pipeline investment. Corticosteroids maintain protocol-embedded volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports active pharmaceutical ingredients and biologics manufacturing equipment to the United States, Japan, and China, anchoring the trade-flow corridor for lymphoma therapeutics. Swiss contract manufacturers supply viral vectors to CAR-T developers across North America and Asia-Pacific. Japanese academic medical centers import apheresis technologies from German and US suppliers.
United States
Hospital-based oncology departments in Houston, New York City, and Boston concentrate leukapheresis capacity for CAR-T administration. The FDA's breakthrough therapy designation compresses Phase II-to-approval timelines for novel mechanisms. The National Cancer Institute's designated cancer centers in Maryland and Texas anchor early-phase trials for allogeneic platform development.
Germany
REACH authorization requirements impose substance registration obligations on novel small-molecule intermediates used in targeted therapy synthesis. Contract manufacturers in Baden-Württemberg and Bavaria consolidate active pharmaceutical ingredient production to amortize compliance costs. The Heidelberg and Munich oncology clusters specialize in biomarker-driven patient stratification for precision enrollment protocols.
Japan
Chuikyo reimbursement frameworks determine real-world access and commercial viability of cell therapies in tertiary referral centers. The PMDA's Sakigake designation accelerates market entry for innovative oncology drugs. Academic medical centers in Tokyo and Osaka anchor early-phase trials for donor-derived allogeneic constructs.
China
The NMPA's priority review pathway accelerates market entry for domestic and multinational developers of Bruton tyrosine kinase inhibitors. Shanghai and Beijing oncology centers expand apheresis infrastructure to support CAR-T manufacturing throughput. Domestic biotech firms in Suzhou and Hangzhou develop rituximab biosimilars for hospital formulary inclusion.
Switzerland
Swissmedic oversees post-market surveillance for companion diagnostics used in CD19 and CD20 expression testing. Basel and Zurich host contract manufacturers specializing in lentiviral and retroviral vector production for cell therapy developers. The country's central logistics position supports cryogenic distribution networks spanning European treatment centers.
Global Non-Hodgkin Lymphoma Therapeutics Market Vendor Landscape
Player mix skews toward integrated biopharmaceutical conglomerates with captive manufacturing infrastructure. The vendor base concentrates around three archetypes: monoclonal antibody specialists with biosimilar portfolios, CAR-T platform developers with apheresis partnerships, and targeted therapy innovators with oral small-molecule pipelines. Dominant competitive moves include indication-based pricing contracts tied to progression-free survival thresholds and backward integration into viral vector manufacturing capacity.
Among Swiss-based biologics manufacturers, Roche anchors the monoclonal antibody tier through in-house production capabilities. Gilead Sciences and Bristol-Myers Squibb occupy positions within the cellular and immuno-oncology archetypes respectively. These three entities exemplify the strategic divergence between biologics manufacturing scale, CAR-T infrastructure investment, and checkpoint inhibitor combination development.
| Leading Market Players |
|---|
| Roche |
| Novartis |
| Gilead Sciences |
| Bristol-Myers Squibb |
| AstraZeneca |
| Takeda Pharmaceutical |
| Johnson & Johnson |
| AbbVie |
| Merck & Co. |
| Others |
Supply Flow & Price Mechanics
Oral small-molecule inhibitors displacing intravenous biologics are redrawing supply geography toward specialty pharmacy channels while compressing hospital-based pricing premiums. This substitution pattern simultaneously fragments distribution networks and erodes the infusion-center margin pools that once anchored revenue capture for institutional providers.
Pricing Analysis
Prior-generation monoclonal antibodies, current-generation Bruton tyrosine kinase inhibitors, and next-generation allogeneic cell therapies operate on divergent pricing architectures. Value-based contracts tie reimbursement to progression-free survival thresholds for CAR-T constructs, while oral targeted therapies command pharmacy benefit management complexity without comparable outcome guarantees. Cost compression in the chemotherapy tier intensifies as biosimilar rituximab saturates hospital formularies. Community oncology practices exhibit highest price sensitivity due to Medicare DRG margin constraints; tertiary academic centers retain lowest sensitivity given apheresis infrastructure amortization.
Supply Chain Analysis
Port congestion on trans-Pacific lanes and container scarcity at Rotterdam and Hamburg elevate inbound logistics costs for cryopreserved cellular products requiring liquid nitrogen maintenance. Active pharmaceutical ingredient production concentrates in Germany, Switzerland, and India, with viral vector manufacturing anchored at contract facilities in Basel and Zurich. Lentiviral vector scarcity, apheresis collection capacity, and cryogenic distribution complexity constitute structural vulnerabilities. Distribution runs through hospital-based pharmacy committees and specialty pharmacy networks with cold chain validation protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive positioning as electronic health record interoperability gaps and real-world evidence mandates force ecosystem-level coordination among developers, diagnostic laboratories, and treatment centers.
For Market Incumbents: Consolidate backward integration into lentiviral vector manufacturing capacity to escape eighteen-month GMP queue times at contract manufacturers. Lock in apheresis partnerships with tertiary oncology centers in Houston, New York City, and Boston to secure patient volume concentration against emerging allogeneic platform threats. For New Entrants and Emerging Players: Lead with outpatient CAR-T observation protocols in United States community oncology practices where site-of-care shifts accelerate fastest. Target Japan's Chuikyo reimbursement frameworks for cell therapy access expansion, leveraging the PMDA's Sakigake designation pathway to compress regulatory timelines relative to European and North American entrants. For Investors and Strategic Acquirers: The market sits at a manufacturing-capacity-constrained phase that favors asset-heavy platform developers with captive GMP infrastructure over pure-play discovery-stage entities. Long-term viability hinges on vector production autonomy and allogeneic pipeline positioning. Watch FDA breakthrough therapy designation velocity as the inflection signal for commercial timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Allogeneic Platform Development | Donor-derived constructs eliminate patient-specific manufacturing timelines and apheresis bottlenecks. |
| Vector Manufacturing Scale-Up | In-house lentiviral production escapes contract manufacturer queue times spanning eighteen months. |
| Companion Diagnostic Integration | CD19 and CD20 expression testing enables precision enrollment and biomarker-driven reimbursement. |
| Outpatient Administration Protocols | Community oncology pilots reduce hospitalization days and improve Medicare total cost of care metrics. |
| Real-World Evidence Infrastructure | EU MDR-mandated post-market follow-up builds comparative effectiveness datasets for HTA submissions. |
Methodological Framework
Operator-level perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists anchored the qualitative base. These primary inputs combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-volume modeling and top-down revenue triangulation across treatment lines, administration routes, and regional regulatory clusters structured the analytical framework.
Sensitivity analysis tested forecast robustness across scenarios varying biomarker-driven patient stratification adoption, CAR-T manufacturing throughput expansion, and oral targeted therapy substitution rates. Segmentation dimensions spanned product type, end-user configuration, administration route, and drug class throughout the projection horizon. CAGRs derived from patent expiry timelines, biosimilar entry curves, and indication expansion pathways for approved agents.
The analysis sits within stated boundaries; outcomes outside sustained FDA breakthrough therapy designation velocity, stable Medicare new technology add-on payment transitions, and resolved vector manufacturing scarcity would require recalibration. Forecasts reflect these embedded assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Blood Plasma Market
Hematology
Mantle Cell Lymphoma Treatment Market
Hematology
Global Hematologic Malignancies Treatment Market
Hematology
Multiple Myeloma Treatment Market
Hematology
Global Bleeding Disorders Market
Hematology
Sickle Cell Disease Market
Hematology
Global Hematology Diagnostics Market
Hematology
Sickle Cell Anemia Market
Hematology
Bleeding Disorders Therapeutics Market
Hematology
Rare Hematology Market
Hematology
Immune Thrombocytopenia (ITP) Market
Hematology
Multiple Myeloma Market
Hematology
Anemia Drugs Market
Hematology
Hemoglobinopathies Treatment Market
Hematology
Congenital Amegakaryocytic Thrombocytopenia (CAMT) Market
Hematology
Lymphoma Treatment Market