
 Sleep Movement Disorders Market | 2026-2036
Sleep Movement Disorders Market Size, Share, and Industry Trends Forecast 2026-2036
Sleep Movement Disorders Market Analytics
Polysomnography-grade diagnostic accuracy is unwinding the historical trade-off between clinical precision and patient accessibility. Teva Pharmaceutical Industries Ltd. leverages its neurology franchise to sustain branded restless legs syndrome therapies against generic erosion. Jazz Pharmaceuticals anchors the narcolepsy-adjacent movement disorder segment with controlled-substance expertise. Pfizer Inc. competes through primary care channel control and broad insomnia-comorbidity prescribing.
Sleep movement disorders comprise involuntary motor phenomena—periodic limb movements, restless legs syndrome, REM sleep behavior disorder, and bruxism—diagnosed via electromyographic channels during nocturnal polysomnography with limb lead placement at 250-500 Hz sampling rates, primarily to prevent sleep architecture fragmentation and cardiovascular comorbidity. The medication segment dominates value pools through dopaminergic agonist maintenance therapy, while wearable devices represent the fastest-expanding technology category as home sleep tests displace in-lab studies for longitudinal monitoring. Homecare end users are capturing share from hospitals as reimbursement shifts favor remote patient management.
The FDA's 510(k) pathway for wearable sleep monitors and CMS reimbursement codes for home sleep testing shape product development priorities and market access conditions for device entrants. EMA's MDR requirements for software-as-medical-device classification impose conformity assessment burdens on European wearable vendors. Stakeholders must monitor whether FDA digital health pre-certification expands to encompass AI-driven movement pattern recognition, as this would redraw competitive barriers between consumer wellness and regulated medical device categories.
Market Dynamics
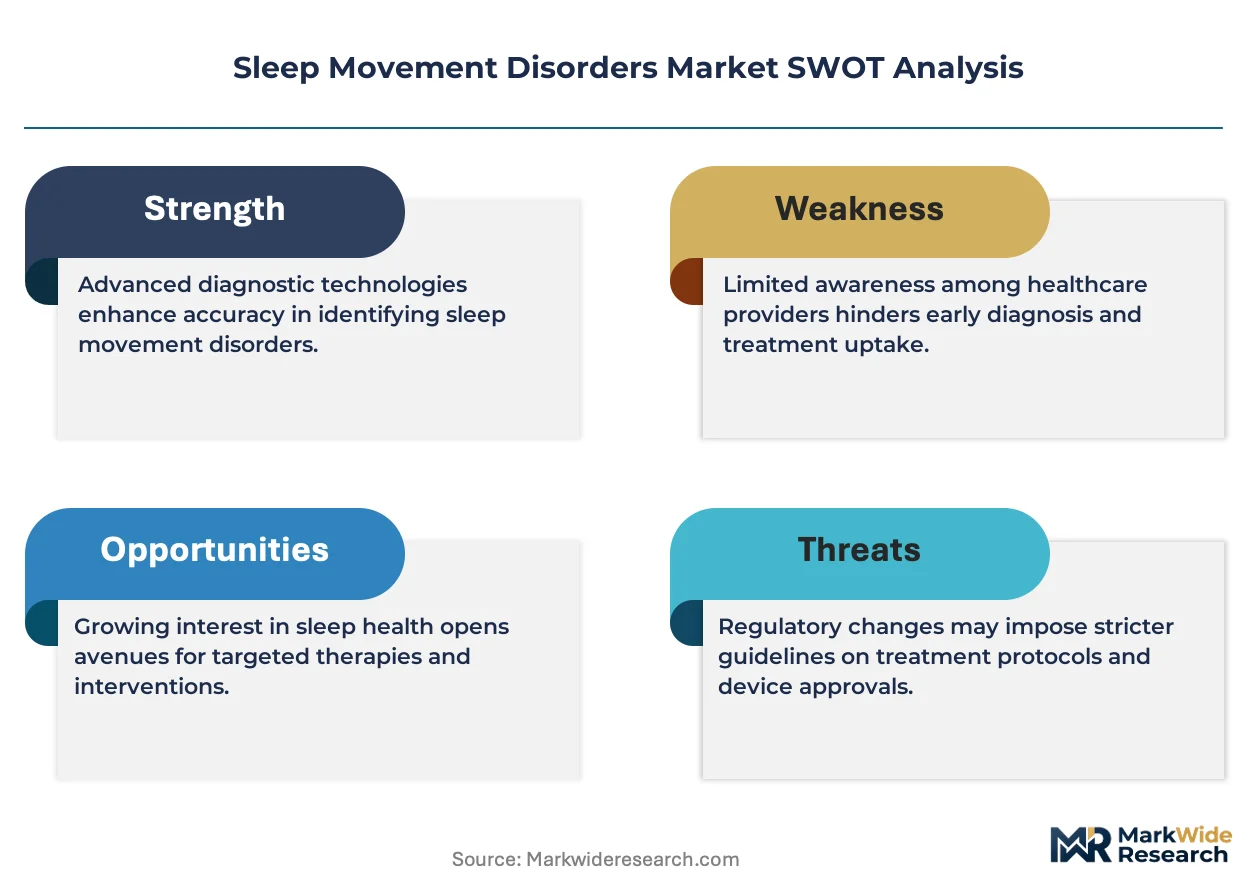
Polysomnography-grade wearables are decomposing the historical trade-off between diagnostic precision and patient accessibility, forcing sleep clinics to reconfigure referral pathways and reimbursement structures around longitudinal home monitoring rather than episodic in-lab studies.
Growth Catalysts
- CMS home sleep testing reimbursement:Medicare coverage expansion for unattended polysomnography accelerates device procurement by independent diagnostic testing facilities across the United States.
- Dopaminergic maintenance protocols:Extended-release pramipexole formulations reduce dosing frequency for restless legs syndrome patients, improving adherence curves in chronic therapy populations.
- Cardiovascular comorbidity screening:Sleep medicine departments in tertiary hospitals integrate periodic limb movement index thresholds into stroke prevention protocols, creating pull-through diagnostic demand.
Market Restraints
- Controlled-substance scheduling:Sodium oxybate's Schedule III designation under the US Controlled Substances Act imposes distribution infrastructure costs and prescriber certification burdens that limit pharmacy channel expansion.
- Sensor calibration drift:Consumer-grade accelerometers in wrist-worn devices exhibit positional artifact susceptibility that degrades periodic limb movement detection accuracy against tibial electromyography reference standards.
- Single-source API concentration:Active pharmaceutical ingredient manufacturing for rotigotine transdermal systems concentrates in Indian contract manufacturers, exposing supply continuity to excipient import licensing delays.
Strategic Opportunities
- EMA MDR software-as-medical-device pathway:Conformity assessment streamlining for AI-driven movement pattern recognition creates first-mover positioning for European wearable vendors against US 510(k) backlog.
- Pediatric sleep medicine expansion:Underpenetrated diagnosis of childhood restless legs syndrome in German university hospital networks offers volume expansion as developmental sleep clinics proliferate.
- Telemedicine-integrated homecare:Remote patient management platforms combining wearable data streams with video consultation reimbursement codes displace traditional sleep center visit models in rural United States markets.
Industry Challenges
- Polysomnography technologist shortage:Registered polysomnographic technologist certification programs produce insufficient graduates to staff expanded diagnostic capacity in US metropolitan sleep centers.
- Legacy EMR integration:Proprietary data formats from wearable sleep monitors require middleware development for seamless ingestion into Epic and Cerner electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sleep Movement Disorders Market |
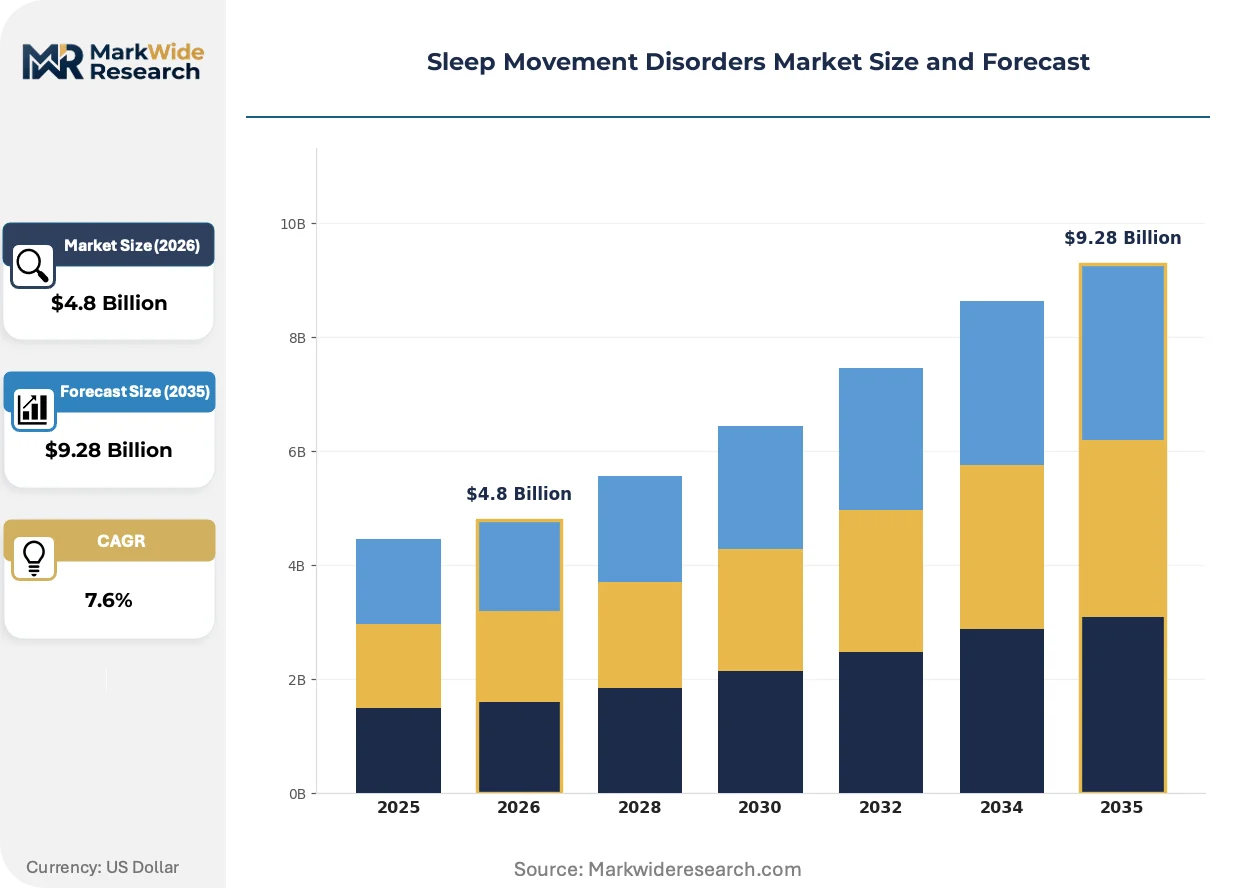
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medication, Device, Therapy, Consultation Technology: Polysomnography, Actigraphy, Home Sleep Tests, Wearable Devices End User: Clinics, Hospitals, Homecare, Research Facilities Application: Diagnosis, Treatment, Monitoring, Patient Education |
| Companies Covered | Pfizer Inc., Teva Pharmaceutical Industries Ltd., Cardinal Health, Inc., Allergan plc, AbbVie Inc., Merck & Co., Inc., Sanofi, Jazz Pharmaceuticals, GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sleep Movement Disorders Market Evolving Landscape
Wearable form factors and machine learning inference are converging to enable diagnostic-grade sleep movement monitoring outside clinical settings, while regulatory frameworks scramble to distinguish medical devices from wellness products.
Photoplethysmography-integrated accelerometry is decomposing the monopoly of in-lab polysomnography for longitudinal sleep architecture assessment. Sleep medicine departments at US academic medical centers are piloting multi-night home protocols for REM sleep behavior disorder screening. This decomposition compresses per-patient diagnostic costs while expanding addressable screening populations beyond geographic proximity to sleep centers.
FDA's evolving 510(k) guidance on home sleep test validation is tightening predicate device comparability requirements for wearable movement monitors. Manufacturers must now demonstrate limb lead electromyography correlation against polysomnography reference standards rather than actigraphy alone. Device entrants are responding by embedding disposable adhesive electrode arrays that bridge consumer convenience with clinical-grade signal acquisition.
Direct-to-employer contracting is disrupting traditional sleep center referral networks in the United States. Self-insured corporations contract with virtual sleep medicine platforms to reduce cardiovascular event costs linked to untreated sleep movement disorders. This channel shift concentrates volume with platforms capable of integrating wearable data into population health dashboards rather than standalone diagnostic facilities.
Sleep Movement Disorders Market Segmentation
Sleep movement disorder interventions fragment across diagnostic precision tiers and care delivery settings. Regulatory pathways distinguish reimbursable medical devices from consumer wellness products, reshaping how each segment captures value.
Product Type:
FDA's 510(k) pathway for devices and DEA scheduling for controlled substances create divergent commercialization timelines across this category.
- Medication:Dopaminergic agonists and alpha-2-delta ligands dominate chronic restless legs syndrome maintenance, with extended-release formulations commanding premium positioning in US Medicare Part D formularies. DEA scheduling requirements for sodium oxybate limit pharmacy channel expansion despite narcolepsy-adjacent movement disorder efficacy.
- Device:Polysomnography-grade wearables bridge clinical precision with home accessibility, capturing fastest volume expansion as CMS reimbursement codes validate unattended diagnostic protocols. EMA MDR software-as-medical-device classification imposes conformity assessment burdens on European entrants that US 510(k) predicates bypass.
- Therapy:Cognitive behavioral interventions for insomnia-comorbid movement disorders concentrate in academic medical center sleep medicine departments.
- Consultation:Telemedicine-integrated virtual sleep medicine platforms displace traditional referral networks through direct-to-employer contracting.
Established volume favors Medication; emerging adoption favors Device.
Technology:
Signal acquisition fidelity determines reimbursement eligibility and clinical adoption velocity across monitoring modalities.
- Polysomnography:Multi-channel electromyography with limb lead placement at 250-500 Hz sampling remains the diagnostic reference standard for REM sleep behavior disorder and periodic limb movement quantification. Registered technologist shortages constrain capacity expansion at US metropolitan sleep centers despite tertiary hospital integration into stroke prevention protocols.
- Home Sleep Tests:Type III and Type IV portable monitors with peripheral arterial tone sensors capture Medicare-reimbursed longitudinal monitoring for cardiovascular comorbidity screening. CMS coverage expansion accelerates procurement by independent diagnostic testing facilities across the United States.
- Actigraphy:Consumer-grade accelerometers face positional artifact susceptibility that degrades periodic limb movement detection accuracy.
- Wearable Devices:Photoplethysmography-integrated accelerometry enables multi-night home protocols for sleep architecture assessment.
Clinical validation concentrates in Polysomnography; steepest expansion trajectory belongs to Home Sleep Tests.
End User:
Reimbursement migration from facility-based to remote patient management reconfigures volume distribution across care settings.
- Homecare:Remote patient management platforms combining wearable data streams with video consultation reimbursement codes displace traditional sleep center visit models in rural United States markets. Direct-to-employer contracting by self-insured corporations concentrates volume with population health dashboard capabilities.
- Clinics:Independent diagnostic testing facilities leverage CMS home sleep testing reimbursement to expand polysomnography-based diagnostic protocols. Sleep clinics reconfigure referral pathways around longitudinal home monitoring rather than episodic in-lab studies.
- Hospitals:Tertiary sleep medicine departments integrate periodic limb movement index thresholds into stroke prevention protocols.
- Research Facilities:Academic medical centers pilot multi-night home protocols for REM sleep behavior disorder screening.
Legacy concentration rests with Clinics; reimbursement tailwinds favor Homecare.
Application:
Diagnostic and monitoring functions capture recurring revenue streams while treatment and education face margin compression from generic substitution and digital commoditization.
- Diagnosis:Polysomnography-grade wearables decompose the historical trade-off between clinical precision and patient accessibility, forcing reconfiguration of referral pathways around home-based screening. FDA's tightening predicate device comparability requirements demand limb lead electromyography correlation against reference standards.
- Monitoring:Longitudinal sleep architecture assessment via adhesive electrode arrays bridges consumer convenience with clinical-grade signal acquisition. AI-driven movement pattern recognition creates first-mover positioning for European wearable vendors against US 510(k) backlog.
- Treatment:Dopaminergic maintenance protocols reduce dosing frequency, improving adherence curves in chronic therapy populations.
- Patient Education:Digital therapeutics platforms face wellness-product categorization that excludes medical device reimbursement.
Recurring revenue concentrates in Monitoring; diagnostic volume anchors Diagnosis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israeli sleep technology developers export wearable diagnostic platforms to United States health systems, while Swiss pharmaceutical manufacturers supply dopaminergic therapies across European hospital networks.
United States
Integrated sleep health networks in Texas and California consolidate fragmented referral pathways through polysomnography-grade home monitoring protocols. FDA's evolving 510(k) guidance on home sleep test validation accelerates wearable device procurement by independent diagnostic testing facilities. Boston's academic medical centers pilot multi-night REM sleep behavior disorder screening protocols that reduce per-patient diagnostic costs.
Germany
Developmental sleep clinics in Bavaria expand childhood restless legs syndrome diagnosis through university hospital network partnerships. EMA's MDR software-as-medical-device classification imposes conformity assessment burdens on wearable vendors seeking European market access. The Rhine-Ruhr metropolitan region concentrates telemedicine-integrated homecare platforms serving rural patient populations.
Japan
PMDA regulatory pathways for AI-driven movement pattern recognition create positioning advantages for domestic wearable manufacturers against US 510(k) backlog. METI supports sleep medicine digitization through reimbursement code expansion for remote patient management. Osaka-based neurology centers integrate periodic limb movement index thresholds into cardiovascular stroke prevention protocols.
United Kingdom
NHS England's sleep service redesign shifts diagnostic volume from hospital-based polysomnography to community home sleep testing. MHRA alignment with FDA predicate device standards tightens wearable validation requirements for limb lead electromyography correlation. London's tertiary hospitals concentrate cognitive behavioral therapy capacity for insomnia-comorbid movement disorders.
India
Contract manufacturing of rotigotine transdermal APIs concentrates in Gujarat and Maharashtra, exposing supply continuity to excipient import licensing delays. CDSCO's evolving medical device rules create classification uncertainty for consumer-grade sleep monitors approaching diagnostic claims. Bangalore's health technology clusters develop middleware solutions for Epic and Cerner EMR integration.
Sleep Movement Disorders Market Competitive Landscape
Listed leaders compete with private specialists across channel access and regulatory certification dimensions. The vendor base organizes around three tiers: multinational pharmaceutical conglomerates with neurology franchises, mid-cap device manufacturers with FDA 510(k) clearance portfolios, and emerging digital health platforms with direct-to-employer contracting capabilities. Consolidation pressure concentrates among device manufacturers seeking predicate device libraries for streamlined regulatory submissions. Strategic moves center on M&A for polysomnography data assets and partnerships with sleep clinic networks for longitudinal patient access.
Among Israel-based pharmaceutical specialists, Teva Pharmaceutical Industries Ltd. exemplifies the branded neurology franchise archetype sustaining market position against generic erosion. Jazz Pharmaceuticals occupies the controlled-substance expertise tier, anchoring narcolepsy-adjacent movement disorder segments through distribution infrastructure investments. Pfizer Inc. represents primary care channel control, competing through broad insomnia-comorbidity prescribing relationships and formulary positioning.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Cardinal Health, Inc. |
| Allergan plc |
| AbbVie Inc. |
| Merck & Co., Inc. |
| Sanofi |
| Jazz Pharmaceuticals |
| GlaxoSmithKline |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day API inventory buffers at Indian contract manufacturers concentrate pricing power with rotigotine transdermal suppliers, while downstream device vendors face margin compression from disposable electrode array costs. This inventory-to-pricing linkage tightens when excipient import licensing delays interrupt active pharmaceutical ingredient flows into European formulation plants.
Pricing Analysis
Hospital procurement committees anchor medication pricing through formulary tier placement negotiations, with extended-release dopaminergic agonists commanding premium positioning against immediate-release generics. Pricing stratifies across FDA 510(k)-cleared wearable tiers, prescription-grade maintenance therapy, and direct-to-employer virtual care bundles. Cost compression in consumer-grade actigraphy reflects positional artifact susceptibility that degrades diagnostic accuracy. Self-insured corporations exhibit lowest price sensitivity for population health dashboard integration, while independent diagnostic testing facilities face acute margin pressure from CMS reimbursement rate stagnation.
Supply Chain Analysis
Just-in-time inventory strategies dominate pharmaceutical finished goods distribution, contrasting with strategic stockpiling of polysomnography electrode arrays by US sleep clinic networks anticipating FDA validation protocol changes. Active pharmaceutical ingredient manufacturing concentrates in India and China, with Swiss and Israeli firms supplying controlled-substance distribution infrastructure. Rotigotine transdermal production draws from Gujarat-based contract manufacturers, while photoplethysmography sensors source from Taiwanese semiconductor foundries. Single-source API concentration creates vulnerability to excipient import licensing delays. Distribution runs through hospital GPO contracts, specialty pharmacy networks, and direct-to-employer virtual care platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recurring revenue from remote patient management software subscriptions expands faster than hardware sales as CMS reimbursement codes validate longitudinal home monitoring protocols. This service-attach dynamic reconfigures competitive moats around data integration capabilities rather than device manufacturing scale.
For Market Incumbents: Consolidate polysomnography data assets through targeted acquisition of AI-driven movement pattern recognition startups, defending against emerging digital health platforms with direct-to-employer contracting capabilities. Deepen backward integration into disposable adhesive electrode manufacturing to capture margin from FDA-mandated limb lead electromyography correlation requirements. Channel control through integrated sleep health network partnerships remains the critical defensive lever against generic erosion in dopaminergic maintenance therapy.
For New Entrants and Emerging Players: Anchor in pediatric sleep medicine expansion across German university hospital networks, where developmental sleep clinics remain underpenetrated for childhood restless legs syndrome diagnosis. Target telemedicine-integrated homecare platforms serving rural United States markets, where video consultation reimbursement codes displace traditional sleep center visit models. Pursue EMA MDR software-as-medical-device pre-certification to bypass US 510(k) backlog and establish first-mover positioning in European wearable markets.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational pharmaceutical conglomerates divesting non-core neurology franchises amid generic erosion pressure. Long-term viability centers on platforms combining diagnostic-grade wearable hardware with recurring software subscription revenue. Monitor FDA digital health pre-certification expansion to AI-driven movement pattern recognition as the inflection indicator redrawing competitive barriers between consumer wellness and regulated medical device categories.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA MDR Software-as-Medical-Device Pathway | Conformity assessment streamlining creates first-mover positioning for European wearable vendors against US regulatory backlog. |
| Hospital System Partnership | Academic medical center alliances secure longitudinal patient access for multi-night REM sleep behavior disorder screening protocols. |
| Reimbursement Strategy | CMS home sleep testing code expansion accelerates procurement by independent diagnostic testing facilities across United States markets. |
| Software Companion Development | AI-driven movement pattern recognition modules differentiate polysomnography-grade wearables from consumer wellness products. |
| CE Marking Pathway | European conformity assessment for adhesive electrode arrays bridges clinical-grade signal acquisition with home accessibility. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with sleep medicine clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EMA MDR submissions, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up triangulation across device shipment data and pharmaceutical prescription volumes converged with top-down spending estimates from integrated sleep health networks.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product type, technology tier, end-user setting, and application function. CAGRs derived from historical growth trajectory analysis and adoption curve projections for home sleep testing protocols. Key inputs incorporated polysomnography technologist shortage constraints, FDA predicate device comparability requirements, and EMA software-as-medical-device classification timelines.
Material uncertainties — regulatory pre-certification timeline shifts, excipient import licensing delays, and wearable sensor calibration drift — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding CMS reimbursement stability and DEA scheduling continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sleep Medicine
Global Sleep Aids Market
Sleep Medicine
Europe Insomnia Market
Sleep Medicine
Asia Pacific Insomnia Market
Sleep Medicine
Global Hypersomnia Treatment Market
Sleep Medicine
Sleep Soother Market
Sleep Medicine
Global Wearable Sleep Trackers Market
Sleep Medicine
Americas Insomnia Market
Sleep Medicine
Hypoventilation Management Market
Sleep Medicine
Excessive Daytime Sleepiness Market
Sleep Medicine
Anti-Snoring Treatment Market
Sleep Medicine
Nasal Pillow Mask Market
Sleep Medicine
Global Sleep Tech Devices Market
Sleep Medicine
Sleeping Bruxism Treatment Market
Sleep Medicine
Sleep Studies Market
Sleep Medicine
Insomnia Treatment Market
Sleep Medicine
Sleep Disorders Treatment Market