
 Chemotherapy-Induced Myelosuppression Treatment Market | 2026-2036
Chemotherapy-Induced Myelosuppression Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Chemotherapy-Induced Myelosuppression Treatment Market Intelligence
The distribution channel through specialized oncology clinics and hospital pharmacies is reconfiguring access to novel supportive care agents. Amgen Inc. leverages its portfolio of established biologics to maintain a dominant position in the growth factors segment. Meanwhile, Teva Pharmaceutical Industries Ltd. competes through its extensive range of generic and specialty pharmaceuticals. Pfizer Inc. sustains its market presence via its broad oncology pipeline and global commercial infrastructure.
Chemotherapy-induced myelosuppression treatment encompasses a range of pharmacological interventions designed to mitigate the cytotoxic effects of chemotherapy on bone marrow. These therapies often target specific hematopoietic cell lineages, such as stimulating granulocyte production to counter neutropenia. Growth factors, particularly granulocyte colony-stimulating factors (G-CSFs), constitute the largest product type segment due to their established efficacy. Subcutaneous delivery modes are gaining preference over intravenous methods in hospital and homecare settings for their convenience and reduced patient burden.
Regulatory frameworks from the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA) dictate the stringent clinical trial endpoints for new drug approvals. Concurrently, guidelines from China's NMPA are shaping the expanding biosimilar landscape in Asia. Navigating the evolving reimbursement policies for both novel biologics and their biosimilar counterparts will be critical for future market positioning.
Market Dynamics
The market's structure is defined by competitive pressure between innovator biologics and the expanding pipeline of biosimilars. This dynamic is accelerated by streamlined approval frameworks from regulators like the US FDA and Europe's EMA, which influence both pricing and market access.
Growth Catalysts
- Biosimilar Approval Pathways:The 351(k) pathway in the US and EMA guidelines lower entry barriers for biosimilar growth factors, increasing treatment accessibility and competition.
- Expanding Oncology Indications:Rising use of intensive chemotherapy for solid tumors in developed nations like Japan and Germany drives demand for myelosuppression management.
- Long-Acting Formulations:Pegylated G-CSFs reduce dosing frequency, enhancing patient compliance and supporting uptake in homecare settings.
Market Restraints
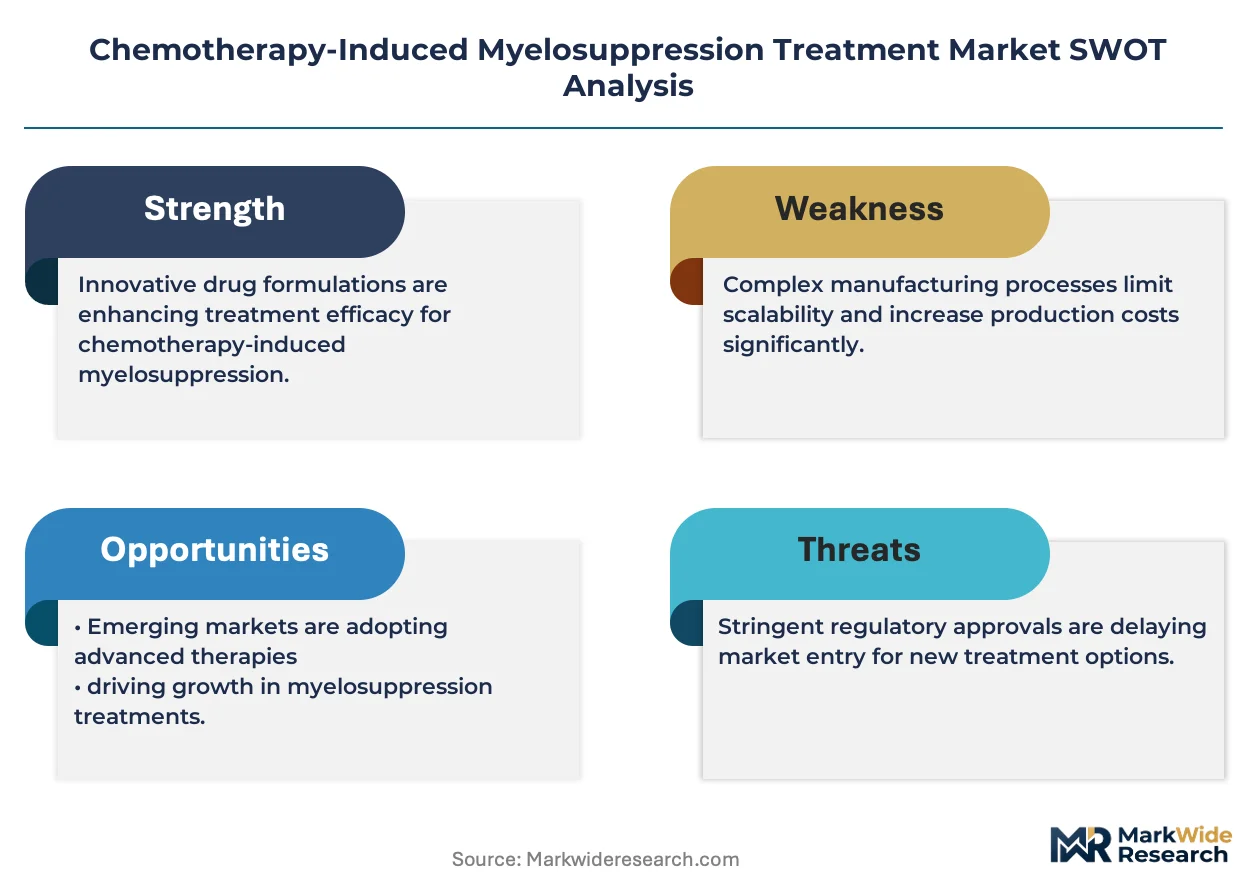
- High Cost of Biologics:The premium price of innovator drugs limits patient access in markets with restrictive reimbursement policies or limited public funding.
- Alternative Management Protocols:Chemotherapy dose reductions or delays by oncologists can substitute the need for pharmacological intervention with growth factors.
- Stringent Clinical Endpoints:Regulatory mandates for proving hematologic recovery endpoints extend development timelines and elevate R&D costs for novel agents.
Strategic Opportunities
- Emerging Asian Markets:China's expanding healthcare access, guided by NMPA regulations, presents an opportunity for both innovator biologics and biosimilars.
- Addressing Thrombocytopenia:Developing treatments for chemotherapy-induced thrombocytopenia (CIT) targets an underserved area with significant unmet clinical need.
- Homecare Delivery Models:The shift to self-administration creates opportunities for patient-friendly autoinjectors that facilitate treatment outside of clinical settings.
Industry Challenges
- Reimbursement Policy Navigation:Manufacturers face complexity in securing favorable reimbursement for biosimilars versus innovator drugs across varied national healthcare systems in Europe.
- Cold Chain Logistics Complexity:Maintaining the integrity of biologic drugs requires an unbroken cold chain from factory to patient, a challenge for subcutaneous homecare delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemotherapy-Induced Myelosuppression Treatment Market |
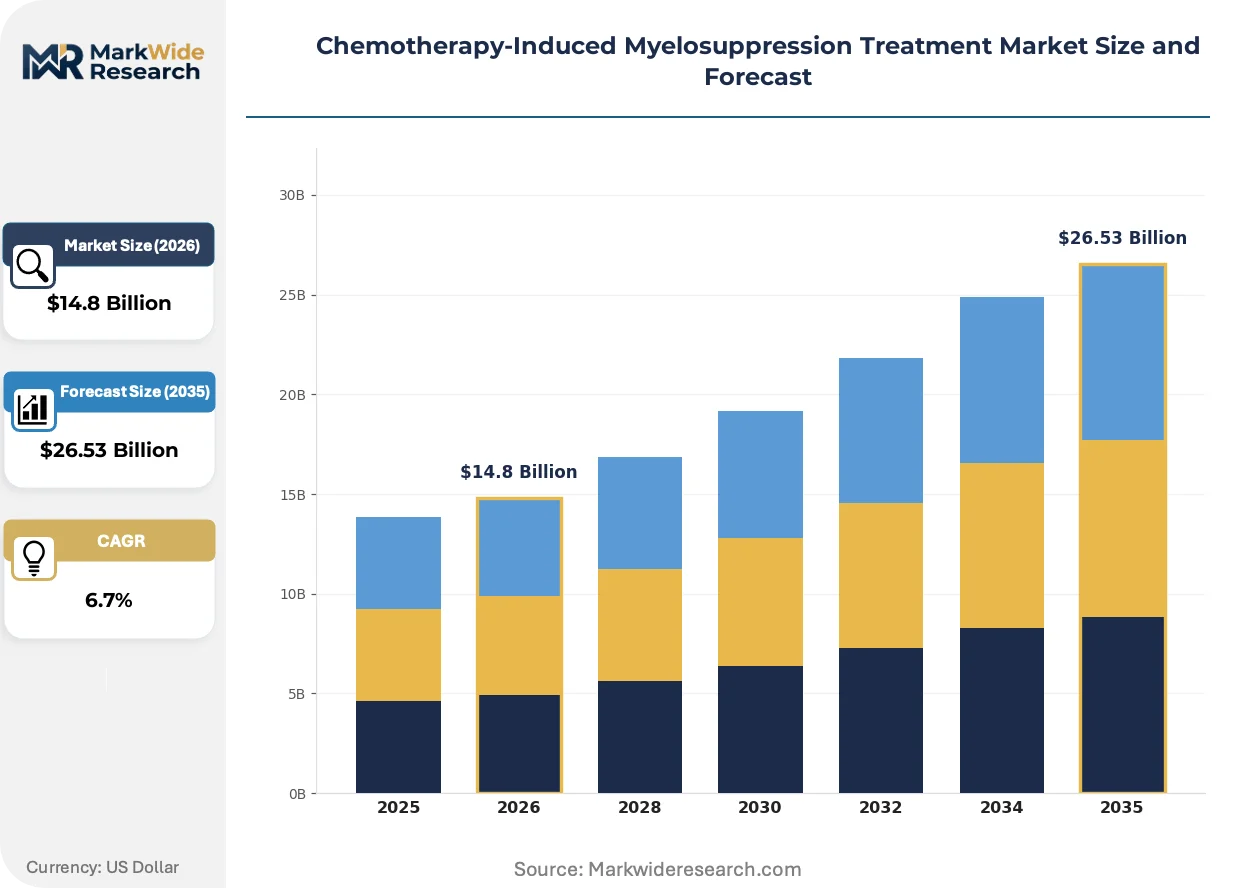
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Growth Factors, Antibodies, Small Molecules, Supportive Care Agents Therapy Area: Oncology, Hematology, Nephrology, General Medicine Delivery Mode: Intravenous, Oral, Subcutaneous, Intramuscular End User: Hospitals, Clinics, Homecare, Ambulatory Surgical Centers |
| Companies Covered | Amgen Inc, Teva Pharmaceutical Industries Ltd, Pfizer Inc, Novartis AG, Janssen Global Services, LLC, Mylan NV, Mission Pharmacal Company, Myelo Therapeutics GmbH, Partner Therapeutics, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemotherapy-Induced Myelosuppression Treatment Market Strategic Shifts & Innovations
A fundamental shift toward personalized supportive care and data-informed decision-making is underway. This evolution prioritizes patient convenience and optimizes therapeutic outcomes through novel drug delivery systems and evolving regulatory standards that encourage innovation.
Patient support platforms and connected autoinjectors provide real-time data to clinicians. Oncology clinics and homecare providers are adopting these tools to track treatment adherence and monitor side effects. This technology is digitizing the management of supportive care, moving it from episodic clinic visits to continuous remote monitoring and intervention.
Regulatory bodies like the EMA are increasingly emphasizing the use of real-world evidence (RWE) in post-approval evaluations. This practice informs the long-term safety and effectiveness assessments of myelosuppression treatments, including biosimilars. Consequently, manufacturers must invest in RWE generation to support market access and reimbursement in European countries.
The model for administering supportive care is moving from provider-centric to patient-centric approaches. This shift disrupts the traditional hospital-based intravenous infusion model in favor of subcutaneous, self-administered formulations. This trend is most visible in developed markets like the US and Germany, where homecare reduces healthcare system costs.
Chemotherapy-Induced Myelosuppression Treatment Market Segmentation
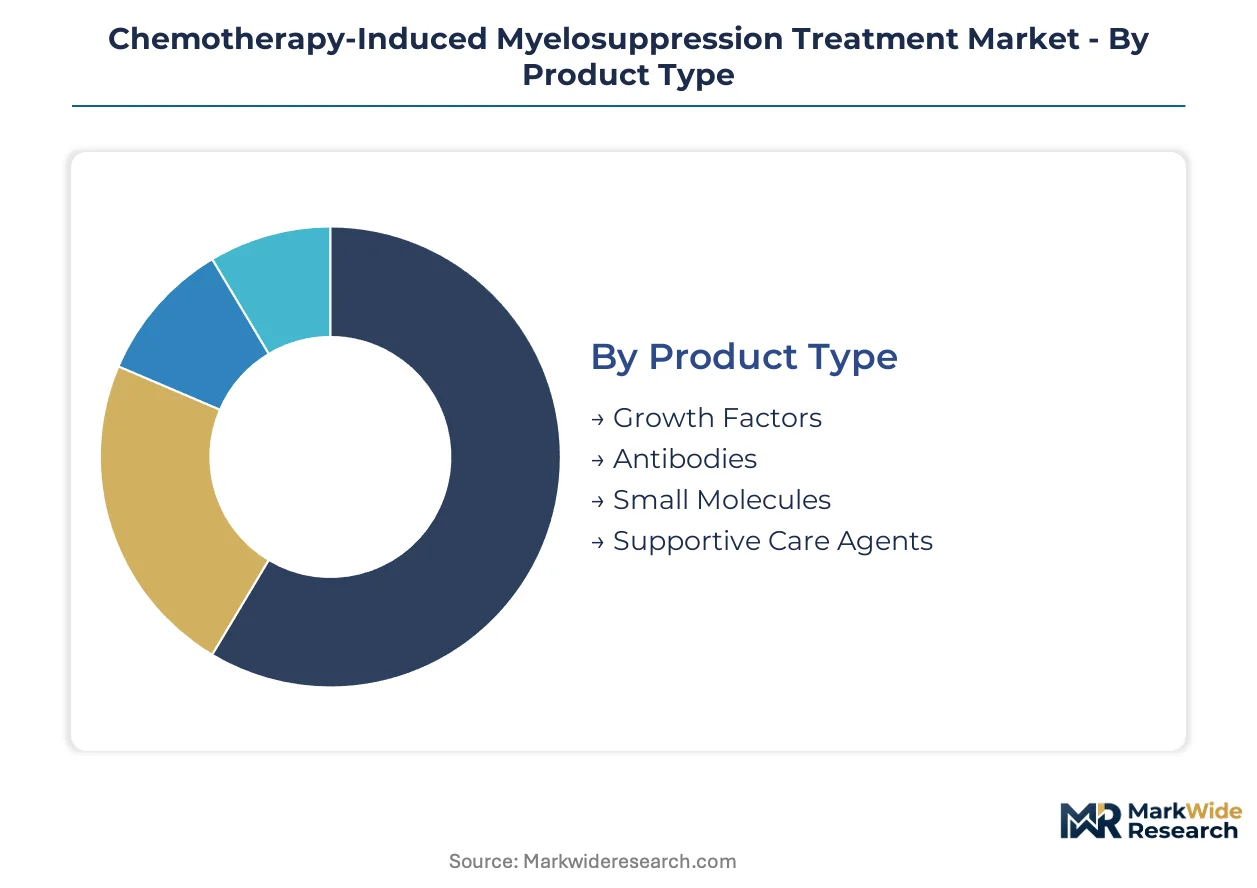
The Chemotherapy-Induced Myelosuppression Treatment Market requires detailed segmentation to understand the diverse therapeutic landscape and patient care pathways. This granular analysis illuminates how different product types, therapy areas, delivery modes, and end-user settings influence treatment accessibility and market dynamics. It also highlights areas of unmet need and emerging growth.
Product Type:
The after-sales service intensity for various product types significantly impacts patient adherence and clinical outcomes.
- Growth Factors:These biologics, such as granulocyte colony-stimulating factors (G-CSFs), stimulate the production of specific blood cells in the bone marrow. Demand concentrates in developed healthcare systems like Japan and Germany, driven by high cancer prevalence and established treatment protocols for neutropenia.
- Antibodies:Monoclonal antibodies can target specific immune cells or signaling pathways involved in myelosuppression, offering precise therapeutic interventions. Adoption is accelerating in advanced oncology centers across Europe, particularly for complex hematological malignancies requiring highly targeted therapies.
- Small Molecules:This category includes chemically synthesized compounds that can modulate bone marrow function or mitigate specific side effects of chemotherapy. These agents often provide oral administration options, improving patient convenience.
- Supportive Care Agents:These treatments encompass a broad range of medications designed to alleviate symptoms and complications of myelosuppression, enhancing patient quality of life. They are widely utilized across all treatment settings.
Growth Factors holds the largest share; momentum sits with Antibodies.
Therapy Area:
Segmentation by therapy area delineates the primary medical applications where myelosuppression treatments are most critically deployed.
- Oncology:This segment involves managing myelosuppression in cancer patients undergoing chemotherapy, particularly for solid tumors and hematological cancers. Demand is highest in regions with advanced cancer treatment infrastructure, such as the US and Germany, where intensive chemotherapy regimens are common.
- Hematology:Treatments within this area focus on blood disorders, including those where bone marrow function is compromised by disease or treatment. Specialized hematology clinics in countries like France and Canada drive significant demand for these interventions.
- Nephrology:Myelosuppression can occur in patients with kidney disease, especially those undergoing dialysis or receiving immunosuppressive therapy. Treatment in this segment addresses specific blood count abnormalities in renal patients.
- General Medicine:This broad category includes myelosuppression cases arising from various non-cancerous conditions or drug toxicities, managed within general hospital settings.
Demand for Oncology remains dominant, while Hematology shows significant expansion.
Delivery Mode:
The volume of treatments administered through different delivery modes reflects evolving patient preferences and healthcare infrastructure capabilities.
- Subcutaneous:This mode involves injecting medication under the skin, increasingly favored for its convenience and suitability for self-administration in homecare settings. Subcutaneous delivery is gaining preference in developed markets like the US and Germany, reducing the burden on hospital resources.
- Intravenous:Administered directly into a vein, intravenous delivery ensures rapid drug absorption and is essential for acute or high-dose treatments. Hospitals and specialized oncology clinics in countries such as the UK and Italy continue to rely heavily on intravenous administration for complex cases.
- Oral:Oral medications offer the highest level of patient convenience, allowing for administration outside of clinical environments. This mode is particularly beneficial for long-term supportive care or less acute myelosuppression.
- Intramuscular:Medications delivered into a muscle provide a sustained release profile, although this method is less common for routine myelosuppression treatment compared to other modes.
The Intravenous approach dominates current patient care, though Subcutaneous is gaining considerable traction.
End User:
Segmentation by end user highlights where chemotherapy-induced myelosuppression treatments are primarily accessed and administered by patients.
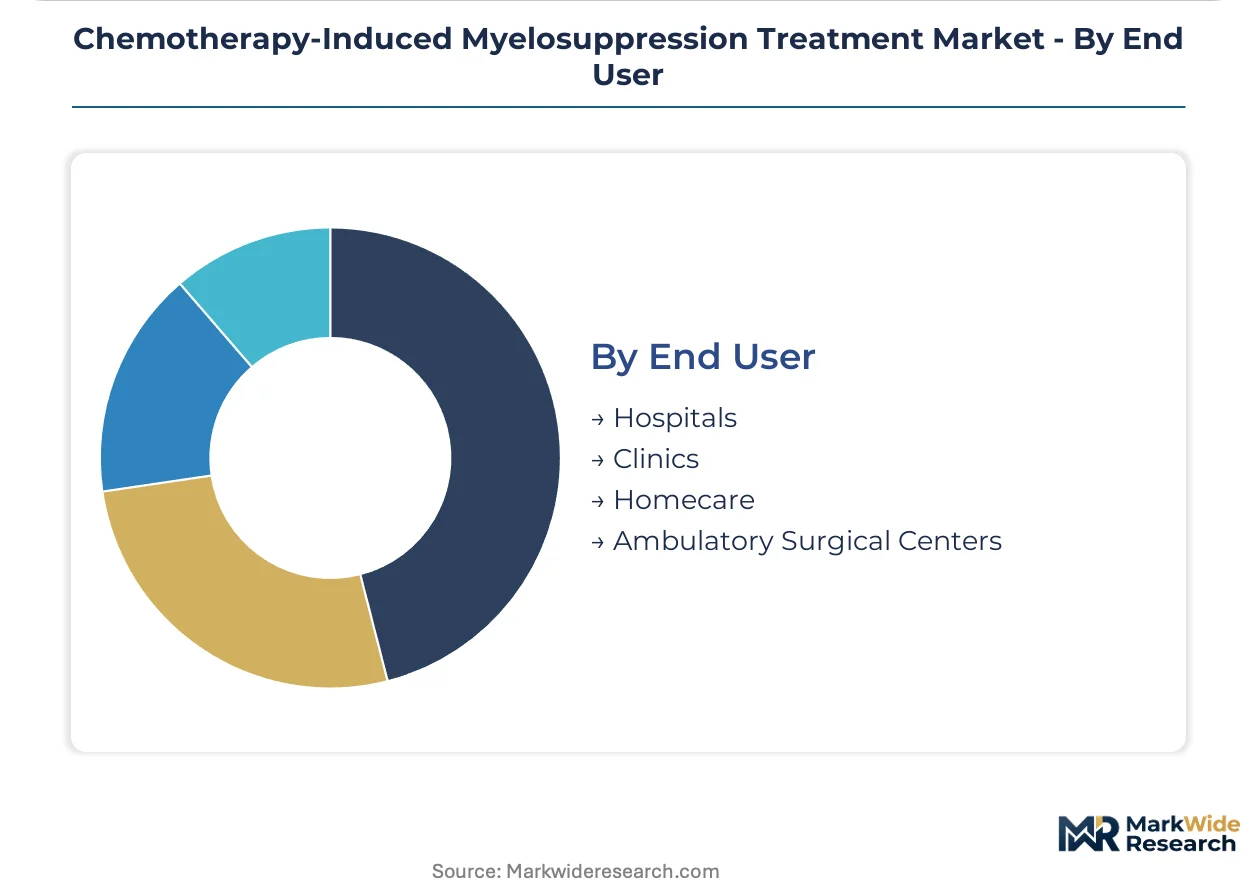
- Hospitals:These institutions serve as primary sites for initial diagnosis, complex chemotherapy regimens, and management of severe myelosuppression complications. Hospitals in major urban centers globally, including Tokyo and London, handle a large volume of these cases.
- Homecare:This setting allows patients to receive treatment and monitoring in their own homes, enhancing convenience and reducing healthcare costs. The shift towards homecare is pronounced in countries with robust home health services, such as the Netherlands and Australia.
- Clinics:Specialized oncology clinics and outpatient facilities provide chemotherapy administration and supportive care, often for less severe or ongoing treatment needs. These clinics are prevalent across all developed healthcare systems.
- Ambulatory Surgical Centers:While less common for myelosuppression treatment, these centers may administer certain supportive care agents or manage minor complications in an outpatient setting.
Hospitals facilities are the primary point of care, but Homecare settings are expanding rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing-power asymmetry shapes market access, with established economies like the United States exhibiting higher biologics pricing power compared to more cost-sensitive European markets where biosimilar competition is more intense. Access to novel therapies for chemotherapy-induced myelosuppression varies significantly across global healthcare systems. Reimbursement policies and regulatory pathways influence treatment availability and adoption rates in different countries.
United States
High cancer prevalence and advanced oncology treatment protocols drive demand for myelosuppression management in the United States. The US FDA's 351(k) pathway facilitates biosimilar entry, increasing treatment options and competition. Major pharmaceutical research hubs in Boston, Massachusetts, and the San Francisco Bay Area, California, continue to innovate in supportive cancer care.
Germany
Germany's robust healthcare infrastructure and high cancer incidence fuel the demand for effective myelosuppression treatments. The European Medicines Agency (EMA) guidelines influence drug approvals, impacting market access for both innovator biologics and biosimilars. Specialized oncology clinics and research institutions in cities like Munich and Berlin are centers for advanced treatment administration.
Japan
An aging population and high cancer prevalence contribute to significant demand for chemotherapy-induced myelosuppression treatments in Japan. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates drug approvals, ensuring high standards for new therapies. Major medical centers in Tokyo and Osaka are at the forefront of adopting new supportive care agents.
China
Expanding healthcare access and a large patient population are driving the chemotherapy-induced myelosuppression treatment market in China. The National Medical Products Administration (NMPA) is streamlining biosimilar approvals, fostering a competitive landscape. Pharmaceutical manufacturing and research clusters in Shanghai and Beijing are developing localized treatment solutions.
France
France maintains strong demand for myelosuppression treatments due to its comprehensive cancer care programs. The Agence Nationale de Sécurité du Médicament et des produits de santé (ANSM) oversees drug regulation, impacting market entry and reimbursement. Leading oncology centers in Paris and Lyon are key sites for clinical trials and advanced patient care.
Chemotherapy-Induced Myelosuppression Treatment Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, focusing on specific therapeutic modalities. The market structure for chemotherapy-induced myelosuppression treatment exhibits a tiered competitive landscape. Innovator biologics manufacturers, specialty pharmaceutical companies, and generics producers form distinct strategic archetypes. Competitive moves center on portfolio diversification into biosimilars and strategic partnerships for global commercialization.
Within the innovator biologics segment, Amgen Inc. and Pfizer Inc. exemplify companies with established portfolios and broad oncology pipelines. Teva Pharmaceutical Industries Ltd. occupies a position among specialty pharmaceutical companies, leveraging its extensive range of generic and specialty pharmaceuticals. These companies anchor market presence through product development and global commercial infrastructure.
| Leading Market Players |
|---|
| Amgen Inc |
| Teva Pharmaceutical Industries Ltd |
| Pfizer Inc |
| Novartis AG |
| Janssen Global Services, LLC |
| Mylan NV |
| Mission Pharmacal Company |
| Myelo Therapeutics GmbH |
| Partner Therapeutics, Inc |
| Others |
Cost & Logistics Intelligence
Global cold chain pharmaceutical freight corridors, crucial for biologics, drive significant cost dynamics that influence supply concentration and downstream price differentiation across regions. These specialized logistics networks ensure product integrity, but their operational expenses contribute to the final cost structure of chemotherapy-induced myelosuppression treatments.
Pricing Analysis
Innovator biologics command a significant premium over biosimilar and generic counterparts, establishing a clear customization-premium spread. Value-based pricing models often dictate the cost of novel biologics, reflecting their clinical efficacy. Regulatory approval status and patient support programs act as key price differentiation drivers. Pricing pressure intensifies from expanding biosimilar market entry and restrictive national reimbursement policies. Public healthcare systems exhibit high price sensitivity, while private payers often absorb higher costs for advanced therapies.
Supply Chain Analysis
Extended payment terms for active pharmaceutical ingredients (APIs) suppliers are common, impacting manufacturer working capital requirements. The supply chain for these treatments concentrates significantly in China and India for APIs, alongside specialized European facilities for complex biologics manufacturing. Key raw material dependencies include specialized excipients and pre-filled syringe components. Cold chain logistics complexity poses a structural risk, particularly for temperature-sensitive biologics. Distribution runs through hospital pharmacies and specialized oncology clinics, with homecare providers gaining importance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chemotherapy-induced myelosuppression treatment is at a platform-economics inflection point, driven by the integration of patient support platforms with connected autoinjectors.
For Market Incumbents: Harden existing market positions through strategic biosimilar portfolio expansion, mitigating the threat from generic competition. Invest in research and development for novel targets like chemotherapy-induced thrombocytopenia to address unmet clinical needs. Leverage existing global commercial infrastructure to optimize market access in emerging regions. Consolidate market share through robust patient support programs and integrated digital health solutions.
For New Entrants and Emerging Players: Build out niche product lines targeting underserved myelosuppression indications like thrombocytopenia. Emerging Asian markets, particularly China with its NMPA regulations, represent a penetrable geographic segment for biosimilar growth factors. Focus on developing patient-centric delivery systems, such as autoinjectors for homecare settings. A compelling go-to-market angle involves digital health integration for remote monitoring and adherence tracking.
For Investors and Strategic Acquirers: Specialized biotechnology firms developing novel cell-line stimulating factors represent attractive long-term acquisition targets. The market offers sustained demand over the next decade due to aging populations and increasing cancer prevalence. Acquisition targets should possess advanced pipeline assets or innovative drug delivery technology. Successful Phase 3 clinical trial readouts for novel agents provide a critical signal for investment inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement for CIT | Addressing chemotherapy-induced thrombocytopenia expands market reach into an underserved therapeutic area. |
| NMPA Regulatory Pathway Focus | Streamlined approvals in China provide accelerated access to a rapidly expanding patient population. |
| Digital Health Platform Integration | Enhancing patient adherence and remote monitoring capabilities improves treatment outcomes and convenience. |
| Biosimilar Manufacturing Scale-Up | Increased production capacity for biosimilars lowers costs, expanding access in price-sensitive markets. |
| Pipeline Diversification Beyond G-CSFs | Developing treatments for other hematopoietic cell lineages reduces reliance on granulocyte-stimulating factors. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through extensive primary interviews, complemented by rigorous secondary validation. Oncologists, hematologists, hospital pharmacists, and regulatory affairs specialists provided critical insights into market dynamics. FDA filings, EMA submissions, ClinicalTrials.gov, and specialized industry reports formed the backbone of secondary data. Bottom-up market sizing and top-down validation ensured data accuracy and comprehensive coverage.
Market volume and value outputs were calibrated using a robust analytical framework across the analysis window. Segmentation dimensions including product type, therapy area, delivery mode, end-user settings, and regional regulatory frameworks were modeled. Compound annual growth rates were calculated from historical data and projected trends. Cancer incidence rates and chemotherapy adoption patterns informed future projections for treatment demand.
Stress conditions across cancer prevalence and reimbursement policy shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding regulatory stability and technological advancements within the sector. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Multiple Myeloma Market
Hematology
Peripheral T-Cell Lymphoma Treatment Market
Hematology
Hemocytometer Market
Hematology
Multiple Myeloma Therapeutics Market
Hematology
Myelodysplastic Syndrome (MDS) Treatment Market
Hematology
Burkitt Lymphoma Treatment Market
Hematology
Sickle Cell Treatment Market
Hematology
Global Bleeding Disorders Market
Hematology
Apheresis Market
Hematology
Small Lymphocytic Lymphoma Market
Hematology
Thalassemia Treatment Market
Hematology
Bone Marrow Transplant Market
Hematology
Alpha Thalassemia Market
Hematology
Hematologic Malignancies Market
Hematology
Pancytopenia Market
Hematology
Langerhans Cell Histiocytosis Management Market