
 Lymphoma Treatment Market | 2026-2036
Lymphoma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Lymphoma Treatment Market Intelligence
The skill gap between academic cell therapy research and commercial-scale manufacturing proficiency is collapsing. F. Hoffmann-La Roche leverages its extensive oncology portfolio and global diagnostic network to maintain a strong market presence. Bristol-Myers Squibb specializes in immunotherapies, particularly its portfolio of CAR-T cell treatments for various lymphoma types. Novartis AG differentiates through its pioneering work in gene therapies and targeted agents for hematological malignancies.
Lymphoma treatment encompasses medical interventions designed to inhibit or destroy cancerous lymphocytes. These advanced therapies often function by targeting specific cell surface antigens like CD20 or by disrupting cancer cell signaling pathways. Monoclonal antibodies and targeted therapy agents constitute the most significant product segments due to their efficacy and specificity. Non-Hodgkin Lymphoma drives the majority of treatment volume within therapy areas, reflecting its higher prevalence compared to Hodgkin Lymphoma.
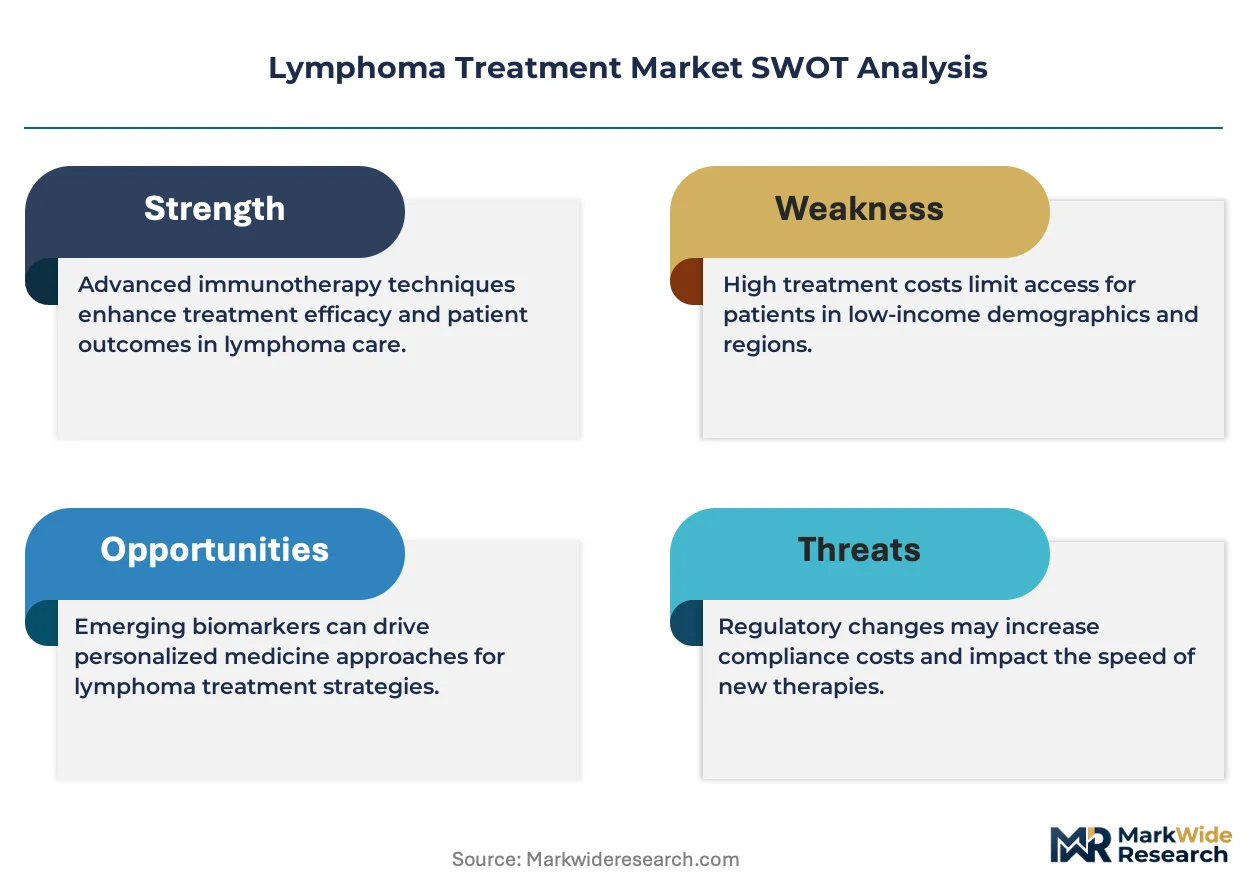
Regulatory bodies such as the US FDA, the European Medicines Agency (EMA), and China's NMPA establish the stringent clinical trial and approval requirements for new lymphoma drugs. These agencies' frameworks for accelerated approvals, like the Breakthrough Therapy Designation, directly influence the speed of market access for innovative therapies. Stakeholders must now decide how to balance investments in broadly applicable chemotherapies against highly specialized but costly cell and gene therapies.
Market Dynamics
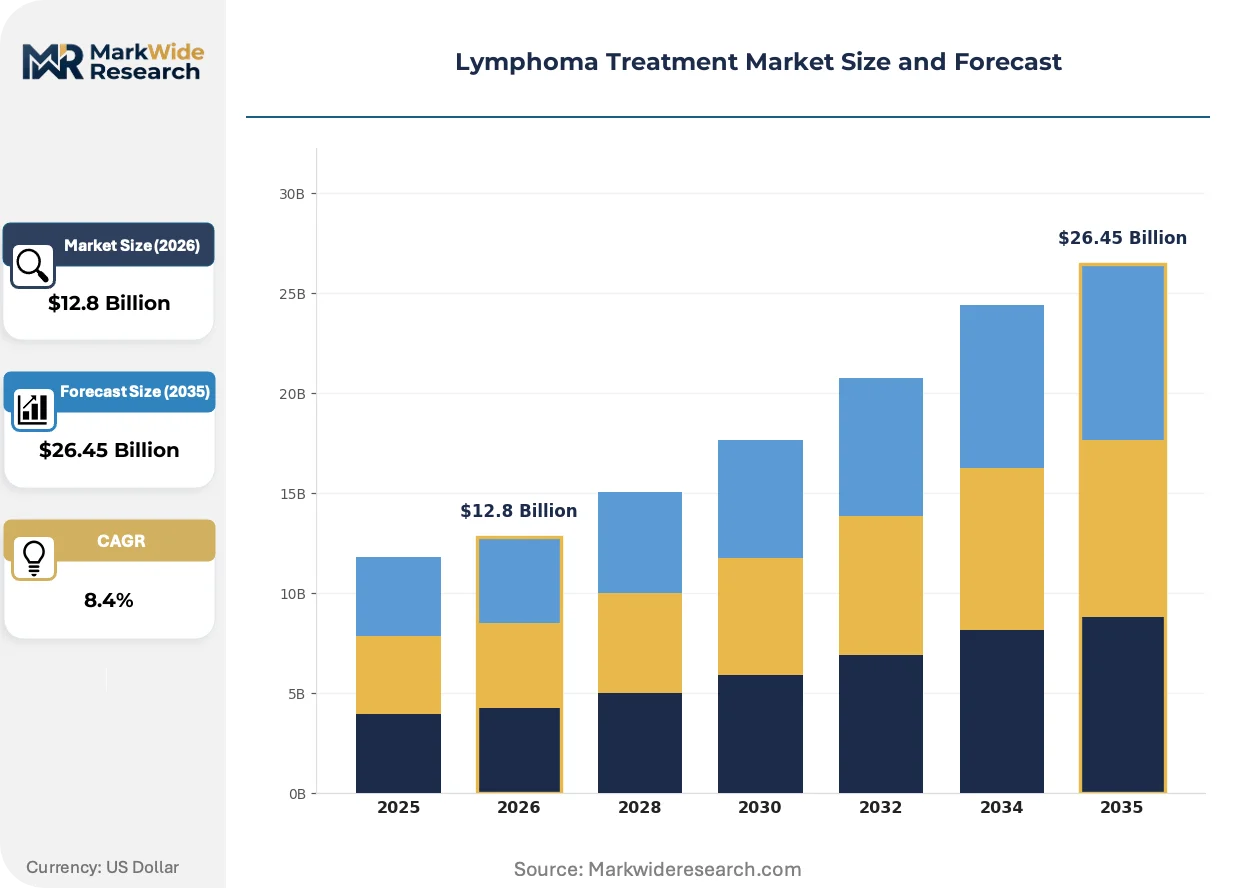
The convergence of accelerated drug approval pathways and breakthroughs in cell therapy manufacturing defines the market's core dynamic. This creates a strategic imperative for stakeholders to balance investment between highly targeted, high-cost innovations and established, broadly applicable treatments for lymphoma.
Growth Catalysts
- Accelerated Regulatory Pathways:Frameworks like the FDA's Breakthrough Therapy Designation and the EMA's PRIME scheme expedite market access for novel lymphoma treatments, encouraging investment in innovative drug development pipelines.
- Cell Therapy Manufacturing Advances:The narrowing skill gap between academic research and commercial-scale cell therapy production lowers barriers to entry and expands the availability of treatments like CAR-T cell therapy.
- Emerging Market Demand:China's NMPA is streamlining its approval processes for oncology drugs, creating significant demand for advanced lymphoma therapies within its large and expanding healthcare system.
Market Restraints
- Prohibitive Treatment Costs:The high price of novel treatments, particularly CAR-T cell therapies, limits patient access and creates significant reimbursement challenges for healthcare systems, even in developed markets.
- Complex Supply Chains:Autologous cell therapies require a sophisticated, patient-specific logistics network, which is difficult to scale and prone to disruptions, thereby constraining overall treatment capacity.
- Antigen Escape and Resistance:The development of resistance mechanisms, such as the loss of targeted antigens like CD19 on cancer cells, limits the long-term efficacy of some targeted therapies and drives research for next-generation options.
Strategic Opportunities
- Allogeneic Cell Therapies:Developing "off-the-shelf" allogeneic CAR-T products presents a major opportunity to overcome the logistical and cost barriers associated with current patient-specific autologous therapies.
- Expansion in Southeast Asia:Beyond China, markets in Southeast Asia with growing middle classes and improving healthcare infrastructure represent an underpenetrated region for advanced lymphoma treatments.
- Novel Antigen Targeting:Research into new cellular targets beyond CD19 and CD20 for monoclonal antibodies and CAR-T cells opens avenues for treating relapsed or refractory lymphoma subtypes.
Industry Challenges
- Specialized Workforce Scarcity:A shortage of technicians and scientists with expertise in GMP-compliant cell therapy manufacturing and quality control impedes the expansion of production capacity.
- Healthcare Infrastructure Demands:Administering cell therapies requires specialized hospital units and staff trained in managing unique side effects, a level of infrastructure not universally available.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lymphoma Treatment Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Hodgkin Lymphoma, Non-Hodgkin Lymphoma, Cutaneous Lymphoma, Mantle Cell Lymphoma, Burkitt Lymphoma Product Type: Monoclonal Antibodies, Chemotherapy Agents, Immunomodulators, Radioimmunotherapy, Targeted Therapy Care Setting: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Cancer Research Institutes, Home Healthcare Delivery Mode: Intravenous, Oral, Subcutaneous, Intramuscular, Intraventricular |
| Companies Covered | F. Hoffmann-La Roche Ltd, Bristol-Myers Squibb Company, Novartis AG, Gilead Sciences, Merck & Co., Inc., AstraZeneca, Takeda Pharmaceutical Company Ltd, AbbVie, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lymphoma Treatment Market Strategic Shifts & Innovations
The lymphoma treatment field is pivoting from broad-spectrum cytotoxic agents toward a paradigm of precision oncology. This shift is driven by a deeper biological understanding of the disease, enabling therapies that are tailored to specific molecular and genetic markers.
Bispecific antibodies are engineered proteins that simultaneously bind to a cancer cell antigen and an immune cell receptor. Specialty clinics and academic medical centers are rapidly adopting these agents for relapsed or refractory lymphoma cases. This dual-targeting mechanism is decomposing the traditional boundary between monoclonal antibody therapy and cellular immunotherapy, creating a new class of off-the-shelf immune-engaging treatments.
Regulatory bodies are implementing novel review frameworks to accelerate drug access. The US FDA's Real-Time Oncology Review (RTOR) pilot program, for instance, allows for early data submission before a formal marketing application is complete. Consequently, therapies for lymphoma subtypes with high unmet need reach patients faster, altering competitive launch timelines for manufacturers.
A shift toward value-based reimbursement models is influencing treatment selection. Instead of paying per vial, payers in some European markets are negotiating agreements where payment is tied to patient outcomes, such as achieving remission. This model is most prominent in the high-cost CAR-T cell therapy segment, forcing manufacturers to generate robust real-world evidence to support their value propositions.
Lymphoma Treatment Market Segmentation
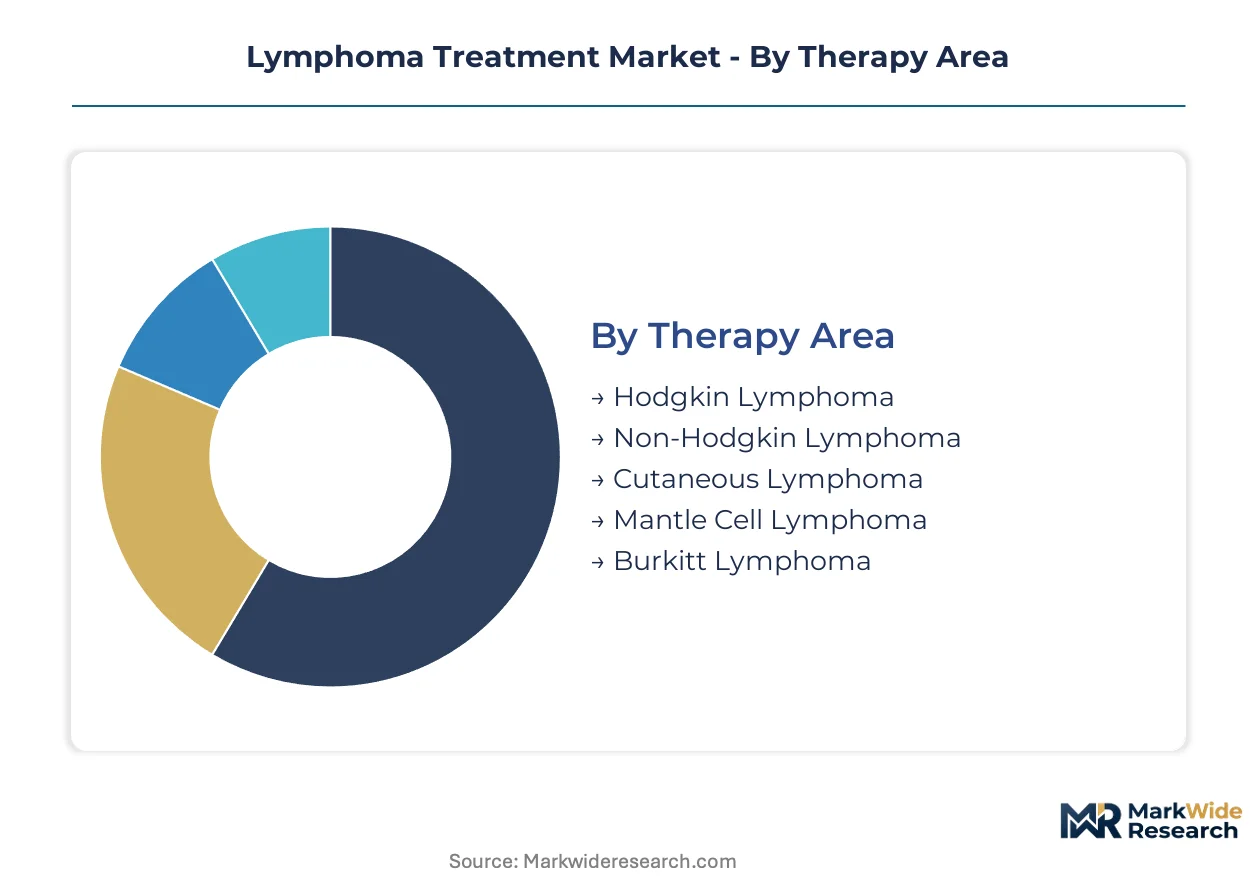
Understanding the Lymphoma Treatment Market through segmentation reveals how diverse patient needs and technological advancements shape therapeutic strategies. This granular analysis illuminates the specific areas where novel therapies gain traction and where established treatments maintain their foundational role.
Therapy Area:
The geographic spread of lymphoma diagnoses varies, with certain therapy areas showing higher prevalence in domestic markets while others drive export-led pharmaceutical development.
- Non-Hodgkin Lymphoma:This diverse group of lymphomas originates from B or T lymphocytes and includes numerous subtypes requiring tailored treatment protocols. Demand concentrates in major healthcare markets like China and the US, driven by its higher prevalence and the continuous introduction of new targeted agents.
- Hodgkin Lymphoma:Characterized by the presence of Reed-Sternberg cells, this lymphoma primarily affects lymph nodes and typically responds well to chemotherapy and radiation. Demand concentrates in developed economies with established treatment protocols, driven by consistent diagnostic rates and long-term survival management.
- Mantle Cell Lymphoma:An aggressive B-cell lymphoma requiring specialized treatment approaches due to its challenging prognosis and often relapsing nature.
- Burkitt Lymphoma:A highly aggressive B-cell non-Hodgkin lymphoma with rapid growth, often seen in pediatric populations and associated with specific genetic translocations.
- Cutaneous Lymphoma:A group of non-Hodgkin lymphomas that primarily affect the skin, often managed with topical or systemic therapies depending on disease stage.
Non-Hodgkin Lymphoma commands the established base. The steepest expansion runs through Mantle Cell Lymphoma.
Product Type:
The maturity of product types spans from traditional cytotoxic agents to cutting-edge cell and gene therapies, influencing their market penetration and adoption rates.
- Monoclonal Antibodies:Laboratory-produced molecules engineered to mimic the immune system's ability to fight harmful pathogens like cancer cells. Demand concentrates in specialty clinics in Europe and North America, driven by their targeted action against specific lymphoma antigens like CD20.
- Targeted Therapy:Drugs designed to interfere with specific molecules involved in cancer cell growth, progression, and spread, offering more precise treatment with fewer side effects. Demand concentrates in advanced oncology centers in Japan and Germany, driven by the shift towards precision medicine and personalized treatment plans.
- Chemotherapy Agents:Traditional cytotoxic drugs that kill rapidly dividing cells, forming the backbone of many lymphoma treatment regimens despite their broad systemic effects.
- Immunomodulators:Agents that modify or regulate the immune system's response, enhancing its ability to combat lymphoma cells or reducing immunosuppression.
- Radioimmunotherapy:Combines a radioactive isotope with a monoclonal antibody to deliver radiation directly to cancer cells, minimizing damage to healthy tissue.
Established therapies like Chemotherapy Agents provide a foundation, while Targeted Therapy drives innovation.
Care Setting:
The volume of patient treatments varies significantly across care settings, reflecting the complexity of lymphoma management and the infrastructure required for advanced therapies.
- Hospitals:These institutions provide a full spectrum of medical services, including diagnostic, surgical, and intensive care for lymphoma patients with complex needs. Demand concentrates in urban healthcare networks in the US and India, driven by the need for complex inpatient treatments and emergency care.
- Specialty Clinics:Dedicated facilities offering specialized oncology services, including administration of advanced targeted and cell therapies for specific lymphoma subtypes. Demand concentrates in metropolitan areas with high patient volumes in France and Canada, driven by the concentration of expert oncologists and specialized equipment.
- Ambulatory Surgical Centers:Provide outpatient surgical procedures and diagnostic interventions, often for less complex lymphoma-related treatments or biopsies.
- Cancer Research Institutes:Focus on clinical trials and developing novel lymphoma treatments, often integrating patient care with research efforts for cutting-edge therapies.
- Home Healthcare:Offers palliative care, medication management, and supportive services for lymphoma patients in their residences, improving quality of life.
Hospitals underpin the majority of patient interactions, while Specialty Clinics represent a growing segment for targeted interventions.
Delivery Mode:
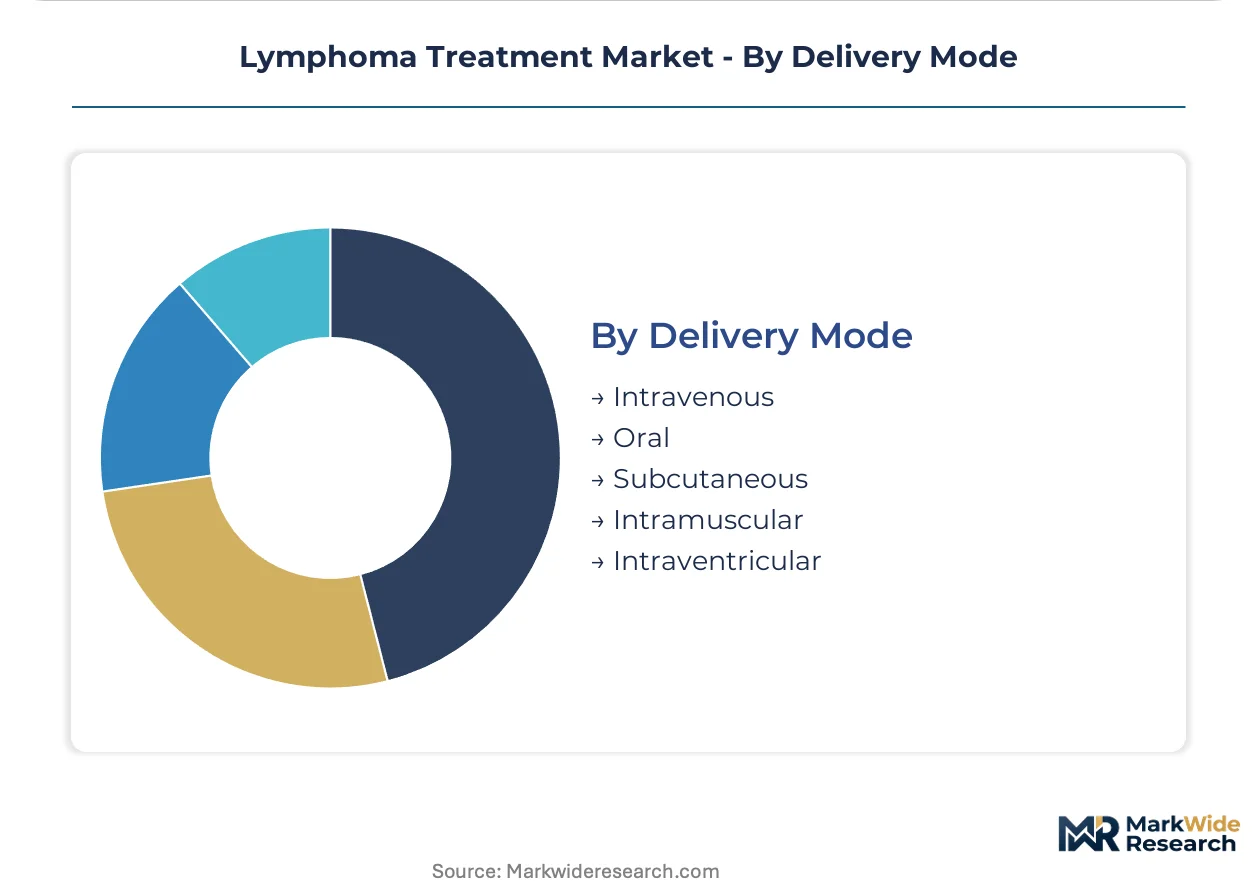
Patient preferences and the pharmacological properties of lymphoma treatments dictate the primary delivery modes, impacting convenience and adherence.
- Intravenous:This mode involves administering drugs directly into a vein, ensuring rapid and complete systemic distribution for potent agents. Demand concentrates in hospital settings across the UK and Australia, driven by the need for precise dosing and immediate therapeutic effect for many chemotherapy and antibody treatments.
- Oral:Medication taken by mouth, offering patient convenience and reducing the need for clinical visits for certain targeted therapies and immunomodulators. Demand concentrates in outpatient clinics in Germany and the US, driven by the development of new oral targeted therapies and improved patient quality of life.
- Subcutaneous:Involves injecting medication into the fatty tissue just under the skin, often used for monoclonal antibodies to allow for easier administration outside of hospital settings.
- Intramuscular:Medication injected into a muscle, providing a slower absorption rate compared to intravenous administration, suitable for some supportive care drugs.
- Intraventricular:Delivers drugs directly into the cerebrospinal fluid, specifically used for lymphomas affecting the central nervous system to bypass the blood-brain barrier.
Intravenous administration remains critical for acute care, while Oral delivery facilitates long-term outpatient management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's NMPA actively streamlines approval processes for oncology drugs, creating significant demand for advanced lymphoma therapies within its large and expanding healthcare system. This regulatory focus encourages investment in innovative treatments across major global healthcare markets. The market's growth patterns reflect both established prevalence and emerging therapeutic adoption.
United States
Demand for advanced lymphoma treatments in the United States is driven by high prevalence rates and a robust healthcare expenditure. The US FDA's Breakthrough Therapy Designation expedites market access for novel lymphoma drugs. Major pharmaceutical research clusters in Boston and the San Francisco Bay Area lead in developing cutting-edge cell and gene therapies.
China
China's healthcare system experiences substantial demand for innovative lymphoma therapies due to its large patient population. The NMPA's accelerated approval pathways for oncology drugs facilitate faster market entry. Shanghai and Beijing serve as key hubs for clinical trials and commercialization of advanced biopharmaceuticals.
Germany
Germany represents a significant market for lymphoma treatment, supported by an advanced healthcare infrastructure and strong research capabilities. The European Medicines Agency (EMA) oversees stringent but efficient approval processes for new therapies. Munich and Berlin host prominent oncology centers and biotech companies focused on hematological malignancies.
Japan
Japan exhibits consistent demand for lymphoma treatments, characterized by an aging population and a focus on precision medicine. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures rigorous evaluation of novel drugs. Tokyo and Osaka are central to pharmaceutical innovation and specialized oncology care delivery.
United Kingdom
The United Kingdom's demand for lymphoma therapies is supported by its National Health Service (NHS) and a focus on value-based care. The EMA's framework, largely mirrored by the MHRA post-Brexit, guides drug approvals. London and Cambridge are vital centers for biomedical research and advanced clinical oncology.
Lymphoma Treatment Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the lymphoma treatment market. This tiered structure reflects the capital intensity of drug development and manufacturing. Strategic archetypes include diversified pharmaceutical giants, specialized immunotherapy developers, and gene therapy innovators. Competitive moves often involve portfolio diversification and strategic partnerships to access new technologies.
Diversified pharmaceutical leaders, such as F. Hoffmann-La Roche Ltd, occupy a position leveraging extensive oncology portfolios and global diagnostic networks. Bristol-Myers Squibb Company exemplifies a specialized immunotherapy developer, focusing on CAR-T cell treatments for various lymphoma types. Novartis AG sits within the gene therapy innovator archetype, differentiating through pioneering work in hematological malignancies.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Bristol-Myers Squibb Company |
| Novartis AG |
| Gilead Sciences |
| Merck & Co., Inc. |
| AstraZeneca |
| Takeda Pharmaceutical Company Ltd |
| AbbVie |
| Johnson & Johnson |
| Others |
Cost & Logistics Intelligence
Allogeneic cell therapy development is reshaping the supply geography of cell-based treatments and influencing the pricing economics of patient-specific autologous therapies. This dynamic encourages investment in standardized manufacturing processes, potentially lowering overall treatment costs. The shift toward off-the-shelf solutions also impacts global distribution networks.
Pricing Analysis
Value-based reimbursement models define the dominant pricing structure for advanced lymphoma therapies in developed markets. Price differentiation stems from clinical efficacy data and the specificity of targeted action against lymphoma antigens. Pricing pressure stems from the high R&D costs associated with novel cell and gene therapies, creating significant reimbursement challenges. Healthcare systems are highly price-sensitive due to budget constraints, while private insurers may exhibit less sensitivity for breakthrough treatments with strong outcome data.
Supply Chain Analysis
The limited availability of GMP-compliant manufacturing facilities for cell therapies creates a significant chokepoint in the lymphoma treatment supply chain. Geographic supply concentration for advanced therapies centers on the United States, Germany, and China. Raw material dependencies include specialized viral vectors and cell culture media. Single-source vulnerability for critical reagents represents a structural supply chain risk. Distribution runs through highly specialized hospital systems and academic medical centers for patient-specific treatments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lymphoma treatment market presents a service-attach opportunity, with patient monitoring and supportive care services expanding faster than initial drug administration. This trend creates avenues for value-added offerings beyond the core therapeutic product.
For Market Incumbents:
Compound existing R&D investments in bispecific antibodies to counter antigen escape mechanisms, a named threat to long-term efficacy. Consolidate market share through strategic partnerships for manufacturing scale-up in key regions like Europe and North America. Deepen R&D into next-generation allogeneic cell therapies to mitigate the logistical complexities of autologous treatments. Investment in global diagnostic networks remains a critical lever for early disease detection and targeted therapy selection.
For New Entrants and Emerging Players:
Specialized patient navigation and personalized treatment planning services represent an underserved service layer for new entrants. Focus on rare lymphoma subtypes or relapsed/refractory patient populations in underpenetrated markets like Southeast Asia. Develop novel antigen-targeting therapies beyond CD19 and CD20 to address unmet needs. A direct-to-specialty clinic partnership model can offer an effective go-to-market angle, bypassing traditional hospital procurement channels.
For Investors and Strategic Acquirers:
Capital is best deployed toward gene therapy innovators with robust clinical pipelines in hematological malignancies. Long-term viability hinges on overcoming manufacturing complexities and demonstrating durable remission in clinical trials. Target biotech firms specializing in allogeneic CAR-T platforms, which promise scalability and reduced treatment times. Early clinical data demonstrating superior safety profiles for "off-the-shelf" treatments is the signal to watch as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Expedites market entry for novel therapies targeting high unmet needs in lymphoma. |
| Manufacturing Scale-Up | Lowers per-dose costs and expands patient access for cell and gene therapies. |
| Pipeline Diversification | Mitigates risk by addressing multiple lymphoma subtypes and resistance mechanisms. |
| Strategic Partnerships | Leverages complementary expertise for R&D, manufacturing, or market access. |
| Novel Antigen Targeting | Opens new treatment avenues for relapsed/refractory lymphoma patient populations. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, clinical trial registries, and academic literature. Primary interviews engaged oncology key opinion leaders, hospital formulary managers, pharmaceutical R&D executives, and regulatory affairs specialists. Secondary sources included US FDA filings, European Medicines Agency submissions, National Institutes of Health (NIH) clinical trial data, and medical journal publications. This approach employed both bottom-up market sizing from patient populations and top-down validation against company revenue reports.
Segmentation dimensions modeled include therapy area, product type, care setting, delivery mode, and regional regulatory frameworks. An analytical framework projects market trajectories over the projection horizon, integrating historical trends and anticipated pipeline advancements. Compound annual growth rates derive from these trends and new drug approval timelines. Key industry-specific forecast inputs include incidence rates of Non-Hodgkin Lymphoma and Hodgkin Lymphoma.
Material uncertainties — unforeseen clinical trial failures or major reimbursement policy shifts — sit outside the modeled envelope for this analysis. Forecasts reflect assumptions regarding technological adoption and healthcare expenditure. Drug resistance development and supply chain disruptions could revise future projections. Practitioners should keep alternative scenarios live as therapeutic paradigms and economic conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Global Bleeding Disorders Market
Hematology
Heparin-Induced Thrombocytopenia (HIT) Treatment Market
Hematology
Warm Autoimmune Hemolytic Anemia (WAIHA) Treatment Market
Hematology
Myelofibrosis Treatment Market
Hematology
Sickle Cell Disease Market
Hematology
Acute Lymphoblastic Leukemia Market
Hematology
Thalassemia Treatment Market
Hematology
Patient Blood Management Market
Hematology
Sickle-Cell Anemia Therapeutics Market
Hematology
Global Non-Hodgkin Lymphoma Therapeutics Market
Hematology
Graft vs Host Disease Market
Hematology
Follicular Lymphoma Treatment Market
Hematology
Burkitt Lymphoma Treatment Market
Hematology
Blood Screening Market
Hematology
Aplastic Anemia Treatment Market
Hematology
Bone Marrow Transplant Market