
 Multiple Myeloma Treatment Market | 2026-2036
Multiple Myeloma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Multiple Myeloma Treatment Market Outlook
The gap between CAR T-cell therapies and conventional chemotherapy is repositioning how payers structure reimbursement and how sites of care credential for advanced modalities. Bristol-Myers Squibb leverages its integrated cell therapy manufacturing network to sustain supply continuity for complex autologous products. Takeda Pharmaceutical Company anchors its presence through proteasome inhibitor specialization across both infused and oral formulations. Johnson & Johnson competes aggressively in the CD38-directed antibody segment with established intravenous and subcutaneous delivery options.
Multiple myeloma treatment encompasses therapeutic interventions targeting malignant plasma cell proliferation, including monoclonal antibodies that bind surface proteins like CD38 and SLAMF7, proteasome inhibitors that disrupt protein degradation pathways, immunomodulatory drugs that modulate cytokine signaling, and CAR T-cell therapies that engineer patient-derived lymphocytes for tumor-specific cytotoxicity. The primary purpose is to achieve durable disease control, extend progression-free survival, and preserve quality of life through sequential lines of therapy. Monoclonal antibodies and CAR T-cell therapies command the deepest investment pipelines as developers chase sustained remission profiles. Proteasome inhibitors retain substantial volume share but face margin compression from biosimilar entry and generic erosion. Oral immunomodulatory drugs sustain strong ambulatory adoption due to convenience advantages in maintenance settings.
The FDA's accelerated approval framework and Breakthrough Therapy designation reshape oncology development economics by enabling earlier revenue recognition based on surrogate endpoints. EMA's Committee for Medicinal Products for Human Use applies evolving benefit-risk standards for novel modalities that influence parallel regulatory strategies. The country's national pharmaceutical regulator in Japan maintains distinct pharmacovigilance requirements that filter which cell therapy platforms achieve commercial access. Stakeholders must monitor how real-world evidence mandates and outcomes-based contracting terms redefine competitive positioning across therapy lines.
Market Dynamics
The FDA's accelerated approval pathway for oncology biologics compresses development timelines from phase 1 to commercial launch, creating competitive pressure on conventional trial designs while academic medical centers race to credential for cellular therapy administration.
Growth Catalysts
- Breakthrough Therapy designation:The FDA's expedited review framework enables earlier revenue recognition based on surrogate endpoints, attracting venture capital into CAR T-cell platforms.
- Academic medical center expansion:Major oncology centers in the United States are building dedicated cell therapy infusion units and apheresis capabilities to capture referral volume.
- CD38-directed antibodies:These monoclonal antibodies demonstrate durable progression-free survival in relapsed settings, expanding addressable patient populations beyond transplant-eligible candidates.
Market Restraints
- Vein-to-vein logistics:Autologous CAR T-cell manufacturing requires cryogenic chain integrity across collection, shipping, and reinfusion, constraining site eligibility to centers with validated cold-chain infrastructure.
- Proteasome inhibitor commoditization:Biosimilar entry and generic erosion of bortezomib formulations compress margins on infused and oral proteasome inhibitors.
- Cytokine release syndrome management:The need for ICU-level monitoring during cellular therapy administration limits treatment capacity at community oncology practices.
Strategic Opportunities
- Subcutaneous delivery formats:CD38-directed antibodies with subcutaneous administration reduce infusion chair time and enable community-based administration, expanding beyond academic center concentration.
- Real-world evidence mandates:FDA guidance on post-marketing surveillance creates pathways for label expansion based on registry data rather than controlled trials.
- Maintenance therapy positioning:Oral immunomodulatory drugs in continuous dosing schedules capture long-duration prescriptions with favorable ambulatory economics.
Industry Challenges
- Cell therapy manufacturing scale-out:Autologous product variability and patient-specific batch release create capacity bottlenecks that constrain commercial expansion.
- Payer prior authorization complexity:CAR T-cell therapies require multi-step coverage determination processes that delay treatment initiation and create administrative burden at treatment centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multiple Myeloma Treatment Market |
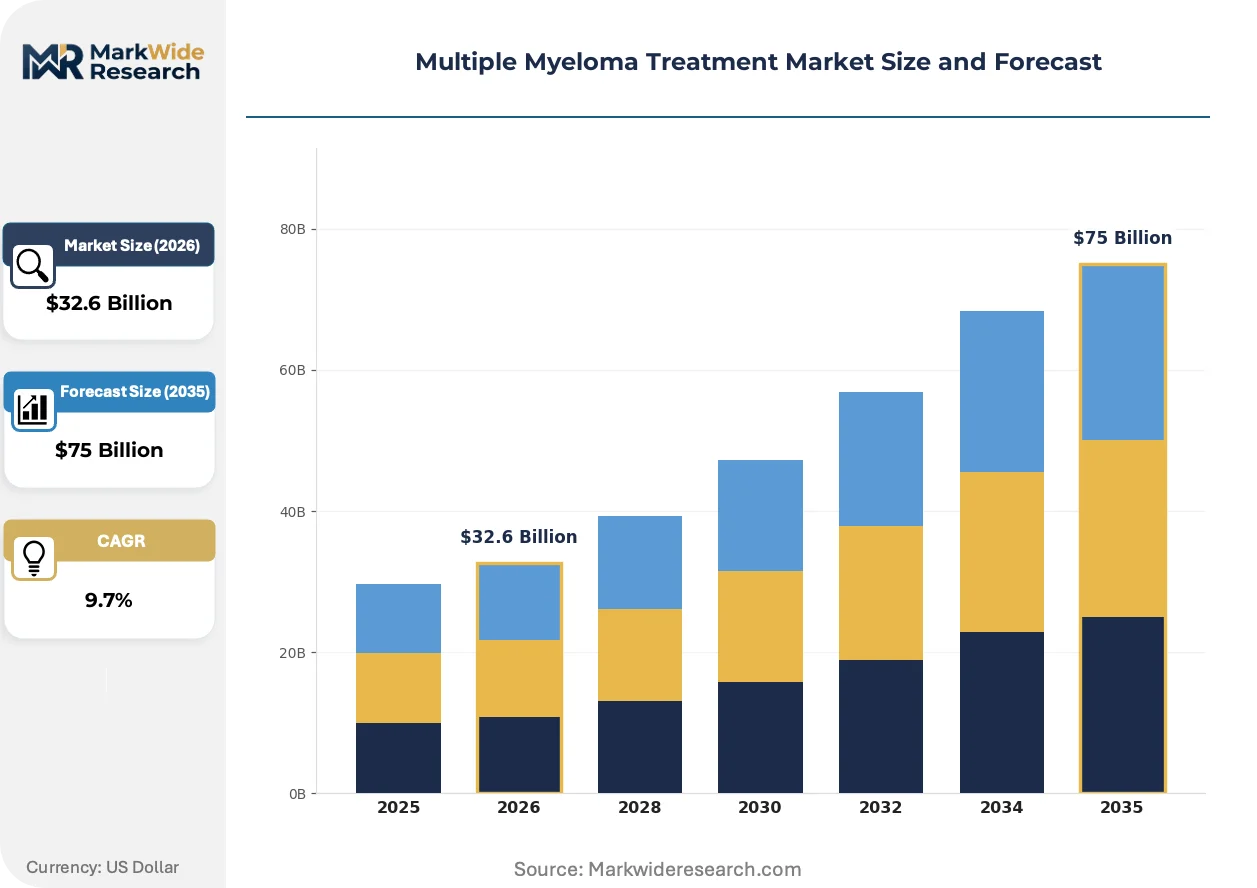
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $75 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Proteasome Inhibitors, Immunomodulatory Drugs, CAR T-Cell Therapy Therapy Area: Oncology, Hematology, Supportive Care, Palliative Care Administration Route: Oral, Intravenous, Subcutaneous, Intramuscular End User: Hospitals, Clinics, Home Care, Ambulatory Surgical Centers |
| Companies Covered | Bristol-Myers Squibb, Takeda Pharmaceutical Company, Johnson & Johnson, Amgen, AbbVie, Sanofi, Novartis, Karyopharm Therapeutics, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multiple Myeloma Treatment Market Strategic Shifts
Cellular engineering and bispecific antibody platforms are displacing sequential chemotherapy paradigms, while regulatory frameworks adapt to evaluate durability of response rather than traditional survival endpoints.
Bispecific T-cell engagers are expanding into earlier lines of therapy, redirecting endogenous T-cells against BCMA and GPRC5D targets without ex vivo manipulation. Community oncology practices are adopting these off-the-shelf formats faster than autologous CAR T-cell programs, compressing the referral window for academic centers. The technology is expanding into combination regimens that pair T-cell redirection with immunomodulatory backbone therapy.
The FDA's Project Confirm initiative strengthens post-marketing requirements for accelerated oncology approvals, mandating confirmatory trial completion timelines. Developers face enrollment pressure to validate surrogate endpoints against overall survival, reshaping phase 3 design priorities. Myeloma programs with Breakthrough Therapy designation experience heightened scrutiny of progression-free survival durability.
Site-of-care migration is accelerating as payers implement differential reimbursement for hospital outpatient versus freestanding infusion center administration. Commercial insurers in the United States are narrowing network panels for high-cost cellular therapies, consolidating volume at centers with outcomes-based contracts. This concentration pattern is most visible in Medicare Advantage plans seeking to manage total cost of care for relapsed patients.
Multiple Myeloma Treatment Market Segmentation
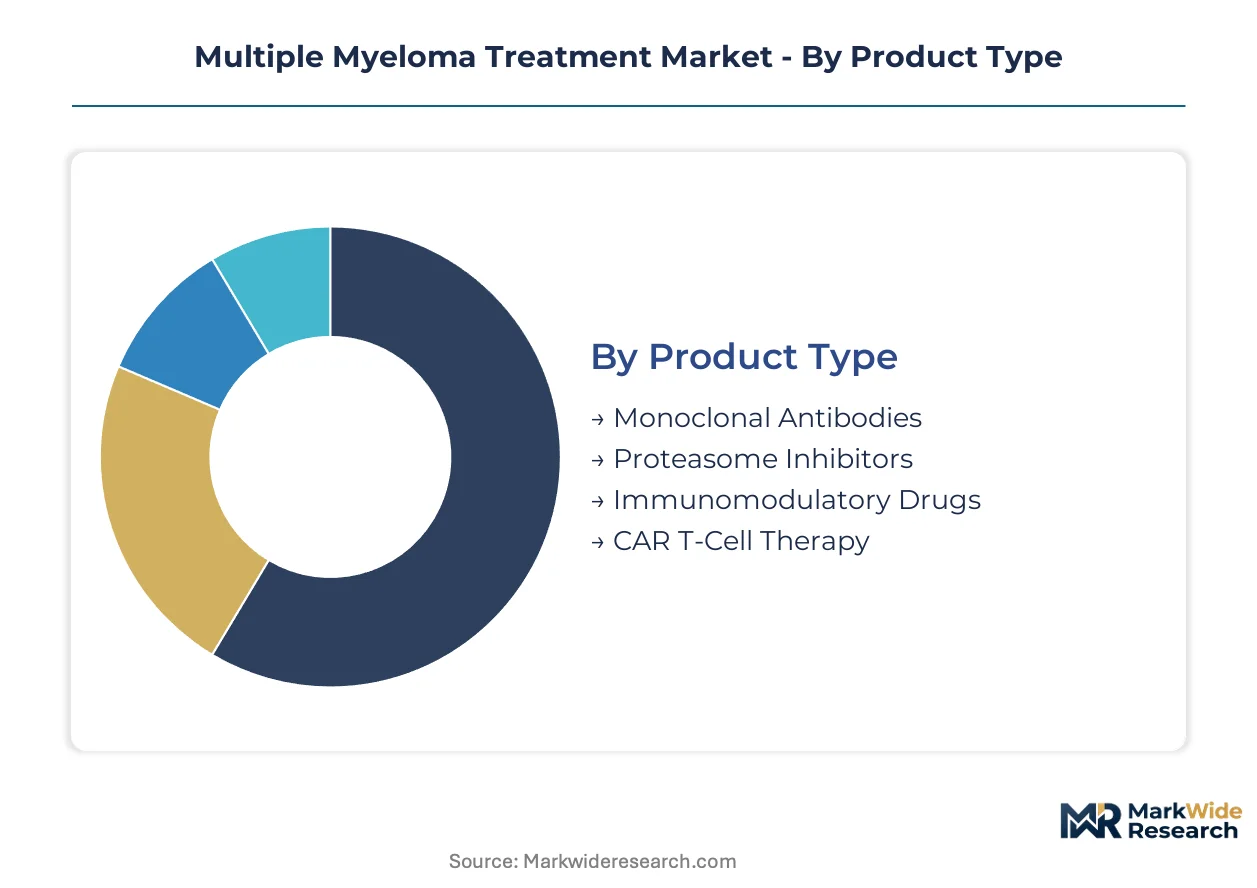
Treatment modality selection in multiple myeloma follows patient-specific biomarker profiles and line-of-therapy positioning. Segmentation reveals how administration logistics and site-of-care capabilities filter which therapeutic platforms achieve commercial scale.
Product Type:
Customization intensity varies sharply across this category, from off-the-shelf small molecules to patient-specific autologous cellular products requiring individualized manufacturing workflows.
- Monoclonal Antibodies:Engineered proteins targeting CD38, SLAMF7, and BCMA surface antigens deliver durable disease control through Fc-mediated cytotoxicity. Demand clusters at academic medical centers in the United States where infusion infrastructure supports extended dosing schedules; subcutaneous formulations are compressing the site-of-care advantage.
- CAR T-Cell Therapy:Autologous products require leukapheresis collection, cryogenic logistics, and lymphodepletion preconditioning before reinfusion. Manufacturing bottlenecks and vein-to-vein timelines restrict eligibility to transplant centers with validated cold-chain capabilities; FDA's Breakthrough Therapy designation pipeline is accelerating credentialing competition.
- Proteasome Inhibitors:Bortezomib, carfilzomib, and ixazomib formulations disrupt protein degradation pathways in malignant plasma cells.
- Immunomodulatory Drugs:Thalidomide analogs modulate cytokine signaling and enhance immune surveillance through cereblon binding.
Most installed capacity flows through Monoclonal Antibodies. Expansion is steepest in CAR T-Cell Therapy.
Therapy Area:
Clinical intent shapes resource allocation across this category, from curative-oriented interventions to symptom-focused supportive measures.
- Oncology:Disease-modifying regimens targeting clonal plasma cell proliferation span induction, consolidation, and maintenance phases. CAR T-cell and bispecific antibody trials are migrating into earlier lines at centers participating in NCI-sponsored cooperative groups.
- Hematology:Stem cell transplantation and cellular therapy coordination require specialized apheresis and cryopreservation infrastructure concentrated at designated transplant centers.
- Supportive Care:Bisphosphonates, growth factors, and infection prophylaxis preserve treatment tolerance and quality of life.
- Palliative Care:Pain management and symptom control for refractory disease states.
Revenue concentration sits with Oncology. Patient volume expansion is climbing fastest in Hematology.
Administration Route:
Convenience economics and reimbursement differentials create distinct competitive arenas across delivery modalities.
- Intravenous:Infusion chair occupancy and pharmacy compounding requirements tether administration to hospital outpatient departments where reimbursement rates sustain specialty pharmacy investment.
- Subcutaneous:CD38-directed antibodies with reduced infusion duration enable community-based administration, extending reach beyond academic referral networks.
- Oral:Immunomodulatory drugs and proteasome inhibitors support continuous dosing in ambulatory settings.
- Intramuscular:Limited applications for specific supportive care agents.
Volume leadership belongs to Intravenous. Share gains are sharpest in Subcutaneous.
End User:
Site-of-care economics and therapy complexity filter patient flow across delivery settings.
- Hospitals:Academic medical centers with FACT-JACIE accreditation dominate cellular therapy administration, capturing CAR T-cell and transplant-eligible referrals through specialized apheresis units and ICU-capable monitoring.
- Clinics:Community oncology practices with pharmacy benefit management contracts handle oral agent dispensing and monoclonal antibody infusion for stable patients.
- Home Care:Oral maintenance regimens and subcutaneous injections shift to home settings with remote monitoring support.
- Ambulatory Surgical Centers:Limited penetration for specific infusion procedures.
Treatment capacity concentrates at Hospitals. Growth velocity is highest at Clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates CAR T-cell therapy administration at academic medical centers, while Germany anchors European proteasome inhibitor manufacturing through specialized chemical synthesis clusters.
United States
Academic medical centers in Boston, Houston, and Seattle compete aggressively for FACT-JACIE accreditation to capture cellular therapy referrals. FDA's Breakthrough Therapy designation pipeline accelerates site credentialing timelines. The National Cancer Institute's cooperative group network coordinates multi-center trials migrating immunomodulatory combinations into earlier treatment lines.
Germany
EMA's centralized marketing authorization procedures enable parallel access across member states for CD38-directed antibodies. Heidelberg and Munich host specialized apheresis units serving cross-border patient flows from Austria and Switzerland. The country's national pharmaceutical regulator maintains stringent pharmacovigilance requirements that filter which bispecific platforms achieve reimbursement.
Japan
PMDA's Sakigake designation system compresses review timelines for BCMA-targeting modalities, attracting sponsor investment into localized clinical development. Tokyo and Osaka academic hospitals build dedicated cell therapy infusion units with ICU-capable monitoring infrastructure. METI's healthcare export initiatives promote Japanese manufacturing standards for regional Asian markets.
United Kingdom
NICE technology appraisals create transparent cost-effectiveness thresholds that shape formulary positioning for novel monoclonal antibodies. London's Royal Marsden and Manchester's Christie Hospital anchor the NHS's specialized cancer treatment network. The MHRA's post-Brexit regulatory autonomy enables accelerated access schemes for patients with relapsed disease.
China
NMPA's priority review pathway for innovative biologics shortens approval timelines for domestically manufactured proteasome inhibitors. Shanghai and Beijing academic centers expand CAR T-cell manufacturing partnerships with multinational sponsors seeking cost-competitive production. The country's dual carbon goals pressure energy-intensive pharmaceutical manufacturing toward renewable power sourcing.
Multiple Myeloma Treatment Market Competitive Environment
Top-tier vendors anchor the cellular therapy segment, while mid-tier specialists concentrate on oral formulation scale-up. The vendor base stratifies across three tiers: integrated pharmaceutical conglomerates with captive manufacturing networks, biotechnology firms with platform-specific specialization, and regional generic manufacturers exploiting proteasome inhibitor patent cliffs. Strategic archetypes include CD38-directed antibody developers pursuing subcutaneous delivery differentiation and CAR T-cell platforms racing to compress vein-to-vein timelines. Competitive moves center on manufacturing capacity expansion and outcomes-based contracting with commercial payers.
Within the integrated conglomerate tier, Bristol-Myers Squibb, Johnson & Johnson, and Takeda Pharmaceutical Company exemplify divergent strategic postures. Bristol-Myers Squibb occupies a position emphasizing cell therapy manufacturing network integration. Johnson & Johnson anchors the CD38-directed antibody competitive vector through delivery format diversification. Takeda Pharmaceutical Company represents proteasome inhibitor specialization across administration routes. These three entities collectively illustrate how therapeutic modality focus shapes capital allocation and site-of-care partnership strategies.
| Leading Market Players |
|---|
| Bristol-Myers Squibb |
| Takeda Pharmaceutical Company |
| Johnson & Johnson |
| Amgen |
| AbbVie |
| Sanofi |
| Novartis |
| Karyopharm Therapeutics |
| AstraZeneca |
| Others |
Value Chain & Pricing Dynamics
Captive manufacturing networks at Bristol-Myers Squibb and Johnson & Johnson anchor both supply continuity and pricing power for autologous cellular products and CD38-directed antibodies. This integration insulates against third-party manufacturing bottlenecks while supporting premium positioning through controlled batch release and cold-chain integrity.
Pricing Analysis
Capacity additions in China for domestically manufactured proteasome inhibitors are reshaping price floors for oral and infused formulations. Three-tier pricing structure across premium cellular therapies, standard monoclonal antibodies, and economy generic proteasome inhibitors reflects manufacturing complexity and site-of-care requirements. Cost compression in the proteasome inhibitor tier is intensifying because of bortezomib biosimilar entry and ixazomib generic erosion. Community oncology practices demonstrate highest price sensitivity due to pharmacy benefit management contract constraints, while academic medical centers with outcomes-based payer contracts exhibit lowest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with cryogenic logistics providers handling autologous CAR T-cell vein-to-vein transport. Manufacturing concentration clusters in the United States, Germany, and China for active pharmaceutical ingredients and finished biologics. Supply chains draw from specialized apheresis collection centers, GMP-certified cell processing facilities, and validated cold-chain distribution networks. Tariff exposure on Chinese-sourced starting materials for immunomodulatory drug synthesis creates input cost volatility. Distribution runs through hospital outpatient departments with FACT-JACIE accreditation for cellular therapies, and through specialty pharmacy channels for oral maintenance agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The multiple myeloma treatment market functions as a regulatory compounder where FDA's Breakthrough Therapy designation pipeline accelerates revenue recognition timelines and reshapes competitive entry dynamics.
For Market Incumbents: Acquire cryogenic logistics capabilities and apheresis center networks to secure vein-to-vein supply chain control against bispecific antibody displacement. Cell therapy manufacturing scale-out at academic medical centers represents a critical defensive lever, while subcutaneous formulation investments defend against site-of-care migration to community oncology practices.
For New Entrants and Emerging Players: Begin with off-the-shelf T-cell engager platforms targeting BCMA and GPRC5D to bypass autologous manufacturing complexity. Maintenance therapy positioning for oral immunomodulatory drugs offers the most penetrable segment due to ambulatory economics and continuous dosing schedules. A go-to-market angle anchored in payer outcomes-based contracting with Medicare Advantage plans enables rapid volume capture.
For Investors and Strategic Acquirers: Consolidation pressure builds where manufacturing bottlenecks constrain commercial expansion of patient-specific cellular products. Long-term viability over the next decade hinges on platforms demonstrating durable progression-free survival in earlier treatment lines. Acquisition targets should display proprietary lymphocyte engineering capabilities or established FACT-JACIE site partnerships. The signal to watch is confirmatory trial completion rates for accelerated approvals under FDA's Project Confirm initiative.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive cell therapy production networks at Bristol-Myers Squibb reduce vein-to-vein timeline variability. |
| Regulatory Approval Pathway | Breakthrough Therapy designation compresses FDA review timelines for BCMA-targeting modalities. |
| Subcutaneous Formulation Development | CD38-directed antibodies with reduced infusion duration enable community-based administration expansion. |
| Site-of-Care Partnership | FACT-JACIE accreditation at academic medical centers concentrates CAR T-cell referral volume. |
| Real-World Evidence Strategy | FDA post-marketing surveillance guidance creates label expansion pathways through registry data. |
Study Parameters
Multiple input streams — primary interviews with drug development executives, regulatory affairs leads, and payer access specialists; secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases; and bottom-up and top-down triangulation — were reconciled to construct market estimates across the analysis window.
Historical volume trajectories were cross-referenced against expert panel input to anchor baseline assumptions. Segmentation dimensions modeled span treatment modality, administration route, therapy line, patient eligibility criteria, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating clinical trial enrollment velocity, approval pathway designations, and site credentialing expansion rates.
Several conditions sit outside the modeled scope, including pipeline attrition from failed confirmatory trials, abrupt payer coverage reversals, and manufacturing facility regulatory actions. Forecasts reflect documented assumptions about therapy sequencing patterns and reimbursement stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
APAC Acute Myeloid Leukemia Treatment Market
Hematology
Bleeding Disorders Therapeutics Market
Hematology
Anemia Drugs Market
Hematology
Small Lymphocytic Lymphoma Market
Hematology
Lymphoproliferative Disorder Treatment Market
Hematology
Thalassemia Treatment Market
Hematology
Haematocrit Centrifuge Market
Hematology
Global Hematology Market
Hematology
Paroxysmal Nocturnal Hemoglobinuria (PNH) Treatment Market
Hematology
Radiation-Induced Myelosuppression Treatment Market
Hematology
Sickle Cell Treatment Market
Hematology
Erythropoietic Protoporphyria (EPP) Treatment Market
Hematology
Multiple Myeloma Market
Hematology
Febrile Neutropenia Market
Hematology
Blood Disorder Therapeutics Market
Hematology
Hemostatic Spray Market