
 Hematology Analyzers Market | 2026-2036
Hematology Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Hematology Analyzers Market Intelligence
Consolidation among large hospital networks and national diagnostic laboratory chains is expanding the base of high-volume purchasers. Sysmex Corporation leverages its strong brand in key Asian markets to secure large-scale contracts with these entities. Danaher Corporation, via its Beckman Coulter brand, competes by offering integrated workflow automation solutions. Abbott Laboratories sustains its market position through a diverse portfolio spanning both core laboratory and point-of-care testing systems.
Hematology analyzers are medical laboratory instruments designed to count and characterize blood cells for disease diagnosis and monitoring. These devices use principles such as electrical impedance and optical flow cytometry to differentiate cell types, including erythrocytes, leukocytes, and platelets. Automated analyzers dominate sales, driven by adoption in high-throughput hospitals and diagnostic laboratories. While impedance technology remains prevalent in semi-automated systems, advanced flow cytometry represents the fastest-growing technology segment, defining performance in premium instruments.
Market access requires adherence to stringent medical device regulations, such as FDA 510(k) clearance in the United States and CE marking under the EU's MDR. Quality system compliance, mandated by standards like ISO 13485 and enforced by bodies including China's NMPA, governs manufacturing processes and product safety. The ability to integrate instruments into hospital information systems while ensuring data security is becoming a critical differentiator for vendors.
Market Dynamics
The market's central dynamic is the divergence between high-throughput, centralized laboratory automation and the decentralization of testing through point-of-care devices. This creates distinct technology, pricing, and distribution requirements for vendors targeting either large diagnostic centers or smaller clinics.
Growth Catalysts
- Advanced Technology Adoption:The integration of digital imaging and flow cytometry improves diagnostic accuracy for complex conditions, compelling high-volume laboratories to upgrade from older impedance-based systems to maintain a competitive edge and meet clinical demand.
- Healthcare Infrastructure Expansion:Public and private investments in hospital and laboratory infrastructure, particularly in India and China, are increasing the installed base of hematology analyzers to serve a larger patient population.
- Chronic Disease Management:A growing emphasis on managing chronic conditions like anemia and leukemia drives higher routine testing volumes, supporting sustained demand for analyzers and associated reagents in developed and emerging economies alike.
Market Restraints
- High Capital Expenditure:The significant upfront cost of fully automated, 5-part and 6-part differential analyzers creates a substantial financial barrier for smaller independent laboratories and clinics with limited budgets, slowing adoption in these segments.
- Stringent Regulatory Hurdles:Navigating complex and lengthy approval pathways, such as FDA 510(k) clearance and the EU's Medical Device Regulation (MDR), delays product launches and increases development costs for manufacturers.
- Reagent Exclusivity:The closed-system design of many analyzers, which restricts the use of third-party reagents, locks customers into proprietary supply chains and limits their ability to control ongoing operational costs.
Strategic Opportunities
- Point-of-Care Expansion:Developing compact, low-cost hematology analyzers for use in physician offices, urgent care clinics, and remote settings addresses an underpenetrated segment of the market, especially in regions with limited central lab access.
- AI-Driven Diagnostics:Integrating artificial intelligence and machine learning algorithms can enhance cell differentiation and flagging capabilities, providing predictive insights for early disease detection and creating new value for clinical end-users.
- Veterinary Hematology:The expanding companion animal and livestock health markets represent a growing niche for specialized analyzers designed and validated for non-human blood samples, offering a distinct revenue stream for vendors.
Industry Challenges
- System Interoperability:Ensuring seamless integration of new analyzers with a wide variety of legacy Laboratory Information Systems (LIS) and hospital networks while complying with standards like HL7 remains a significant technical hurdle. *Skilled Technician Scarcity: A shortage of medical technologists trained to operate, maintain, and troubleshoot advanced hematology systems creates an operational bottleneck for laboratories, potentially limiting the adoption of more complex instruments.
- Data Security Compliance:Adherence to evolving data privacy regulations, including HIPAA in the United States and GDPR in Europe, requires continuous investment in cybersecurity measures to protect sensitive patient health information.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hematology Analyzers Market |
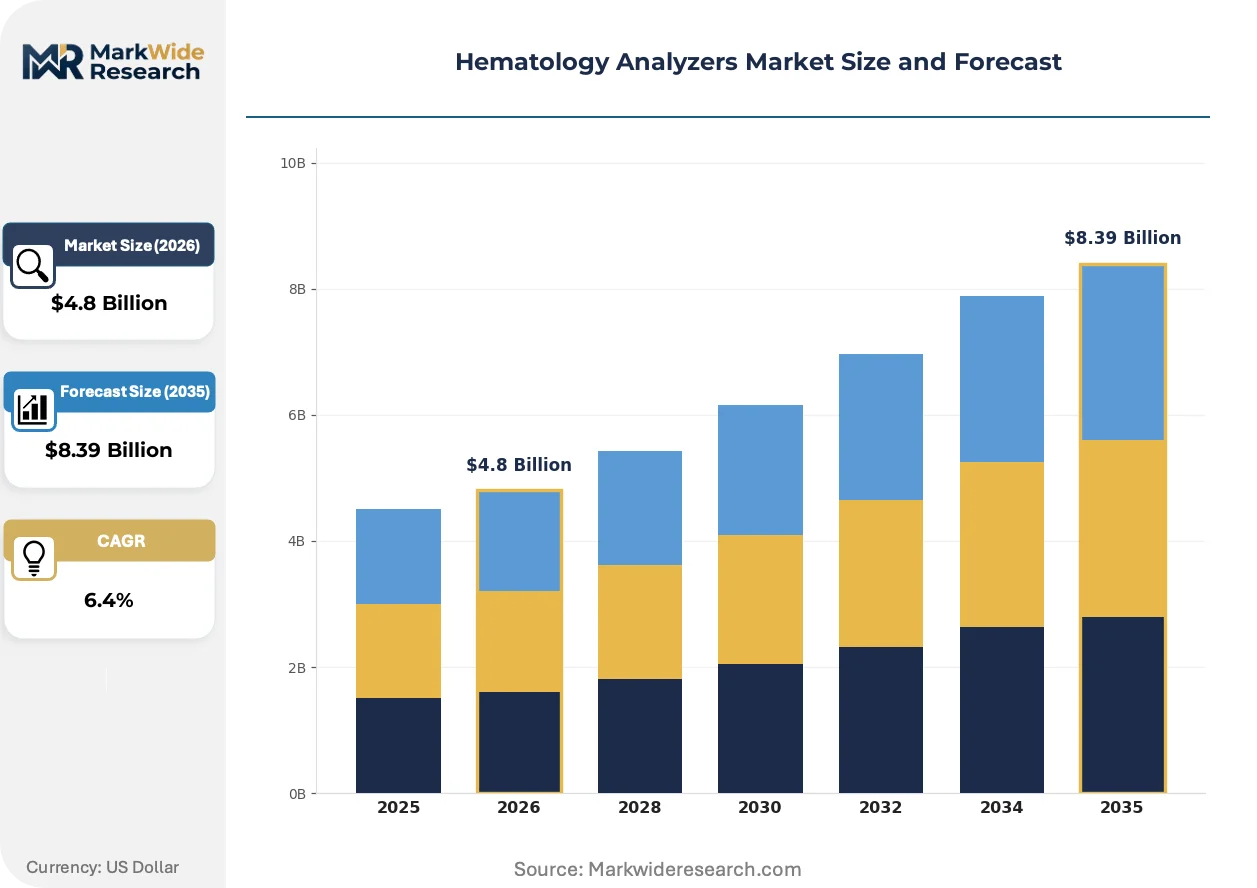
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Analyzers, Semi-Automated Analyzers, Benchtop Analyzers, Portable Analyzers End User: Hospitals, Diagnostic Laboratories, Clinics, Research Institutes Technology: Flow Cytometry, Impedance, Optical, Centrifugation Application: Blood Testing, Hemoglobin Analysis, CBC, Platelet Count |
| Companies Covered | Sysmex Corporation, Danaher Corporation, Abbott Laboratories, Siemens Healthineers, Beckman Coulter Inc., Shenzhen Mindray Bio-Medical Electronics Co. Ltd., HORIBA Ltd., Nihon Kohden Corporation, Boule Diagnostics AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hematology Analyzers Market Strategic Shifts & Innovations
The convergence of data analytics with hardware innovation is reshaping the field. This evolution is pushing hematology analysis beyond simple cell counting toward providing deeper, more predictive clinical insights from routine blood tests, both in central labs and at the point of care.
Digital morphology, a technology that uses AI-powered imaging to automate the review of blood smears, is gaining traction. High-volume clinical laboratories and specialized hematology centers are adopting these systems to improve workflow efficiency and standardize cell classification. This software-driven analysis is expanding into routine screening workflows, reducing reliance on time-consuming manual microscopy and improving turnaround times for abnormal results.
China's National Medical Products Administration (NMPA) is implementing policies to accelerate the review and approval of domestically manufactured medical devices. This regulatory shift fosters local competition, particularly impacting multinational vendors in the mid-range and point-of-care analyzer segments. Consequently, the market is seeing a rise in locally produced, cost-effective systems tailored to the needs of regional hospitals and clinics within China.
A shift toward reagent rental agreements and cost-per-test contracts is altering instrument acquisition patterns for large healthcare networks. This model displaces traditional outright capital purchases, enabling laboratories to access the latest technology with lower upfront financial commitment. The trend is most prominent in North America and Western Europe, where large integrated delivery networks seek to standardize instrumentation and manage operational expenditures more effectively.
Hematology Analyzers Market Segmentation
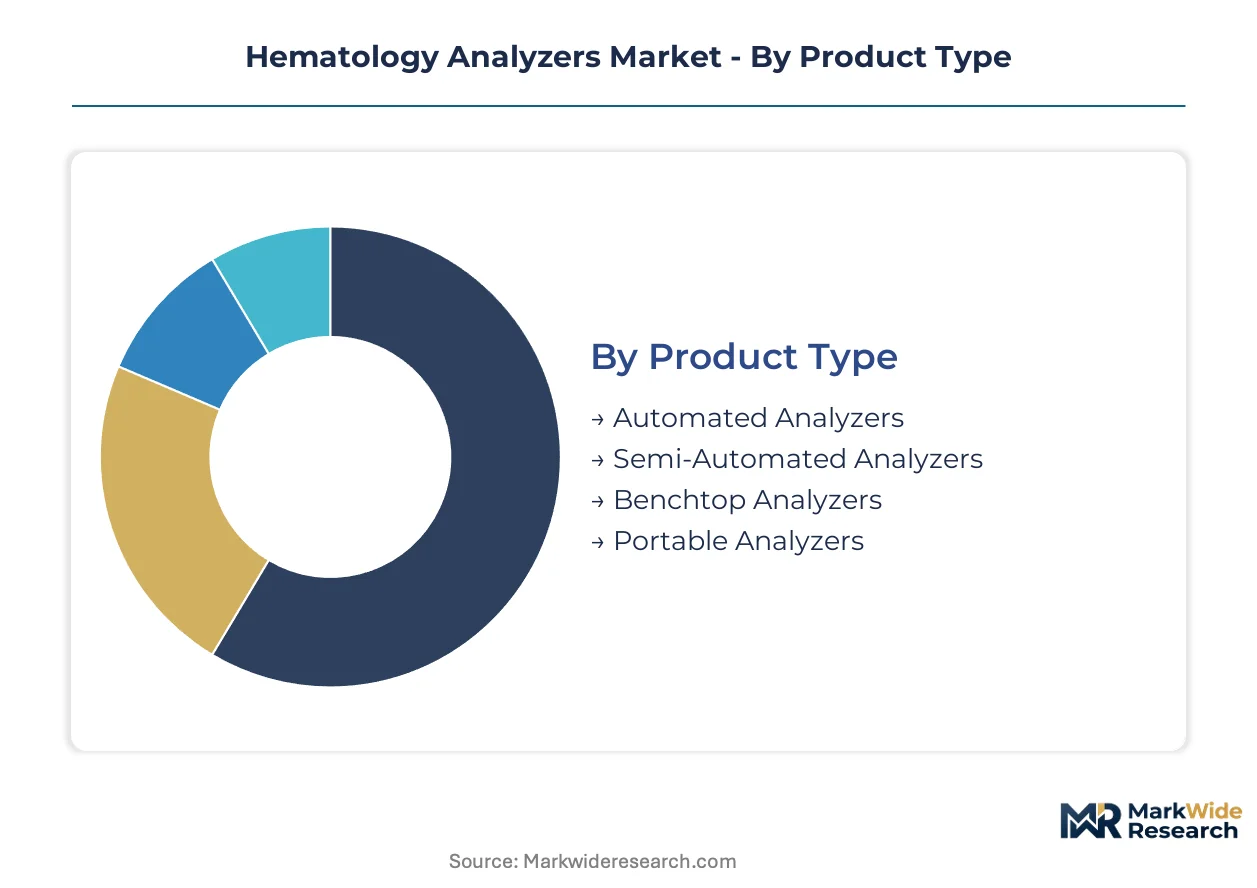
The Hematology Analyzers Market segments reveal distinct purchasing behaviors and technological preferences across various healthcare providers. Understanding these classifications helps manufacturers tailor product development and market access strategies. Different product types cater to varied throughput needs, while end-user categories reflect specific operational environments.
Product Type:
Product type segmentation differentiates buyers based on their laboratory volume and automation requirements for blood analysis.
- Automated Analyzers:These high-throughput systems perform complete blood counts and differential analyses without manual intervention, integrating advanced flow cytometry for precise cell characterization. High-volume diagnostic laboratories and large hospital networks drive demand for these efficient instruments.
- Portable Analyzers:Compact, easy-to-use devices designed for rapid blood analysis outside central laboratory settings, typically using microfluidics or impedance technology. Demand is concentrating in remote clinics and emergency departments for immediate diagnostic results.
- Semi-Automated Analyzers:These instruments require some manual input for sample loading or reagent preparation, offering a balance between automation and cost-effectiveness. Smaller clinics and laboratories in emerging economies frequently adopt these systems.
- Benchtop Analyzers:Medium-throughput devices suitable for moderate-volume laboratories, providing comprehensive blood cell analysis in a compact footprint. Academic research institutes often utilize benchtop models for specialized studies.
Volume sits with Automated Analyzers; growth tilts toward Portable Analyzers.
End User:
The end-user segmentation highlights distinct application needs across healthcare settings.
- Hospitals:Large hospital networks require integrated hematology systems capable of processing high volumes of patient samples with rapid turnaround times. These institutions prioritize seamless integration with hospital information systems and robust data security.
- Diagnostic Laboratories:Centralized diagnostic laboratories focus on high-throughput automation and advanced analytical capabilities for comprehensive blood cell analysis. These facilities often seek integrated workflow solutions and specialized flagging algorithms.
- Clinics:Smaller clinics and physician offices require user-friendly, compact analyzers for routine blood tests and point-of-care diagnostics. Cost-effectiveness and minimal maintenance are critical purchasing factors for these users.
- Research Institutes:Academic and commercial research facilities utilize hematology analyzers for studying blood disorders, drug development, and cellular analysis. These institutes often require instruments with high precision and flexibility for diverse experimental protocols.
The market prioritizes Hospitals for scale, with Research Institutes showing significant expansion.
Technology:
Technology choices often reflect varying cost structures and performance requirements for laboratories.
- Flow Cytometry:This advanced technology uses laser light and detectors to analyze cell characteristics as they pass through a fluid stream, providing highly accurate cell differentiation and enumeration. Premium instruments in high-throughput laboratories utilize flow cytometry for superior diagnostic accuracy.
- Impedance:Electrical impedance technology counts and sizes blood cells by detecting changes in electrical resistance as cells pass through an aperture. This widely adopted method remains prevalent in semi-automated and core laboratory systems due to its reliability and cost-effectiveness.
- Optical:Optical detection methods utilize light scattering and absorption to characterize blood cells, often complementing impedance for enhanced differentiation. Some automated analyzers combine optical and impedance principles for comprehensive analysis.
- Centrifugation:This method separates blood components based on density, allowing for manual or semi-automated analysis of cell layers. Centrifugation is less common in modern automated hematology analyzers but remains relevant for certain specialized tests.
Demand remains concentrated in Impedance solutions, while Flow Cytometry solutions demonstrate the strongest upward trajectory.
Application:
The application segments reflect the varied volumes and diagnostic complexities encountered in clinical practice.
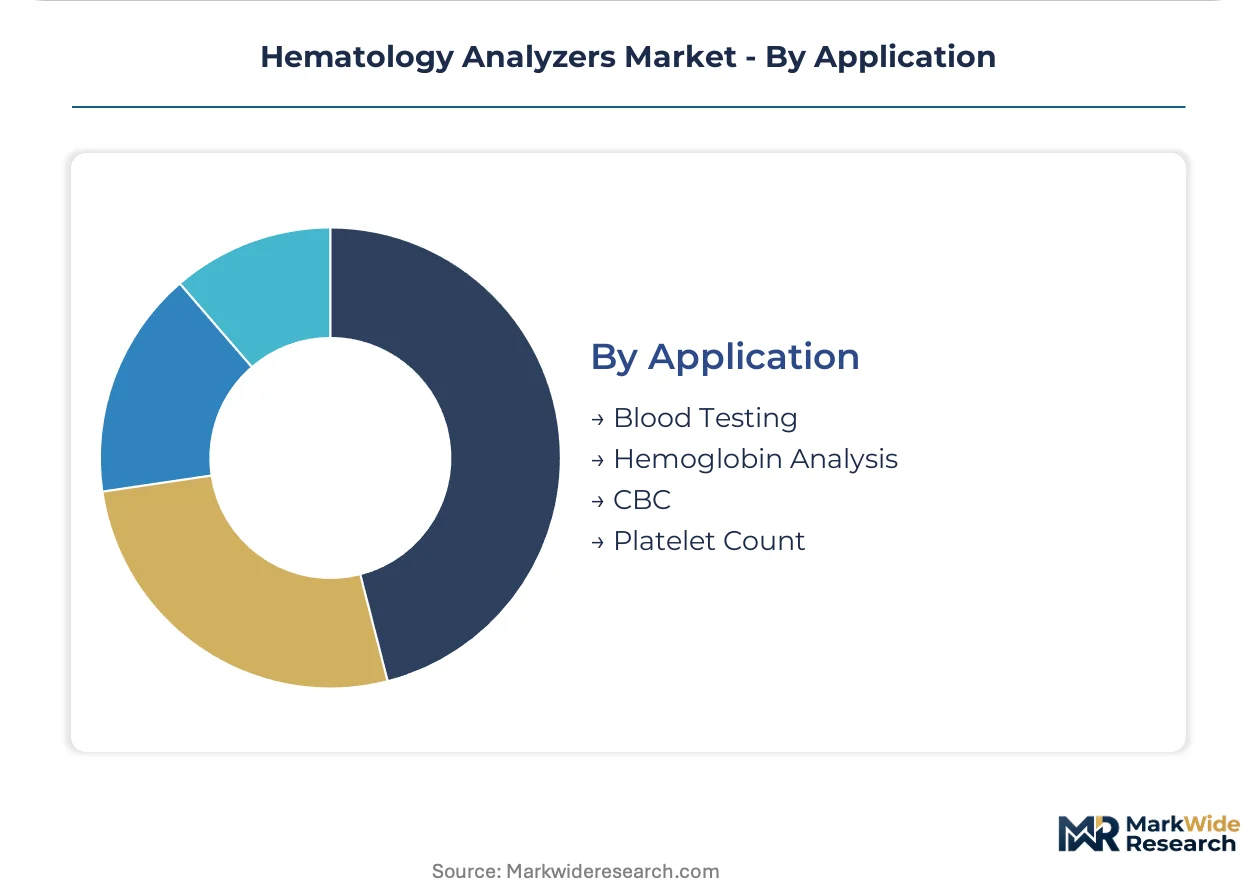
- Blood Testing:This broad category encompasses general health screenings, disease monitoring, and diagnostic investigations requiring comprehensive blood analysis. Routine blood testing represents the largest volume application across all healthcare settings.
- CBC:Complete Blood Count (CBC) is a fundamental diagnostic test providing information on red blood cells, white blood cells, and platelets. The CBC application forms the backbone of hematology analyzer utilization in clinical laboratories.
- Hemoglobin Analysis:This application specifically measures hemoglobin levels in blood, crucial for diagnosing and monitoring anemia and other blood disorders. Specialized analyzers and modules often handle hemoglobin analysis.
- Platelet Count:Accurate platelet counting is essential for assessing coagulation disorders and monitoring treatment efficacy. Advanced analyzers provide precise platelet enumeration and aggregation analysis.
Core diagnostic activities center on Blood Testing, with specialized testing driving demand for Platelet Count.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's expanding healthcare infrastructure anchors the market's regional dynamics. Significant investments in public and private facilities are increasing the installed base of hematology analyzers. This growth supports a larger patient population and higher testing volumes across the country.
China
Chinese demand for hematology analyzers is driven by extensive healthcare infrastructure expansion and a rising prevalence of chronic conditions. The NMPA implements policies to accelerate domestic medical device approvals, fostering local competition. Manufacturers in the Yangtze River Delta region are developing cost-effective systems tailored for regional hospitals.
United States
Demand in the United States concentrates in high-throughput diagnostic laboratories and large hospital networks. FDA 510(k) clearance is a critical regulatory hurdle for market access, ensuring product safety and efficacy. Major medical technology hubs like Boston and California continue to innovate in advanced flow cytometry solutions.
Germany
German market growth stems from advanced technology adoption in academic research institutes and well-established hospital systems. CE marking under the EU's MDR mandates strict quality system compliance for all medical devices. Bavaria and North Rhine-Westphalia house significant R&D centers focusing on premium instrument development.
India
India's market expansion is fueled by substantial public and private investments in healthcare infrastructure, particularly in tier-2 and tier-3 cities. The CDSCO regulates medical device imports and local manufacturing, influencing market entry strategies for multinational vendors. Major medical equipment manufacturing clusters in Maharashtra and Karnataka are gaining prominence.
Japan
Japanese demand for hematology analyzers is supported by an aging population requiring frequent diagnostic testing and strong R&D capabilities. PMDA approvals ensure that advanced diagnostic technologies meet stringent national quality and safety standards. The Kanto region, including Tokyo, remains a hub for innovation in high-precision laboratory instrumentation.
Hematology Analyzers Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue point-of-care and AI-driven diagnostics segments. The market structure exhibits tiered competition, with large conglomerates offering integrated solutions alongside specialized technology innovators. Key strategic archetypes include diversified medical technology providers, focused diagnostics specialists, and regional cost-effective manufacturers. Companies pursue portfolio diversification and strategic partnerships to expand their market reach.
Within the integrated solution providers tier, Sysmex Corporation leverages its strong brand in key Asian markets to secure large-scale contracts. Danaher Corporation, through its Beckman Coulter brand, competes by offering integrated workflow automation solutions that enhance laboratory efficiency. Abbott Laboratories maintains its market position with a diverse portfolio spanning both core laboratory and point-of-care testing systems. These entities exemplify the trend toward comprehensive diagnostic offerings for high-volume end-users and specialized clinical needs.
| Leading Market Players |
|---|
| Sysmex Corporation |
| Danaher Corporation |
| Abbott Laboratories |
| Siemens Healthineers |
| Beckman Coulter Inc. |
| Shenzhen Mindray Bio-Medical Electronics Co. Ltd. |
| HORIBA Ltd. |
| Nihon Kohden Corporation |
| Boule Diagnostics AB |
| Others |
Cost & Logistics Intelligence
Optical component sourcing significantly impacts the final cost of premium hematology analyzers, influencing their pricing across high-throughput laboratory tiers.
Pricing Analysis
Bundled service contracts alongside instrument sales define the primary pricing structure for advanced hematology analyzers. Price differentiation stems from certification levels, such as FDA 510(k) clearance and CE marking, and the extent of after-sales support offered. Cost compression is intensifying in the mid-range segment due to the rise of local competition, particularly from Chinese manufacturers. Smaller clinics and emerging market laboratories exhibit high price sensitivity, while large hospital networks prioritize comprehensive solutions and robust support.
Supply Chain Analysis
Regional distribution centers facilitate the efficient delivery of hematology analyzers and reagents across established markets. Geographic supply concentration for key components resides in countries like China for electronics, Germany for precision engineering, and Japan for optical sensors. Raw material dependencies include specialized reagents, microfluidic chips, and high-performance microcontrollers. Regulatory restrictions, such as NMPA policies affecting imported medical devices in China, represent a structural supply chain risk. Distribution primarily occurs through direct sales channels for major vendors and specialized distributor networks for broader market reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hematology analyzers market is undergoing a significant technology-transition phase, as advanced flow cytometry solutions displace older impedance-based systems in high-throughput laboratories.
For Market Incumbents: Hedge against emerging competition from regional manufacturers by deepening vertical integration into proprietary reagent production. Consolidate market share through strategic acquisitions of specialized AI diagnostics firms to enhance cell differentiation capabilities. Investing in advanced R&D for next-generation flow cytometry technology acts as a critical lever against technological obsolescence.
For New Entrants and Emerging Players: NMPA policies in China open a window for local manufacturers to scale cost-effective hematology analyzers for mid-tier hospitals. Target underpenetrated point-of-care segments in India and Southeast Asia with compact, semi-automated devices. A direct-to-clinic sales model, emphasizing ease of use and local support, will facilitate market entry and build customer loyalty.
For Investors and Strategic Acquirers: The successful integration of AI-driven digital morphology into routine workflows is the leading indicator that predictive diagnostics are gaining clinical acceptance. Long-term viability favors firms capable of offering integrated diagnostic platforms, combining hardware, reagents, and advanced software solutions. Acquisition targets should include innovators in microfluidics for portable systems or AI for advanced cell analysis, focusing on their intellectual property portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand AI-Driven Diagnostics Portfolio | Enhances diagnostic accuracy and provides predictive insights for complex blood conditions. |
| Pursue Point-of-Care Product Development | Addresses demand for rapid, decentralized testing in clinics and remote healthcare settings. |
| Secure Large-Scale Hospital System Contracts | Establishes a stable revenue base and market presence with high-volume purchasers. |
| Invest in Proprietary Reagent Manufacturing | Mitigates supply chain risks and improves margin control for closed-system analyzers. |
| Navigate Regulatory Approval Pathways | Ensures market access and compliance with stringent medical device regulations like FDA 510(k). |
Research Approach
Multi-period observation of installed base expansion and technology upgrades anchored the trend analysis, supplemented by interviews with clinicians, biomedical engineers, GPO managers, and R&D directors. Secondary validation involved reviewing FDA filings, CE marking documentation, NMPA data, hospital procurement databases, and scientific journals. Bottom-up aggregation and top-down market sizing provided triangulation across diverse data points.
An input-output matrix structured the quantitative model, projecting market evolution across the analysis window. Segmentation dimensions included product type, end-user, technology, application, and regional regulatory environments. Compound annual growth rates were derived from historical data extrapolation and expert consensus, integrating factors like patient population growth and healthcare infrastructure investment.
The model assumes a particular technology adoption path; alternative pathways for point-of-care diagnostics would alter the outlook. Forecasts reflect inherent assumptions regarding regulatory stability and economic conditions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Single Blood Drop Analysis Market
Hematology
Global Immunohematology Market
Hematology
Chronic Immune Thrombocytopenia Treatment Market
Hematology
Mantle Cell Lymphoma Treatment Market
Hematology
Chemotherapy-Induced Myelosuppression Treatment Market
Hematology
Multiple Myeloma Therapeutics Market
Hematology
Radiation-Induced Myelosuppression Treatment Market
Hematology
Hematologic Malignancies Market
Hematology
Lymphoproliferative Disorder Treatment Market
Hematology
Follicular Lymphoma Treatment Market
Hematology
Warm Autoimmune Hemolytic Anemia Market
Hematology
Allogeneic Stem Cell Therapy Market
Hematology
Hypereosinophilic Syndrome Market
Hematology
Heparin-Induced Thrombocytopenia (HIT) Treatment Market
Hematology
Congenital Amegakaryocytic Thrombocytopenia (CAMT) Market
Hematology
Global Bleeding Disorders Market