
 Polycythemia Vera Market | 2026-2036
Polycythemia Vera Market Size, Share, and Industry Trends Forecast 2026-2036
Polycythemia Vera Market Analysis
FDA orphan drug exclusivity provisions are rebalancing the cost-of-entry calculus for developers of myeloproliferative neoplasm therapies. Incyte Corporation leverages its first-mover position in JAK inhibition to sustain pricing power in the branded oncology segment. Roche anchors its competitive stance through diagnostic-therapeutic integration, pairing companion testing with therapeutic protocols. Pfizer Inc. differentiates via manufacturing scale that supports global supply security for oral kinase inhibitors.
Polycythemia vera is a Philadelphia-chromosome-negative myeloproliferative neoplasm characterized by clonal expansion of hematopoietic stem cells and elevated red blood cell mass, typically confirmed by JAK2 V617F mutation testing and bone marrow biopsy. The condition drives thrombotic risk management and cytoreductive intervention across hematology practice settings. JAK Inhibitors command the dominant revenue position due to superior splenomegaly and symptom control versus historical hydroxyurea standards. Targeted Therapy segments attract the fastest clinical investment as precision mechanisms displace broad cytotoxic approaches, while Oral administration routes capture preference share from intravenous alternatives in maintenance settings.
FDA, EMA, and the EU MDR collectively enforce pharmacovigilance and manufacturing quality standards that shape trial design, labeling requirements, and post-market surveillance obligations for polycythemia vera therapeutics. These frameworks elevate development costs while creating durable competitive moats for sponsors with established regulatory infrastructure. Stakeholders must monitor evolving MRD detection thresholds and real-world evidence mandates that will redefine value demonstration for payer negotiations.
Market Dynamics
The polycythemia vera therapeutic landscape is undergoing structural transformation as JAK2 inhibitor pipelines mature and FDA accelerated approval pathways compress development-to-commercialization timelines for rare disease indications.
Growth Catalysts
- EMA orphan designation incentives:European regulatory frameworks reduce trial size requirements and extend market exclusivity, lowering capital barriers for novel cytoreductive agents.
- Specialty hematology clinic networks:Concentrated referral pathways in the United States enable rapid adoption of targeted therapies within Medicare-reimbursed outpatient settings.
- JAK2 V617F mutation testing standardization:Companion diagnostic integration into clinical workflows is expanding addressable patient pools eligible for precision intervention.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing for kinase inhibitors clusters in specific Asian contract manufacturing organizations, creating single-source vulnerability.
- EU MDR compliance burden:In vitro diagnostic reclassification requirements are extending companion test approval timelines and elevating quality management system costs.
- Hydroxyurea generic substitution:Established low-cost cytoreduction creates pricing ceiling pressure for novel branded entrants in front-line settings.
Strategic Opportunities
- Real-world evidence mandates:FDA and EMA post-market surveillance requirements create demand for registry infrastructure partnerships between sponsors and hematology networks.
- Subcutaneous administration formats:Novel delivery mechanisms address patient compliance gaps in oral JAK inhibitor maintenance regimens.
- Minimal residual disease monitoring:Next-generation sequencing integration into response assessment protocols opens adjacent diagnostic service revenue streams.
Industry Challenges
- Hematopathology specialist scarcity:Bone marrow biopsy interpretation expertise concentrates in academic medical centers, limiting community-based trial enrollment capacity.
- Cross-border pharmacovigilance harmonization:Divergent FDA-EMA adverse event reporting standards complicate global safety database management for multinational sponsors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polycythemia Vera Market |
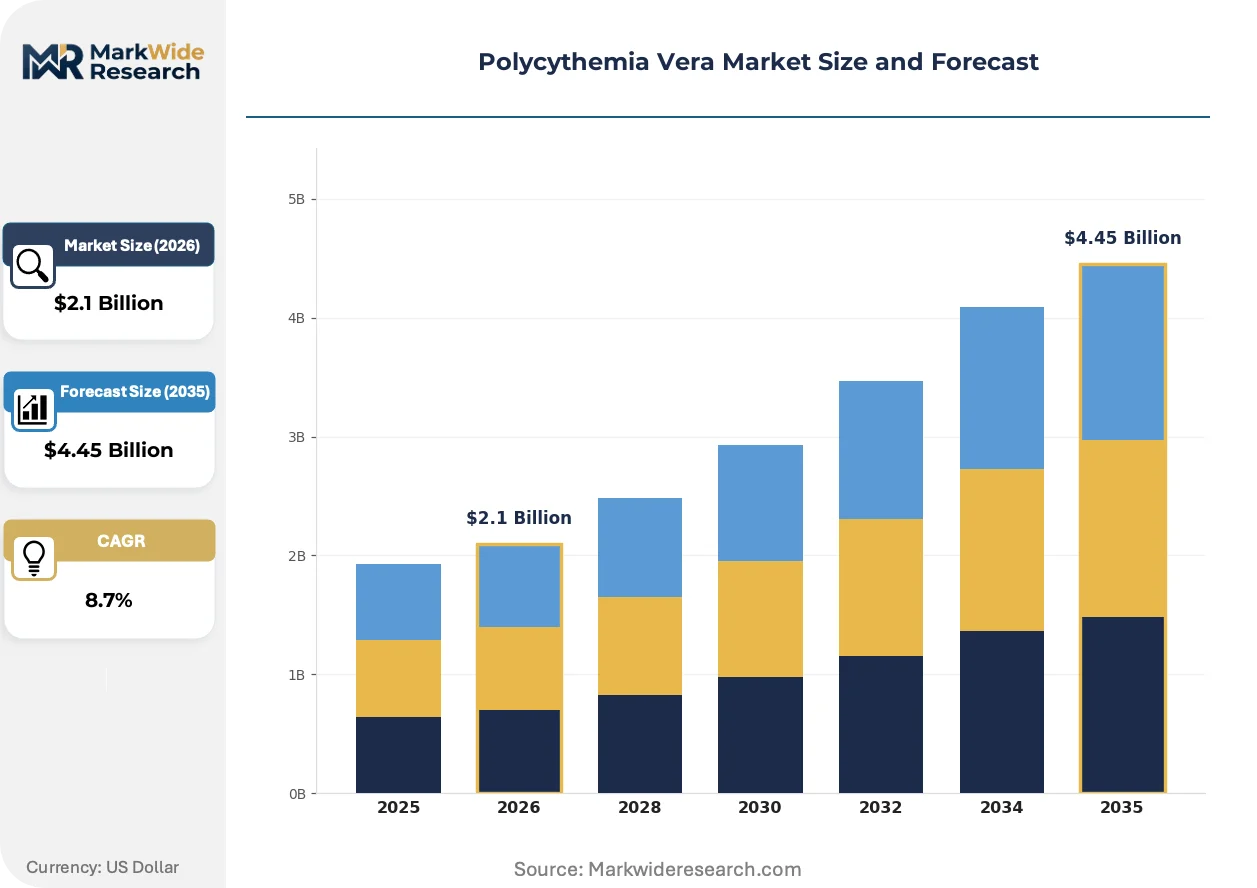
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
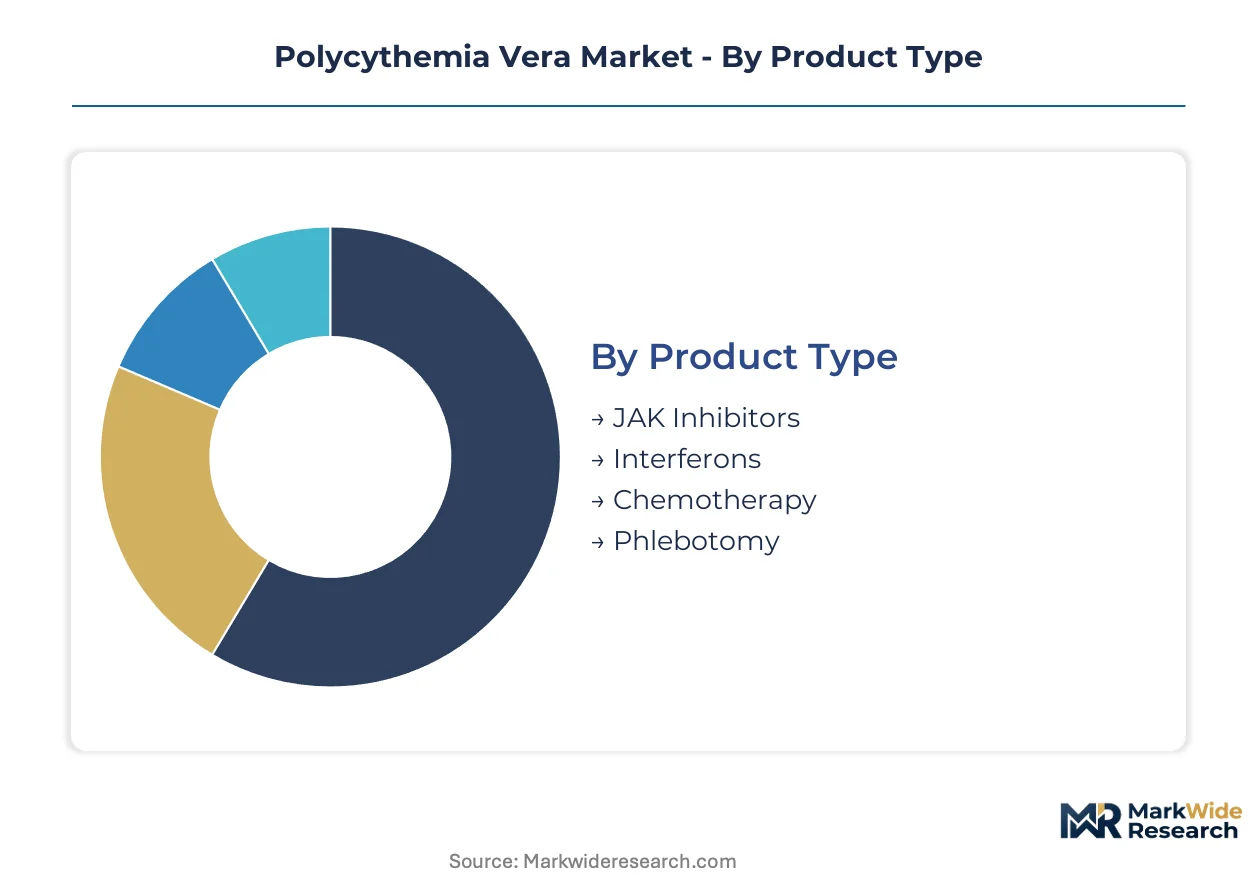
| Segmentation | Product Type: JAK Inhibitors, Interferons, Chemotherapy, Phlebotomy Treatment Approach: Targeted Therapy, Symptom Management, Combination Treatment, Supportive Care Administration Route: Oral, Injectable, Intravenous, Subcutaneous End User: Hospitals, Outpatient Clinics, Research Laboratories, Homecare |
| Companies Covered | Pfizer Inc., Roche, Novartis AG, Merck & Co., Inc., Protagonist Therapeutics, Incyte Corporation, PharmaEssentia Corporation, Gilead Sciences, Inc., Bristol-Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polycythemia Vera Market Emerging Trajectories
Precision medicine architectures are restructuring polycythemia vera care delivery, with molecular stratification replacing empirical treatment selection and digital biomarkers supplementing conventional response criteria.
Next-generation JAK inhibitors with improved selectivity profiles are consolidating therapeutic positioning in second-line and refractory patient segments. Academic medical centers in Germany and the United States are prioritizing these agents for patients with inadequate responses to hydroxyurea. The technology is consolidating prescribing influence within specialized myeloproliferative neoplasm centers at the expense of general hematology-oncology practices.
REACH regulation compliance requirements for pharmaceutical manufacturing are reshaping supply chain qualification protocols for European market access. ECHA substance of very high concern listings are forcing reformulation of certain excipient compositions used in oral kinase inhibitor tablets. Sponsors with established green chemistry programs are capturing preferred supplier status with EU-based contract manufacturers.
Patient-reported outcome integration into reimbursement negotiations is altering value demonstration requirements for cytoreductive therapies. German statutory health insurance funds are conditioning coverage decisions on symptom burden data collected through validated instruments. This behavioral shift is most pronounced in European markets where health technology assessment bodies command formal influence over pricing and access.
Polycythemia Vera Market Segmentation
Molecular stratification in polycythemia vera care demands precise segment alignment between therapeutic modality and clinical setting. Treatment selection now hinges on JAK2 mutation status, symptom burden, and thrombotic risk profile rather than empirical protocols.
Product Type:
Standalone therapeutic agents dominate front-line protocols, while combination-ready formulations embed into multi-modal regimens for refractory cases.
- JAK Inhibitors:Small-molecule agents targeting JAK1/JAK2 kinases deliver superior splenomegaly reduction and constitutional symptom control versus hydroxyurea. Demand concentrates in United States specialty hematology clinics where Medicare reimbursement favors oral targeted agents. Incyte Corporation's first-mover position sustains premium pricing power in this segment.
- Interferons:Recombinant alpha-interferons and pegylated variants induce molecular responses with disease-modifying potential in younger patients. German academic medical centers prioritize interferon therapy for cytoreduction in pregnancy-eligible populations. EMA orphan designation incentives accelerate pipeline expansion for next-generation interferon formulations.
- Chemotherapy:Hydroxyurea remains the historical standard for cytoreduction in high-risk thrombotic patients.
- Phlebotomy:Mechanical red cell reduction addresses iron deficiency and hematocrit control in low-risk cohorts.
JAK Inhibitors lead volumes today; Interferons are gaining share fastest.
Treatment Approach:
Cost-tier stratification separates precision interventions from supportive modalities, with reimbursement thresholds determining access to molecularly targeted options.
- Targeted Therapy:Mechanism-driven interventions using JAK inhibitors or interferons address clonal disease biology. United States payers require companion diagnostic confirmation for prior authorization. FDA accelerated approval pathways compress commercialization timelines for novel agents in this category.
- Symptom Management:Pruritus control, fatigue mitigation, and microvascular symptom relief address quality-of-life endpoints. Patient-reported outcome integration into German statutory health insurance coverage decisions elevates demand for validated instruments. This segment expands most quickly as value demonstration requirements tighten.
- Combination Treatment:Sequential or concurrent multi-agent protocols for refractory disease.
- Supportive Care:Anticoagulation, cardiovascular risk modification, and thrombosis prevention.
Targeted Therapy commands premium pricing tiers; Symptom Management shows steepest expansion trajectory.
Administration Route:
Patient compliance patterns and clinic capacity constraints determine route selection, with oral formats reducing infusion chair dependency.
- Oral:Tablet and capsule formulations of ruxolitinib and fedratinib enable home-based maintenance therapy. Outpatient clinic networks in the United States prioritize oral agents to maximize Medicare-reimbursed patient throughput. Manufacturing scale at Pfizer Inc. secures global supply continuity for kinase inhibitor tablets.
- Injectable:Pegylated interferon formulations require less frequent administration than standard interferon.
- Intravenous:Hospital-based infusion for acute cytoreduction or clinical trial protocols.
- Subcutaneous:Novel delivery mechanisms address compliance gaps in maintenance regimens.
Oral administration leads prescription volumes; Subcutaneous formats are climbing the fastest.
End User:
Site-of-care economics and specialist availability shape patient flow, concentrating complex cases in academic centers while shifting stable patients to community settings.
- Hospitals:Academic medical centers manage high-risk thrombotic events, transformation to myelofibrosis, and clinical trial enrollment. Bone marrow biopsy interpretation expertise concentrates in United States and German university hospitals. Hematopathology specialist scarcity limits community-based trial capacity.
- Outpatient Clinics:Specialty hematology networks deliver maintenance JAK inhibitor therapy and phlebotomy services. Medicare reimbursement policies favor United States outpatient administration settings. Concentrated referral pathways enable rapid adoption of targeted therapies.
- Research Laboratories:Companion diagnostic testing and minimal residual disease monitoring.
- Homecare:Oral therapy administration and remote symptom monitoring.
Outpatient Clinics lead patient volumes; Research Laboratories are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hematopathology specialists concentrate in academic medical centers across the United States, Germany, and Japan, anchoring regional capacity for bone marrow biopsy interpretation and clinical trial enrollment. These talent clusters determine where novel JAK inhibitor therapies achieve first adoption and where companion diagnostic testing achieves workflow integration.
United States
Medicare reimbursement policies favor outpatient administration settings for oral JAK inhibitors, concentrating patient volumes in specialty hematology clinic networks. FDA accelerated approval pathways compress commercialization timelines for rare disease indications. The Mayo Clinic in Rochester and MD Anderson in Houston anchor myeloproliferative neoplasm referral pathways that drive rapid targeted therapy adoption.
Germany
German statutory health insurance funds condition coverage decisions on patient-reported outcome data, elevating demand for validated symptom burden instruments. EMA orphan designation incentives reduce trial size requirements for novel cytoreductive agents. Heidelberg University Hospital and Charité Berlin concentrate interferon therapy expertise for pregnancy-eligible patient populations.
Japan
PMDA regulatory frameworks emphasize pharmacovigilance harmonization with FDA standards, streamlining multinational sponsor safety database management. METI industrial policy supports domestic manufacturing scale for oral kinase inhibitor supply security. Tokyo and Osaka academic medical centers lead Asia-Pacific enrollment in JAK inhibitor clinical trials.
Switzerland
Swissmedic maintains alignment with EMA centralized procedures while offering rapid national authorization pathways for breakthrough oncology therapies. The country's diagnostic-therapeutic integration expertise concentrates in Basel and Geneva clusters. Roche anchors companion diagnostic development partnerships that reshape molecular stratification protocols.
United Kingdom
NICE health technology assessment mandates condition NHS access decisions on cost-effectiveness thresholds that pressure branded therapy pricing. The MHRA operates post-Brexit recognition pathways for EMA-approved rare disease treatments. London and Manchester hematology networks drive real-world evidence collection for payer negotiation preparation.
Polycythemia Vera Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the polycythemia vera therapeutic landscape, creating a tiered market structure where scale advantages meet regulatory agility. Large-cap pharmaceutical firms leverage manufacturing infrastructure and global distribution networks to secure supply continuity for oral kinase inhibitors. Mid-cap biotech specialists concentrate R&D investment on next-generation JAK selectivity profiles and novel interferon formulations. Strategic moves center on diagnostic-therapeutic integration partnerships and real-world evidence registry collaborations with academic hematology networks.
Within the diversified pharmaceutical tier, Pfizer Inc. and Roche occupy positions defined by manufacturing scale and diagnostic integration capabilities respectively. Incyte Corporation exemplifies the focused specialist archetype, having established first-mover positioning in JAK inhibition that sustains premium pricing power in branded oncology segments. These three anchors represent the competitive spectrum from global supply security to precision mechanism development.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Roche |
| Novartis AG |
| Merck & Co., Inc. |
| Protagonist Therapeutics |
| Incyte Corporation |
| PharmaEssentia Corporation |
| Gilead Sciences, Inc. |
| Bristol-Myers Squibb |
| Others |
Supply Flow & Price Mechanics
Active pharmaceutical ingredient spot indices for kinase inhibitors cascade through contract manufacturing tiers into differentiated pricing bands for oral JAK inhibitors versus legacy hydroxyurea generics. This cost transmission mechanism stratifies patient access across Medicare-reimbursed outpatient settings and cash-pay markets.
Pricing Analysis
Companion diagnostic bundling separates premium JAK inhibitor protocols from unbundled phlebotomy services. FDA-accelerated orphan drug exclusivity sustains branded pricing power in first-line cytoreduction, while hydroxyurea generic substitution compresses margins at the standard tier. Price differentiation hinges on molecular stratification requirements and site-of-care economics. Community hematology clinics exhibit highest price sensitivity due to formulary budget constraints; academic medical centers show lowest sensitivity where trial infrastructure offsets acquisition costs.
Supply Chain Analysis
Domestic-content mandates in Japanese METI industrial policy and emerging US pharmaceutical security provisions are reshaping API sourcing away from concentrated Asian contract manufacturers. Kinase inhibitor production draws from India, China, and South Korea for intermediate chemical synthesis, with final formulation clustering in Switzerland and the United States. Single-source vulnerability pervades JAK2 inhibitor active pharmaceutical ingredient supply. Distribution runs through specialty pharmacy networks and hospital outpatient infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polycythemia vera therapeutic landscape functions as a stable compounder anchored by Medicare reimbursement durability for oral targeted agents in aging populations.
For Market Incumbents: Cement diagnostic-therapeutic integration partnerships with academic hematology networks to lock in companion diagnostic workflows. Deepen backward integration into JAK inhibitor API supply through preferred contracting with Indian and Chinese manufacturers. Incyte Corporation's first-mover positioning demonstrates how regulatory infrastructure investment creates durable moats against biosimilar entrants. For New Entrants and Emerging Players: Next-generation interferon selectivity profiles offer a technology-first wedge into pregnancy-eligible patient segments where JAK inhibitors carry teratogenic liability. German academic medical centers represent the most penetrable geography given EMA orphan designation incentives and established interferon expertise. Pursue subcutaneous formulation development to differentiate from oral JAK inhibitor compliance gaps. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap biotech specialists possessing Phase II JAK2 inhibitor assets and established regulatory affairs infrastructure. The five-to-ten year viability window favors platforms with pipeline diversification beyond single-mechanism dependence. Watch FDA real-world evidence mandate implementation as the inflection signal for registry infrastructure valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | Roche anchors competitive positioning through paired testing and therapeutic protocols. |
| Manufacturing Scale-Up | Pfizer Inc. leverages global tablet production capacity to secure supply continuity. |
| Real-World Evidence Registry | German statutory health insurance funds condition coverage on validated patient-reported outcomes. |
| Subcutaneous Formulation Development | Novel delivery mechanisms address compliance gaps in maintenance JAK inhibitor regimens. |
| EMA Orphan Designation Pathway | Reduced trial size requirements accelerate pipeline expansion for interferon cytoreductive agents. |
Methodological Framework
Bottom-up hematology clinic throughput modeling reconciled against top-down pharmaceutical manufacturing tracking forms the analytical core. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists cross-validated against FDA filings, EMA submissions, ClinicalTrials.gov records, and Medicare reimbursement databases. Secondary sources include hospital procurement databases, GPO contracts, and specialty pharmacy dispensing records.
Input-output matrices map JAK inhibitor prescription volumes through administration route, treatment line, patient risk stratification, and regional regulatory clusters across the projection horizon. CAGRs derive from segmented volume-price interactions and patent expiry modeling. Forecast inputs incorporate JAK2 V617F testing penetration rates and Medicare Advantage formulary placement trends.
The model holds under stable FDA orphan exclusivity enforcement and consistent Medicare reimbursement rates; deviation in health technology assessment mandates or API supply disruptions would shift volume trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Global Sickle Cell Disease Treatment Market
Hematology
Thalassemia Treatment Market
Hematology
Erythropoietic Protoporphyria (EPP) Treatment Market
Hematology
Global Hematologic Malignancies Treatment Market
Hematology
Hairy Cell Leukemia Treatment Market
Hematology
Immune Thrombocytopenia (ITP) Market
Hematology
APAC Acute Myeloid Leukemia Treatment Market
Hematology
Hematologic Malignancies Market
Hematology
Acute Lymphoblastic Leukemia Market
Hematology
Blood Screening Market
Hematology
Global Non-Hodgkin Lymphoma Therapeutics Market
Hematology
Alpha Thalassemia Market
Hematology
Small Lymphocytic Lymphoma Market
Hematology
Idiopathic Thrombocytopenic Purpura Market
Hematology
Global Immunohematology Market
Hematology
Hemoglobin Analyzer Market