
 PACS and RIS Market | 2026-2036
PACS and RIS Market Size, Share, and Industry Trends Forecast 2026-2036
PACS and RIS Market Analysis
Multi-source procurement of imaging IT components is broadening as health systems reduce dependence on single-vendor ecosystems. GE HealthCare leverages deep modality integration to sustain installed-base loyalty across radiology departments. Siemens Healthineers anchors European hospital networks with native RIS-PACS interoperability, while Philips Healthcare competes through enterprise-wide diagnostic informatics platforms that extend beyond cardiology and oncology into pathology workflows.
Picture Archiving and Communication Systems (PACS) and Radiology Information Systems (RIS) constitute integrated software platforms that manage medical image storage, retrieval, distribution, and examination workflow orchestration, typically supporting DICOM and HL7 FHIR protocols for data exchange. Their primary purpose is to replace film-based radiology with digital workflows that accelerate diagnosis, enable remote consultation, and consolidate imaging records across hospital departments. Cloud-based and SaaS deployment models are gaining structural momentum as capital-constrained imaging centers prioritize operational expenditure over upfront licensing, while integrated interoperability configurations command premium positioning due to their capacity to unify siloed specialty workflows. Stand-alone PACS installations retain relevance in smaller clinics with limited IT infrastructure.
FDA 21 CFR Part 820 governs quality system design for medical device software, directly influencing validation requirements for PACS and RIS deployments in United States clinical settings. HIPAA security and privacy rules mandate encryption standards and access controls that shape vendor product roadmaps and hospital procurement checklists. The Office of the National Coordinator for Health IT pushes interoperability mandates through the 21st Century Cures Act that require API-enabled data exchange. Stakeholders must weigh cloud migration timelines against evolving federal certification requirements and the operational risks of hybrid infrastructure during transition periods.
Market Dynamics
Hospital networks are dismantling single-vendor imaging ecosystems to reduce lock-in risk, forcing PACS and RIS vendors to prove interoperability across heterogeneous IT estates rather than proprietary stack dominance.
Growth Catalysts
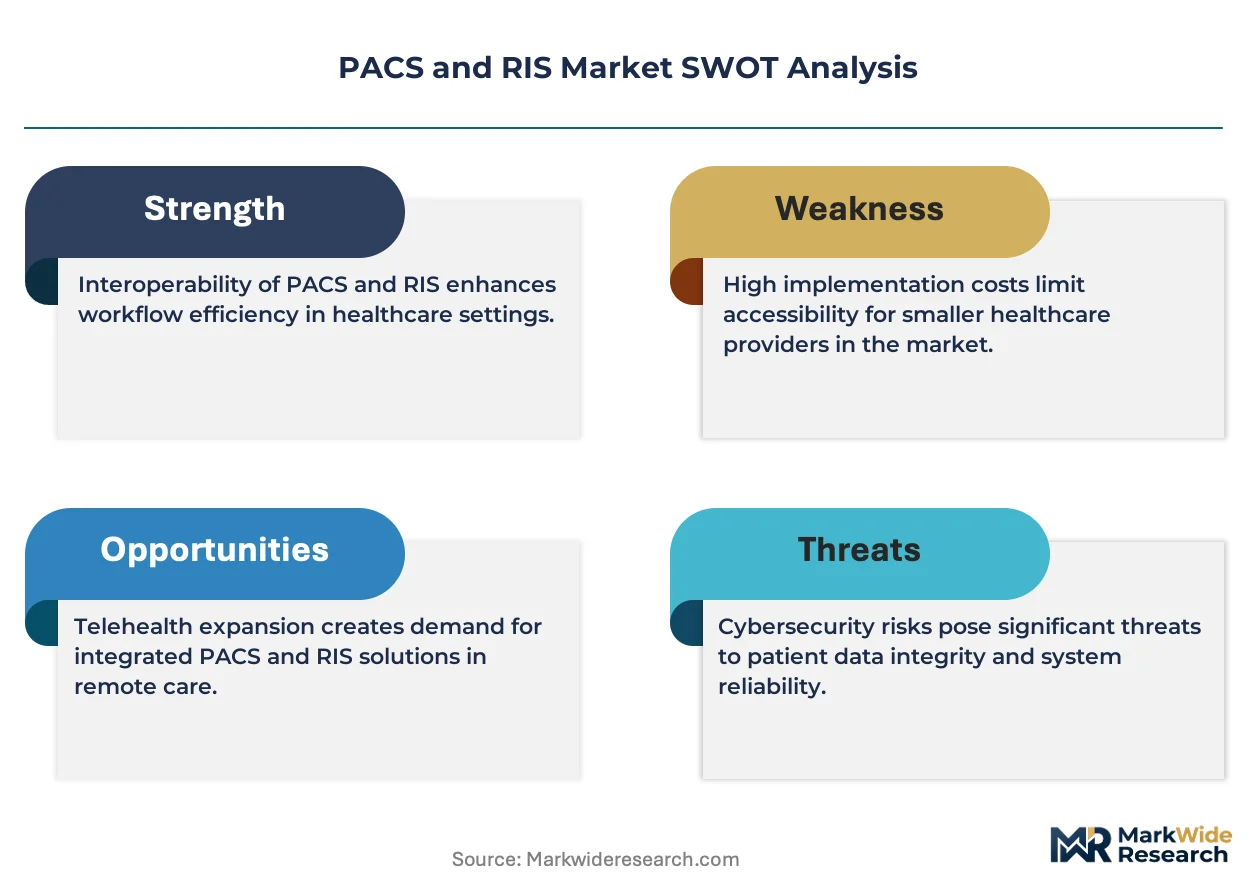
- HIPAA security mandates:Encryption and access control requirements from the 1996 statute are accelerating replacement cycles for legacy systems that lack modern cybersecurity architectures in United States hospital networks.
- Cloud-native deployment models:SaaS delivery is displacing perpetual licensing in capital-constrained imaging centers, converting upfront expenditure into predictable operational budgets.
- Enterprise imaging consolidation:United States, Germany, and Japan are modernizing radiology IT estates to unify cardiology, pathology, and oncology workflows under single diagnostic informatics platforms.
Market Restraints
- Hybrid infrastructure complexity:Transitional states between on-premise archives and cloud repositories create operational friction and data sovereignty risks during multi-year migration timelines.
- FDA 21 CFR Part 820 validation burden:Quality system documentation requirements for medical device software extend procurement cycles and inflate implementation costs for United States deployments.
- DICOM-HL7 FHIR interoperability gaps:Protocol translation between legacy PACS and modern health information exchanges requires costly middleware that smaller clinics cannot sustain.
Strategic Opportunities
- Pathology workflow extension:Digital pathology adoption in oncology centers creates demand for PACS architectures that ingest whole-slide imaging alongside radiology DICOM streams.
- API-enabled data exchange:21st Century Cures Act interoperability mandates are opening federal reimbursement pathways for vendors that certify seamless health information exchange capabilities.
- Remote consultation infrastructure:Teleradiology networks in rural United States markets require cloud-native RIS deployments with sub-second latency for emergency stroke and trauma reads.
Industry Challenges
- Legacy system integration:Decades-old departmental PACS installations resist standard data migration, forcing expensive custom extraction tools and extended parallel operation periods.
- Specialized informatics talent scarcity:Health systems compete for radiology IT architects who understand both DICOM metadata structures and modern Kubernetes container orchestration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PACS and RIS Market |
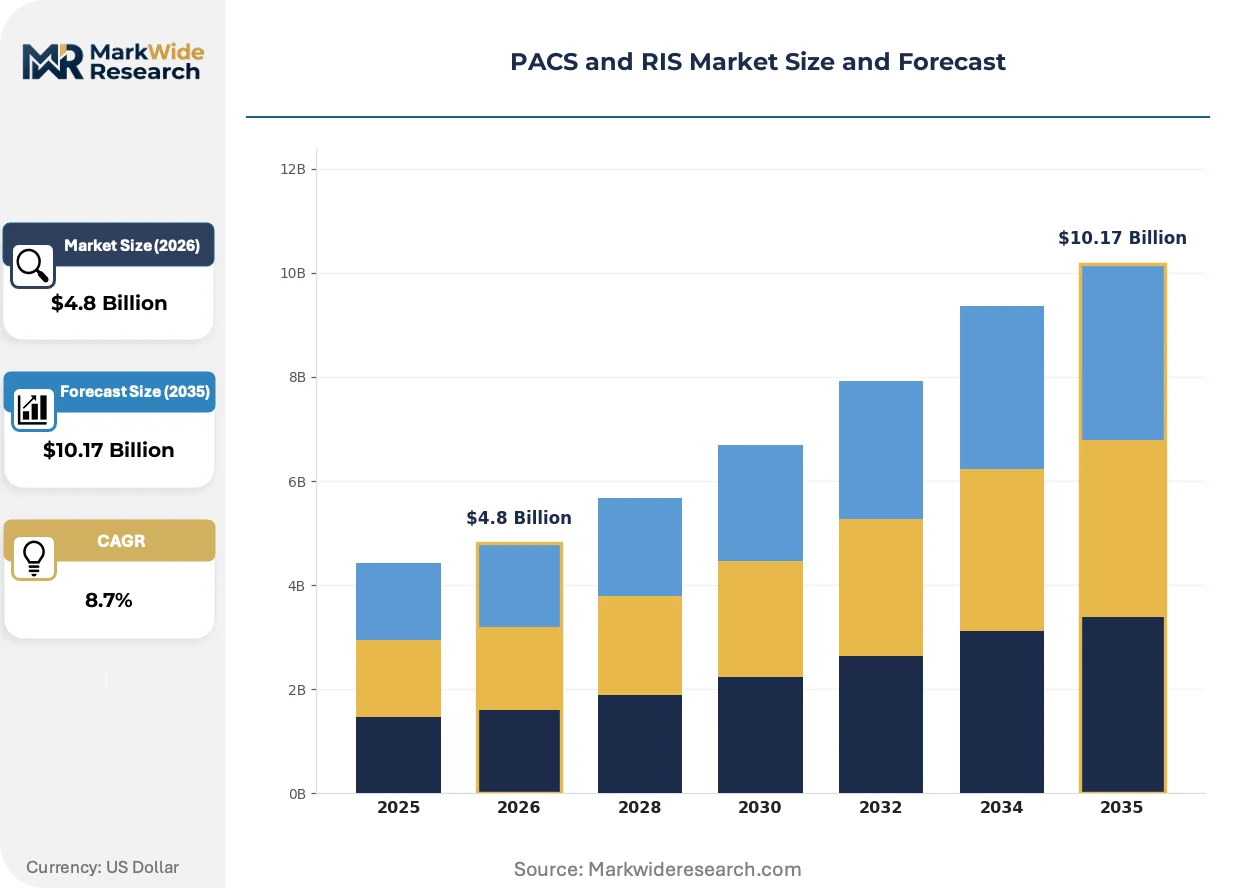
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PACS, RIS, Modality Worklist, Image Management Deployment Model: On-Premise, Cloud-Based, Hybrid, SaaS End User: Hospitals, Imaging Centers, Clinics, Research Facilities Integration Level: Stand-Alone, Integrated, Interoperable, Customizable |
| Companies Covered | Fujifilm Holdings Corporation, McKesson Corporation, GE HealthCare, Allscripts Healthcare Solutions, Cerner Corporation, Siemens Healthineers, Agfa-Gevaert Group, Canon Medical Systems Corporation, Philips Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PACS and RIS Market Emerging Trajectories
Artificial intelligence inference engines are embedding directly into imaging workflows, compressing diagnostic turnaround from hours to minutes while restructuring how radiologists interact with diagnostic software.
AI-powered clinical decision support is integrating anomaly detection algorithms into PACS viewer layers, flagging critical findings for priority review. Academic medical centers in the United States are deploying these tools for pulmonary embolism and intracranial hemorrhage screening. The technology is integrating radiologist workflow prioritization with automated report generation, reducing time-to-diagnosis for emergency cases.
The European Union's Medical Device Regulation is reclassifying AI-enabled diagnostic software as Class IIa or higher medical devices, imposing clinical validation and post-market surveillance obligations on vendors. Manufacturers must now maintain quality management systems equivalent to traditional hardware device producers. Software-only PACS vendors without existing MDR infrastructure face certification barriers that favor established modality manufacturers with regulatory affairs departments.
Subscription-based commercial models are displacing perpetual license sales in mid-market hospital segments, with buyers preferring operational expenditure classification for budget flexibility. Imaging centers in Germany and Japan are negotiating multi-year SaaS contracts that bundle storage, software updates, and cybersecurity monitoring. This shift pressures vendor cash flow structures and forces product development cycles toward continuous deployment rather than versioned releases.
PACS and RIS Market Segmentation
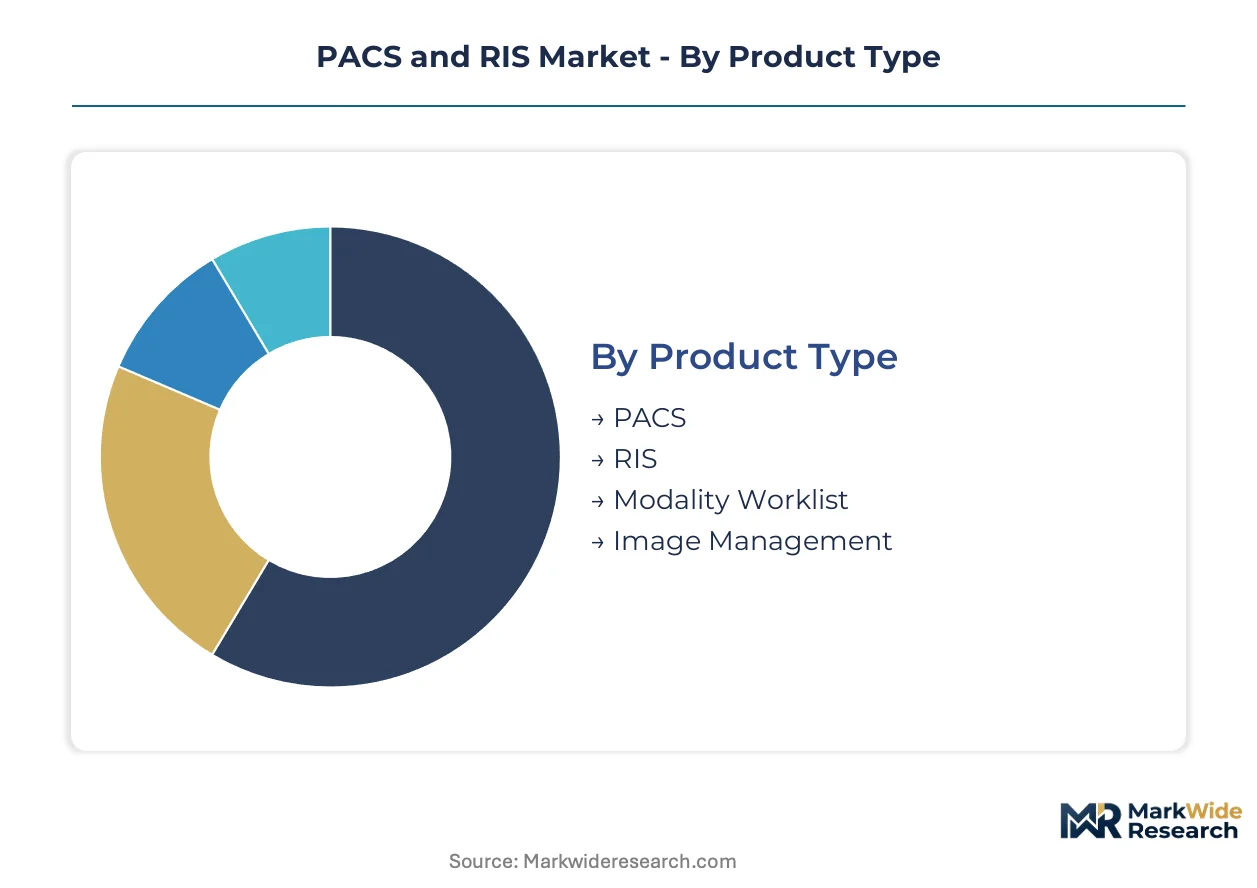
PACS and RIS procurement patterns diverge sharply by infrastructure maturity and capital availability. Hospital networks weigh interoperability depth against total cost of ownership, while smaller providers prioritize deployment simplicity over enterprise-grade feature sets.
Product Type:
Volume deployments concentrate in modular components that slot into existing IT estates, while premium positioning attaches to unified platforms that consolidate multiple workflow layers.
- PACS:Digital image storage and retrieval systems supporting DICOM standardization across radiology departments. Demand concentrates in United States hospital networks modernizing legacy archives to meet HIPAA encryption mandates and enable cloud-hybrid architectures.
- RIS:Examination scheduling, workflow orchestration, and reporting platforms that interface with hospital information systems. Academic medical centers in Germany and Japan are prioritizing native RIS-PACS integration to reduce middleware dependencies and accelerate turnaround times.
- Modality Worklist:DICOM MPPS-compliant scheduling bridges connecting imaging devices to hospital information systems. Critical for high-throughput CT and MRI suites.
- Image Management:Vendor-neutral archive layers enabling cross-departmental image sharing. Gaining traction in oncology centers consolidating radiology and pathology workflows.
Today's leader: PACS. Tomorrow's challenger: RIS.
Deployment Model:
Procurement patterns split between capital-constrained buyers seeking operational expenditure classification and risk-averse institutions demanding data sovereignty controls.
- On-Premise:Local server installations with full data custody retained by hospital IT departments. Large United States health systems with dedicated security operations centers favor this model to satisfy HIPAA audit requirements and maintain sub-millisecond latency for emergency reads.
- Cloud-Based:Fully hosted infrastructure with remote data centers managing storage and compute. Imaging centers in Japan are expanding fastest here, converting upfront licensing into predictable monthly expenditures while outsourcing cybersecurity monitoring.
- Hybrid:Tiered architectures keeping recent studies on-premise while archiving historical records to cloud repositories. Addresses transitional states during multi-year migration timelines.
- SaaS:Subscription software delivery with continuous feature updates and managed infrastructure. Mid-market German hospitals negotiate multi-year contracts bundling storage, updates, and compliance monitoring.
On-premise retains installed-base dominance. SaaS is climbing the fastest among new procurements.
End User:
Scale requirements and regulatory exposure determine feature prioritization across buyer categories, from enterprise interoperability to single-physician usability.
- Hospitals:Enterprise-grade deployments requiring EMR integration, multi-site federation, and 99.999% uptime SLAs. United States hospital networks are dismantling single-vendor ecosystems to reduce lock-in risk.
- Imaging Centers:High-volume, specialized facilities prioritizing throughput optimization and teleradiology connectivity. Rural United States markets drive demand for sub-second latency cloud-native RIS deployments.
- Clinics:Limited IT infrastructure settings favoring stand-alone PACS with minimal configuration overhead.
- Research Facilities:Academic medical centers requiring DICOM-structured data pipelines for clinical trial imaging cores and AI training datasets.
Hospitals command procurement volume. Imaging centers are expanding most quickly.
Integration Level:
Interoperability depth directly correlates with implementation complexity and long-term vendor switching costs.
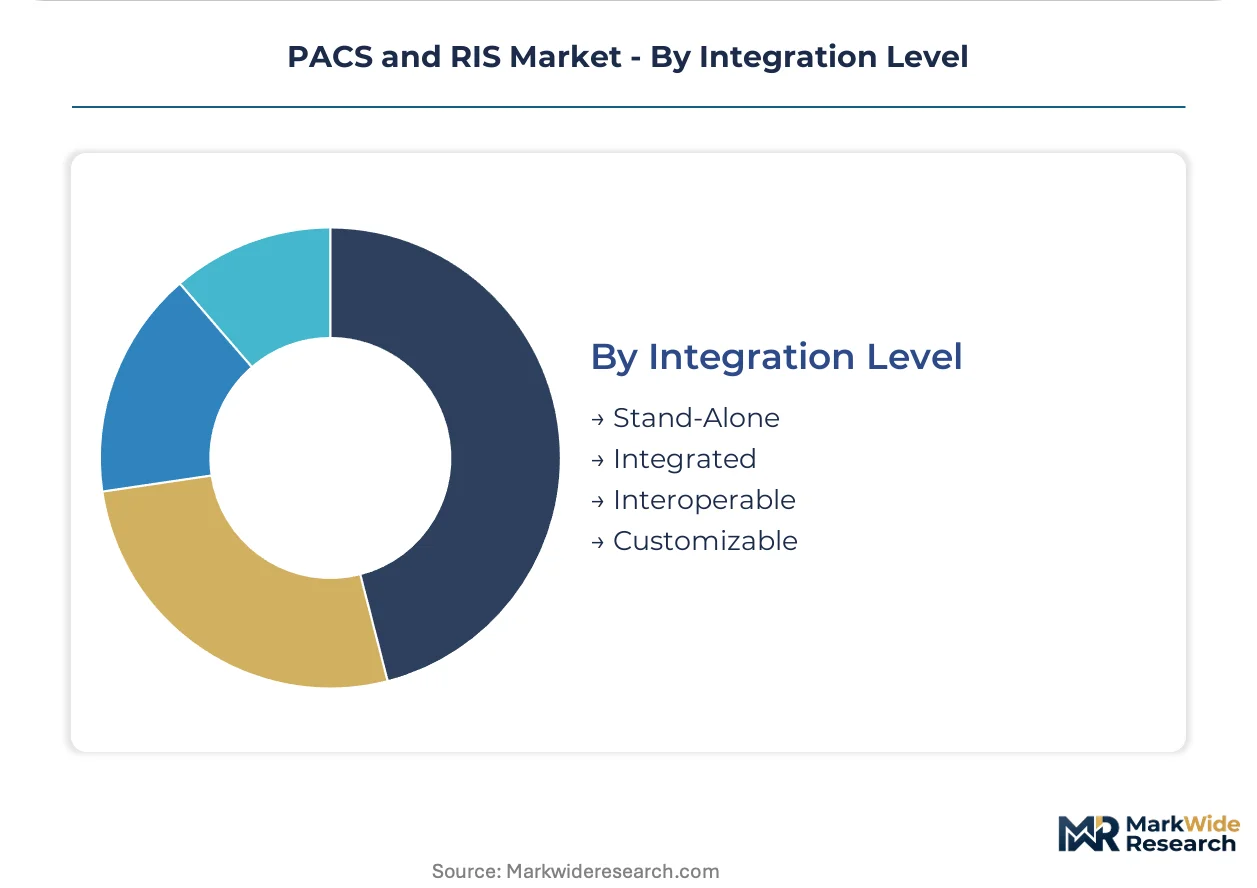
- Stand-Alone:Self-contained departmental systems with minimal external interfaces. Smaller clinics with limited IT staffing sustain demand for simplified deployments.
- Integrated:Native RIS-PACS combinations from single vendors reducing middleware requirements. European hospital networks anchor procurement here.
- Interoperable:API-enabled platforms certified for 21st Century Cures Act health information exchange mandates. United States vendors pursue federal reimbursement pathways through this classification.
- Customizable:Modular architectures permitting workflow-specific configuration and specialty-specific viewer customization. Oncology centers demand this for pathology workflow extension.
Integrated systems hold current preference. Interoperable configurations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital networks in the United States anchor enterprise imaging procurement volume, with Germany and Japan following as concentrated modernization markets. Regulatory mandates from FDA, EU MDR, and Japan's PMDA reshape vendor certification requirements across these territories.
United States
Academic medical centers in Boston and the Research Triangle are dismantling single-vendor imaging ecosystems to reduce lock-in risk. FDA 21 CFR Part 820 quality system regulations extend procurement cycles for cloud-native deployments. The Cleveland Clinic and Mayo Clinic networks are piloting API-enabled platforms that satisfy 21st Century Cures Act interoperability mandates.
Germany
University hospitals in Bavaria and North Rhine-Westphalia prioritize native RIS-PACS integration to eliminate middleware dependencies. The EU Medical Device Regulation reclassifies AI-enabled diagnostic software as Class IIa devices, imposing clinical validation obligations on vendors. Siemens Healthineers anchors European hospital networks from its Erlangen headquarters.
Japan
Imaging centers in Tokyo and Osaka are expanding cloud-based deployments fastest among developed markets, converting upfront licensing into predictable operational budgets. METI digital health initiatives and PMDA software validation guidelines shape procurement checklists. Canon Medical Systems and Fujifilm Holdings drive domestic vendor competition.
United Kingdom
NHS trusts in London and Manchester are consolidating radiology IT estates under enterprise diagnostic informatics platforms. GDPR data sovereignty requirements and NHS Digital cybersecurity frameworks complicate hybrid cloud migrations. The Cambridge-Oxford-London corridor concentrates academic medical center demand for AI-integrated PACS architectures.
India
Private hospital chains in Maharashtra and Karnataka are adopting SaaS delivery models to bypass capital constraints on IT infrastructure. CDSCO medical device software regulations and state-level digital health missions accelerate standardization. Apollo Hospitals and Fortis Healthcare networks in Hyderabad and Bengaluru drive mid-market procurement volume.
PACS and RIS Market Vendor Landscape
Global majors compete with regional champions across regulatory certification depth and modality integration breadth. The vendor base clusters around three strategic tiers: diversified health technology conglomerates with end-to-end imaging stacks, specialized diagnostic informatics vendors with workflow-specific expertise, and cloud-native software platforms targeting capital-constrained providers. Consolidation pressures favor established modality manufacturers with existing FDA and EU MDR quality management infrastructure over software-only entrants facing certification barriers.
Within the diversified health technology tier, GE HealthCare, Siemens Healthineers, and Philips Healthcare exemplify archetypes competing through deep modality integration and enterprise-wide platform positioning. These manufacturers occupy positions where installed-base loyalty across radiology departments sustains replacement cycle capture. Regional specialists including Fujifilm Holdings and Canon Medical Systems anchor Asia-Pacific procurement flows with localized service networks and regulatory compliance pathways tailored to PMDA and CDSCO requirements.
| Leading Market Players |
|---|
| Fujifilm Holdings Corporation |
| McKesson Corporation |
| GE HealthCare |
| Allscripts Healthcare Solutions |
| Cerner Corporation |
| Siemens Healthineers |
| Agfa-Gevaert Group |
| Canon Medical Systems Corporation |
| Philips Healthcare |
| Others |
Supply Flow & Price Mechanics
Hospital procurement committees in the United States anchor pricing power through multi-year SaaS contract negotiations that bundle storage, cybersecurity monitoring, and compliance updates into predictable operational expenditures. This buyer concentration shifts vendor revenue recognition from perpetual licensing toward recurring subscription models.
Pricing Analysis
Input-cost pass-through from cloud infrastructure providers and cybersecurity compliance tooling compresses margins for SaaS-native vendors. Pricing stratifies across enterprise-grade integrated platforms, mid-market interoperable configurations, and stand-alone departmental systems. Cost compression in the mid-market tier intensifies because smaller imaging centers lack procurement scale to negotiate volume discounts. Academic medical centers exhibit lowest price sensitivity due to federal research funding cushions, while independent imaging centers in rural markets face acute budget constraints.
Supply Chain Analysis
Dual-sourcing requirements from United States hospital networks mandate qualified backup vendors for critical PACS and RIS components, reducing single-vendor lock-in risk. Software development concentrates in the United States, Germany, and Japan, with cloud infrastructure drawing from hyperscaler data centers across North America and Western Europe. Supply chain risk centers on regulatory divergence between FDA 21 CFR Part 820, EU MDR, and Japan PMDA validation timelines that delay product releases. Distribution runs through direct enterprise sales teams for hospital networks and channel partners for mid-market clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 21 CFR Part 820 quality system regulations compound procurement complexity, creating sustained demand for vendors with established validation infrastructure as hospital networks replace legacy archives.
For Market Incumbents: Cement installed-base loyalty through deep modality integration and native RIS-PACS interoperability that reduces customer switching propensity. Invest in FDA and EU MDR quality management infrastructure to defend against software-only entrants facing certification barriers. Prioritize continuous deployment pipelines that accelerate feature delivery under subscription contracts. For New Entrants and Emerging Players: The price-point gap between premium enterprise platforms and economy stand-alone systems opens white-space opportunity in mid-market imaging centers seeking cloud-native SaaS delivery. Target German and Japanese hospital networks modernizing radiology IT estates with API-enabled interoperability configurations. Pursue teleradiology infrastructure partnerships as the go-to-market angle for rural United States penetration. For Investors and Strategic Acquirers: Diversified health technology conglomerates with end-to-end imaging stacks are the most active acquirer in this space, consolidating specialized diagnostic informatics vendors for workflow-specific expertise. Long-term viability favors targets with existing FDA and EU MDR certification infrastructure over software-only platforms facing regulatory barriers. Watch AI-enabled diagnostic software reclassification under EU MDR as the inflection signal for vendor consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| API-Enabled Interoperability Certification | 21st Century Cures Act mandates open federal reimbursement pathways for compliant vendors. |
| Cloud-Native SaaS Transition | Mid-market imaging centers in Japan and Germany prioritize operational expenditure classification. |
| AI Inference Engine Integration | Academic medical centers deploy pulmonary embolism screening tools for emergency workflow prioritization. |
| Digital Pathology Workflow Extension | Oncology centers demand PACS architectures ingesting whole-slide imaging alongside radiology streams. |
| Multi-Site Federation Capability | United States hospital networks dismantle single-vendor ecosystems to reduce lock-in risk. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital CIOs, radiology department heads, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, hospital procurement databases, CMS Medicare reimbursement data, and hyperscaler cloud infrastructure disclosures. Bottom-up deployment modeling and top-down market sizing triangulated volume estimates.
Segment-weighting approaches distributed value across deployment model, integration level, end-user scale, and regional regulatory cluster dimensions. CAGRs derived from fitted growth curves applied to base-year estimates, with cloud-native SaaS penetration and AI-enabled diagnostic software adoption serving as primary demand drivers across the projection horizon.
Caveats apply where HIPAA security mandate acceleration, EU MDR reclassification timelines, or hybrid infrastructure migration delays could materially shift the outlook. Forecasts reflect documented assumptions about regulatory enforcement intensity and hospital capital availability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Preclinical Imaging (in-VIVO) Market
Medical Imaging
South Africa Nuclear Imaging Market
Medical Imaging
Enterprise Medical Image Viewers Market
Medical Imaging
Non-Invasive Coronary Imaging Market
Medical Imaging
Nuclear Magnetic Resonance Spectroscopy Market
Medical Imaging
Global Stroke Post Processing Software Market
Medical Imaging
India Computed Tomography Market
Medical Imaging
Ultrasound Systems Market
Medical Imaging
Dental Diagnostic Imaging Equipment Market
Medical Imaging
Dermatology Imaging Market
Medical Imaging
Republic of Ireland (ROI) and Northern Ireland MRI and CT Scan Radiology Services Market
Medical Imaging
North America Digital Pathology Market
Medical Imaging
United Kingdom Magnetic Resonance Imaging Market
Medical Imaging
United Arab Emirates Diagnostic Imaging Equipment Market
Medical Imaging
Asia Pacific Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Asia Pacific Nuclear Imaging Devices Market