
 Global Cone Beam Computed Tomography Market | 2026-2036
Global Cone Beam Computed Tomography Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cone Beam Computed Tomography Market Foresight
Subscription-based software modules for 3D treatment planning and remote diagnostics is shifting how CBCT vendors monetize hardware deployments. Dentsply Sirona leverages its installed base to anchor recurring revenue streams across dental practices. Planmeca differentiates through integrated CAD/CAM workflows that extend beyond pure imaging. VATECH competes aggressively on price-performance ratios in Asian markets while sustaining R&D intensity in detector technology.
Cone beam computed tomography captures volumetric anatomical data using a cone-shaped X-ray beam rotating around the patient, producing sub-millimeter isotropic voxel resolution with radiation doses significantly lower than conventional multi-slice CT systems. Flat panel detectors dominate the imaging technology segment due to superior spatial resolution and faster readout speeds for dental applications. Dental implant planning represents the most mature clinical application with established reimbursement pathways, while ENT imaging captures the fastest expansion as otolaryngologists adopt CBCT for sinus and temporal bone evaluation. Portable and tabletop units are gaining traction among orthodontic laboratories seeking flexible deployment without dedicated scanner rooms.
The FDA enforces 510(k) premarket notification requirements for CBCT systems, while the EU Medical Device Regulation mandates CE marking with strengthened clinical evidence standards under MDR. Japan's PMDA maintains distinct pharmaceutical and medical device approval pathways that foreign manufacturers must navigate for market access. Stakeholders should monitor evolving radiation exposure limits from WHO guidance and national regulators, as dose optimization becomes a decisive procurement criterion alongside image quality benchmarks.
Market Dynamics
Subscription software modules for 3D treatment planning and remote diagnostics are restructuring how CBCT vendors monetize hardware deployments, pulling recurring revenue streams forward while compressing capital sales cycles. This shift from perpetual licensing to SaaS architectures is redistributing cash flows across the value chain.
Growth Catalysts
- Japan's PMDA streamlined approval pathways:Foreign manufacturers gain faster market access for radiological devices, accelerating product launches in East Asian dental clusters.
- Flat panel detector resolution improvements:Sub-millimeter isotropic voxel capture enables precise implant planning, expanding CBCT into complex oral surgery workflows.
- South Korea's orthodontic laboratory export cluster:Concentrated demand from precision appliance manufacturers drives volume procurement of portable tabletop units.
Market Restraints
- Detector component supply concentration:Flat panel manufacturing concentrates among Asian semiconductor foundries, exposing OEMs to single-source fragility.
- Eu Medical Device Regulation clinical evidence standards:Strengthened MDR requirements for CE marking extend certification timelines and inflate documentation costs.
- Conventional multi-slice CT substitution threat:Hospital-based ENT departments retain access to existing CT infrastructure for sinus and temporal bone evaluation.
Strategic Opportunities
- Germany's dental clinic consolidation wave:Mid-sized practice networks seek standardized imaging platforms across multiple locations, favoring vendors with fleet management tools.
- AI-assisted radiology workflow convergence:Automated segmentation algorithms integrate with CBCT datasets, reducing manual interpretation time for orthodontic treatment planning.
- India's underpenetrated tier-2 cities:Rising dental tourism infrastructure and private clinic expansion create first-mover advantages for price-optimized system configurations.
Industry Challenges
- ISO 13485 quality management certification timelines:Extended audit backlogs delay market entry for new manufacturers seeking medical device quality system recognition.
- Legacy PACS integration complexity:Dental practices with decade-old practice management software face costly middleware development for CBCT connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cone Beam Computed Tomography Market |
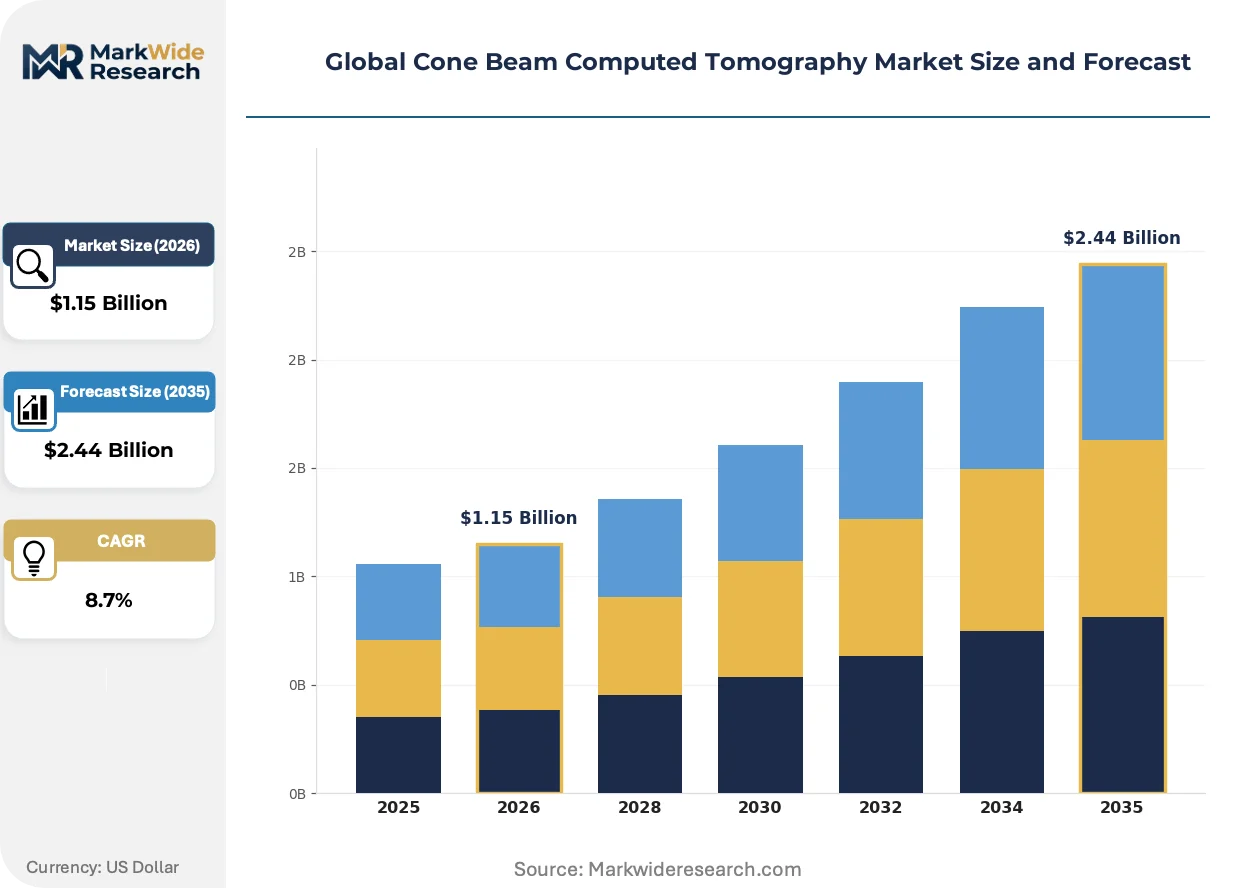
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $2.44 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Cone Beam CT, Portable Cone Beam CT, Tabletop Units, Mobile Systems Imaging Technology: Flat Panel Detectors, Charge-Coupled Devices, Amorphous Silicon Detectors, CMOS Sensors Clinical Application: Dental Implant Planning, ENT Imaging, Orthodontics, Oral Surgery, Endodontics End User: Dental Clinics, Diagnostic Centers, Orthodontic Laboratories, Oral Surgery Centers |
| Companies Covered | Dentsply Sirona, Planmeca, VATECH, Carestream Health, J. Morita Manufacturing, KaVo, CurveBeam AI, Danaher Corporation, PreXion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cone Beam Computed Tomography Market Shifts & Advancements
Photon-counting detector architectures and AI-native reconstruction algorithms are rewriting performance benchmarks across the CBCT installed base. Vendors race to embed computational imaging pipelines that compress scan times while preserving diagnostic fidelity.
Photon-counting detectors with direct X-ray conversion are rewriting spatial resolution standards for dental CBCT systems. Orthodontic laboratories in Seoul and Tokyo adopt these sensors for crown-margin visualization at sub-100-micron precision. The technology is rewriting procurement criteria, forcing flat-panel incumbents to accelerate readout speed roadmaps or concede premium positioning.
The EU Medical Device Regulation's post-market surveillance requirements are tightening real-world performance documentation for CE-marked CBCT systems. Manufacturers must maintain active implant registries and adverse event tracking beyond initial approval. Dental OEMs serving European markets respond by embedding remote diagnostic connectivity that automates usage logging and anomaly flagging.
Orthodontic laboratories now unbundle hardware acquisition from software subscription tiers, compressing traditional capital expenditure cycles. This procurement pattern disrupts distributor financing models that relied on bundled lease-to-own structures. The shift is most visible in South Korea's export-oriented appliance manufacturing cluster, where volume buyers negotiate pure-hardware pricing separately from cloud-based treatment planning access.
Global Cone Beam Computed Tomography Market Segmentation
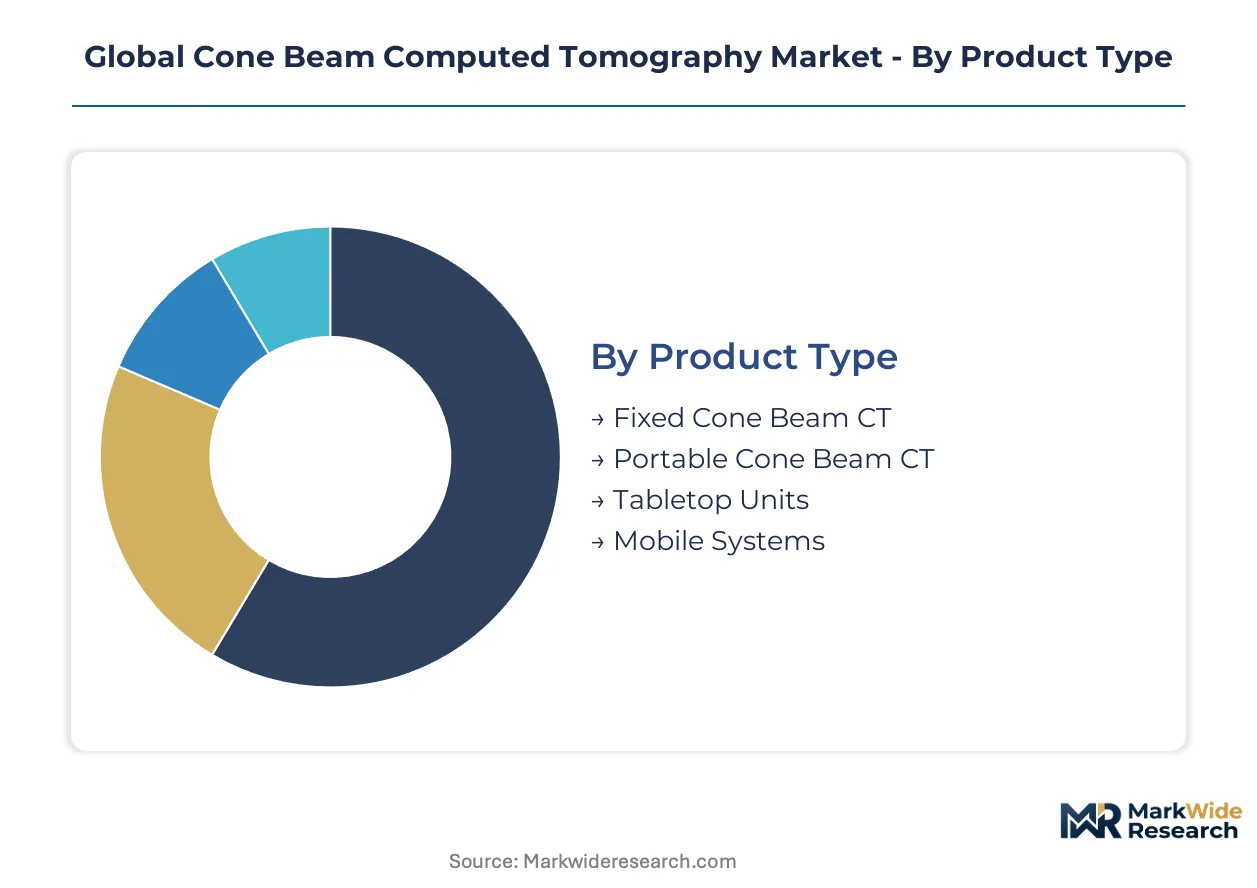
CBCT market segmentation reveals how hardware form factors, detector architectures, clinical workflows, and buyer economics fragment procurement patterns across dental and ENT specialties. Understanding these divides exposes where vendors can defend premium positioning versus where price competition dominates.
Product Type:
Buyers differentiate primarily by floor space constraints and patient throughput requirements rather than image quality alone.
- Fixed Cone Beam CT:Permanent installations with gantry-mounted rotating sources deliver the highest voxel resolution and field-of-view flexibility. Hospital-based oral surgery centers in Germany and Japan specify these systems for complex maxillofacial reconstruction workflows where sub-millimeter accuracy determines implant success rates.
- Portable Cone Beam CT:Self-contained units on wheeled chassis relocate between operatories without dedicated scanner rooms. Mobile dental service providers across India's tier-2 cities deploy these configurations to serve dispersed patient populations without capital-intensive facility buildouts.
- Tabletop Units:Compact footprints suit orthodontic laboratories with limited square footage.
- Mobile Systems:Vehicle-mounted configurations serve temporary clinical deployments and rural outreach programs.
Volume sits with fixed installations; growth tilts toward portable configurations.
Imaging Technology:
Detector selection determines spatial resolution ceilings, readout speeds, and ultimately the clinical procedures each system can support.
- Flat Panel Detectors:Amorphous selenium and cesium iodide scintillator layers convert X-ray photons to electrical signals with superior dose efficiency. Seoul's orthodontic export cluster demands these sensors for crown-margin visualization at sub-100-micron precision, driving premium procurement in South Korea's appliance manufacturing hub.
- CMOS Sensors:Complementary metal-oxide-semiconductor architectures enable faster frame rates and lower power consumption than legacy alternatives. Emerging manufacturers target cost-optimized dental clinics in India's expanding private practice sector where acquisition price sensitivity outweighs absolute resolution requirements.
- Charge-Coupled Devices:Mature technology with established supply chains but slower readout characteristics.
- Amorphous Silicon Detectors:Intermediate performance tier serving mid-market system configurations.
Flat panel detectors command the installed base; CMOS sensors are expanding most quickly in cost-sensitive geographies.
Clinical Application:
Reimbursement pathway maturity and procedure volume intensity segment demand across dental specialties.
- Dental Implant Planning:Preoperative bone density mapping and nerve canal tracing represent the most established CBCT application with defined insurance coverage in Germany and Japan. Implantologists require isotropic voxel resolution below 200 microns to assess cortical bone thickness for immediate loading protocols.
- ENT Imaging:Otolaryngologists evaluate sinus pathology and temporal bone anatomy with CBCT doses substantially below conventional CT. Japanese ENT departments increasingly specify these systems for chronic rhinosinusitis workups where radiation exposure accumulation concerns drive modality substitution.
- Orthodontics:Cephalometric analysis and airway assessment support treatment planning for malocclusion correction.
- Oral Surgery:Third molar extraction planning and orthognathic surgical guidance utilize medium field-of-view configurations.
- Endodontics:Root canal morphology visualization demands ultra-high resolution in limited anatomical regions.
Implant planning anchors current revenue; ENT imaging shows the steepest expansion trajectory as hospital departments replace conventional CT referrals.
End User:
Capital availability and utilization economics separate high-throughput clinical settings from specialized laboratory environments.
- Dental Clinics:General practitioners and specialists with direct patient contact represent the largest addressable pool. Germany's consolidating mid-sized practice networks negotiate fleet pricing for standardized platforms across multiple locations, favoring vendors with centralized device management software.
- Orthodontic Laboratories:Appliance manufacturers serving export markets operate at production scale that justifies dedicated imaging capacity. Seoul's precision manufacturing cluster procures tabletop units in volume for digital model fabrication serving North American and European orthodontic practices.
- Diagnostic Centers:Multi-specialty imaging facilities amortize equipment costs across diverse referral streams.
- Oral Surgery Centers:Hospital-affiliated and independent surgical practices require premium specifications for complex interventions.
Dental clinics concentrate absolute volume; orthodontic laboratories are gaining share fastest through export-driven capacity expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Asian semiconductor foundries while clinical demand fragments across high-income dental markets. Germany and Japan absorb premium fixed installations; South Korea's orthodontic laboratories drive portable unit volumes. India's tier-2 cities represent the largest latent installation base.
United States
Hospital-based oral surgery centers and multi-location dental service organizations anchor demand for premium fixed systems. The FDA's 510(k) premarket notification pathway governs radiological device entry, with recent guidance emphasizing dose optimization documentation. The Greater Boston corridor hosts concentrated ENT imaging adoption as academic medical centers replace conventional CT referrals for sinus evaluation.
Germany
Consolidating mid-sized dental practice networks seek standardized imaging platforms across multiple locations, favoring vendors with centralized fleet management software. The EU Medical Device Regulation mandates strengthened clinical evidence standards for CE marking, extending certification timelines for new market entrants. Bavaria's dental implantology clusters drive specification requirements for sub-200-micron isotropic voxel resolution.
Japan
Chronic rhinosinusitis workups in otolaryngology departments accelerate CBCT substitution for conventional CT, driven by radiation exposure accumulation concerns. The PMDA maintains distinct pharmaceutical and medical device approval pathways that foreign manufacturers must navigate for market access. Tokyo's Kanto region concentrates dental clinic procurement of fixed installations for complex maxillofacial reconstruction workflows.
South Korea
Export-oriented orthodontic appliance manufacturers in Seoul's precision manufacturing cluster procure tabletop units in volume for digital model fabrication. The MFDS regulates medical device quality systems with ISO 13485 alignment requirements that extend audit backlogs for new entrants. Busan-Ulsan's dental laboratory corridor drives pure-hardware pricing negotiations unbundled from software subscription tiers.
India
Private dental clinic expansion in tier-2 cities and rising dental tourism infrastructure create first-mover advantages for price-optimized system configurations. The CDSCO oversees medical device import licensing with strengthened post-market surveillance obligations. Maharashtra's Mumbai-Pune corridor anchors mobile dental service deployment of portable units to dispersed patient populations.
Global Cone Beam Computed Tomography Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across detector fabrication and software architecture layers. The vendor base separates into three tiers: integrated dental equipment conglomerates with installed base leverage; specialized imaging OEMs with detector technology depth; and emerging cost-optimized challengers targeting price-sensitive geographies. Dominant competitive moves include backward integration into flat panel detector supply and geographic expansion through distributor network capture.
Within the integrated conglomerate tier, Dentsply Sirona and Danaher Corporation exemplify installed-base monetization strategies that anchor recurring revenue through subscription software modules. Planmeca occupies a position bridging premium hardware specifications with integrated CAD/CAM workflow extension. VATECH represents the price-performance specialist archetype, sustaining R&D intensity in detector technology while competing aggressively on acquisition cost in Asian markets.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Planmeca |
| VATECH |
| Carestream Health |
| J. Morita Manufacturing |
| KaVo |
| CurveBeam AI |
| Danaher Corporation |
| PreXion |
| Others |
Supply & Pricing Matrix
Photon-counting detector maturation simultaneously compresses manufacturing yields at Asian foundries and concentrates procurement leverage among premium-tier buyers. This technology transition rewards early adopters with resolution advantages while squeezing mid-tier vendors unable to amortize R&D across sufficient unit volumes.
Pricing Analysis
Margin tightening in standard-tier fixed installations traces to CMOS sensor commoditization and aggressive Korean challenger pricing. Three-tier pricing structure across premium photon-counting, standard flat-panel, and economy CMOS configurations dominates procurement negotiations. Price differentiation hinges on detector resolution grade and FDA 510(k) clearance tier. Cost-down pressure on economy configurations accelerates because Indian tier-2 clinics prioritize acquisition price over absolute voxel precision. Orthodontic laboratories in Seoul exhibit lowest price sensitivity; mobile dental providers in Maharashtra show highest.
Supply Chain Analysis
Dual-sourcing requirements from German and Japanese OEMs now mandate qualified second-source flat panel suppliers beyond primary Taiwanese foundry relationships. Manufacturing concentrates in Taiwan, South Korea, and Japan for amorphous selenium deposition and CMOS wafer fabrication. Component dependencies include cesium iodide scintillator crystals, amorphous silicon backplanes, and precision rotation bearings. Single-source vulnerability concentrates in Taiwanese semiconductor foundry capacity for large-area detector substrates. Distribution runs through authorized dental equipment distributors with regional service depot networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flat panel detector fabrication capacity constraints prop pricing power for qualified suppliers. Foundry slot allocation among competing OEMs determines market share trajectories.
For Market Incumbents: To counter photon-counting detector substitution, accelerate backward integration into captive scintillator crystal supply and secure multi-year foundry slot commitments at Taiwanese semiconductor partners. Prioritize ISO 13485 certification maintenance to defend hospital procurement eligibility under EU MDR strengthened requirements. For New Entrants and Emerging Players: Orthodontic laboratory distributors in South Korea's Busan-Ulsan corridor offer the most penetrable channel partnership pathway. Target India's tier-2 city mobile dental service providers with price-optimized portable configurations unbundled from software subscriptions. Pursue CDSCO import licensing partnerships with established regional service organizations to bypass direct regulatory navigation. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated dental equipment conglomerates seeking detector technology depth. Five-to-ten-year viability favors specialized imaging OEMs with photon-counting R&D pipelines and Asian manufacturing footprints. Monitor PMDA approval timeline compression for foreign manufacturers as inflection signal for Japanese market accessibility.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Optimization | Streamlined radiation dose documentation accelerates product entry for US hospital oral surgery centers. |
| Photon-Counting Detector Development | Sub-100-micron resolution capability captures premium positioning in Seoul orthodontic export clusters. |
| CE Marking MDR Compliance | Strengthened clinical evidence standards under EU Medical Device Regulation extend certification timelines for European market access. |
| Orthodontic Laboratory Partnership | Volume procurement agreements with Seoul precision manufacturing hubs anchor portable tabletop unit deployment. |
| Software-Companion Development | AI-native reconstruction algorithms embedded in subscription modules shift vendor monetization toward recurring revenue streams. |
Research Methodology
Independent corroboration across primary interviews with dental equipment procurement managers, biomedical engineers at hospital oral surgery centers, orthodontic laboratory operations directors, and flat panel detector manufacturing executives underwrites the qualitative findings. Secondary validation draws from FDA 510(k) premarket notification databases, PMDA approval registries, EU MDR CE marking documentation, and hospital GPO contract awards. Bottom-up unit shipment estimates triangulate against top-down addressable market sizing.
Rate-of-change decomposition across the analysis window segments volume trajectories by product type, imaging technology architecture, clinical application specialty, and end-user procurement archetype. CAGR derivation rests on installed base replacement cycles, procedure volume intensity by specialty, and reimbursement pathway maturity differentials. Forecast inputs incorporate PMDA regulatory timeline assumptions and orthodontic laboratory export demand elasticity from South Korea's manufacturing cluster.
Caveats apply where photon-counting detector yield improvements or Taiwanese foundry capacity expansion could materially shift the outlook. Deviation in EU MDR audit backlog duration or CDSCO import licensing timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Cone Beam CT Scanner Market
Medical Imaging
Orthopedic Imaging Market
Medical Imaging
Ultrasound Image Processing Software Market
Medical Imaging
Global Contrast-Enhanced Ultrasound Market
Medical Imaging
Germany Computed Tomography Market
Medical Imaging
Global 3D Laparoscopy Imaging Market
Medical Imaging
Global Medical Imaging Reagents Market
Medical Imaging
Dental X-Ray Market
Medical Imaging
Middle East and Africa Mammography Market
Medical Imaging
Global Medical Image Management Market
Medical Imaging
Automated Contouring Radiotherapy Software Market
Medical Imaging
Interventional X - Ray Systems Market
Medical Imaging
Digital Telepathology Market
Medical Imaging
Italy Nuclear Imaging Market
Medical Imaging
Robotic X-Ray Scanner Market
Medical Imaging
Global Veterinary Diagnostic Imaging Market