
 AI Surgical Video Intelligence System Market | 2026-2036
AI Surgical Video Intelligence System Market Size, Share, and Industry Trends Forecast 2026-2036
AI Surgical Video Intelligence System Market Insights
FDA 510(k) premarket notification cycles for AI-enabled surgical devices is collapsing from historical norms, compressing competitive windows for new entrants. Medtronic leverages its integrated surgical ecosystem to sustain hardware-software bundling advantages across hospital networks. Intuitive Surgical anchors its position through da Vinci system compatibility, dominating the installed base for real-time video analytics deployment.
An AI surgical video intelligence system comprises computer vision algorithms, deep learning inference engines, and edge computing nodes that process endoscopic and laparoscopic video streams at sub-100-millisecond latency to annotate anatomy, flag operative deviations, and generate structured operative reports. Real-Time Assistance platforms command premium positioning due to intraoperative decision-support value, while Postoperative Review modules scale through subscription economics in academic medical centers. Deep Learning architectures lead technology segmentation by training data requirements, though Edge Computing deployment is accelerating in ambulatory settings with bandwidth constraints.
FDA premarket review, EU MDR conformity assessment under notified body oversight, and Japan PMDA software-as-medical-device classifications collectively shape product development roadmaps and geographic launch sequencing. HIPAA compliance obligations in the United States and GDPR data governance in Europe further constrain cross-border video data flows for algorithm training. Stakeholders must monitor evolving software-as-medical-device taxonomies across regulators to anticipate classification changes that would trigger additional clinical evidence requirements.
Market Dynamics
FDA 510(k) clearance compression is collapsing development timelines from 18 months to under 9 months for AI-enabled surgical devices, forcing incumbents to accelerate R&D cycles or cede first-mover positioning in real-time video analytics.
Growth Catalysts
- Reimbursement Maturation:Germany's G-DRG framework now covers computer-assisted surgery add-on payments, incentivizing hospital procurement of intraoperative decision-support platforms.
- Edge Computing Deployment:Ambulatory surgical centers with bandwidth constraints are adopting on-premise inference nodes to enable sub-100-millisecond latency for laparoscopic video annotation.
- FDA Pre-Certification Pathway:The FDA's Software Pre-Certification Program streamlines review for established AI/ML-based device manufacturers, reducing time-to-market for iterative algorithm updates.
Market Restraints
- GPU Supply Concentration:NVIDIA's dominance in medical-grade inference accelerators creates single-source dependency for edge computing hardware in surgical video systems.
- Training Data Friction:HIPAA constraints on cross-institutional video sharing limit algorithm training dataset diversity, degrading model generalization across patient populations.
- EU MDR Conformity Costs:Notified body oversight requirements for software-as-medical-device classification impose six-figure assessment fees that exclude mid-tier developers.
Strategic Opportunities
- Japan PMDA Streamlining:METI's 2024 software medical device guidance reduces clinical evidence requirements for AI surgical tools with predicate device equivalence.
- Veterans Health Administration:The VA's centralized procurement structure offers single-contract access to 170+ medical centers for postoperative review module deployment.
- Multimodal Sensor Fusion:Integration of haptic feedback data with video streams enables new operative deviation detection capabilities beyond pure computer vision.
Industry Challenges
- Computational Pathology Talent Scarcity:The intersection of surgical domain expertise and deep learning engineering remains critically under-supplied, extending hiring timelines to 8-12 months.
- Legacy PACS Integration:Hospital picture archiving systems require custom HL7 FHIR middleware development, inflating implementation costs and delaying go-live dates.
- Algorithm Drift Monitoring:Continuous validation requirements for deployed models demand dedicated MLOps infrastructure that most academic medical centers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Surgical Video Intelligence System Market |
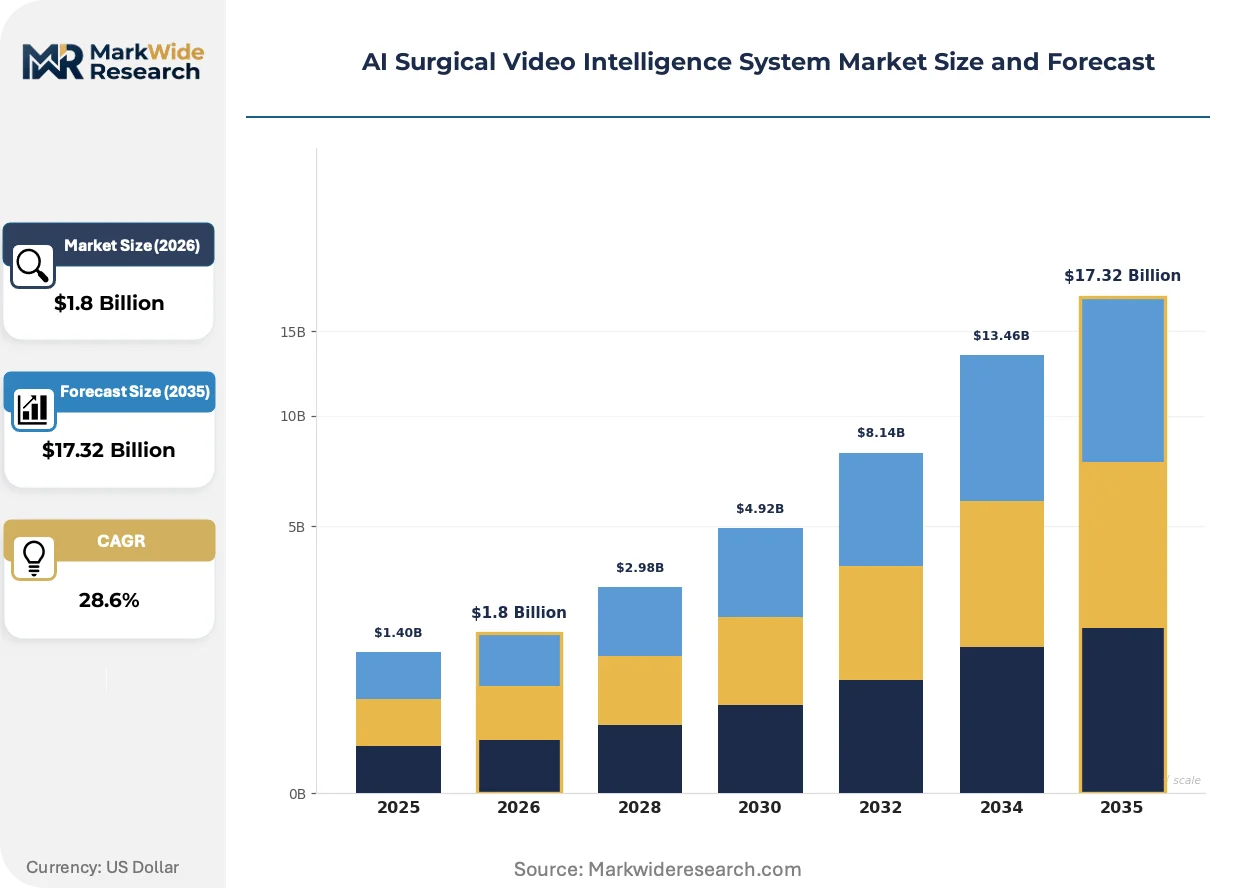
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preoperative Analysis, Real-Time Assistance, Postoperative Review, Training Simulation Technology: Computer Vision, Deep Learning, Natural Language Processing, Augmented Reality, Edge Computing Application: Neurosurgery, Orthopedic Surgery, Cardiothoracic Surgery, Laparoscopic Surgery, Urology Procedures End User: Hospitals, Ambulatory Surgery Centers, Medical Schools, Research Institutes |
| Companies Covered | Medtronic, Intuitive Surgical, Johnson & Johnson, Olympus Corporation, CARL ZEISS Meditec, Brainlab, Caresyntax, Proximie, Theator, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Surgical Video Intelligence System Market Trends and Innovations
Transformer-based architectures are displacing convolutional neural networks as the dominant approach for surgical phase recognition, compressing training data requirements while improving anatomical landmark detection accuracy across endoscopic modalities.
Federated learning protocols are displacing centralized model training, enabling multi-institutional algorithm development without HIPAA-prohibited video data sharing. Academic medical centers in Boston, Heidelberg, and Tokyo are deploying cross-border federated nodes to train pancreas segmentation models. This architecture is displacing traditional data-pooling business models while preserving institutional data sovereignty.
The EU AI Act's high-risk system classification for surgical decision-support software imposes conformity assessment obligations that extend beyond MDR requirements. Developers must now maintain post-market monitoring systems and algorithm change control protocols. Real-time assistance platforms face the steepest compliance burden, with several European launches delayed pending notified body capacity expansion.
Subscription economics are displacing perpetual licensing for postoperative review modules, with academic medical centers preferring per-procedure pricing that aligns costs with utilization. Procurement committees in tertiary hospitals now require SaaS architecture with API-accessible structured operative reports. This shift is most pronounced in United States academic medical centers, where bundled payments create demand for automated quality documentation.
AI Surgical Video Intelligence System Market Segmentation
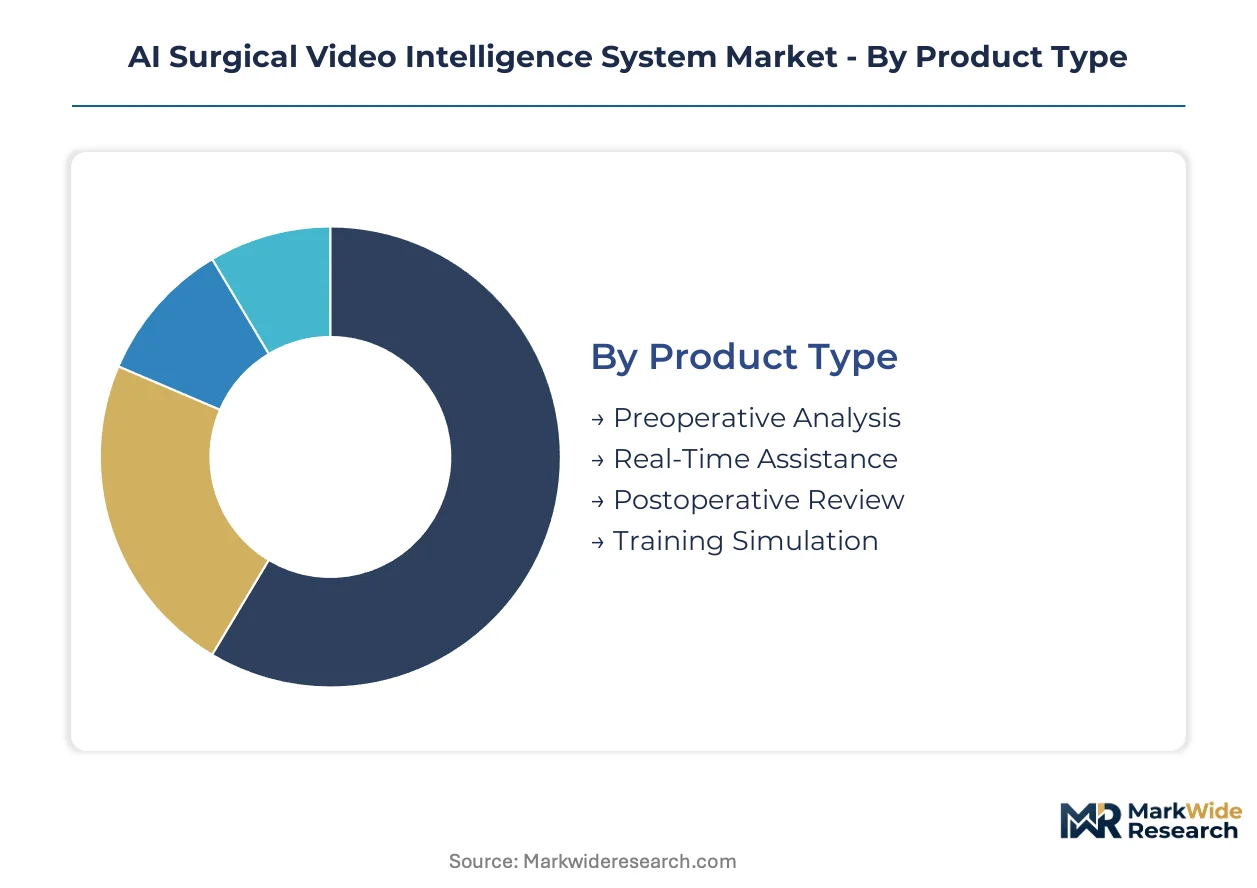
Surgical video intelligence systems fragment across four distinct dimensions that shape procurement patterns and vendor positioning. Product type determines pricing architecture and regulatory pathway complexity. Technology selection drives latency requirements and infrastructure investment. Application specialization dictates anatomical training data needs and clinical validation scope.
Product Type:
Real-Time Assistance platforms face acute substitution pressure from conventional surgical navigation systems that hospitals already own, forcing AI vendors to demonstrate measurable operative time reduction or complication rate improvement to justify replacement expenditure.
- Preoperative Analysis:Algorithms reconstruct patient-specific anatomy from preoperative imaging to generate risk stratification scores and operative approach recommendations. Academic medical centers in Germany and Japan deploy these modules for complex oncologic resections where patient-specific modeling reduces exploratory operative time.
- Real-Time Assistance:Sub-100-millisecond latency platforms annotate live endoscopic feeds with anatomical landmarks and deviation alerts. Hospitals in the United States concentrate procurement here, driven by malpractice liability reduction and bundled payment quality documentation requirements.
- Postoperative Review:Structured operative report generation and outcome correlation analytics delivered through SaaS subscription models. Medical schools leverage these systems for competency-based resident evaluation where automated skill assessment replaces labor-intensive faculty video review.
- Training Simulation:Synthetic video generation and procedural rehearsal environments for surgical education. Research institutes deploy these where cadaveric specimen access is constrained or cost-prohibitive.
Real-Time Assistance retains volume leadership; Training Simulation holds the steepest expansion curve.
Technology:
Cost tier stratification separates capital-intensive edge computing deployments from cloud-dependent deep learning architectures, with ambulatory surgery centers gravitating toward lower-infrastructure alternatives.
- Computer Vision:Traditional image processing pipelines for anatomical segmentation and instrument tracking. Mature implementations in laparoscopic surgery applications where annotated datasets span decades of procedural archives.
- Deep Learning:Neural network architectures requiring substantial GPU infrastructure for training and inference. Transformer-based models are displacing convolutional approaches in surgical phase recognition tasks.
- Natural Language Processing:Operative report generation and voice-controlled annotation interfaces. Hospitals with structured documentation mandates drive procurement for automated coding and quality metric extraction.
- Augmented Reality:Overlay visualization of preoperative imaging onto live video feeds. Neurosurgery applications concentrate demand where precise anatomical registration directly impacts resection margins.
- Edge Computing:On-premise inference nodes eliminating cloud latency and data egress concerns. Ambulatory surgery centers with bandwidth constraints adopt these for standalone laparoscopic video annotation without hospital IT dependency.
Deep Learning commands the premium tier; Edge Computing is climbing the fastest as infrastructure constraints spread beyond tertiary centers.
Application:
Customer type differentiation separates high-acuity tertiary hospital procedures from high-volume ambulatory interventions, with reimbursement density determining AI platform ROI timelines.
- Neurosurgery:Cranial and spinal procedures requiring submillimeter anatomical registration accuracy. Academic medical centers in Boston and Heidelberg deploy these systems where resection margin precision directly impacts patient neurological outcomes.
- Orthopedic Surgery:Arthroscopic and joint replacement procedures with standardized instrument sets enabling algorithm generalization. Ambulatory surgery centers in the United States concentrate adoption for outpatient arthroscopy where operative volume supports platform utilization.
- Cardiothoracic Surgery:Minimally invasive cardiac and pulmonary resections with high-stakes anatomical variation. Research institutes validate algorithms here where procedural complexity demands extensive clinical evidence packages.
- Laparoscopic Surgery:General surgical and gynecological procedures with the largest installed base of compatible video systems. Medical schools prioritize this segment for resident training where procedural volume enables competency curve analysis.
- Urology Procedures:Prostate and renal interventions with well-defined anatomical landmarks and established robotic platforms. Hospitals with existing da Vinci installations extend video intelligence capabilities through compatible software modules.
Laparoscopic Surgery dominates procedural volume; Neurosurgery carries the highest per-procedure platform value.
End User:
Supply concentration in GPU hardware creates tiered access, with well-capitalized hospital systems securing priority allocation while smaller ambulatory centers face extended procurement timelines.
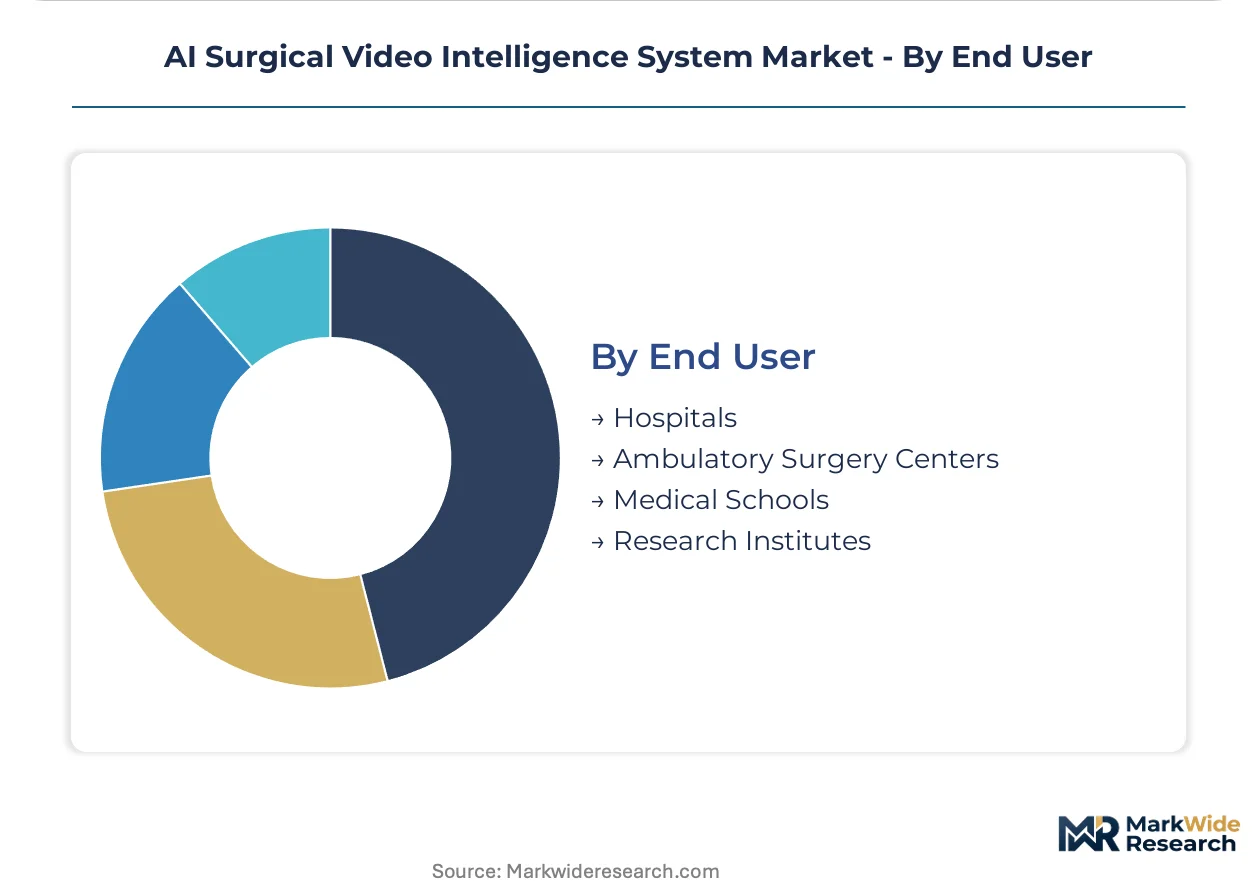
- Hospitals:Integrated delivery networks with centralized surgical suites and dedicated IT infrastructure. Tertiary centers in the United States, Germany, and Japan drive premium platform adoption where capital budgets accommodate six-figure system investments.
- Ambulatory Surgery Centers:Freestanding facilities with constrained technical staffing and bandwidth limitations. Edge computing deployment models address infrastructure gaps where cloud dependency is operationally impractical.
- Medical Schools:Accreditation-driven competency evaluation requirements and structured curriculum mandates. Subscription economics align procurement with academic budget cycles and resident cohort sizes.
- Research Institutes:Algorithm development and clinical validation partnerships with technology vendors. Federated learning protocols enable multi-institutional collaboration without HIPAA-prohibited data sharing.
Hospitals anchor installed base expansion; Ambulatory Surgery Centers are gaining share fastest as edge computing removes infrastructure barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's G-DRG framework now covers computer-assisted surgery add-on payments, creating direct procurement incentives for intraoperative decision-support platforms. Japan's METI streamlined software medical device guidance in 2024, compressing clinical evidence requirements for predicate-equivalent AI surgical tools. The United States maintains the densest concentration of real-time assistance deployments, driven by malpractice liability reduction imperatives and bundled payment quality documentation mandates.
United States
Hospital procurement committees in tertiary centers prioritize real-time assistance platforms that demonstrate measurable operative time reduction. The FDA's Software Pre-Certification Program accelerates review cycles for established AI/ML device manufacturers. Boston and Palo Alto academic medical centers anchor federated learning networks for multi-institutional algorithm development without HIPAA-prohibited data sharing.
Germany
University hospitals in Heidelberg and Munich deploy preoperative analysis modules for complex oncologic resections where patient-specific modeling reduces exploratory operative time. The EU AI Act's high-risk system classification imposes conformity assessment obligations extending beyond MDR requirements. Baden-Württemberg's medical technology cluster concentrates notified body capacity for software-as-medical-device certification.
Japan
Tokyo and Osaka medical centers concentrate demand for postoperative review modules aligned with resident competency evaluation requirements. PMDA software-as-medical-device classifications shape product development roadmaps and geographic launch sequencing. METI's 2024 guidance reduces clinical evidence burdens for predicate-equivalent AI surgical tools, accelerating market entry timelines.
United Kingdom
London teaching hospitals leverage subscription economics for automated operative report generation and quality metric extraction. GDPR data governance constraints limit cross-border video data flows for algorithm training. The Midlands and Greater Manchester clusters participate in federated learning protocols for pancreas segmentation model development.
France
Parisian academic medical centers drive procurement of augmented reality overlay systems for neurosurgery applications where anatomical registration precision impacts resection margins. ANSM oversight of software medical devices requires post-market monitoring systems and algorithm change control protocols. The Île-de-France region concentrates research institute partnerships for clinical validation of transformer-based surgical phase recognition architectures.
AI Surgical Video Intelligence System Market Competitive Landscape
Player mix skews toward integrated surgical ecosystem vendors with hardware-software bundling capabilities. Consolidation pressure intensifies as FDA 510(k) clearance compression collapses development timelines from eighteen months to under nine months. Three archetypes dominate: diversified medtech conglomerates with installed base leverage, pure-play AI software vendors with subscription economics, and robotic platform specialists with video analytics integration. Competitive moves concentrate on strategic partnerships for federated learning data access and edge computing hardware co-development.
Within the integrated ecosystem tier, Medtronic and Johnson & Johnson exemplify hardware-software bundling advantages across hospital network procurement. Intuitive Surgical occupies a distinctive position through da Vinci system compatibility, anchoring real-time video analytics deployment within the dominant robotic surgery installed base. Caresyntax represents the pure-play software archetype with SaaS-native architecture for postoperative review modules.
| Leading Market Players |
|---|
| Medtronic |
| Intuitive Surgical |
| Johnson & Johnson |
| Olympus Corporation |
| CARL ZEISS Meditec |
| Brainlab |
| Caresyntax |
| Proximie |
| Theator |
| Others |
Pricing and Supply Chain Analysis
FDA 510(k) clearance compression and EU MDR notified body oversight jointly gate supplier qualification and tier price differentiation in surgical video intelligence systems. Certification-grade stratification separates premium real-time assistance platforms from economy-tier postoperative review modules, with reimbursement density in the United States, Germany, and Japan determining hospital procurement willingness-to-pay.
Pricing Analysis
Certification level (FDA 510(k)-cleared versus CE-marked versus predicate-equivalent) creates the primary spread between premium real-time assistance platforms and standard postoperative review subscriptions. Three-tier pricing structure across premium, standard, and economy levels aligns with latency performance and anatomical annotation depth. Pricing pressure stems from ambulatory surgery center budget constraints and edge computing hardware commoditization. Academic medical centers in the United States exhibit lowest price sensitivity due to bundled payment quality documentation mandates, while freestanding ambulatory centers in Germany and Japan face acute cost compression.
Supply Chain Analysis
Inventory lead times for NVIDIA medical-grade inference accelerators stretch 16-24 weeks, constraining edge computing node deployment timelines for ambulatory surgery centers. GPU supply concentrates in Taiwan and South Korea, with final system assembly anchored in the United States and Germany. Deep learning training infrastructure draws from cloud hyperscaler capacity in the United States and Ireland. Single-source vulnerability in medical-grade GPU supply creates procurement risk for real-time assistance platform manufacturers. Distribution runs through hospital GPO contracts in the United States and direct university hospital procurement in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surgical video intelligence sits in early-cycle expansion with reimbursement frameworks for computer-assisted surgery maturing across the United States, Germany, and Japan. Edge computing deployment in bandwidth-constrained ambulatory settings extends addressable market penetration beyond tertiary hospital installations.
For Market Incumbents: Fortify hardware-software bundling advantages through da Vinci system compatibility extensions and integrated surgical ecosystem lock-in. Accelerate federated learning data access partnerships with academic medical centers in Boston, Heidelberg, and Tokyo to preempt pure-play AI vendors from building training dataset moats. Deepen edge computing hardware co-development with NVIDIA to secure GPU allocation priority against emerging entrant demand surges.
For New Entrants and Emerging Players: Anchor in postoperative review modules where SaaS-native architecture and subscription economics face lower regulatory burden than real-time assistance platforms. Target ambulatory surgery centers in the United States with standalone edge computing deployments that bypass hospital IT dependency and legacy PACS integration friction. Pursue VA centralized procurement contracts for single-contract access to 170+ medical centers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across postoperative review software as cloud-native architectures displace on-premise infrastructure requirements. Long-term viability favors vendors with federated learning protocol deployment and multi-institutional algorithm development capabilities without HIPAA-prohibited data sharing. Acquisition target archetype: pure-play AI software vendors with SaaS-native architecture and existing hospital system pilot contracts. Signal to watch: FDA Software Pre-Certification Program expansion to mid-tier developers as inflection indicator for regulatory barrier reduction.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compresses competitive windows from 18 months to under 9 months for AI-enabled surgical devices. |
| CE Marking Pathway Under EU MDR | Notified body oversight for software-as-medical-device classification imposes six-figure assessment fees excluding mid-tier developers. |
| Hospital System Partnership | Integrated delivery networks with centralized surgical suites drive premium platform adoption through GPO contract concentration. |
| Software Companion Development | da Vinci system compatibility anchors real-time video analytics deployment within dominant robotic surgery installed base. |
| Reimbursement Strategy | Germany's G-DRG framework computer-assisted surgery add-on payments create direct procurement incentives for intraoperative decision-support platforms. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs leads at AI surgical device manufacturers. Secondary validation drew from FDA 510(k) filings, EU MDR notified body submission databases, hospital procurement records, and CMS Medicare reimbursement schedules. Bottom-up segmentation modeling triangulated against top-down market sizing from surgical procedure volume databases and robotic system installed base estimates.
Across the projection horizon, analytical frameworks modeled volume and value trajectories through product type, technology architecture, application specialization, and end-user category segmentation dimensions. CAGRs were derived from procedure volume elasticity to reimbursement coverage expansion and edge computing hardware cost curves. Federated learning protocol adoption rates and FDA Software Pre-Certification Program participation informed algorithm development capacity assumptions.
Material uncertainties — reimbursement policy reversals, GPU supply disruption, EU AI Act high-risk system classification delays — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway stability and training data access liberalization that may not materialize. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Computed Tomography (CT) Scanners Market
Medical Imaging
South Africa Computed Tomography Market
Medical Imaging
UK Imaging Services Market
Medical Imaging
United Kingdom Digital X-Ray Devices Market
Medical Imaging
South America Fluoroscopy Market
Medical Imaging
North America MRI (Magnetic Resonance Imaging) Market
Medical Imaging
Global Veterinary Radiography System Market
Medical Imaging
Radiology Positioning Aids Market
Medical Imaging
Global Medical Cameras Market
Medical Imaging
Cone Beam Computed Tomography (CBCT) System Market
Medical Imaging
Mobile Computed Tomography Scanners Market
Medical Imaging
Structural Heart Imaging Market
Medical Imaging
Non-Invasive & Minimally Invasive Medical Imaging and Visualization Systems Market
Medical Imaging
Brazil Mammography Market
Medical Imaging
Mobile Radiography Systems Market
Medical Imaging
Asia-Pacific Digital Pathology Market