
 Healthcare ERP Consulting Services Market | 2026-2036
Healthcare ERP Consulting Services Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare ERP Consulting Services Market Intelligence
Modular service bundling is shifting buyer choice in healthcare ERP consulting. Hospitals now procure implementation, optimization, and change management as integrated packages rather than discrete engagements. Deloitte anchors its competitive position through deep clinical workflow expertise. Cognizant Technology Solutions Corporation leverages its offshore delivery model to compete on cost for large-scale Epic deployments.
Healthcare ERP consulting services encompass advisory and technical implementation support for enterprise resource planning systems tailored to medical environments, typically involving HL7 FHIR integration, revenue cycle module configuration, and compliance-aligned workflow redesign. These services enable providers to unify financial operations, supply chain, and patient billing within a single system architecture. Implementation and optimization services command the largest share of project value, while cloud-based deployment models represent the fastest-growing engagement type as providers migrate from on-premise Cerner and Epic instances. Hospitals remain the dominant end-user segment, though long-term care facilities are emerging as a specialized consulting niche due to Medicaid reimbursement complexity.
FDA interoperability rules, HIPAA security requirements, and CMS Promoting Interoperability standards collectively shape system design priorities and consulting scope. The FDA mandates data exchange capabilities that legacy ERP configurations cannot satisfy without substantial reengineering. Stakeholders must monitor how emerging CMS value-based payment models alter the required depth of financial-clinical integration in ERP platforms.
Market Dynamics
Multi-hospital health systems are consolidating vendor relationships and demanding unified financial-clinical ERP modules that satisfy FDA interoperability mandates without custom integration layers.
Growth Catalysts
- FDA 21st Century Cures Act:Interoperability mandates are compelling health systems to replace siloed legacy architectures with integrated platforms requiring extensive consulting support.
- Cloud migration:Providers are accelerating transitions from on-premise Epic and Cerner instances to cloud-native deployments, generating sustained implementation and optimization demand.
- United States hospital consolidation:Multi-facility health systems in Texas, California, and Florida are standardizing ERP platforms across acquired networks, expanding consulting scope per engagement.
Market Restraints
- Specialized talent scarcity:Certified Epic and Cerner consultants command premium rates that compress project margins and extend implementation timelines.
- Legacy system technical debt:Decades-old HL7 v2 interfaces require expensive reengineering to achieve FHIR compliance, inflating total cost of ownership.
- HIPAA security complexity:Cloud migration projects face extended audit cycles as security officers validate data residency and access controls across hybrid environments.
Strategic Opportunities
- Long-term care specialization:Skilled nursing facilities face Medicaid reimbursement complexity that creates demand for ERP consultants with state-specific regulatory expertise.
- Value-based payment integration:CMS alternative payment models are forcing deeper financial-clinical data linkage that legacy ERP configurations cannot support without redesign.
- AI-augmented workflow optimization:Machine learning tools for revenue cycle automation are expanding consulting portfolios beyond implementation into predictive analytics services.
Industry Challenges
- Change management execution:Clinical staff resistance to new billing workflows frequently derails go-live schedules despite technical system readiness.
- Interface engine complexity:Each additional EHR, laboratory, and pharmacy system integration multiplies testing cycles and defect remediation burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare ERP Consulting Services Market |
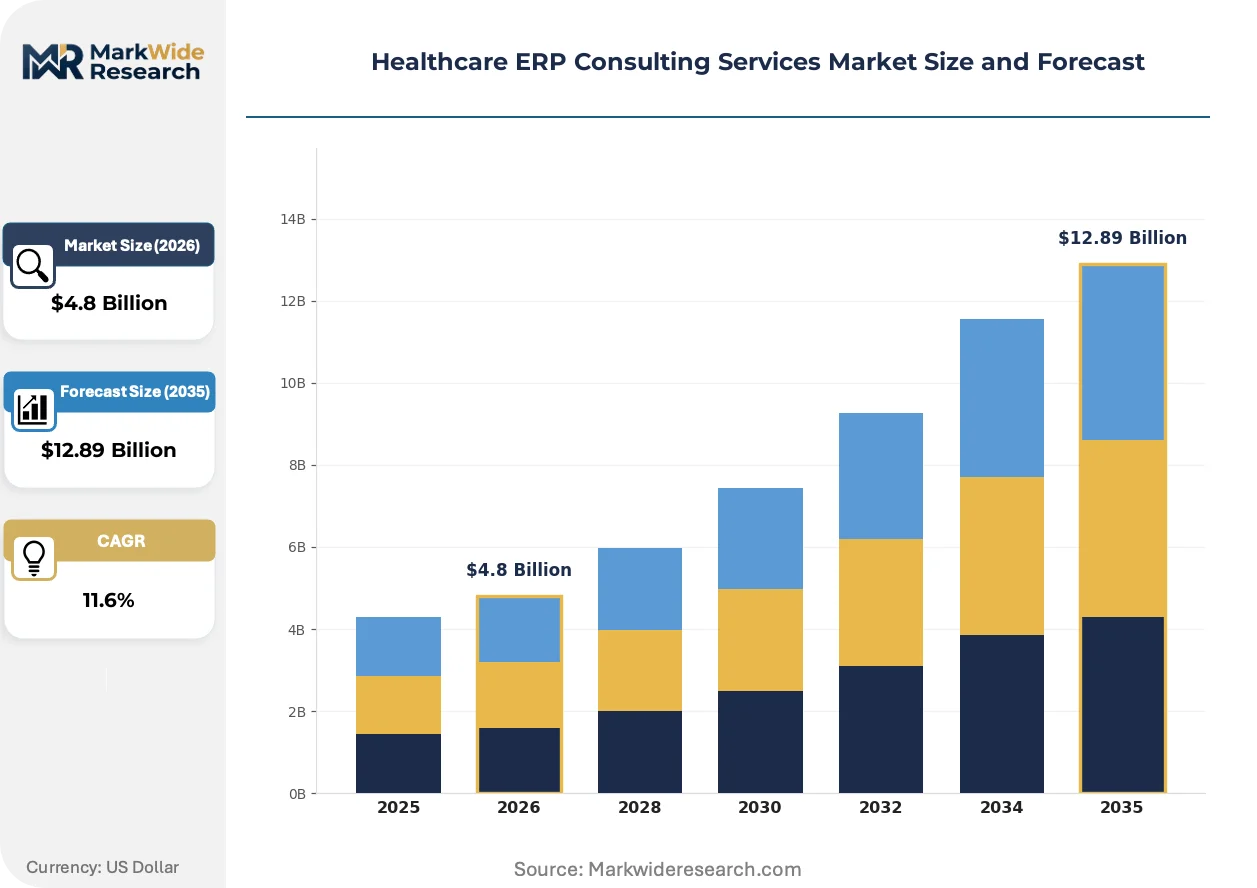
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.89 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Implementation, Customization, Support, Optimization End User: Hospitals, Clinics, Long-term Care Facilities, Health Systems Consulting Approach: Strategic Planning, Process Improvement, Change Management, Data Analytics Deployment Model: On-premise, Cloud-based, Hybrid, Mobile |
| Companies Covered | Accenture, Deloitte, PwC, KPMG, Cerner Corp., Premier, Inc., Workday, Inc., McKinsey & Company, Cognizant Technology Solutions Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare ERP Consulting Services Market Strategic Shifts & Innovations
Healthcare ERP consulting is pivoting from discrete implementation projects toward continuous optimization engagements as cloud platforms enable iterative module deployment.
Artificial intelligence is expanding into revenue cycle automation, with machine learning models now flagging prior authorization denials and predicting claim rejection probability. Community hospitals and regional health systems are piloting these tools fastest, drawn by immediate ROI visibility. This capability compression is displacing manual denial management staff and redirecting consulting budgets toward algorithm training and exception handling.
CMS Promoting Interoperability standards are mandating patient access APIs that expose clinical and financial data through standardized endpoints. Health systems must reconfigure ERP security models to support third-party application integration while maintaining HIPAA compliance. Organizations in Massachusetts and Minnesota are furthest along in compliance, driven by state-level health information exchange mandates that preceded federal requirements.
Subscription-based advisory retainers are replacing fixed-scope SOWs as health systems seek ongoing optimization rather than one-time implementation. Large integrated delivery networks in Illinois and Ohio are consolidating vendor relationships under multi-year partnerships that bundle training, upgrade management, and regulatory readiness. This shift concentrates consulting spend with firms demonstrating sustained clinical workflow expertise rather than pure technical credentials.
Healthcare ERP Consulting Services Market Segmentation
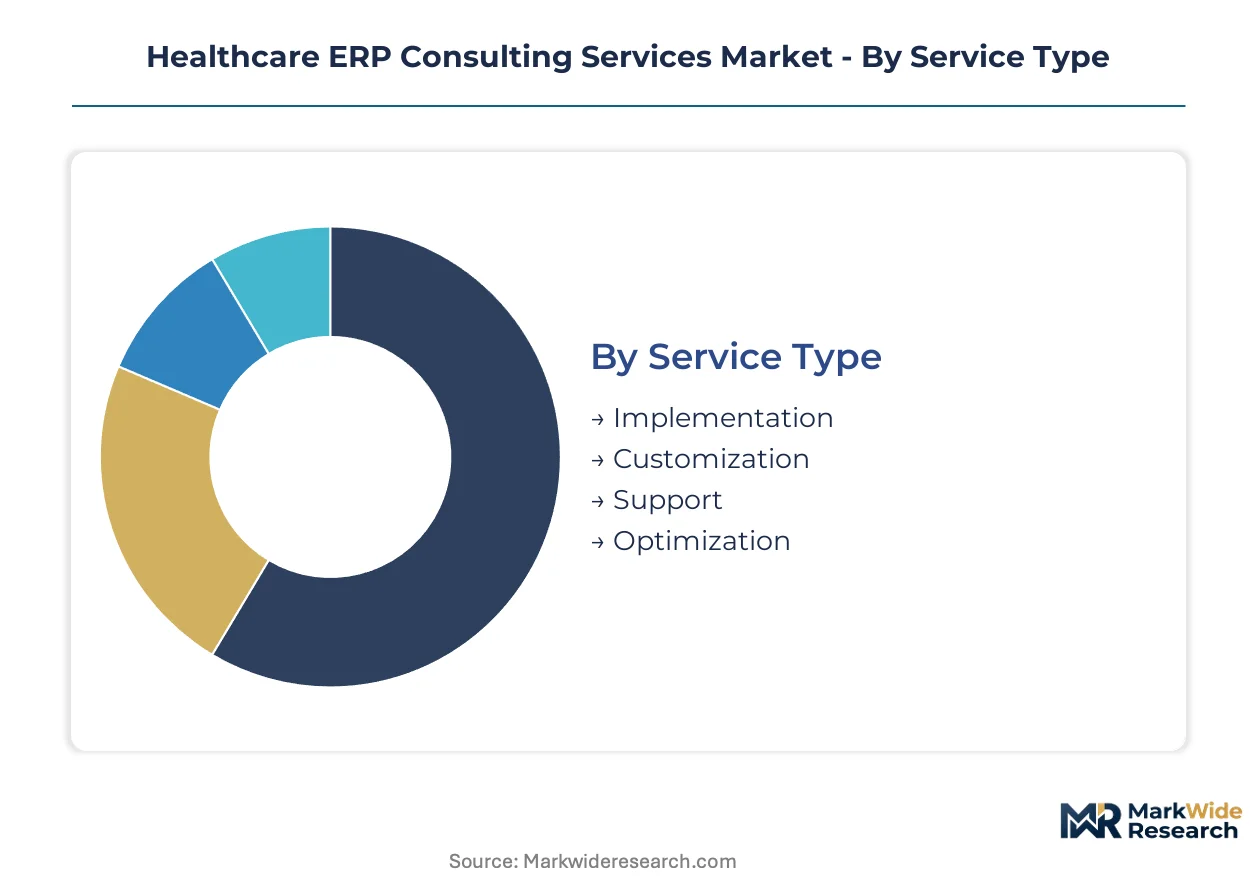
Healthcare ERP consulting engagements vary sharply by technical complexity and organizational readiness. Service mix, end-user scale, and deployment architecture determine project duration, staffing ratios, and margin structure for consulting firms competing in this space.
Service Type:
Legacy system replacement cycles and cloud migration waves are reshaping how providers procure consulting support across the implementation-to-optimization continuum.
- Implementation:New platform deployments require certified consultants for system configuration, data migration, and go-live support. Health systems in Texas and California concentrate demand here as multi-facility standardization projects accelerate.
- Optimization:Post-implementation tuning of revenue cycle modules and clinical workflows extends consulting relationships beyond initial deployment. This segment climbs fastest as cloud-native platforms enable iterative enhancement cycles rather than rip-and-replace upgrades.
- Customization:Specialized interface development and workflow tailoring for unique specialty service lines.
- Support:Ongoing technical assistance and break-fix services for stabilized production environments.
Implementation sits at the top of the volume ranking, with optimization climbing the fastest.
End User:
Organizational scale dictates consulting engagement architecture and regulatory complexity.
- Hospitals:Acute care facilities drive the largest individual contracts, with multi-hospital systems in Florida and Illinois bundling ERP standardization across acquired networks. FDA interoperability mandates force substantial reengineering of legacy financial-clinical integrations.
- Health Systems:Integrated delivery networks demand unified platforms spanning inpatient, outpatient, and post-acute settings. These engagements concentrate in states with aggressive hospital consolidation activity.
- Clinics:Ambulatory settings require lighter-touch implementation support with emphasis on patient portal integration and scheduling module configuration.
- Long-term Care Facilities:Skilled nursing and assisted living operators face Medicaid reimbursement complexity that creates specialized demand for state-specific regulatory expertise.
Hospitals anchor the revenue base, while long-term care facilities gain share fastest as Medicaid managed care expansion deepens.
Consulting Approach:
Buyer procurement patterns are shifting from discrete technical projects toward sustained advisory relationships.
- Strategic Planning:ERP roadmap development and vendor selection advisory for executive leadership. Health systems in Ohio and Massachusetts concentrate demand as they evaluate cloud migration timing against legacy depreciation schedules.
- Change Management:Clinical staff training and workflow transition support to mitigate go-live disruption. Resistance to new billing procedures frequently derails implementation timelines despite technical readiness.
- Process Improvement:Operational redesign to align clinical and financial workflows with value-based payment requirements.
- Data Analytics:Predictive modeling and dashboard development for revenue cycle performance monitoring.
Strategic planning commands premium pricing, with change management expanding most quickly as health systems recognize adoption risk.
Deployment Model:
Infrastructure decisions determine consulting skill requirements and project risk profiles.
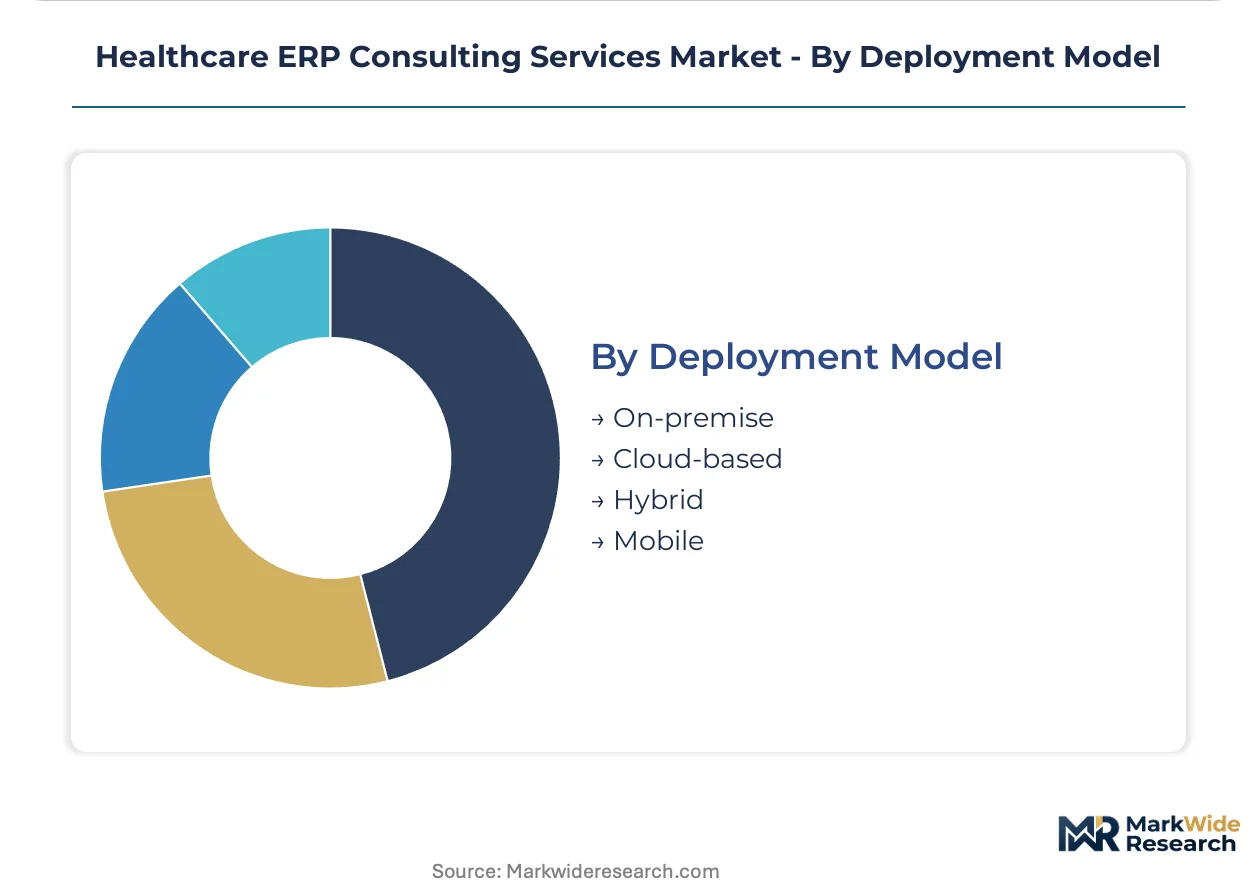
- Cloud-based:Migration from on-premise Epic and Cerner instances to hosted environments dominates current demand. HIPAA security validation for hybrid data residency configurations extends implementation timelines.
- Hybrid:Mixed architectures retaining sensitive financial data on-premise while moving clinical modules to cloud. These engagements concentrate among mid-size regional systems seeking staged transition paths.
- On-premise:Legacy maintenance and security patching for organizations deferring cloud migration.
- Mobile:Point-of-care access layer development for clinical workflow enablement.
Cloud-based deployments lead current project volume, with hybrid architectures steepest in expansion trajectory among risk-averse mid-market buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Healthcare ERP Consulting Services Market traces its commercial lineage to the United States, where Epic Systems and Cerner Corporation pioneered integrated clinical-financial platforms in the 1990s and early 2000s, establishing the consulting ecosystem that now spans multiple continents.
United States
Multi-hospital consolidation in Texas, California, and Florida drives sustained demand for ERP standardization across acquired networks. FDA 21st Century Cures Act interoperability mandates compel health systems to replace siloed legacy architectures with integrated platforms requiring extensive consulting support. The Greater Boston and Chicago metropolitan areas concentrate the highest density of Epic-certified implementation specialists.
Germany
Hospital digitization initiatives under the Hospital Future Act (KHZG) accelerate procurement of integrated financial-clinical systems. EMA regulatory alignment with FDA interoperability standards forces reengineering of legacy HL7 v2 interfaces. The Rhine-Ruhr and Bavarian hospital clusters are standardizing ERP platforms across regional health networks, expanding consulting engagement scope.
United Kingdom
NHS England's federated data platform procurement is driving ERP consolidation across integrated care systems. NHS Digital interoperability standards mandate FHIR-compliant data exchange that legacy configurations cannot satisfy without substantial consulting intervention. The London and Greater Manchester health economies lead deployment velocity, with Midlands systems following in subsequent waves.
Canada
Provincial health authority consolidation in Ontario and British Columbia is standardizing ERP platforms across previously autonomous hospitals. Health Canada digital health strategies align with FDA interoperability trajectories, requiring substantial legacy system reengineering. The Toronto-Waterloo corridor and Vancouver health clusters concentrate consulting demand for Epic and Cerner cloud migrations.
Australia
State-level hospital digitization programs in New South Wales and Victoria are replacing fragmented legacy systems with unified ERP architectures. TGA recognition of FDA interoperability standards accelerates compliance-driven consulting demand. The Sydney and Melbourne metropolitan health networks are furthest along in cloud-native deployment, with Queensland and Western Australia following.
Healthcare ERP Consulting Services Market Key Industry Players
The competitive structure tilts toward professional services conglomerates with deep healthcare vertical expertise. Tier-one consulting firms anchor the premium segment through sustained clinical workflow specialization, while technology-enabled delivery models compete on cost for large-scale implementations. Three archetypes dominate: global professional services networks, offshore-centric technology integrators, and boutique healthcare specialists. Consolidation through strategic acquisitions and multi-year advisory retainers represent the dominant competitive vectors reshaping vendor relationships.
Within the professional services tier, Deloitte exemplifies clinical workflow depth, while Cognizant Technology Solutions Corporation represents the offshore-enabled scale model. Accenture occupies a position spanning both technology implementation and strategic advisory. These three anchors illustrate how competitive positioning separates firms with sustained healthcare vertical expertise from those competing primarily on technical credentials or cost structure.
| Leading Market Players |
|---|
| Accenture |
| Deloitte |
| PwC |
| KPMG |
| Cerner Corp. |
| Premier, Inc. |
| Workday, Inc. |
| McKinsey & Company |
| Cognizant Technology Solutions Corporation |
| Others |
Cost & Logistics Intelligence
Multi-hospital health system consolidation in Texas, California, and Florida is compressing consulting procurement timelines and forcing vendors to absorb upfront certification costs, which in turn stratifies service tiers by Epic and Cerner credential depth rather than geographic delivery cost alone.
Pricing Analysis
Project-based engagements with outcome-linked milestones anchor the dominant pricing structure across implementation and optimization services. Price differentiation hinges on consultant certification tier—Epic-certified specialists command substantial premiums over general healthcare IT practitioners—and engagement complexity measured by interface engine count and legacy system vintage. Cost compression in mid-market health systems is intensifying because offshore delivery models from Cognizant and similar firms are compressing margins for standardized Cerner deployments. Large integrated delivery networks exhibit the lowest price sensitivity, prioritizing clinical workflow expertise and change management depth over per-hour rate competition.
Supply Chain Analysis
Certified consultant availability in the United States, India, and the Philippines directly constrains project throughput and delivery timelines. The talent pipeline draws from university partnerships in the Greater Boston and Chicago metropolitan areas, offshore training centers in Hyderabad and Manila, and lateral hiring from health system IT departments. Single-source vulnerability concentrates around Epic Systems' proprietary certification programs, which control consultant credential supply without third-party alternatives. Distribution runs through direct enterprise sales teams for tier-one consultancies and channel partnerships for boutique specialists serving regional health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as FDA interoperability mandates perpetuate legacy system replacement cycles regardless of macroeconomic conditions, embedding recurring consulting demand into health system capital planning.
For Market Incumbents: Cement competitive position by acquiring boutique healthcare workflow specialists in long-term care and Medicaid reimbursement niches before regional players scale. Deepen vertical integration into cloud-native training and certification programs to offset talent scarcity premiums that compress project margins. Prioritize multi-year advisory retainers with Illinois and Ohio integrated delivery networks that are consolidating vendor relationships. For New Entrants and Emerging Players: Begin with skilled nursing facility ERP optimization in states with aggressive Medicaid managed care expansion, where incumbent presence remains thin and state-specific regulatory expertise creates defensible positioning. Target community hospitals piloting AI-augmented revenue cycle automation, as these organizations seek algorithm training and exception handling support beyond pure technical implementation. Lead with subscription-based advisory retainers rather than fixed-scope proposals to align with shifting procurement preferences. For Investors and Strategic Acquirers: Asymmetric upside sits with boutique healthcare specialists possessing deep Medicaid reimbursement expertise and established state health authority relationships. Long-term viability rests on consulting firms' ability to pivot from implementation toward continuous optimization as cloud platforms enable iterative module deployment. Monitor CMS alternative payment model expansion velocity as the signal indicating when financial-clinical integration depth requirements will accelerate consulting demand beyond current replacement-cycle baselines.| Strategic Initiative | Industry Significance |
|---|---|
| Epic-Certified Talent Acquisition | Builds delivery capacity for Texas and California multi-facility standardization projects. |
| Long-Term Care Specialization | Captures Medicaid reimbursement complexity demand as skilled nursing facilities digitize. |
| AI Workflow Partnership | Positions firms for predictive analytics services beyond traditional implementation scope. |
| Multi-Year Advisory Retainer | Aligns with Illinois and Ohio health systems consolidating vendor relationships. |
| FHIR Compliance Practice | Addresses FDA 21st Century Cures Act mandates forcing legacy system reengineering. |
Research Approach
Coverage spans the United States, Germany, United Kingdom, Canada, and Australia, with primary inputs from each market informing regional demand calibration. Primary interviews with Epic-certified implementation specialists, health system CIOs, GPO contracts managers, and CMS policy officers combined with secondary validation from hospital procurement databases, FDA 510(k) filings, and CMS Medicare cost report data. Bottom-up project pipeline analysis and top-down health system capital expenditure triangulation anchored market sizing.
Granularity-level modeling deployed service type, end-user scale, deployment architecture, and geographic regulatory cluster as core segmentation dimensions across the projection horizon. CAGRs derived from weighted average of historical implementation velocity and cloud migration adoption curves. Industry-specific forecast inputs included Epic and Cerner certification program throughput rates and state-level hospital consolidation transaction volume.
Several conditions sit outside the modeled scope, including potential repeal or substantial modification of FDA interoperability mandates, disruptive vendor consolidation among ERP platform providers, and macroeconomic conditions that could defer health system capital expenditures. Forecasts reflect assumptions about sustained regulatory pressure and cloud migration continuity. Practitioners should monitor CMS value-based payment model expansion and Epic certification program capacity constraints for early signals of demand inflection or supply bottleneck severity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Consulting
Global Strategic Consulting Services Market
Healthcare Consulting
Africa Pharmaceutical Regulatory Affairs Market
Healthcare Consulting
Pharmaceutical Regulatory Affairs Market
Healthcare Consulting
Global Medical Device Regulatory Affairs Outsourcing Market
Healthcare Consulting
Global Healthcare Consulting Services Market
Healthcare Consulting
Healthcare Regulatory Affairs Outsourcing Market
Healthcare Consulting
UK Healthcare Consulting Market
Healthcare Consulting
Global Regulatory Affairs Market
Healthcare Consulting
Global Public Sector Consulting and Advisory Services Market
Healthcare Consulting
Global Healthcare IT Consulting Market
Healthcare Consulting
Europe Medical Device Regulatory Affairs Outsourcing Market
Healthcare Consulting
Italy Operations Service Consulting Market
Healthcare Consulting
Consulting Service Market
Healthcare Consulting
Healthcare Contract Sales Organizations Market