
 Global Micro-Ultrasound Systems Market | 2026-2036
Global Micro-Ultrasound Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Micro-Ultrasound Systems Market Foresight
High-frequency transducer miniaturization is reshaping how micro-ultrasound systems penetrate previously inaccessible anatomical spaces. GE HealthCare leverages its probe manufacturing scale to supply academic institutions with research-grade micro-ultrasound platforms. Siemens Healthineers anchors its position through deep R&D investment in 3D imaging algorithms for urological applications. Koninklijke Philips differentiates by controlling distribution channels that reach specialized clinics across multiple continents.
Micro-ultrasound systems employ acoustic frequencies exceeding 20 MHz to achieve spatial resolutions below 50 micrometers, enabling visualization of cellular-level tissue architecture for diagnostic and interventional guidance. High-frequency technology leads product development as clinicians demand finer resolution for dermatology and ophthalmology applications. Software platforms represent the fastest-expanding segment as artificial intelligence integration creates recurring revenue models for vendors serving diagnostic centers. The accessories category remains mature with stable margins tied to disposable probe covers and coupling gels.
FDA 510(k) premarket notification requirements and the EU MDR conformity assessment process shape product development timelines and clinical evidence standards for micro-ultrasound manufacturers. Japan's PMDA and China's NMPA impose additional localization testing that filters market access for smaller entrants. Stakeholders must monitor evolving reimbursement codes for micro-ultrasound-guided biopsies as payor decisions will determine clinical adoption velocity in outpatient settings.
Market Dynamics
High-frequency transducer miniaturization is compressing the boundary between diagnostic imaging and cellular-level intervention, forcing manufacturers to recalibrate R&D priorities toward acoustic engineering and software integration simultaneously.
Growth Catalysts
- EU MDR conformity pathways:The Medical Device Regulation's stricter clinical evidence requirements are filtering out marginal competitors and elevating quality benchmarks for surviving vendors.
- Cardiology catheterization labs:Intravascular imaging demand from specialized cardiac centers in Germany and Japan is pulling high-frequency probe development toward 40-70 MHz ranges.
- Artificial intelligence integration:Machine learning algorithms for real-time tissue characterization are creating recurring revenue streams through software licensing models.
Market Restraints
- Piezoelectric material concentration:Single-crystal PZT supply chains concentrate in East Asian foundries, exposing probe manufacturers to input volatility and geopolitical friction.
- Acoustic attenuation physics:Frequency-resolved depth trade-offs above 30 MHz limit micro-ultrasound penetration to superficial tissues regardless of transducer quality.
- Japan PMDA localization mandates:Extended clinical testing requirements for foreign manufacturers delay market entry by 18-24 months versus domestic competitors.
Strategic Opportunities
- India's diagnostic infrastructure expansion:Government-funded medical device parks in Andhra Pradesh and Gujarat offer tax incentives for probe assembly localization.
- Ophthalmology anterior segment imaging:Corneal and trabecular meshwork visualization applications remain underpenetrated relative to dermatology and urology deployments.
- Point-of-care workflow convergence:Handheld micro-ultrasound platforms combined with tablet-based AI interpretation are opening ambulatory surgery centers previously served by referral imaging.
Industry Challenges
- Acoustic engineer scarcity:Specialized expertise in high-frequency transducer design concentrates within a handful of academic programs in Boston, Munich, and Tokyo.
- FDA 510(k) predicate device drift:Evolving substantial equivalence standards for software-as-medical-device components are extending clearance timelines unpredictably.
- Legacy PACS integration:Hospital information systems built for conventional 2-15 MHz ultrasound formats require middleware development for micro-ultrasound DICOM compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Micro-Ultrasound Systems Market |
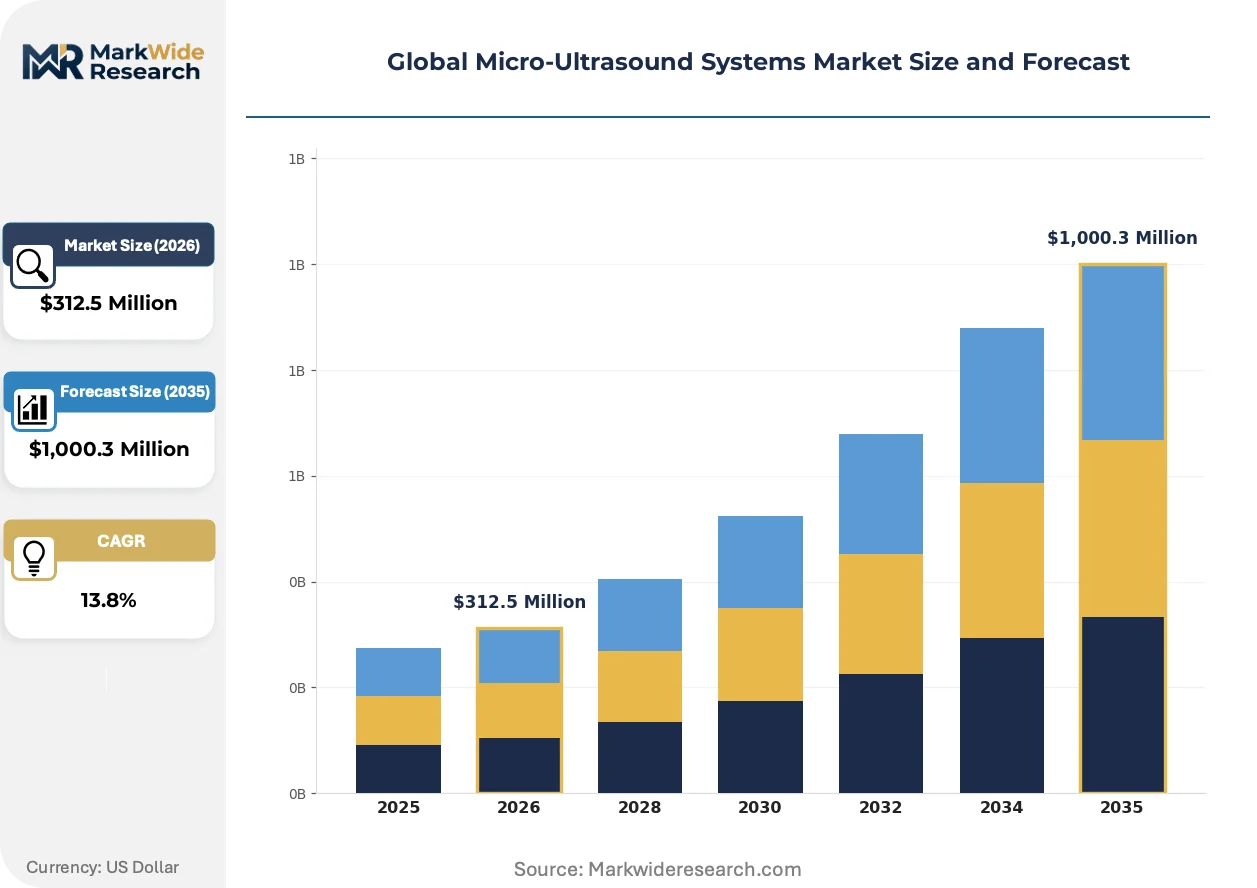
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $1,000.3 Million |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probes, Imaging Consoles, Software Platforms, Accessories Technology: High-Frequency, 3D Imaging, Doppler Ultrasound, Elastography, Contrast-Enhanced Application: Urology, Cardiology, Oncology, Obstetrics, Dermatology End User: Diagnostic Centers, Academic Institutions, Specialized Clinics, Research Laboratories |
| Companies Covered | GE HealthCare, Koninklijke Philips, Siemens Healthineers, Canon Medical Systems Corporation, FUJIFILM, Shenzhen Mindray Bio-Medical Electronics, Samsung Healthcare, Esaote, Hologic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Micro-Ultrasound Systems Market Shifts & Advancements
Three convergent forces are restructuring how micro-ultrasound systems deliver value: acoustic hardware miniaturization, algorithmic automation of image interpretation, and regulatory frameworks that increasingly treat software as the primary value determinant rather than probe hardware.
Capacitive micromachined ultrasonic transducer (CMUT) arrays are collapsing the cost-performance frontier for frequencies above 50 MHz. Academic medical centers in Stanford and Heidelberg are piloting CMUT-based intravascular platforms that eliminate the ceramic bonding steps constraining conventional piezoelectric manufacturing. The technology is collapsing the minimum viable scale for high-frequency probe production, enabling niche applications previously uneconomical at low volumes.
China's NMPA issued draft guidance in 2024 establishing standalone software validation requirements for AI-assisted diagnostic features, diverging from hardware-centric approval templates. Domestic manufacturers in Shenzhen must now submit algorithm training datasets and performance validation across demographic subgroups. Dermatology applications face the steepest compliance burden given the ethnic diversity of training data requirements.
Specialized clinics are unbundling capital equipment purchasing from service contracts, treating micro-ultrasound platforms as modular components within broader procedural revenue streams. Outpatient urology centers in Texas and Florida now lease probe hardware while subscribing separately to cloud-based 3D reconstruction software. This consumption pattern is most visible in United States markets where reimbursement for micro-ultrasound-guided biopsies creates direct procedure-level ROI visibility.
Global Micro-Ultrasound Systems Market Segmentation
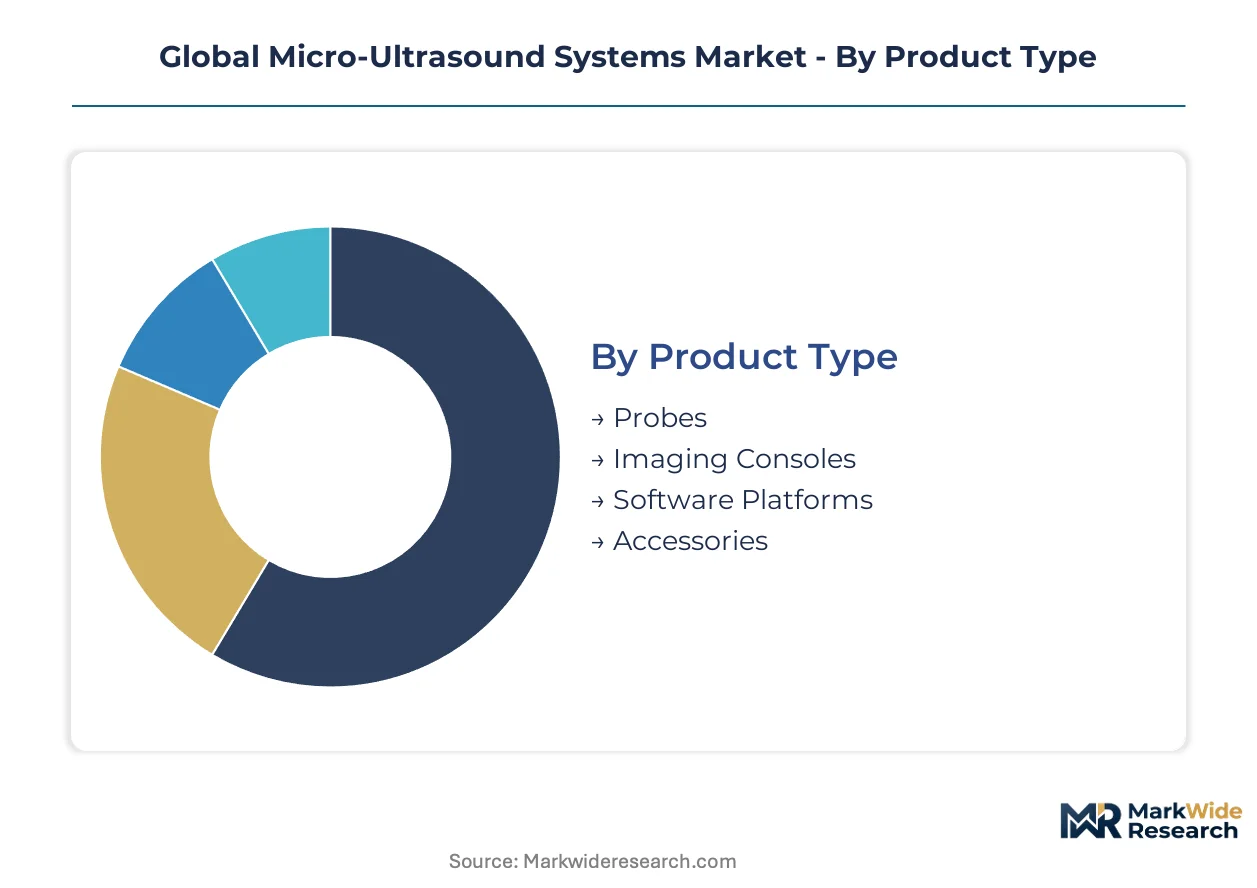
Micro-ultrasound systems fragment across hardware, software, and service layers that demand distinct procurement cycles and technical support intensities. Vendors must calibrate portfolio investments across these boundaries where margin profiles and customer retention mechanics diverge sharply.
Product Type:
After-sales service intensity varies dramatically across hardware-software boundaries, with probe replacement cycles and software update subscriptions creating divergent recurring revenue streams for manufacturers.
- Probes:Piezoelectric transducer assemblies operating at 20-70 MHz frequencies constitute the primary value anchor, with single-crystal PZT materials dominating high-performance tiers. Demand concentrates in German and Japanese cardiology catheterization labs where intravascular imaging protocols mandate 40-70 MHz specifications for plaque characterization. Acoustic engineer scarcity in Boston, Munich, and Tokyo constrains manufacturing scale-up regardless of material availability.
- Software Platforms:AI-powered tissue characterization and 3D reconstruction algorithms generate recurring licensing revenue through cloud-based subscription models. Diagnostic centers in the United States increasingly unbundle software procurement from hardware, treating image analysis capabilities as independent budget line items with annual renewal cycles.
- Imaging Consoles:Hardware chassis with beamforming electronics and display interfaces represent capital-intensive procurement decisions with 7-10 year replacement cycles. Academic medical centers prioritize research-grade flexibility over clinical workflow optimization.
- Accessories:Disposable probe covers, coupling gels, and sterilization trays generate stable margins with minimal technical support burden. Procurement concentrates in high-volume outpatient settings where per-procedure economics dominate purchasing decisions.
Probes hold the largest share; momentum sits with software platforms.
Technology:
Cost tier differentiation separates research-grade capabilities from clinical workhorse specifications, with premium frequencies commanding 3-5x price multiples over standard diagnostic ranges.
- High-Frequency:Acoustic platforms exceeding 30 MHz enable sub-50 micrometer spatial resolution for cellular-level tissue architecture visualization. Dermatology departments in Heidelberg and Stanford academic centers drive specification requirements toward 50+ MHz for non-melanoma skin cancer margin assessment. Physics-imposed depth limitations above 30 MHz restrict applications to superficial anatomical structures regardless of transducer investment.
- 3D Imaging:Volumetric reconstruction algorithms transform sequential 2D slices into navigable tissue models for interventional planning. Urology clinics in Texas and Florida leverage cloud-based 3D reconstruction subscriptions to differentiate biopsy guidance services without capital equipment expansion.
- Doppler Ultrasound:Velocity-sensitive detection of blood flow complements structural imaging in vascular access and perfusion monitoring applications. Standard-of-care deployment across most clinical settings limits premium pricing power.
- Elastography:Tissue stiffness mapping through acoustic radiation force impulse techniques enables non-invasive fibrosis staging. Hepatology and urology applications drive niche adoption with specialized training requirements.
- Contrast-Enhanced:Microbubble agent compatibility expands perfusion imaging capabilities for tumor characterization and treatment monitoring. Regulatory complexity across FDA, EMA, and NMPA jurisdictions constrains standardized protocol development.
High-frequency technology commands premium positioning; 3D imaging gains share fastest through software-centric delivery models.
Application:
Volume concentration in established specialties funds cross-subsidization of emerging indications where clinical evidence accumulation remains incomplete.
- Urology:Transrectal micro-ultrasound dominates prostate biopsy guidance with established reimbursement pathways in United States outpatient settings. Specialized clinics in Florida and Texas treat probe hardware as leased equipment while subscribing separately to AI-enhanced targeting software.
- Cardiology:Intravascular imaging at 40-70 MHz frequencies enables plaque characterization and stent placement optimization in German and Japanese catheterization labs. PMDA localization mandates extend market entry timelines for foreign manufacturers by 18-24 months versus domestic competitors.
- Oncology:Tumor margin delineation and treatment response monitoring applications span multiple anatomical sites with indication-specific probe requirements. Reimbursement code development lags technology capability, constraining outpatient adoption velocity.
- Obstetrics:Fetal micro-imaging remains investigational with limited clinical evidence supporting routine deployment over conventional ultrasound. Academic research programs dominate current utilization.
- Dermatology:Non-melanoma skin cancer and inflammatory condition assessment represents underpenetrated expansion territory relative to urology and cardiology installed bases. NMPA draft guidance imposes steepest algorithm training data requirements for ethnic diversity compliance.
Urology holds the largest share; dermatology presents the steepest expansion trajectory as anterior segment protocols mature.
End User:
Customer type determines procurement authority structures, with hospital system administrators, research principal investigators, and clinic owner-operators exercising divergent evaluation criteria and budget timelines.
- Diagnostic Centers:High-volume outpatient imaging facilities prioritize throughput optimization and technologist workflow efficiency in equipment selection. United States markets exhibit strongest unbundling of hardware procurement from software subscription services.
- Academic Institutions:Research-grade flexibility and publication-supporting technical specifications dominate purchasing decisions over clinical reimbursement optimization. Stanford and Heidelberg programs pilot CMUT-based intravascular platforms eliminating conventional ceramic bonding constraints.
- Specialized Clinics:Urology and cardiology single-specialty practices treat micro-ultrasound as procedural revenue enablers with direct ROI visibility at the intervention level. Texas and Florida markets lead leasing-plus-subscription consumption patterns.
- Research Laboratories:Preclinical and translational imaging applications demand customizable acoustic parameters and open software architectures. Procurement cycles align with grant funding timelines rather than capital budget calendars.
Diagnostic centers hold the largest share; specialized clinics are expanding most quickly through ambulatory surgery center penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for single-crystal PZT transducer materials shapes regional manufacturing strategies, with probe assembly capacity concentrating in East Asian foundries while clinical demand pulls finished systems toward Western academic medical centers and specialized clinics.
United States
Academic medical centers in Stanford and Boston pilot CMUT-based intravascular platforms, driving specification requirements toward research-grade flexibility. FDA 510(k) premarket notification pathways impose evolving substantial equivalence standards for software-as-medical-device components. Texas and Florida urology clinics treat micro-ultrasound hardware as leased equipment while subscribing separately to AI-enhanced targeting software.
Germany
Cardiology catheterization labs in Munich and Heidelberg anchor European demand for 40-70 MHz intravascular imaging systems. EU MDR conformity assessment processes filter marginal competitors through stricter clinical evidence requirements. The Baden-Württemberg industrial corridor hosts precision acoustic engineering clusters supplying probe manufacturing for research institutions.
Japan
Domestic manufacturers benefit from PMDA localization mandates that extend foreign competitor market entry timelines by 18-24 months. METI-funded medical device initiatives support high-frequency transducer development for plaque characterization applications. Tokyo and Osaka academic programs concentrate scarce acoustic engineering expertise.
China
Shenzhen-based manufacturers face NMPA draft guidance establishing standalone software validation requirements for AI-assisted diagnostic features. Government-funded medical device parks in Guangdong and Jiangsu provinces offer tax incentives for probe assembly localization. Domestic vendors must submit algorithm training datasets across demographic subgroups for dermatology applications.
India
Government-funded medical device parks in Andhra Pradesh and Gujarat attract probe assembly investment through tax incentives and tariff exemptions. CDSCO regulatory pathways remain less stringent than FDA or EU MDR equivalents, enabling faster market entry for mid-tier equipment. Diagnostic infrastructure expansion in metropolitan centers creates demand for handheld point-of-care platforms.
Global Micro-Ultrasound Systems Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: diversified imaging conglomerates with captive probe manufacturing, specialized acoustic engineering firms, and software-centric platform developers. Tiered competitive dynamics separate premium research-grade specifications from clinical workhorse deployments. Dominant competitive moves include strategic partnerships between hardware manufacturers and AI software developers, plus geographic expansion through localized assembly joint ventures.
Within the diversified imaging conglomerate tier, GE HealthCare, Koninklijke Philips, and Siemens Healthineers exemplify scale-driven positioning. These manufacturers leverage existing distribution channels and hospital system relationships to bundle micro-ultrasound platforms within broader imaging equipment portfolios. Their geographic footprints span North American, European, and Asia-Pacific clinical markets.
| Leading Market Players |
|---|
| GE HealthCare |
| Koninklijke Philips |
| Siemens Healthineers |
| Canon Medical Systems Corporation |
| FUJIFILM |
| Shenzhen Mindray Bio-Medical Electronics |
| Samsung Healthcare |
| Esaote |
| Hologic |
| Others |
Supply & Pricing Matrix
East Asian foundry concentration for single-crystal PZT piezoelectric materials funnels pricing power toward probe manufacturers with captive supply agreements or long-term offtake contracts, compressing margins for assembly-dependent vendors in Europe and North America. Research-grade micro-ultrasound platforms command 3-5x multiples over clinical workhorse specifications, with AI-enhanced software subscriptions extracting recurring value independent of hardware depreciation cycles.
Pricing Analysis
Academic medical centers and specialized clinics anchor a hybrid pricing structure combining capital equipment procurement with recurring software licensing. Price differentiation rests on frequency specification tiers and FDA 510(k) clearance status, with 40-70 MHz intravascular systems carrying substantial premiums over standard 20-30 MHz dermatology platforms. Pricing pressure intensifies in outpatient urology segments where leasing models commoditize probe hardware and shift margin capture toward cloud-based 3D reconstruction subscriptions. Diagnostic centers exhibit highest price sensitivity, prioritizing per-procedure economics over research-grade flexibility.
Supply Chain Analysis
Export control regimes restricting advanced piezoelectric manufacturing equipment constrain capacity expansion outside established East Asian production clusters. Single-crystal PZT supply concentrates in Chinese and Japanese foundries, with CMUT wafer fabrication emerging from South Korean semiconductor manufacturing ecosystems. Raw material dependencies span rare-earth dopants for ceramic formulations, precision-machined acoustic lenses, and high-density interconnect substrates. Supply chain risk centers on single-source vulnerability for frequencies exceeding 50 MHz where qualified alternative suppliers remain scarce. Distribution runs through diversified imaging conglomerate channels reaching hospital systems and specialized clinics across North American, European, and Asia-Pacific clinical markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global micro-ultrasound systems markets are recovering from regulatory-induced investment pauses as EU MDR conformity pathways and FDA software-as-medical-device guidance stabilize, enabling predictable product development timelines and capital commitment resumption.
For Market Incumbents: Pre-empt CMUT-based probe commoditization by securing exclusive licensing agreements with Stanford and Heidelberg academic programs piloting capacitive micromachined ultrasonic transducer platforms. Deepen backward integration into single-crystal PZT supply through joint ventures with East Asian foundries, insulating manufacturing scale from geopolitical friction and input volatility threatening competitors dependent on spot-market procurement. For New Entrants and Emerging Players: Establish a beachhead in India's diagnostic infrastructure expansion by localizing probe assembly within Andhra Pradesh and Gujarat medical device parks, leveraging CDSCO regulatory pathways that enable faster market entry than FDA or EU MDR equivalents. Target handheld point-of-care platforms for ambulatory surgery centers in United States markets where reimbursement visibility for micro-ultrasound-guided biopsies creates direct procedure-level ROI justification. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed acoustic engineering specialists holding scarce high-frequency transducer design expertise concentrated in Boston, Munich, and Tokyo academic programs. Long-term viability hinges on software recurring revenue ratios rather than hardware shipment volumes, favoring targets with cloud-based AI tissue characterization platforms. Watch NMPA dermatology algorithm validation requirements as inflection indicator—domestic Chinese vendors submitting ethnic-diverse training datasets signal regulatory pathway maturation enabling scaled market entry.| Strategic Initiative | Industry Significance |
|---|---|
| CMUT Technology Licensing | Capacitive micromachined ultrasonic transducer partnerships collapse ceramic bonding constraints for frequencies above 50 MHz. |
| AI Software Companion Development | Machine learning tissue characterization algorithms create recurring revenue streams through cloud-based subscription models. |
| East Asian Supply Joint Venture | Captive single-crystal PZT access insulates probe manufacturing from geopolitical friction and input volatility. |
| India Localization Assembly | Andhra Pradesh and Gujarat medical device parks offer tax incentives and faster CDSCO regulatory pathways. |
| Reimbursement Strategy Investment | CMS and commercial payor code development for micro-ultrasound-guided biopsies determines outpatient adoption velocity. |
Research Methodology
A standing panel of interventional cardiologists, urology clinic owner-operators, biomedical engineers, hospital GPO contracts managers, and FDA regulatory affairs consultants provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR conformity assessment records, PMDA approval timelines, NMPA draft guidance documents, and hospital procurement contract repositories. Bottom-up probe shipment estimates and top-down imaging equipment capital expenditure patterns were triangulated against academic research funding disclosures.
Scenario bracketing anchored optimistic and conservative growth trajectories around EU MDR implementation pace, FDA software-as-medical-device guidance evolution, and reimbursement code development timelines across the analysis window. Segmentation modeling spanned product type, frequency specification tier, clinical application, end-user category, and regional regulatory cluster. CAGRs were derived from installed base growth rates, replacement cycle compression, and software attach rate assumptions. Industry-specific inputs included acoustic engineer graduation rates from Munich and Tokyo programs, single-crystal PZT foundry capacity utilization, and CMUT wafer yield improvements from South Korean semiconductor manufacturing.
Stress conditions across PMDA localization mandate duration, East Asian export control expansion, and AI algorithm validation requirement stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding regulatory pathway stability, probe manufacturing scale economics, and software recurring revenue capture rates. Material shifts in FDA substantial equivalence standards for software components or single-crystal PZT supply disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Gallium-68 Market
Medical Imaging
France Computed Tomography Market
Medical Imaging
Diagnostic Imaging Markers Market
Medical Imaging
Echocardiography Market
Medical Imaging
Japan Computed Tomography Market
Medical Imaging
Ultrasound Image Processing Software Market
Medical Imaging
Mammography Detectors Market
Medical Imaging
Argentina Digital X-Ray Market
Medical Imaging
Global 3D Laparoscopy Imaging Market
Medical Imaging
Europe Digital Radiology Market
Medical Imaging
Medical Imaging Software Market
Medical Imaging
3D Imaging Surgical Solution Market
Medical Imaging
Middle East and Africa Mammography Market
Medical Imaging
India Diagnostic Imaging Equipment Market
Medical Imaging
Europe Fluoroscopy Market
Medical Imaging
South Korea Digital X-Ray Market