
 South Korea Mammography Market | 2026-2036
South Korea Mammography Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Mammography Market Outlook
Artificial intelligence integration into mammography reading workflows is fragmenting the traditional radiologist-centered diagnostic chain. Samsung Medison leverages its domestic manufacturing footprint to control service response times in Seoul metropolitan installations. Hologic Inc. anchors its position through dense breast tissue imaging protocols that differentiate its 3D platform from conventional digital systems. Fujifilm Holdings Corp. competes by extending its endoscopy channel relationships into breast imaging procurement decisions at multi-site hospital groups.
Mammography denotes X-ray-based breast imaging using low-dose ionizing radiation, typically operating at 25-35 kVp tube voltage with molybdenum or rhodium target materials and dedicated compression paddles to optimize tissue separation and dose efficiency. The primary purpose is early detection of microcalcifications and mass lesions for cancer screening and diagnostic workup. Digital mammography systems occupy the largest installed base across South Korean screening centers, while 3D mammography captures the fastest growth trajectory as breast density notification requirements expand. Portable mammography units serve rural and island communities where fixed infrastructure remains limited, though margin pools concentrate in premium 3D systems deployed at breast clinics in Daegu and Gwangju.
MFDS device licensing requirements and KHIDI screening quality standards shape product entry pathways and clinical validation obligations for imported and domestically manufactured systems. The Ministry of Health and Welfare reimbursement schedules for national cancer screening programs directly determine hospital upgrade cycles and technology substitution rates. Stakeholders must monitor how MFDS software-as-medical-device classifications for AI detection algorithms reshape competitive boundaries between hardware manufacturers and algorithm developers.
Market Dynamics
Digital breast tomosynthesis is compressing upgrade cycles at Seoul Capital Area tertiary hospitals while MFDS quality mandates force simultaneous software validation timelines for AI-enabled reading workflows.
Growth Catalysts
- MFDS Screening Quality Mandates:National cancer screening program expansions under KHIDI protocols compel breast clinics in Busan and Daegu to replace aging analog systems with certified digital platforms.
- Seoul Capital Area Hospital Networks:Tertiary institutions anchor procurement volumes through centralized purchasing consortia that standardize on 3D mammography for dense breast tissue protocols.
- AI Detection Algorithms:Software-as-medical-device classifications are creating new revenue streams for algorithm developers integrated into hardware manufacturer service contracts.
Market Restraints
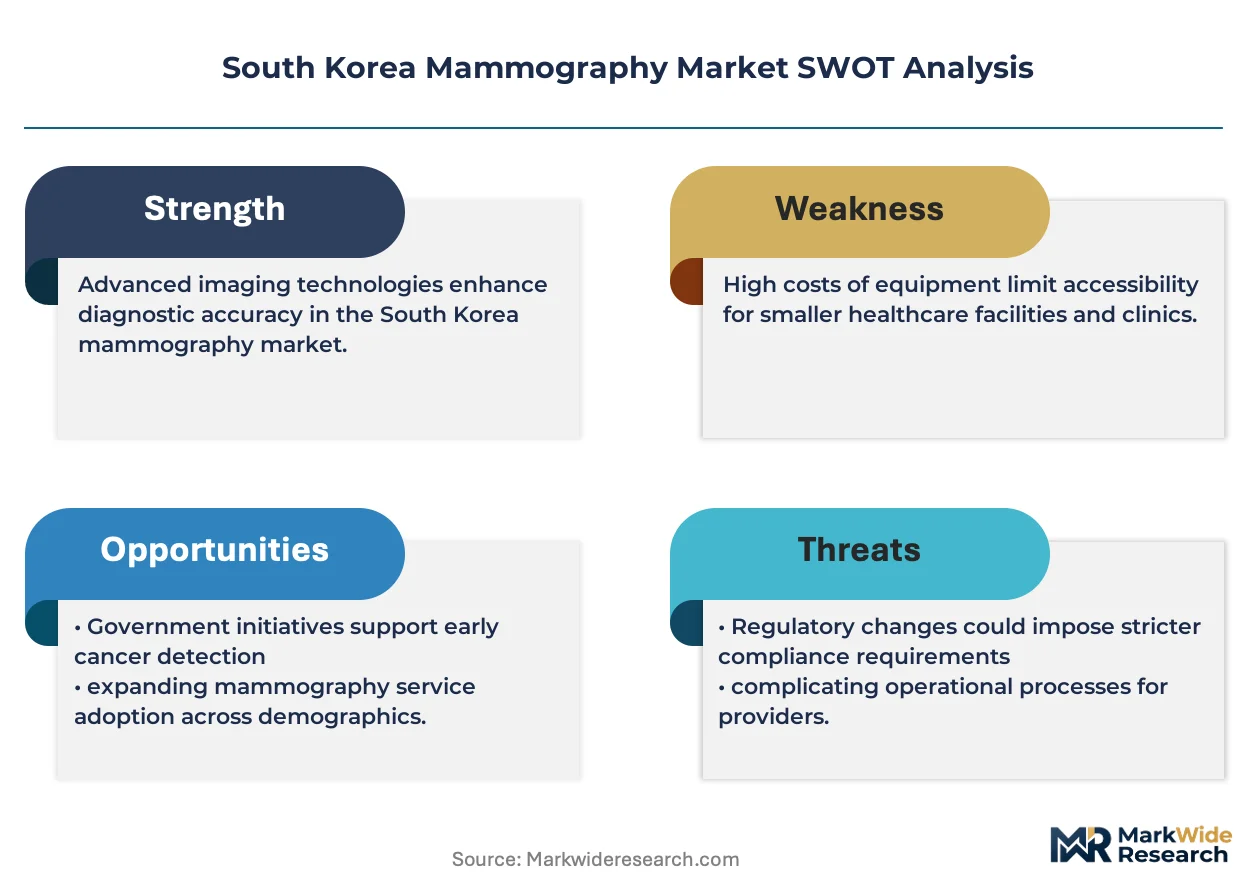
- Import Dependency for X-ray Tube Assemblies:Domestic manufacturers lack captive production of molybdenum and rhodium target materials, exposing procurement to tungsten supply volatility and currency fluctuation.
- MFDS Software Validation Timelines:AI algorithm licensing requires 12-18 month clinical validation studies that delay product commercialization and compress first-mover advantage windows.
- Fixed Infrastructure Limitations:Rural island communities in Jeollanam-do and Gyeongsangbuk-do lack grid stability for high-voltage digital systems, restricting portable unit margins.
Strategic Opportunities
- Gwangju-Daejeon Corridor Expansion:Secondary metropolitan breast clinics outside Seoul exhibit underpenetrated 3D system density relative to screening-eligible population concentration.
- Tele-radiology Convergence:Cloud-based image transmission paired with AI pre-reading is enabling hub-and-spoke screening networks that centralize specialist interpretation.
- Ministry of Health and Welfare Reimbursement Adjustments:Pending schedule revisions for dense breast supplemental imaging create procurement pull-through for tomosynthesis-capable systems.
Industry Challenges
- Breast Imaging Specialist Shortage:Radiologist training programs in South Korea produce insufficient fellowship-trained mammographers to match screening volume expansion targets.
- Legacy PACS Integration Complexity:Hospital information systems at provincial medical centers require costly middleware development to accommodate DICOM-structured report outputs from new 3D platforms.
- AI Algorithm Retraining Obligations:MFDS post-market surveillance mandates continuous validation dataset updates that strain developer resources and create compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Mammography Market |
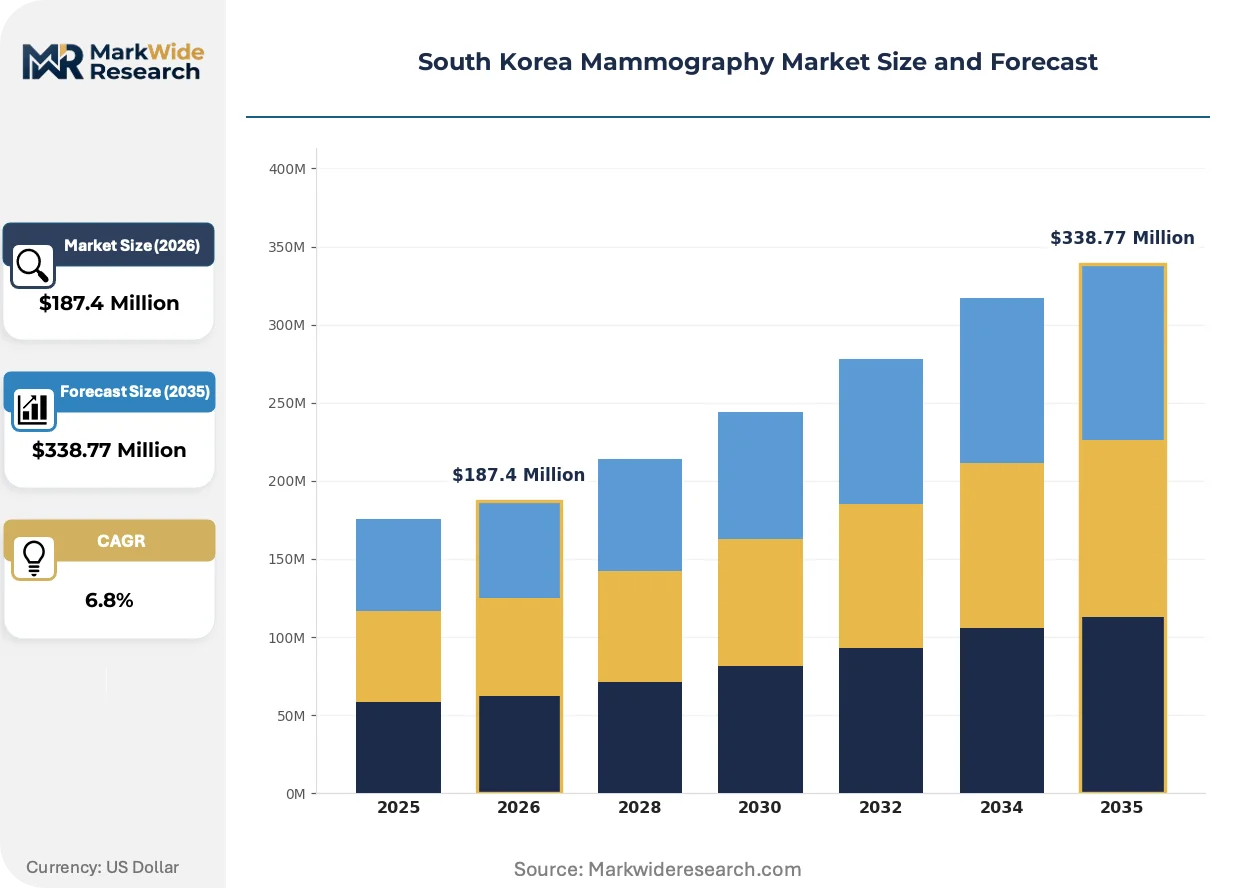
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Mammography, 3D Mammography, Contrast-Enhanced Mammography, Portable Mammography End User: Hospitals, Diagnostic Centers, Research Institutes, Breast Clinics Technology: Computed Radiography, Direct Radiography, Film-Screen Technology, Magnetic Resonance Imaging Application: Screening, Diagnostic Imaging, Research Studies, Follow-Up Procedures |
| Companies Covered | Fujifilm Holdings Corp., Canon Medical Systems Corp., Hologic Inc., Planmed Oy, Koninklijke Philips N.V., GE HealthCare, Samsung Medison, Lunit Inc., Siemens Healthineers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Mammography Market Strategic Shifts
Workflow virtualization is collapsing the traditional sequential chain of image acquisition, radiologist interpretation, and patient notification into parallel processing streams that compress diagnostic timelines.
Photon-counting detector technology is virtualizing the conventional indirect conversion architecture in digital mammography systems. Samsung Medison and domestic imaging consortia are piloting cadmium-zinc-telluride direct conversion panels at Seoul National University Hospital and Asan Medical Center. This virtualization is eliminating scintillator light loss and enabling spectral imaging protocols that separate tissue composition without additional radiation exposure.
MFDS software-as-medical-device classifications for AI detection algorithms are restructuring competitive boundaries between hardware manufacturers and independent algorithm developers. The regulation requires clinical validation studies at minimum three domestic sites for licensing, favoring partnerships with established hospital networks. Breast clinics in Daegu and Incheon are responding by consolidating procurement decisions around integrated hardware-software bundles rather than standalone device purchases.
After-sales service unbundling is fragmenting the traditional captive maintenance model dominated by manufacturer field engineers. Third-party imaging equipment service providers in Gyeonggi-do are capturing calibration and quality assurance contracts through specialized breast imaging technician certifications. This shift is most visible at mid-sized breast clinics in Suwon and Seongnam where capital constraints favor operational expenditure structures over bundled service agreements.
South Korea Mammography Market Segmentation
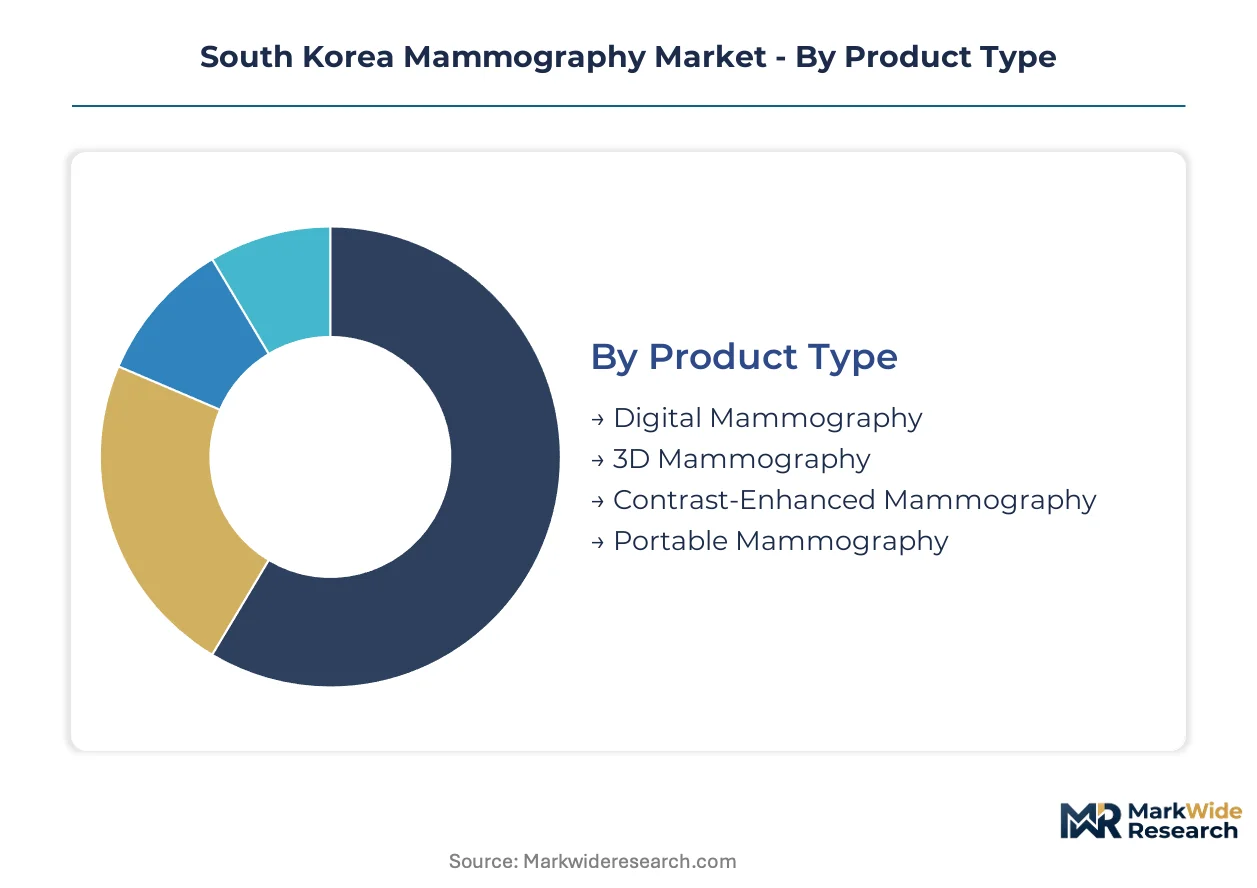
Mammography market segmentation in South Korea reflects the tension between centralized screening infrastructure in Seoul and distributed access requirements across provincial health systems. Product, end-user, technology, and application dimensions each capture distinct procurement patterns shaped by MFDS quality mandates and Ministry of Health and Welfare reimbursement schedules.
Product Type:
Cost tiers separate fixed-installation premium systems from mobile units serving infrastructure-constrained regions.
- Digital Mammography:Two-dimensional full-field digital systems with amorphous selenium or cesium iodide detectors form the installed base across KHIDI-certified screening centers. Demand concentrates at secondary hospitals in Daejeon and Gwangju where upgrade cycles lag Seoul by 24-36 months due to capital allocation priorities.
- 3D Mammography:Digital breast tomosynthesis systems acquire multiple projection angles for tomographic reconstruction, enabling dense breast tissue visualization without supplemental imaging. Seoul Capital Area tertiary hospitals anchor procurement volumes through centralized purchasing consortia that standardize on tomosynthesis protocols.
- Contrast-Enhanced Mammography:Dual-energy iodinated contrast protocols for lesion characterization in diagnostic workups.
- Portable Mammography:Battery-powered or generator-dependent units with lightweight tube heads for rural island communities in Jeollanam-do.
Digital Mammography holds installed capacity. 3D Mammography is rotating up the share rankings.
End User:
Customer type determines procurement scale, with tertiary institutions driving volume through multi-site standardization.
- Hospitals:Tertiary and secondary general hospitals operate centralized breast imaging departments with integrated biopsy capabilities. Asan Medical Center and Samsung Medical Center in Seoul anchor national referral networks that concentrate complex diagnostic volume and shape technology adoption curves.
- Diagnostic Centers:Dedicated imaging facilities without inpatient services focus on high-throughput screening workflows. Breast clinics in Busan and Daegu under KHIDI quality mandates are replacing aging analog systems with certified digital platforms.
- Research Institutes:Academic medical centers conducting clinical validation studies for MFDS software-as-medical-device licensing.
- Breast Clinics:Single-specialty outpatient facilities in Suwon and Seongnam favor operational expenditure structures over bundled service agreements.
Hospitals dominate absolute unit shipments. Breast Clinics are gaining procurement autonomy as third-party service providers fragment traditional manufacturer maintenance models.
Technology:
Maturity curves separate legacy analog architectures from direct conversion detector platforms gaining share in metropolitan installations.
- Computed Radiography:Photostimulable phosphor plate systems with intermediate digitization steps persist at provincial medical centers with constrained capital budgets.
- Direct Radiography:Amorphous silicon or selenium flat-panel detectors enable immediate digital acquisition without intermediate processing. Samsung Medison and domestic imaging consortia are piloting cadmium-zinc-telluride direct conversion panels at Seoul National University Hospital.
- Film-Screen Technology:Analog cassette-based systems remaining in rural health centers pending MFDS-mandated replacement timelines.
- Magnetic Resonance Imaging:Supplemental breast MRI for high-risk screening and implant evaluation protocols.
Direct Radiography is climbing the fastest among detector architectures. Film-Screen Technology retains residual installed base only in Jeollanam-do island communities.
Application:
Volume distribution across screening versus diagnostic workflows determines system utilization rates and reimbursement capture efficiency.
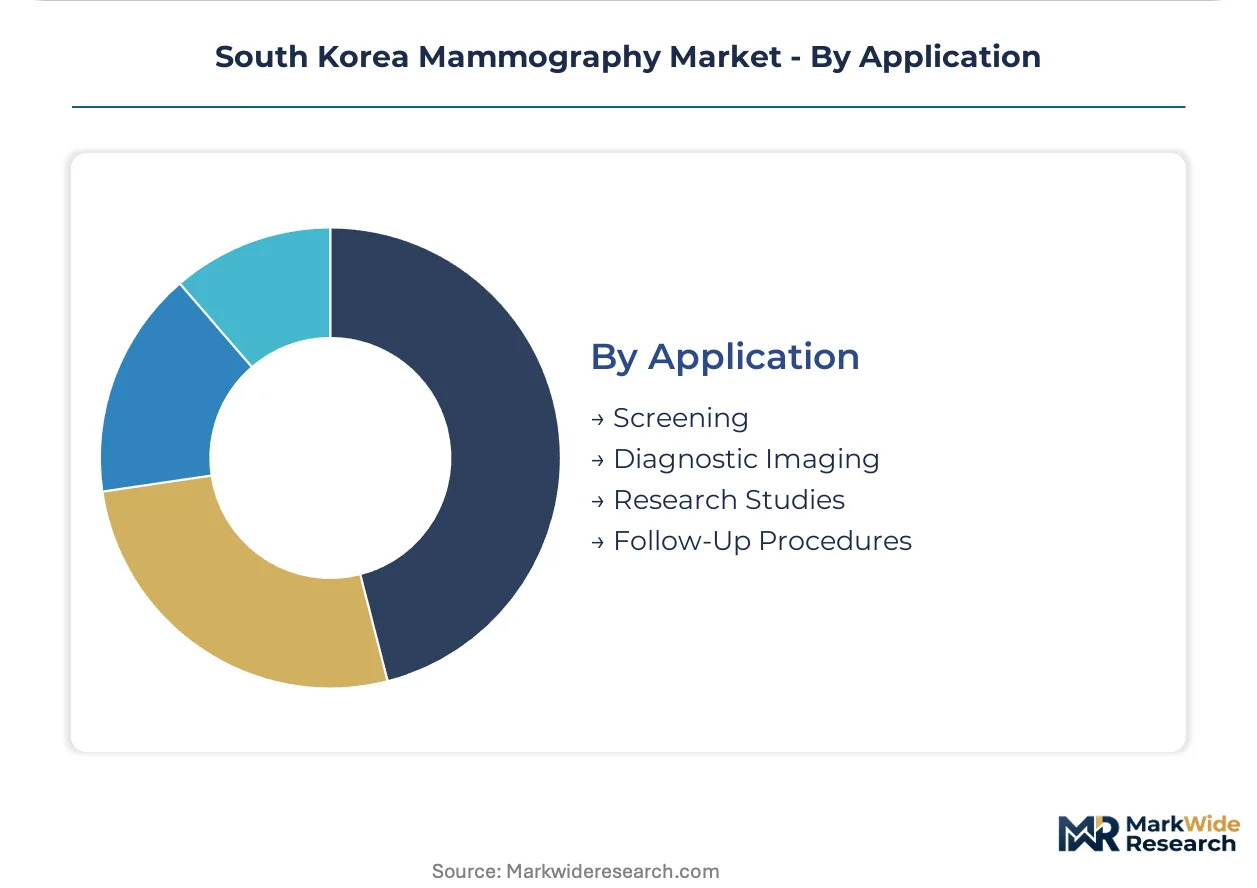
- Screening:Asymptomatic population imaging under National Cancer Screening Program protocols with biennial intervals for women 40-69. Ministry of Health and Welfare reimbursement schedules directly determine hospital upgrade cycles and technology substitution rates.
- Diagnostic Imaging:Symptomatic workups and callback evaluations from abnormal screening results. Tertiary hospitals in Seoul concentrate diagnostic volume through referral networks that require integrated biopsy and localization capabilities.
- Research Studies:Clinical validation cohorts for AI algorithm development and MFDS licensing requirements.
- Follow-Up Procedures:Surveillance imaging for prior cancer patients and high-risk cohorts with dense breast tissue notification requirements.
Screening captures the highest examination volume. Diagnostic Imaging commands premium reimbursement rates per procedure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for X-ray tube assemblies constrains domestic manufacturing scale, while metropolitan hospital networks concentrate procurement decisions in Seoul and Busan. The analysis examines five sub-regional clusters where screening infrastructure expansion and technology substitution are reshaping equipment deployment patterns.
Seoul Capital Area
Tertiary hospitals anchor national procurement volumes through centralized purchasing consortia that standardize on 3D mammography protocols. MFDS quality mandates compel simultaneous software validation timelines for AI-enabled reading workflows at Asan Medical Center and Samsung Medical Center. Photon-counting detector pilots at Seoul National University Hospital are validating cadmium-zinc-telluride direct conversion panels for spectral imaging protocols.
Busan-Ulsan
Breast clinics under KHIDI screening quality mandates are replacing aging analog systems with certified digital platforms to maintain program participation eligibility. The Ministry of Health and Welfare reimbursement schedules for national cancer screening programs determine hospital upgrade cycles across the metropolitan cluster. Diagnostic centers in Busan are consolidating procurement decisions around integrated hardware-software bundles rather than standalone device purchases.
Daegu-Gyeongbuk
Secondary metropolitan breast clinics exhibit underpenetrated 3D system density relative to screening-eligible population concentration. Third-party imaging equipment service providers in Gyeonggi-do are capturing calibration contracts through specialized breast imaging technician certifications. Breast clinics in Daegu are responding to MFDS software-as-medical-device classifications by favoring operational expenditure structures over bundled service agreements.
Daejeon-Sejong
Research institutes conducting clinical validation studies for MFDS licensing requirements concentrate validation cohorts at academic medical centers. Secondary hospitals in Daejeon lag Seoul upgrade cycles by 24-36 months due to capital allocation priorities. The Gwangju-Daejeon corridor expansion represents underpenetrated 3D system deployment opportunity relative to metropolitan screening demand.
Gwangju-Honam
Rural island communities in Jeollanam-do lack grid stability for high-voltage digital systems, restricting portable unit margins and examination throughput. Portable mammography units serve infrastructure-constrained regions where fixed installation remains economically unviable. Breast clinics in Gwangju are consolidating procurement decisions around integrated hardware-software bundles to streamline MFDS compliance obligations.
South Korea Mammography Market Competitive Environment
On the supply side, the industry is structured around three distinct competitive tiers: multinational imaging conglomerates with full diagnostic portfolios, specialized breast imaging manufacturers with focused technology platforms, and domestic equipment assemblers leveraging geographic proximity for service response optimization. Strategic archetypes include hardware-software integrators pursuing bundled contract structures, algorithm developers seeking software-as-medical-device licensing pathways, and third-party service providers unbundling traditional captive maintenance models. Dominant competitive moves encompass AI algorithm partnership formations with hospital networks and photon-counting detector technology licensing for spectral imaging differentiation.
Among multinational imaging conglomerates, Hologic Inc. and Fujifilm Holdings Corp. exemplify hardware-centric positioning anchored by dense breast tissue imaging protocols and endoscopy channel relationship extension respectively. Samsung Medison occupies a distinct archetype as a domestic manufacturer controlling service response times through captive manufacturing footprint. Lunit Inc. represents the algorithm developer archetype navigating MFDS software-as-medical-device classification requirements through clinical validation partnerships. These three companies illustrate the competitive boundary restructuring between hardware manufacturers and independent algorithm developers that MFDS regulations are accelerating.
| Leading Market Players |
|---|
| Fujifilm Holdings Corp. |
| Canon Medical Systems Corp. |
| Hologic Inc. |
| Planmed Oy |
| Koninklijke Philips N.V. |
| GE HealthCare |
| Samsung Medison |
| Lunit Inc. |
| Siemens Healthineers |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Japanese and German molybdenum target suppliers determines both three-tier pricing spreads across premium, standard, and economy system tiers and the elongated procurement timelines that Korean manufacturers face. This chokepoint compresses margins on mid-range digital systems while concentrating pricing power with photon-counting detector platforms at Seoul tertiary hospitals.
Pricing Analysis
Tertiary hospital procurement committees anchor pricing stratification across premium 3D tomosynthesis, standard full-field digital, and economy portable configurations. Price differentiation rests on MFDS certification tier and dense-breast imaging protocol capability rather than hardware alone. Cost compression in the standard tier intensifies because third-party service providers unbundle maintenance contracts and erode manufacturer captive revenue. Breast clinics in Suwon and Seongnam exhibit highest price sensitivity due to capital constraints, while Seoul Capital Area academic medical centers prioritize spectral imaging capability over acquisition cost.
Supply Chain Analysis
Export-control regimes on cadmium-zinc-telluride detector substrates limit technology transfer from US and European suppliers to Korean pilot programs. X-ray tube assemblies draw from Germany, Japan, and the United States, with rhodium and molybdenum target materials sourced from Russian and Chilean mining operations. Single-source vulnerability concentrates in high-voltage generator modules where Siemens Healthineers and GE HealthCare control proprietary designs. Distribution runs through manufacturer-direct field engineering networks for premium installations, while provincial diagnostic centers rely on Gyeonggi-based third-party imaging equipment servicers for calibration and quality assurance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where MFDS software-as-medical-device licensing creates regulatory entrenchment that protects validated algorithm-hospital partnerships from fast-follower disruption.
For Market Incumbents: Insulate installed base positions by deepening AI algorithm exclusivity at Asan Medical Center and Samsung Medical Center through co-development contracts that extend validation dataset access. Capture backward integration into photon-counting detector substrate supply through joint ventures with domestic semiconductor consortia to reduce exposure to German and Japanese component volatility. For New Entrants and Emerging Players: Build out tele-radiology infrastructure partnerships in the Gwangju-Daejeon corridor where 3D system penetration lags screening-eligible population density by measurable gaps. Target secondary breast clinics in Daegu with operational expenditure-based AI-as-a-service offerings that circumvent upfront capital barriers and MFDS hardware certification complexity. For Investors and Strategic Acquirers: The market sits at a technology-substitution phase that favors algorithm developers with cleared software-as-medical-device portfolios over pure hardware manufacturers. Long-term viability hinges on spectral imaging protocol adoption curves and AI detection standard-of-care evolution. Watch MFDS reimbursement schedule revisions for dense breast supplemental imaging as the inflection signal that would accelerate tomosynthesis procurement pull-through.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Software-as-Medical-Device Licensing | Creates 12-18 month validation barriers that protect first-mover algorithm developers from replication. |
| Photon-Counting Detector Pilot Expansion | Samsung Medison pilots at Seoul National University Hospital validate spectral imaging without dose penalty. |
| Third-Party Service Provider Certification | Gyeonggi-do technicians capture calibration contracts that fragment traditional manufacturer maintenance revenue. |
| Hub-and-Spoke Tele-Radiology Networks | Cloud-based image transmission centralizes specialist interpretation for Jeollanam-do island communities. |
| Dense Breast Reimbursement Schedule Advocacy | Ministry of Health and Welfare revisions would create procurement pull-through for tomosynthesis-capable systems. |
Study Parameters
A spread of perspectives from hospital purchasing committee members, biomedical engineers at tertiary institutions, GPO contracts managers, and third-party imaging equipment servicers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against MFDS device licensing databases, KHIDI screening quality protocol filings, and Ministry of Health and Welfare reimbursement schedule documentation. Bottom-up equipment shipment tracking across Seoul Capital Area procurement consortia was triangulated with top-down National Cancer Screening Program volume projections.
Demand-supply balance modeling anchored quantitative outputs across the projection horizon, with segmentation dimensions spanning product type, end-user tier, detector technology maturity, and application workflow. CAGRs were derived from installed base replacement cycles, technology substitution elasticity, and reimbursement-adjusted procurement timing. Industry-specific forecast inputs incorporated AI algorithm licensing approval timelines and photon-counting detector yield rates from pilot installations.
The forecast holds incumbent behavior within observed patterns; aggressive moves by multinational imaging conglomerates pursuing exclusive AI partnerships would shift outcomes. Material shifts in MFDS software validation timelines or Ministry of Health and Welfare dense breast imaging reimbursement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Contrast Media Market
Medical Imaging
Asia-Pacific Intraoperative Imaging Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Coils Market
Medical Imaging
Asia Pacific Nuclear Imaging Market
Medical Imaging
AI Surgical Video Intelligence System Market
Medical Imaging
Italy Digital X-Ray Market
Medical Imaging
North America Open System MRI Market
Medical Imaging
PSMA-PET Imaging Market
Medical Imaging
Non-Invasive & Minimally Invasive Medical Imaging and Visualization Systems Market
Medical Imaging
Digital Telepathology Market
Medical Imaging
Ultrasound Systems Market
Medical Imaging
US Magnetic Resonance Imaging Market
Medical Imaging
Wireless Ultrasound Scanner Market
Medical Imaging
3D Medical and Surgical Imaging Market
Medical Imaging
Nuclear Magnetic Resonance Spectroscopy Market
Medical Imaging
China Nuclear Imaging Market