
 Global Mobile C-Arm Market | 2026-2036
Global Mobile C-Arm Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile C-Arm Market Foresight
Germany is rewriting the competitive map for mobile C-Arm manufacturing as Siemens Healthineers sustains deep R&D investment in flat-panel detector technology. GE HealthCare Technologies dominates North American service networks through captive supply of imaging components. Ziehm Imaging specializes in compact system architectures that target budget-constrained surgical centers across emerging European markets.
A mobile C-Arm is a fluoroscopic imaging system mounted on a wheeled gantry, typically operating at 50-120 kVp with flat-panel or image intensifier detectors, designed to deliver real-time X-ray guidance during surgical procedures. The device enables intraoperative visualization of bone, contrast media, and instrument placement without repositioning the patient. Flat panel technology now anchors the highest-margin product tier, while pulsed fluorography variants are gaining share in trauma applications where dose reduction commands priority. Orthopedic surgery remains the largest application segment by installed base, though cardiovascular procedures represent the fastest-growing demand pool as hybrid operating rooms multiply.
The FDA's 510(k) framework governs device clearance in the United States, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence requirements for CE marking across European markets. Japan's PMDA maintains distinct quality management system audits that filter market access for non-domestic manufacturers. Stakeholders must weigh regulatory pathway complexity against reimbursement velocity when prioritizing geographic expansion sequences.
Market Dynamics
Flat-panel detector technology is compressing product lifecycles and forcing incumbent manufacturers to accelerate R&D cadence or cede premium tier positioning to specialized detector suppliers.
Growth Catalysts
- Hybrid OR expansion:Hospital construction of hybrid operating rooms in the United States, Germany, and China is pulling demand for high-resolution mobile fluoroscopy systems that integrate with surgical navigation platforms.
- MDR compliance timelines:The EU Medical Device Regulation's stricter clinical evidence requirements for CE marking is filtering out marginal competitors and consolidating procurement toward established vendors with robust quality management systems.
- Ambulatory surgical center proliferation:Orthopedic-focused ASCs across the American Midwest and Southern Germany are deploying compact C-Arm configurations to support same-day joint procedures outside traditional hospital infrastructure.
Market Restraints
- Flat-panel detector supply concentration:Production of high-performance amorphous silicon and CMOS flat-panel sensors concentrates among a handful of Japanese and Korean component suppliers, creating input bottlenecks during demand surges.
- Capital intensity barriers:Full-field digital mammography and interventional radiology systems compete for the same hospital capital budgets, forcing C-Arm vendors into extended financing arrangements that compress working capital cycles.
- Image intensifier obsolescence risk:Legacy image intensifier technology faces rapid depreciation as flat-panel price-performance curves improve, stranding installed bases in secondary markets with limited upgrade pathways.
Strategic Opportunities
- Indian hospital modernization:India's PLI scheme for medical device manufacturing and expanding private hospital networks in Mumbai, Delhi, and Bangalore create first-mover advantages for vendors establishing localized assembly and service infrastructure.
- Trauma and emergency medicine penetration:Pulsed fluorography variants with dose-optimized protocols are opening deployment in Level I trauma bays where radiation exposure constraints previously limited fluoroscopy utilization.
- Artificial intelligence integration:Real-time image enhancement algorithms and automated anatomical landmark recognition are converging with mobile C-Arm hardware to reduce operator training requirements and expand addressable user bases.
Industry Challenges
- Clinical engineering talent scarcity:Maintenance and calibration of flat-panel detector systems requires specialized biomedical engineering expertise that remains concentrated in major metropolitan hospital clusters, limiting rural and small-facility penetration.
- Legacy system integration friction:PACS connectivity and DICOM compliance variations across hospital IT environments force customized interface development that extends deployment timelines and strains technical support resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile C-Arm Market |
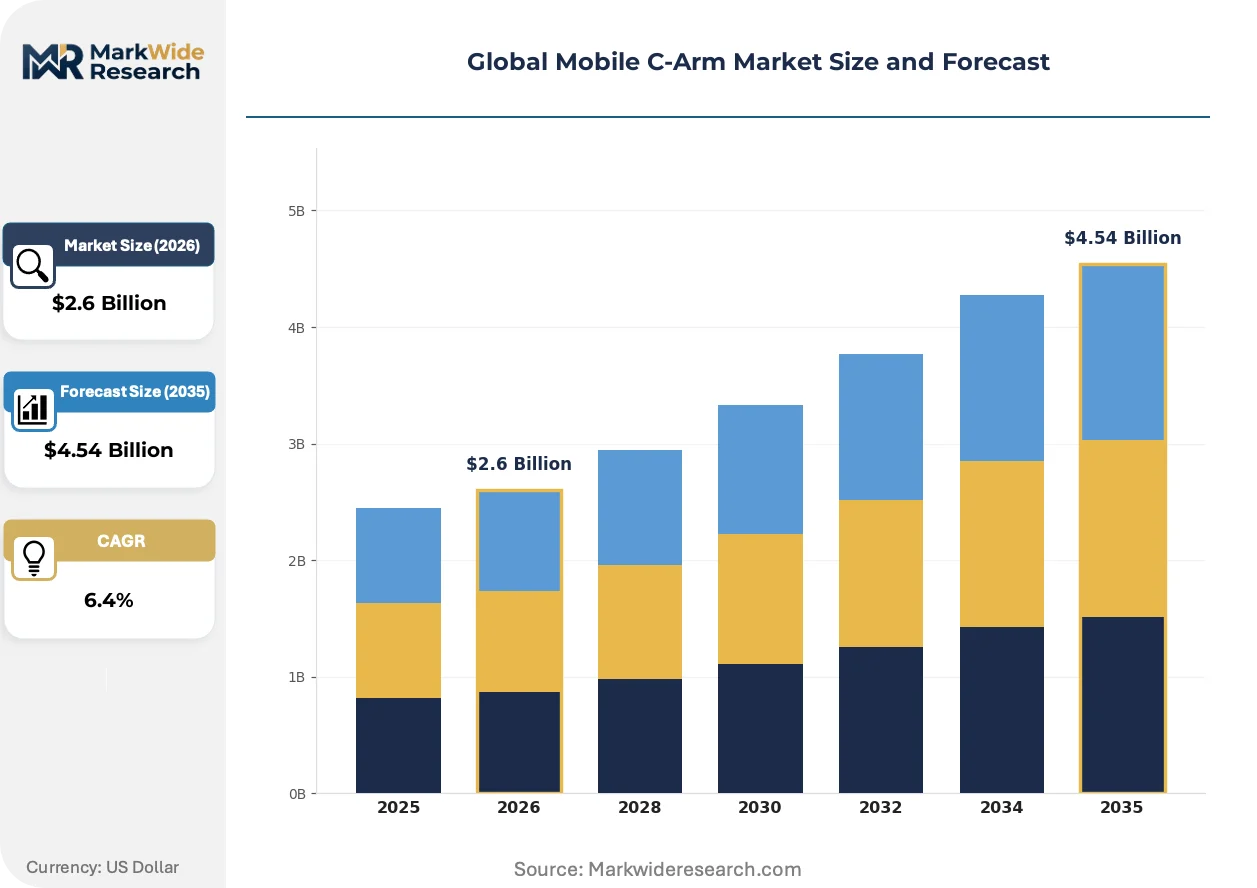
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $4.54 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
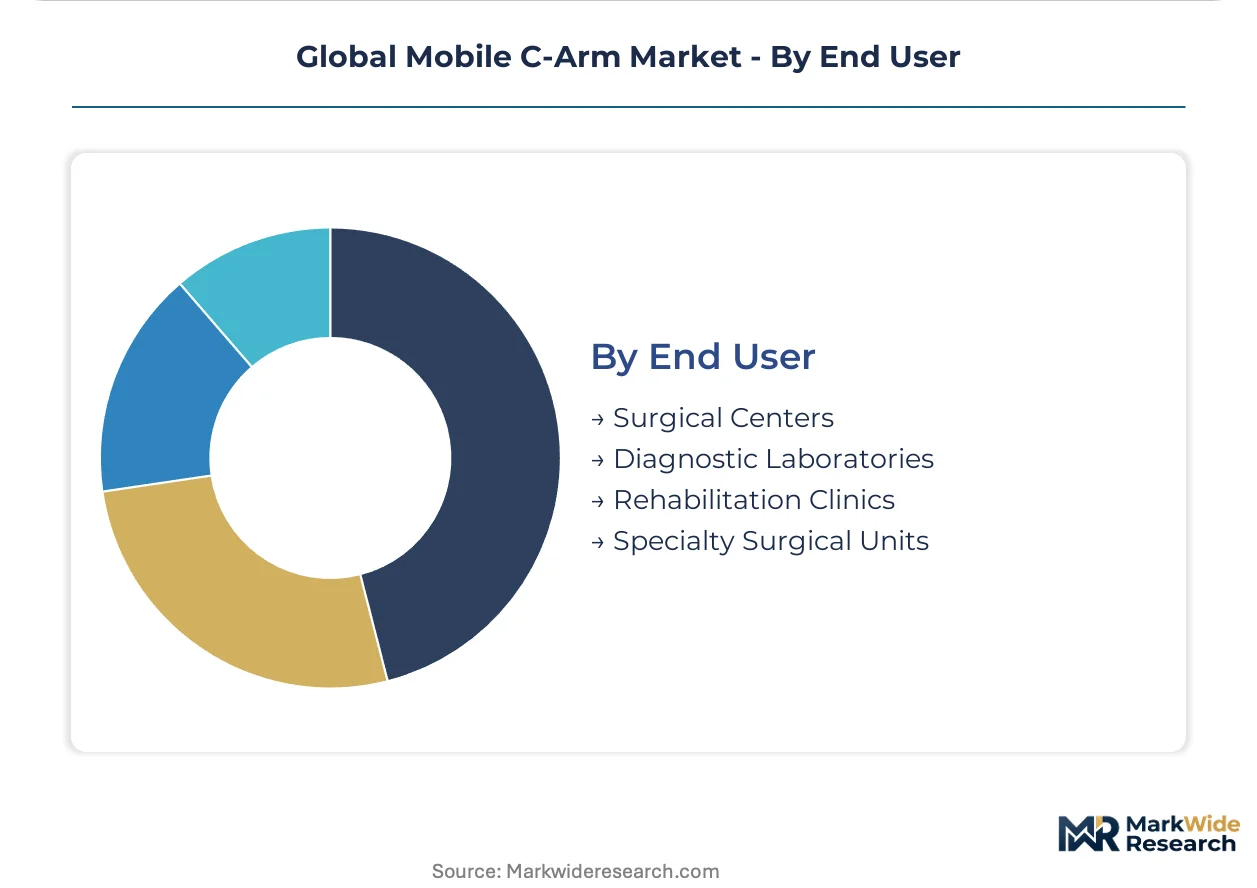
| Segmentation | Product Type: Compact, Standard, Mini, Flat Panel Technology: Digital Imaging, Fluoroscopy, 3D Imaging, Pulsed Fluoroscopy Application: Orthopedic Surgery, Trauma Surgery, Cardiovascular Procedures, Pain Management End User: Surgical Centers, Diagnostic Laboratories, Rehabilitation Clinics, Specialty Surgical Units |
| Companies Covered | GE HealthCare Technologies, Siemens Healthineers, Ziehm Imaging, Koninklijke Philips, Fujifilm Holdings Corporation, Hologic, Shimadzu Corporation, Genoray, Nanjing Perlove Medical Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile C-Arm Market Shifts & Advancements
Three distinct vectors are restructuring competitive advantage: detector technology migration, regulatory pathway redesign, and procurement model fragmentation that separates hardware ownership from utilization-based service economics.
CMOS-based flat-panel detectors with higher detective quantum efficiency and lower electronic noise profiles are hybridizing mobile C-Arm architectures previously segmented by price tier. Trauma centers and high-volume orthopedic hospitals in the American South and German industrial corridors are adopting these systems to reduce repeat exposures and extend surgical throughput. The technology is hybridizing premium and mid-market product categories, collapsing traditional segmentation schemes that separated flat-panel and image intensifier configurations.
The EU Medical Device Regulation's enhanced post-market surveillance requirements and clinical evaluation standards are extending CE marking timelines for new mobile C-Arm submissions. Manufacturers must now maintain systematic literature reviews and periodic safety update reports that increase regulatory affairs staffing by forty to sixty percent compared to previous Medical Device Directive obligations. European orthopedic and cardiovascular surgery device vendors are responding by front-loading clinical evidence generation and consolidating product portfolios to focus resources on highest-margin system configurations.
Hospital procurement departments are unbundling equipment acquisition from long-term service contracts, separating capital expenditure approval processes from operational technology management decisions. This fragmentation is compressing vendor switching costs and enabling third-party independent service organizations to capture maintenance revenue previously captive to original equipment manufacturers. The pattern is most pronounced in German university hospital systems and American integrated delivery networks where centralized supply chain functions have gained authority over clinical technology selection.
Global Mobile C-Arm Market Segmentation
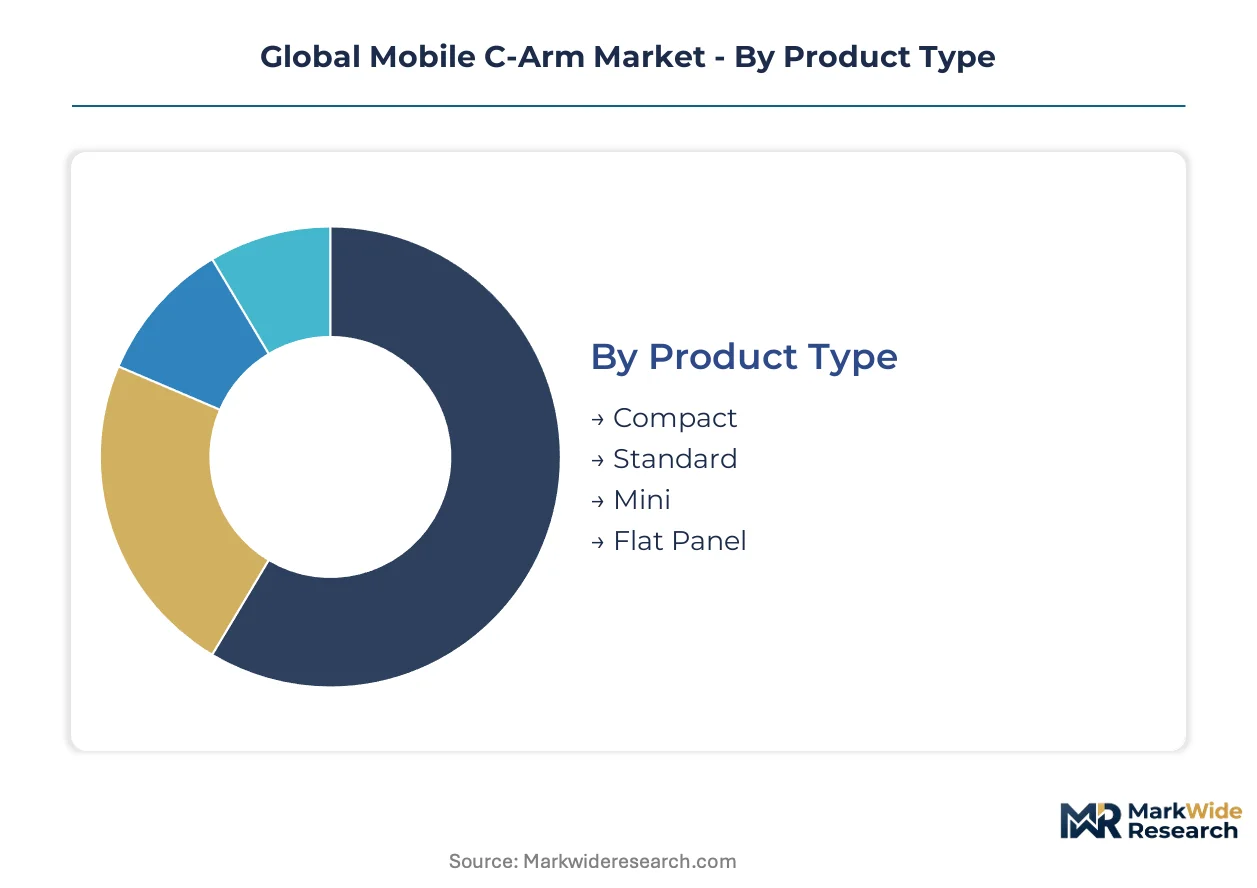
Mobile C-Arm procurement patterns diverge sharply across facility types and procedural volumes, with after-sales service intensity varying from quarterly calibration contracts for high-throughput trauma centers to break-fix arrangements for low-utilization rehabilitation clinics. Understanding these segment-specific service economics helps vendors align pricing architectures and field engineering deployment.
Product Type:
Service contract attach rates and spare parts logistics complexity scale directly with detector technology sophistication and mechanical articulation range.
- Flat Panel:Amorphous silicon and CMOS detector architectures deliver detective quantum efficiency above 70% with electronic noise floors below 300 electrons. German university hospitals and American Level I trauma centers concentrate procurement of these systems, driven by dose reduction mandates and surgical throughput targets. Flat panel holds the largest share; momentum sits with compact configurations.
- Compact:Reduced footprint designs with 55-75 cm source-to-image distances and motorized C-arm rotation under 90 kg total system weight. Ambulatory surgical centers in the American Midwest and Southern Germany deploy these for same-day orthopedic procedures where space constraints and capital budgets intersect.
- Standard:Full-size gantry systems with 100+ cm source-to-image distance and extended lateral rotation range serving high-volume cardiovascular hybrid operating rooms.
- Mini:Ultra-portable configurations under 50 kg targeting extremity imaging and podiatric surgery in satellite clinic networks.
Flat panel systems command premium service margins; compact variants are gaining share fastest among budget-constrained surgical centers.
Technology:
Regulatory clearance pathways and clinical evidence requirements fragment by imaging modality, with 3D reconstruction submissions facing extended FDA 510(k) review timelines compared to conventional fluoroscopy.
- Digital Imaging:Direct radiography capture with 14-bit grayscale depth and real-time DICOM transmission to PACS infrastructure. American integrated delivery networks prioritize these systems for enterprise-wide standardization and reduced training overhead.
- Fluoroscopy:Continuous X-ray beam operation at 15-30 frames per second for real-time instrument guidance during fracture reduction and hardware placement.
- 3D Imaging:Isocentric rotational acquisition with cone-beam CT reconstruction for intraoperative spinal navigation and complex arthroplasty verification.
- Pulsed Fluoroscopy:Intermittent beam exposure protocols reducing patient dose by 50-80% compared to continuous mode, penetrating Level I trauma bays where radiation safety committees previously restricted fluoroscopy utilization.
Digital imaging anchors installed base volume; pulsed fluoroscopy is climbing the fastest as dose monitoring protocols tighten across German and American hospital systems.
Application:
Procedure reimbursement rates and case volume volatility determine capital recovery timelines, with cardiovascular applications requiring longer depreciation schedules due to payer mix complexity.
- Orthopedic Surgery:Arthroplasty, fracture fixation, and spinal instrumentation procedures generating 60-80% of mobile C-Arm utilization hours in typical hospital deployments. German industrial corridor hospitals and American Sun Belt surgical centers concentrate demand for high-resolution systems supporting navigated implant placement.
- Trauma Surgery:Emergency department and operating room deployment for polytrauma assessment and urgent fracture stabilization.
- Cardiovascular Procedures:Electrophysiology mapping, pacemaker implantation, and structural heart interventions in hybrid operating rooms.
- Pain Management:Fluoroscopy-guided injections and radiofrequency ablation in outpatient interventional suites.
Orthopedic surgery retains dominant procedure volume; cardiovascular applications show steepest expansion trajectory as hybrid OR construction accelerates.
End User:
Procurement authority centralization versus clinical department autonomy shapes vendor relationship dynamics, with integrated delivery networks consolidating purchasing decisions while specialty surgical units retain equipment selection independence.
- Surgical Centers:Ambulatory facilities performing same-day joint replacement and spine procedures, prioritizing rapid room turnover and compact system footprints. Mumbai and Delhi private hospital networks are expanding mobile C-Arm deployment under India's PLI scheme for medical device manufacturing.
- Diagnostic Laboratories:Imaging-focused facilities requiring high-throughput systems with automated positioning and streamlined workflow protocols.
- Rehabilitation Clinics:Post-acute settings with intermittent utilization patterns and minimal on-site biomedical engineering support.
- Specialty Surgical Units:Cardiovascular and neurosurgical departments with procedure-specific imaging requirements and dedicated capital budgets.
Surgical centers represent the largest addressable user base; specialty surgical units concentrate premium system procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's 510(k) clearance pathway compresses time-to-market for manufacturers targeting the United States, while EU MDR obligations and Japan's PMDA audits fragment regulatory velocity across major demand centers. Hospital infrastructure modernization concentrates procurement authority in metropolitan clusters spanning three continents.
United States
Hybrid operating room construction accelerates demand for high-resolution fluoroscopy systems integrating with surgical navigation platforms. FDA's streamlined 510(k) digital radiography pathway reduces clearance timelines compared to European equivalents. Level I trauma centers across Texas Medical Center and American Sun Belt surgical networks deploy pulsed fluorography variants to satisfy radiation safety committee mandates.
Germany
EU Medical Device Regulation's enhanced clinical evidence requirements filter marginal competitors toward established vendors with robust quality management systems. Siemens Healthineers sustains deep R&D investment in flat-panel detector technology from its Forchheim operations. University hospital systems in Baden-Württemberg and Bavaria unbundle equipment acquisition from service contracts, compressing vendor switching costs.
China
Hospital infrastructure modernization pulls demand as private networks expand in Shanghai, Beijing, and Shenzhen. NMPA maintains distinct quality management system audits that filter market access for non-domestic manufacturers. Yangtze River Delta medical device clusters concentrate localized assembly investments targeting mid-market surgical center procurement.
India
PLI scheme for medical device manufacturing creates first-mover advantages for vendors establishing localized assembly infrastructure. CDSCO regulatory pathways require systematic quality management documentation extending registration timelines. Mumbai and Delhi private hospital networks expand mobile C-Arm deployment for same-day orthopedic procedures outside traditional hospital infrastructure.
Japan
PMDA quality management system audits maintain stringent technical barriers for imported imaging equipment. Domestic manufacturers concentrate flat-panel detector supply among specialized component suppliers in Osaka and Nagoya industrial corridors. Aging demographic pressures accelerate hybrid OR construction in Tokyo and Kansai metropolitan hospital networks.
Global Mobile C-Arm Market Competitive Landscape
Capability concentration sits with specialized detector technology developers; scale advantage sits with diversified imaging conglomerates commanding captive service networks. The vendor base organizes across three tiers: premium flat-panel specialists, mid-market compact system providers, and legacy image intensifier maintainers. Dominant competitive moves include strategic partnerships with surgical navigation platform vendors and backward integration into flat-panel detector supply chains.
Among diversified health technology conglomerates, GE HealthCare Technologies and Siemens Healthineers occupy positions anchoring premium-tier procurement in North American and European hospital systems. Ziehm Imaging exemplifies the compact system specialist archetype targeting budget-constrained ambulatory surgical centers across emerging European markets. Koninklijke Philips represents the hybrid imaging portfolio approach spanning diagnostic and interventional modalities.
| Leading Market Players |
|---|
| GE HealthCare Technologies |
| Siemens Healthineers |
| Ziehm Imaging |
| Koninklijke Philips |
| Fujifilm Holdings Corporation |
| Hologic |
| Shimadzu Corporation |
| Genoray |
| Nanjing Perlove Medical Equipment |
| Others |
Supply & Pricing Matrix
Osaka and Nagoya industrial corridors concentrate flat-panel detector fabrication capacity, with amorphous silicon and CMOS sensor output dictating downstream pricing power for mobile C-Arm manufacturers. Korean component suppliers in Gyeonggi Province add secondary capacity, yet their production allocation decisions ripple through tier-one vendor pricing within six-month procurement cycles.
Pricing Analysis
American Midwest surgical centers pay fifteen to twenty percent premiums over Mumbai private hospital networks for identical compact system configurations. Pricing stratifies across premium flat-panel, standard image-intensifier, and economy refurbished tiers, with detector technology grade and FDA 510(k) clearance status as primary differentiation drivers. Cost compression in mid-market segments is intensifying because Indian PLI scheme subsidies attract localized assembly investments. Ambulatory surgical centers in Southern Germany show least price sensitivity due to unbundled service contract procurement authority.
Supply Chain Analysis
Foxconn Medical and Jabil Healthcare hold contract manufacturing capacity for mobile C-Arm mechanical gantry assemblies across Shenzhen and Penang facilities. Production draws from Japanese and Korean flat-panel sensor supply, German precision motor components, and Chinese aluminum extrusion feedstock. Single-source vulnerability concentrates in CMOS detector wafer fabrication. Distribution runs through regional imaging equipment distributors with hospital GPO contract access in the United States and direct OEM sales teams in Germany and China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile C-Arm penetration sits at early-cycle expansion as hybrid operating room construction accelerates across American Sun Belt hospital networks and German university systems. Flat-panel detector cost curves and AI integration timelines will determine adoption velocity across mid-market surgical centers.
For Market Incumbents: Build captive service network moats by acquiring independent service organizations in Texas Medical Center and Baden-Württemberg hospital clusters. Siemens Healthineers and GE HealthCare Technologies must deepen backward integration into CMOS detector supply chains before Korean component suppliers extend downstream into finished system assembly. FDA 510(k) clearance velocity and MDR clinical evidence requirements filter marginal competitors; front-load regulatory affairs staffing to maintain clearance cadence. For New Entrants and Emerging Players: Establish a beachhead in Indian private hospital networks under PLI scheme localization requirements. Mumbai and Delhi surgical centers offer lowest competitive density among top-twenty metropolitan clusters. Compact system configurations for same-day orthopedic procedures present the most penetrable segment. Pursue CDSCO registration pathways with systematic quality management documentation to compress time-to-first-revenue versus European MDR timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among flat-panel detector specialists with hospital service contract attach rates above sixty percent. Long-term viability over the projection horizon favors vendors with hybrid OR navigation platform partnerships and AI image enhancement software pipelines. Acquisition targets should show detector technology differentiation and established GPO contract presence. Monitor NMPA registration approvals for non-domestic manufacturers as inflection signal for Chinese market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR clinical evidence requirements filter marginal competitors toward established vendors with robust quality management systems. |
| Hospital System Partnership | American integrated delivery networks and German university hospitals unbundle equipment acquisition from service contracts. |
| Software Companion Development | Real-time image enhancement algorithms reduce operator training requirements and expand addressable user bases. |
| Reimbursement Strategy | Cardiovascular procedure reimbursement complexity determines capital recovery timelines for hybrid OR system deployments. |
| Backward Integration | Captive flat-panel detector supply insulates margin compression from Japanese and Korean component supplier pricing power. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs. Biomedical engineering directors at Level I trauma centers, hospital purchasing committee members, GPO contracts managers, and flat-panel detector R&D leads provided operational perspective. Secondary validation drew from FDA 510(k) filings, EU MDR submission databases, NMPA registration records, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up surgical procedure volume estimates and top-down imaging equipment capital expenditure forecasts were triangulated.
Calibration anchored installed base depreciation schedules against replacement cycle assumptions across the analysis window. Segmentation dimensions modeled include detector technology tier, system footprint category, application specialty, and end-user facility type. CAGRs derived from procedure volume elasticity to hospital construction pipelines and reimbursement rate trajectories. Forecast inputs incorporated hybrid OR construction permits and PLI scheme subsidy disbursement velocity.
Stress conditions across flat-panel detector supply disruptions, MDR compliance timeline extensions, and trauma center radiation safety committee restrictions were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of NMPA registration approval rates and Indian private hospital network expansion announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Spirometers Market
Medical Devices
Pelvic Floor Electrical Stimulation Devices Market
Medical Devices
Disposable Lancets Market
Medical Devices
Europe Artificial Organs and Bionic Implants Market
Medical Devices
Veterinary Catheters Market
Medical Devices
Balloon Inflation Devices Market
Medical Devices
Global Amniocentesis Needle Market
Medical Devices
Ophthalmoscopes Market
Medical Devices
MRI Coils Market
Medical Devices
Implantable Pulse Generator Market
Medical Devices
Global Emerging Mental Health Devices and Platforms Market
Medical Devices
Global Spinal Cord Stimulation Devices Market
Medical Devices
Artificial Urinary Sphincters Market
Medical Devices
Veterinary Respiratory Ventilators Market
Medical Devices
Minimally Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Neonatal Hearing Screening Devices Market