
 Global Ultrasound Imaging Devices Market | 2026-2036
Global Ultrasound Imaging Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ultrasound Imaging Devices Market Foresight
Aftermarket service revenue is narrowing as manufacturers shift toward software-subscription and AI-diagnostic bundles. GE HealthCare leverages its installed base of cart-based systems to lock in recurring revenue through proprietary analytics platforms. Siemens Healthineers anchors its competitive stance with deep integration of clinical workflow software across European hospital networks.
Ultrasound imaging devices generate real-time anatomical visualizations through piezoelectric transducer arrays operating at frequencies between 2 and 18 megahertz, with beamforming algorithms processing reflected acoustic signals for diagnostic interpretation. Portable ultrasound dominates unit shipments across outpatient clinics and emergency departments where space constraints and mobility requirements override premium imaging specifications. Contrast-enhanced ultrasound and elastography command superior margins in oncology and hepatology applications where tissue characterization demands exceed conventional B-mode capabilities.
The FDA governs 510(k) clearance pathways for diagnostic ultrasound systems in the United States, while the EU MDR imposes stricter clinical evidence requirements for CE marking across European member states. Japan's PMDA maintains distinct technical standards for harmonic imaging and acoustic output limits that shape product localization strategies for Asia-Pacific entry. Stakeholders must monitor evolving AI diagnostic classifications as regulators in multiple jurisdictions determine whether machine-learning algorithms constitute standalone medical devices or accessory software.
Market Dynamics
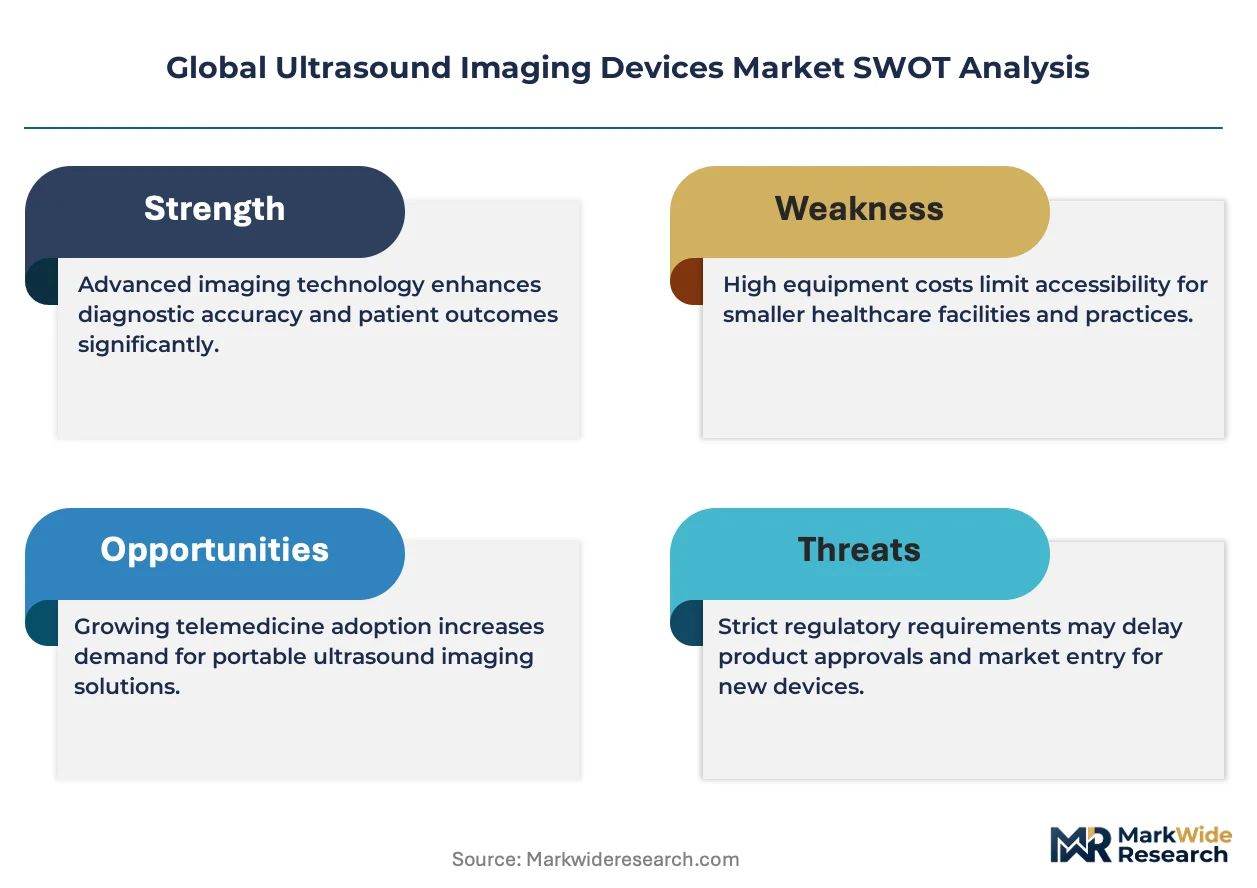
AI-assisted diagnostic workflows are compressing hardware replacement cycles while EU MDR clinical evidence requirements extend product development timelines, creating divergent pressures on capital allocation across the ultrasound imaging devices sector.
Growth Catalysts
- Point-of-care emergency medicine:Portable ultrasound systems are displacing traditional triage protocols in hospital emergency departments and pre-hospital ambulance services where rapid diagnostic confirmation reduces time-to-treatment.
- CE marking under EU MDR:Stricter clinical evidence requirements for Class IIa and IIb medical devices are accelerating consolidation toward manufacturers with robust quality management systems and post-market surveillance infrastructure.
- Handheld platform miniaturization:Semiconductor advances in application-specific integrated circuits are enabling smartphone-connected transducers that expand access to anatomical imaging in resource-limited outpatient settings.
Market Restraints
- Piezoelectric crystal supply concentration:High-purity lead zirconate titanate and single-crystal materials are concentrated among Japanese and Chinese specialty ceramics suppliers, exposing transducer manufacturers to input cost volatility and geopolitical trade friction.
- 510(k) predicate device pathway:FDA reliance on substantial equivalence to legally marketed devices creates regulatory friction for breakthrough ultrasound technologies that lack appropriate predicates, delaying market entry for novel beamforming architectures.
- CT and MRI substitution in oncology staging:Contrast-enhanced computed tomography and magnetic resonance imaging maintain superior spatial resolution for metastatic disease assessment, limiting ultrasound penetration in high-value cancer imaging workflows.
Strategic Opportunities
- Rural India diagnostic access:India's Ayushman Bharat health infrastructure expansion is creating procurement channels for low-cost handheld ultrasound systems in primary health centers where radiologist density remains critically low.
- Elastography-thermography convergence:Integration of shear wave elastography with thermal mapping is opening interventional oncology applications for real-time ablation monitoring that command premium pricing beyond conventional diagnostic use.
- Japan PMDA harmonization initiatives:Mutual recognition agreements between Japan's Pharmaceuticals and Medical Devices Agency and foreign regulators are reducing duplicate testing burdens for manufacturers seeking simultaneous Asia-Pacific market entry.
Industry Challenges
- Acoustic engineer talent scarcity:Specialized expertise in transducer array design and acoustic beamforming algorithm development is concentrated among aging cohorts in Germany, Japan, and the United States, constraining product innovation pipelines.
- Legacy PACS integration complexity:Hospital information systems built on DICOM standards from the 1990s require costly middleware development to accommodate AI-augmented ultrasound workflows with real-time decision support.
- EU MDR technical documentation burden:Clinical evaluation reports and post-market clinical follow-up protocols for CE marking are extending certification timelines by 18-24 months for mid-tier manufacturers without established notified body relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ultrasound Imaging Devices Market |
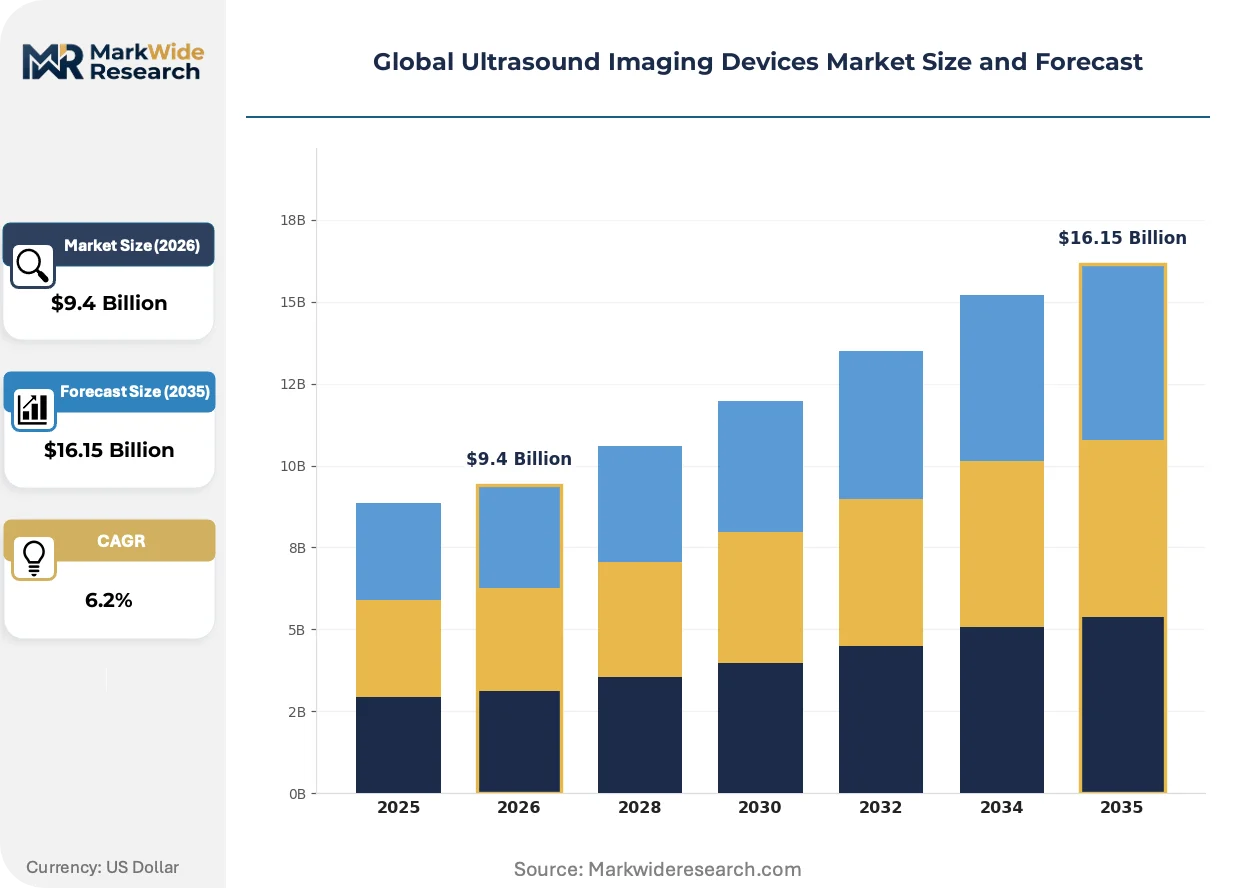
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.15 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Ultrasound, Cart-Based Ultrasound, Handheld Ultrasound, Laptop-Based Ultrasound, Others Technology: Doppler Ultrasound, 3D Ultrasound, 4D Ultrasound, Elastography, Contrast-Enhanced Ultrasound Application: Cardiology, Obstetrics and Gynecology, Urology, Musculoskeletal, Emergency Medicine, Pediatrics End User: Hospitals, Diagnostic Imaging Centers, Outpatient Clinics, Academic Research Institutes, Specialty Clinics |
| Companies Covered | GE HealthCare, Koninklijke Philips N.V., Siemens Healthineers, Canon Medical Systems Corporation, Mindray Medical International Limited, Samsung Healthcare, FUJIFILM Holdings Corporation, Esaote SpA, Hitachi Medical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ultrasound Imaging Devices Market Shifts & Advancements
Cloud-native ultrasound architectures are decoupling image acquisition from interpretation, enabling distributed diagnostic networks that challenge traditional radiology department hierarchies and equipment ownership models.
Shear wave elastography is digitizing tissue stiffness quantification for non-invasive liver fibrosis staging and thyroid nodule risk stratification. Gastroenterology and hepatology departments in tertiary hospitals across Germany, South Korea, and the United States are adopting these systems at replacement-cycle velocity. The technology is digitizing reimbursement pathways by generating quantifiable biomarkers that satisfy payer evidence requirements for pre-biopsy screening protocols.
EU MDR post-market surveillance mandates are compelling manufacturers to establish systematic vigilance systems for adverse event reporting and periodic safety updates. Industrial consequence includes mandatory clinical follow-up studies that increase regulatory compliance costs by 15-30% for legacy product portfolios. Class IIb ultrasound systems with AI diagnostic modules face the most severe documentation burdens, driving harmonization efforts between notified bodies in Germany, the Netherlands, and Ireland to reduce redundant audit cycles.
Subscription-based software licensing is displacing perpetual ownership models for advanced imaging analytics. Hospital procurement departments in the United States and United Kingdom are negotiating enterprise agreements that bundle AI diagnostic tools with hardware service contracts. This pattern is most visible in integrated delivery networks where chief financial officers prioritize operational expenditure predictability over capital asset depreciation schedules.
Global Ultrasound Imaging Devices Market Segmentation
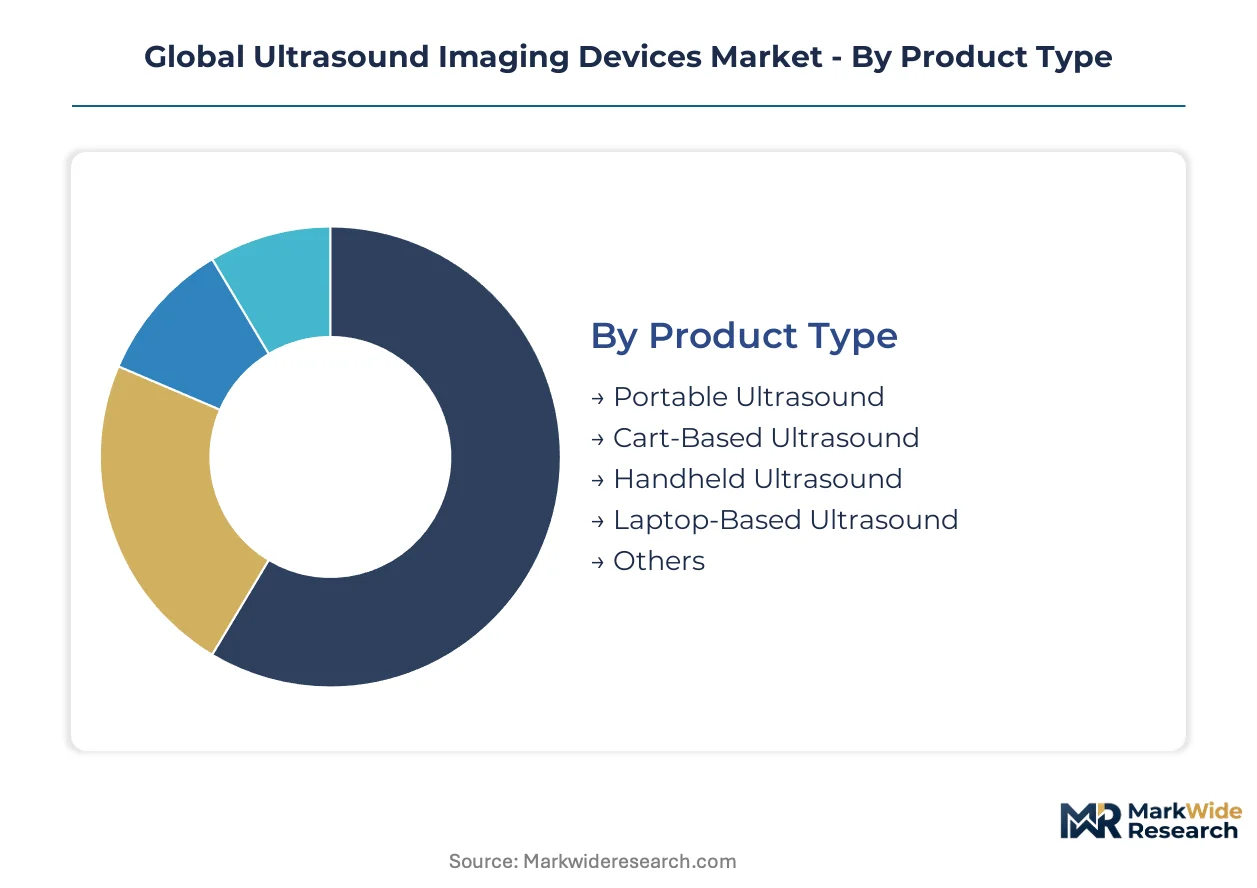
Ultrasound imaging devices fragment across four structural dimensions that determine procurement patterns, service revenue models, and regulatory pathways. Product type and technology choices lock in replacement cycles spanning 5-12 years, while application and end-user concentration shapes geographic demand distribution and margin structures.
Product Type:
Replacement velocity varies dramatically across form factors, with handheld platforms cycling fastest due to semiconductor obsolescence and battery degradation, while cart-based systems endure longest through modular upgrade paths.
- Portable Ultrasound:Compact units with integrated displays and battery packs operate at 3-7 MHz for abdominal and cardiac screening. Emergency departments across the United States and Germany are standardizing these for triage protocols where rapid deployment overrides image resolution. Battery replacement costs and transducer connector wear drive 4-6 year replacement cycles.
- Cart-Based Ultrasound:Full-featured platforms with 19-inch displays and multi-frequency transducer arrays (2-18 MHz) support advanced modalities including elastography and contrast imaging. Tertiary hospitals in China concentrate procurement for oncology and hepatology departments where AI-assisted diagnostic workflows justify premium capital expenditure. Modular software upgrades extend functional lifespans to 8-12 years.
- Handheld Ultrasound:Smartphone-connected transducers weighing under 400 grams transmit images via USB-C or wireless protocols. Primary health centers in rural India are expanding access where radiologist density remains critically low. Semiconductor advances in application-specific integrated circuits enable annual feature iterations that compress hardware cycles to 2-4 years.
- Laptop-Based Ultrasound:Notebook-integrated systems with foldable displays balance mobility against processing power for outpatient clinics with space constraints. Cardiology practices in Japan favor these for bedside echocardiography where Doppler resolution requirements exceed handheld capabilities.
- Others:Tablet-integrated configurations and veterinary-adapted platforms serve niche specifications including equine tendon imaging and point-of-care military medicine.
Cart-based systems dominate installed base across tertiary hospitals. Handheld ultrasound is where expansion concentrates for resource-limited outpatient settings.
Technology:
Margin structures stratify sharply across imaging modalities, with conventional Doppler commanding commodity pricing while elastography and contrast-enhanced platforms sustain premium positioning through proprietary algorithms and disposable agent dependencies.
- Doppler Ultrasound:Frequency-shift detection of moving blood cells enables velocity quantification and regurgitation assessment. Cardiology departments across Germany and the United States deploy these for routine valvular evaluation where reimbursement codes favor established modalities over experimental techniques.
- 3D Ultrasound:Volume acquisition through mechanical or matrix array transducers reconstructs multiplanar anatomical views. Obstetrics practices in South Korea and Brazil have adopted these for fetal facial anomaly detection where parental demand drives capital allocation despite limited outcome evidence.
- 4D Ultrasound:Real-time volumetric rendering adds temporal dimension to 3D acquisition for dynamic cardiac or fetal movement assessment. Private diagnostic chains in the United Arab Emirates market these for elective prenatal imaging where consumer payment capacity exceeds public reimbursement rates.
- Elastography:Shear wave propagation measurement quantifies tissue stiffness for liver fibrosis staging and thyroid nodule risk stratification. Gastroenterology departments in tertiary hospitals across Germany, South Korea, and the United States are adopting these at replacement-cycle velocity.
- Contrast-Enhanced Ultrasound:Microbubble agent injection improves vascular delineation for focal liver lesion characterization and endocardial border detection. Oncology workflows in France and Italy favor these for patients with renal contraindications to CT contrast agents.
Doppler ultrasound saturates installed base across primary care networks. Elastography is climbing the fastest as hepatology departments digitize reimbursement pathways through quantifiable biomarkers.
Application:
Clinical utility varies across specialties, with cardiology and emergency medicine driving highest utilization rates while pediatrics and urology concentrate procurement in academic medical centers with research funding.
- Cardiology:Echocardiography for chamber quantification, wall motion assessment, and hemodynamic estimation. Integrated delivery networks in the United States negotiate enterprise AI-bundled contracts where workflow integration justifies premium hardware expenditure.
- Obstetrics and Gynecology:Fetal biometry, placental localization, and adnexal mass characterization. Public hospital systems in Brazil and Mexico prioritize these for maternal health initiatives where ultrasound reduces referral bottlenecks to tertiary centers.
- Urology:Prostate volume measurement, bladder residual assessment, and renal calculus detection. Academic urology departments in the Netherlands and Sweden concentrate procurement for research protocols on contrast-enhanced microbubble agents.
- Musculoskeletal:Tendon integrity evaluation, joint effusion assessment, and guided injection procedures. Sports medicine clinics in Australia and Spain favor portable configurations for pitch-side or court-side immediate diagnosis.
- Emergency Medicine:FAST protocol for trauma, lung sliding assessment for pneumothorax, and deep vein thrombosis exclusion. Pre-hospital ambulance services in the United Kingdom are expanding deployment where rapid diagnostic confirmation reduces time-to-treatment.
- Pediatrics:Cranial imaging for intraventricular hemorrhage, hip dysplasia screening, and pyloric stenosis evaluation. Neonatal intensive care units in Canada and Switzerland concentrate procurement where radiation avoidance justifies premium transducer expenditure.
Cardiology commands the deepest installed base across hospital networks. Emergency medicine is gaining share fastest as point-of-care protocols displace traditional radiology department hierarchies.
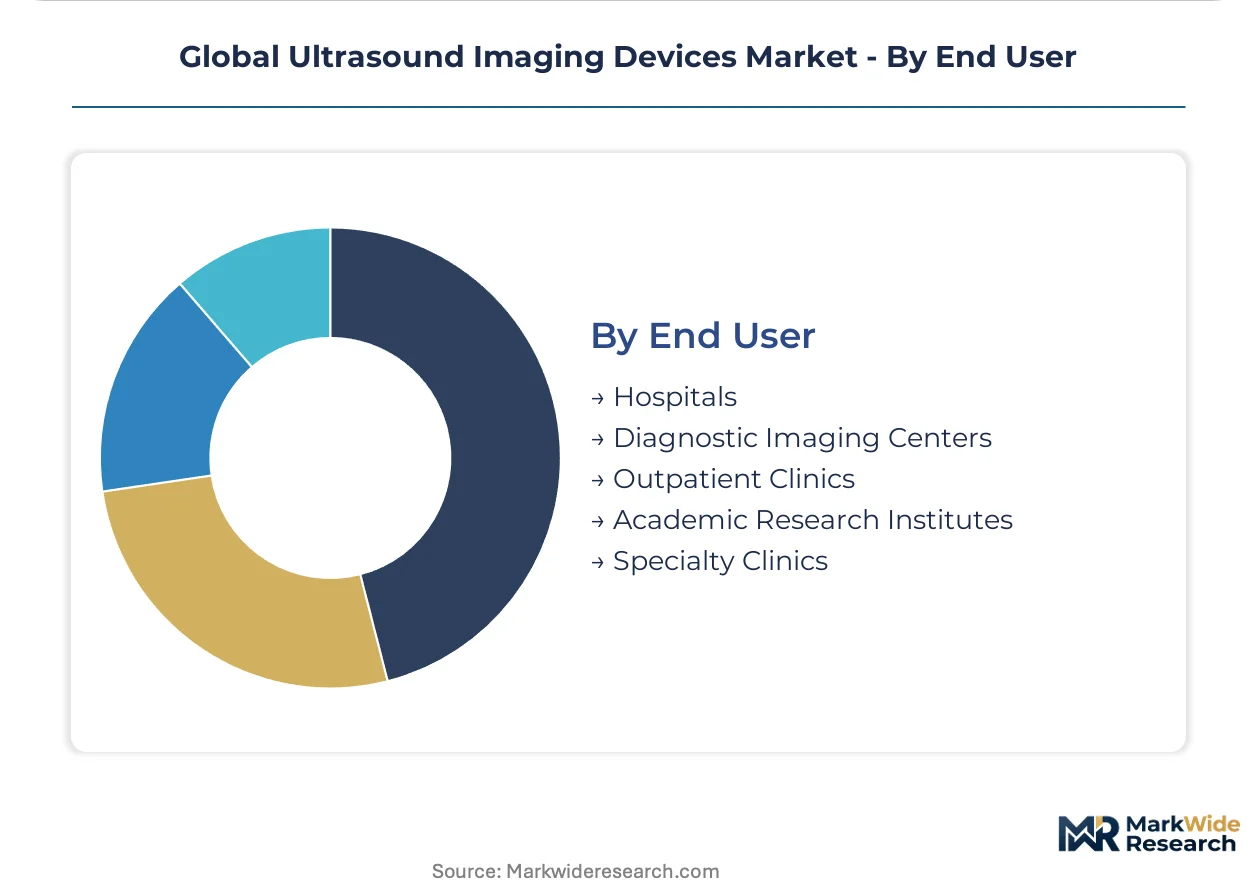
End User:
Procurement authority and budget sources fragment across institutional types, with hospitals consolidating vendor relationships through multi-year enterprise agreements while outpatient clinics favor leasing arrangements that convert capital expenditure to operational predictability.
- Hospitals:Multi-departmental procurement with centralized biomedical engineering oversight and PACS integration requirements. National health service trusts in the United Kingdom and Italy negotiate framework agreements that bundle hardware, software, and service across 5-7 year terms.
- Diagnostic Imaging Centers:High-throughput operations where patient volume justifies premium elastography and contrast-enhanced platforms. Independent chains in Germany and Poland compete on appointment availability where equipment utilization rates determine profitability.
- Outpatient Clinics:Space-constrained environments where portable and handheld configurations predominate. Primary care networks in rural India expand access through government procurement channels under Ayushman Bharat infrastructure programs.
- Academic Research Institutes:Protocol-driven procurement emphasizing experimental modalities and publication-grade image quality. University hospitals in Japan and South Korea concentrate funding for shear wave elastography validation studies.
- Specialty Clinics:Fertility centers, sports medicine practices, and veterinary hospitals with procedure-specific requirements. Fertility clinics in Spain and Denmark favor 3D/4D platforms for embryo transfer guidance where patient experience differentiation supports premium pricing.
Hospitals anchor installed base through enterprise procurement consolidation. Outpatient clinics represent the steepest expansion trajectory as handheld miniaturization decouples imaging capability from capital-intensive infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across procurement environments. Hospital systems in Germany and the United States absorb premium cart-based platforms with AI bundles, while primary health centers in rural India and outpatient clinics in Brazil prioritize sub-$5,000 handheld configurations where capital constraints override imaging specifications.
United States
Emergency medicine departments drive portable ultrasound deployment through FAST protocol standardization and pre-hospital ambulance integration. FDA 510(k) clearance pathways govern diagnostic system market entry, with predicate device requirements creating friction for novel beamforming architectures. The Cleveland Clinic and Mayo Clinic anchor tertiary adoption of elastography platforms for liver fibrosis staging protocols.
Germany
Tertiary hospital networks concentrate procurement of cart-based systems with integrated AI diagnostic workflows for oncology and hepatology departments. EU MDR CE marking requirements impose stricter clinical evidence burdens for Class IIb devices, accelerating consolidation toward manufacturers with established notified body relationships. The Rhine-Ruhr metropolitan region hosts Siemens Healthineers' European headquarters and radiology department standardization programs.
China
Domestic manufacturers capture share in primary health center procurement through government tender programs under the Healthy China 2030 initiative. NMPA regulatory harmonization with international standards reduces duplicate testing for multinational entrants. Shenzhen and Beijing concentrate R&D facilities for semiconductor-integrated transducer miniaturization targeting handheld platform cost reduction.
India
Ayushman Bharat health infrastructure expansion creates procurement channels for low-cost handheld systems in primary health centers where radiologist density remains critically low. CDSCO medical device regulations are tightening quality management system requirements for imported ultrasound platforms. Karnataka and Tamil Nadu host diagnostic imaging distribution networks serving South Asian outpatient clinic expansion.
Japan
Cardiology practices favor laptop-based configurations for bedside echocardiography where Doppler resolution requirements exceed handheld capabilities. PMDA maintains distinct technical standards for harmonic imaging and acoustic output limits that shape product localization strategies. Tokyo and Osaka metropolitan areas concentrate university hospital procurement for shear wave elastography validation studies.
Global Ultrasound Imaging Devices Market Competitive Landscape
Capability concentration sits with established imaging conglomerates possessing proprietary transducer manufacturing and AI algorithm development pipelines; scale advantage sits with diversified health technology conglomerates leveraging installed base lock-in for recurring software revenue. The vendor base stratifies across three tiers: integrated conglomerates with full modality portfolios, mid-scale specialists with regional distribution depth, and emerging entrants with semiconductor-native handheld architectures. Dominant competitive moves include enterprise software bundling to convert capital expenditure into operational predictability, and strategic partnerships with cloud infrastructure providers to decouple image acquisition from interpretation.
Within the integrated conglomerate tier, GE HealthCare and Siemens Healthineers exemplify archetypes leveraging installed base relationships to anchor recurring revenue through proprietary analytics platforms. Koninklijke Philips N.V. occupies a position bridging European hospital network integration with semiconductor-integrated handheld development. Among Asia-Pacific-based manufacturers, Mindray Medical International Limited represents the scale-driven archetype capturing government tender volumes through cost-optimized portable configurations.
| Leading Market Players |
|---|
| GE HealthCare |
| Koninklijke Philips N.V. |
| Siemens Healthineers |
| Canon Medical Systems Corporation |
| Mindray Medical International Limited |
| Samsung Healthcare |
| FUJIFILM Holdings Corporation |
| Esaote SpA |
| Hitachi Medical Corporation |
| Others |
Supply & Pricing Matrix
Single-source dependency on Japanese and Chinese specialty ceramics suppliers for high-purity lead zirconate titanate determines both tiered pricing spreads across transducer grades and supply chain vulnerability to geopolitical friction. Cart-based systems with premium elastography modules command hardware-plus-software bundles exceeding portable configurations by multiples, while handheld platforms compete on semiconductor cost curves.
Pricing Analysis
After-sales service contracts and AI diagnostic subscriptions drive lifetime value beyond hardware margins. Three-tier pricing structure across premium cart-based, standard portable, and economy handheld levels reflects transducer array complexity and software bundling intensity. Cost compression in the handheld tier stems from application-specific integrated circuit commoditization. Primary health centers in rural India exhibit highest price sensitivity, whereas integrated delivery networks in the United States absorb premium AI-bundled expenditure.
Supply Chain Analysis
Supplier-financing facilities from Japanese ceramics producers extend payment terms for transducer manufacturers managing working capital cycles. High-purity piezoelectric crystal supply concentrates in Japan, China, and Germany. Semiconductor fabrication for beamforming processors draws from Taiwan and South Korea. Single-source vulnerability in single-crystal material sourcing exposes manufacturers to input cost volatility. Distribution runs through authorized dealer networks serving hospital procurement committees and government tender channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ultrasound platform economics reaches an inflection as cloud-native architectures decouple image acquisition from interpretation, enabling distributed diagnostic networks that challenge traditional radiology department hierarchies and equipment ownership models.
For Market Incumbents: Entrench installed base relationships through proprietary AI analytics platforms that lock in recurring software revenue. Deepen backward integration into transducer array manufacturing to defend margin position against semiconductor-native handheld entrants. Prioritize CE marking readiness under EU MDR post-market surveillance mandates to accelerate consolidation toward quality-system leaders.
For New Entrants and Emerging Players: Rural India diagnostic access represents the most penetrable white-space target, where Ayushman Bharat infrastructure expansion and critically low radiologist density create procurement channels for sub-$5,000 handheld systems. Target smartphone-connected transducer form factors with annual feature iteration velocity. Pursue government tender relationships as the primary go-to-market angle.
For Investors and Strategic Acquirers: EU MDR clinical evidence requirements reshape the acquisition landscape toward manufacturers with established notified body relationships and post-market surveillance infrastructure. Long-term viability favors platform-economics plays with software-subscription revenue over hardware-dependent models. Monitor FDA AI diagnostic classification determinations as the critical inflection signal for regulatory risk recalibration.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements favor manufacturers with notified body relationships in Germany and the Netherlands. |
| Software Companion Development | AI diagnostic bundles convert capital expenditure into operational predictability for hospital procurement committees. |
| Hospital System Partnership | Enterprise agreements with integrated delivery networks anchor recurring revenue through proprietary analytics platforms. |
| Backward Integration | In-house transducer array production defends margin position against semiconductor-native handheld competitors. |
| Reimbursement Strategy | Quantifiable elastography biomarkers satisfy payer evidence requirements for pre-biopsy screening protocols. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists; and secondary validation through FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up unit shipment estimates triangulated against top-down revenue assessments across product type, technology, application, and end-user dimensions.
Forecast inputs encompassed replacement cycle velocity by form factor, AI diagnostic adoption curves, and regulatory timeline compression effects. Segmentation modeling spanned product type, technology modality, clinical application, and institutional end-user tier across the projection horizon. CAGRs derived from fitted growth curves applied to base-year estimates, with elasticity adjustments for price-tier penetration and geographic expansion patterns.
Practitioners should monitor EU MDR notified body capacity constraints, FDA AI classification determinations, and piezoelectric crystal supply disruptions for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Americas Interventional Radiology Market
Medical Imaging
Fluorescein Angiography Market
Medical Imaging
Asia Pacific Open System MRI Market
Medical Imaging
Remanufactured Medical Imaging Devices Market
Medical Imaging
Europe Fluoroscopy Market
Medical Imaging
Global Refurbished Medical Imaging Equipment Market
Medical Imaging
Global Magnetic Resonance Imaging System Market
Medical Imaging
Global Electroretinography Market
Medical Imaging
Australia Mammography Market
Medical Imaging
Molecular Imaging Market
Medical Imaging
Stationary Anode CT X-Ray Tube Market
Medical Imaging
Europe Medical Imaging Market
Medical Imaging
Preclinical Ultrasound Systems Market
Medical Imaging
Canada Nuclear Medicine Market
Medical Imaging
Spectroscopy Intravascular Imaging System Market
Medical Imaging
Industrial Radiography Equipment Market