
 US Digital Radiology Market | 2026-2036
US Digital Radiology Market Size, Share, and Industry Trends Forecast 2026-2036
US Digital Radiology Market Insights
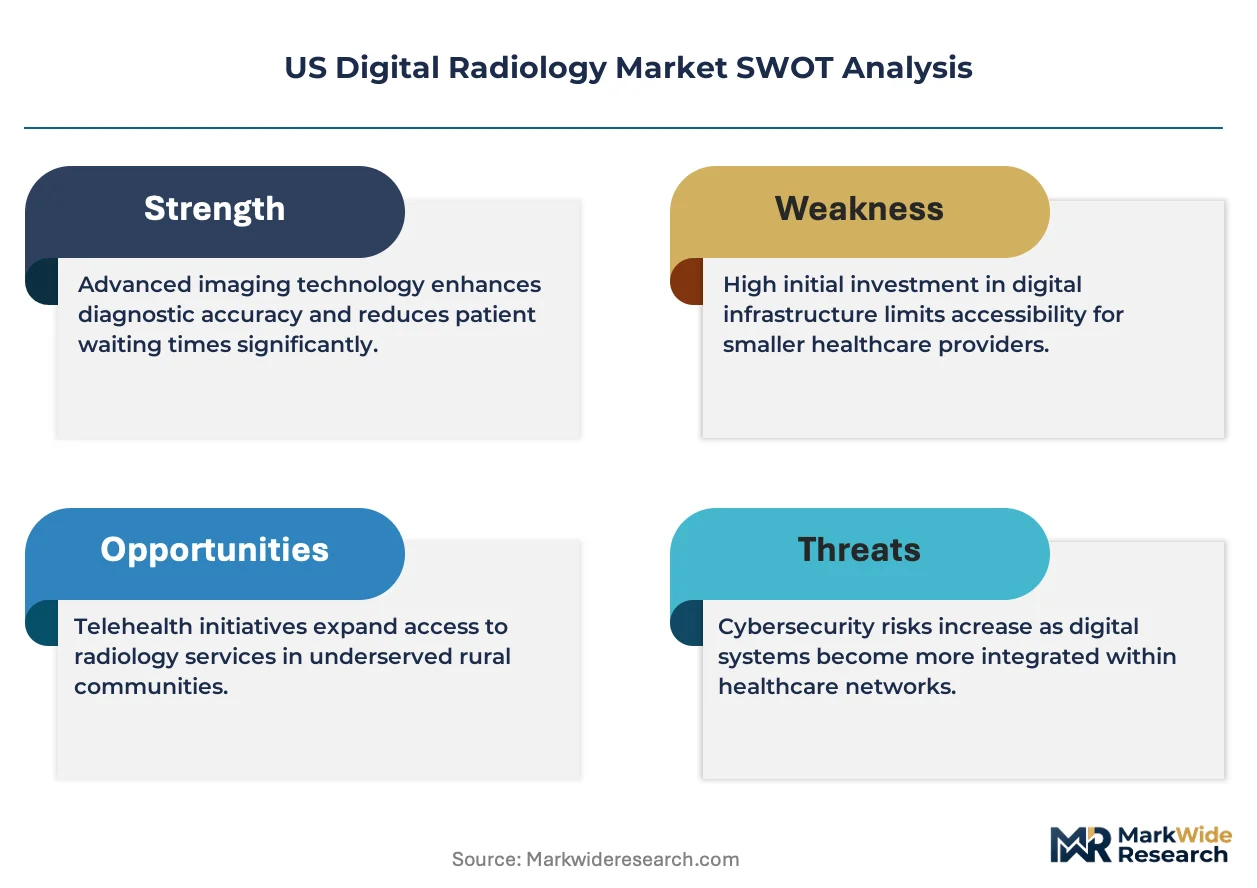
FDA's 510(k) premarket notification framework is consolidating the cost-of-entry calculus for digital radiology vendors seeking clearance for AI-integrated imaging platforms. GE Healthcare leverages its installed base of CT and MRI modalities to sustain service contract renewals across IDN networks. Siemens Healthineers anchors its North American position through captive manufacturing of photon-counting detector arrays. Fujifilm Holdings differentiates via end-to-end PACS integration that extends from image capture to cloud archiving.
Digital radiology encompasses the acquisition, processing, storage, and transmission of diagnostic medical images using detector arrays with spatial resolutions typically exceeding 2.5 line pairs per millimeter, replacing analog film-screen combinations with direct digital readout. Its primary purpose centers on enabling real-time image enhancement, dose reduction, and seamless integration with hospital information systems for clinical decision support. CT scanners command the largest revenue share among product types due to their indispensability in trauma and oncology staging protocols, while portable radiography represents the fastest-expanding technology segment as point-of-care imaging migrates into emergency departments and surgical suites. Direct digital radiography systems capture disproportionate margin pools through detector panel replacement cycles and software subscription attach rates.
FDA oversees device safety and effectiveness through 510(k) and De Novo pathways, while HIPAA mandates encryption and access controls for digital image transmission, collectively elevating compliance costs for new market entrants. The Centers for Medicare & Medicaid Services shapes demand through reimbursement codes that favor digital over analog modalities in outpatient settings. Stakeholders must monitor how FDA's evolving software-as-a-medical-device guidance recalibrates validation requirements for machine learning algorithms embedded in image reconstruction pipelines.
Market Dynamics
Hospital networks are accelerating replacement of analog film infrastructure with detector-based digital suites, while FDA's evolving software-as-a-medical-device guidance is recalibrating validation requirements for machine learning algorithms embedded in image reconstruction pipelines.
Growth Catalysts
- CMS Reimbursement Codes:The Centers for Medicare & Medicaid Services favors digital over analog modalities in outpatient settings, creating direct financial pull for imaging suite upgrades.
- Photon-Counting CT:Detector material advances enable spectral imaging with reduced radiation dose, accelerating protocol adoption in oncology staging.
- Integrated Delivery Networks:Consolidated hospital systems in the Northeast corridor command capital budgets that support enterprise-wide digital radiology deployments.
Market Restraints
- Detector Panel Supply Concentration:Manufacturing of amorphous selenium and cesium iodide arrays concentrates among a limited supplier base, creating input vulnerability.
- FDA 510(k) Validation Burden:The premarket notification framework demands substantial clinical evidence for AI-integrated platforms, extending clearance timelines.
- Legacy PACS Interoperability:Existing picture archiving systems from prior vendor generations resist seamless integration with cloud-native architectures.
Strategic Opportunities
- Surgical Suite Point-of-Care:Portable digital radiography systems penetrate operating rooms and emergency departments where fixed-room installations remain underdeployed.
- HIPAA-Compliant Cloud Archiving:Encryption and access control mandates create white space for vendors offering end-to-end PACS-to-cloud integration.
- AI-Enhanced Workflow:Machine learning algorithms for automated image prioritization and lesion detection converge with digital detector hardware.
Industry Challenges
- Radiological Informatics Talent:Health systems face scarcity of specialists capable of managing DICOM standard integration and AI validation pipelines.
- Capital Equipment Refresh Cycles:CT and MRI modalities require substantial capital commitment with extended depreciation schedules limiting upgrade frequency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Digital Radiology Market |
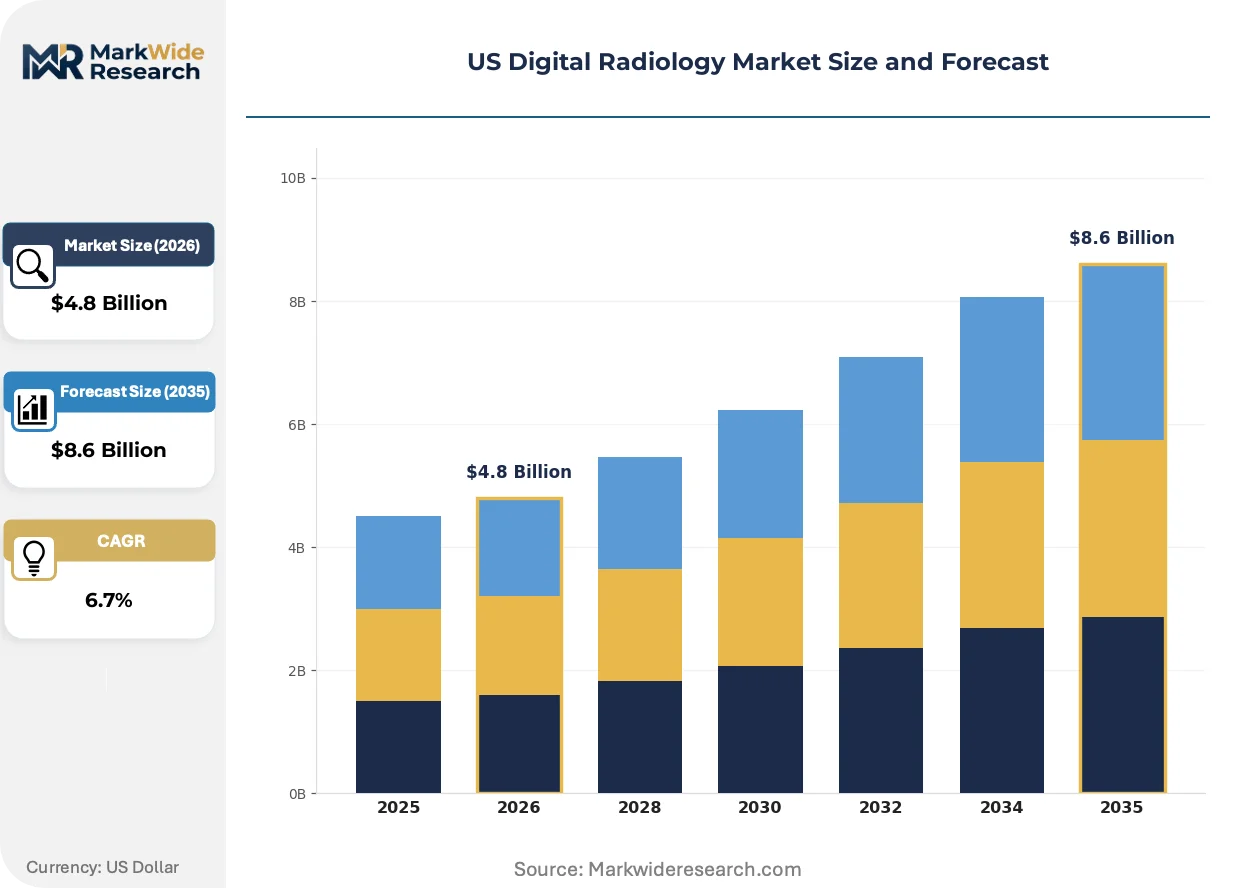
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray Systems, CT Scanners, MRI Systems, Ultrasound Systems End User: Hospitals, Diagnostic Imaging Centers, Research Institutions, Outpatient Clinics Technology: Computed Radiography, Direct Digital Radiography, Digital X-Ray, Portable Radiography Application: Oncology, Orthopedics, Cardiology, Emergency Medicine |
| Companies Covered | Philips Healthcare, Fujifilm Holdings, GE Healthcare, Agfa-Gevaert Group, Hologic, Carestream Health, Canon Medical Systems, Varex Imaging Corporation, Siemens Healthineers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Digital Radiology Market Trends and Innovations
Digital radiology is absorbing computational advances that compress reconstruction times and enable real-time decision support at the point of image acquisition.
Photon-counting detector technology is absorbing spectral imaging capabilities that differentiate tissue composition at the photon level. Major academic medical centers are deploying these systems for cardiac and pediatric protocols where dose reduction carries maximum clinical value. The technology is absorbing market share from conventional energy-integrating detectors by enabling material decomposition without dual-source hardware.
FDA's software-as-a-medical-device guidance is tightening validation requirements for machine learning algorithms used in diagnostic image analysis. The framework demands locked algorithm versions with predetermined change control plans, elevating documentation burdens for vendors. Radiology AI developers are responding by segregating training pipelines from deployed inference engines to satisfy predicate device comparisons.
Health system procurement is consolidating vendor relationships through enterprise imaging contracts that bundle hardware, software, and managed services. Integrated delivery networks are displacing departmental purchasing autonomy with centralized capital allocation committees. This concentration is most visible in the Northeast corridor where multi-hospital systems negotiate multi-year radiology suite standardization.
US Digital Radiology Market Segmentation
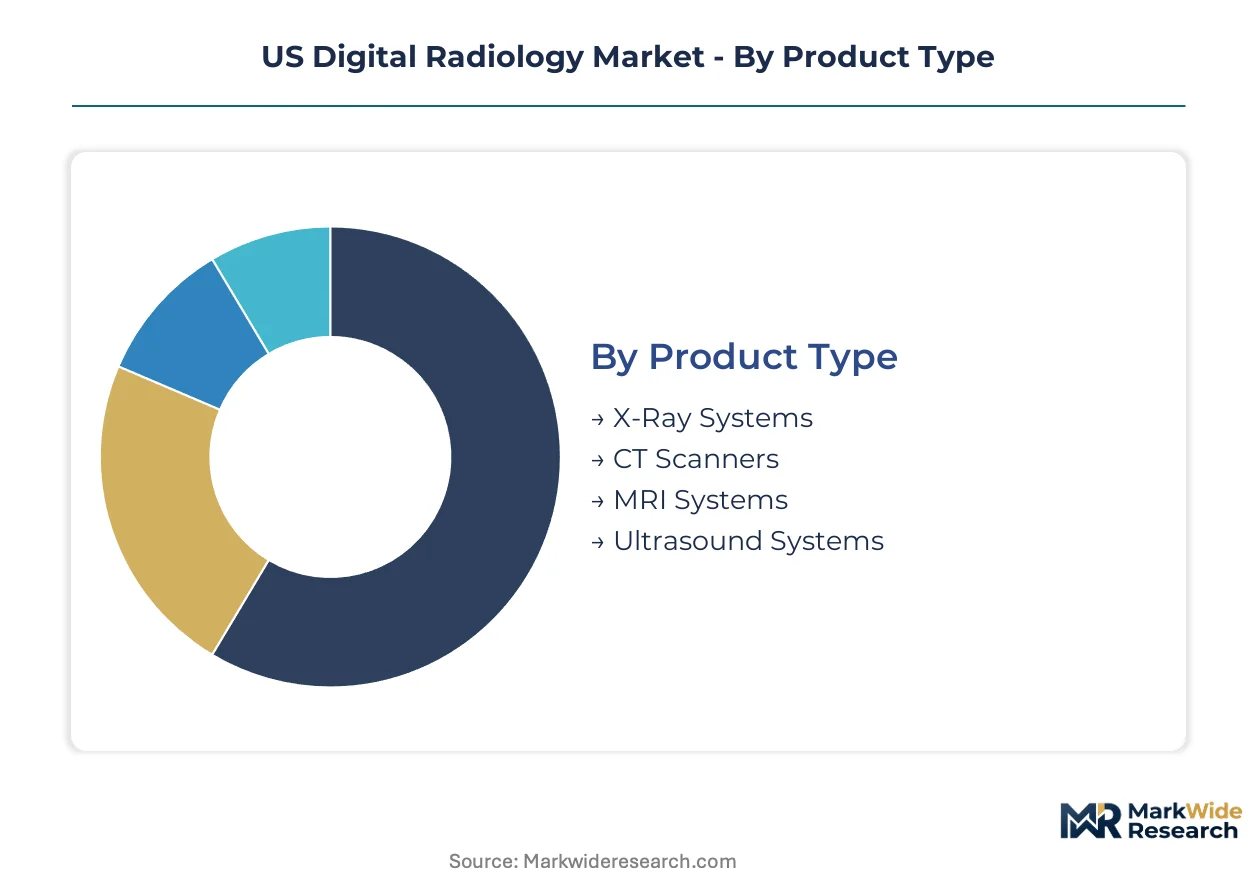
Procurement decisions in US digital radiology hinge on capital allocation authority, with integrated delivery networks standardizing vendor selection across hospital networks while outpatient clinics prioritize lease-based acquisition models for cost containment.
Product Type:
Capital intensity and reimbursement yield drive hospital procurement committees toward specific modality investments.
- CT Scanners:Energy-integrating and photon-counting detector arrays enable spectral imaging with tissue differentiation at the photon level. Demand concentrates in academic medical centers across the Northeast corridor where trauma and oncology staging protocols require high-throughput capabilities.
- X-Ray Systems:Fixed-room and portable configurations deploy amorphous selenium detector panels with spatial resolution exceeding 2.5 line pairs per millimeter. Hospital networks in California and Texas favor these systems for emergency department throughput and surgical suite integration.
- MRI Systems:Superconducting magnet arrays with 1.5T and 3T field strengths serve neurological and musculoskeletal protocols. Research institutions in Massachusetts and Maryland drive demand for advanced gradient coil configurations.
- Ultrasound Systems:Phased-array transducers with digital beamforming support point-of-care cardiac and abdominal imaging. Outpatient clinics in Florida and Arizona deploy these for cost-effective vascular access guidance.
Volume sits with CT Scanners; growth tilts toward X-Ray Systems.
End User:
Reimbursement structure and patient throughput determine technology deployment across care settings.
- Hospitals:Enterprise imaging contracts bundle hardware, software, and managed services across radiology, cardiology, and emergency departments. IDNs in New York, Pennsylvania, and Ohio command capital budgets supporting multi-year standardization programs.
- Diagnostic Imaging Centers:Freestanding facilities operate on fee-for-service models with CMS reimbursement codes favoring digital over analog modalities. Centers in Illinois and Georgia optimize throughput through extended operating hours and teleradiology partnerships.
- Research Institutions:NIH-funded academic medical centers deploy experimental detector configurations for clinical trial protocols. Massachusetts General Hospital and Johns Hopkins anchor demand for photon-counting CT validation studies.
- Outpatient Clinics:Limited capital budgets drive preference for refurbished systems and software-as-a-service PACS arrangements. Clinics in suburban Texas and North Carolina markets expand imaging capacity through vendor financing programs.
Procurement volume clusters with Hospitals; expansion tilts fastest toward Diagnostic Imaging Centers.
Technology:
Detector material and image processing architecture separate premium deployments from cost-optimized installations.
- Direct Digital Radiography:Amorphous silicon thin-film transistor arrays with cesium iodide scintillation layers capture images with immediate DICOM transmission. Hospital networks prioritize these systems for radiology department throughput and reduced retake rates.
- Portable Radiography:Battery-powered wireless detector panels enable imaging at bedside in intensive care units and operating rooms. Emergency departments in urban trauma centers across Chicago and Los Angeles drive adoption for rapid triage protocols.
- Computed Radiography:Photostimulable phosphor plates with laser scanning readout bridge analog-to-digital transition for budget-constrained facilities. Rural hospitals in Montana and Wyoming retain these systems for lower-examination-volume departments.
- Digital X-Ray:Integrated detector-panel and generator systems with automated exposure control serve high-volume screening programs. Federally qualified health centers deploy these for tuberculosis and lung cancer screening initiatives.
Deployment volume favors Direct Digital Radiography; Portable Radiography gains share fastest.
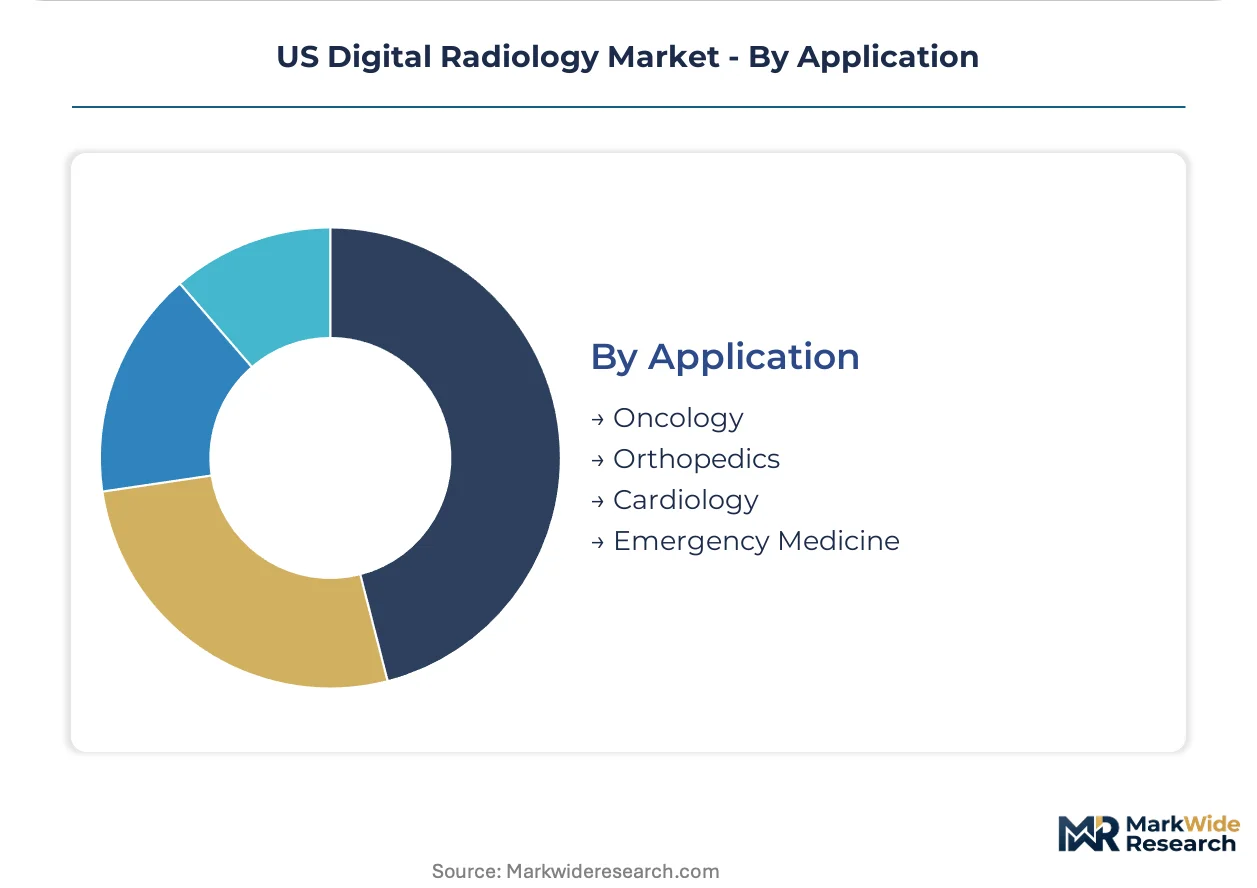
Application:
Clinical protocol requirements and reimbursement differentiation shape modality selection by specialty.
- Oncology:Spectral CT and multiparametric MRI support tumor characterization, staging, and treatment response monitoring. Comprehensive cancer centers in Houston and Seattle anchor demand for quantitative imaging biomarker validation.
- Emergency Medicine:Rapid-sequence CT and digital radiography protocols prioritize speed over resolution for trauma and stroke assessment. Level I trauma centers in Philadelphia and Atlanta require sub-minute image-to-diagnosis workflows.
- Orthopedics:Weight-bearing digital radiography and high-field MRI enable functional joint assessment and implant evaluation. Ambulatory surgery centers in Florida concentrate demand for post-operative hardware visualization.
- Cardiology:ECG-gated CT angiography and stress echocardiography support coronary artery and valvular disease evaluation. Cardiovascular service lines in Cleveland and Minneapolis drive replacement cycles for dual-source CT platforms.
Examination volume concentrates in Oncology; Emergency Medicine climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity zones and research corridor tax incentives are concentrating digital radiology deployment along the Northeast corridor and major metropolitan hospital networks. IDN consolidation in these zones accelerates enterprise-wide imaging standardization.
Northeast Corridor
Integrated delivery networks in New York, Pennsylvania, and Massachusetts command capital budgets supporting multi-year radiology suite deployments. FDA 510(k) clearance holders cluster near Boston and Philadelphia regulatory consulting hubs. Massachusetts General Hospital and Johns Hopkins anchor photon-counting CT validation studies in Baltimore and Boston research corridors.
Southeast
Florida ambulatory surgery centers drive demand for post-operative orthopedic imaging and cardiovascular service line expansion. CMS reimbursement codes favoring digital modalities pull investment into Georgia and North Carolina outpatient clinic networks. Duke University Health System and Emory Healthcare anchor research partnerships in Raleigh-Durham and Atlanta metropolitan clusters.
Midwest
Cleveland Clinic and University of Michigan Health System drive replacement cycles for dual-source CT platforms in Ohio and Michigan. HIPAA-compliant cloud archiving vendors target Chicago and Minneapolis health system procurement committees. Level I trauma centers in Detroit and Chicago require sub-minute image-to-diagnosis workflows for emergency medicine protocols.
Southwest
Texas Medical Center in Houston anchors demand for quantitative imaging biomarker validation in oncology staging. Federally qualified health centers in Dallas and San Antonio deploy digital X-ray systems for tuberculosis and lung cancer screening initiatives. MD Anderson Cancer Center drives spectral CT adoption for tumor characterization protocols.
Pacific Coast
Stanford University and UCLA Health System deploy experimental detector configurations for NIH-funded clinical trial protocols in California. Portable radiography penetrates Los Angeles urban trauma centers for rapid triage protocols. Seattle comprehensive cancer centers anchor demand for multiparametric MRI in treatment response monitoring.
US Digital Radiology Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across detector hardware, PACS software, and AI-integrated imaging platforms. The vendor base separates into three strategic tiers: integrated modality manufacturers with captive detector production, software-centric workflow specialists, and component suppliers feeding OEM assembly lines. M&A activity concentrates on AI algorithm developers and cloud-native PACS platforms, while strategic partnerships link hardware vendors with teleradiology service providers.
Within the diversified conglomerate tier, GE Healthcare and Siemens Healthineers occupy positions anchored by installed bases of CT and MRI modalities. Fujifilm Holdings exemplifies the end-to-end integration archetype spanning detector hardware through cloud archiving. Philips Healthcare sits within the premium-tier imaging systems segment alongside Canon Medical Systems.
| Leading Market Players |
|---|
| Philips Healthcare |
| Fujifilm Holdings |
| GE Healthcare |
| Agfa-Gevaert Group |
| Hologic |
| Carestream Health |
| Canon Medical Systems |
| Varex Imaging Corporation |
| Siemens Healthineers |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up diagnostic imaging specialists have consolidated detector panel manufacturing capacity, tightening supply discipline and supporting premium pricing for photon-counting CT arrays while squeezing margin pools for conventional digital radiography hardware.
Pricing Analysis
Short lead-time premiums dominate contract negotiations for amorphous selenium detector panels, with spot inventory discounts emerging for legacy cesium iodide arrays nearing technology obsolescence. Pricing stratifies across premium, standard, and economy tiers based on detector resolution specifications and FDA 510(k) clearance status, with certified spectral imaging platforms commanding substantial markups over uncertified equivalents. Cost compression in portable radiography intensifies as Chinese manufacturers expand wireless detector panel output. Outpatient clinics exhibit highest price sensitivity, while academic medical centers prioritize performance specifications over unit economics.
Supply Chain Analysis
Workforce availability constraints in Japan and Germany limit expansion of precision photon-counting detector fabrication, constraining output growth for next-generation CT platforms despite surging clinical demand. Manufacturing draws from amorphous silicon foundries in Taiwan, cesium iodide crystal growers in the United States, and rare-earth phosphor processors in China. Single-source vulnerability concentrates in photon-counting semiconductor substrates, where two Japanese suppliers anchor global capacity. Distribution runs through OEM direct sales teams for hospital networks and specialized imaging distributors for outpatient clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Detector panel foundry capacity serves as the binding constraint propping pricing power for spectral imaging hardware, with photon-counting semiconductor substrate output lagging installed base expansion across Northeast corridor IDNs.
For Market Incumbents: Anchor service contract renewal rates by embedding AI reconstruction software into CT and MRI modality leases, creating switching costs against emerging cloud-native PACS vendors. Pursue backward integration into amorphous selenium deposition equipment to secure detector panel input costs against Asian supplier pricing volatility. Prioritize FDA 510(k) clearance for locked-algorithm AI platforms ahead of evolving software-as-a-medical-device guidance. For New Entrants and Emerging Players: Begin with HIPAA-compliant cloud archiving for mid-sized diagnostic imaging centers in Texas and Florida, where legacy PACS interoperability failures create immediate replacement demand. Target outpatient orthopedic clinics in suburban North Carolina markets with vendor-financed portable radiography bundles. Lead with teleradiology partnership integrations that incumbent hardware vendors underinvest in. For Investors and Strategic Acquirers: Distressed-cycle entries favor AI algorithm developers with locked FDA predicates in Massachusetts regulatory consulting corridors, where validation documentation burdens have thinned competitive ranks. Long-term viability hinges on software attach rates outpacing hardware depreciation cycles. Monitor CMS reimbursement code expansions for spectral imaging as the inflection signal for photon-counting CT adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Locked-algorithm AI platforms satisfy predicate device comparisons for Massachusetts-based developers. |
| Hospital System Partnership | Enterprise imaging contracts with New York IDNs displace departmental purchasing autonomy. |
| Software Companion Development | Automated lesion detection algorithms attach to GE Healthcare CT installed bases. |
| Reimbursement Strategy | CMS outpatient codes favoring digital modalities pull Texas clinic network upgrades. |
| CE Marking Pathway | European regulatory alignment opens parallel revenue streams for photon-counting detector vendors. |
Research Methodology
Multi-period observation of hospital procurement cycle timing, FDA 510(k) clearance velocity, and CMS reimbursement code revisions anchored the trend analysis, supplemented by interviews with biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and radiology department directors. Secondary validation drew from FDA premarket notification databases, CMS Medicare physician fee schedules, hospital procurement contract registries, and medical device trade flow records. Bottom-up modality shipment estimates triangulated against top-down health system capital expenditure surveys.
Segment-weighting across product type, end user, technology, and application dimensions shaped volume and value outputs over the projection horizon. CAGRs were derived from installed base replacement cycle modeling and technology adoption curve fitting. Forecast inputs included photon-counting detector yield rates, AI algorithm validation pipeline durations, and IDN consolidation transaction velocity.
Underlying measurement precision varies by segment; CT scanner and MRI system revenue estimates carry tighter precision than portable radiography unit economics given fragmented outpatient clinic reporting. Forecasts reflect assumptions on FDA software guidance stability, detector material supply continuity, and reimbursement code parity maintenance. Material deviation in photon-counting substrate output or CMS spectral imaging coverage expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Radiation Dose Management Market
Medical Imaging
Dermatology Imaging Market
Medical Imaging
Global Stroke Post Processing Software Market
Medical Imaging
Brazil Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Diagnostic Imaging Market
Medical Imaging
Neurophotonics Market
Medical Imaging
Digital Radiology Market
Medical Imaging
AI Capsule Endoscopy Reading Platform Market
Medical Imaging
United Kingdom Mammography Market
Medical Imaging
Australia Computed Tomography Market
Medical Imaging
Dental Diagnostic Imaging Equipment Market
Medical Imaging
Perfusion Radiology Market
Medical Imaging
Global Vendor-Neutral Archive (VNA) and PACS Market
Medical Imaging
South America Portable X Ray Devices Market
Medical Imaging
AI-Assisted Digital Radiography Equipment Market
Medical Imaging
Brazil Digital Radiology Market