
 Digital X-Ray Imaging Market | 2026-2036
Digital X-Ray Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Digital X-Ray Imaging Market Insights
Equipment leasing and managed service contracts is fragmenting competitive dynamics in digital x-ray imaging by lowering capital barriers for mid-sized hospitals and independent diagnostic centers. Siemens Healthineers leverages its installed base of imaging hardware to bundle software subscriptions and maintenance agreements. GE Healthcare anchors its position through backward integration into detector manufacturing and proprietary image reconstruction algorithms. Philips Healthcare differentiates via workflow-integrated AI tools that reduce radiologist reading times in high-volume emergency settings.
Digital x-ray imaging encompasses the capture, processing, and display of radiographic images using solid-state detectors rather than analog film or phosphor plates, with spatial resolutions typically ranging from 100 to 400 micrometers and dynamic ranges exceeding 14 bits for soft-tissue visualization. The technology eliminates chemical processing, enables immediate image distribution through PACS networks, and supports dose-reduction protocols in pediatric and repeat-examination scenarios. Flat panel detectors now dominate new system deployments due to faster image acquisition cycles and improved low-dose performance compared to legacy computed radiography cassettes. Portable x-ray systems represent the fastest-expanding product category as hospitals prioritize bedside imaging for intensive care and emergency departments to reduce patient transport risks. AI imaging solutions command disproportionate attention from procurement committees despite higher upfront costs, because automated abnormality flagging addresses radiologist staffing constraints in high-throughput general radiography workflows.
FDA 510(k) clearance requirements govern detector safety and software diagnostic claims in the United States, while the EU Medical Device Regulation enforces stricter clinical evidence standards for AI-augmented x-ray systems sold across European member states. Japan's PMDA maintains distinct software validation protocols that create separate approval timelines for algorithm developers targeting hospital networks in Tokyo and Osaka. China's NMPA has accelerated review pathways for domestically manufactured digital radiography equipment under national healthcare infrastructure programs. Stakeholders must monitor divergent regulatory timelines for AI diagnostic software, because asynchronous approval schedules across major jurisdictions will determine which vendors can deploy unified product platforms versus maintaining region-specific codebases.
Market Dynamics
AI-assisted diagnostic software is compressing radiologist reading times while simultaneously raising capital requirements for hardware-software integration, forcing vendors to restructure service delivery models around predictive maintenance and outcome-based performance guarantees.
Growth Catalysts
- FDA 510(k) pathway acceleration:Streamlined software-as-medical-device clearances in the United States reduce time-to-market for algorithm developers deploying automated abnormality detection in emergency radiography workflows.
- Bedside imaging demand:Intensive care units and emergency departments across Germany and China are prioritizing portable x-ray systems to eliminate patient transport risks and accelerate clinical decision cycles.
- Flat panel detector performance:Solid-state capture technology with sub-400 micrometer spatial resolution and 14-bit dynamic range enables dose-reduction protocols in pediatric repeat-examination scenarios.
Market Restraints
- Detector manufacturing concentration:Backward integration into amorphous silicon and cesium iodide scintillator production limits supplier diversity, with fabrication capacity concentrated among integrated systems manufacturers.
- EU MDR clinical evidence requirements:Stricter validation standards for AI-augmented x-ray systems sold across European member states extend approval timelines and increase regulatory compliance costs for algorithm developers.
- Computed radiography legacy installed base:Phosphor plate systems in budget-constrained outpatient facilities create substitution friction despite superior flat panel acquisition speed and low-dose performance.
Strategic Opportunities
- Rural hospital networks in India:Underpenetrated diagnostic infrastructure and government health scheme expansion create whitespace for leasing-based managed service contracts with remote AI interpretation support.
- PACS-integrated workflow AI:Convergence of picture archiving systems with real-time abnormality flagging enables radiologist staffing optimization in high-throughput general radiography departments.
- Japan PMDA software validation pathway:Distinct approval protocols for algorithm developers targeting Tokyo and Osaka hospital networks reward early regulatory engagement with accelerated market access.
Industry Challenges
- Radiologist workforce constraints:Specialized training requirements for AI-augmented image interpretation outpace medical education pipeline output in high-volume screening programs.
- Legacy system integration complexity:DICOM conformance variations between installed hardware generations and new AI software platforms create deployment friction requiring customized interface engineering.
- Asynchronous multi-jurisdiction approvals:Divergent FDA, EMA, PMDA, and NMPA timelines for diagnostic algorithms force vendors to maintain region-specific codebases rather than unified product platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital X-Ray Imaging Market |
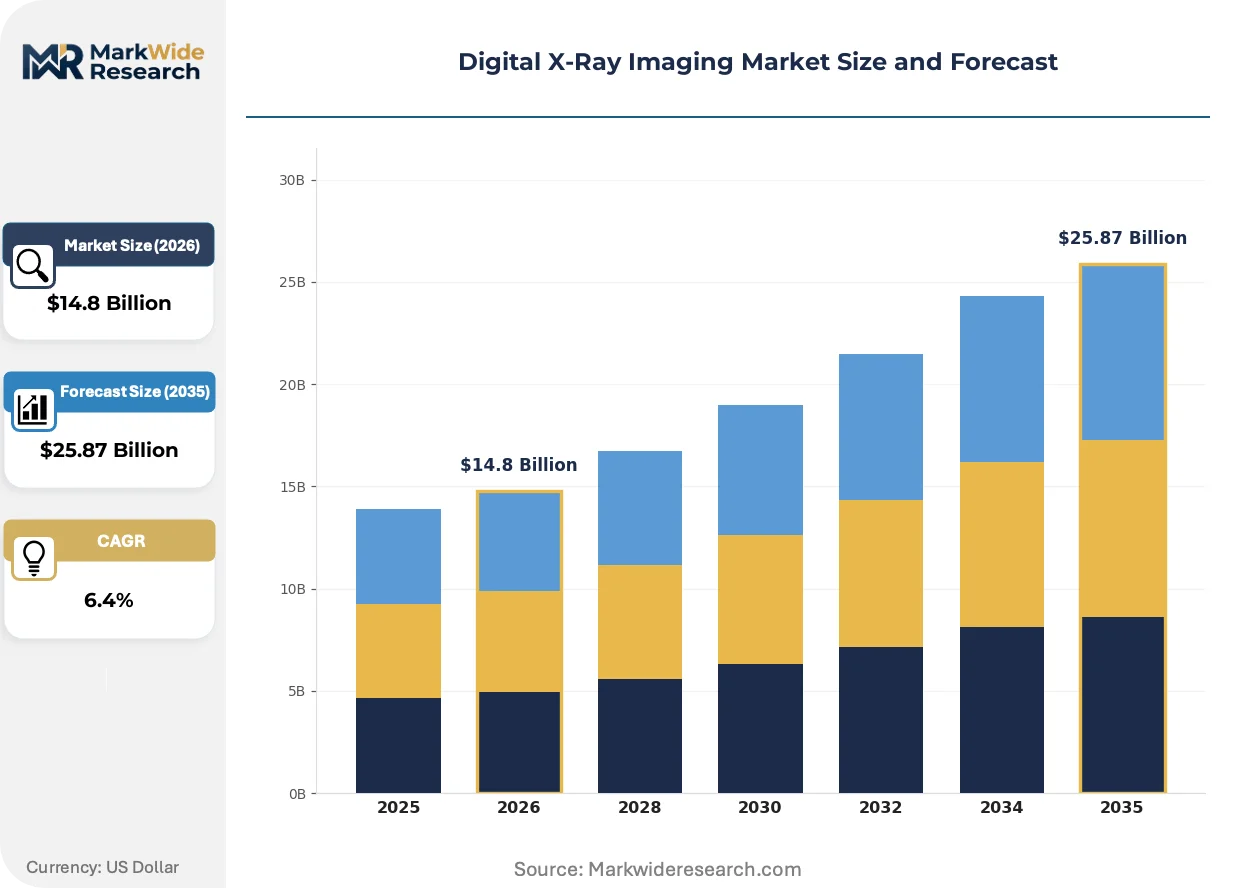
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Panel Detectors, Computed Radiography, Digital Radiography Systems, Portable X-Ray Systems Application: General Radiography, Dental Imaging, Mammography, Chest Imaging Technology: Imaging Software, Detectors, AI Imaging Solutions, Cloud-Based Systems End User: Hospitals, Diagnostic Imaging Centers, Clinics, Research Institutions |
| Companies Covered | Siemens Healthineers, GE Healthcare, Philips Healthcare, Fujifilm Holdings Corporation, Canon Medical Systems Corporation, Carestream Health, Shimadzu Corporation, Agfa-Gevaert Group, Konica Minolta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital X-Ray Imaging Market Trends and Innovations
Workflow automation and detector material science are converging to redefine performance benchmarks in diagnostic radiography, with software-defined imaging capabilities now matching hardware specifications as primary procurement criteria.
Dual-energy subtraction acquisition is hybridizing conventional projection radiography with tissue-specific material decomposition. Trauma centers and pulmonary clinics in the United States are adopting these systems to eliminate follow-up CT examinations for suspected nodule characterization. The technology is hybridizing clinical pathways by collapsing multi-modality diagnostic sequences into single-examination protocols.
China's NMPA has accelerated review pathways for domestically manufactured digital radiography equipment under national healthcare infrastructure programs. Domestic detector fabrication and image reconstruction algorithm development now receive priority regulatory attention. Equipment vendors targeting hospital procurement tenders in Beijing and Shanghai are restructuring supply chains to qualify for expedited clearance benefits.
Service contract unbundling is separating hardware maintenance from software subscription renewals in procurement negotiations. Independent diagnostic centers in Germany are negotiating standalone AI licensing agreements rather than bundled managed service packages. This pattern is most visible in outpatient imaging networks where capital lease structures predominate over direct equipment purchase.
Digital X-Ray Imaging Market Segmentation
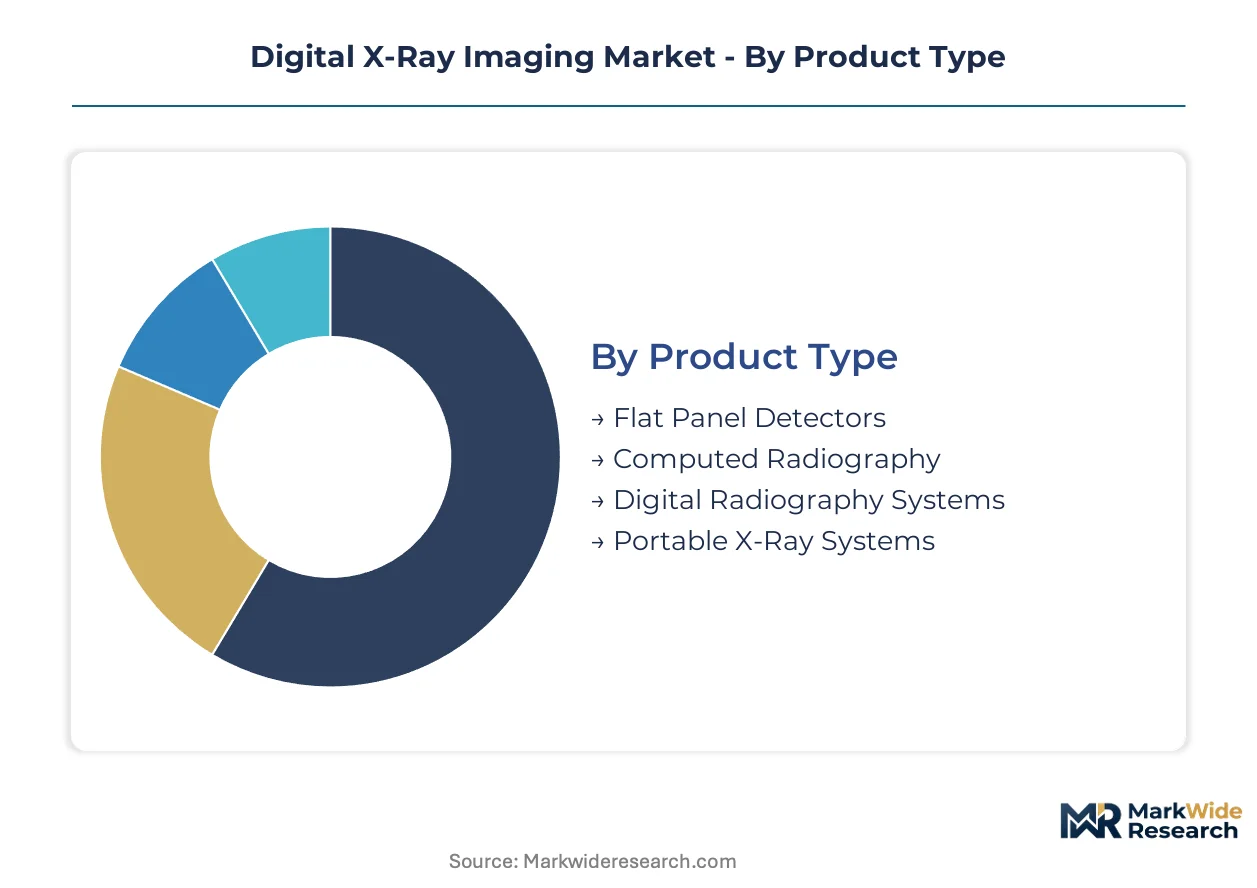
Digital x-ray imaging vendors structure product portfolios across four intersecting dimensions. Procurement committees evaluate hardware specifications against software capabilities, while end-use settings dictate workflow integration requirements and capital deployment models.
Product Type:
Mature cassette-based systems coexist with emerging solid-state architectures across replacement cycles and greenfield installations.
- Flat Panel Detectors:Amorphous silicon or CMOS active matrix arrays with cesium iodide scintillator layers deliver sub-400 micrometer spatial resolution. Demand concentrates in United States trauma centers and German university hospitals seeking dose-reduction protocols for pediatric populations.
- Portable X-Ray Systems:Battery-powered mobile units with wireless detector pairing enable bedside acquisition in intensive care settings. China's tertiary hospitals in Beijing and Shanghai are expanding fleets to eliminate patient transport risks in emergency departments.
- Computed Radiography:Photostimulable phosphor plate systems persist in budget-constrained outpatient networks.
- Digital Radiography Systems:Fixed-room installations integrate automated positioning and exposure control for high-throughput screening workflows.
Flat panel detectors retain volume leadership; portable x-ray systems hold the steepest expansion curve.
Application:
Clinical use cases span from high-volume screening programs to specialized diagnostic protocols with distinct reimbursement and regulatory profiles.
- General Radiography:Skeletal and abdominal examinations constitute the procedural backbone of hospital radiology departments. United States outpatient imaging networks prioritize throughput optimization to maximize CMS reimbursement per technologist hour.
- Chest Imaging:Pulmonary and cardiac projection radiography supports tuberculosis screening and post-operative monitoring. India's government health schemes are expanding procurement of AI-augmented systems for rural district hospitals.
- Dental Imaging:Intraoral and panoramic systems serve orthodontic and implant planning workflows.
- Mammography:Dedicated systems with specialized compression and angulation capabilities address breast cancer screening programs.
General radiography dominates procedure volume; chest imaging is climbing the fastest as tuberculosis resurgence and post-pandemic pulmonary monitoring expand screening mandates.
Technology:
Software-defined capabilities now rival hardware specifications as primary procurement criteria across integrated delivery networks.
- AI Imaging Solutions:Deep learning algorithms for automated abnormality detection and triage prioritization. FDA 510(k) clearance pathways in the United States are compressing deployment timelines for emergency radiography workflows.
- Detectors:Solid-state capture elements with optimized quantum efficiency and signal-to-noise ratios. German detector manufacturers maintain upstream control over amorphous silicon fabrication for premium system tiers.
- Imaging Software:Reconstruction algorithms and post-processing toolkits for noise reduction and edge enhancement.
- Cloud-Based Systems:Distributed storage and remote interpretation infrastructure for multi-site networks.
Detectors retain component revenue concentration; AI imaging solutions are gaining share fastest as workforce constraints drive automation procurement.
End User:
Capital availability and patient volume stratify purchasing behavior across institutional settings.
- Hospitals:Integrated health systems with centralized radiology departments and 24/7 emergency coverage. United States IDNs negotiate enterprise-wide managed service contracts bundling hardware, software, and maintenance across multiple facilities.
- Diagnostic Imaging Centers:Independent outpatient facilities competing on appointment availability and report turnaround. German radiology networks unbundle AI licensing from equipment leases to optimize operating cost structures.
- Clinics:Limited-service settings with restricted capital budgets and lower daily examination volumes.
- Research Institutions:Academic medical centers evaluating novel acquisition protocols and algorithm validation.
Hospitals command the largest equipment installed base; diagnostic imaging centers are expanding most quickly as outpatient efficiency incentives reshape referral patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States, Germany, and China concentrate demand for digital radiography systems, with each geography presenting distinct regulatory pathways and reimbursement incentives that shape vendor market access strategies.
United States
Integrated delivery networks in Texas and Florida are consolidating radiology service contracts under enterprise-wide managed service agreements. FDA 510(k) clearance pathways for software-as-medical-device products compress deployment timelines for AI-assisted abnormality detection algorithms. Boston and San Francisco hospital clusters prioritize dual-energy subtraction systems for trauma center pulmonary nodule characterization.
Germany
University hospitals in Munich and Heidelberg are expanding flat panel detector fleets to meet pediatric dose-reduction mandates. EU Medical Device Regulation enforces stricter clinical evidence standards for AI-augmented x-ray systems, extending approval timelines for algorithm developers. Diagnostic imaging networks in North Rhine-Westphalia unbundle AI licensing from equipment leases to optimize operating cost structures.
China
Tertiary hospitals in Beijing and Shanghai are prioritizing portable x-ray system deployments to eliminate patient transport risks in emergency departments. NMPA has accelerated review pathways for domestically manufactured digital radiography equipment under national healthcare infrastructure programs. Domestic detector fabrication clusters in Shenzhen and Shanghai qualify for expedited clearance benefits.
Japan
Hospital networks in Tokyo and Osaka are adopting workflow-integrated AI tools to address radiologist staffing constraints in high-volume screening programs. PMDA maintains distinct software validation protocols that create separate approval timelines for algorithm developers. Medical device manufacturing clusters in Nagoya supply solid-state detector components to premium system integrators.
India
Rural district hospitals in Maharashtra and Karnataka are expanding procurement under government health scheme expansion programs. CDSCO regulatory frameworks govern medical device import and domestic manufacturing standards for imaging equipment. Diagnostic infrastructure gaps in secondary cities create whitespace for leasing-based managed service contracts with remote AI interpretation support.
Digital X-Ray Imaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Integrated systems manufacturers with captive detector fabrication and proprietary algorithm development occupy premium positions in procurement negotiations. Independent software vendors and component suppliers compete on specialized performance metrics or cost-optimized configurations. Dominant competitive moves include backward integration into scintillator material production and strategic bundling of hardware maintenance with software subscription renewals.
Among diversified healthcare technology conglomerates, Siemens Healthineers, GE Healthcare, and Philips Healthcare exemplify the integrated systems archetype. These players anchor competitive positioning through installed base leverage, captive supply chain control, and workflow-embedded AI differentiation. Each occupies a distinct strategic vector: Siemens emphasizes software subscription bundling across hardware fleets, GE anchors through detector manufacturing integration, and Philips differentiates via emergency department workflow optimization.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Philips Healthcare |
| Fujifilm Holdings Corporation |
| Canon Medical Systems Corporation |
| Carestream Health |
| Shimadzu Corporation |
| Agfa-Gevaert Group |
| Konica Minolta |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in amorphous silicon detector fabrication across East Asian manufacturing clusters is compressing component margins while simultaneously enabling aggressive system-level pricing from integrated manufacturers with captive supply. This utilization dynamic rewards backward-integrated vendors with procurement leverage while forcing independent detector suppliers toward specialty premium tiers or exit.
Pricing Analysis
Cost-plus service contracts with raw material indexation dominate hospital procurement negotiations for digital radiography systems. Three-tier pricing structure across premium, standard, and economy levels separates AI-bundled managed service agreements from bare hardware leases and refurbished detector deployments. Pricing pressure stems from NMPA-favored domestic manufacturers in China undercutting premium import tiers in government tenders. Independent diagnostic centers exhibit highest price sensitivity due to capital lease constraints, while United States integrated delivery networks prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk planning for detector component sourcing. Amorphous silicon wafer fabrication concentrates in Japan, South Korea, and Taiwan, while cesium iodide scintillator crystal growth feeds from specialized facilities in China and the United States. Single-source vulnerability in CMOS active matrix arrays for premium portable systems creates qualification bottlenecks when switching suppliers. Distribution runs through authorized dealer networks for hospital capital equipment, with direct manufacturer relationships governing high-volume GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where PACS interoperability standards and AI algorithm deployment frameworks are consolidating around vendor-neutral integration architectures. The shift from closed proprietary ecosystems toward DICOM-conformant, cloud-accessible diagnostic pipelines restructures competitive moats around data liquidity rather than hardware lock-in.
For Market Incumbents: Build switching-cost moats through embedded workflow AI that integrates with existing PACS infrastructure and radiologist reading protocols. Siemens Healthineers and GE Healthcare should deepen backward integration into scintillator material production to defend margin position against Chinese domestic entrants. Priority lever rests on predictive maintenance service contracts that capture recurring revenue from installed flat panel detector fleets. For New Entrants and Emerging Players: Rural hospital networks in India represent the most penetrable geographic whitespace, with government health scheme expansion creating procurement volume without incumbent saturation. Target leasing-based managed service contracts with remote AI interpretation support as the go-to-market angle. Focus initial deployment on portable x-ray systems where capital barriers are lowest and bedside imaging demand is climbing fastest. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across AI software-only diagnostic tools relative to hardware-integrated systems. Long-term viability favors platform plays with recurring SaaS revenue over cyclical equipment sales. Acquisition target archetype: algorithm developers with FDA 510(k) clearances and hospital pilot data but limited commercial scale. Signal to watch is NMPA approval velocity for domestic Chinese AI imaging solutions as indicator of regulatory arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm FDA 510(k) Submission | Accelerates emergency radiography deployment timelines in United States hospital networks. |
| Detector Manufacturing Backward Integration | Captures scintillator margin and insulates against raw material price volatility. |
| PACS-Integrated Workflow Partnership | Locks in radiologist user base through seamless abnormality flagging deployment. |
| Managed Service Contract Expansion | Converts capital equipment sales into recurring revenue across hospital IDNs. |
| NMPA Expedited Pathway Qualification | Unlocks government procurement tenders in Beijing and Shanghai tertiary hospitals. |
Research Methodology
A standing panel of hospital purchasing committee chairs, biomedical engineering directors, radiology department heads, and GPO contracts managers provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, NMPA registration filings, hospital procurement contract repositories, and CMS reimbursement schedules. Bottom-up equipment shipment tracking and top-down healthcare capital expenditure analysis were triangulated against vendor-reported installed base metrics.
Scenario-bracketing framed the analytical approach across the analysis window, with base, upside, and downside cases reflecting divergent AI adoption curves and regulatory approval velocities. Segmentation dimensions modeled include product architecture, clinical application, technology integration level, end-user capital availability, and regional reimbursement framework. CAGRs were derived from curve-fitting historical replacement cycles against projected greenfield installation demand, with specific inputs from pediatric dose-reduction mandate timelines and portable system fleet expansion trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic manufacturers with NMPA-favored status would shift outcomes toward faster price erosion and earlier flat panel detector commoditization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Digital Radiography Detectors Market
Medical Imaging
Asia-Pacific Digital X-Ray Devices Market
Medical Imaging
Digital Breast Tomosynthesis Market
Medical Imaging
Automated Contouring Radiotherapy Software Market
Medical Imaging
India Digital Radiology Market
Medical Imaging
North America Computed Tomography (CT) Market
Medical Imaging
Dental X-Ray Market
Medical Imaging
Pediatric Imaging Market
Medical Imaging
US Magnetic Resonance Imaging Coils Market
Medical Imaging
Mexico Nuclear Imaging Market
Medical Imaging
South Korea Nuclear Imaging Market
Medical Imaging
Portable X-Ray Devices Market
Medical Imaging
Ultrasound Elastography Systems Market
Medical Imaging
Argentina Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Canada Mammography Market
Medical Imaging
China VNA and PACS Market