
 AI in Diagnostic Imaging Market | 2026-2036
AI in Diagnostic Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Diagnostic Imaging Market Outlook
Silicon Valley chip fabrication capacity for medical-grade GPUs is decoupling from general-purpose AI training demand, creating dedicated supply lines for healthcare inference workloads. NVIDIA Corporation leverages its CUDA ecosystem to anchor dominance in radiology model training infrastructure. Siemens Healthineers sustains European market presence through deep integration of AI into MRI and CT hardware control systems. GE HealthCare competes by embedding real-time inference engines directly into imaging device firmware, reducing latency for critical care workflows.
AI in diagnostic imaging encompasses deep learning algorithms, computer vision pipelines, and regulatory-compliant software that analyze medical images to detect, classify, or segment pathological findings with specified sensitivity thresholds exceeding 90% for certain malignancies. Its primary purpose is to reduce radiologist reading time, standardize inter-reader variability, and flag time-critical findings such as intracranial hemorrhage or pulmonary embolism for priority review. Image analysis software captures the dominant revenue share as hospitals prioritize lesion detection and quantification tools over workflow add-ons. Cloud-based deployment is expanding fastest among mid-sized diagnostic laboratories seeking to avoid capital-intensive on-premises GPU clusters. X-ray interpretation retains the largest installed base due to high exam volumes, though MRI analysis commands premium pricing for neuro-oncology and musculoskeletal subspecialties.
FDA software-as-a-medical-device pathways and EU MDR Class IIa/IIb certification requirements are reshaping product development timelines and clinical evidence standards for algorithm commercialization. EMA guidance on AI-based diagnostic devices is pushing developers toward prospective validation studies rather than retrospective dataset benchmarking. Stakeholders must monitor evolving reimbursement decisions by CMS and Germany's G-BA, as these will determine whether health systems absorb AI costs or pass them to patients.
Market Dynamics
Hospital procurement committees now mandate AI-augmented reads for stroke and trauma protocols, compressing vendor selection cycles from eighteen months to under six months as clinical evidence thresholds tighten.
Growth Catalysts
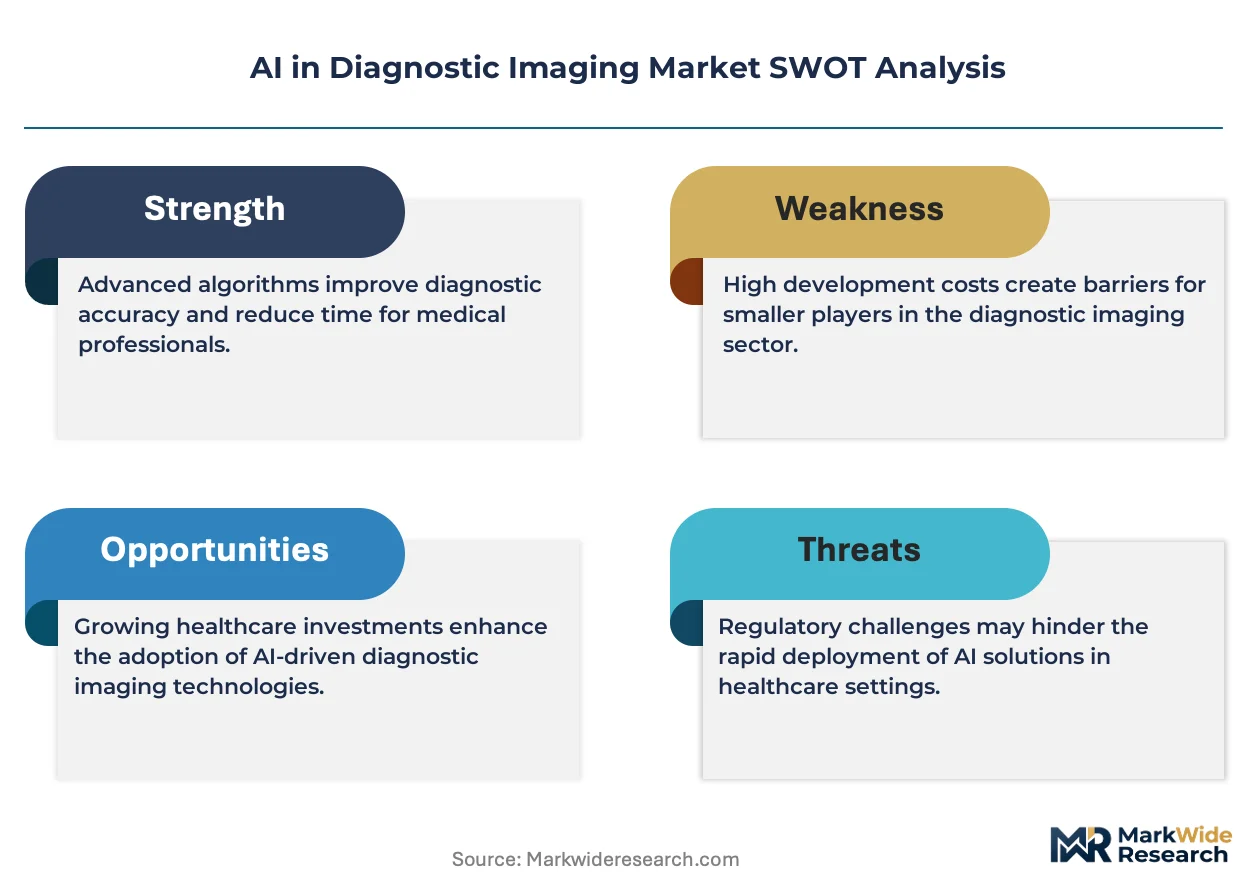
- FDA 510(k) Software-as-a-Medical-Device pathway:The FDA's streamlined premarket notification process for AI-based diagnostic tools accelerates commercialization timelines for algorithm developers seeking clearance for radiology applications.
- Germany's G-BA reimbursement framework:Germany's Federal Joint Committee is establishing Diagnosis-Related Group add-on payments for AI-augmented imaging reads, creating direct revenue pathways for hospital radiology departments.
- Edge inference deployment:On-device GPU architectures are migrating from cloud-dependent workflows to localized processing, reducing latency for time-critical findings in emergency department CT interpretation.
Market Restraints
- Medical-grade GPU supply concentration:Taiwan-based foundry capacity for healthcare-optimized inference chips remains captive to automotive and consumer electronics demand cycles, creating allocation bottlenecks for imaging OEMs.
- EU MDR Class IIb clinical evidence requirements:The European Medical Device Regulation mandates prospective validation studies for AI diagnostic software, extending development timelines and elevating capital requirements for algorithm commercialization.
- Inter-reader variability standardization:Persistent discordance between AI algorithm outputs and subspecialist radiologist interpretations limits deployment confidence in complex oncologic imaging protocols.
Strategic Opportunities
- Mid-sized diagnostic laboratory cloud migration:Radiology groups with annual exam volumes below fifty thousand studies are bypassing on-premises infrastructure through GPU-as-a-service arrangements with specialized healthcare cloud providers.
- Japan's PMDA fast-track designation:Japan's Pharmaceuticals and Medical Devices Agency offers accelerated review pathways for AI diagnostic devices addressing designated intractable diseases, opening priority market access for neurodegenerative imaging applications.
- Multi-modal fusion imaging:Convergence of PET-MRI co-registration algorithms with real-time CT fluoroscopy guidance is creating new procedural navigation tools for interventional radiology suites.
Industry Challenges
- Regulatory science workforce scarcity:Algorithm developers face acute shortages of professionals qualified to bridge clinical validation design with FDA Q-Submission preparation and EU MDR technical documentation.
- Legacy PACS integration complexity:Hospital information technology departments encounter protocol incompatibilities when embedding AI inference engines into decade-old picture archiving and communication systems without vendor-native API support.
- Algorithm drift monitoring infrastructure:Continuous validation requirements for deployed AI models demand dedicated quality assurance personnel and automated performance tracking systems that most radiology practices lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Diagnostic Imaging Market |
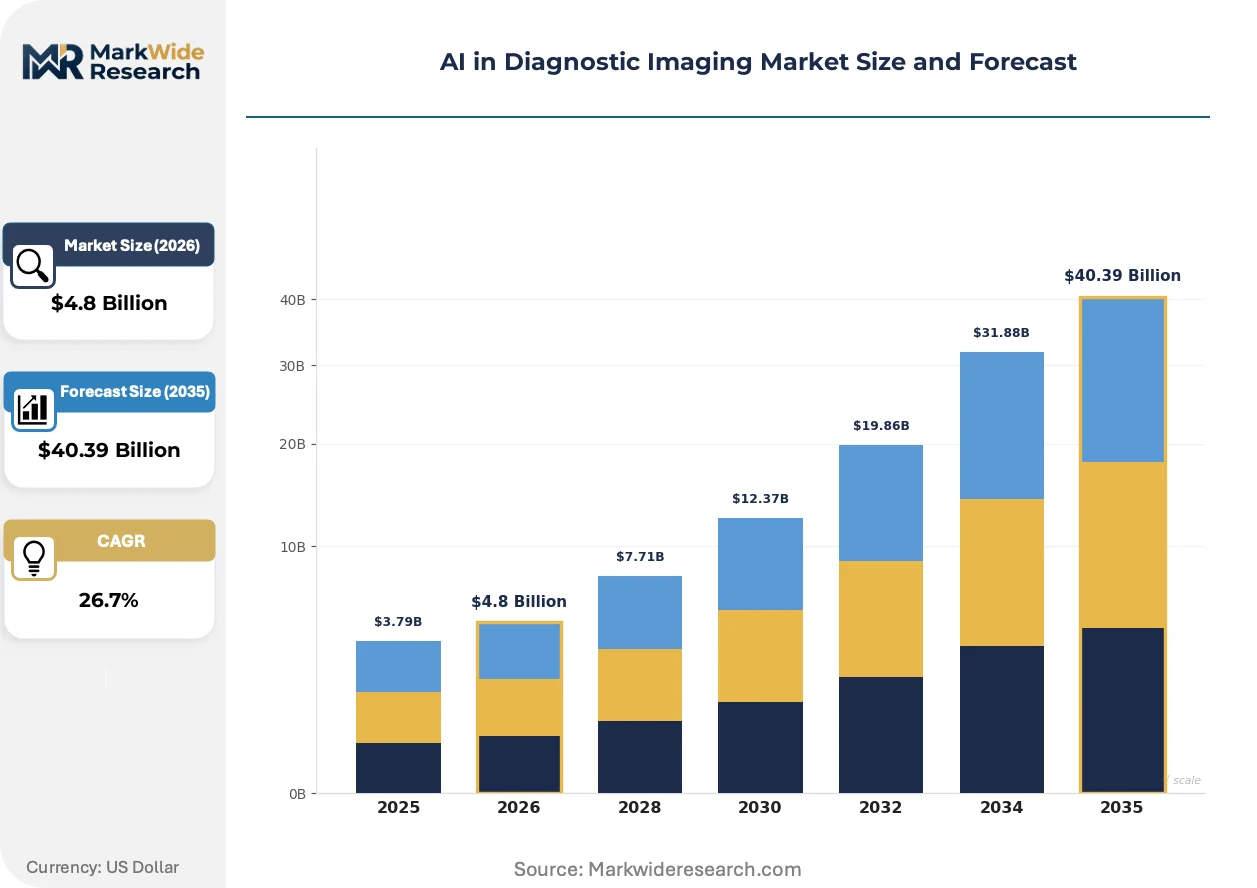
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $40.39 Billion |
| CAGR (2026 – 2036) | 26.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Image Analysis Software, Workflow Optimization, Reporting Tools, Visualization Solutions End User: Hospitals, Specialty Clinics, Research Institutions, Diagnostic Laboratories Application: X-Ray Interpretation, MRI Analysis, CT Scan Evaluation, Ultrasound Assessment Deployment: Cloud-Based, On-Premises, Hybrid Solutions, Edge Computing |
| Companies Covered | GE HealthCare, Siemens Healthineers, Koninklijke Philips N.V., NVIDIA Corporation, Microsoft, Digital Diagnostics Inc., Canon Medical Systems, Enlitic Inc., Viz.ai Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Diagnostic Imaging Market Strategic Shifts
Foundation models trained on multi-institutional imaging archives are compressing algorithm development cycles while raising new questions about data governance and consent frameworks for retrospective clinical datasets.
Federated learning architectures are converging with differential privacy protocols to enable multi-site algorithm training without centralizing patient data. Academic medical centers in the United States and Switzerland are deploying these frameworks for rare disease detection models where single-institution case volumes prove insufficient. This convergence is enabling cross-border research collaborations that previously stalled on data residency restrictions.
The EU AI Act's high-risk system classification for medical diagnostic applications imposes conformity assessment obligations and post-market monitoring requirements on AI imaging software. Developers must now maintain risk management systems and quality management systems audited by notified bodies. European radiology departments are prioritizing vendors with established EU MDR Class IIb certifications to preempt compliance gaps.
Subscription-based licensing models are displacing perpetual software licenses in hospital procurement negotiations for AI imaging tools. Chief financial officers prefer operational expenditure structures that align costs with exam volume fluctuations rather than capital-intensive upfront purchases. This shift is most pronounced in United States health systems undergoing debt restructuring or private equity ownership transitions.
AI in Diagnostic Imaging Market Segmentation
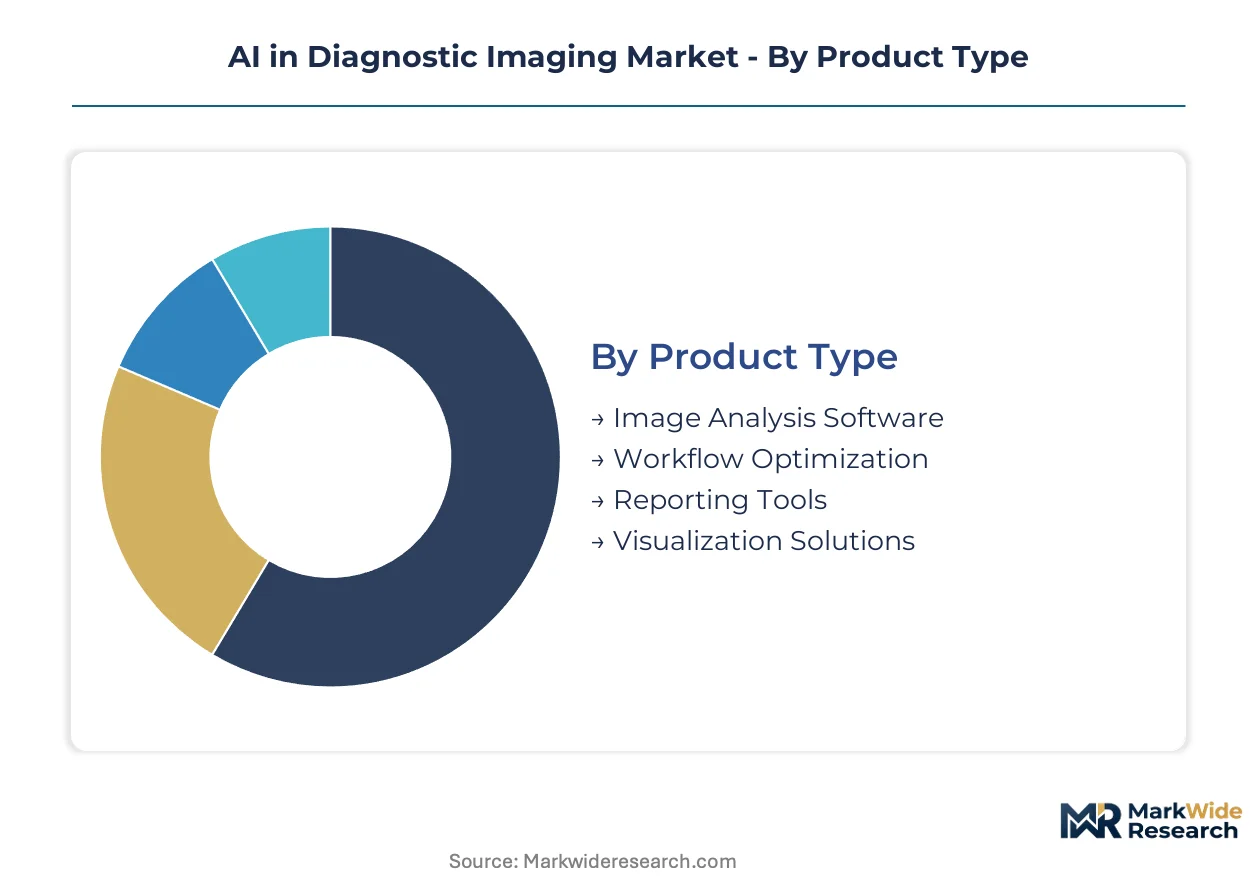
Segmentation in AI diagnostic imaging reveals distinct procurement patterns across buyer types and technical requirements. Hospital radiology departments prioritize different capabilities than research institutions or outpatient clinics. Understanding these divides shapes vendor positioning and product development roadmaps.
Product Type:
Procurement committees weight clinical utility against integration burden when evaluating AI software categories.
- Image Analysis Software:Deep learning algorithms detect, classify, and segment pathological findings in radiological images with specified sensitivity thresholds. Demand concentrates in United States hospital systems where CMS reimbursement decisions for AI-augmented reads are advancing through parallel pathways. FDA 510(k) clearances for lesion detection tools outpace other categories.
- Workflow Optimization:Automated triage and prioritization systems route critical findings to radiologist worklists based on acuity scoring. Specialty clinics in Germany adopt these tools fastest under G-BA Diagnosis-Related Group add-on payment frameworks that reward efficiency gains.
- Reporting Tools:Structured reporting templates auto-populate findings into standardized formats compatible with electronic health records.
- Visualization Solutions:Three-dimensional rendering and multi-planar reconstruction interfaces enhance surgical planning and patient consultation workflows.
Volume sits with Image Analysis Software; growth tilts toward Workflow Optimization.
End User:
Capital intensity and regulatory exposure separate buyer segments across the care continuum.
- Hospitals:Academic medical centers and community hospital systems deploy comprehensive AI suites across radiology, emergency, and surgical departments. Stroke and trauma protocols in United States facilities now mandate AI-augmented reads, compressing vendor selection cycles.
- Diagnostic Laboratories:Mid-sized independent labs with annual exam volumes below fifty thousand studies bypass on-premises GPU clusters through cloud-based GPU-as-a-service arrangements. This segment climbs fastest as operational expenditure models displace capital-intensive purchases.
- Specialty Clinics:Orthopedic, cardiology, and women's health outpatient centers deploy narrow-use algorithms for specific imaging modalities.
- Research Institutions:Academic medical centers train foundation models on multi-institutional archives and deploy federated learning architectures for rare disease detection.
Procurement volume concentrates in Hospitals; Diagnostic Laboratories expand most quickly.
Application:
Exam volume and reimbursement rates create divergent investment profiles across imaging modalities.
- X-Ray Interpretation:High-throughput chest and musculoskeletal radiography drives the largest installed base of AI deployment. United States emergency departments prioritize automated pneumonia and fracture detection for throughput gains. Plain film algorithms command lower per-study pricing but scale through volume.
- MRI Analysis:Neuro-oncology and musculoskeletal subspecialties generate premium pricing for AI tools that quantify tumor burden or cartilage degeneration. Japan's PMDA fast-track designation accelerates market access for neurodegenerative imaging applications addressing designated intractable diseases.
- CT Scan Evaluation:Time-critical intracranial hemorrhage and pulmonary embolism detection commands priority review workflows in trauma settings.
- Ultrasound Assessment:Point-of-care cardiac and obstetric applications expand AI deployment into non-radiologist hands.
X-Ray Interpretation holds installed base leadership; MRI Analysis captures value concentration.
Deployment:
Latency requirements and data residency rules determine infrastructure architecture decisions.
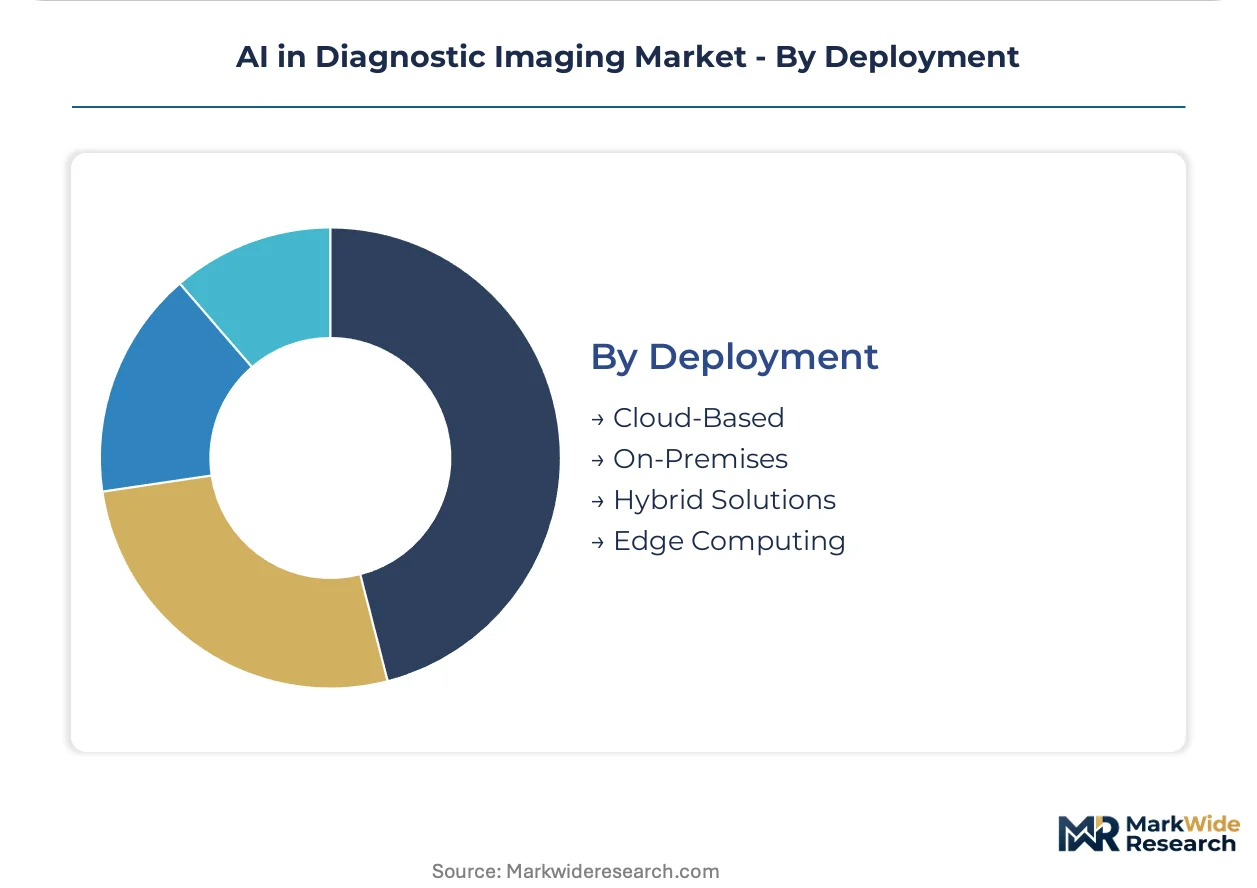
- Cloud-Based:Scalable GPU resources eliminate capital expenditure for mid-sized diagnostic laboratories. United States health systems undergoing private equity ownership transitions prefer subscription licensing aligned with operational expenditure structures.
- Edge Computing:On-device inference engines embedded directly into CT and MRI hardware reduce latency for emergency department workflows. Siemens Healthineers and GE HealthCare compete through firmware-integrated processing that eliminates network dependency for critical findings.
- On-Premises:Captive GPU clusters serve large hospital systems with stringent data residency requirements or high-volume academic research needs.
- Hybrid Solutions:Split architectures route non-urgent studies to cloud resources while retaining time-critical processing at the edge.
Cloud-Based deployment scales fastest; Edge Computing gains share in latency-sensitive protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade GPU foundry capacity in Taiwan anchors the hardware supply geography for AI diagnostic imaging infrastructure, while algorithm development clusters concentrate in jurisdictions with mature regulatory pathways and reimbursement frameworks.
United States
Hospital radiology departments drive procurement volume through stroke and trauma protocol mandates that compress vendor selection cycles. FDA 510(k) Software-as-a-Medical-Device clearances accelerate time-to-market for algorithm developers seeking radiology applications. The Boston-Cambridge corridor hosts academic medical centers deploying federated learning architectures for rare disease detection models.
Germany
G-BA Diagnosis-Related Group add-on payments for AI-augmented reads create direct revenue pathways for hospital radiology departments. EU MDR Class IIb certification requirements reshape product development timelines and clinical evidence standards for commercialization. Siemens Healthineers anchors European market presence through deep integration of AI into MRI and CT hardware control systems in Erlangen and Forchheim.
Japan
PMDA fast-track designation accelerates market access for AI diagnostic devices addressing designated intractable diseases, particularly neurodegenerative imaging applications. METI industrial policy supports domestic imaging OEMs in embedding real-time inference engines into device firmware. Tokyo-Osaka medical device clusters concentrate neuro-oncology algorithm development for premium-priced MRI analysis tools.
United Kingdom
NHS England pilot programs for AI-augmented radiology reads establish procurement templates for national health system adoption. MHRA convergence with FDA breakthrough device pathways streamlines regulatory navigation for transatlantic algorithm developers. London-based academic medical centers train foundation models on multi-institutional imaging archives under differential privacy protocols.
China
NMPA medical device registration pathways for AI diagnostic software compress approval timelines for domestic algorithm developers. National hospital digitization mandates under the 14th Five-Year Plan accelerate procurement of AI-assisted CT and MRI interpretation tools. Beijing-Shanghai-Shenzhen clusters concentrate computer vision pipeline development for high-throughput chest radiography applications.
AI in Diagnostic Imaging Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue cloud-native deployment models and workflow optimization add-ons. The vendor base stratifies across imaging hardware OEMs with firmware-integrated AI, independent algorithm developers seeking regulatory clearance, and hyperscale cloud providers offering GPU-as-a-service infrastructure. Three archetypes dominate: device-integrated incumbents, software-native challengers, and platform-layer enablers. Competitive moves concentrate on strategic partnerships between hardware OEMs and algorithm developers, plus M&A activity targeting workflow optimization capabilities.
Within the device-integrated tier, GE HealthCare and Siemens Healthineers exemplify hardware control system anchoring strategies. NVIDIA Corporation occupies the platform-layer position through CUDA ecosystem dominance in radiology model training infrastructure. Among software-native specialists, Digital Diagnostics Inc. and Viz.ai Inc. represent regulatory-first pathways targeting specific clinical indications with FDA-cleared algorithms.
| Leading Market Players |
|---|
| GE HealthCare |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| NVIDIA Corporation |
| Microsoft |
| Digital Diagnostics Inc. |
| Canon Medical Systems |
| Enlitic Inc. |
| Viz.ai Inc. |
| Others |
Value Chain & Pricing Dynamics
Edge inference migration from cloud-dependent workflows to localized GPU processing simultaneously compresses latency premiums and concentrates procurement leverage among CT and MRI hardware OEMs with captive firmware integration. This shift rewards vendors controlling both silicon allocation and device control systems while squeezing standalone algorithm developers on margin.
Pricing Analysis
Warranty and continuous validation service bundling now separates premium AI imaging contracts from unbundled software licenses that leave drift monitoring to hospital IT departments. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance tier, prospective clinical evidence depth, and after-sales algorithm update commitments. Cost compression in the mid-tier is intensifying because G-BA reimbursement frameworks in Germany reward efficiency gains over detection sensitivity. Mid-sized diagnostic laboratories exhibit highest price sensitivity due to operational expenditure constraints, while academic medical centers prioritize evidence quality over per-study licensing costs.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for medical-grade GPUs, bypassing distribution intermediaries that serve smaller cloud-as-a-service arrangements. Taiwan-based foundry capacity for healthcare-optimized inference chips draws from automotive and consumer electronics allocation pools, creating bottlenecks during demand spikes. NVIDIA Corporation's CUDA ecosystem anchors model training infrastructure sourcing, while discrete inference silicon feeds from Samsung and TSMC logic nodes. Single-source vulnerability concentrates in Taiwan Strait logistics exposure, with hospital radiology departments now demanding six-month buffer inventory commitments from imaging OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical-grade GPU foundry capacity constraints prop pricing power for device-integrated incumbents, while standalone algorithm developers face margin compression from cloud infrastructure markups and regulatory validation cost inflation.
For Market Incumbents: Acquire federated learning platform capabilities to preempt software-native challengers targeting multi-institutional training demand. Siemens Healthineers and GE HealthCare should deepen backward integration into edge inference silicon design, mirroring NVIDIA's CUDA ecosystem lock-in. FDA Q-Submission preparation capacity represents the critical bottleneck; incumbents must secure regulatory science workforce pipelines before EU MDR Class IIb certification timelines extend further. For New Entrants and Emerging Players: Mid-sized diagnostic laboratories with annual exam volumes below fifty thousand studies represent the most penetrable buyer archetype, bypassing entrenched hospital procurement committees through GPU-as-a-service cloud arrangements. Workflow optimization add-ons for legacy PACS integration offer faster time-to-revenue than competing on detection sensitivity. Japan's PMDA fast-track designation for neurodegenerative imaging provides regulatory arbitrage against FDA 510(k) backlog delays. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by imaging hardware OEMs seeking algorithm differentiation, with IPO windows narrowing for standalone software vendors lacking device integration. Five-to-ten year viability favors vendors with established EU MDR Class IIb certifications and CMS reimbursement pathway clarity. Watch Germany's G-BA Diagnosis-Related Group add-on payment expansion decisions as the inflection signal for hospital radiology department procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Software-as-a-Medical-Device Submission | Accelerates commercialization timelines for algorithm developers seeking radiology clearance pathways. |
| EU MDR Class IIb Certification Investment | Establishes European market access under post-market monitoring and risk management system requirements. |
| Hospital System Partnership for Stroke Protocol Integration | Compresses vendor selection cycles from eighteen months to under six months through clinical evidence mandates. |
| Edge Inference Firmware Development | Eliminates network dependency for critical care CT and MRI workflows in emergency department settings. |
| Reimbursement Strategy Alignment with CMS and G-BA | Determines whether health systems absorb AI costs or pass them to patients through add-on payments. |
Study Parameters
Independent corroboration across primary interviews with hospital purchasing committees, FDA regulatory consultants, and GPO contracts managers, plus secondary validation through FDA 510(k) clearance databases, CMS reimbursement decision records, and EU MDR notified body certification registries underwrites the qualitative findings. Bottom-up triangulation against top-down imaging modality installation base estimates from hospital procurement databases anchors volume assumptions. Conversations with biomedical engineers deploying federated learning architectures and cloud infrastructure specialists serving diagnostic laboratories informed deployment model segmentation.
Comparable-period anchoring to historical FDA clearance velocity and G-BA reimbursement framework adoption curves shaped the projection horizon calibration. The analytical framework models segmentation across product type, end user, application, and deployment architecture throughout the forecast period. CAGRs derive from installed base growth rates, replacement cycle compression, and pricing trajectory assumptions. Cloud migration patterns among mid-sized laboratories and edge inference adoption in trauma protocols represent key forecast sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Taiwan foundry allocation shifts, EU AI Act enforcement intensity, and CMS national coverage determination reversals. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Medical Imaging Phantoms Market
Medical Imaging
US Gadolinium-Based Contrast Media Market
Medical Imaging
Argentina Mammography Market
Medical Imaging
United States Computed Tomography Market
Medical Imaging
Orthopedic Radiology Equipment Market
Medical Imaging
Brazil Digital Radiology Market
Medical Imaging
United Kingdom Mammography Market
Medical Imaging
Industrial Computed Radiography Market
Medical Imaging
US and Europe Digital Pathology Market
Medical Imaging
Argentina Digital X-Ray Market
Medical Imaging
North America Open System MRI Market
Medical Imaging
North America Medical Imaging Software Market
Medical Imaging
Open System MRI Market
Medical Imaging
Perfusion Imaging Market
Medical Imaging
Global Artificial Intelligence in MRI Market
Medical Imaging
Italy Magnetic Resonance Imaging Market