
 Europe Orthopedic Navigation Systems Market | 2026-2036
Europe Orthopedic Navigation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Orthopedic Navigation Systems Market Intelligence
Project finance and equipment leasing is rewriting competitive access across European orthopedic navigation, allowing mid-tier hospitals to deploy capital-intensive platforms without full ownership burdens. Stryker Corporation leverages its installed base of surgical robotics to bundle navigation subscriptions, while Brainlab AG sustains independence through software-centric models that minimize hardware exposure. Medtronic Plc anchors its position via deep integration with spine navigation workflows across Nordic hospital networks.
Orthopedic navigation systems employ optical, electromagnetic, or hybrid tracking modalities to register patient anatomy against preoperative imaging and guide instrument positioning in real time, typically achieving sub-millimetre accuracy through infrared camera arrays or electromagnetic field generators. The primary purpose is to reduce implant malalignment and revision rates in joint replacement and spinal fixation. Optical systems dominate current European procurement due to proven reliability in crowded operating theatres, while augmented reality overlays represent the fastest-expanding technology segment as vendors race to reduce surgeon cognitive load. Knee surgery applications command the largest share of installed systems, though spine surgery generates premium pricing through longer procedure complexity and higher disposable content per case.
The EU Medical Device Regulation and CE marking framework enforce escalating clinical evidence requirements that filter out undercapitalized competitors, while GDPR constraints shape how intraoperative patient data flows to cloud-based planning platforms. EMA-aligned notified bodies in Germany and the Netherlands now demand extended follow-up studies for software-as-medical-device upgrades. Stakeholders must weigh whether to absorb compliance costs directly or exit lower-margin mechanical navigation segments entirely.
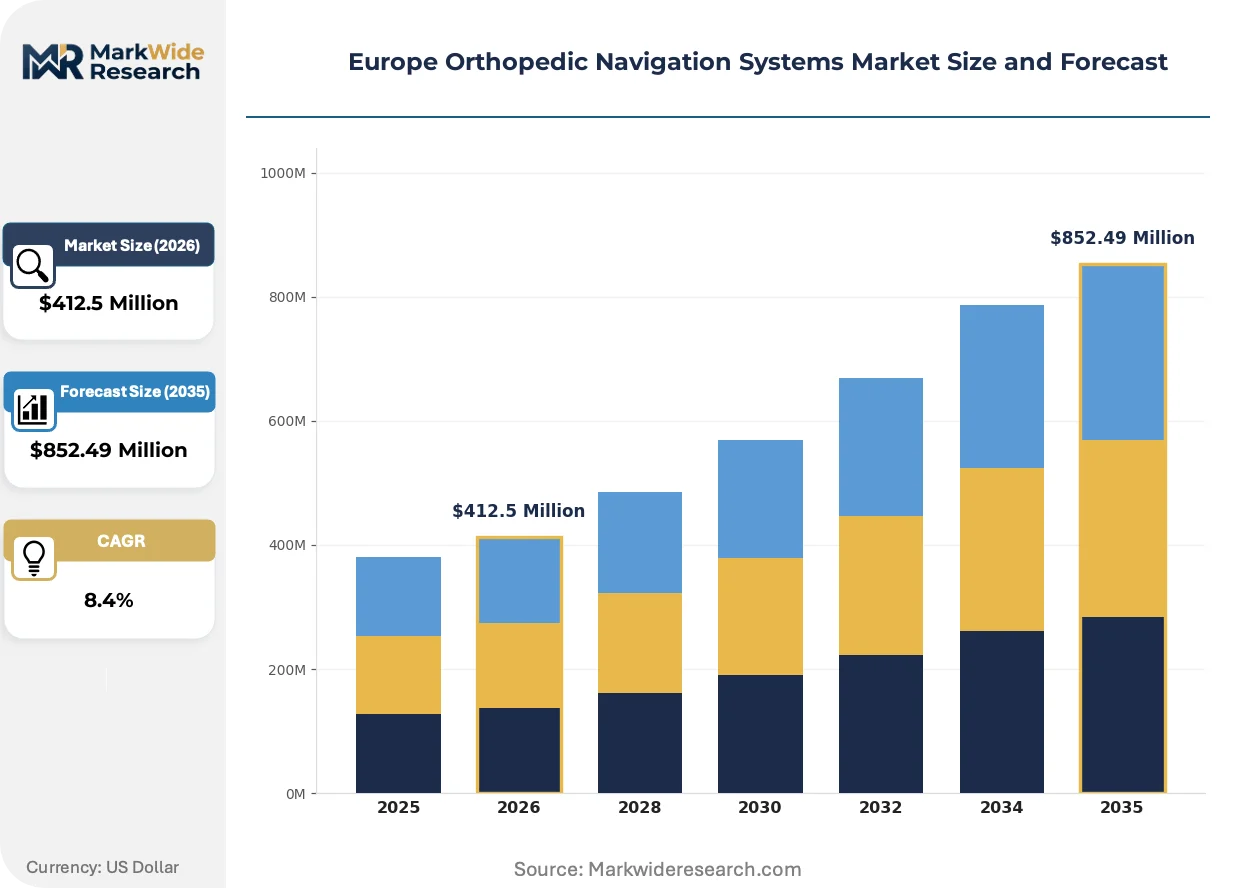
Market Dynamics
The EU Medical Device Regulation is compressing vendor economics across European orthopedic navigation, forcing capital reallocation toward clinical evidence generation while optical tracking platforms face accelerated obsolescence from augmented reality integration.
Growth Catalysts
- MDR compliance deadlines:The EU Medical Device Regulation's extended transition timelines for Class IIb devices create temporary procurement windows as hospitals lock in legacy system purchases before 2027 certification requirements tighten.
- German university hospital robotics programs:Academic medical centers in Berlin and Munich anchor demand for integrated knee and hip arthroplasty platforms, generating reference-site effects across Central European procurement networks.
- Electromagnetic tracking miniaturization:Coil-array advances enable navigation inside MRI suites previously restricted to optical systems, opening spine surgery applications without line-of-sight constraints.
Market Restraints
- Notified body capacity constraints:EMA-aligned bodies in Germany and the Netherlands face application backlogs exceeding 18 months, delaying CE marking for software-as-medical-device navigation upgrades.
- Disposable sensor cost volatility:Single-use electromagnetic trackers and optical reference arrays concentrate supply among three component manufacturers, exposing margins to rare-earth magnet pricing swings.
- Optical system spatial limitations:Infrared camera arrays require unobstructed sightlines that crowded European operating theatres frequently compromise, restricting deployment in smaller surgical suites.
Strategic Opportunities
- Polish and Romanian hospital network expansion:EU cohesion fund infrastructure investments are equipping regional orthopedic centers in Warsaw and Bucharest with first-generation navigation capability, creating greenfield installation demand.
- AR-fluoroscopy convergence:Overlay navigation combining preoperative CT with intraoperative C-arm imaging reduces registration time by eliminating separate tracking hardware, compressing total procedure cost.
- Ambulatory surgery center leasing models:Equipment-as-a-service contracts allow French and Italian day-surgery facilities to access navigation without capital ownership, expanding addressable provider base beyond traditional hospital procurement.
Industry Challenges
- Surgeon learning curve compression:Navigation-assisted arthroplasty requires 40-60 supervised cases for proficiency, straining training capacity at high-volume German and French reference centers already operating at throughput limits.
- Legacy PACS integration complexity:Hospital information systems running decade-old DICOM implementations demand expensive middleware development to support real-time navigation data feeds, extending deployment timelines.
- Cross-border service technician scarcity:Electromagnetic and hybrid system maintenance requires specialized field engineers concentrated in Germany and Switzerland, creating response-time gaps for installations in Southern and Eastern Europe.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Orthopedic Navigation Systems Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $852.49 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromagnetic Systems, Optical Systems, Mechanical Systems, Hybrid Systems Technology: 3D Imaging, Augmented Reality, Robotic Navigation, Computer-Assisted Application: Knee Surgery, Hip Surgery, Spine Surgery, Trauma Surgery End User: Hospitals, Ambulatory Surgery Centers, Orthopedic Clinics, Rehabilitation Centers |
| Companies Covered | Stryker Corporation, Medtronic Plc, Zimmer Biomet Holdings Inc, B Braun SE, Brainlab AG, Siemens Healthineers AG, DePuy Synthes (Johnson & Johnson), GE HealthCare Technologies Inc, CASCINATION, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Orthopedic Navigation Systems Market Strategic Shifts & Innovations
Navigation technology is bifurcating between hardware-light software platforms and integrated robotic ecosystems, with regulatory data requirements now shaping R&D allocation more directly than clinical efficacy alone.
Augmented reality headsets with inside-out tracking are rendering obsolete conventional optical camera arrays in European teaching hospitals. Surgeons at Amsterdam UMC and Charité Berlin now overlay 3D patient anatomy directly onto their field of view without external hardware. This compression of physical footprint eliminates line-of-sight constraints while reducing setup time by half, forcing traditional optical vendors to accelerate software porting or cede the segment.
MDR Article 10 clinical evidence requirements now mandate post-market surveillance extending five years for navigation software updates. Manufacturers must maintain patient registries tracking implant alignment outcomes, adding €2-4 million per major release in follow-up study costs. German notified bodies are rejecting predicate-device equivalence claims for algorithm modifications, pushing vendors toward prospective randomized trials previously reserved for novel implant classes.
Subscription-based navigation access is displacing perpetual license sales across Nordic hospital procurement. Stockholm's Karolinska University Hospital now pays per-procedure fees bundled with disposable instrument trays, transferring utilization risk to vendors. This model concentrates in Sweden and Denmark where regional procurement authorities negotiate system-wide contracts, compressing upfront revenue recognition while extending customer lifetime value for platform holders.
Europe Orthopedic Navigation Systems Market Segmentation
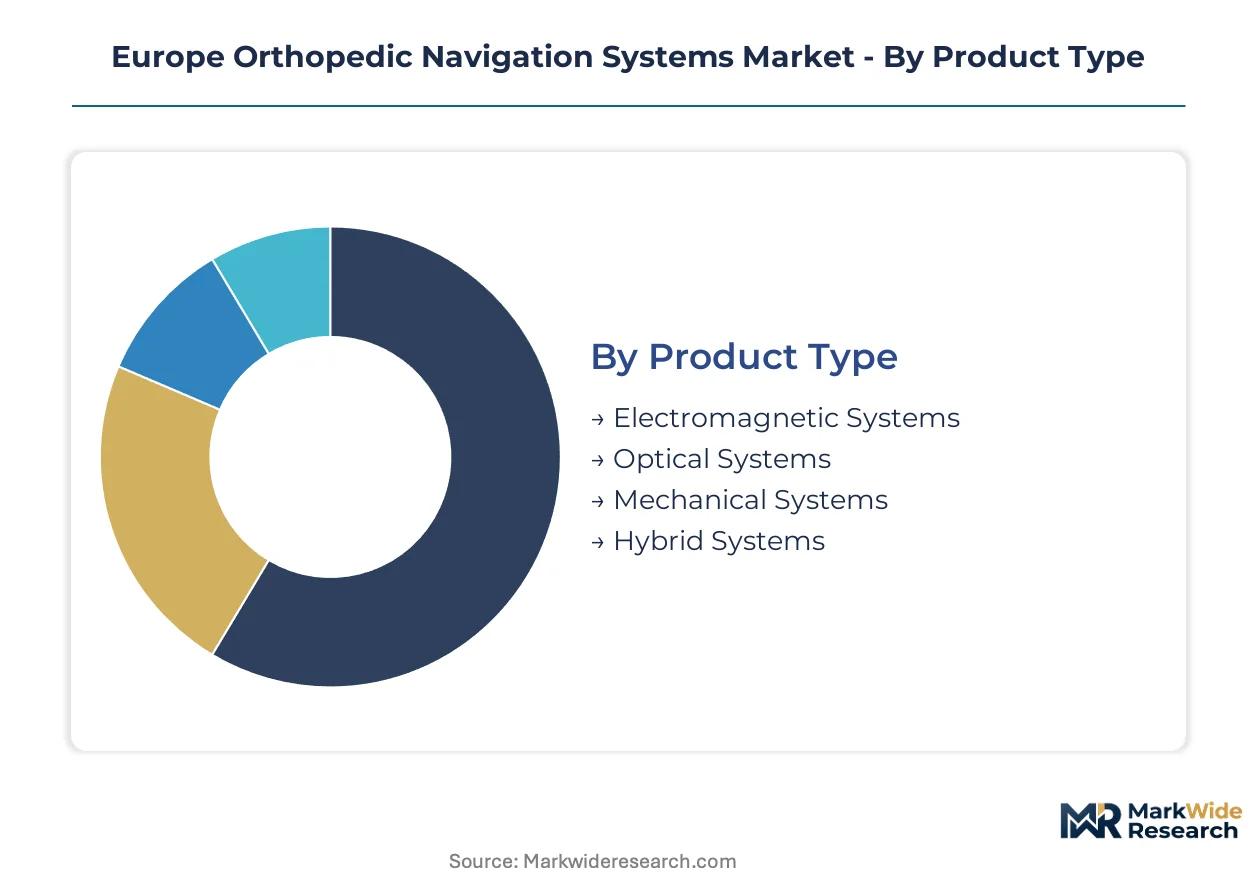
Segmentation in European orthopedic navigation reveals how procurement priorities diverge across care settings and procedure types. Hospital capital committees weight upfront hardware costs against per-procedure disposable burdens, while ambulatory centers prioritize footprint minimization and setup speed.
Product Type:
Cost tier determines competitive access, with electromagnetic platforms commanding premium positioning and mechanical systems facing accelerated obsolescence from software-centric alternatives.
- Electromagnetic Systems:Coil-array tracking generates real-time instrument positioning through magnetic field mapping without line-of-sight constraints. German university hospitals in Berlin and Munich anchor demand for spine applications where optical arrays fail in MRI environments. MDR Article 10 clinical evidence requirements now mandate extended follow-up studies for software updates, adding compliance costs that concentrate procurement among deep-pocketed academic centers.
- Optical Systems:Infrared camera arrays achieve sub-millimetre accuracy through triangulated reference markers on instruments and patient anatomy. French and Italian day-surgery facilities drive replacement demand as legacy installations approach end-of-service life. Crowded European operating theatres compromise sightline requirements, restricting deployment in smaller surgical suites and accelerating interest in hybrid alternatives.
- Mechanical Systems:Rigid frame-based registration with physical guides for instrument positioning.
- Hybrid Systems:Combined optical-electromagnetic tracking with automatic modality switching.
Optical systems hold installed capacity. Electromagnetic platforms are rotating up the share rankings.
Technology:
Application maturity separates established imaging modalities from emerging interfaces that reduce surgeon cognitive load.
- Augmented Reality:Head-mounted displays with inside-out tracking overlay 3D patient anatomy directly onto the surgeon's field of view without external hardware. Amsterdam UMC and Charité Berlin anchor early adoption in teaching hospitals where setup time compression justifies training investment. This interface eliminates line-of-sight constraints while halving preparation duration, forcing traditional optical vendors to accelerate software porting.
- Computer-Assisted:Software platforms registering preoperative CT/MRI against intraoperative instrument position through standardized tracking arrays. Nordic hospital networks in Sweden and Denmark concentrate demand through regional procurement authorities negotiating system-wide subscription contracts. Per-procedure fee structures transfer utilization risk to vendors while extending customer lifetime value.
- 3D Imaging:Preoperative volumetric reconstruction for surgical planning and intraoperative reference.
- Robotic Navigation:Motorized arm positioning with integrated tracking feedback.
Computer-assisted platforms dominate procedure volume. Augmented reality is climbing the fastest.
Application:
Procedure complexity drives pricing architecture, with joint replacement generating volume and spinal fixation commanding premium disposable content per case.
- Knee Surgery:Total and partial arthroplasty navigation achieves mechanical alignment verification against preoperative planning. German university hospital robotics programs in Munich generate reference-site effects across Central European procurement networks. Surgeon proficiency requires 40-60 supervised cases, straining training capacity at high-volume centers already operating at throughput limits.
- Spine Surgery:Pedicle screw placement and vertebral body navigation demand extended procedure duration with higher disposable sensor consumption. Longer case complexity supports premium pricing through bundled instrument trays and specialized electromagnetic trackers. Three component manufacturers concentrate supply of rare-earth magnet arrays, exposing margins to raw material volatility.
- Hip Surgery:Acetabular component positioning and femoral stem alignment verification.
- Trauma Surgery:Fracture reduction and intramedullary nail placement guidance.
Knee surgery commands installed base. Spine surgery is gaining share fastest.
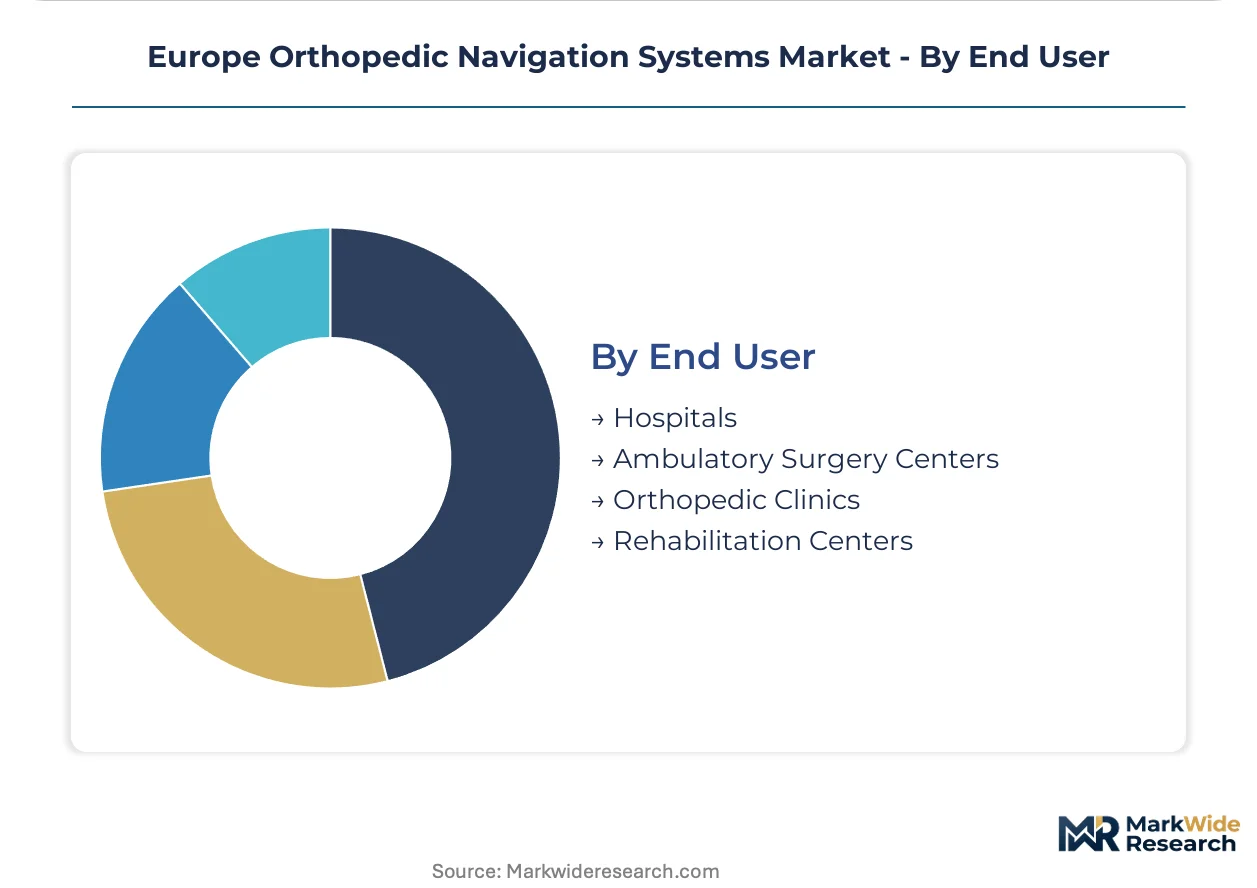
End User:
Customer type shapes contract structure, with capital ownership yielding to equipment-as-a-service models in non-hospital settings.
- Hospitals:Integrated delivery networks with dedicated biomedical engineering and PACS infrastructure. Legacy DICOM implementations running decade-old versions demand expensive middleware development for real-time navigation data feeds, extending deployment timelines. German and French reference centers concentrate specialized field engineers for electromagnetic system maintenance.
- Ambulatory Surgery Centers:Day-surgery facilities across France and Italy expanding navigation capability through leasing arrangements. Equipment-as-a-service contracts eliminate capital ownership burdens while transferring obsolescence risk to vendors. EU cohesion fund infrastructure investments are equipping regional orthopedic centers in Warsaw and Bucharest with first-generation navigation.
- Orthopedic Clinics:Specialist practices with focused joint replacement volume.
- Rehabilitation Centers:Post-acute facilities with navigation-assisted revision planning.
Hospitals retain installed capacity. Ambulatory surgery centers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's orthopedic navigation systems trade flows reflect concentrated production capacity in Germany and Switzerland against import dependency for specialized electromagnetic components from US and Japanese suppliers. The region's installed base expansion outpaces domestic manufacturing growth, creating persistent equipment trade deficits offset by software and service exports from Nordic vendors.
Germany
University hospitals in Berlin and Munich anchor demand for integrated knee and hip arthroplasty platforms through robotics programs that generate reference-site effects across Central European procurement networks. The EU MDR Article 10 clinical evidence requirements now mandate five-year post-market surveillance for navigation software updates, concentrating certification resources among deep-pocketed academic centers. Charité Berlin and Heidelberg University Hospital drive augmented reality adoption in teaching environments.
France
Day-surgery facilities in Paris and Lyon expand navigation capability through equipment-as-a-service contracts that eliminate capital ownership burdens. ANSM oversight of software-as-medical-device classifications creates compliance complexity for cloud-based planning platforms subject to GDPR data localization requirements. The Île-de-France region concentrates ambulatory surgery center leasing demand while Toulouse anchors electromagnetic system maintenance training.
United Kingdom
NHS England's specialized commissioning frameworks restrict navigation procurement to designated high-volume arthroplasty centers in London, Manchester, and Birmingham. MHRA post-Brexit regulatory divergence from EMA notified body procedures creates dual certification burdens for vendors seeking UK and EU market access. The Oxford-Cambridge corridor concentrates research collaborations between medical device developers and academic surgical units.
Netherlands
Amsterdam UMC and Erasmus MC Rotterdam anchor early augmented reality adoption through head-mounted display trials that eliminate optical camera array footprint constraints. EMA-aligned notified bodies in Utrecht face application backlogs exceeding eighteen months for MDR Class IIb device certifications, delaying CE marking timelines. The Randstad region concentrates per-procedure subscription contracting through regional procurement authorities.
Poland
EU cohesion fund infrastructure investments equip regional orthopedic centers in Warsaw and Kraków with first-generation navigation capability, creating greenfield installation demand absent legacy system replacement cycles. The national reimbursement framework lags Western European levels, restricting procurement to basic optical platforms rather than electromagnetic or hybrid systems. Warsaw's private hospital networks drive subscription-based access models for mid-tier facilities.
Europe Orthopedic Navigation Systems Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying coil arrays, infrared cameras, and disposable trackers to multiple OEMs. The vendor base organizes around three strategic archetypes: diversified medtech conglomerates bundling navigation with implant portfolios; pure-play navigation developers sustaining independence through software-centric revenue models; and imaging equipment manufacturers extending into surgical guidance. Competitive moves concentrate on M&A absorption of electromagnetic tracking startups and strategic partnerships between robotic platform holders and independent software vendors.
Within the diversified conglomerate tier, Stryker Corporation and Medtronic Plc occupy positions reflecting installed base leverage across European hospital networks. Stryker exemplifies platform bundling strategy through surgical robotics integration, while Medtronic anchors spine navigation workflows across Nordic procurement networks. Brainlab AG represents the independent software archetype, sustaining market presence through minimized hardware exposure and subscription-based delivery models that transfer utilization risk to provider customers.
| Leading Market Players |
|---|
| Stryker Corporation |
| Medtronic Plc |
| Zimmer Biomet Holdings Inc |
| B Braun SE |
| Brainlab AG |
| Siemens Healthineers AG |
| DePuy Synthes (Johnson & Johnson) |
| GE HealthCare Technologies Inc |
| CASCINATION |
| Others |
Cost & Logistics Intelligence
Rare-earth magnet price volatility determines both tier spreads in electromagnetic navigation platforms and the geographic shape of component sourcing across European orthopedic navigation. MDR compliance cost absorption concentrates procurement power among German university hospitals, compressing margins for mid-tier optical system vendors while rewarding deep-pocketed academic centers with volume-based pricing leverage.
Pricing Analysis
German university hospital procurement committees anchor a three-tier pricing structure across premium, standard, and economy levels in European orthopedic navigation. Price differentiation hinges on CE marking tier under MDR Article 10 and bundled after-sales service coverage, with premium electromagnetic platforms commanding substantial uplifts over optical alternatives. Cost compression in mid-tier optical systems intensifies because Polish and Romanian hospitals prioritize capital expenditure minimization over tracking accuracy. Ambulatory surgery centers in France and Italy exhibit the highest price sensitivity, while Nordic integrated delivery networks demonstrate lowest sensitivity due to per-procedure subscription models that transfer utilization risk to vendors.
Supply Chain Analysis
Single-source vulnerability for electromagnetic coil arrays dominates supply chain risk in European orthopedic navigation, with Japanese and US component manufacturers controlling rare-earth magnet processing. Manufacturing concentration centers on Germany and Switzerland for final system assembly, while optical infrared cameras draw from Taiwanese sensor foundries and German precision optics houses. Disposable tracker production hinges on neodymium magnet supply from Chinese processing facilities and specialized polymer housings from Italian molders. Distribution runs through regional procurement authorities in Sweden and Denmark for subscription-contracted platforms, alongside direct hospital sales for capital-purchase electromagnetic systems in Berlin and Munich academic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European orthopedic navigation represents a defensive-moat market where MDR regulatory entrenchment creates prohibitive switching costs for hospital customers locked into validated software workflows. Network effects concentrate among reference-site German university hospitals whose procurement decisions cascade through Central European hospital networks.
For Market Incumbents: Pre-empt augmented reality displacement by accelerating software porting to head-mounted display platforms before Amsterdam UMC and Charité Berlin adoption patterns diffuse to mid-tier centers. Secure backward integration into electromagnetic coil manufacturing to offset rare-earth magnet price volatility threatening margin stability in spine navigation applications. Consolidate maintenance technician training capacity in Toulouse and Zurich to close response-time gaps for Southern and Eastern European installations. For New Entrants and Emerging Players: Polish regional orthopedic centers present the most penetrable white-space opportunity, with EU cohesion fund infrastructure investments creating greenfield demand absent legacy optical system replacement cycles. Bucharest private hospital networks offer secondary entry through subscription-based access models that bypass capital committee approval barriers. Target electromagnetic tracking miniaturization for MRI-suite spine applications where line-of-sight constraints exclude established optical vendors. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors software-centric navigation developers with minimized hardware exposure and recurring revenue visibility. Five-to-ten-year viability rests on MDR certification asset values rather than pure technology differentiation, privileging targets with established notified body relationships over novel tracking modalities. Watch electromagnetic tracking startup acquisition activity by diversified medtech conglomerates as the inflection signal for platform bundling acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EMA-aligned notified body backlog compression in Germany and Netherlands unlocks software upgrade revenue recognition. |
| Hospital System Partnership | Karolinska University Hospital subscription models demonstrate per-procedure contracting viability across Nordic procurement networks. |
| Software Companion Development | AR-fluoroscopy convergence at Amsterdam UMC eliminates separate tracking hardware and compresses total procedure cost. |
| Backward Integration into Coil Arrays | Captive supply of electromagnetic trackers insulates margins from rare-earth magnet price volatility concentrated among three component manufacturers. |
| Reimbursement Strategy | ANSM software-as-medical-device classification alignment secures cloud-based planning platform access in French day-surgery facilities. |
Research Approach
Cross-validation between primary interviews with orthopedic surgeons, hospital biomedical engineers, GPO contracts managers, and notified body auditors anchors the qualitative findings in this study. Secondary validation draws from EMA MDR submission databases, hospital procurement records in Germany and France, CE marking registries, and Nordic regional authority contracting disclosures. Bottom-up demand modeling from installed base counts and replacement cycles triangulates against top-down market sizing from vendor revenue disclosures and trade flow analysis.
Calibration against historical adoption curves for optical-to-electromagnetic technology transitions shapes the analytical framework across the projection horizon. Segmentation dimensions span tracking modality, application type, end-user setting, and regional regulatory cluster. CAGRs derive from procedure volume elasticity to navigation penetration rates, weighted by MDR compliance cost pass-through assumptions and EU cohesion fund infrastructure investment schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified medtech conglomerates acquiring electromagnetic tracking startups would shift outcomes through accelerated platform bundling. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Non-Operative Spine Care Market
Orthopedic Devices
Saudi Arabia Spinal Surgery Devices Market
Orthopedic Devices
Orthopedic Wire Pin Driver Market
Orthopedic Devices
Vertebroplasty Needles Market
Orthopedic Devices
Animal External Fixation Market
Orthopedic Devices
Kyphoplasty Systems Market
Orthopedic Devices
Orthobiologics Market
Orthopedic Devices
Global Orthopedic Bone Cement Market
Orthopedic Devices
Medical Crutches Market
Orthopedic Devices
Personalized Orthopaedic Implant Market
Orthopedic Devices
Global Orthopedic Splints Market
Orthopedic Devices
Global Personalized 3D Printed Orthopedic Implants Market
Orthopedic Devices
France Neurology Devices Market
Orthopedic Devices
Orthopedic Support Systems Market
Orthopedic Devices
Cartilage Repair Market
Orthopedic Devices
Global Orthopedic Digit Implants Market