
 South Korea Nuclear Imaging Market | 2026-2036
South Korea Nuclear Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Nuclear Imaging Market Analytics
Equipment leasing and pay-per-scan service contracts is fragmenting the competitive landscape for high-cost hybrid imaging systems. Siemens Healthineers leverages its installed base of PET-CT platforms to sustain recurring service revenue across Seoul's academic medical centers. GE Healthcare anchors its position through backward integration into cyclotron-produced radiotracers, reducing supply chain exposure for Korean customers. Samyoung Unitech competes on localized maintenance networks, offering faster technician dispatch than multinational rivals.
South Korea nuclear imaging encompasses diagnostic modalities that detect gamma-ray or positron emissions from administered radiopharmaceuticals, with spatial resolution thresholds typically below 5 mm for PET systems and energy discrimination windows calibrated to technetium-99m at 140 keV. These technologies enable functional tissue characterization for disease detection, treatment monitoring, and surgical planning across clinical settings. Hybrid imaging systems combining PET with CT or MRI dominate capital expenditure flows, while radiopharmaceuticals represent the fastest-growing recurring revenue stream as therapeutic radioligands expand beyond diagnostic use. Oncology applications lead procedure volumes, though neurology segments for amyloid and tau imaging are gaining traction as aging demographics drive dementia workups.
MFDS regulates radiopharmaceutical manufacturing and clinical trial approvals under the Pharmaceutical Affairs Act, while KIRAMS oversees radiation safety standards and medical physicist certification for nuclear medicine departments. The Ministry of Health and Welfare's reimbursement decisions for new PET tracers directly shape hospital procurement timelines and patient access. Stakeholders must monitor how KAERI's domestic isotope production investments alter import dependency for molybdenum-99 and other critical raw materials.
Market Dynamics
MFDS accelerated approval pathways for novel radiotracers are compressing time-to-clinic and forcing incumbent vendors to restructure service delivery models around faster regulatory cycles.
Growth Catalysts
- Oncology Precision Staging:Tertiary hospitals in Seoul are expanding PET-CT utilization for tumor characterization, driving procedural volume growth in the metropolitan hospital cluster.
- Domestic Isotope Production:KAERI investments in molybdenum-99 production capacity are reducing import dependency and stabilizing radiopharmaceutical supply chains for Korean nuclear medicine departments.
- Dementia Imaging Demand:Aging demographics are accelerating amyloid and tau imaging workups, extending PET tracer applications beyond oncology into neurology segments.
Market Restraints
- Capital Equipment Costs:Hybrid imaging systems require substantial upfront investment, limiting procurement to tertiary institutions and constraining penetration into provincial hospitals.
- Radiotracer Supply Concentration:Cyclotron-produced isotopes depend on a small network of domestic production facilities, creating vulnerability to single-point failures in Seoul's radiopharmaceutical supply base.
- Technetium-99m Shortage Exposure:Reactor maintenance cycles at foreign molybdenum-99 sources periodically disrupt technetium generator availability for SPECT procedures.
Strategic Opportunities
- Busan-Ulsan Medical Corridor:Secondary metropolitan areas outside Seoul show underpenetrated PET-CT density, offering expansion targets for equipment leasing and pay-per-scan service models.
- Theranostic Convergence:Therapeutic radioligands paired with diagnostic tracers are opening recurring revenue streams beyond pure diagnostics, with lutetium-177 based therapies leading adoption.
- Regional Training Networks:KIRAMS certification expansion into provincial centers addresses medical physicist scarcity, enabling decentralized nuclear medicine service delivery.
Industry Challenges
- Medical Physicist Certification Bottleneck:KIRAMS examination capacity limits the pipeline of qualified personnel, delaying department commissioning and equipment utilization ramp.
- Reimbursement Lag for Novel Tracers:Ministry of Health and Welfare pricing committee decisions trail MFDS approvals by 12-18 months, compressing hospital margins on innovative radiopharmaceuticals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Nuclear Imaging Market |
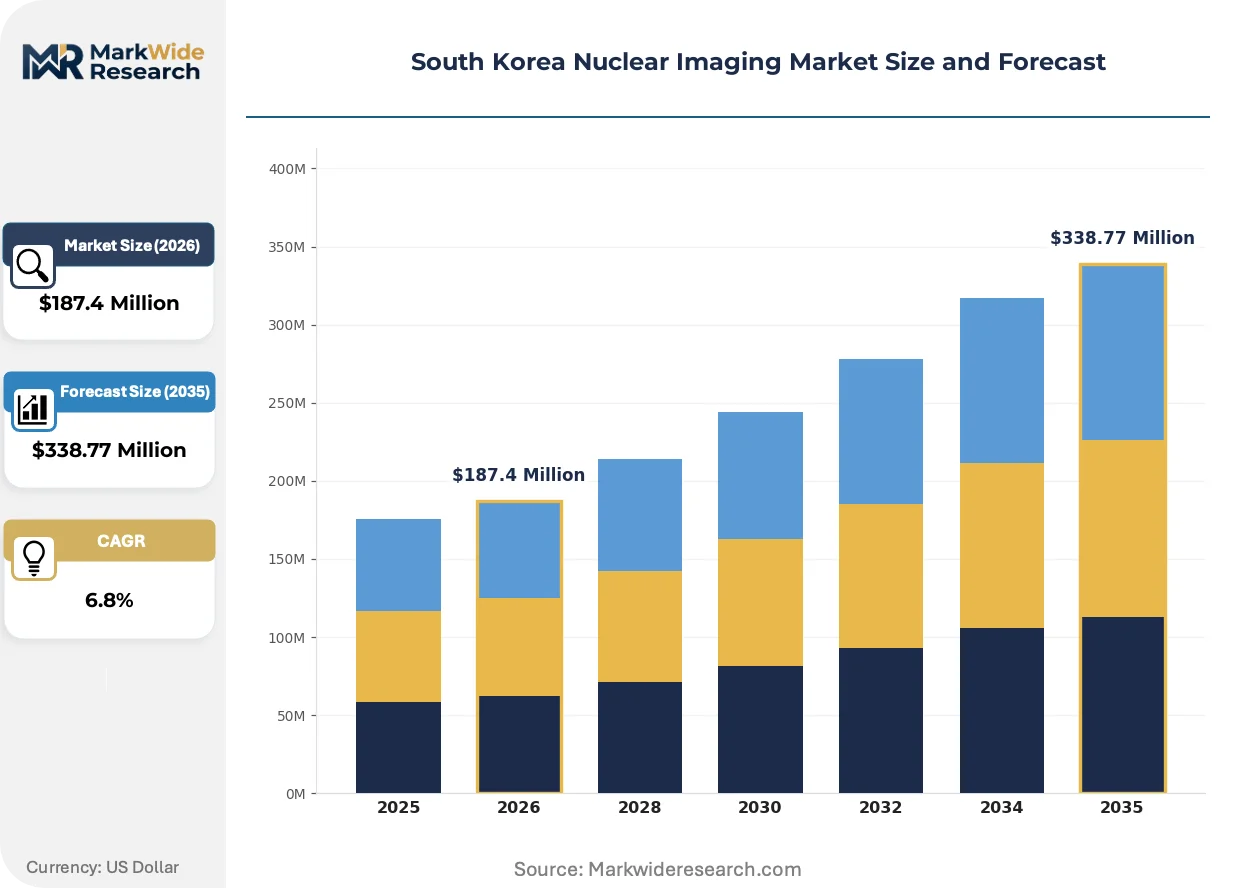
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Photon Emission Computed Tomography, Positron Emission Tomography, Hybrid Imaging Systems, Radiopharmaceuticals End User: Hospitals, Diagnostic Centers, Research Institutions, Imaging Clinics Technology: Analog, Digital, Advanced Imaging Software, Automated Systems Application: Oncology, Cardiology, Neurology, Thyroid Function |
| Companies Covered | GE Healthcare, Siemens Healthineers, Samyoung Unitech, IBA Radiopharma Solutions, FutureChem, NuCare Inc., KAERI (Korea Atomic Energy Research Institute), KIRAMS (Korea Institute of Radiological & Medical Sciences), DuChemBIO Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Nuclear Imaging Market Evolving Landscape
Artificial intelligence reconstruction algorithms and digital PET detector architectures are compressing scan times while improving signal-to-noise ratios, reshaping operational economics for high-volume departments.
Digital PET detector technology with silicon photomultiplier arrays is replacing conventional photomultiplier tubes, enabling improved time-of-flight resolution and reduced radiotracer dose requirements. Seoul's academic medical centers are adopting these platforms fastest, driven by research protocols demanding sub-5 mm spatial resolution. This hardware transition is virtualizing the distinction between diagnostic and research-grade imaging capabilities, allowing clinical departments to capture premium reimbursement while supporting investigator-initiated trials.
MFDS conditional approval pathways for radiopharmaceuticals are shortening pre-market clinical trial requirements for companion diagnostics paired with approved therapeutics. This regulatory compression allows tracer developers to reach commercial scale faster, though post-market surveillance obligations intensify. Oncology departments at tertiary hospitals are responding by expanding theranostic service lines, integrating diagnostic and therapeutic workflows under unified nuclear medicine divisions.
Equipment leasing and pay-per-scan contracts are displacing traditional capital purchase models for hybrid imaging systems, particularly among mid-sized hospitals seeking PET-CT capability without balance-sheet commitment. Siemens Healthineers and GE Healthcare are restructuring Korean sales organizations around service-based revenue, with local distributors like Samyoung Unitech competing on technician dispatch speed. This financing evolution concentrates most visibly in Seoul's metropolitan hospital cluster, where capital allocation discipline among competing institutions favors operational expenditure structures.
South Korea Nuclear Imaging Market Segmentation
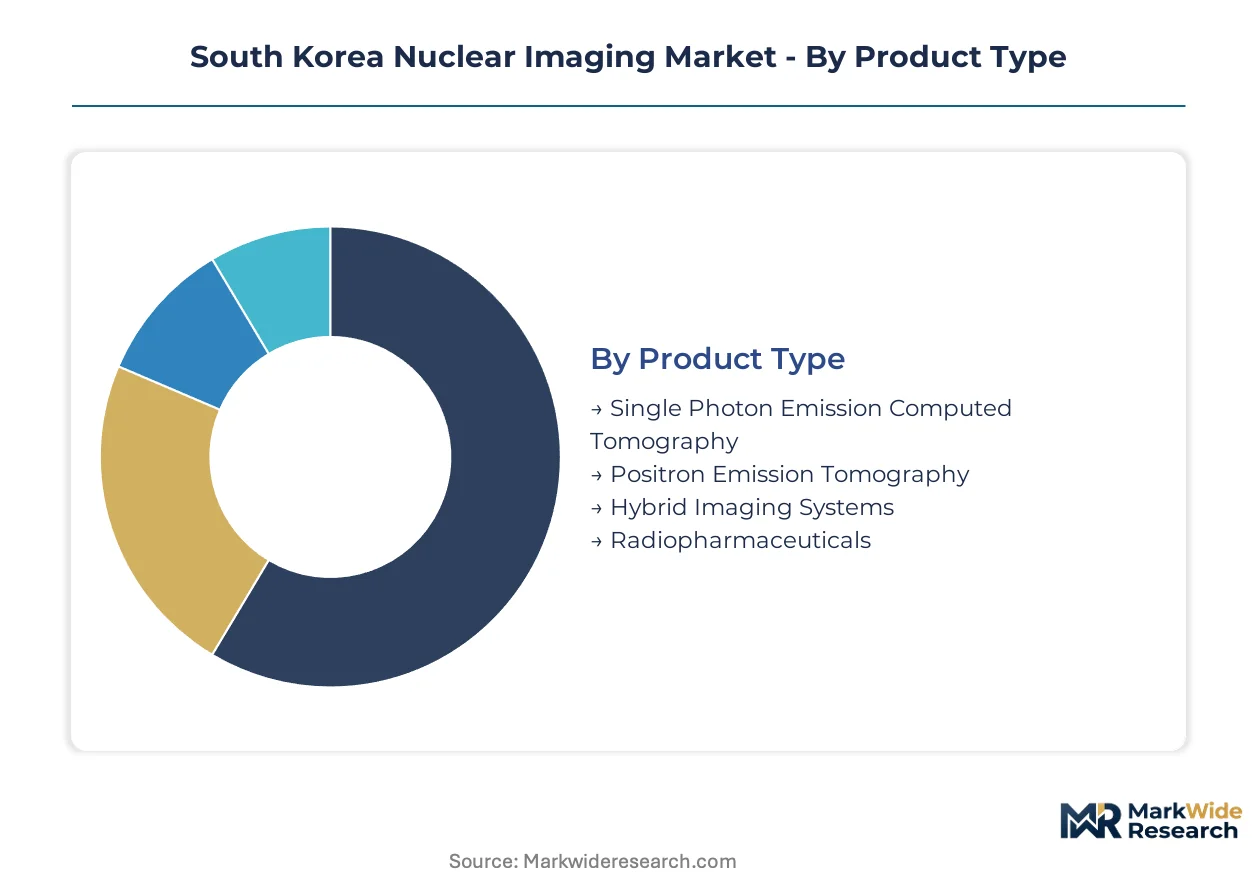
Segmentation reveals how capital flows diverge between equipment procurement and consumable replenishment cycles. Understanding these splits exposes where MFDS regulatory pressure reshapes competitive positioning and where Seoul's metropolitan hospital cluster concentrates purchasing power.
Product Type:
Use-case spectrum spans from standalone functional imaging to integrated anatomical-functional fusion systems, with recurring revenue models displacing capital-intensive ownership structures.
- Single Photon Emission Computed Tomography:Gamma camera systems detect technetium-99m emissions through rotating detector heads, with energy windows calibrated to 140 keV. Provincial hospitals outside Seoul rely on refurbished SPECT installations where capital constraints limit hybrid system procurement.
- Positron Emission Tomography:Ring-based detector arrays capture 511 keV annihilation photon pairs, achieving sub-5 mm spatial resolution with digital silicon photomultiplier architectures. Seoul's tertiary oncology departments drive demand for time-of-flight capable platforms supporting precision staging protocols.
- Hybrid Imaging Systems:PET-CT fusion dominates Seoul's academic medical centers where anatomical correlation improves lesion localization accuracy.
- Radiopharmaceuticals:Cyclotron-produced fluorodeoxyglucose and generator-derived technetium compounds constitute recurring procurement for nuclear medicine departments.
The dominant share belongs to Hybrid Imaging Systems, while Radiopharmaceuticals is closing the gap fastest through theranostic expansion.
End User:
Customer type stratification reflects reimbursement authorization tiers and capital allocation discipline across South Korea's healthcare infrastructure.
- Hospitals:Tertiary institutions in Seoul's metropolitan cluster anchor PET-CT installation bases, with pay-per-scan contracts penetrating mid-sized facilities seeking hybrid capability without balance-sheet commitment.
- Diagnostic Centers:Independent imaging operators concentrate in Seoul and Busan, competing on throughput velocity for routine SPECT procedures where MFDS licensing requirements create entry barriers.
- Research Institutions:KAERI-affiliated facilities and university hospitals pioneer novel tracer validation under accelerated MFDS approval pathways.
- Imaging Clinics:Specialized outpatient operators focus on thyroid function studies and cardiac stress testing with compact gamma camera configurations.
Hospitals command the installed base majority, though Diagnostic Centers are expanding most quickly through equipment leasing arrangements.
Technology:
Cost tier differentiation separates legacy analog installations from premium digital platforms commanding research-grade reimbursement premiums.
- Analog:Photomultiplier tube-based detector architectures persist in provincial facilities where replacement cycles lag Seoul's academic centers by several years.
- Digital:Silicon photomultiplier arrays enable improved time-of-flight resolution and reduced radiotracer dosing, with Seoul's metropolitan hospitals adopting these platforms fastest for precision oncology protocols.
- Advanced Imaging Software:AI reconstruction algorithms compress scan durations while enhancing signal-to-noise ratios, reshaping operational economics for high-volume departments.
- Automated Systems:Integrated radiopharmaceutical dispensing and patient positioning modules reduce technician exposure and protocol variability.
Digital platforms claim the technology leadership position, while Advanced Imaging Software is gaining share fastest through retrofit installations.
Application:
Volume concentration tracks disease burden demographics and reimbursement authorization patterns across South Korean clinical practice.
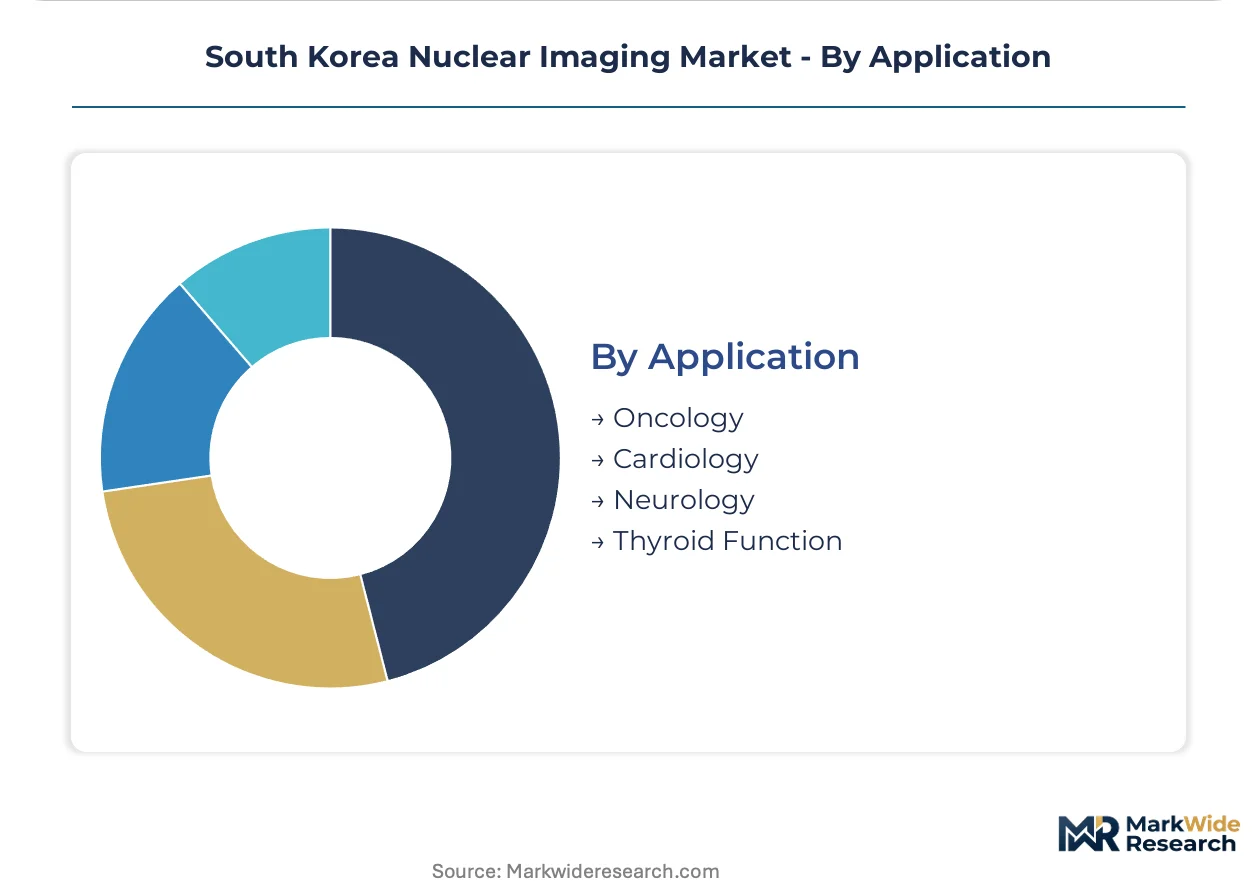
- Oncology:Tumor characterization, staging, and treatment response monitoring drive PET-CT procedural volumes, with lung and colorectal malignancies dominating tracer consumption at Seoul's tertiary institutions.
- Cardiology:Myocardial perfusion imaging with technetium-99m sestamibi constitutes the largest SPECT application segment, concentrated in hospital-based nuclear medicine departments.
- Neurology:Amyloid and tau imaging for dementia workups is extending PET applications beyond oncology as aging demographics accelerate diagnostic demand.
- Thyroid Function:Iodine-131 uptake studies and parathyroid scintigraphy represent established SPECT applications with stable procedural volumes.
Oncology holds the dominant application share, while Neurology is climbing the fastest as dementia imaging protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's nuclear imaging market operates as a net importer of raw isotopes while exporting finished radiopharmaceuticals and diagnostic services across East Asia. The country's trade balance reflects concentrated domestic production capacity against persistent dependency on foreign molybdenum-99 sources.
Seoul Capital Area
Seoul's metropolitan hospital cluster anchors national PET-CT installation density, with tertiary oncology departments driving procedural volumes for precision staging protocols. MFDS accelerated approval pathways for novel radiotracers compress regulatory timelines for Seoul-based research hospitals. Samsung Medical Center and Asan Medical Center operate the country's highest-throughput nuclear medicine divisions, integrating theranostic workflows under unified departmental structures.
Busan-Ulsan Medical Corridor
Secondary metropolitan demand for hybrid imaging systems is accelerating as pay-per-scan contracts penetrate mid-sized hospitals seeking PET-CT capability without capital commitment. Pusan National University Hospital anchors regional tracer distribution networks, reducing transit times for short-half-life isotopes. Equipment leasing models from Siemens Healthineers and GE Healthcare are displacing traditional purchase structures across Busan's independent diagnostic centers.
Daegu-Gyeongbuk
Provincial hospital networks in this southeastern region rely on refurbished SPECT installations where capital constraints limit hybrid system procurement. Kyungpook National University Hospital maintains the region's only academic nuclear medicine division with research-grade PET-MR capability. KIRAMS certification programs are expanding into Daegu to address medical physicist scarcity delaying department commissioning.
Daejeon-Sejong
KAERI's domestic isotope production investments concentrate in this central region, with reactor facilities targeting reduced import dependency for molybdenum-99 and technetium-99m generators. The Korea Institute of Radiological and Medical Sciences operates adjacent cyclotron complexes supplying fluorodeoxyglucose to national hospital networks. Sejong's administrative city status attracts MFDS regulatory staff co-location, streamlining radiopharmaceutical licensing workflows.
Gwangju-Honam
Southwestern provincial hospitals exhibit the lowest PET-CT density nationally, creating expansion targets for equipment leasing and service-based revenue models. Chonnam National University Hospital anchors regional nuclear medicine service delivery, with SPECT myocardial perfusion imaging dominating procedural volumes. Aging demographics in this rural-heavy region are accelerating dementia diagnostic demand, though amyloid tracer reimbursement lags Seoul's tertiary institutions by 18-24 months.
South Korea Nuclear Imaging Market Competitive Landscape
On the supply side, the industry is bifurcated between multinational imaging system manufacturers and domestic radiopharmaceutical specialists. Siemens Healthineers and GE Healthcare anchor the equipment tier through installed base expansion and service contract penetration, while Korean entities concentrate on tracer production and localized maintenance networks. Three strategic archetypes define competitive positioning: integrated hybrid imaging vendors, cyclotron-based radiopharmaceutical producers, and regional service specialists competing on technician dispatch velocity. Dominant competitive moves include backward integration into isotope production and restructuring sales organizations around recurring service revenue rather than capital equipment transactions.
Among multinational healthcare technology conglomerates, GE Healthcare and Siemens Healthineers occupy positions as archetypal integrated system vendors, leveraging global manufacturing scale against localized service commitments. Samyoung Unitech represents the domestic specialist archetype, competing on maintenance network density and faster technician response times than foreign rivals. IBA Radiopharma Solutions exemplifies the radiopharmaceutical production specialist, with cyclotron infrastructure positioning it within the tracer supply tier. These three entities collectively illustrate how competitive segmentation tracks capital intensity, with equipment ownership concentrating among multinationals while service and consumable revenue fragments across domestic players.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Samyoung Unitech |
| IBA Radiopharma Solutions |
| FutureChem |
| NuCare Inc. |
| KAERI (Korea Atomic Energy Research Institute) |
| KIRAMS (Korea Institute of Radiological & Medical Sciences) |
| DuChemBIO Co. Ltd |
| Others |
Value Network & Pricing Analysis
Daejeon-Sejong's KAERI reactor complex anchors domestic isotope production capacity, translating upstream supply security into downstream pricing leverage for Seoul's cyclotron operators against import-dependent competitors.
Pricing Analysis
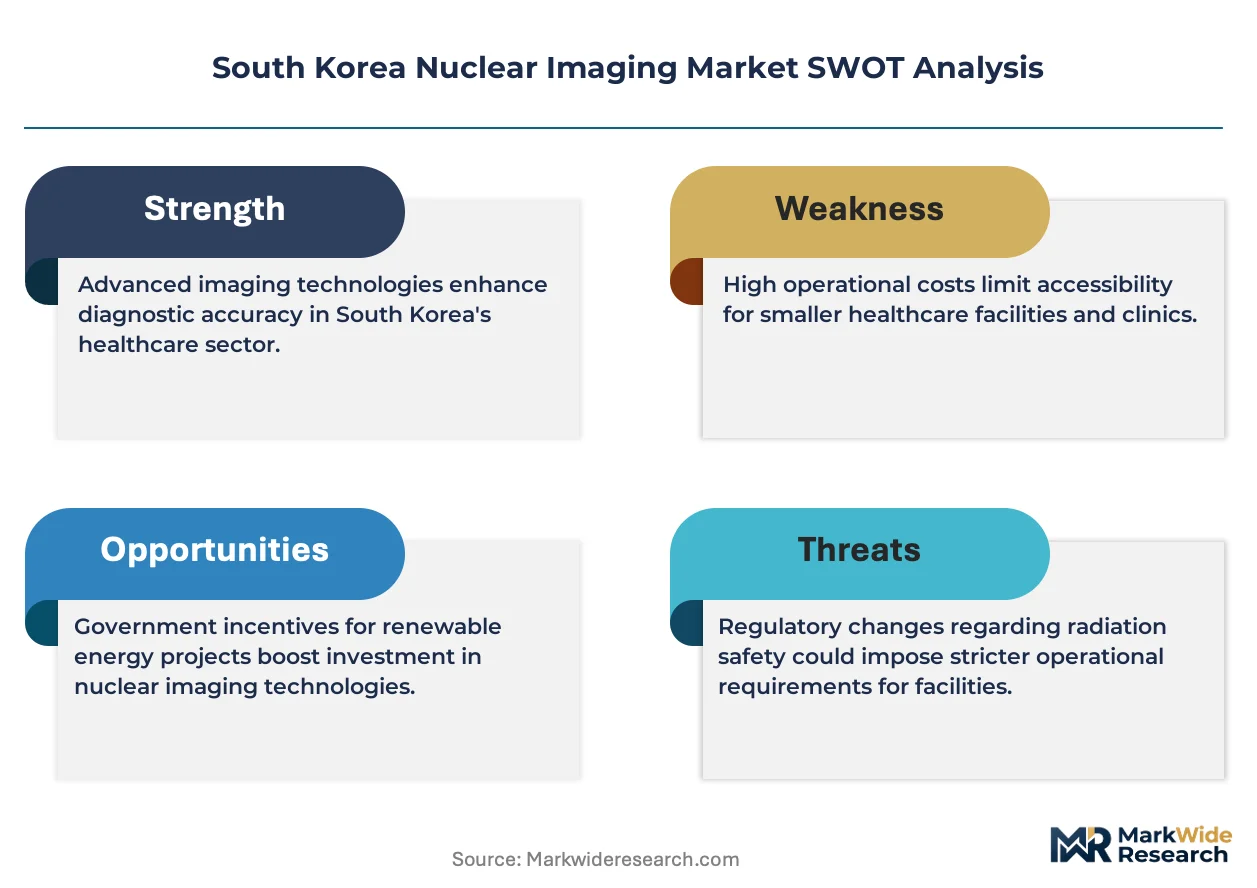
Tertiary hospital procurement committees anchor three-tier pricing structure across premium, standard, and economy levels for hybrid imaging systems. Price differentiation separates digital PET-CT platforms with silicon photomultiplier arrays from refurbished SPECT installations and entry-level gamma camera configurations. Cost compression in the standard tier is intensifying because equipment leasing models displace capital purchases. Provincial hospitals outside Seoul's metropolitan cluster exhibit highest price sensitivity, while academic medical centers prioritize resolution specifications over acquisition cost.
Supply Chain Analysis
Export-control regimes on high-purity germanium and specialized scintillation crystals limit detector component flows to Korean manufacturers. Supply concentrates in Germany, Japan, and the United States for precision detector arrays, while cyclotron-produced fluorodeoxyglucose draws from domestic KIRAMS facilities and Belgian import channels. Raw material dependencies include molybdenum-99 for technetium generators, lutetium-177 for theranostic therapies, and enriched uranium for research reactor fuel. Single-source vulnerability at Seoul's radiopharmaceutical production cluster creates supply chain risk. Distribution runs through hospital-integrated nuclear medicine departments and regional diagnostic center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive-moat story anchored in regulatory entrenchment. MFDS licensing requirements and KIRAMS medical physicist certification create structural barriers that protect incumbent service revenue streams.
For Market Incumbents: Build switching-cost moats through embedded service contracts and proprietary radiotracer formulation libraries. Siemens Healthineers and GE Healthcare should deepen backward integration into cyclotron infrastructure to secure isotope supply against KAERI capacity expansion. Consolidation moves should target provincial maintenance networks where Samyoung Unitech holds technician density advantages. Threat from pay-per-scan financing models demands response through outcome-based pricing structures. For New Entrants and Emerging Players: Busan-Ulsan's underpenetrated PET-CT density offers white-space expansion targets outside Seoul's saturated hospital cluster. Secondary metropolitan areas lack time-of-flight capable platforms for precision oncology staging. Gwangju-Honam's aging demographics accelerate dementia imaging demand where amyloid tracer reimbursement lags. Go-to-market angle should emphasize equipment leasing partnerships with mid-sized hospitals seeking hybrid capability without balance-sheet commitment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors radiopharmaceutical specialists with cyclotron infrastructure over capital-intensive equipment manufacturers. Long-term viability across the analysis window hinges on theranostic convergence expanding addressable market beyond diagnostics. Acquisition target archetype includes domestic tracer producers with MFDS approval track records and established hospital distribution relationships. Signal to watch is Ministry of Health and Welfare reimbursement committee acceleration for novel PET tracers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cyclotron Infrastructure | Captive isotope production reduces supply chain exposure to foreign molybdenum-99 reactor maintenance cycles. |
| Pay-per-Scan Service Contract Expansion | Equipment leasing models penetrate mid-sized hospitals in Busan-Ulsan corridor seeking PET-CT without capital commitment. |
| KIRAMS Medical Physicist Certification Investment | Addressing personnel scarcity enables faster department commissioning and equipment utilization ramp across provincial centers. |
| Theranostic Workflow Integration | Unified diagnostic-therapeutic service lines capture recurring revenue from lutetium-177 based radioligand therapies. |
| Digital PET Detector Platform Upgrade | Silicon photomultiplier arrays command research-grade reimbursement premiums while reducing radiotracer dose requirements. |
Research Methodology
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings. Nuclear medicine department heads, hospital procurement managers, biomedical engineers at tertiary institutions, and cyclotron facility operators provided operational perspective. Secondary sources include MFDS radiopharmaceutical approval databases, KIRAMS certification records, hospital procurement disclosures, and Korea Customs Service trade data for isotope imports. Bottom-up procedure volume estimates triangulate against top-down equipment installation base analysis.
Calibration against historical PET-CT shipment data and radiotracer consumption patterns validates projection assumptions across the analysis window. Segmentation dimensions encompass product type, end-user category, technology tier, and application area with geographic stratification by metropolitan hospital cluster. CAGRs derive from equipment replacement cycles, reimbursement expansion trajectories, and demographic disease burden modeling. Industry-specific inputs include KAERI reactor capacity expansion timelines and MFDS accelerated approval pathway utilization rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by multinational imaging vendors into cyclotron-based tracer production would shift outcomes. Material shifts in Ministry of Health and Welfare reimbursement policy or KIRAMS certification capacity expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Radiology Services Market
Medical Imaging
Mobile Computed Tomography Scanners Market
Medical Imaging
US Magnetic Resonance Angiography Market
Medical Imaging
PACS and RIS Market
Medical Imaging
Portable X-Ray Devices Market
Medical Imaging
C-Arms Market
Medical Imaging
Mexico Mammography Market
Medical Imaging
Dental Digital X Ray Market
Medical Imaging
Radiology As a Service Market
Medical Imaging
Ultrasound Imaging Solution Market
Medical Imaging
AI Capsule Endoscopy Reading Platform Market
Medical Imaging
South Africa Computed Tomography Market
Medical Imaging
Global Medical Imaging Workstation Market
Medical Imaging
Automated Contouring Radiotherapy Software Market
Medical Imaging
Digital Pathology Market
Medical Imaging
France Digital X-Ray Devices Market