
 Fluid and Blood Warmer Market | 2026-2036
Fluid and Blood Warmer Market Size, Share, and Industry Trends Forecast 2026-2036
Fluid and Blood Warmer Market Analysis
Emergency services is collapsing the traditional hospital-centric procurement model for fluid and blood warmers as pre-hospital trauma protocols mandate thermal management during transport. Stryker Corporation leverages its emergency care portfolio to anchor pre-hospital placements across North American ambulance fleets. Smiths Medical competes through deep specialization in disposable warmer configurations that reduce cross-contamination risk in high-turnover settings. Barkey GmbH & Co. KG dominates European hospital installations with conductive heating platforms engineered for cardiac surgery suites.
Fluid and blood warmers are electromechanical devices that maintain intravenous fluids, blood products, and irrigation solutions within a narrow therapeutic temperature band, typically 37°C to 41°C, using conductive, resistive, or forced-air thermal transfer mechanisms to prevent hypothermia-induced coagulopathy and patient distress during infusion. Their primary commercial purpose centers on reducing perioperative complications, transfusion reactions, and recovery times across surgical and trauma interventions. Disposable warmers now lead product type dynamics because infection control committees prioritize single-patient-use disposables over reusable cabinet systems that require sterilization validation. Forced air heating technology sustains the fastest expansion trajectory among warming modalities as manufacturers engineer lighter, battery-powered field units for emergency services and military medicine applications.
FDA 510(k) clearance requirements and updated ISO 80601-2-35 standards for warming device electrical safety shape product development timelines and market access barriers for new entrants. The EU Medical Device Regulation imposes additional clinical evidence burdens on conductive heating platforms seeking CE marking for blood product applications. Stakeholders must monitor evolving battery chemistry regulations and transport-device electromagnetic compatibility standards as pre-hospital deployment expands beyond traditional hospital electrical infrastructure.
Market Dynamics
The pre-hospital emergency services segment is collapsing the traditional hospital-centric procurement model for fluid and blood warmers as trauma protocols mandate thermal management during patient transport.
Growth Catalysts
- EU Medical Device Regulation:The MDR's stricter clinical evidence requirements for blood product warming devices are accelerating product refresh cycles and replacement demand across European hospital systems.
- Hypothermia prevention protocols:Emergency medical services in the United States, Germany, and Japan are mandating active warming during ground and air transport, expanding addressable demand beyond operating rooms.
- Battery chemistry advances:Lithium-ion and solid-state battery improvements are enabling portable forced-air warmers that operate independently of vehicle electrical systems.
Market Restraints
- Conductive heating component concentration:Precision heating elements and temperature sensors concentrate supply among Japanese and German component specialists, creating input vulnerability.
- ISO 80601-2-35 compliance costs:Electrical safety testing and documentation for warming device standards impose six-figure certification burdens that disadvantage smaller manufacturers.
- Reusable cabinet sterilization validation:Central sterile processing departments face rising labor and documentation costs for reusable warmer systems, compressing margins on legacy product lines.
Strategic Opportunities
- Military medicine applications:Armed forces medical corps in NATO member states are procuring ruggedized battery-powered warmers for forward surgical teams and casualty evacuation platforms.
- India trauma system investment:The country's national highway trauma network expansion creates first-mover positioning for manufacturers establishing local distribution and service infrastructure.
- Disposable warmer rental models:Equipment-as-a-service pricing for high-turnover ambulance fleets converts capital expenditure to operational budgets, reducing customer acquisition friction.
Industry Challenges
- Biomedical engineering talent scarcity:The intersection of thermal engineering, battery management systems, and medical device regulatory expertise concentrates among a small pool of specialists in Boston, Stuttgart, and Tokyo metropolitan clusters.
- Legacy hospital IT integration:Newer connected warmers with temperature logging and alert capabilities require integration with electronic health record systems, stretching implementation timelines and technical support resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluid and Blood Warmer Market |
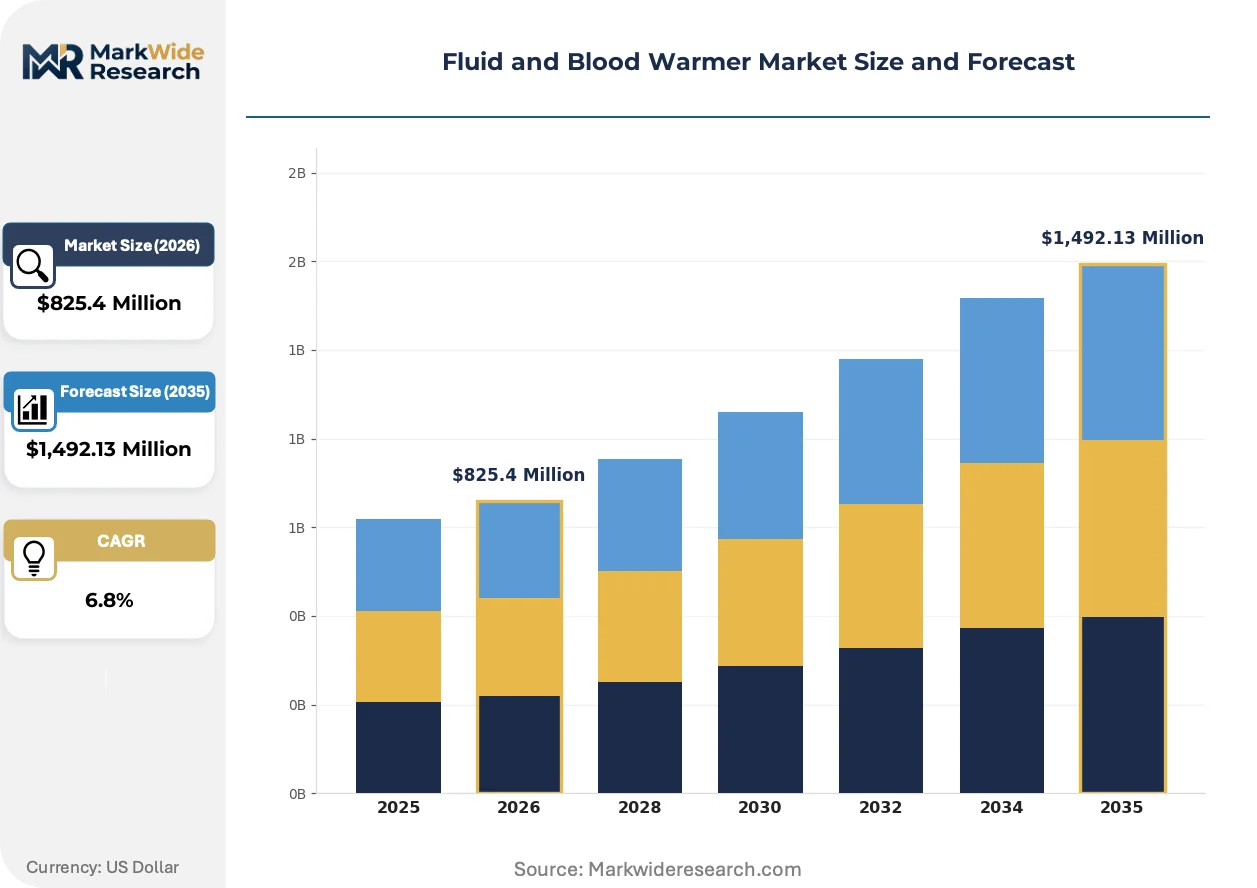
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,492.13 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Warming Cabinets, Disposable Warmers, Intravenous Warmers, Blood Warmers End User: Hospitals, Emergency Services, Outpatient Clinics, Surgical Centers Technology: Conductive Heating, Resistive Heating, Microwave Technology, Forced Air Heating Application: Surgery, Trauma Care, Blood Transfusion, Anesthesia |
| Companies Covered | 3M Company, Belmont Medical Technologies, Stryker Corporation, Smiths Medical, GE Healthcare, GENTHERM, Becton, Dickinson and Company, Barkey GmbH & Co. KG, ICU Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluid and Blood Warmer Market Emerging Trajectories
Forced-air warming technology is displacing conductive and resistive platforms as the dominant thermal transfer mechanism across pre-hospital and military applications.
Battery-powered forced-air warmers are displacing conductive heating plates in emergency medical services vehicles. Ambulance operators in the United States and Germany are standardizing lightweight portable units that maintain 37°C to 41°C output without vehicle inverter dependence. This shift is displacing heavier conductive systems that required fixed installation and electrical infrastructure, compressing the addressable market for cabinet-style reusable warmers.
Updated ISO 80601-2-35 standards for warming device electrical safety are tightening leakage current limits and electromagnetic compatibility requirements. Manufacturers must redesign power supply architectures and shielding to meet amended testing protocols. Pre-hospital portable warmers face the steepest redesign burden, as battery-powered devices must demonstrate equivalent safety margins to mains-connected hospital units.
Hospital purchasing committees are unbundling warmer acquisition from disposable set contracts, reversing a decade of bundled procurement. Materials management departments now negotiate warmer hardware and single-use sets as separate line items, enabling competitive substitution of disposable suppliers. This pattern is most visible in German and Japanese university hospital systems with centralized procurement functions.
Fluid and Blood Warmer Market Segmentation
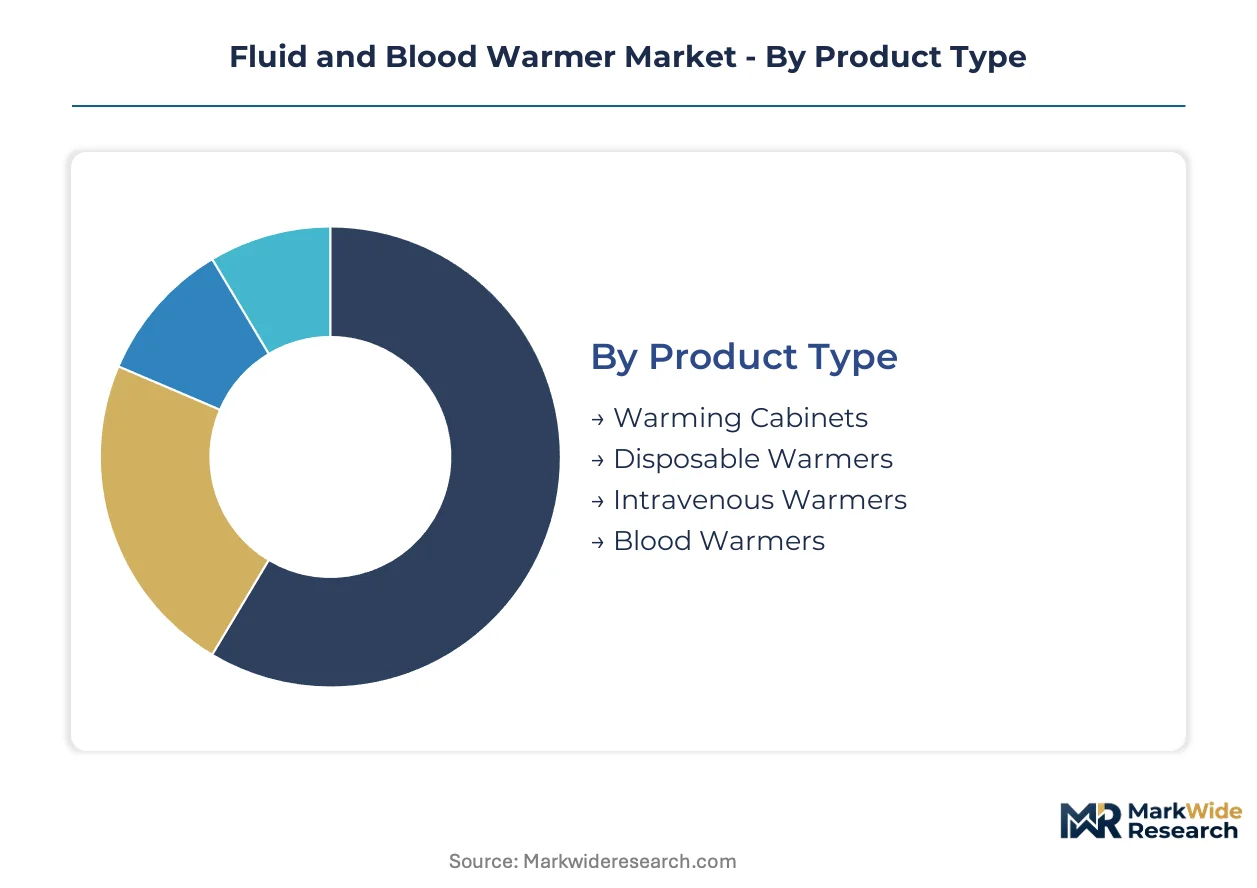
Product configuration decisions in the fluid and blood warmer market hinge on infection control priorities, power infrastructure constraints, and procedural throughput requirements. Segment boundaries are blurring as portable forced-air systems penetrate hospital settings while disposable configurations displace reusable cabinets in high-turnover environments.
Product Type:
Substitution pressure runs strongest against warming cabinets as disposable warmers eliminate sterilization validation burdens and cross-contamination risks in emergency workflows.
- Disposable Warmers:Single-patient-use devices incorporating integrated heating elements and temperature sensors eliminate central sterile processing requirements. Demand concentrates in United States ambulance fleets and German emergency medical services where rapid patient turnover and infection control protocols prioritize elimination of reusable components.
- Warming Cabinets:Stationary conductive heating units maintaining multiple fluid bags at therapeutic temperatures through precision-controlled warming plates. German university hospitals and Japanese surgical centers retain these systems for cardiac surgery suites where simultaneous warming of multiple blood products remains operationally critical.
- Intravenous Warmers:In-line devices positioned between infusion bags and patient access points, delivering point-of-use warming without bulk storage requirements.
- Blood Warmers:Specialized high-flow units engineered for rapid transfusion scenarios, incorporating advanced temperature feedback loops to prevent hemolysis.
Disposable warmers anchors the volume base while warming cabinets gains share at the steepest rate in cost-sensitive outpatient settings seeking capital expenditure avoidance.
End User:
Customer procurement authority is fragmenting as emergency services departments gain independent budget lines previously controlled by hospital materials management.
- Emergency Services:Ground and air ambulance operators, military medical evacuation platforms, and disaster response teams requiring battery-independent thermal management. United States trauma system investments and NATO armed forces medical modernization programs are expanding deployments beyond traditional hospital boundaries.
- Hospitals:Operating rooms, emergency departments, and intensive care units with established electrical infrastructure and biomedical engineering support. Japanese tertiary centers and German cardiac surgery departments maintain the highest per-facility warmer density due to complex procedural volumes.
- Outpatient Clinics:Ambulatory surgical and infusion centers with lower throughput and constrained capital budgets.
- Surgical Centers:Specialized facilities prioritizing rapid turnover and streamlined supply chains over comprehensive warming capabilities.
Hospitals retain the installed base majority while emergency services climbs the fastest as pre-hospital trauma protocols mandate active warming during transport.
Technology:
Technology selection trade-offs center on warming speed, power autonomy, and electromagnetic compatibility with patient monitoring systems.
- Forced Air Heating:Convective thermal transfer using heated air streams directed through disposable blankets or warming chambers. Battery-powered portable units are penetrating United States and German ambulance fleets where vehicle electrical independence and rapid deployment speed override conductive warming precision.
- Conductive Heating:Direct surface contact warming through precision-engineered heating plates and thermal exchange surfaces. German Barkey installations and Japanese cardiac surgery suites favor this modality for blood product applications requiring exact temperature maintenance without air turbulence.
- Resistive Heating:Electrical resistance elements embedded in warming surfaces or fluid lines, offering simplicity but slower thermal response.
- Microwave Technology:Electromagnetic warming of fluid volumes, limited by uneven heating patterns and regulatory constraints on blood product applications.
Conductive heating anchors the volume base in hospital settings while forced air heating expands most quickly across pre-hospital and military applications.
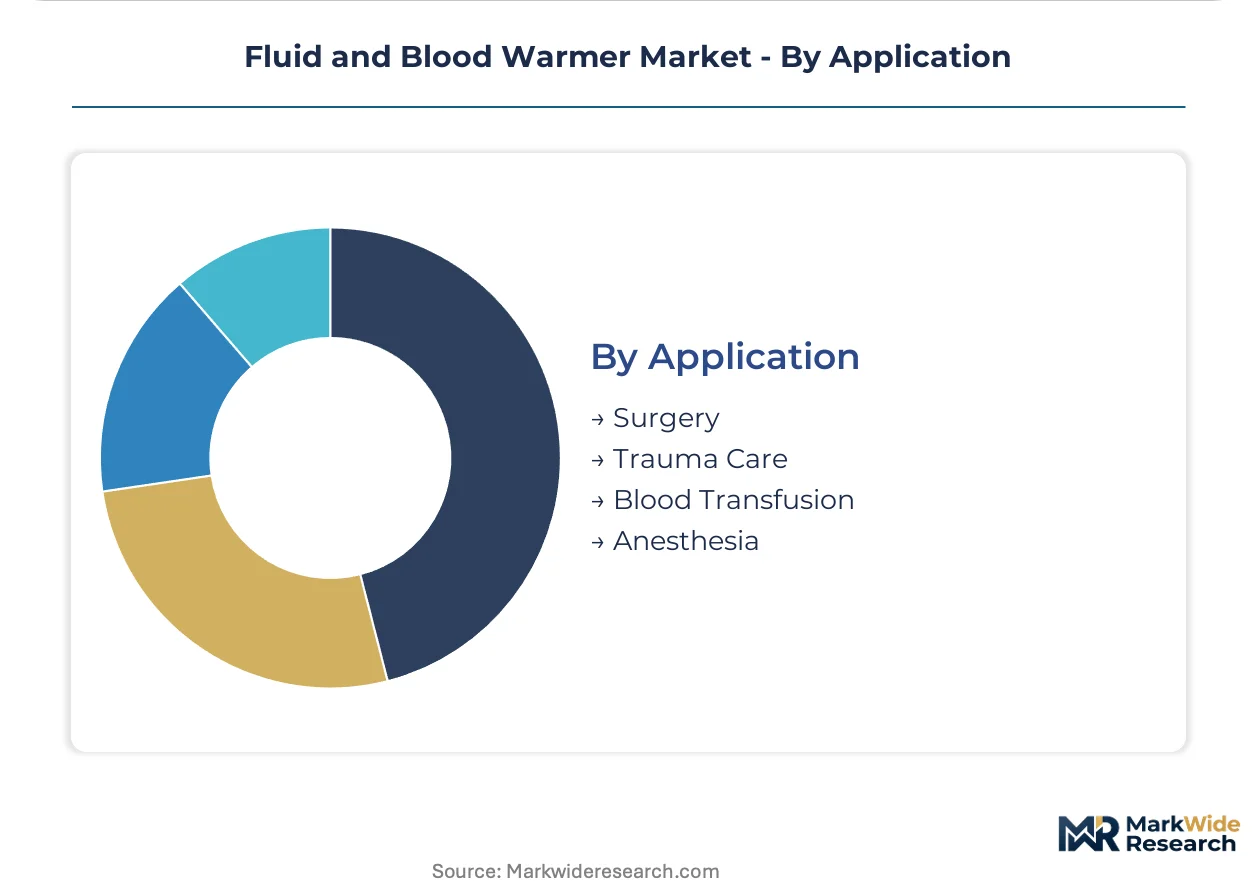
Application:
Application-specific warming requirements diverge on flow rate demands, temperature precision, and integration with procedural workflows.
- Surgery:Perioperative fluid and blood warming preventing hypothermia-induced coagulopathy during prolonged procedures. German and Japanese cardiac and orthopedic surgical volumes drive demand for high-capacity warming systems with integrated monitoring capabilities.
- Trauma Care:Rapid thermal intervention for hypothermic patients in hemorrhagic shock, requiring portable high-flow warming independent of fixed infrastructure. United States emergency medical services and military forward surgical teams prioritize battery-powered forced-air solutions for field deployment.
- Blood Transfusion:Controlled warming of refrigerated blood products to physiological temperature prior to infusion, with strict hemolysis prevention protocols.
- Anesthesia:Maintenance of patient core temperature during sedation, typically employing lower-flow warming adjuncts to primary surgical warming systems.
Surgery anchors the volume base while trauma care demonstrates the steepest expansion trajectory as pre-hospital warming mandates extend beyond hospital walls.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States interstate highway trauma network and Germany's autobahn rescue system anchor emergency medical infrastructure that underwrites regional demand for portable warming systems. Japan's Shinkansen medical emergency protocols and India's Golden Quadrilateral highway trauma investments expand addressable deployment beyond traditional hospital settings.
United States
FDA 510(k) clearance pathways accelerate product refresh cycles for emergency medical services procurement. The Department of Transportation mandates active warming during air ambulance transport under revised trauma care guidelines. Boston's biomedical engineering cluster concentrates talent for battery-powered forced-air warmer development.
Germany
EU Medical Device Regulation imposes stricter clinical evidence requirements on conductive heating platforms seeking CE marking. The autobahn rescue system operates 700 helicopter landing sites with standardized thermal management protocols. Stuttgart's precision engineering base supplies temperature sensor components to domestic warmer manufacturers.
Japan
PMDA regulatory updates align with ISO 80601-2-35 electrical safety standards for warming devices. METI trauma system investments target pre-hospital thermal management during Shinkansen medical emergencies. Tokyo metropolitan hospital networks maintain the highest per-facility warmer density for cardiac surgery applications.
India
CDSCO medical device registration requirements are harmonizing with international standards for blood product warming equipment. The national highway trauma network expansion along the Golden Quadrilateral creates distribution infrastructure for field-deployable units. Maharashtra's medical device manufacturing zone attracts assembly operations for disposable warmer production.
United Kingdom
MHRA post-Brexit regulatory framework maintains alignment with EU MDR for warming device approvals. NHS ambulance trusts are standardizing battery-independent warmers for rural response vehicles. London's university hospital procurement consortium negotiates unbundled warmer and disposable set contracts.
Fluid and Blood Warmer Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and regulatory navigation capabilities. The vendor base concentrates among diversified medical technology conglomerates and focused thermal management specialists. Three archetypes dominate: emergency care portfolio builders, disposable component specialists, and precision conductive heating engineers. Competitive moves center on pre-hospital placement expansion and unbundled procurement positioning.
Within the emergency care portfolio tier, Stryker Corporation and Smiths Medical exemplify contrasting strategic positions. Stryker anchors North American ambulance fleet placements through integrated emergency care bundling. Smiths Medical occupies a specialist position in disposable warmer configurations that reduce cross-contamination documentation burdens. Barkey GmbH & Co. KG represents the precision conductive heating archetype with European hospital installation concentration.
| Leading Market Players |
|---|
| 3M Company |
| Belmont Medical Technologies |
| Stryker Corporation |
| Smiths Medical |
| GE Healthcare |
| GENTHERM |
| Becton, Dickinson and Company |
| Barkey GmbH & Co. KG |
| ICU Medical |
| Others |
Supply Flow & Price Mechanics
Battery chemistry migration from nickel-metal hydride to lithium-ion and solid-state configurations simultaneously redistributes component sourcing toward East Asian cell manufacturers and compresses per-unit power costs for portable forced-air warmers. This substitution dynamic weakens pricing power for legacy conductive heating platforms while elevating procurement leverage for emergency services buyers negotiating volume contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement negotiations, with differentiation anchored in FDA 510(k) clearance tier and ISO 80601-2-35 electrical safety certification grade. German university hospitals and Japanese cardiac surgery centers absorb premium pricing for precision conductive systems, while United States ambulance fleets drive cost compression through competitive bidding for battery-powered disposable configurations. Pricing pressure stems from unbundled procurement patterns that separate warmer hardware from disposable set contracts, enabling competitive substitution. Emergency services departments exhibit highest price sensitivity due to constrained municipal budgets, whereas cardiac surgery suites demonstrate lowest sensitivity given procedural criticality.
Supply Chain Analysis
Strait of Malacca transit underwrites precision temperature sensor supply chains feeding German and Japanese warmer manufacturers, creating vulnerability to maritime disruption. Component sourcing concentrates in Japan for heating elements, Germany for thermal sensors, and South Korea for lithium-ion battery cells. Raw material dependencies span rare-earth magnets for motor assemblies, platinum-group coatings for heating surfaces, and medical-grade polymers for disposable warming chambers. Single-source vulnerability concentrates in Japanese temperature sensor specialists supplying Barkey and domestic cardiac surgery equipment makers. Distribution runs through hospital GPOs and emergency services procurement consortiums in North America, with direct manufacturer relationships dominating European hospital installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat defense where FDA 510(k) clearance history and ISO 80601-2-35 electrical safety certification create switching costs that entrench incumbents against unproven entrants. Network effects concentrate among biomedical engineering talent pools in Boston, Stuttgart, and Tokyo metropolitan clusters.
For Market Incumbents: Fortify pre-hospital placement density through equipment-as-a-service rental models that convert ambulance fleet capital expenditure to operational budgets, locking out competitors. Deepen backward integration into lithium-ion battery pack assembly to capture margin compression from cell suppliers and accelerate portable product refresh cycles. Prioritize ISO 80601-2-35 certification maintenance as emerging solid-state battery chemistries trigger redesign requirements. For New Entrants and Emerging Players: Lead with disposable warmer specialization targeting India's Golden Quadrilateral highway trauma network expansion, where first-mover distribution infrastructure remains unclaimed. Exploit unbundled procurement patterns in German university hospital systems to substitute premium conductive systems with standard-tier forced-air alternatives. Anchor go-to-market strategy through military medicine procurement channels in NATO member states, where ruggedization requirements filter out established hospital-centric competitors. For Investors and Strategic Acquirers: The market sits at a product-refresh acceleration phase that favors specialist manufacturers with regulatory navigation capabilities over diversified conglomerates with legacy reusable cabinet exposure. Long-term viability centers on battery chemistry adaptability and pre-hospital channel control rather than hospital installed base maintenance. Acquisition target archetype: mid-cap disposable warmer specialists with CE marking and FDA 510(k) clearances in place. Monitor solid-state battery commercialization timelines as inflection indicator for next-generation portable warmer deployment economics.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Accelerates emergency services procurement eligibility for battery-powered forced-air warmers in United States trauma networks. |
| CE Marking Pathway under EU MDR | Unlocks conductive heating platform placements in German autobahn rescue helicopter installations requiring clinical evidence compliance. |
| Hospital System Partnership | Secures unbundled contract positioning for disposable warmers in Japanese university hospital procurement consortiums. |
| Software Companion Development | Enables EHR integration for temperature logging capabilities that stretch implementation timelines but lock in technical support revenue. |
| Reimbursement Strategy | Aligns pre-hospital warming protocols with United States Department of Transportation trauma care guideline mandates. |
Methodological Framework
The analysis maps forced-air warming systems, conductive heating platforms, disposable warmer configurations, and battery-powered portable units, each validated through hospital purchasing committee interviews, emergency services procurement officers, biomedical engineering directors, and GPO contracts managers. Primary fieldwork combined with secondary validation against FDA 510(k) clearance databases, ISO standards documentation, EU MDR technical file submissions, and hospital procurement database extracts. Bottom-up unit deployment estimates triangulated against top-down surgical volume and trauma system investment data across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including surgical procedure databases, trauma system capital expenditure disclosures, and military medical modernization program budgets. The analytical framework modeled product type, technology modality, end-user segment, and application across the projection horizon, with CAGRs derived from procedure volume elasticity and replacement cycle compression. Forecast inputs incorporated battery chemistry cost curves, regulatory clearance timeline distributions, and unbundled procurement adoption rates.
The analysis sits within stated boundaries; outcomes outside sustained trauma system investment levels, stable battery chemistry regulatory frameworks, and continued ISO 80601-2-35 electrical safety standard enforcement would require recalibration. Forecasts reflect documented assumptions regarding procedure volume growth and pre-hospital protocol adoption. Practitioners should keep alternative scenarios live as EU MDR clinical evidence requirements, solid-state battery commercialization timelines, and India trauma network deployment pace evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ophthalmic Ultrasound Devices Market
Medical Devices
Automatic Clotting Timer Systems Market
Medical Devices
Digital Orthodontics Market
Medical Devices
Medical Device Coating Market
Medical Devices
Global Stroke Assistive Devices Market
Medical Devices
Global Tympanostomy Products Market
Medical Devices
Needle-Free Injectors Market
Medical Devices
Intracranial Stents Total Addressable Market
Medical Devices
Illuminating Eye Massagers Market
Medical Devices
Massage Equipment Market
Medical Devices
North America and Europe Medical Technology Market
Medical Devices
Capnography Devices Market
Medical Devices
Left Atrial Appendage (LAA) Closure Device Market
Medical Devices
Phakic Intraocular Lenses (IOL) Market
Medical Devices
Sleep Apnea Devices Market
Medical Devices
Partial Ossicular Replacement Prosthesis Market