
 Controlled Substance Market | 2026-2036
Controlled Substance Market Size, Share, and Industry Trends Forecast 2026-2036
Controlled Substance Market Analysis
Pain management protocols in hospital settings is expanding as perioperative care standards tighten and multimodal analgesia gains institutional backing. Pfizer Inc. leverages its manufacturing scale to sustain DEA quota allocations for Schedule II opioid APIs. Teva Pharmaceutical Industries Ltd. competes through vertical integration into generic controlled substance production. Johnson & Johnson anchors its position via specialized hospital formulary contracts for transdermal delivery systems.
Controlled substances comprise chemically defined compounds regulated under national and international scheduling frameworks based on abuse potential, medical utility, and safety profiles, with manufacturing governed by strict batch tracking, dual-lock storage, and chain-of-custody documentation. Opioids remain the dominant product type by revenue, though stimulants for ADHD treatment represent the fastest-growing category as diagnostic thresholds broaden in pediatric and adult populations. Injectable delivery modes command premium positioning in acute care settings, while oral formulations occupy the volume base across retail pharmacy channels.
The FDA, DEA, and WHO International Drug Control Conventions collectively shape product development timelines, manufacturing quotas, and cross-border trade flows for active pharmaceutical ingredients. The DEA's aggregate production quota system directly constrains how much oxycodone, fentanyl, and amphetamine salts manufacturers may produce annually. Stakeholders must monitor how rescheduling petitions and state-level prescription drug monitoring program interoperability mandates reshape distribution network requirements and compliance infrastructure investments.
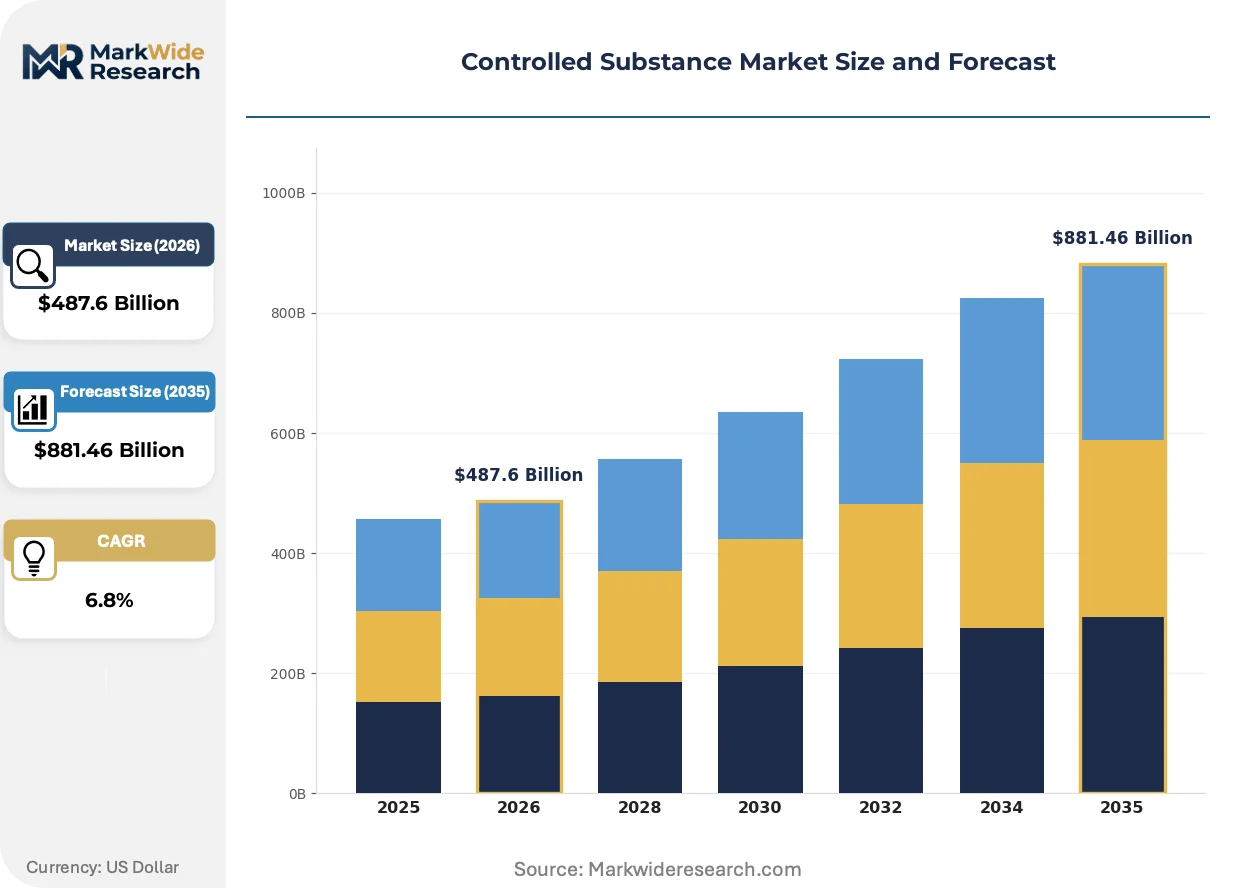
Market Dynamics
The DEA's aggregate production quota system functions as the central allocative mechanism, directly constraining manufacturing volumes for oxycodone, fentanyl, and amphetamine salts while forcing API producers to compete for finite Schedule II authorization slots.
Growth Catalysts
- Prescription Monitoring Program Expansion:Nearly every US state now operates interoperable PDMP databases, creating standardized demand visibility that reduces diversion risk and enables legitimate volume growth.
- Multimodal Analgesia Protocols:Perioperative care standards in tertiary hospitals are embedding controlled substances into broader pain management frameworks, expanding institutional procurement.
- ADHD Diagnostic Threshold Broadening:Pediatric and adult psychiatry practices are identifying more patients eligible for stimulant therapy, pulling amphetamine salt demand upward.
Market Restraints
- API Supply Geographic Concentration:Active pharmaceutical ingredient production for Schedule II substances clusters in a limited set of DEA-registered facilities, creating single-point vulnerability.
- Quota Allocation Volatility:Annual DEA production quota adjustments inject uncertainty into manufacturing planning cycles and inventory positioning.
- Abuse-Deterrent Formulation Costs:Resin complex and polymer matrix technologies for tamper-resistant tablets add 15-40% to unit production costs versus conventional formulations.
Strategic Opportunities
- Transdermal Delivery Expansion:Fentanyl and buprenorphine patch formulations are penetrating palliative care and opioid use disorder maintenance markets previously served by oral routes.
- Long-Acting Injectable Platforms:Monthly depot formulations for schizophrenia and substance use disorder are reducing adherence gaps and opening institutional pharmacy channels.
- State-Level PDMP Integration Mandates:Federal interoperability requirements are creating demand for compliance infrastructure vendors and data analytics services.
Industry Challenges
- Dual-Lock Storage Infrastructure:DEA vault specifications for Schedule II substances require specialized physical security investments that strain smaller distributors.
- Chain-of-Custody Documentation Burden:Batch-level tracking from API synthesis through dispensing creates compliance overhead that scales non-linearly with product portfolio breadth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Controlled Substance Market |
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $881.46 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Opioids, Stimulants, Depressants, Hallucinogens End User: Hospitals, Clinics, Pharmacies, Research Institutions Delivery Mode: Injectable, Oral, Transdermal, Inhalation Certification: FDA Approved, GMP Certified, WHO Listed, EMEA Approved |
| Companies Covered | Merck & Co. Inc., Johnson & Johnson, Pfizer Inc., AbbVie Inc., Teva Pharmaceutical Industries Ltd., Sanofi, Novartis AG, Lannett Co Inc., Noramco Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Controlled Substance Market Emerging Trajectories
Formulation chemistry and distribution architecture are undergoing parallel transformation as abuse-deterrent technologies mature and digital tracking systems replace paper-based custody records.
Abuse-deterrent polymer matrix technology is consolidating market share in extended-release opioid segments. Hospital formularies and managed care pharmacy benefit managers are prioritizing tamper-resistant formulations in prior authorization criteria. This consolidation is compressing demand for conventional immediate-release tablets in chronic pain indications.
The FDA's Risk Evaluation and Mitigation Strategy requirements for extended-release opioids are mandating prescriber training and patient registry participation. Manufacturers must fund and administer these programs as condition of approval, embedding fixed compliance costs into product economics. Brand and generic sponsors alike are restructuring field forces to support REMS education obligations.
Hospital procurement of controlled substances is consolidating through specialty distributors with DEA vault infrastructure. Integrated delivery networks are reducing their supplier base to three or fewer wholesalers with full cold-chain and controlled-substance capabilities. This consolidation is most visible in the southeastern United States where health system mergers have concentrated buying power.
Controlled Substance Market Segmentation
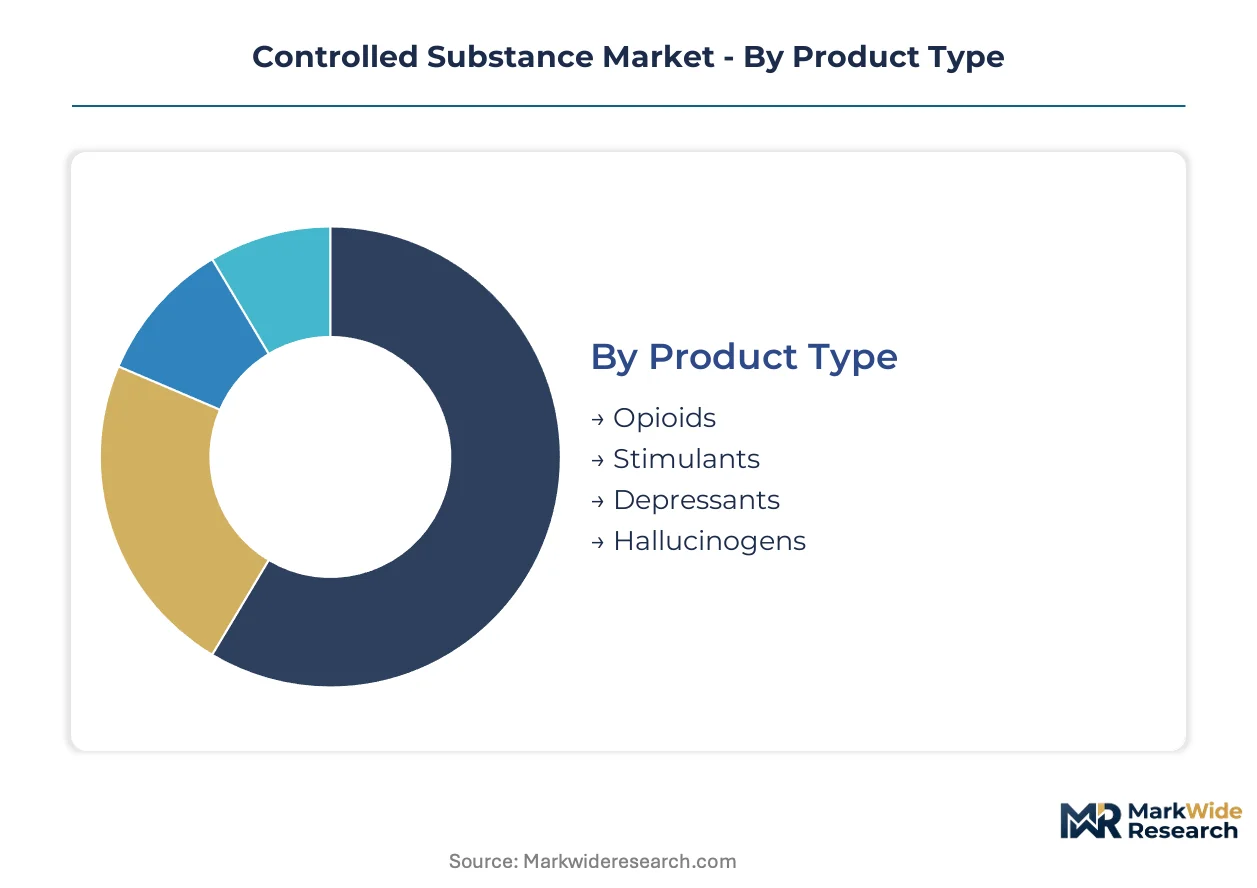
Segmentation in the controlled substance market reveals how regulatory burden, security infrastructure, and clinical application shape investment priorities. Capital allocation decisions diverge sharply across product categories and delivery modes due to DEA quota constraints and specialized manufacturing requirements.
Product Type:
Capital intensity peaks with Schedule II opioid APIs requiring dedicated DEA-registered facilities and dual-lock vault infrastructure costing millions in upfront compliance investment.
- Opioids:Extended-release oxycodone and fentanyl formulations demand polymer matrix manufacturing lines and resin complex processing equipment. Hospital procurement of these formulations concentrates in tertiary care centers with palliative care capabilities, driven by multimodal analgesia protocol adoption and prior authorization requirements for tamper-resistant alternatives.
- Stimulants:Amphetamine salt production for ADHD treatment operates under strict DEA aggregate quotas with batch-level tracking from synthesis through dispensing. Pediatric and adult psychiatry practices in the United States are expanding diagnostic eligibility criteria, pulling demand upward for both immediate-release and long-acting formulations.
- Depressants:Benzodiazepine and barbiturate compounds serve anesthesia and seizure disorder indications with lower abuse-deterrent formulation investment requirements.
- Hallucinogens:Psilocybin and ketamine derivatives for treatment-resistant depression occupy emerging therapeutic niches with limited commercial scale.
Opioids absorb the bulk of installed capacity; stimulants are expanding most quickly.
End User:
Customer type determines distribution architecture complexity, with institutional buyers demanding integrated cold-chain and controlled-substance capabilities that smaller retail channels cannot support.
- Hospitals:Integrated delivery networks in the southeastern United States have consolidated supplier bases to three or fewer wholesalers with full DEA vault infrastructure and chain-of-custody documentation systems.
- Clinics:Outpatient pain management and psychiatry practices rely on specialty distributors with regional DEA registration and real-time inventory tracking.
- Pharmacies:Retail chains face prescription monitoring program interoperability mandates requiring data infrastructure investments that strain independent operators.
- Research Institutions:Academic medical centers and contract research organizations source reference standards and investigational compounds through limited DEA-registered chemical suppliers.
Hospitals command the highest per-transaction value; clinics are gaining share fastest as ambulatory care shifts accelerate.
Delivery Mode:
Manufacturing process complexity and regulatory filing burden vary dramatically across administration routes, with parenteral forms requiring sterile facility validation and transdermal patches demanding specialized adhesive chemistry.
- Injectable:Fentanyl citrate and morphine sulfate solutions for acute perioperative care command premium positioning in hospital formularies. Tertiary care standards embedding these agents into enhanced recovery after surgery protocols are expanding institutional procurement volumes.
- Oral:Immediate-release and extended-release tablets occupy the volume base across retail pharmacy channels, though abuse-deterrent formulation costs add substantial unit production expense.
- Transdermal:Fentanyl and buprenorphine patches penetrate palliative care and opioid use disorder maintenance markets previously served by oral routes, requiring polymer matrix expertise.
- Inhalation:Limited applications in acute pain and anesthesia delivery with specialized device compatibility requirements.
Oral formulations dominate transaction volume; transdermal systems show the steepest expansion trajectory as adherence advantages drive formulary placement.
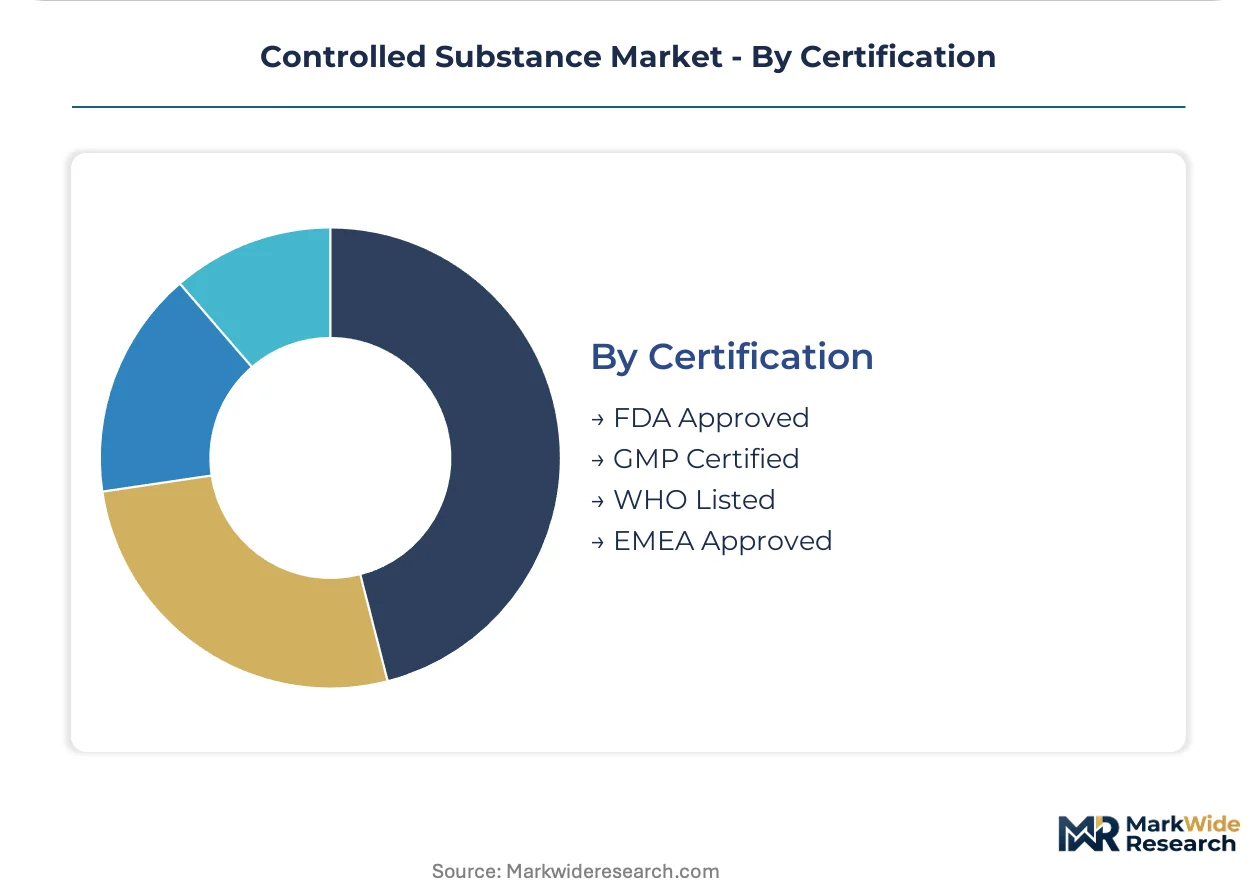
Certification:
Regulatory pathway selection determines market access speed and geographic scope, with multilateral recognition agreements reducing redundant facility inspections for qualified manufacturers.
- FDA Approved:New drug applications and abbreviated new drug applications for controlled substances require Risk Evaluation and Mitigation Strategy programs with prescriber training and patient registry obligations that embed fixed compliance costs.
- GMP Certified:Current good manufacturing practice inspection by the FDA or recognized foreign regulators enables API sourcing for both innovator and generic finished dosage forms.
- WHO Listed:Prequalification by the World Health Organization facilitates procurement by international health organizations and national programs in lower-income markets.
- EMEA Approved:European Medicines Agency centralized procedures provide access to European Union member states with mutual recognition extending to additional European Economic Area countries.
FDA approval anchors revenue concentration for United States-focused manufacturers; WHO listing is climbing fastest as global health procurement expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for pharmaceutical manufacturing in India and tax-advantaged research corridors in the United States concentrate controlled substance API production. These zones attract DEA-registered and FDA-inspected facilities through streamlined permitting and dedicated customs infrastructure.
United States
Pain management protocols in tertiary hospitals drive institutional procurement of Schedule II opioids. The DEA's aggregate production quota system caps annual manufacturing volumes for oxycodone and fentanyl APIs. New Jersey and North Carolina host concentrated clusters of DEA-registered formulation facilities serving hospital networks.
Germany
Specialized hospital formulary contracts for transdermal delivery systems sustain demand for fentanyl patches. EMA centralized procedures govern market access with mutual recognition extending to European Economic Area countries. The Rhine-Ruhr corridor maintains API synthesis capabilities for export to regulated markets.
India
Generic controlled substance production expands as CDSCO aligns inspection standards with FDA and WHO prequalification schemes. The country's national pharmaceutical regulator enforces dual-lock storage mandates for Schedule II substance exports. Hyderabad and Ahmedabad house DEA-registered API facilities serving North American and European markets.
Switzerland
Swissmedic oversight of abuse-deterrent formulation trials attracts development-stage investment from multinational sponsors. Specialized polymer matrix research clusters in Basel support tamper-resistant tablet programs. The country's precision chemistry infrastructure serves niche hallucinogen derivative production for clinical research.
Japan
PMDA scheduling reviews for stimulant therapies influence regional regulatory harmonization efforts. Long-acting injectable platforms for schizophrenia maintenance penetrate hospital pharmacy channels. The Kansai region concentrates formulation manufacturing for domestic distribution and limited export to Asian markets.
Controlled Substance Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated innovators commanding premium positioning in extended-release opioids while generic API houses compete on quota efficiency. The structure tiers across three concentration levels: multinational conglomerates with DEA vault infrastructure, mid-scale specialists with single-schedule focus, and regional distributors with limited manufacturing authorization. Dominant competitive moves include backward integration into captive API supply and strategic partnerships with institutional pharmacy networks to secure formulary placement.
Among Israel-based and US-domiciled pharmaceutical conglomerates, Teva Pharmaceutical Industries Ltd. exemplifies the mid-scale specialist archetype with vertical control over generic controlled substance production. Pfizer Inc. and Johnson & Johnson occupy positions within the multinational tier, anchoring hospital procurement relationships through manufacturing scale and specialized delivery system portfolios. These three entities represent distinct strategic postures: quota-secured volume leadership, formulary-anchored institutional access, and integrated generic production.
| Leading Market Players |
|---|
| Merck & Co. Inc. |
| Johnson & Johnson |
| Pfizer Inc. |
| AbbVie Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Sanofi |
| Novartis AG |
| Lannett Co Inc. |
| Noramco Inc. |
| Others |
Supply Flow & Price Mechanics
API precursor chemical indices for narcotic raw materials cascade through DEA-registered manufacturing tiers into three pricing levels: premium for abuse-deterrent formulations, standard for conventional extended-release tablets, and economy for immediate-release generics. This stratification reflects quota scarcity, vault infrastructure costs, and formulation complexity premiums that concentrate pricing power among manufacturers with secured Schedule II authorization slots.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to spot API purchases when DEA quota allocations tighten mid-year, while contract-based long-term offtake agreements secure volume discounts for integrated delivery networks. Price differentiation hinges on FDA Risk Evaluation and Mitigation Strategy certification tier and abuse-deterrent polymer matrix technology adoption. Cost compression in the economy tier is intensifying because Indian generic API houses are expanding DEA-registered capacity. Retail pharmacy chains exhibit highest price sensitivity due to thin dispensing margins, while hospital procurement committees prioritize formulary security over unit cost.
Supply Chain Analysis
Domestic-content mandates in the United States are reshaping sourcing patterns for Schedule II API finishing operations, pushing investment toward New Jersey and North Carolina corridor facilities. Active pharmaceutical ingredient synthesis concentrates in India, the United States, and Switzerland, with the Rhine-Ruhr corridor maintaining specialized polymer matrix capabilities. Raw material dependencies include Tasmanian poppy straw, synthetic fentanyl precursors from Chinese chemical suppliers, and amphetamine salt intermediates. Single-source vulnerability pervades the DEA vault infrastructure tier, where only twelve registered facilities handle bulk Schedule II storage. Distribution runs through three-tier wholesaler networks terminating at institutional pharmacies with dual-lock capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The controlled substance market functions as a cost-of-compliance fortress where DEA aggregate production quota regulations erect barrier-to-entry moats that protect incumbent positions. This regulatory architecture rewards players who have already amortized vault infrastructure investments and secured manufacturing authorization slots.
For Market Incumbents: Deepen backward integration into Tasmanian poppy straw sourcing and synthetic fentanyl precursor supply to insulate margin structures from API price volatility. Expand DEA-registered vault capacity in the southeastern United States corridor to capture health system merger-driven procurement consolidation. The emergence of long-acting injectable platforms for substance use disorder maintenance threatens oral formulation volumes, making depot manufacturing capability the critical defensive lever. For New Entrants and Emerging Players: Abuse-deterrent transdermal patch technology offers a technology-first wedge into palliative care formularies previously locked by extended-release tablet incumbents. Target the opioid use disorder maintenance segment where buprenorphine-naloxone film demand outstrips qualified manufacturing capacity. Pursue strategic licensing partnerships with established DEA-registered API houses rather than greenfield facility investment, accelerating market entry through regulatory piggybacking. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale specialists with single-schedule DEA registration and established hospital formulary relationships in the United States. Long-term viability rests on regulatory capacity scarcity rather than product innovation velocity. Watch DEA quota allocation announcements as the primary inflection signal; downward adjustments in oxycodone or amphetamine salt ceilings trigger immediate valuation repricing across the manufacturing tier.| Strategic Initiative | Industry Significance |
|---|---|
| DEA Vault Infrastructure Expansion | Dual-lock storage capacity in New Jersey and North Carolina corridors secures health system procurement consolidation. |
| Abuse-Deterrent Formulation Licensing | Polymer matrix technology partnerships with Swissmedic-registered Basel clusters accelerate tamper-resistant tablet development. |
| Long-Acting Injectable Platform Development | Monthly depot formulations for schizophrenia and substance use disorder penetrate institutional pharmacy channels. |
| Backward Integration into API Synthesis | Captive Tasmanian poppy straw and synthetic precursor supply insulates margin structures from quota-driven price spikes. |
| PDMP Compliance Infrastructure Partnership | Real-time prescription monitoring data analytics services capture state-level interoperability mandate spending. |
Methodological Framework
Document review covered DEA aggregate production quota filings, FDA Risk Evaluation and Mitigation Strategy program disclosures, and state prescription monitoring program interoperability mandates, complemented by interviews with regulatory affairs directors at DEA-registered API manufacturers, hospital formulary committee chairs, and specialty distributor operations heads. Secondary validation drew from WHO International Drug Control Convention reports, EMA centralized procedure submissions, and CDSCO inspection alignment documentation. Bottom-up volume modeling triangulated against top-down quota allocation analysis.
Segment-level projections across product type, delivery mode, end user, and certification tier generated volume and value trajectories over the projection horizon. CAGRs derived from historical quota adjustment patterns, formulary adoption curves for abuse-deterrent technologies, and diagnostic threshold expansion rates in ADHD treatment. Key inputs included DEA manufacturing authorization slot utilization rates, hospital procurement consolidation transaction data, and transdermal patch adhesion chemistry advancement timelines.
Several conditions sit outside the modeled scope, including unscheduled rescheduling petitions, international treaty reclassification actions, and novel synthetic opioid emergency scheduling interventions. Forecasts reflect documented assumptions regarding quota stability, PDMP interoperability implementation pace, and polymer matrix manufacturing yield improvements. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Hard Gelatin Capsules Market
Pharmaceuticals
Biguanides Market
Pharmaceuticals
Global Eylea Market
Pharmaceuticals
Dermatological Drugs Market
Pharmaceuticals
Adenosine Market
Pharmaceuticals
India Over-The-Counter Drugs (OTC) Market
Pharmaceuticals
Disease-Modifying Agents Market
Pharmaceuticals
Germany Pharmaceutical Warehousing Market
Pharmaceuticals
Calcitriol Capsules Market
Pharmaceuticals
Focal Segmental Glomerulosclerosis (FSGS) Therapeutics Market
Pharmaceuticals
Cardiometabolic Drugs Market
Pharmaceuticals
Global Central Nervous System (CNS) Stimulant Drugs Market
Pharmaceuticals
Daratumumab Market
Pharmaceuticals
Global Androgen Deprivation Therapy Market
Pharmaceuticals
Ocular Drug Delivery System Market
Pharmaceuticals
Global PD-1 and PD-L1 Inhibitors Market