
 Global Stroke Assistive Devices Market | 2026-2036
Global Stroke Assistive Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stroke Assistive Devices Market Foresight
Aftermarket service revenue for robotic exoskeleton fleets is tilting toward software subscription models and remote calibration contracts. Ekso Bionics leverages its installed base of rehabilitation centers to secure recurring telemetry revenue. Medtronic anchors its neurostimulation portfolio with deep brain stimulation systems that extend into post-stroke spasticity management. Stryker Corporation dominates hospital capital equipment procurement through integrated servicing agreements that bundle mobility aids with surgical navigation platforms.
Stroke assistive devices encompass electromechanical systems, wearable robotics, and sensor-based interfaces engineered to restore motor function, communication capacity, or cognitive processing after cerebrovascular injury, with typical specifications including torque limits of 15-50 Nm for lower-limb exoskeletons and sampling rates exceeding 1,000 Hz for EMG-driven controllers. Rehabilitation robots command the largest installed base among product categories, though soft robotics architectures are gaining fastest in home care settings where device weight and power consumption constrain adoption. Artificial Intelligence integration within sensor-based systems is concentrating margin pools in algorithm licensing rather than hardware fabrication, while virtual reality modules for cognitive rehabilitation remain nascent with reimbursement codes still under negotiation in most health systems.
FDA breakthrough device designation and EU MDR Class IIa certification requirements are shaping development roadmaps, with the former compressing premarket timelines and the latter imposing clinical evidence burdens that favor firms with existing quality management systems. Japan's PMDA has streamlined approval for designated orphan medical devices, creating a parallel pathway for stroke-specific neuroprosthetics. Stakeholders must monitor reimbursement parity between clinic-based and home-deployed devices, as this determination will reallocate volume across end user segments regardless of technical performance benchmarks.
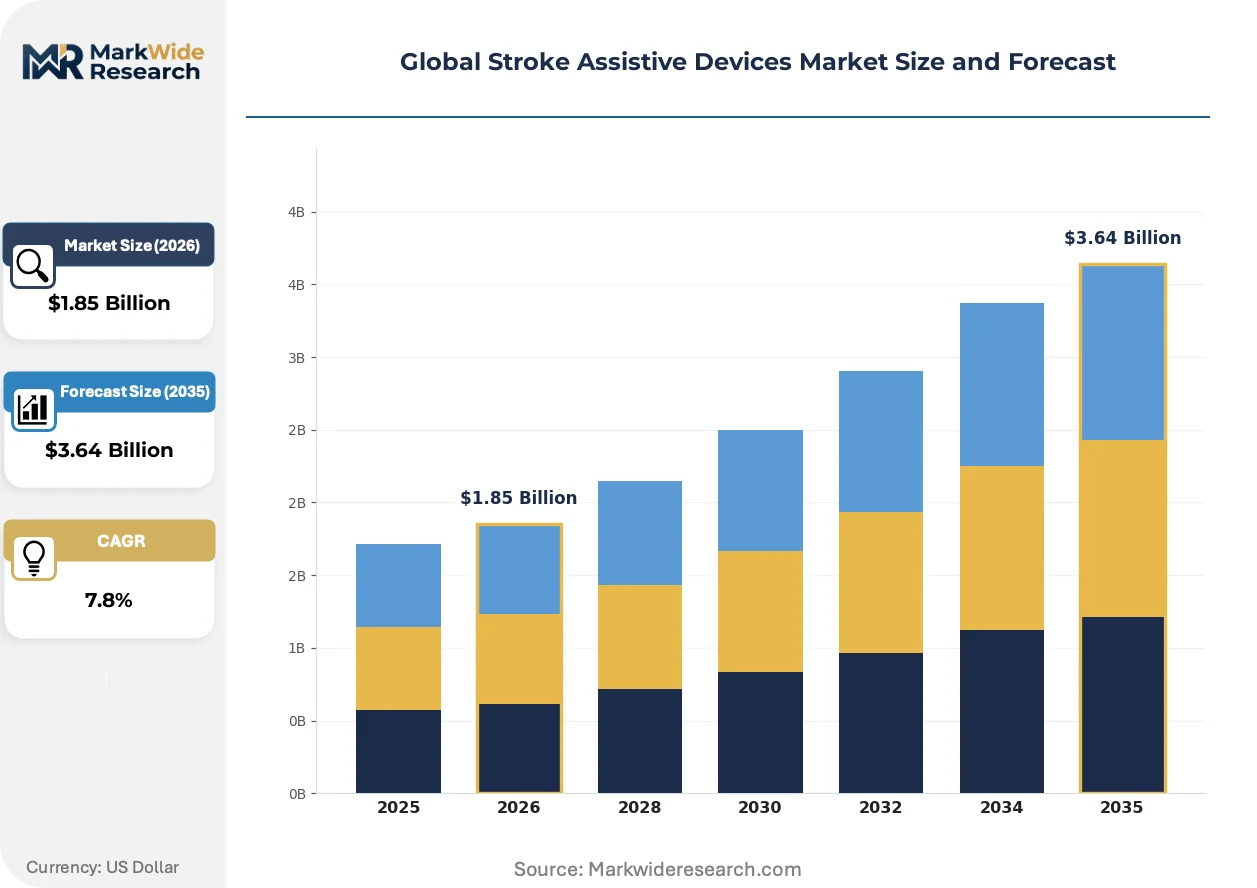
Market Dynamics
Software subscription models are displacing hardware-centric revenue streams across the stroke assistive device landscape, with algorithm licensing now commanding margin premiums that hardware fabrication cannot match. This structural shift concentrates value capture in firms controlling telemetry infrastructure and remote calibration protocols.
Growth Catalysts
- EU MDR Class IIa certification:The regulation's clinical evidence requirements favor established quality management systems, accelerating consolidation among rehabilitation robot manufacturers with pre-existing certification infrastructure.
- Japan's PMDA orphan device pathway:Streamlined approval timelines for stroke-specific neuroprosthetics are unlocking municipal subsidy programs in super-aging prefectures.
- Electromechanical gait trainers:German rehabilitation centers are expanding fleet procurement as insurers recognize measurable gait velocity outcomes from robotic therapy protocols.
Market Restraints
- High-torque actuator costs:Rare-earth magnet price volatility constrains lower-limb exoskeleton production economics, particularly for 15-50 Nm specification devices.
- EU MDR transition costs:Small manufacturers face disproportionate clinical trial burdens for Class IIa neurostimulation systems, reducing competitive diversity.
- Non-invasive brain-computer interfaces:Consumer-grade EEG headsets threaten clinical neuroprosthetic pricing power for cognitive rehabilitation applications.
Strategic Opportunities
- Home care soft robotics:Lightweight pneumatic actuators and fabric-based exoskeletons address power consumption constraints in Japan's municipal-subsidized home therapy programs.
- AI-EMG convergence:Machine learning integration with 1,000+ Hz sampling rate controllers enables predictive movement assistance beyond reactive mechanical support.
- FDA breakthrough designation:Compressed premarket timelines for novel neuroprosthetics create first-mover advantages in US rehabilitation center procurement cycles.
Industry Challenges
- Cross-functional engineering talent:Integration of biomechanics, embedded systems, and clinical validation expertise remains scarce, delaying product development cycles.
- Legacy hospital IT integration:Robotic therapy platforms require costly interoperability work with existing electronic health record systems and surgical navigation infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stroke Assistive Devices Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rehabilitation Robots, Mobility Aids, Communication Devices, Sensory Feedback Devices, Cognitive Training Tools Technology: Electromechanical, Soft Robotics, Virtual Reality, Artificial Intelligence, Sensor-Based Systems Application: Motor Function Recovery, Speech Therapy, Cognitive Rehabilitation, Daily Living Assistance, Balance Improvement End User: Neurological Clinics, Rehabilitation Centers, Home Care Providers, Elder Care Facilities, Therapy Institutes |
| Companies Covered | ReWalk Robotics, Bionik Laboratories, Ekso Bionics, Medtronic, Stryker Corporation, Intuitive Surgical Inc., Mazor Robotics Ltd., Boston Scientific, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stroke Assistive Devices Market Shifts & Advancements
Sensor-based control architectures are fundamentally altering how motor assistance is delivered, shifting value from mechanical hardware to algorithmic interpretation of patient biomechanical data. This transformation is compressing development cycles and enabling personalization at scale.
Soft pneumatic actuators are digitizing the interface between patient and device. These fabric-based systems replace rigid exoskeleton frames with compliant structures that adapt to individual limb morphology. Home care providers in Japan are adopting them rapidly to meet weight and power constraints of municipal-subsidized deployments. The technology is digitizing patient-specific gait pattern libraries, enabling remote therapeutic adjustment without physical clinic visits.
Japan's PMDA orphan medical device designation is compressing approval timelines for stroke-specific neuroprosthetics. The policy creates parallel regulatory tracks that bypass standard review queues for conditions with limited treatment alternatives. European manufacturers are responding by establishing Tokyo-based clinical trial operations to access this accelerated pathway, particularly for EMG-driven controllers targeting upper-limb rehabilitation.
Reimbursement code negotiations are restructuring how cognitive rehabilitation modules reach patients. Virtual reality therapy platforms face coverage determination delays that clinic-based robotic systems have already cleared. US hospital systems are delaying VR procurement until CPT codes stabilize, while German statutory insurers pilot bundled payment models that include both hardware and software therapeutic content.
Global Stroke Assistive Devices Market Segmentation
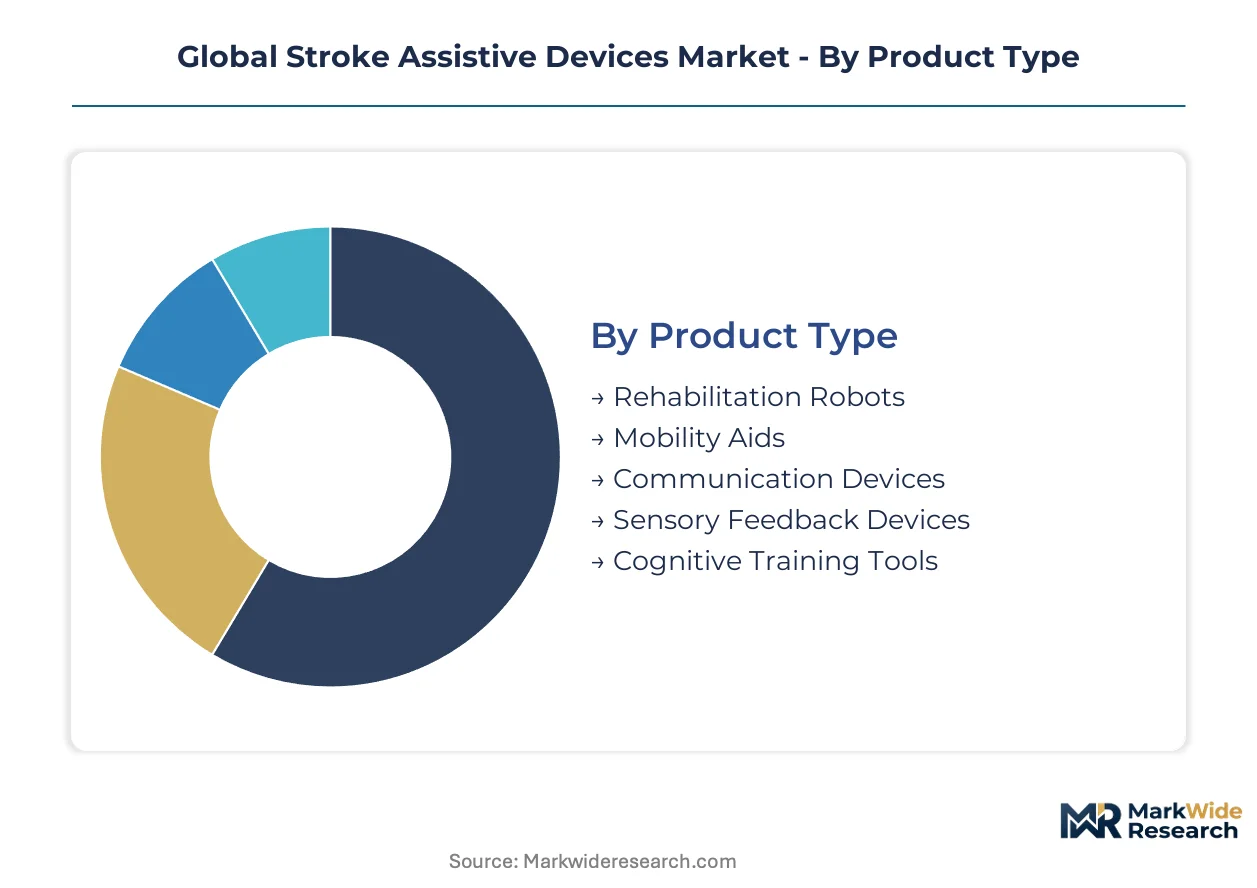
Stroke assistive devices fragment across four critical dimensions that determine reimbursement pathways, regulatory requirements, and procurement cycles. Product type dictates capital intensity and service revenue potential. Technology selection shapes margin structure through hardware-software value splits. Application focus determines clinical evidence requirements. End user concentration influences distribution architecture and pricing power.
Product Type:
Rehabilitation robots anchor hospital procurement budgets while lightweight alternatives penetrate municipal home care programs.
- Rehabilitation Robots:Electromechanical gait trainers and upper-limb systems deliver 15-50 Nm torque assistance with embedded telemetry for remote outcome monitoring. German rehabilitation centers are expanding fleet procurement as statutory insurers recognize measurable gait velocity improvements from robotic therapy protocols.
- Mobility Aids:Sensor-integrated walkers and powered wheelchairs incorporate balance detection algorithms that prevent falls during post-stroke ambulation. Japan's super-aging municipalities subsidize home deployments where device weight and battery life constrain adoption of heavier electromechanical alternatives.
- Communication Devices:Eye-tracking and EMG-driven speech synthesis systems restore expression capacity in aphasia patients.
- Sensory Feedback Devices:Haptic gloves and vibration arrays retrain proprioceptive pathways damaged by cerebrovascular injury.
- Cognitive Training Tools:Tablet-based attention and memory modules target executive function deficits with adaptive difficulty algorithms.
Established volume favors rehabilitation robots; emerging adoption favors mobility aids.
Technology:
Cost tiers separate premium electromechanical platforms from software-weighted alternatives that capture margin through algorithm licensing rather than hardware fabrication.
- Electromechanical:Rare-earth magnet actuators and precision gearboxes enable high-torque assistance for lower-limb rehabilitation. Price volatility in neodymium supply chains constrains production economics for 15-50 Nm specification devices.
- Artificial Intelligence:Machine learning integration with 1,000+ Hz EMG sampling rate controllers enables predictive movement assistance beyond reactive mechanical support. AI-EMG convergence is climbing the fastest as value capture concentrates in algorithm licensing rather than sensor hardware.
- Soft Robotics:Pneumatic fabric actuators reduce device weight for home care deployment.
- Virtual Reality:Immersive environments for cognitive rehabilitation face reimbursement code negotiation delays in US and European health systems.
- Sensor-Based Systems:Inertial measurement units and surface EMG arrays provide closed-loop control for assistive force modulation.
Hardware fabrication margins favor electromechanical platforms; recurring revenue architecture favors artificial intelligence.
Application:
Maturity gradients separate clinic-validated motor recovery protocols from nascent cognitive modules awaiting reimbursement stabilization.
- Motor Function Recovery:Gait and upper-limb rehabilitation commands the largest installed base with established CPT and DRG reimbursement codes. FDA breakthrough device designation is compressing premarket timelines for novel neuroprosthetics targeting this application.
- Cognitive Rehabilitation:VR-based attention and memory training lacks standardized outcome metrics that insurers require for coverage determination. US hospital systems delay procurement until reimbursement codes stabilize, while German statutory insurers pilot bundled payment models.
- Speech Therapy:Augmentative communication devices address aphasia and dysarthria through multimodal input systems.
- Daily Living Assistance:Adaptive eating and dressing tools support functional independence in home environments.
- Balance Improvement:Postural control systems prevent falls through real-time center-of-mass monitoring.
Reimbursement security favors motor function recovery; regulatory acceleration favors cognitive rehabilitation.
End User:
Customer type determines contract structure, with integrated servicing agreements dominating hospital capital equipment procurement and per-device subsidies characterizing municipal home care programs.
- Rehabilitation Centers:German facilities are expanding electromechanical gait trainer procurement as insurers recognize measurable outcomes. Bundled servicing agreements that include preventive maintenance and software updates dominate capital equipment contracts.
- Home Care Providers:Japan's super-aging municipalities subsidize lightweight robotic therapy for home deployment where power consumption and device weight constrain adoption. Soft pneumatic actuators address these constraints through fabric-based exoskeleton architectures.
- Neurological Clinics:Outpatient stroke units prioritize portable assessment tools for motor function quantification.
- Elder Care Facilities:Long-term care operators seek fall prevention systems with minimal staff training requirements.
- Therapy Institutes:Private rehabilitation chains negotiate volume discounts for multi-site equipment deployments.
Contract value concentration favors rehabilitation centers; volume expansion favors home care providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: German rehabilitation centers prioritize electromechanical gait trainers for measurable outcome metrics, while Japanese municipalities subsidize lightweight home-deployed systems where power constraints dominate procurement criteria.
United States
FDA breakthrough device designation compresses premarket timelines for novel neuroprosthetics, accelerating commercialization for firms targeting rehabilitation center procurement cycles. The Centers for Medicare & Medicaid Services maintains separate reimbursement tracks for clinic-based versus home-deployed devices, creating volume allocation uncertainty. Greater Boston anchors neurotechnology R&D clusters where academic medical centers pilot EMG-driven controller validation protocols.
Germany
Statutory insurers now recognize gait velocity improvements from robotic therapy, triggering fleet expansion across Baden-Württemberg rehabilitation networks. EU MDR Class IIa certification requirements favor established quality management systems, consolidating procurement toward pre-certified manufacturers. The Rhine-Ruhr metropolitan region concentrates electromechanical gait trainer deployment through integrated servicing agreements bundling hardware with preventive maintenance.
Japan
PMDA orphan medical device designation creates accelerated approval tracks for stroke-specific neuroprosthetics, unlocking municipal subsidy programs in super-aging prefectures. METI coordinates home care robotics deployment through standardized power consumption specifications addressing domestic electricity constraints. Osaka-Kobe manufacturing corridors specialize in fabric-based soft pneumatic actuators for lightweight exoskeleton production.
China
NMPA streamlined review pathways for innovative medical devices reduce registration timelines for rehabilitation robot manufacturers with existing quality infrastructure. Provincial health commissions in Guangdong pilot bundled payment models combining hardware procurement with software therapeutic content. Yangtze River Delta industrial clusters integrate rare-earth magnet supply chains with precision actuator fabrication for 15-50 Nm specification lower-limb systems.
Global Stroke Assistive Devices Market Competitive Landscape
Capability concentration sits with specialized neuroprosthetic developers possessing integrated biomechanics and embedded systems expertise; scale advantage sits with diversified medical technology conglomerates leveraging hospital capital equipment relationships. The vendor landscape organizes into three functional tiers: rehabilitation robotics specialists, neurostimulation platform holders, and diversified surgical equipment suppliers. Consolidation pressure intensifies as EU MDR clinical evidence burdens favor firms with pre-existing certification infrastructure. Dominant competitive moves include strategic partnerships pairing hardware fabrication with algorithm licensing, and geographic expansion establishing Tokyo-based clinical operations to access Japan's accelerated PMDA pathway.
Within the neuroprosthetic specialist tier, Ekso Bionics and ReWalk Robotics exemplify rehabilitation robotics developers leveraging installed base relationships for recurring telemetry revenue. Medtronic anchors the neurostimulation platform segment through deep brain stimulation system extensions into post-stroke spasticity management. Stryker Corporation represents diversified surgical equipment suppliers dominating hospital procurement through bundled servicing agreements integrating mobility aids with existing navigation infrastructure.
| Leading Market Players |
|---|
| ReWalk Robotics |
| Bionik Laboratories |
| Ekso Bionics |
| Medtronic |
| Stryker Corporation |
| Intuitive Surgical Inc. |
| Mazor Robotics Ltd. |
| Boston Scientific |
| Abbott Laboratories |
| Others |
Supply & Pricing Matrix
Rare-earth magnet price volatility cascades through both tier spreads and sourcing geography for electromechanical gait trainers and lower-limb exoskeletons. Neodymium supply concentration in Chinese processing facilities compresses margins for 15-50 Nm specification devices while pushing German and Japanese manufacturers toward long-term offtake contracts that lock in component costs.
Pricing Analysis
Long-term offtake agreements dominate procurement for high-torque actuators, though spot purchasing persists for consumable sensor arrays and standard electronics. Pricing stratifies across premium, standard, and economy tiers based on FDA breakthrough designation status and embedded telemetry capability. Cost compression in the economy tier intensifies because consumer-grade EEG headsets erode clinical neuroprosthetic pricing power. Hospital procurement committees exhibit lowest price sensitivity due to bundled servicing agreements, while municipal home care programs in Japan face strict per-device subsidy caps.
Supply Chain Analysis
Export controls on precision motion control software limit actuator controller flows from US and German suppliers to Chinese manufacturers. Final assembly concentrates in China, Germany, and Japan, with rare-earth magnet fabrication drawing from Yangtze River Delta clusters. Neodymium price volatility and single-source vulnerability for high-resolution EMG sensors constitute the primary structural risk. Distribution runs through hospital capital equipment purchasing committees and municipal procurement offices rather than retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward integrated hospital systems and municipal aggregators that consolidate stroke assistive device procurement across multiple rehabilitation centers or prefectures.
For Market Incumbents: Entrench telemetry infrastructure advantages by deepening software subscription attach rates and securing exclusive remote calibration protocols. Counter non-invasive brain-computer interface substitution threats by accelerating FDA breakthrough pathway submissions for next-generation EMG-driven controllers. Prioritize backward integration into rare-earth magnet sourcing through Japanese or Australian offtake partnerships. For New Entrants and Emerging Players: Municipal home care programs in Japan's super-aging prefectures represent the most penetrable entry point, given streamlined PMDA orphan device pathways and standardized power consumption specifications. Soft pneumatic actuator architectures for fabric-based exoskeletons offer differentiation against rigid electromechanical incumbents. Pursue algorithm licensing partnerships with established telemetry platforms rather than competing on hardware fabrication. For Investors and Strategic Acquirers: EU MDR Class IIa certification deadlines reshape the acquisition landscape by devaluing uncertified development-stage assets and privileging firms with pre-existing quality management infrastructure. Target rehabilitation robotics specialists with installed base relationships convertible to recurring telemetry revenue. Monitor reimbursement parity determinations between clinic-based and home-deployed devices as the critical inflection signal for volume reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Designation Pursuit | Compressed premarket timelines accelerate rehabilitation center procurement cycles for novel neuroprosthetics. |
| EU MDR Class IIa Certification Investment | Clinical evidence infrastructure requirements favor consolidation toward pre-certified manufacturers. |
| Software Companion Development | Algorithm licensing captures margin premiums that hardware fabrication cannot match. |
| Tokyo Clinical Trial Establishment | PMDA orphan device pathway access unlocks municipal subsidy programs in super-aging prefectures. |
| Reimbursement Strategy Execution | CPT code stabilization determines cognitive rehabilitation module adoption velocity. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with rehabilitation center directors, biomedical engineers, hospital purchasing committee members, and GPO contracts managers; and secondary validation through FDA 510(k) filings, PMDA approval databases, CMS Medicare reimbursement schedules, and EU MDR notified body certification records. Bottom-up demand modeling from installed base telemetry data was triangulated against top-down market sizing from capital equipment procurement disclosures.
Forecast inputs span product type segmentation, technology architecture, application focus, and end user concentration across the projection horizon. CAGRs were derived from regression analysis of historical procurement cycles and regulatory approval velocity. AI-EMG convergence adoption curves and municipal subsidy program expansion rates in super-aging geographies provided industry-specific forecast inputs.
Practitioners should monitor rare-earth magnet price movements, reimbursement parity determinations, and PMDA orphan device pathway utilization for early signals. Forecasts reflect assumptions about regulatory timeline compression and subsidy program continuity. Material shifts in EU MDR enforcement intensity or Japanese municipal budget allocations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Implantable Pacemaker Market
Medical Devices
Kirschner Wires Market
Medical Devices
South Africa Ultrasound Devices Market
Medical Devices
Australia Spinal Surgery Devices Market
Medical Devices
Asia-Pacific Respiratory Devices Market
Medical Devices
Global Airway Stent/Lung Stent Market
Medical Devices
Artificial Disc Replacement Market
Medical Devices
Infant Oxygen Hoods Market
Medical Devices
EEG and EMG Equipment Market
Medical Devices
Wearable Defibrillators Market
Medical Devices
Germany Respiratory Devices Market
Medical Devices
Global Thrombectomy Devices Market
Medical Devices
Neuromodulation Devices Market
Medical Devices
Global Automatic Stair Climbing Wheelchair Market
Medical Devices
Tissue Embedding Center Market
Medical Devices
Canada Respiratory Devices Market