
 Sleep Apnea Devices Market | 2026-2036
Sleep Apnea Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Sleep Apnea Devices Market Analysis
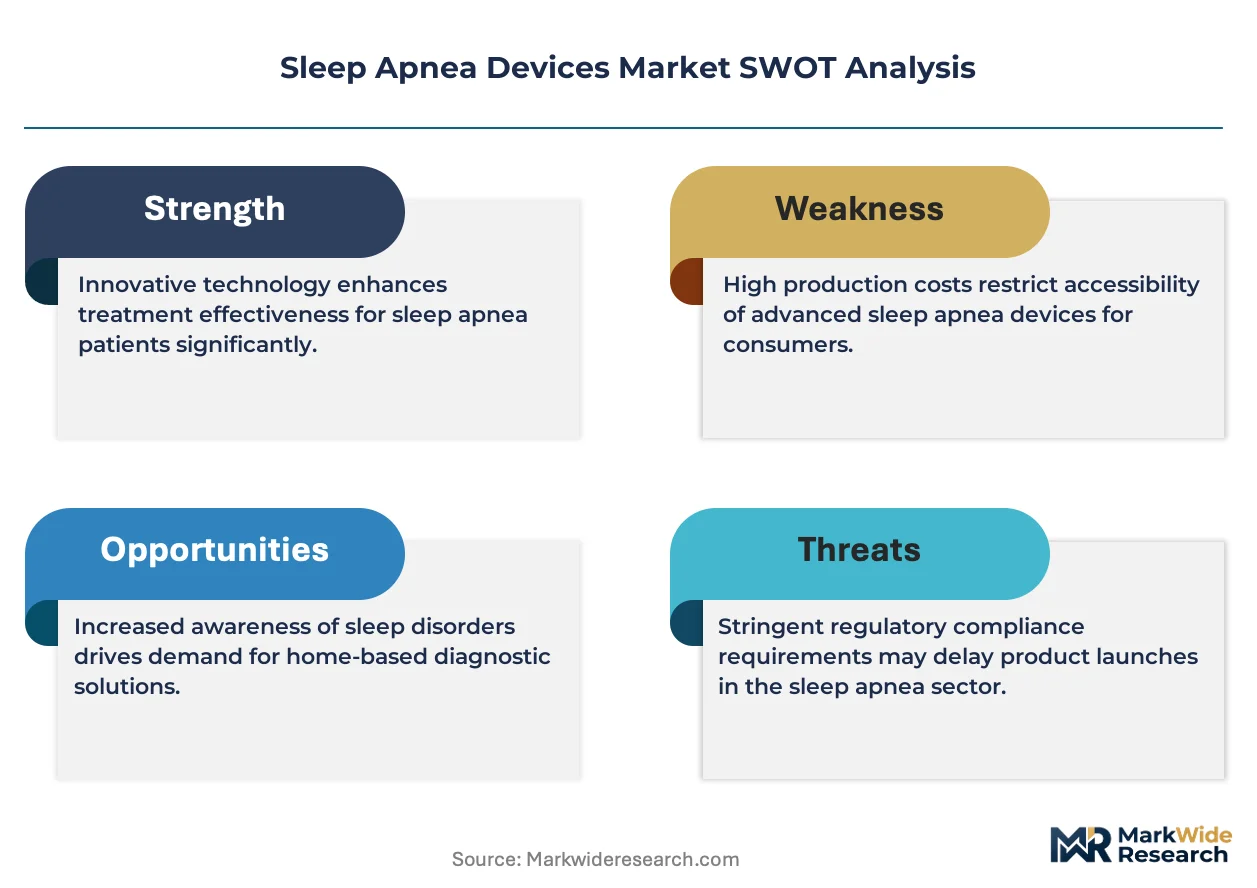
A shortage of board-certified sleep technologists is unwinding clinical throughput and pushing diagnostic workflows toward automated and home-based platforms. ResMed leverages cloud-connected device ecosystems to sustain recurring revenue streams beyond hardware sales. Philips Respironics navigates manufacturing quality remediation while Fisher & Paykel Healthcare Limited anchors competitive positioning through humidification technology leadership.
Sleep apnea devices are therapeutic and diagnostic systems that deliver pressurized airflow or mechanical intervention to maintain patent upper airways during sleep, typically operating at pressure ranges of 4-20 cm H2O with integrated flow sensors and algorithmic titration. Their primary commercial purpose is to reduce apnea-hypopnea index scores and mitigate cardiovascular comorbidities in diagnosed patients. CPAP systems occupy the largest installed base and margin pool across product type categories, while remote monitoring capabilities within delivery mode segments are capturing the fastest expansion as payors tighten adherence verification requirements. Auto-titration technology leads innovation investment among technology segments by reducing manual sleep lab dependency.
FDA clearance requirements for adaptive algorithms and software updates shape product development timelines and post-market surveillance obligations for manufacturers targeting the United States. ISO 13485 quality management standards and MDR conformity pathways in Europe impose parallel compliance architectures that filter market entry for smaller device developers. Stakeholders must monitor how reimbursement authorities weigh automated adherence data against traditional polysomnography documentation when setting coverage thresholds.
Market Dynamics
Automated titration algorithms are collapsing diagnostic bottlenecks by replacing manual polysomnography interpretation with machine-driven pressure adjustment. This shift compresses the traditional sleep-lab-to-treatment pathway from weeks to days while redistributing economic value from clinical facilities toward device manufacturers with integrated software ecosystems.
Growth Catalysts
- Home-based diagnostic pathways:Payers in the United States now reimburse unattended sleep studies under CMS guidelines, accelerating patient identification without facility bottlenecks.
- FDA 510(k) software-as-medical-device clearances:Adaptive algorithm updates receive streamlined premarket review, enabling faster feature deployment for cloud-connected CPAP systems.
- Auto-titrating positive airway pressure:Split-night polysomnography protocols in Germany and France increasingly incorporate APAP titration, reducing technician labor per diagnosis.
Market Restraints
- Polymer supply concentration:Medical-grade silicone for mask cushions concentrates among Asian compounders, exposing manufacturers to freight cost volatility and customs delays.
- Reimbursement compression:Medicare competitive bidding programs in the United States cap rental rates for PAP devices, squeezing margin pools for durable medical equipment suppliers.
- Oral appliance substitution:Mandibular advancement devices prescribed by dental sleep medicine practitioners capture mild-to-moderate OSA cases before PAP therapy initiation.
Strategic Opportunities
- Underpenetrated rural diagnostics:Telemedicine-integrated home sleep testing in Australia and Canada reaches populations beyond urban sleep center catchments.
- Software subscription layering:Recurring revenue from adherence monitoring dashboards and coaching apps attaches to hardware sales, improving lifetime value per patient.
- EU MDR conformity acceleration:Manufacturers achieving CE marking under the 2017/745 Medical Device Regulation gain preferential positioning in European public procurement frameworks.
Industry Challenges
- Sleep technologist scarcity:Board-certified polysomnographic technologist programs in the United States graduate fewer candidates than clinical demand requires, constraining lab throughput.
- Legacy system integration friction:Hospital electronic health record architectures resist seamless data ingestion from proprietary device cloud platforms, complicating care coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sleep Apnea Devices Market |
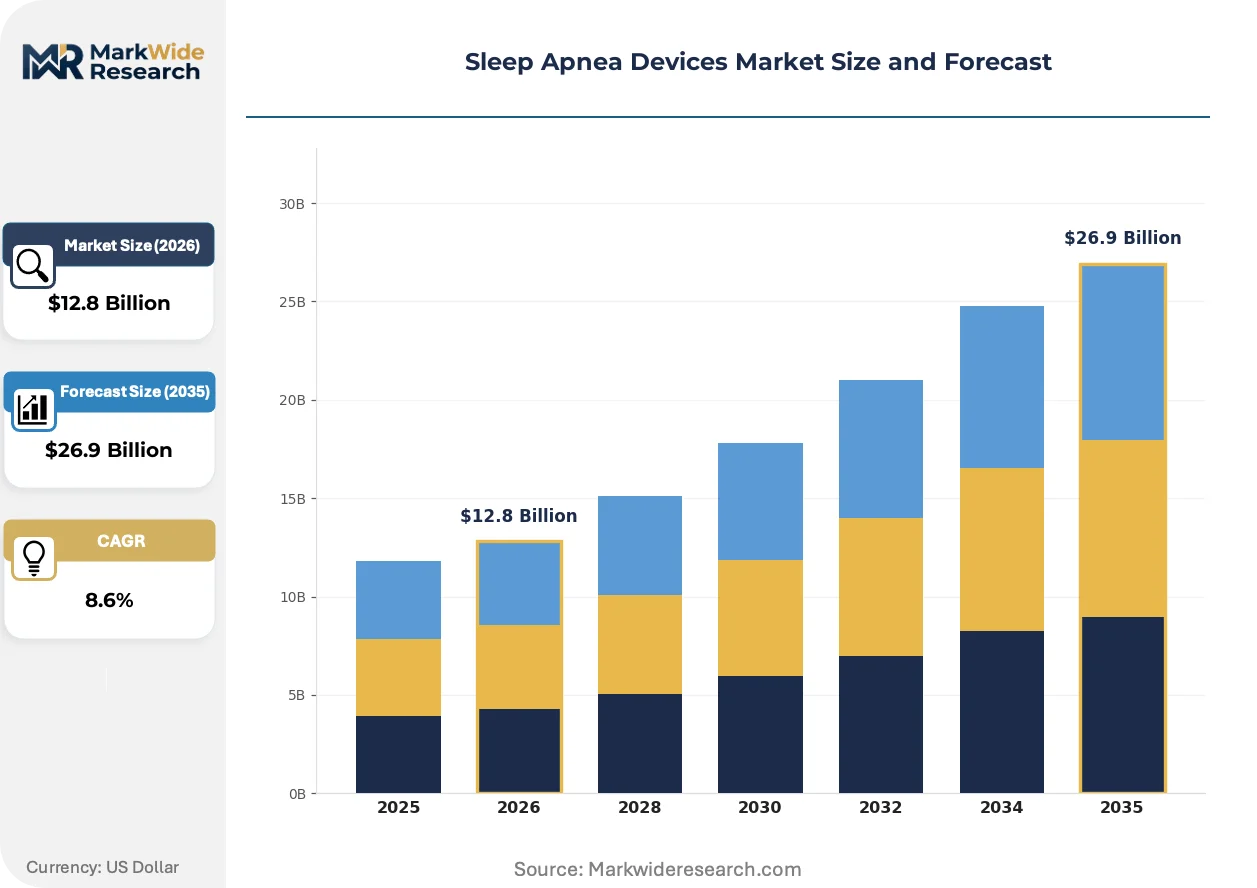
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.9 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CPAP, BiPAP, APAP, Oral Appliances End User: Hospitals, Homecare, Sleep Clinics, Dental Offices Technology: Auto-Titration, Fixed Pressure, Adaptive Servo-Ventilation, Positional Therapy Delivery Mode: Manual, Automatic, Integrated, Remote Monitoring |
| Companies Covered | Curative Medical, Somnetics International, ResMed, SomnoMed, BMC Medical Co., Ltd., Philips Respironics, React Health, Itamar Medical Ltd., Fisher & Paykel Healthcare Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sleep Apnea Devices Market Emerging Trajectories
Cloud-native device architectures are transforming competitive economics by decoupling hardware margins from software-enabled service revenue. This shift rewards manufacturers with integrated data platforms while pressuring pure-play equipment vendors.
Machine learning-driven event detection is fragmenting the diagnostic landscape by enabling single-channel home monitors to approximate multi-parameter polysomnography accuracy. Sleep clinics in the United Kingdom and Netherlands are adopting these systems to triage patients before full laboratory study commitment. The technology is fragmenting referral patterns by allowing primary care physicians to initiate diagnostic pathways without specialist gatekeeping.
The European Union's Medical Device Regulation imposes stricter clinical evidence requirements for algorithm-driven pressure adjustment systems than predecessor directives. Manufacturers must generate prospective validation data for software updates, lengthening development cycles. High-acuity device categories face notified body capacity constraints, delaying market entry for novel auto-titration features.
Patients are demanding direct-to-consumer purchase options for replacement masks and tubing, bypassing traditional durable medical equipment distributors. This pattern concentrates in the United States where high-deductible health plans increase price sensitivity. Online retail channels now capture growing share of accessory revenue, compressing distributor margins and forcing inventory repositioning toward patient-facing fulfillment centers.
Sleep Apnea Devices Market Segmentation
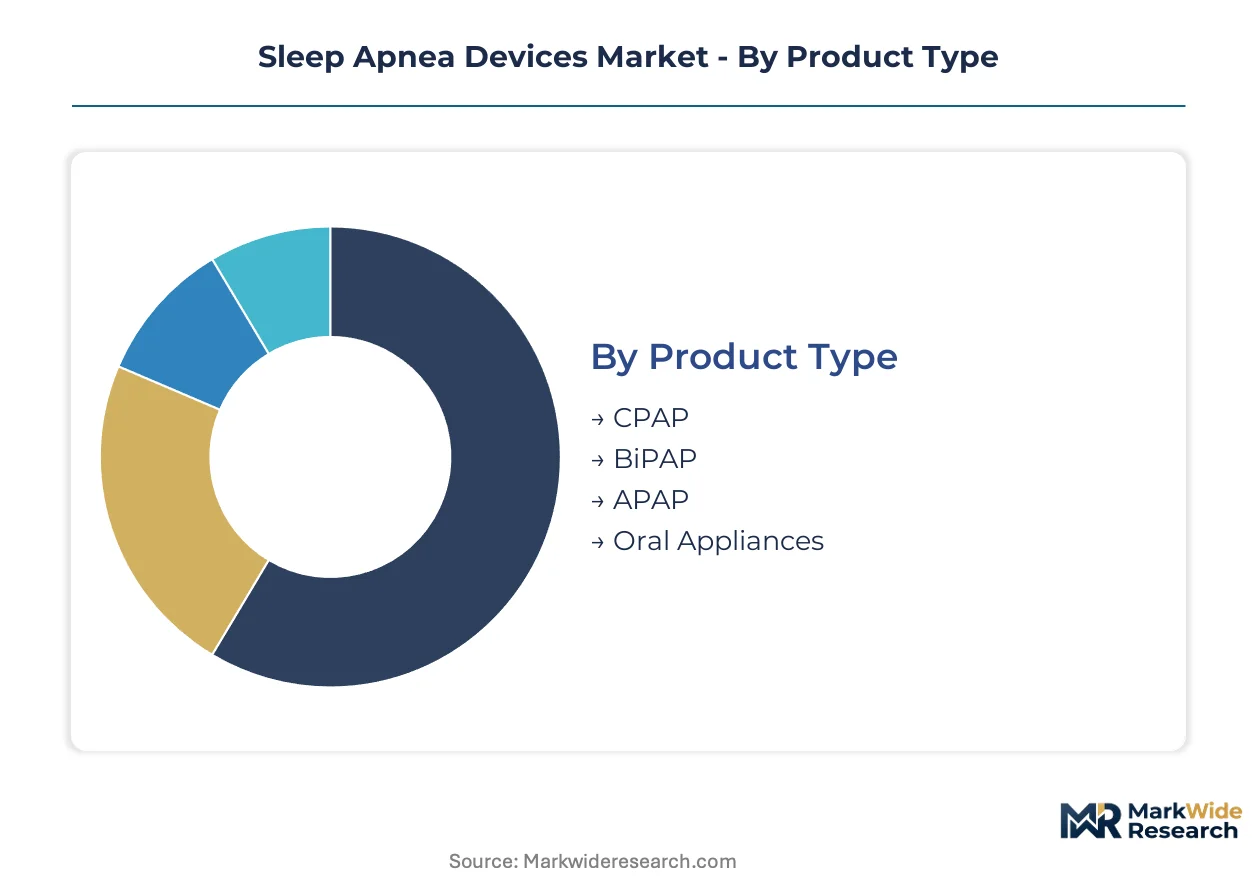
Sleep apnea device segmentation reveals divergent commercial models across clinical and consumer pathways. Product architecture choices determine reimbursement eligibility, while technology sophistication separates hardware vendors from platform players.
Product Type:
CPAP systems anchor domestic demand in the United States and Germany where reimbursement pathways favor established therapeutic categories. Export-led growth concentrates in APAP and oral appliance segments targeting Asian and Latin American markets with lighter regulatory burdens.
- CPAP:Continuous positive airway pressure systems deliver fixed therapeutic pressure via turbine-driven airflow generators. Demand concentrates in Medicare-reimbursed homecare settings across the United States where prior authorization requirements favor proven modalities.
- APAP:Auto-titrating positive airway pressure devices algorithmically adjust pressure delivery based on real-time respiratory event detection. Export markets in Japan and Australia drive volume as these systems reduce dependency on scarce sleep technologists.
- BiPAP:Bilevel positive airway pressure systems alternate inspiratory and expiratory pressure levels for patients with central sleep apnea or hypoventilation syndromes.
- Oral Appliances:Mandibular advancement devices fabricated by dental sleep medicine practitioners capture mild-to-moderate obstructive sleep apnea cases before PAP therapy initiation.
CPAP holds the largest share; momentum sits with APAP as automated titration collapses diagnostic bottlenecks.
End User:
Cost tier stratification separates capital-intensive hospital installations from distributed homecare economics. Premium pricing persists in sleep clinics where diagnostic bundling justifies higher reimbursement.
- Homecare:Patient-owned devices operating in residential settings with remote clinician oversight. Demand concentrates in United States metropolitan corridors where durable medical equipment suppliers maintain local inventory and repair networks.
- Hospitals:Acute care installations for perioperative sleep apnea management and respiratory failure comorbidities. High-reliability specifications and EMR integration requirements sustain pricing premiums in tertiary centers.
- Sleep Clinics:Dedicated diagnostic and titration facilities with in-lab polysomnography capabilities.
- Dental Offices:Point-of-care fabrication and fitting of mandibular advancement devices by credentialed practitioners.
Homecare commands the dominant revenue pool; dental offices are climbing the fastest as primary care referral patterns fragment.
Technology:
Application intensity varies by patient acuity and comorbidity burden. Fixed pressure systems serve stable chronic populations while adaptive technologies address complex cardiorespiratory overlap syndromes.
- Auto-Titration:Machine learning algorithms dynamically adjust pressure parameters without manual sleep lab intervention. United States payers increasingly reimburse unattended home titration studies, accelerating substitution for fixed-pressure protocols.
- Adaptive Servo-Ventilation:Specialized pressure support for central sleep apnea and Cheyne-Stokes respiration in heart failure patients. Concentrated demand in German and Japanese cardiology referral networks with established heart failure management pathways.
- Fixed Pressure:Conventional CPAP with manually determined therapeutic pressure settings.
- Positional Therapy:Vibratory or positional feedback devices targeting supine-predominant obstructive sleep apnea.
Auto-Titration leads volume expansion; Adaptive Servo-Ventilation maintains the steepest pricing tier.
Delivery Mode:
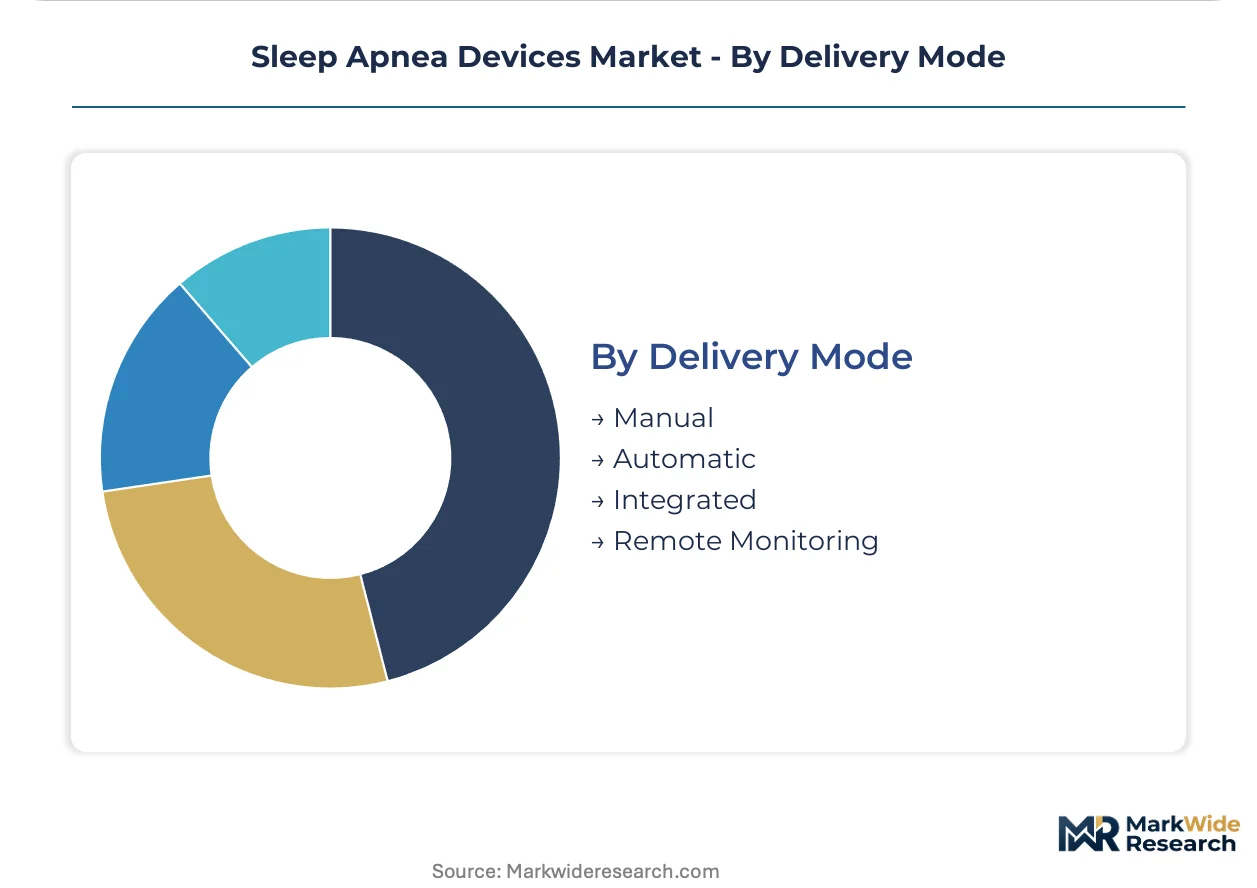
Customer type fragmentation separates institutional procurement from direct-to-consumer channels. Remote monitoring capabilities now table stakes for United States Medicare competitive bidding participation.
- Remote Monitoring:Cloud-connected devices transmitting adherence data to payers and clinicians for reimbursement compliance verification. United States DME suppliers deploy these systems to defend Medicare accreditation and reduce audit exposure.
- Automatic:Self-adjusting pressure delivery without clinician intervention during routine operation. Homecare patients in Australia and Canada favor these systems where geographic distance from sleep centers complicates in-person follow-up.
- Manual:Clinician-directed pressure adjustment requiring facility-based intervention.
- Integrated:Combined diagnostic and therapeutic platforms with embedded sleep staging capabilities.
Remote Monitoring is gaining share fastest; Automatic delivery retains the broadest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between reimbursement-heavy markets where homecare dominates and cash-pay environments where direct-to-consumer channels thrive. Diagnostic penetration rates vary by an order of magnitude across comparable income levels, reflecting regulatory pathway efficiency rather than disease prevalence alone.
United States
Medicare competitive bidding programs and commercial payer prior authorization requirements shape device procurement through durable medical equipment networks. FDA 510(k) clearances for cloud-connected auto-titration systems enable faster feature deployment than full PMA pathways. The Southeast corridor from Florida through Georgia concentrates DME supplier operations and sleep clinic density.
Germany
Statutory health insurance reimbursement for split-night polysomnography with embedded APAP titration compresses diagnostic-to-treatment intervals below European averages. The country's national pharmaceutical regulator, BfArM, coordinates with notified bodies on MDR conformity assessments for algorithm-driven pressure adjustment systems. Industrial concentration in Baden-Württemberg and Bavaria hosts precision manufacturing clusters for turbine airflow generators.
Japan
PMDA marketing authorization requirements for software-as-medical-device features impose longer validation timelines than FDA equivalents, favoring established players with regulatory infrastructure. METI industrial policy supports domestic manufacturing of respiratory care equipment through targeted subsidy programs. The Kansai region around Osaka anchors production capacity for humidification modules and mask cushion assemblies.
Australia
Medicare reimbursement for unattended home sleep studies reaches populations beyond urban sleep center catchments, accelerating diagnostic identification in rural Queensland and Western Australia. The Therapeutic Goods Administration aligns software update requirements with FDA precedent to reduce manufacturer compliance burden. Telemedicine-integrated diagnostic platforms concentrate operational scale in Sydney and Melbourne.
China
NMPA Class II medical device registration for auto-titrating PAP systems requires local clinical trials, creating entry barriers for foreign manufacturers. Volume procurement through provincial centralized purchasing platforms compresses pricing for basic CPAP configurations. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta dominate global supply of motor assemblies and polymer mask components.
Sleep Apnea Devices Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with cloud-connected platform players commanding recurring revenue premiums over pure hardware vendors. The structure rewards manufacturers with proprietary data ecosystems and penalizes those dependent on distributor networks for patient adherence verification. Three archetypes dominate: vertically integrated respiratory care conglomerates, dental sleep medicine specialists, and component-focused contract manufacturers. Competitive moves concentrate on software subscription layering and regional regulatory fast-tracking rather than capacity expansion.
Within the integrated platform tier, ResMed and Philips Respironics occupy positions defined by cloud infrastructure scale and reimbursement network penetration. BMC Medical Co., Ltd. represents the manufacturing efficiency archetype, with corporate structure indicating Chinese operational base. Fisher & Paykel Healthcare Limited exemplifies the humidification technology specialization vector, with geographic origin in New Zealand evident from company nomenclature. These three anchors illustrate divergent strategic postures: platform lock-in versus component excellence versus cost-optimized production.
| Leading Market Players |
|---|
| Curative Medical |
| Somnetics International |
| ResMed |
| SomnoMed |
| BMC Medical Co., Ltd. |
| Philips Respironics |
| React Health |
| Itamar Medical Ltd. |
| Fisher & Paykel Healthcare Limited |
| Others |
Supply Flow & Price Mechanics
Scale economies in turbine airflow generator manufacturing concentrate production among three industrial clusters, compressing unit costs for high-volume CPAP platforms while elevating price floors for specialized adaptive servo-ventilation systems where batch sizes remain constrained.
Pricing Analysis
Long-term rental contracts dominate United States Medicare competitive bidding channels, locking durable medical equipment suppliers into fixed monthly rates that compress margin pools. Three-tier pricing structure across premium, standard, and economy levels separates cloud-connected auto-titration systems with remote monitoring capabilities from basic fixed-pressure CPAP units and refurbished legacy devices. Pricing pressure stems from oral appliance substitution in mild-to-moderate obstructive sleep apnea cases, forcing PAP manufacturers to bundle coaching subscriptions. Homecare patients with high-deductible health plans exhibit highest price sensitivity, while hospital procurement committees prioritize EMR integration over unit cost.
Supply Chain Analysis
Port congestion on transpacific trade lanes elevates inbound logistics costs for medical-grade silicone mask cushion assemblies sourced from Yangtze River Delta compounders. Manufacturing concentration in China, Japan, and Germany supplies motor assemblies, polymer components, and precision turbine housings respectively. Raw material dependencies on Asian silicone compounders, Taiwanese semiconductor foundries for flow sensors, and German precision bearing manufacturers create single-source vulnerability for algorithm-driven pressure adjustment modules. Distribution runs through durable medical equipment supplier networks in metropolitan United States corridors, with direct-to-consumer channels capturing growing accessory share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Home-based diagnostic pathway expansion represents an early-cycle penetration tailwind, as unattended sleep study reimbursement protocols unlock patient identification beyond urban sleep center catchments.
For Market Incumbents: Fortify cloud platform lock-in by deepening software subscription layering and securing FDA 510(k) clearances for adaptive algorithm updates ahead of competitors. Philips Respironics' manufacturing quality remediation and BMC Medical's cost-optimized production both threaten margin positioning; vertical integration into humidification module supply secures component cost control. For New Entrants and Emerging Players: Lead with telemedicine-integrated diagnostic platforms targeting underpenetrated rural populations in Australia and Canada where geographic distance from sleep centers complicates traditional referral patterns. Dental sleep medicine practitioner networks offer the most penetrable channel for mandibular advancement device fabrication before PAP therapy initiation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with integrated adherence monitoring dashboards and coaching app ecosystems that attach to hardware sales. Long-term viability favors platform players over pure-play equipment vendors; watch Medicare competitive bidding program expansions as inflection indicators for durable medical equipment supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Software-as-Medical-Device Clearance | Streamlined premarket review accelerates cloud-connected CPAP feature deployment against PMA pathways. |
| Cloud Platform Integration | Remote adherence data transmission defends Medicare accreditation and reduces audit exposure for DME suppliers. |
| EU MDR Conformity Acceleration | CE marking under 2017/745 regulation secures preferential positioning in European public procurement frameworks. |
| Telemedicine Diagnostic Partnership | Home sleep testing integration reaches rural Australian and Canadian populations beyond urban sleep center catchments. |
| Software Subscription Layering | Recurring revenue from coaching apps improves lifetime value per patient beyond hardware margin capture. |
Methodological Framework
Cross-validation between primary interviews with sleep technologists, biomedical engineers, and durable medical equipment procurement managers and secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, and GPO contract repositories anchors the qualitative findings. Bottom-up demand modeling triangulates against top-down market sizing across product type, technology, and delivery mode segmentation dimensions.
Sensitivity analysis tests forecast robustness across auto-titration adoption scenarios and reimbursement policy shifts throughout the projection horizon. Segmentation modeling incorporates product architecture choices, end-user cost tier stratification, and regional regulatory pathway efficiency as core dimensions. CAGRs derive from installed base expansion rates, replacement cycle compression, and software-enabled service revenue attachment.
The analysis sits within stated boundaries; outcomes outside FDA clearance timeline assumptions, sleep technologist graduation rates, or polymer supply stability would require recalibration. Forecasts reflect documented assumptions regarding Medicare competitive bidding program continuity and cloud platform interoperability standards. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Dry Powder Inhaler (DPI) Market
Medical Devices
Wearable Artificial Kidney Market
Medical Devices
Pelvic Reconstruction Market
Medical Devices
Intrauterine Insemination Devices Market
Medical Devices
Organ Transport Devices Market
Medical Devices
Europe Manual Resuscitators Market
Medical Devices
India Contraceptive Devices Market
Medical Devices
UK Artificial Organs and Bionic Implants Market
Medical Devices
Global Venous Blood Collection Devices Market
Medical Devices
Pressotherapy Systems Market
Medical Devices
Smart Medical Devices Market
Medical Devices
Sinus Implants Market
Medical Devices
Global Self Care Medical Devices Market
Medical Devices
Steam Inhaler Devices Market
Medical Devices
Pelvic Floor Electrical Stimulation Devices Market
Medical Devices
Medical Electronics Market