
 Digital Orthodontics Market | 2026-2036
Digital Orthodontics Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Orthodontics Market Analysis
EU MDR compliance deadlines for software-as-medical-device are shifting procurement criteria across European orthodontic practices. 3Shape leverages its intraoral scanner ecosystem to sustain recurring revenue from treatment planning subscriptions. Align Technology dominates clear aligner volume through its proprietary thermoplastic material science and direct-to-practice digital workflow. Ormco anchors the fixed appliance segment with self-ligating bracket systems that integrate with third-party digital treatment platforms.
Digital orthodontics encompasses computer-aided diagnosis, simulation, and fabrication technologies that replace conventional physical impressions and manual wire bending with sub-50-micron accuracy digital workflows. The field employs stereolithography 3D printing, AI-driven root movement algorithms, and cloud-based treatment monitoring to deliver predictable tooth positioning outcomes. Aligners command the largest revenue pool within product type segments due to patient preference for aesthetic removable therapy and higher per-case fees. 3D printing technology leads manufacturing throughput growth as printer resolution improvements enable same-day appliance delivery in dental laboratories. Cosmetic orthodontics application segments attract premium pricing through direct-to-consumer marketing channels and reduced chair time requirements.
FDA 510(k) premarket notification requirements govern AI treatment planning software and custom aligner manufacturing in the United States, while EU MDR Class IIa classification imposes clinical evidence standards on European market entrants. ISO 13485 quality management certification remains mandatory for scanner and appliance producers supplying regulated jurisdictions. China's NMPA medical device registration creates a separate approval pathway for imported digital orthodontic platforms seeking access to its domestic clinic network. Stakeholders must monitor evolving software validation requirements as regulators scrutinize autonomous treatment planning algorithms.
Market Dynamics
AI-assisted treatment planning algorithms are compressing orthodontic workflow timelines from weeks to hours, forcing established scanner manufacturers to bundle software subscriptions with hardware or face margin erosion from standalone SaaS competitors.
Growth Catalysts
- FDA 510(k) Streamlining:The FDA's premarket notification pathway for AI-driven orthodontic software accelerates commercialization timelines for algorithm developers seeking US market entry.
- Thermoplastic Material Science:Advances in multilayer polymer engineering enable aligners to deliver complex root movements previously requiring fixed appliances.
- Adult Cosmetic Demand:Metropolitan dental service organizations in the United States, Germany, and China report accelerating patient preference for aesthetic removable therapy.
Market Restraints
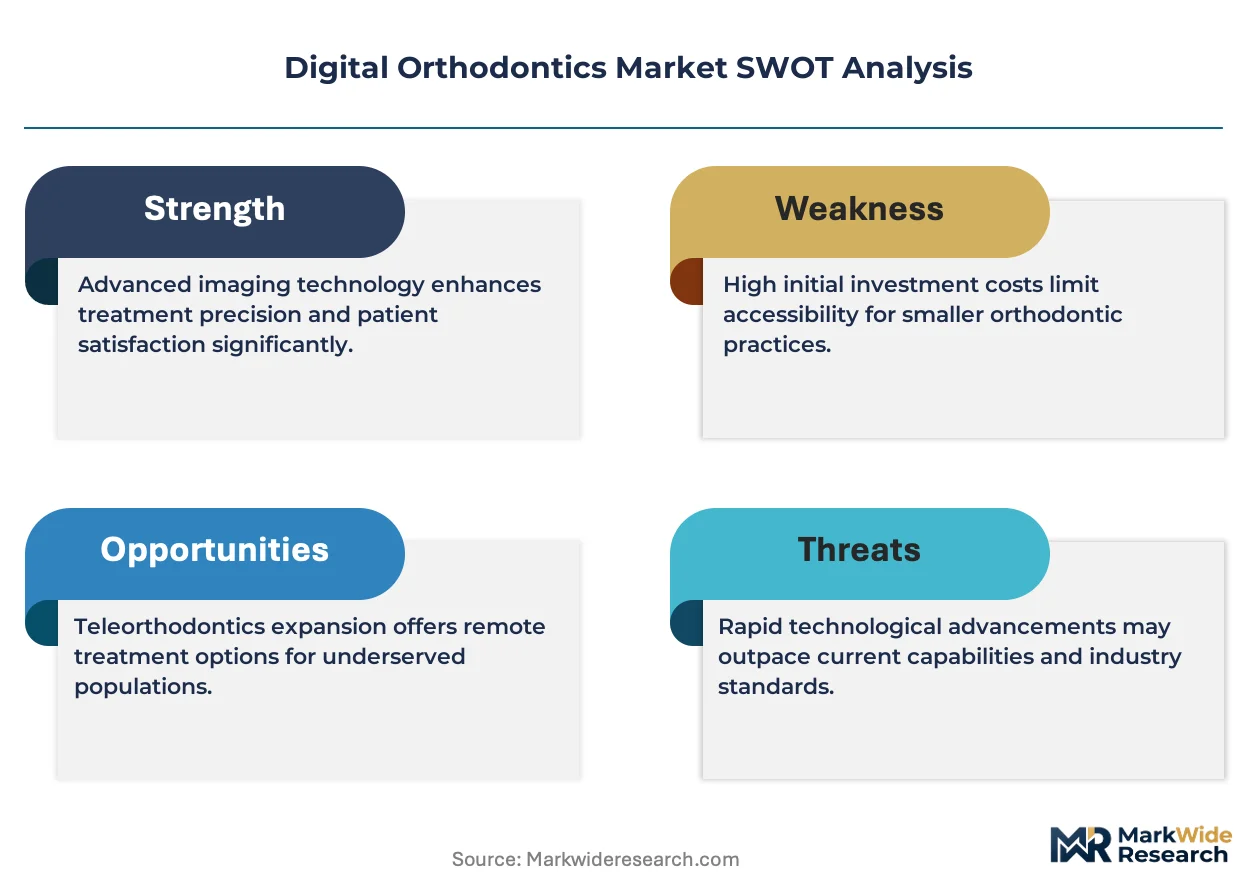
- EU MDR Compliance Burden:The European Medical Device Regulation's Class IIa clinical evidence standards impose documentation costs that favor large incumbents over emerging software entrants.
- Intraoral Scanner Supply Concentration:Three manufacturers control proprietary scanning ecosystems, creating vendor lock-in that limits interoperability across treatment planning platforms.
- Clinical Validation Gaps:Autonomous treatment planning algorithms lack long-term outcome data for complex malocclusion cases, constraining adoption in academic orthodontic settings.
Strategic Opportunities
- Direct-to-Consumer Channels:East Asian teleorthodontia platforms demonstrate viable remote monitoring models that bypass traditional clinic-based distribution.
- Same-Day Appliance Delivery:Sub-50-micron resolution stereolithography enables dental laboratories to compress aligner fabrication from two weeks to single-visit service.
- Cloud-Based Treatment Monitoring:Remote patient tracking applications reduce chair time requirements while expanding addressable geography beyond metropolitan catchment areas.
Industry Challenges
- Algorithm Training Data Scarcity:High-quality annotated orthodontic imaging datasets remain concentrated within proprietary corporate archives, limiting third-party AI development.
- ISO 13485 Certification Complexity:Quality management system implementation for software-as-medical-device requires 18-24 month timelines that delay revenue recognition for startups.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Orthodontics Market |
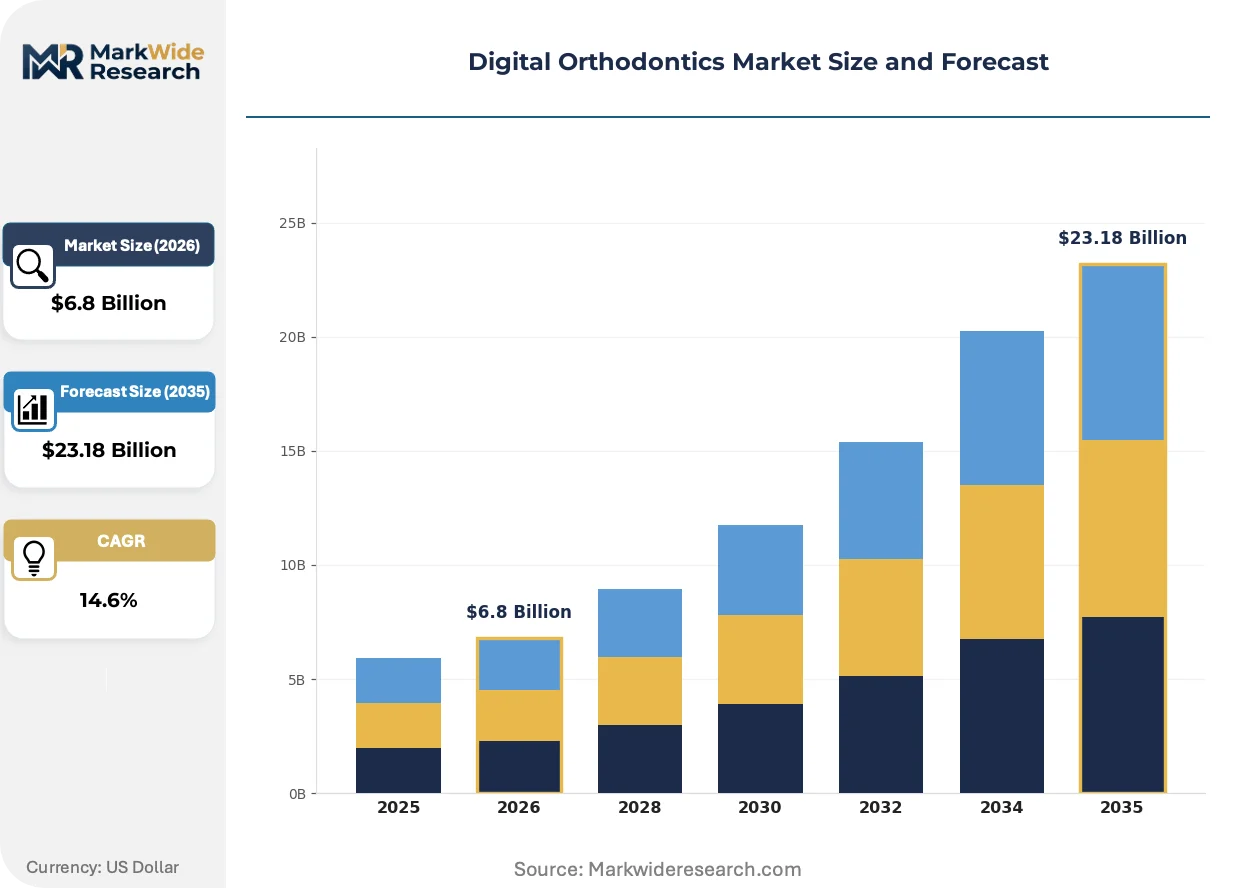
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $23.18 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aligners, Digital Braces, Imaging Software, Orthodontic Appliances Technology: 3D Printing, CAD/CAM, Digital Scanners, Virtual Treatment Planning End User: Orthodontic Clinics, Dental Practices, Research Institutes, Dental Laboratories Application: Cosmetic Orthodontics, Functional Orthodontics, Preventive Orthodontics, Post-Operative Treatment |
| Companies Covered | 3Shape, Ormco, Align Technology, Planmeca, Carestream Health, 3M, Stratasys, Angelalign Technology, Dentsply Sirona, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Orthodontics Market Emerging Trajectories
Digital orthodontics is experiencing fundamental workflow compression as cloud infrastructure, AI inference engines, and chairside manufacturing converge into integrated clinical systems that reduce dependency on external dental laboratories.
Intraoral scanning hardware paired with real-time AI segmentation algorithms is consolidating diagnostic and treatment planning stages into single-visit protocols. Specialist orthodontic practices in North American metropolitan markets now deploy chairside 3D printing for same-day appliance delivery. This technology compression eliminates traditional impression shipping logistics and reduces patient case turnaround from fourteen days to under four hours.
The EU MDR's software-as-medical-device classification requirements are forcing European orthodontic platform developers to maintain clinical evidence dossiers for algorithm updates. Manufacturers must now treat each significant AI model revision as a regulatory submission event. This policy friction slows iterative improvement cycles and advantages firms with established notified body relationships.
Patient acquisition patterns are rotating toward direct-to-consumer marketing channels that bypass traditional dentist referral networks. Teleorthodontia platforms in China and South Korea demonstrate remote initial screening via smartphone imaging, with physical clinic visits reserved for complex case escalation. This channel disintermediation compresses customer acquisition costs while expanding addressable markets beyond conventional dental service organization territories.
Digital Orthodontics Market Segmentation
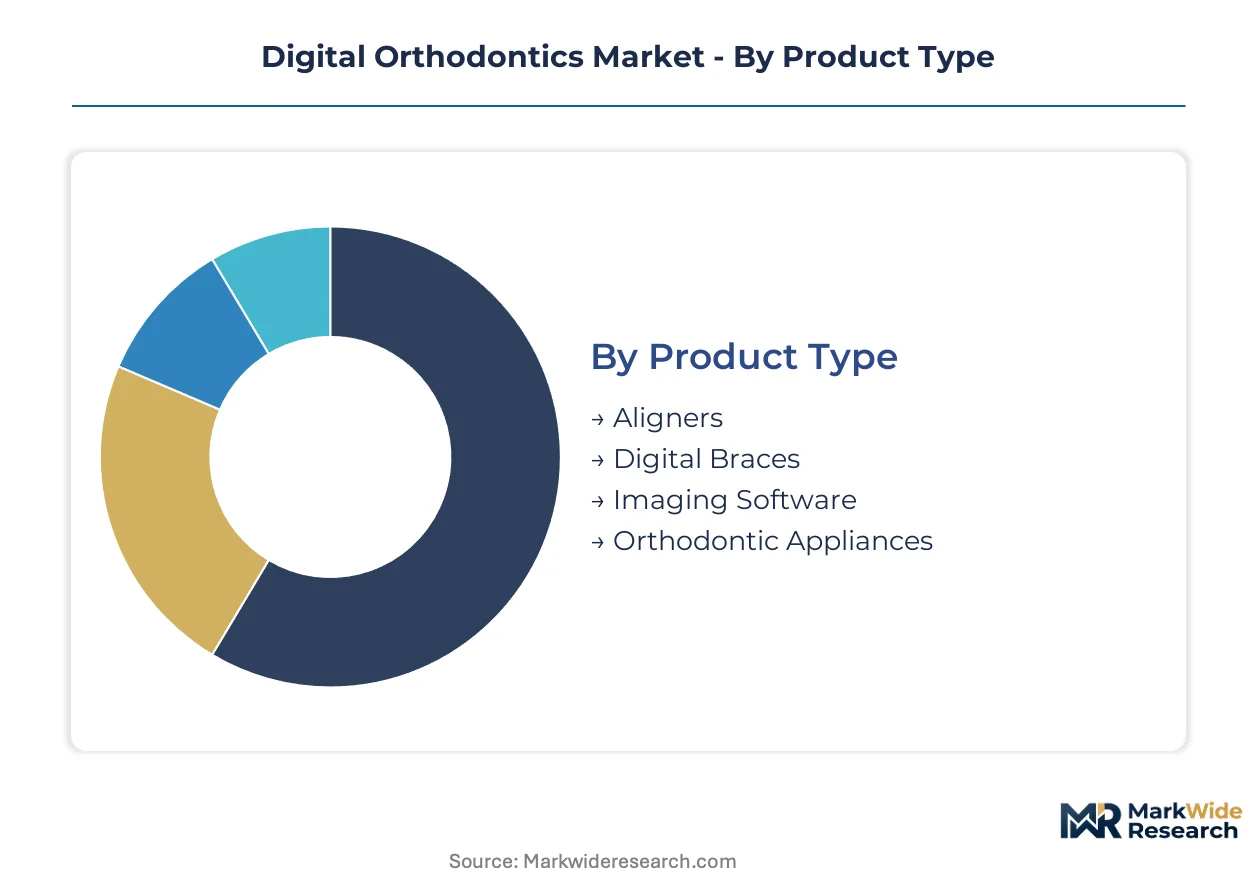
Segmentation in digital orthodontics reveals how value migrates between hardware, software, and service layers. Manufacturers configure product portfolios around either bundled ecosystem plays or modular best-of-breed positioning.
Product Type:
Standardization dominates commodity brackets while premium tiers demand bespoke material engineering and proprietary algorithm stacks.
- Aligners:Multilayer thermoplastic polymers engineered for sequential force delivery now achieve root movements previously requiring fixed appliances. Demand concentrates in United States metropolitan dental service organizations and East Asian direct-to-consumer platforms where adult cosmetic patients pay premium fees for aesthetic removable therapy.
- Digital Braces:Self-ligating bracket systems integrate with third-party digital treatment platforms through standardized file exchange protocols. Adoption is accelerating in Germany and China where orthodontic clinics seek hybrid workflows combining fixed appliance precision with digital planning efficiency.
- Imaging Software:AI-driven segmentation and root movement simulation tools.
- Orthodontic Appliances:Custom-fabricated retainers, space maintainers, and auxiliary devices.
Most installed capacity flows through Aligners. Expansion is steepest in Digital Braces.
Technology:
Resolution specifications and regulatory validation status separate laboratory-grade systems from chairside deployment candidates.
- 3D Printing:Sub-50-micron resolution stereolithography enables same-day appliance delivery in dental laboratories equipped with biocompatible resin workflows. Adoption clusters in North American orthodontic practices seeking to eliminate external laboratory dependencies and compress case turnaround timelines.
- CAD/CAM:Computer-aided design and manufacturing systems for bracket placement and wire bending automation.
- Digital Scanners:Intraoral scanning hardware paired with real-time AI segmentation.
- Virtual Treatment Planning:Cloud-based simulation platforms for remote collaboration.
Capital deployment favors 3D Printing for throughput expansion. Virtual Treatment Planning gains share fastest among software categories.
End User:
Procurement authority and reimbursement pathways determine whether sales cycles target individual practitioners or institutional purchasing committees.
- Orthodontic Clinics:Specialist practices with dedicated orthodontic software budgets and trained staff.
- Dental Practices:General dentistry settings adding orthodontic services through aligner integration.
- Research Institutes:Academic medical centers conducting clinical validation studies for autonomous treatment algorithms.
- Dental Laboratories:Centralized fabrication facilities serving multiple clinic accounts with volume-based pricing.
Volume concentrates in Orthodontic Clinics. Dental Practices show the steepest expansion trajectory as generalists enter cosmetic orthodontics.
Application:
Clinical outcome requirements and patient payment models create divergent margin profiles across intervention categories.
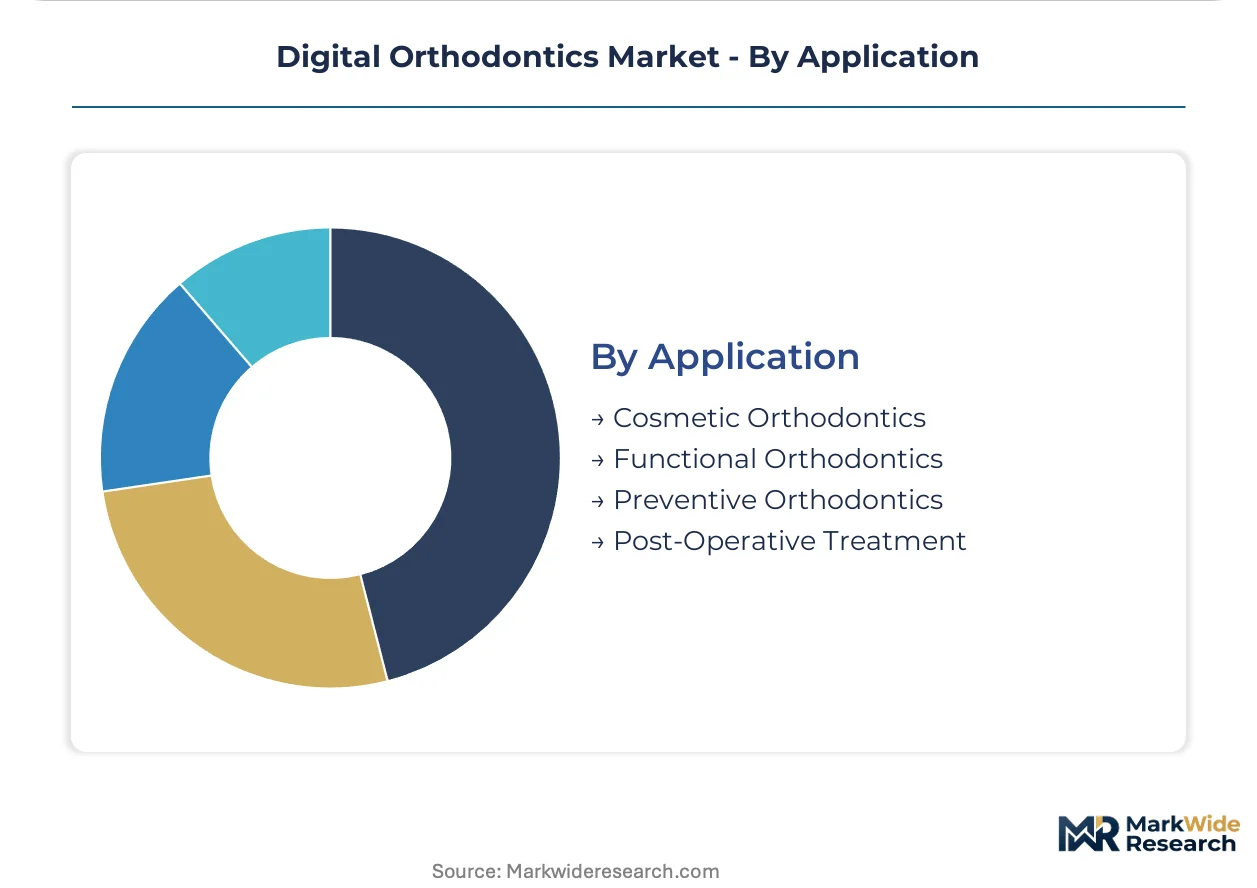
- Cosmetic Orthodontics:Aesthetic-driven treatments for adult patients seeking discrete appliance options. Demand localizes in United States and Chinese metropolitan markets where direct-to-consumer marketing channels bypass traditional referral networks and reduce customer acquisition costs.
- Functional Orthodontics:Malocclusion correction addressing bite function and occlusal health.
- Preventive Orthodontics:Early intervention protocols for pediatric patients.
- Post-Operative Treatment:Retention and stabilization following surgical or comprehensive orthodontic care.
Revenue pools are deepest in Cosmetic Orthodontics. Functional Orthodontics is climbing the fastest as AI planning penetrates complex case categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Digital orthodontics originated in United States orthodontic research centers during the 1990s, with Align Technology pioneering thermoplastic aligner fabrication from Stanford University laboratories. This American foundation established the template for computer-aided treatment planning now diffusing across specialist clinics worldwide.
United States
FDA 510(k) premarket notifications govern AI-assisted orthodontic software and custom appliance manufacturing, streamlining commercialization for algorithm developers. Metropolitan dental service organizations in California, Texas, and New York drive clear aligner volume through direct-to-practice digital workflows. The Boston-Cambridge corridor anchors venture financing for orthodontic AI startups seeking regulatory validation.
Germany
EU MDR Class IIa clinical evidence standards reshape procurement criteria across Baden-Württemberg and Bavaria orthodontic practices. Self-ligating bracket systems integrate with third-party digital platforms in Frankfurt and Munich specialist clinics. The country's notified body infrastructure advantages established manufacturers over emerging software entrants seeking CE marking.
China
NMPA medical device registration creates a separate approval pathway for imported platforms accessing domestic clinic networks. Direct-to-consumer teleorthodontia platforms in Shanghai and Shenzhen demonstrate remote screening models that bypass traditional dentist referrals. Yangtze River Delta manufacturing clusters supply stereolithography hardware for same-day appliance delivery.
Japan
PMDA software-as-medical-device classifications impose validation requirements on AI treatment planning tools entering Tokyo and Osaka orthodontic markets. Conservative clinical adoption patterns favor incremental digitization of existing fixed appliance workflows over disruptive aligner transitions. Kanto region academic medical centers conduct longitudinal outcome studies for autonomous planning algorithms.
South Korea
MFDS medical device regulations align with international standards while maintaining separate documentation requirements for AI-driven orthodontic platforms. Seoul Capital Area cosmetic dentistry clinics pioneer smartphone-based remote monitoring applications that reduce chair time requirements. Busan-Ulsan manufacturing bases export intraoral scanning hardware to Southeast Asian markets.
Digital Orthodontics Market Vendor Landscape
Premium-margin players sit above commodity-margin players across software subscription and hardware bundling dimensions, with ecosystem control determining pricing power. Three manufacturers dominate proprietary scanning ecosystems, creating vendor lock-in that limits interoperability. The competitive field organizes around integrated platform providers, standalone software specialists, and hardware-agnostic appliance fabricators. Dominant moves include strategic partnerships between scanner manufacturers and treatment planning developers, plus backward integration into proprietary material science.
Within the integrated platform tier, Align Technology and 3Shape exemplify ecosystem bundling strategies that capture recurring revenue from treatment planning subscriptions. Ormco occupies a position anchoring the fixed appliance segment through interoperability with third-party digital workflows. These three companies represent contrasting archetypes: Align Technology demonstrates vertical control over thermoplastic materials and direct-to-practice distribution; 3Shape leverages scanner hardware penetration to sustain software attach rates; Ormco maintains positioning through bracket system precision rather than proprietary scanning capture.
| Leading Market Players |
|---|
| 3Shape |
| Ormco |
| Align Technology |
| Planmeca |
| Carestream Health |
| 3M |
| Stratasys |
| Angelalign Technology |
| Dentsply Sirona |
| Others |
Supply Flow & Price Mechanics
Metropolitan dental service organization procurement consolidation in the United States, Germany, and China is forcing scanner manufacturers to bundle hardware with software subscriptions or sacrifice margin to standalone SaaS competitors, compressing pricing power across the hardware tier while elevating recurring revenue multiples for integrated platform providers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the digital orthodontics landscape, with premium tiers capturing value through FDA 510(k) cleared AI algorithms and proprietary thermoplastic material formulations while economy tiers compete on per-unit scanner hardware cost. Price differentiation rests on ISO 13485 certification status and geographic delivery infrastructure, with European practices paying compliance premiums for EU MDR Class IIa validated software. Cost compression in the hardware tier is intensifying because intraoral scanner supply concentrates among three ecosystem providers. General dentistry settings entering cosmetic orthodontics exhibit highest price sensitivity, while specialist orthodontic clinics with dedicated software budgets demonstrate lowest sensitivity to subscription pricing.
Supply Chain Analysis
Thermoplastic polymer supply rests on German and Japanese specialty chemical producers with proprietary multilayer engineering capabilities for sequential force delivery aligners. Stereolithography 3D printing hardware sources from Yangtze River Delta manufacturing clusters in China and select North American precision equipment fabricators. Cloud infrastructure for treatment planning platforms draws from hyperscaler data center networks concentrated in the United States and Ireland. Single-source vulnerability persists in AI training data archives held by incumbent platform providers. Distribution runs through direct-to-practice digital workflows for aligner platforms and dental laboratory networks for appliance fabrication.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital orthodontics functions as a regulatory compounder where FDA 510(k) clearance pathways and EU MDR software-as-medical-device classifications create escalating compliance barriers that systematically advantage scaled incumbents with established notified body relationships.
For Market Incumbents: Deploy backward integration into proprietary thermoplastic material science to defend margin position against emerging aligner fabricators with commodity resin sourcing. Anchor ecosystem control through scanner-hardware-to-software bundling that raises switching costs for orthodontic clinics invested in treatment planning workflows. Counter standalone SaaS competitors by accelerating AI model iteration cycles within existing regulatory dossiers. For New Entrants and Emerging Players: The price-point gap between premium ecosystem bundles and economy scanner hardware creates white-space opportunity for modular best-of-breed positioning targeting general dentistry practices in secondary United States metropolitan markets. East Asian teleorthodontia platforms demonstrate viable remote monitoring models with compressed customer acquisition costs. Pursue regulatory arbitrage through initial MFDS or NMPA clearance in South Korea or China before attempting FDA or EU MDR submission. For Investors and Strategic Acquirers: Asymmetric upside sits with orthodontic AI startups possessing annotated imaging datasets and established notified body relationships for EU MDR Class IIa software validation. Long-term viability in this market hinges on recurring revenue attach rates rather than hardware shipment volumes. Watch FDA 510(k) submission volume for autonomous treatment planning algorithms as inflection indicator for competitive intensity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance pathways accelerate commercialization timelines for AI-assisted orthodontic software developers seeking United States market entry. |
| CE Marking Pathway | EU MDR Class IIa clinical evidence standards favor established manufacturers with notified body relationships over emerging entrants. |
| Hospital System Partnership | Metropolitan dental service organization procurement consolidation creates volume concentration for integrated platform providers. |
| Software Companion Development | Cloud-based treatment monitoring applications expand addressable geography beyond traditional clinic catchment areas. |
| Reimbursement Strategy | Direct-to-consumer marketing channels bypass traditional dentist referral networks and reduce customer acquisition costs. |
Methodological Framework
Direct dialogue with orthodontic practice owners, dental laboratory operations managers, biomedical engineers at scanner manufacturers, and regulatory affairs specialists at aligner platform companies grounded this analysis in operational reality. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR notified body submission records, NMPA medical device registration filings, and orthodontic clinical trial registries. Bottom-up and top-down triangulation cross-checked volume estimates across hardware shipment data, software subscription metrics, and appliance fabrication throughput.
Bottom-up modeling of intraoral scanner installations, aligner case starts, and treatment planning software seats across the projection horizon anchored volume estimates. Segmentation dimensions included product type, technology layer, end-user category, application, and geographic regulatory cluster. CAGRs were derived from trend extrapolation of adult cosmetic patient preference data and AI-assisted workflow adoption curves. Industry-specific forecast inputs incorporated stereolithography printer resolution improvement timelines and EU MDR compliance deadline impacts on European procurement patterns.
Caveats apply where autonomous treatment planning algorithm validation gaps or thermoplastic material science breakthroughs could materially shift the outlook. Forecasts reflect assumptions about regulatory pathway stability and orthodontic clinic consolidation trajectories. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Handheld Bladder Scanner Market
Medical Devices
Global External Fixators Market
Medical Devices
Transplant Monitoring Kits Market
Medical Devices
Global Emerging Mental Health Devices and Platforms Market
Medical Devices
Pelvic Muscle Probes Market
Medical Devices
Europe Biopsy Devices Market
Medical Devices
Global Automatic Stair Climbing Wheelchair Market
Medical Devices
Large Volume Nebulizers Market
Medical Devices
China Respiratory Devices Market
Medical Devices
Healthcare Additive Manufacturing Market
Medical Devices
US Trauma Fixation Devices Market
Medical Devices
Leadless Pacing Systems Market
Medical Devices
Sweden Respiratory Devices Market
Medical Devices
Implantable Pacemaker Market
Medical Devices
Global Abdominal Surgical Robot Market
Medical Devices
Global Airway Stent/Lung Stent Market