
 Global Tympanostomy Products Market | 2026-2036
Global Tympanostomy Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tympanostomy Products Market Foresight
Premium-grade titanium tube specifications is redrawing competitive boundaries in tympanostomy care. Medtronic leverages its R&D intensity across North American and European distribution networks. Smith+Nephew anchors its position through specialized ENT surgical portfolios. Olympus Corporation dominates manufacturing scale in fluoroplastic and silicone tube variants.
Tympanostomy products are tiny cylindrical implants inserted through the tympanic membrane to ventilate the middle ear and equalize pressure, typically manufactured from silicone, titanium, or fluoroplastic with outer diameters ranging from 1.14 mm to 1.27 mm and functional lifespans tailored to short-term resorption or long-term retention. Their primary purpose is to prevent fluid accumulation and restore hearing in chronic otitis media or eustachian tube dysfunction patients. Ventilation tubes command the largest volume share due to standardized reimbursement across ambulatory settings, while titanium segments capture disproportionate margin pools from pediatric and revision surgery applications. Donaldson tubes occupy a mature niche with limited growth, whereas paparella tubes sustain demand in specialized cholesteatoma management protocols.
FDA 510(k) clearance pathways and CE marking under the EU Medical Device Regulation shape product entry timelines and biocompatibility testing burdens for silicone and polyethylene formulations. The EPA and REACH frameworks increasingly influence fluoroplastic raw material sourcing and waste disposal compliance across manufacturing facilities. WHO prequalification standards for surgical devices are gaining traction in emerging procurement systems. Stakeholders must monitor evolving MDR technical documentation requirements and titanium supply chain concentration before committing to capacity expansion.
Market Dynamics
Pediatric clinics are driving specification upgrades toward titanium-ventilation tubes as FDA and CE marking requirements tighten biocompatibility standards for silicone and fluoroplastic formulations.
Growth Catalysts
- Pediatric ENT expansion:Ambulatory surgical centers in the United States and Germany are expanding pediatric otology services, creating sustained pull for premium-grade titanium tubes with extended functional retention.
- REACH fluoroplastic compliance:ECHA restrictions on perfluorinated compound manufacturing are accelerating material substitution toward medical-grade silicone and surface-modified titanium alloys.
- Revision surgery protocols:Specialized cholesteatoma management centers in Japan are standardizing paparella tube specifications for complex middle ear reconstruction cases.
Market Restraints
- Titanium supply concentration:Sponge and mill product sourcing clusters in Russia and China expose manufacturers to export control volatility and alloy specification inconsistency.
- MDR technical documentation burden:EU Medical Device Regulation clinical evaluation requirements extend CE marking timelines for novel tube geometries beyond thirty-six months.
- Fluoroplastic waste disposal:EPA hazardous waste regulations and state-level PFAS restrictions in California and New York elevate end-of-life compliance costs for silicone-fluoroplastic composite tubes.
Strategic Opportunities
- Brazilian public procurement:ANVISA harmonization with ISO 13485 standards opens access to government-funded pediatric otology programs through centralized hospital purchasing consortia.
- Bioresorbable magnesium alloys:Convergence of corrosion-controlled metallurgy and minimally invasive insertion techniques enables single-procedure pediatric applications without secondary extraction.
- Tele-otology screening:Remote diagnostic platforms in rural India are identifying chronic otitis media cases earlier, expanding addressable patient populations beyond urban tertiary centers.
Industry Challenges
- Micro-machining skill scarcity:Precision tube fabrication requires sub-millimeter tolerance control that outstrips available training pipelines in Eastern European and Southeast Asian manufacturing hubs.
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization studies face eighteen-month queue times at accredited laboratories, compressing product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tympanostomy Products Market |
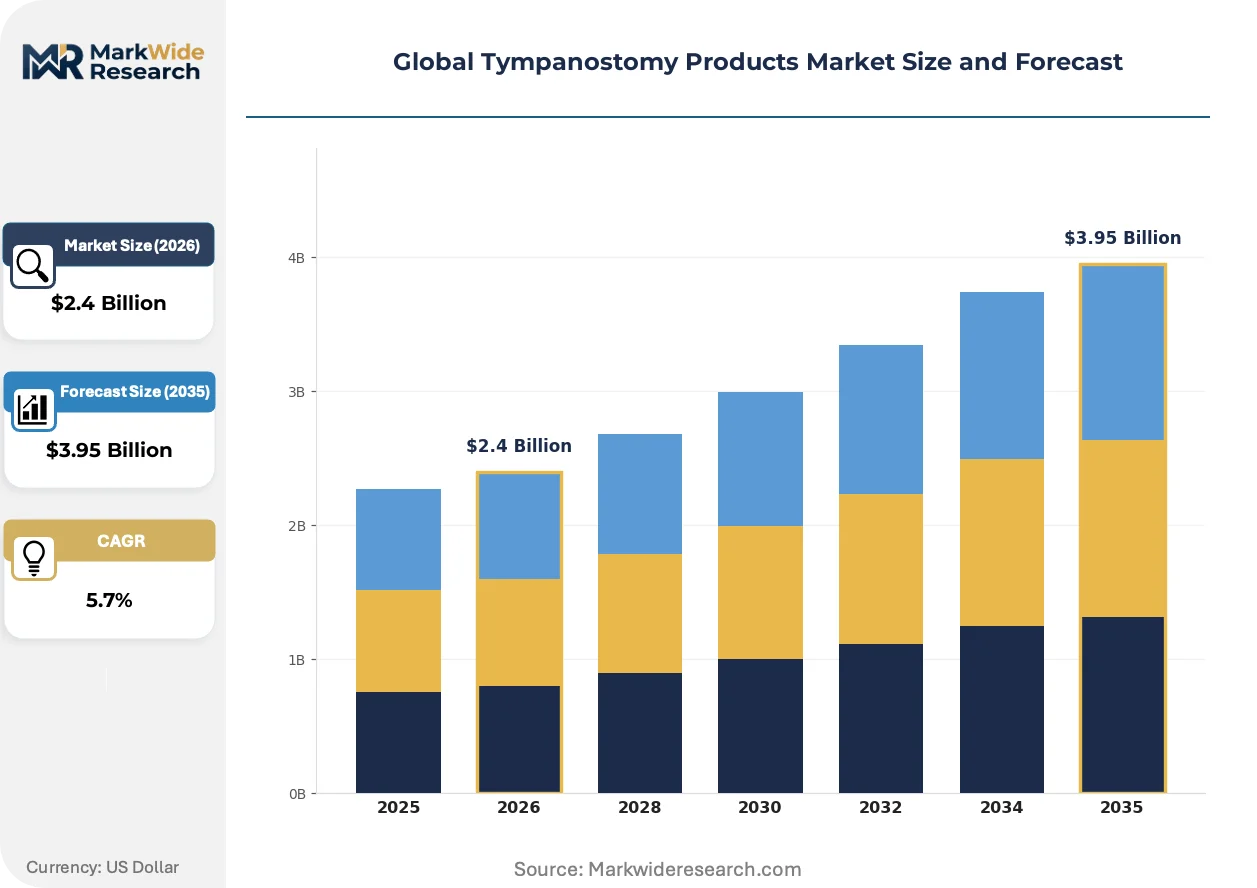
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.95 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ventilation Tubes, Pressure Equalization Tubes, Paparella Tubes, Donaldson Tubes Application: Otitis Media, Eustachian Tube Dysfunction, Tympanic Membrane Perforation, Cholesteatoma End User: ENT Clinics, Ambulatory Surgical Centers, Pediatric Clinics, Specialized Hospitals Material: Silicone, Polyethylene, Titanium, Fluoroplastic |
| Companies Covered | Atos Medical, Preceptis Medical, Olympus Corporation, Medtronic, Grace Medical, Summit Medical, Integra LifeSciences Corporation, Smith+Nephew, Adept Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tympanostomy Products Market Shifts & Advancements
Material science advances and regulatory harmonization are compressing product development cycles while fragmenting traditional supply relationships between raw material suppliers and finished device manufacturers.
Surface-engineered titanium alloys with nanotextured osseointegration layers are fragmenting the long-standing silicone tube dominance in pediatric applications. Children's hospitals in the United States and Germany are specifying these variants for patients with history of tube extrusion or persistent otorrhea. The technology is fragmenting procurement decisions away from commoditized ventilation tubes toward patient-matched material selection protocols.
EU Medical Device Regulation Annex I general safety and performance requirements are forcing manufacturers to document clinical evidence for tube retention duration claims. The regulation compresses market access for legacy silicone designs lacking prospective outcome data. European notified bodies are prioritizing titanium and bioresorbable submissions, redirecting R&D investment from fluoroplastic platforms.
Consolidated purchasing by United States hospital networks is compressing supplier margins and forcing direct manufacturer-contractor relationships that bypass traditional distributor markups. Integrated delivery networks in Texas and Florida are mandating standardized tube specifications across affiliated ambulatory surgery centers. The shift is most visible in pediatric-focused health systems where volume commitments secure preferential pricing for premium titanium inventories.
Global Tympanostomy Products Market Segmentation
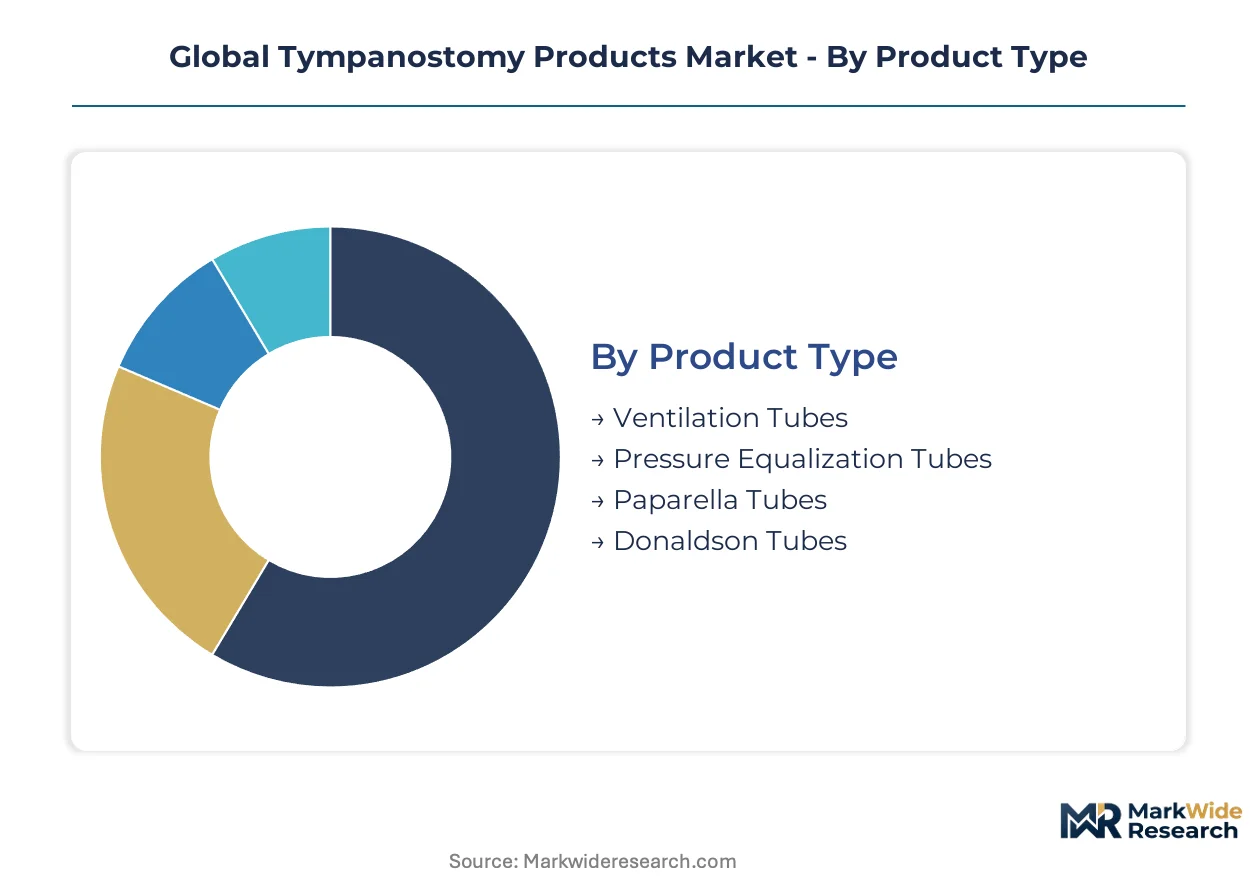
Material selection and clinical setting specificity drive purchasing fragmentation across the tympanostomy value chain. Surgeons weigh biocompatibility profiles against reimbursement codes while procurement teams negotiate volume commitments tied to ambulatory network affiliations.
Product Type:
Domestic manufacturing concentrates on standardized ventilation tubes for high-volume ambulatory procedures, while specialized variants command export premiums from revision surgery centers in Germany and Japan.
- Ventilation Tubes:Cylindrical silicone or titanium implants with 1.14 mm to 1.27 mm outer diameters designed for middle ear pressure equalization. Pediatric clinics in the United States specify these for recurrent otitis media cases, with titanium variants capturing premium positioning amid FDA biocompatibility tightening.
- Pressure Equalization Tubes:Shorter-retention designs manufactured from fluoroplastic or medical-grade polyethylene for temporary dysfunction management. Demand clusters in German ambulatory surgical centers seeking REACH-compliant alternatives to perfluorinated formulations.
- Paparella Tubes:Specialized configurations for complex cholesteatoma reconstruction protocols.
- Donaldson Tubes:Mature designs with limited growth trajectory in niche revision applications.
Ventilation tubes hold the largest share; momentum sits with pressure equalization tubes as material substitution accelerates.
Application:
Cost tier stratification separates high-reimbursement cholesteatoma procedures from commoditized otitis media interventions.
- Otitis Media:The dominant indication driving standardized ventilation tube volumes across pediatric populations.
- Eustachian Tube Dysfunction:Pressure equalization tubes address persistent barometric instability in adult patients.
- Tympanic Membrane Perforation:Repair adjunct applications requiring biocompatible temporary stenting.
- Cholesteatoma:Complex middle ear reconstruction demanding specialized paparella specifications and extended surgical time allowances.
Otitis media dominates procedure volumes; cholesteatoma applications command the steepest expansion trajectory amid specialized center proliferation.
End User:
Customer type fragmentation splits procurement between integrated delivery networks and independent specialty practices.
- ENT Clinics:Independent otology practices purchasing mixed material portfolios based on surgeon preference.
- Ambulatory Surgical Centers:High-volume settings in Texas and Florida mandating standardized titanium specifications across network affiliations.
- Pediatric Clinics:Premium-grade titanium adopters with specification authority tied to children's hospital systems.
- Specialized Hospitals:Tertiary centers in Japan and Germany managing complex revision and cholesteatoma caseloads.
Ambulatory surgical centers capture the highest throughput; pediatric clinics are gaining share fastest through titanium upgrade cycles.
Material:
Supply concentration in titanium sponge processing shapes margin structures differently than commoditized silicone compounding.
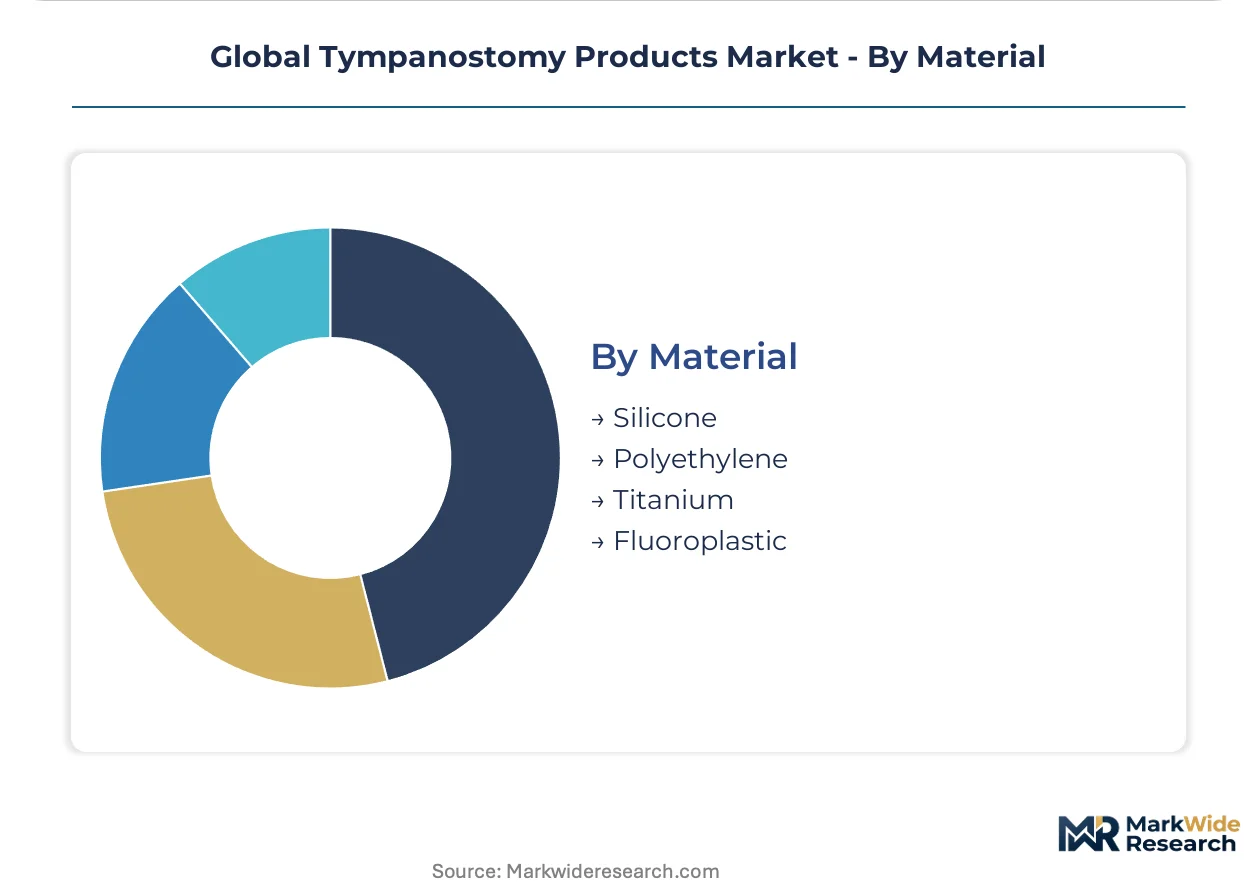
- Silicone:Medical-grade elastomer formulations facing ISO 10993 cytotoxicity testing backlogs and MDR clinical evidence requirements.
- Polyethylene:Lower-cost alternative for short-term retention applications with limited pediatric adoption.
- Titanium:Surface-engineered alloys with nanotextured osseointegration layers fragmenting procurement toward patient-matched selection protocols in U.S. and German children's hospitals.
- Fluoroplastic:PTFE and FEP variants confronting EPA hazardous waste regulations and ECHA perfluorinated compound restrictions.
Silicone retains volume leadership; titanium is climbing the fastest as biocompatibility standards tighten and pediatric specification authority consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for titanium sponge and medical-grade silicone concentrates supply risk in Russia and China, while finished device exports flow predominantly toward the United States, Germany, and Japan where reimbursement density supports premium positioning.
United States
Pediatric clinics in Texas and Florida are mandating standardized titanium specifications across ambulatory surgery center networks. FDA 510(k) clearance pathways shape entry timelines for novel tube geometries. Children's hospital systems in Boston and Philadelphia anchor procurement authority for surface-engineered alloys.
Germany
Specialized cholesteatoma centers in Munich and Hamburg drive demand for paparella tube configurations. ECHA REACH restrictions on perfluorinated compounds accelerate material substitution toward medical-grade silicone. The Stuttgart industrial corridor hosts precision micro-machining clusters serving ENT device fabrication.
Japan
Revision surgery protocols in Tokyo and Osaka tertiary centers standardize titanium specifications for complex middle ear reconstruction. PMDA biocompatibility requirements align with ISO 10993 cytotoxicity testing standards. The Nagoya manufacturing belt concentrates fluoroplastic and silicone tube production for domestic and regional supply.
Brazil
Government-funded pediatric otology programs in São Paulo and Rio de Janeiro are expanding access through centralized hospital purchasing consortia. ANVISA harmonization with ISO 13485 standards streamlines registration for foreign manufacturers. The São Paulo state health network anchors volume procurement for ventilation tube inventories.
India
Tele-otology screening platforms in rural Maharashtra and Karnataka are identifying chronic otitis media cases earlier than urban tertiary referral patterns. CDSCO medical device rules govern silicone and titanium implant registration timelines. The Hyderabad medical device cluster is developing assembly capacity for standard ventilation tube variants.
Global Tympanostomy Products Market Competitive Landscape
Listed leaders compete with private specialists across material science capabilities and regulatory navigation bandwidth. The vendor base splits between diversified medical technology conglomerates with ENT surgical portfolios and focused single-product manufacturers serving regional procurement systems. Two archetypes dominate: integrated device manufacturers controlling titanium alloy supply relationships, and specialized otology suppliers concentrating on surgeon training and clinical evidence generation. Competitive moves center on backward integration into titanium sponge sourcing and strategic partnerships with children's hospital systems for specification authority.
Within the diversified conglomerate tier, Medtronic, Olympus Corporation, and Smith+Nephew exemplify scale-driven positioning. Medtronic leverages North American and European distribution density across ambulatory and hospital settings. Olympus Corporation anchors manufacturing scale in fluoroplastic and silicone tube variants for standardized procedure volumes. Smith+Nephew occupies a position tied to specialized ENT surgical portfolio breadth and surgeon education infrastructure.
| Leading Market Players |
|---|
| Atos Medical |
| Preceptis Medical |
| Olympus Corporation |
| Medtronic |
| Grace Medical |
| Summit Medical |
| Integra LifeSciences Corporation |
| Smith+Nephew |
| Adept Medical |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between titanium sponge processors and ENT device manufacturers lock in alloy specification consistency while anchoring price visibility against export control volatility from Russian and Chinese supply clusters. These arrangements insulate pediatric clinic procurement from spot-market titanium fluctuations but expose buyers to minimum volume commitments that compress flexibility during silicone substitution cycles.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the tympanostomy market. Premium-grade surface-engineered titanium commands positioning through FDA biocompatibility certification and nanotextured osseointegration layers, while standard silicone tubes compete on ISO 10993 cytotoxicity compliance and economy polyethylene variants serve short-term retention protocols. Cost compression in the silicone tier intensifies because MDR clinical evidence requirements extend development timelines and concentrate R&D spending toward titanium platforms. Ambulatory surgical centers exhibit highest price sensitivity due to integrated delivery network volume mandates, whereas Japanese specialized hospitals show least sensitivity given cholesteatoma procedure reimbursement density.
Supply Chain Analysis
Inventory buffers for medical-grade titanium alloys extend lead times when Russian sponge export permits face regulatory scrutiny, compressing just-in-time availability for U.S. and German children's hospitals. Raw material sourcing draws from Chinese titanium mill products, Japanese fluoroplastic resin synthesis, and German precision micro-machining clusters for sub-millimeter tolerance fabrication. Single-source vulnerability concentrates in Russian sponge processing capabilities subject to geopolitical export controls. Distribution runs through specialized ENT surgical distributors in North America and direct manufacturer contracting with European hospital purchasing consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interoperability between tele-otology screening platforms and hospital electronic health record systems is fragmenting referral patterns and creating platform-economics inflection points for device specification authority.
For Market Incumbents: Compound specification authority through exclusive supply agreements with children's hospital systems in Texas and Florida, locking in titanium variant standardization before bioresorbable magnesium alloys reach corrosion-controlled maturity. Backward integration into titanium sponge sourcing mitigates Russian export control exposure. Prioritize MDR technical documentation investment to accelerate CE marking timelines against silicone platform competitors. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for surface-modified titanium alloys offer regulatory arbitrage against legacy silicone incumbents burdened by ISO 10993 testing backlogs. Brazilian ANVISA harmonization with ISO 13485 standards represents the most penetrable geography through centralized hospital purchasing consortia in São Paulo. Target tele-otology platform partnerships as go-to-market angle to bypass established distributor relationships in rural Indian markets. For Investors and Strategic Acquirers: Precision micro-machining specialists with captive titanium alloy relationships represent acquisition targets with defensible moats against commoditized silicone competitors. Long-term viability hinges on material science transitions across the next decade as bioresorbable platforms displace extraction-dependent protocols. Watch for ECHA REACH enforcement actions against perfluorinated compounds as inflection signal accelerating fluoroplastic substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Annex I compliance accelerates market access for titanium variants ahead of silicone competitors. |
| Hospital System Partnership | Children's hospital affiliations in Boston and Philadelphia secure specification authority for surface-engineered alloys. |
| Backward Integration | Captive titanium sponge relationships insulate against Russian export control volatility and alloy inconsistency. |
| Reimbursement Strategy | Standardized coding across ambulatory settings anchors ventilation tube volume commitments from integrated networks. |
| Software Companion Development | Tele-otology platforms in rural India expand addressable patient populations beyond urban tertiary catchment areas. |
Research Methodology
A standing panel of pediatric otologists, ambulatory surgical center procurement directors, biomedical engineers, and GPO contracts managers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) filings, EMA MDR technical documentation submissions, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up procedure volume estimates triangulated against top-down titanium alloy consumption data from medical device manufacturers.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across material type, tube geometry specification, end-user facility tier, and regional regulatory cluster. CAGRs derived from procedure volume growth rates, material substitution elasticities, and reimbursement code evolution. Forecast inputs incorporated REACH fluoroplastic restriction timelines and pediatric clinic expansion trajectories in high-reimbursement markets.
Decision-makers should treat outputs as directional under assumptions of stable FDA 510(k) clearance timelines and continued titanium sponge export availability from Russian processors; material deviation in either assumption would warrant model refresh. Specific risk factors include MDR clinical evidence requirement tightening, ECHA perfluorinated compound enforcement acceleration, and tele-otology platform reimbursement recognition delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Portable Ultrasound Devices Market
Medical Devices
Global Foot Orthotic Insoles Market
Medical Devices
Global Auto-Injectors Market
Medical Devices
Self-Injections Market
Medical Devices
Neurotechnology Market
Medical Devices
Tracheostomy Tubes Market
Medical Devices
Neurovascular Catheters Market
Medical Devices
Global Electroceuticals Market
Medical Devices
Global Concussion Market
Medical Devices
Oxygen Conservers Market
Medical Devices
Implantable Port Devices Market
Medical Devices
Cryoballoon Ablation System Market
Medical Devices
Polymer-Based Prefilled Syringe Market
Medical Devices
Syringe Scale Magnifiers Market
Medical Devices
Nephrostomy Catheters Market
Medical Devices
Brazil Aesthetic Equipment Market