
 Vaccine Transport Carrier Market | 2026-2036
Vaccine Transport Carrier Market Size, Share, and Industry Trends Forecast 2026-2036
Vaccine Transport Carrier Market Analytics
FDA 21 CFR Part 211 is restructuring the cost-of-entry calculus for vaccine transport carrier manufacturers by mandating validated cold chain documentation and temperature monitoring protocols. Thermo Fisher Scientific leverages its life sciences instrumentation heritage to integrate sensor telemetry directly into carrier designs. B Medical Systems anchors its competitive position through WHO PQS prequalification across passive carrier portfolios. Pelican BioThermal differentiates via reusable phase-change material systems that reduce total cost of ownership for pharmaceutical distributors.
Vaccine transport carriers are engineered thermal enclosures designed to maintain specified temperature bands for biological payloads, typically employing vacuum-insulated panels, phase-change materials, or compressor-based active cooling to preserve potency from manufacture through administration. Passive carriers dominate procurement volumes for last-mile delivery in resource-limited settings, while active carrier systems capture premium margins from pharmaceutical companies requiring precise set-point control for mRNA and viral-vector vaccines. Ultra-low temperature segments are expanding fastest, driven by cryogenic requirements for emerging vaccine platforms that demand sustained minus seventy-degree Celsius stability.
WHO PQS standards, FDA 21 CFR Part 211, and EU GDP guidelines collectively shape product design, testing protocols, and market access for vaccine transport carriers across regulated jurisdictions. These frameworks compel manufacturers to invest in validated thermal packaging, real-time data logging, and qualification documentation that raises barriers for unqualified suppliers. Stakeholders must monitor evolving pharmacopeial temperature standards and prequalification timelines to align R&D roadmaps with procurement eligibility requirements.
Market Dynamics
WHO PQS prequalification tightening is compressing supplier margins while elevating technical barriers for vaccine transport carrier manufacturers serving immunization programs.
Growth Catalysts
- Ultra-low temperature platforms:Cryogenic stability requirements for mRNA and viral-vector vaccines are expanding addressable market for minus seventy-degree Celsius capable carriers.
- India Universal Immunization Programme:Government procurement of last-mile passive carriers drives volume demand through national cold chain infrastructure expansion.
- FDA 21 CFR Part 211:Validated cold chain documentation mandates force pharmaceutical distributors to upgrade carrier fleets with integrated temperature monitoring systems.
Market Restraints
- Vacuum-insulated panel supply concentration:Core thermal barrier materials depend on limited Asian manufacturing capacity, creating input cost volatility and lead time risk.
- WHO PQS testing timelines:Extended prequalification protocols delay product commercialization and tie up R&D capital for eighteen to twenty-four month cycles.
- Active cooling energy dependency:Compressor-based systems require reliable power infrastructure unavailable in remote last-mile settings, limiting deployment geography.
Strategic Opportunities
- Reusable phase-change material systems:Pharmaceutical distributors seek total cost of ownership reduction through multi-use thermal mass technologies replacing single-use gel packs.
- Sensor-telemetry integration:Real-time data logging convergence with IoT connectivity enables outcome-based service contracts and predictive maintenance revenue streams.
- Sub-Saharan Africa immunization scale-up:Gavi and UNICEF procurement programs create white space for WHO PQS-qualified passive carriers in underpenetrated distribution networks.
Industry Challenges
- Thermal qualification engineering talent:Validated packaging design expertise sits concentrated at legacy cold chain specialists, constraining new entrant scaling.
- Legacy carrier fleet interoperability:New sensor-integrated designs face integration friction with existing inventory management and training protocols at national immunization programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vaccine Transport Carrier Market |
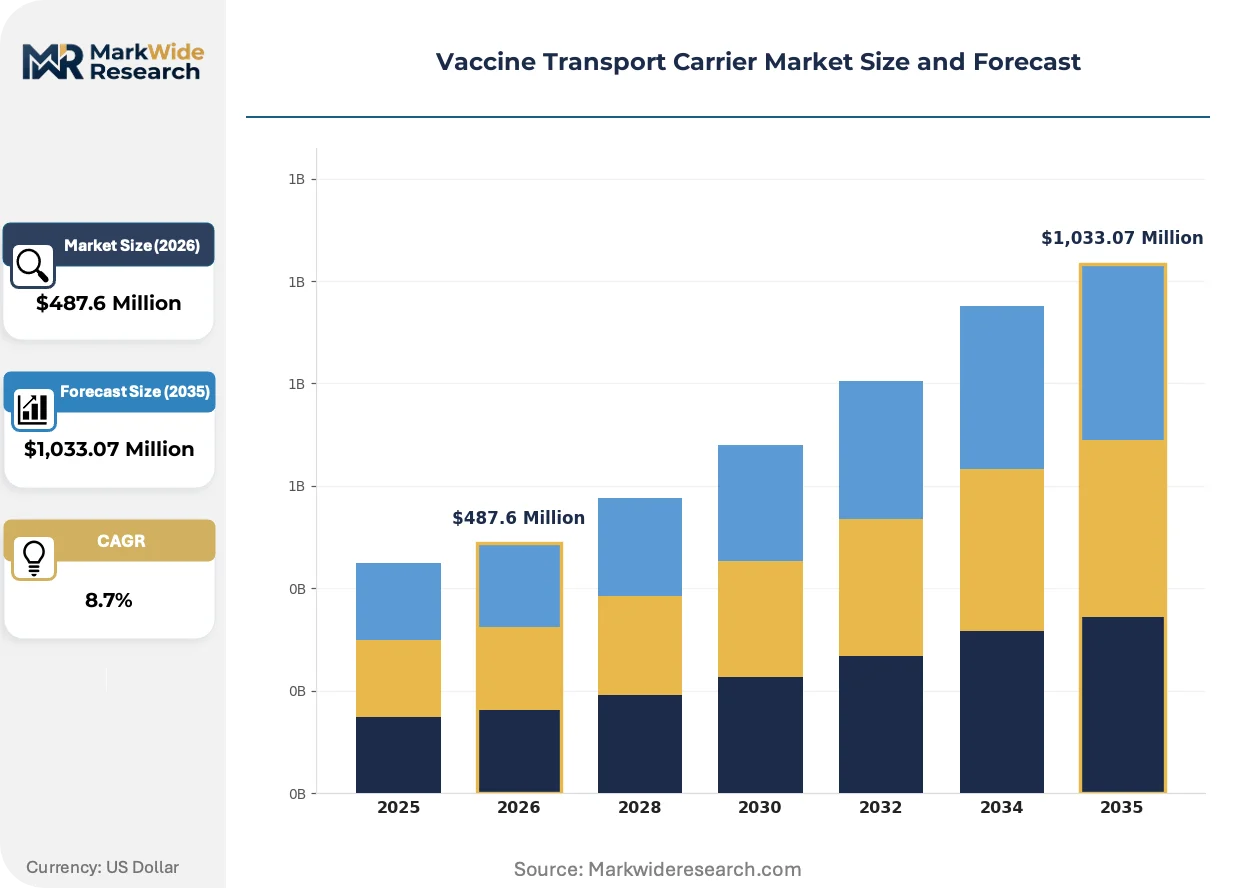
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Carriers, Active Carriers, Thermal Blankets, Refrigerated Vehicles End User: Pharmaceutical Companies, Hospitals, Distribution Centers, Research Laboratories Temperature Range: Room Temperature, Cold Chain, Ultra-Low Temperature, Cryogenic Distribution Channel: Direct Sales, Distributors, Online Retail, Specialty Stores |
| Companies Covered | Thermo Fisher Scientific, B Medical Systems, Sintex Plastic Technology, Cyro Scientific Systems Pvt Ltd., Sofrigam SA, Sonoco ThermoSafe, Cryopak Industries, Pelican BioThermal, Softbox Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vaccine Transport Carrier Market Evolving Landscape
Sensor-embedded telemetry is absorbing capital allocation across vaccine transport carrier R&D programs as pharmaceutical cold chain accountability requirements tighten.
Vacuum-insulated panel technology is absorbing manufacturing investment from passive carrier producers seeking extended hold times without weight penalties. UNICEF and Gavi procurement officers are specifying VIP-constructed carriers for outreach immunization campaigns. This materials shift is absorbing market share from expanded polystyrene alternatives in premium vaccine distribution segments.
EU GDP guidelines are mandating temperature excursion documentation across all pharmaceutical distribution tiers, compelling carrier manufacturers to pre-integrate data logger mounting and calibration protocols. Cold chain logistics providers in Germany and France now reject non-GDP-compliant equipment from approved vendor lists. This regulatory pressure is accelerating sensor standardization across European vaccine transport fleets.
Pharmaceutical distributors are unbundling carrier procurement from cold chain service contracts, shifting toward equipment-as-a-subscription models with embedded maintenance and qualification support. This buying-pattern change disrupts traditional capital purchase relationships between manufacturers and hospital pharmacy departments. The subscription pivot is most visible in US and Western European mRNA vaccine distribution networks where uptime guarantees command premium pricing.
Vaccine Transport Carrier Market Segmentation
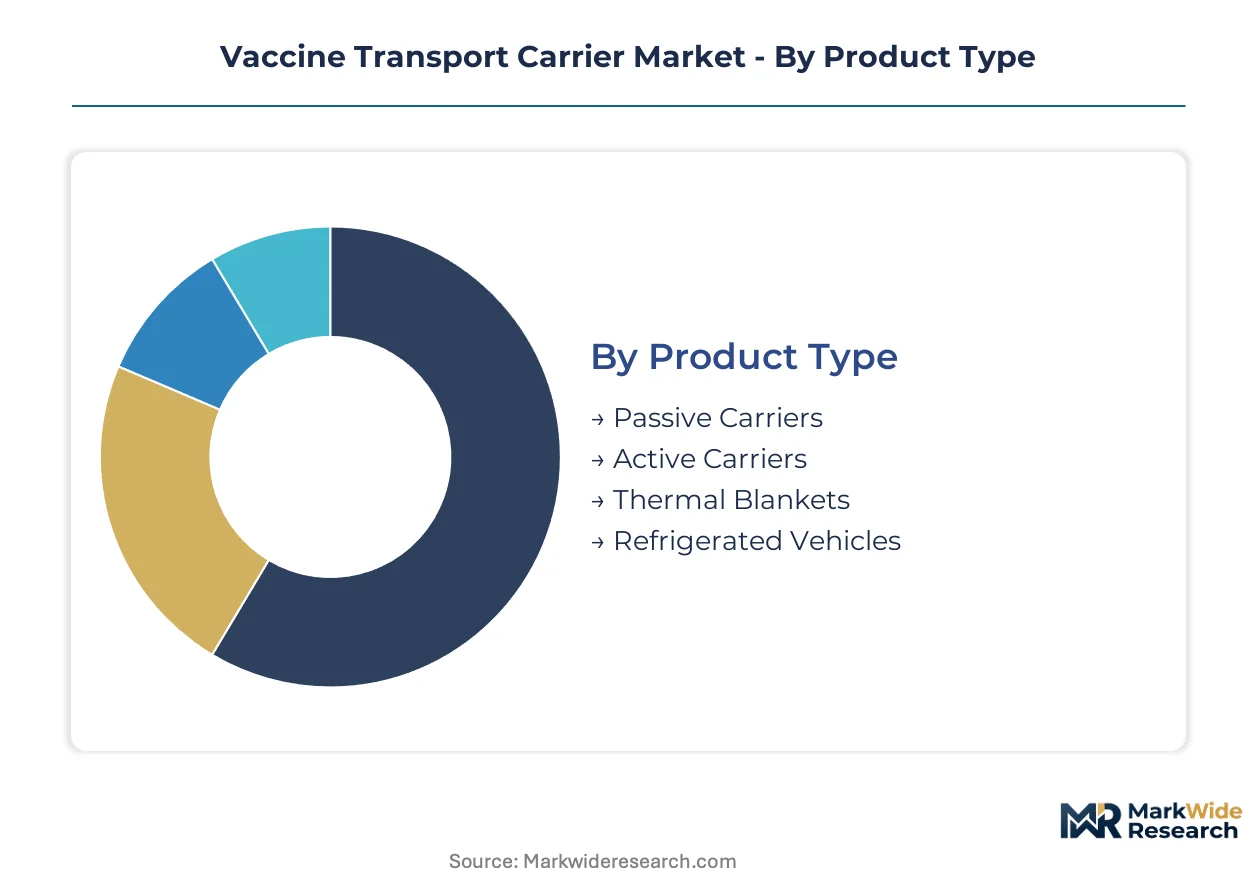
Vaccine transport carrier procurement decisions pivot on thermal performance specifications, regulatory compliance tiers, and total cost of ownership calculations across divergent distribution infrastructures. Manufacturers must architect product portfolios that span passive last-mile solutions through active pharmaceutical-grade systems to capture full market participation.
Product Type:
Capital intensity and power infrastructure availability drive buyer selection between passive and active thermal platforms.
- Passive Carriers:Vacuum-insulated panels and phase-change materials maintain temperature bands without external power, serving UNICEF and Gavi procurement programs across India and sub-Saharan Africa. India's Universal Immunization Programme generates concentrated volume demand for outreach-compatible designs.
- Active Carriers:Compressor-based cooling delivers precise set-point control for mRNA and viral-vector vaccines requiring sustained ultra-low stability. Pharmaceutical distributors in Germany and France specify active systems for EU GDP-compliant distribution networks where excursion documentation is mandatory.
- Thermal Blankets:Flexible insulating wraps provide short-duration protection for palletized vaccine shipments during airport tarmac transfers.
- Refrigerated Vehicles:Fleet-based cold chain infrastructure serves national immunization programs requiring bulk transport from central stores to district warehouses.
Volume sits with Passive Carriers; growth tilts toward Active Carriers.
End User:
Regulatory accountability tiers separate institutional buyers by validation requirements and documentation stringency.
- Pharmaceutical Companies:FDA 21 CFR Part 211 mandates force integrated temperature monitoring and validated cold chain documentation for commercial vaccine distribution. Thermo Fisher Scientific and B Medical Systems compete for qualification-dependent procurement contracts.
- Hospitals:Pharmacy departments require WHO PQS-prequalified carriers for vaccine storage and patient administration workflows.
- Distribution Centers:Third-party logistics operators seek reusable phase-change material systems to reduce per-shipment thermal packaging costs.
- Research Laboratories:Clinical trial material transport demands calibrated data logging and chain-of-custody documentation.
Procurement scale concentrates at Pharmaceutical Companies; capability requirements stiffen fastest at Research Laboratories.
Temperature Range:
Vaccine platform chemistry dictates thermal stability specifications from standard refrigeration through cryogenic preservation.
- Ultra-Low Temperature:Sustained minus seventy-degree Celsius capability addresses mRNA vaccine cryogenic requirements, expanding addressable market for specialized carrier engineering. Pelican BioThermal's reusable phase-change material systems target this segment for pharmaceutical distributor cost reduction.
- Cold Chain:Two-to-eight-degree Celsius maintenance serves traditional attenuated and inactivated vaccine formulations across national immunization programs.
- Room Temperature:Ambient stability requirements apply to select lyophilized vaccine presentations and diluent components.
- Cryogenic:Liquid nitrogen vapor phase systems preserve cellular therapies and certain viral-vector platforms at minus one hundred fifty degrees Celsius.
Installed base clusters at Cold Chain; capability investment flows toward Ultra-Low Temperature.
Distribution Channel:
Equipment-as-a-subscription models are restructuring traditional capital purchase relationships between manufacturers and institutional buyers.
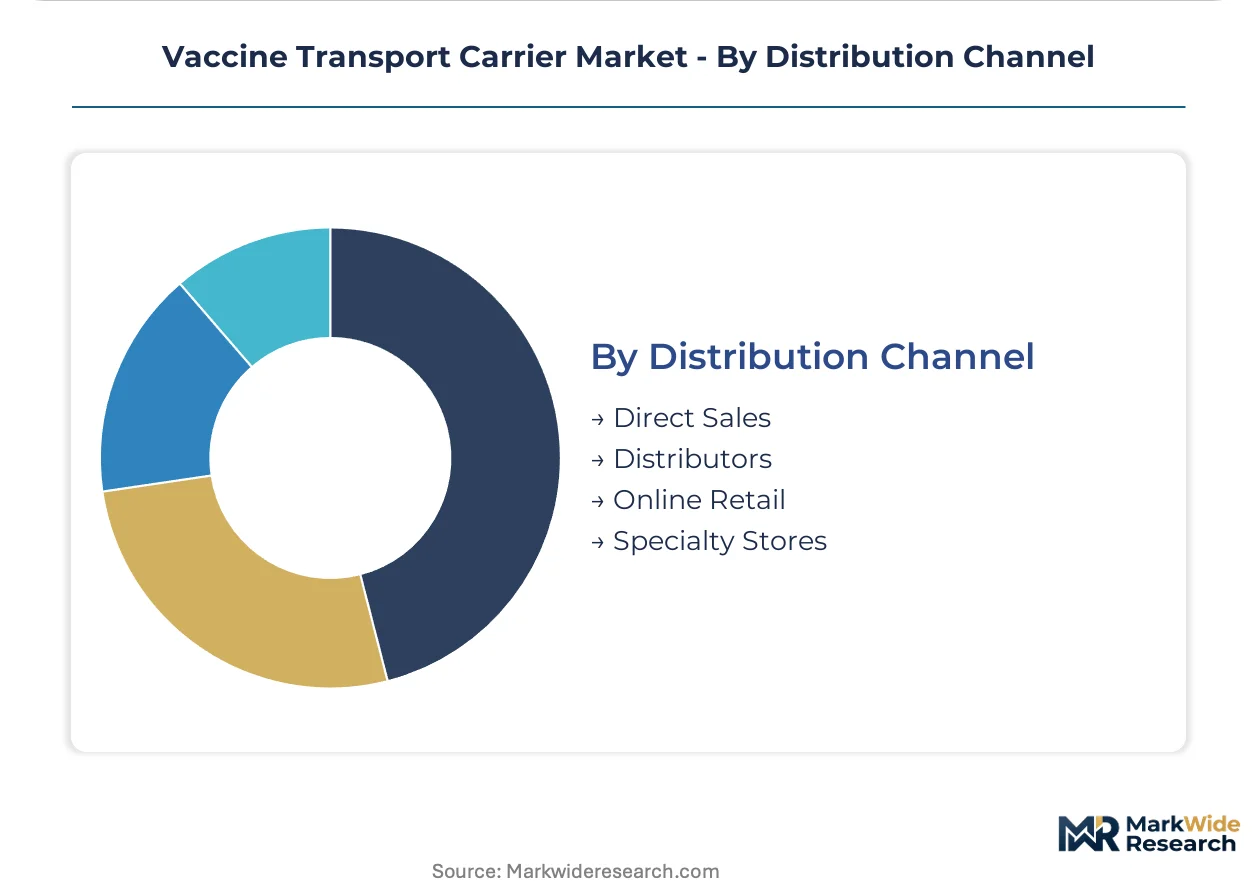
- Direct Sales:Manufacturer relationships with pharmaceutical cold chain operators enable embedded maintenance contracts and uptime guarantees. US and Western European mRNA vaccine networks show strongest subscription pivot activity.
- Distributors:Medical equipment wholesalers aggregate procurement for hospital pharmacy departments and smaller immunization programs.
- Online Retail:E-commerce platforms serve research laboratory and clinic customers requiring standardized carrier configurations with rapid fulfillment.
- Specialty Stores:Cold chain equipment dealers provide localized qualification support and calibration services for national immunization programs.
Revenue concentration remains with Direct Sales; channel diversification accelerates through Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Gujarat and Maharashtra concentrate vaccine carrier manufacturing capacity through tax incentives and export-oriented infrastructure. India's pharmaceutical logistics corridor anchors passive carrier production for immunization programs across South Asia and Africa.
United States
FDA 21 CFR Part 211 mandates validated cold chain documentation for pharmaceutical distributors, forcing carrier fleet upgrades with integrated temperature monitoring. The Boston-Cambridge biotech cluster generates demand for ultra-low temperature active systems serving mRNA vaccine developers. Cold chain logistics providers in Massachusetts and New Jersey are consolidating procurement through equipment-as-a-subscription models.
Germany
EU GDP guidelines require temperature excursion documentation across pharmaceutical distribution tiers, compelling sensor-integrated carrier adoption. The Rhine-Main logistics hub around Frankfurt anchors cold chain service provider consolidation for European vaccine distribution. Manufacturers in Baden-Württemberg specialize in precision-engineered active cooling systems for pharmaceutical-grade transport.
India
The Universal Immunization Programme drives volume procurement of WHO PQS-prequalified passive carriers for last-mile outreach. CDSCO regulatory alignment with international standards accelerates domestic manufacturer qualification for export markets. Gujarat's plastics engineering cluster supplies vacuum-insulated panel carriers to UNICEF and Gavi procurement programs.
France
ANSM pharmaceutical distribution oversight tightens carrier validation requirements for hospital pharmacy supply chains. The Lyon-Grenoble medical technology corridor hosts phase-change material engineering specialists serving European pharmaceutical distributors. Cold chain operators in Île-de-France are retrofitting fleets with GDP-compliant telemetry systems.
Japan
PMDA stability testing protocols for temperature-sensitive biologics elevate carrier performance benchmarks for domestic manufacturers. The Kansai pharmaceutical manufacturing belt around Osaka generates demand for precision thermal packaging in clinical trial logistics. METI industrial policy supports domestic production of advanced insulation materials for vaccine transport applications.
Vaccine Transport Carrier Market Competitive Landscape
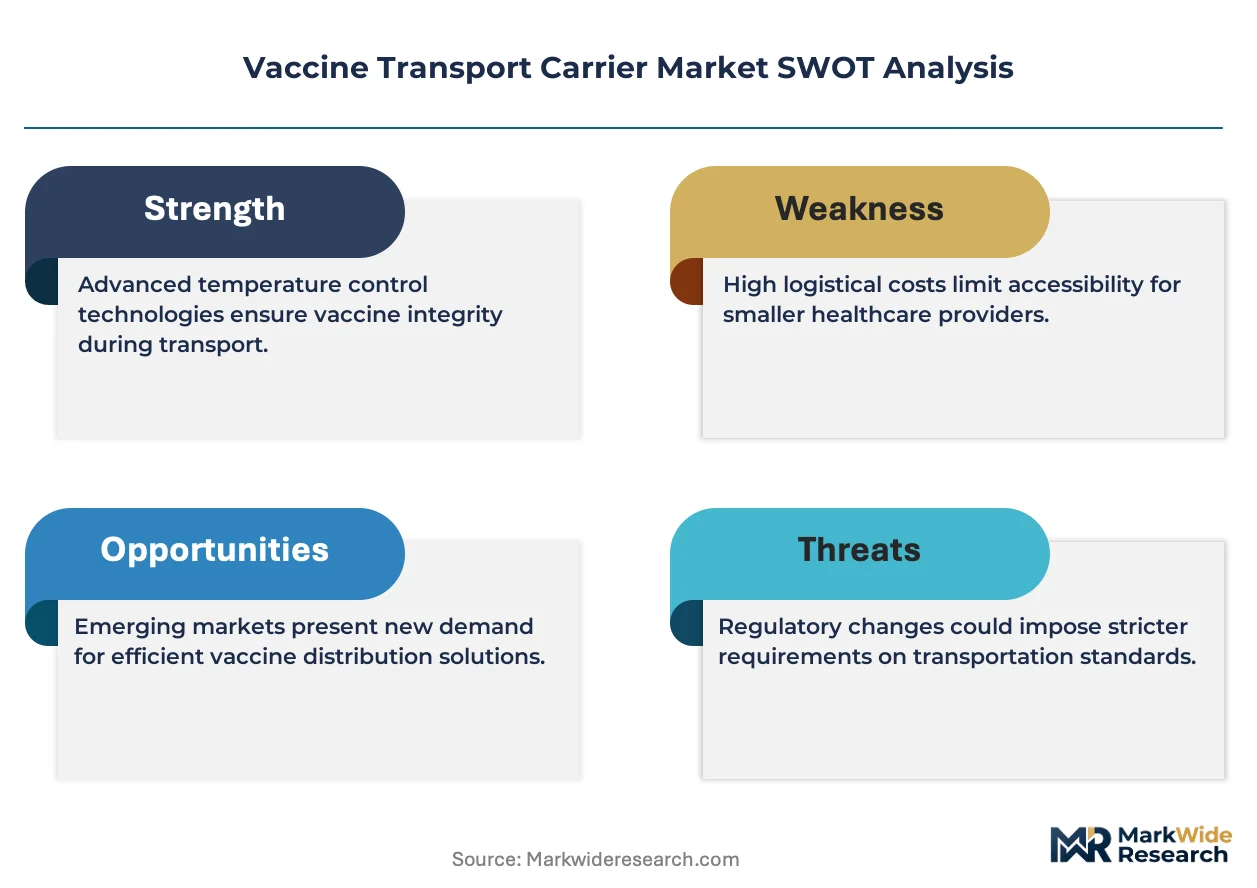
North American producers anchor the premium active-cooling tier; European specialists hold position in reusable phase-change systems and regulatory-compliant documentation platforms. The vendor base separates into three functional layers: instrumentation conglomerates with sensor integration capabilities, cold chain purists with WHO PQS prequalification depth, and regional fabricators serving price-sensitive immunization programs. Consolidation pressure concentrates among mid-scale passive carrier producers facing extended prequalification timelines and input material volatility.
Among diversified life sciences conglomerates, Thermo Fisher Scientific exemplifies the instrumentation-integrated archetype through its telemetry-enabled carrier designs. B Medical Systems and Pelican BioThermal occupy differentiated positions within the premium thermal packaging tier—B Medical Systems through WHO PQS prequalification breadth, Pelican BioThermal through reusable phase-change material engineering. These three anchors represent the competitive spectrum from sensor-embedded active systems to sustainable thermal mass technologies.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| B Medical Systems |
| Sintex Plastic Technology |
| Cyro Scientific Systems Pvt Ltd. |
| Sofrigam SA |
| Sonoco ThermoSafe |
| Cryopak Industries |
| Pelican BioThermal |
| Softbox Systems Ltd. |
| Others |
Value Network & Pricing Analysis
Vacuum-insulated panel resin costs cascade through carrier pricing tiers, with Gujarat-based manufacturers converting petrochemical feedstock into WHO PQS-qualified passive units at economy price points while German precision-engineered active systems command premium positioning for EU GDP-compliant pharmaceutical distribution.
Pricing Analysis
Expedited lead-time premiums separate spot buyers from contract purchasers, with UNICEF procurement officers securing volume discounts through eighteen-month forward commitments while hospital pharmacy departments absorb surcharges for immediate fulfillment. Three-tier pricing structure across premium, standard, and economy levels aligns with certification depth: WHO PQS-prequalified carriers with integrated telemetry capture premium positioning, CDSCO-registered domestic units serve standard demand, and unqualified regional fabricators populate economy tiers. Cost compression in passive carrier segments intensifies as Sintex Plastic Technology and Cryopak Industries compete for India's Universal Immunization Programme tenders. Pharmaceutical companies demonstrate lowest price sensitivity due to FDA 21 CFR Part 211 compliance mandates, while sub-Saharan African national immunization programs exhibit acute budget constraint responsiveness.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Mumbai, and Singapore anchor hub-and-spoke patterns for vaccine carrier fulfillment, with forward stocking locations positioned near Gavi procurement consolidation points. Manufacturing concentrates in India, Germany, and the United States: Gujarat's plastics engineering cluster supplies vacuum-insulated panel fabrication, Baden-Württemberg specializes in compressor-based active cooling assemblies, and Massachusetts hosts telemetry-integrated system integration. Raw material dependencies draw from South Korean petrochemical feedstock for VIP cores, Chinese rare-earth elements for phase-change material formulations, and Japanese precision electronics for sensor modules. Single-source vulnerability concentrates in Asian vacuum-insulated panel membrane supply, where two manufacturers control qualified pharmaceutical-grade production. Distribution runs through cold chain logistics providers who unbundle carrier procurement from service contracts, shifting toward equipment-as-a-subscription models with embedded maintenance obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum accelerates as manufacturers pursue captive supply of vacuum-insulated panels and phase-change materials to insulate margins from petrochemical volatility and Asian supply concentration.
For Market Incumbents: Cement WHO PQS prequalification depth as the primary defensive moat against emerging Asian fabricators, extending qualification portfolios into ultra-low temperature segments before cryogenic carrier demand consolidates. Backward integration into phase-change material chemistry protects margin structures from specialty chemical supply shocks. Acquire distressed regional distributors in sub-Saharan Africa to preempt Gavi procurement channel control by mid-scale competitors. For New Entrants and Emerging Players: FDA 21 CFR Part 211 in the United States opens a window for sensor-telemetry specialists to displace legacy carrier fleets lacking validated documentation protocols. Target India's CDSCO-aligned domestic manufacturers seeking export qualification for UNICEF and Gavi programs, where WHO PQS testing timeline bottlenecks create white space for prequalified portfolio acquisitions. Pursue white-label partnerships with established cold chain logistics providers rather than direct pharmaceutical company sales cycles. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale passive carrier producers in Gujarat and Maharashtra facing extended WHO PQS capital tie-up, where tax-advantaged Special Economic Zone infrastructure preserves underlying asset value. Monitor Gavi procurement acceleration signals as inflection indicators for premium carrier demand migration toward reusable phase-change material systems with total cost of ownership advantages.| Strategic Initiative | Industry Significance |
|---|---|
| WHO PQS Prequalification Expansion | UNICEF and Gavi procurement eligibility gates commercial access to immunization program volumes. |
| Sensor-Telemetry Integration | FDA 21 CFR Part 211 mandates force pharmaceutical distributor fleet upgrades with validated data logging. |
| Reusable Phase-Change Material Development | Pelican BioThermal's thermal mass engineering reduces per-shipment packaging costs for distribution centers. |
| Backward Integration into VIP Manufacturing | Captive vacuum-insulated panel production insulates margins from Asian petrochemical feedstock volatility. |
| Equipment-as-a-Subscription Pivot | Cold chain logistics providers in Massachusetts and New Jersey unbundle capital purchase relationships with uptime guarantees. |
Research Methodology
Multi-period observation of WHO PQS prequalification timelines, UNICEF procurement award patterns, and FDA warning letter trends anchored the trend analysis, supplemented by interviews with cold chain logistics directors, pharmaceutical distribution executives, national immunization program procurement officers, and vacuum-insulated panel manufacturing engineers. Secondary validation drew from WHO PQS product database entries, CDSCO manufacturing license registries, Gavi disbursement records, and EU GDP guidance document revisions. Bottom-up carrier shipment estimates triangulated against top-down immunization program budget allocations across the analysis window.
Segment-weighting approaches distributed value projections across passive, active, thermal blanket, and refrigerated vehicle categories, with temperature range stratification from room temperature through cryogenic tiers. Product type, end user regulatory tier, and distribution channel subscription penetration formed core segmentation dimensions, with regional regulatory cluster and carrier hold-time specification as industry-specific modifiers. CAGRs derived from logistic curve fitting to immunization program expansion trajectories, incorporating mRNA vaccine platform adoption rates and ultra-low temperature infrastructure buildout assumptions.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery-powered active cooling or advanced aerogel insulation would alter the outlook for compressor-based and vacuum-insulated panel carrier demand respectively. Forecasts reflect assumptions regarding WHO PQS testing timeline stability, Gavi funding continuity, and petrochemical feedstock price normalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Global Ambulatory Services Market
Healthcare Services
Australia Senior Living Market
Healthcare Services
Europe Pharmaceutical Logistics Market
Healthcare Services
Medical Waste Disposal Services Market
Healthcare Services
European Union Cross Border Healthcare Market
Healthcare Services
Pharmaceutical Contract Sales Organizations Market
Healthcare Services
Patient Throughput and Capacity Management Market
Healthcare Services
Global Geriatric Care Services Market
Healthcare Services
Vaccine Logistics Market
Healthcare Services
Hair Restoration Services Market
Healthcare Services
Inhaled and Intranasal Products Contract Service Providers Market
Healthcare Services
UK Pharmaceutical Logistics Market
Healthcare Services
Medical Billing Outsourcing Market
Healthcare Services
US Value-Based Healthcare Service Market
Healthcare Services
Global Healthcare Contract Development and Manufacturing Organization Market
Healthcare Services
Global Healthcare Services Market