
 Phakic Intraocular Lenses (IOL) Market | 2026-2036
Phakic Intraocular Lenses (IOL) Market Size, Share, and Industry Trends Forecast 2026-2036
Phakic Intraocular Lenses (IOL) Market Analytics
Specialty ophthalmology distribution is tilting toward consolidated procurement networks that serve high-volume ambulatory surgical centers. STAAR Surgical Company leverages its direct surgeon training infrastructure to sustain implant loyalty across key refractive corridors. Johnson & Johnson Vision anchors its position through integrated femtosecond laser-to-lens workflows. Alcon competes on manufacturing scale, controlling global supply of hydrophilic acrylic raw stock for phakic platforms.
Phakic intraocular lenses are implantable optical devices placed in the anterior or posterior chamber while the natural crystalline lens remains intact, typically manufactured from biocompatible silicone or hydrophilic acrylic with optical powers ranging from minus twenty to plus ten diopters to correct high refractive errors. Their primary purpose is to provide permanent vision correction for patients with severe myopia, hyperopia, or astigmatism who fall outside laser ablation treatment parameters. Toric IOL variants occupy the strongest margin pools due to astigmatism correction premiums, while extended depth of focus platforms represent the fastest-growing technology segment as presbyopia-correcting demand expands. Ambulatory surgical centers now dominate volume throughput for phakic procedures, displacing traditional hospital-based ophthalmology units.
The FDA maintains stringent premarket approval pathways for phakic IOLs through its Office of Ophthalmic Devices, while the EMA enforces MDR-compliant clinical follow-up requirements across European member states. Japan's PMDA imposes additional JIS-standard biocompatibility testing that extends registration timelines but elevates product credibility. Stakeholders must monitor evolving reimbursement thresholds for premium lens categories and position portfolio mixes before payer preference shifts crystallize.
Market Dynamics
Consolidated procurement networks serving ambulatory surgical centers are compressing distributor margins and forcing manufacturers to build direct surgeon training infrastructures to maintain implant loyalty.
Growth Catalysts
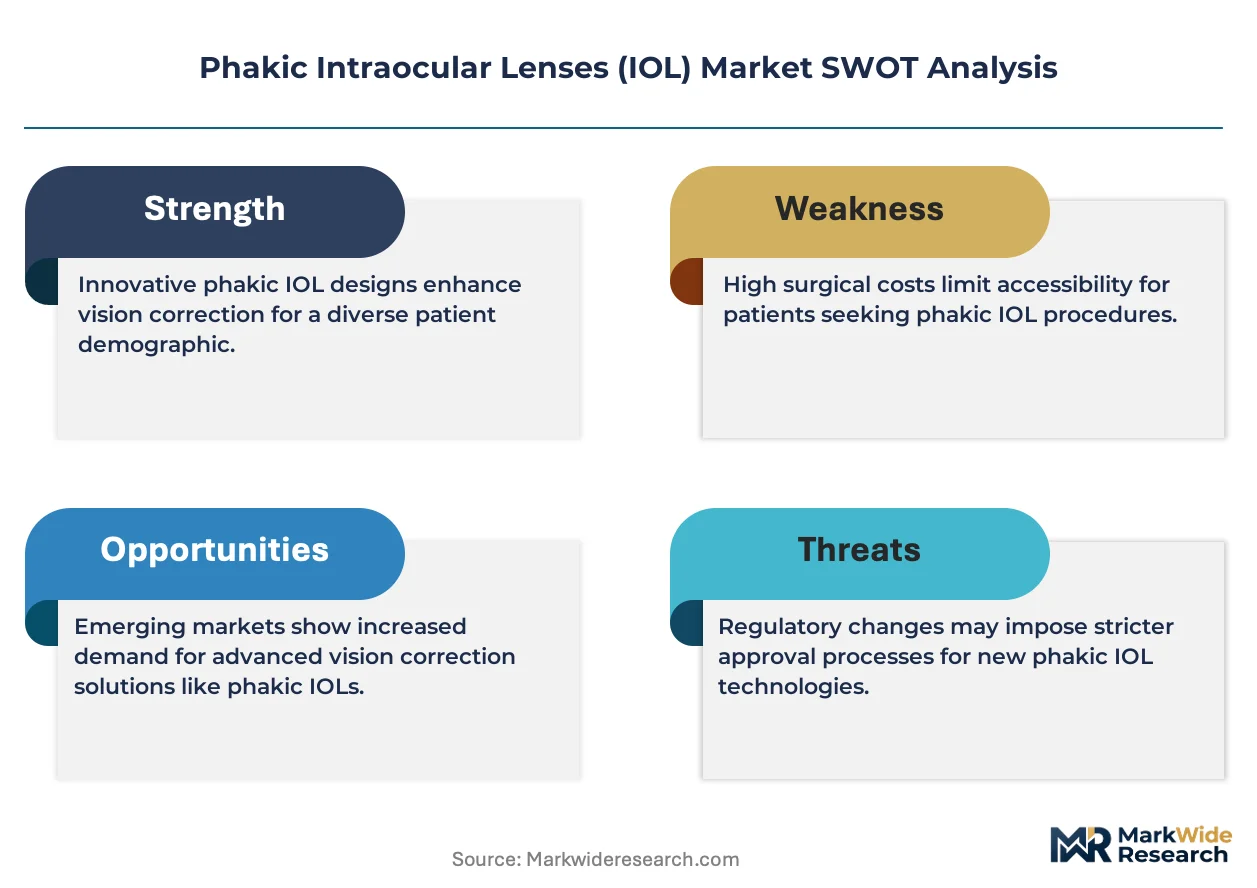
- MDR-compliant clinical follow-up mandates:The EMA's strengthened post-market surveillance requirements across European member states are elevating product credibility and filtering out marginal competitors.
- Myopia prevalence among younger demographics:Rising refractive error rates in pediatric and adolescent populations are expanding the addressable patient pool beyond traditional laser ablation candidates.
- Extended depth of focus platforms:Presbyopia-correcting lens technologies are capturing premium pricing tiers as aging populations seek spectacle independence.
Market Restraints
- Hydrophilic acrylic raw stock concentration:Single-source dependency for specialized polymer feedstock creates vulnerability to supply disruptions and input cost volatility.
- JIS-standard biocompatibility testing:Japan's PMDA imposes extended registration timelines that delay market entry and elevate compliance expenditures.
- Laser vision correction substitution:Femtosecond laser platforms continue refining treatment parameters, encroaching on mild-to-moderate myopia segments previously reserved for phakic intervention.
Strategic Opportunities
- Direct-to-surgeon digital education channels:Virtual training platforms bypass traditional distributor relationships and accelerate adoption curves in underpenetrated refractive corridors.
- Premium toric portfolio expansion:Astigmatism-correcting variants command stronger margin pools as ambulatory surgical centers seek higher reimbursement per procedure.
- Integrated femtosecond laser-to-lens workflows:Convergence between corneal incision technology and implantable lens placement is creating procedure standardization opportunities.
Industry Challenges
- Refractive surgeon training capacity:The specialized skill set required for anterior chamber angle assessment and proper lens sizing creates bottlenecks in procedure volume expansion.
- FDA premarket approval pathway duration:The Office of Ophthalmic Devices maintains stringent evidentiary standards that compress development timelines and strain R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phakic Intraocular Lenses (IOL) Market |
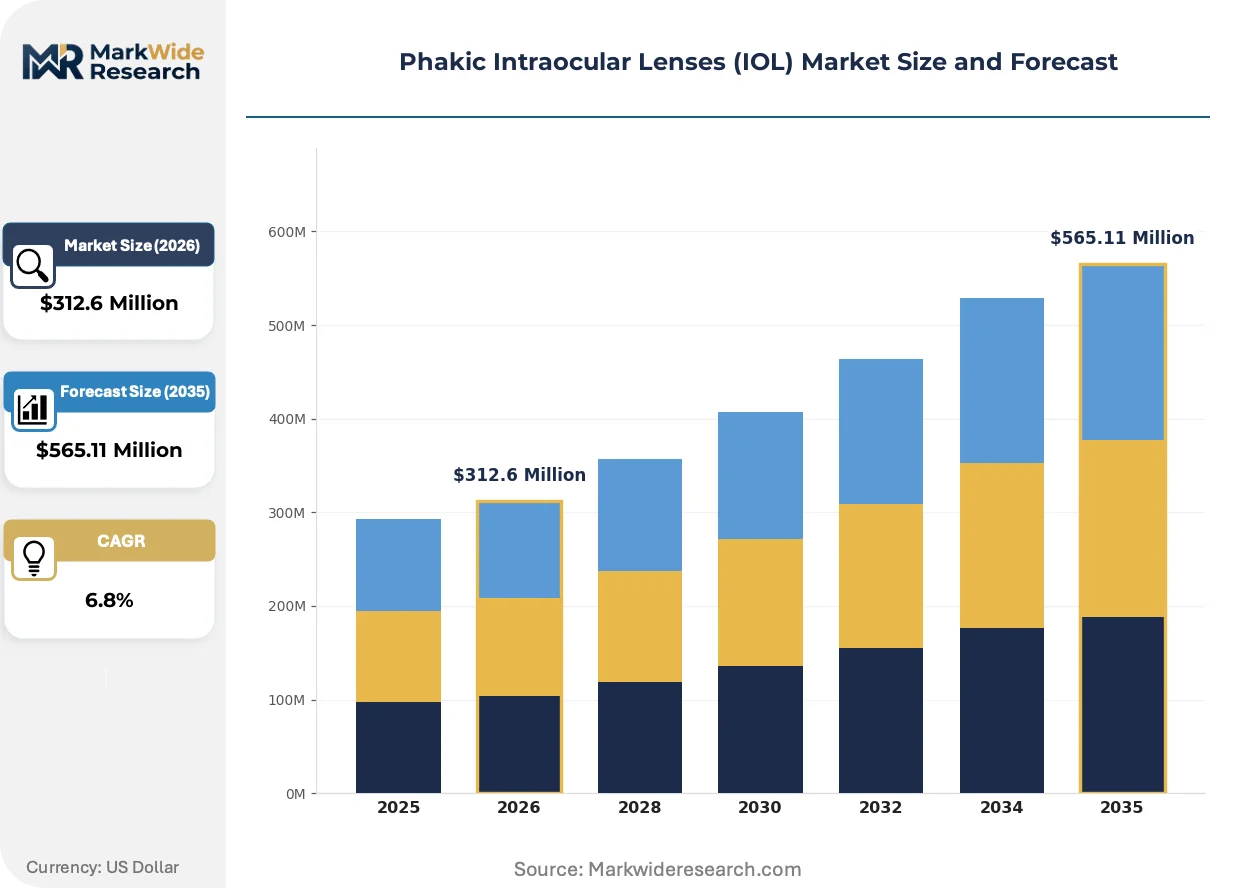
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $565.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard IOL, Toric IOL, Multifocal IOL, Extended Depth of Focus IOL End User: Ophthalmology Clinics, Hospitals, Eye Care Centers, Ambulatory Surgical Centers Material: Silicone, Acrylic, Polypropylene, Hydrophilic Acrylic Technology: Femtosecond Laser, Phacoemulsification, Wavefront-guided, Active Pigment |
| Companies Covered | STAAR Surgical Company, Johnson & Johnson Vision, Alcon, Carl Zeiss Meditec, Bausch + Lomb, Hoya Surgical Optics, Nidek Co., Ltd., EyeYon Medical, Rayner Surgical Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phakic Intraocular Lenses (IOL) Market Evolving Landscape
Digital simulation and preoperative planning tools are virtualizing traditional clinical workflows, compressing consultation-to-surgery intervals while elevating predictive accuracy for refractive outcomes.
Extended depth of focus lens designs are virtualizing the conventional trade-off between near and distance vision correction. High-volume ambulatory surgical centers in the United States are adopting these platforms at accelerated pace to differentiate against commoditized monofocal offerings. The technology is virtualizing patient expectations around spectacle independence and forcing competitors to accelerate presbyopia-correcting R&D pipelines.
The FDA's Office of Ophthalmic Devices has tightened premarket approval evidentiary requirements for novel lens materials. This regulatory friction is extending development cycles and elevating clinical trial expenditure thresholds. Premium toric and extended depth of focus platforms face the steepest compliance burden, prompting manufacturers to prioritize incremental material modifications over breakthrough innovations.
Consolidated procurement networks serving ambulatory surgical centers are displacing traditional distributor relationships across key refractive corridors. Germany and Japan exhibit the most pronounced concentration, with multi-site surgery groups negotiating direct manufacturer contracts. This channel compression is forcing legacy distributors to unbundle service offerings or exit the phakic IOL category entirely.
Phakic Intraocular Lenses (IOL) Market Segmentation
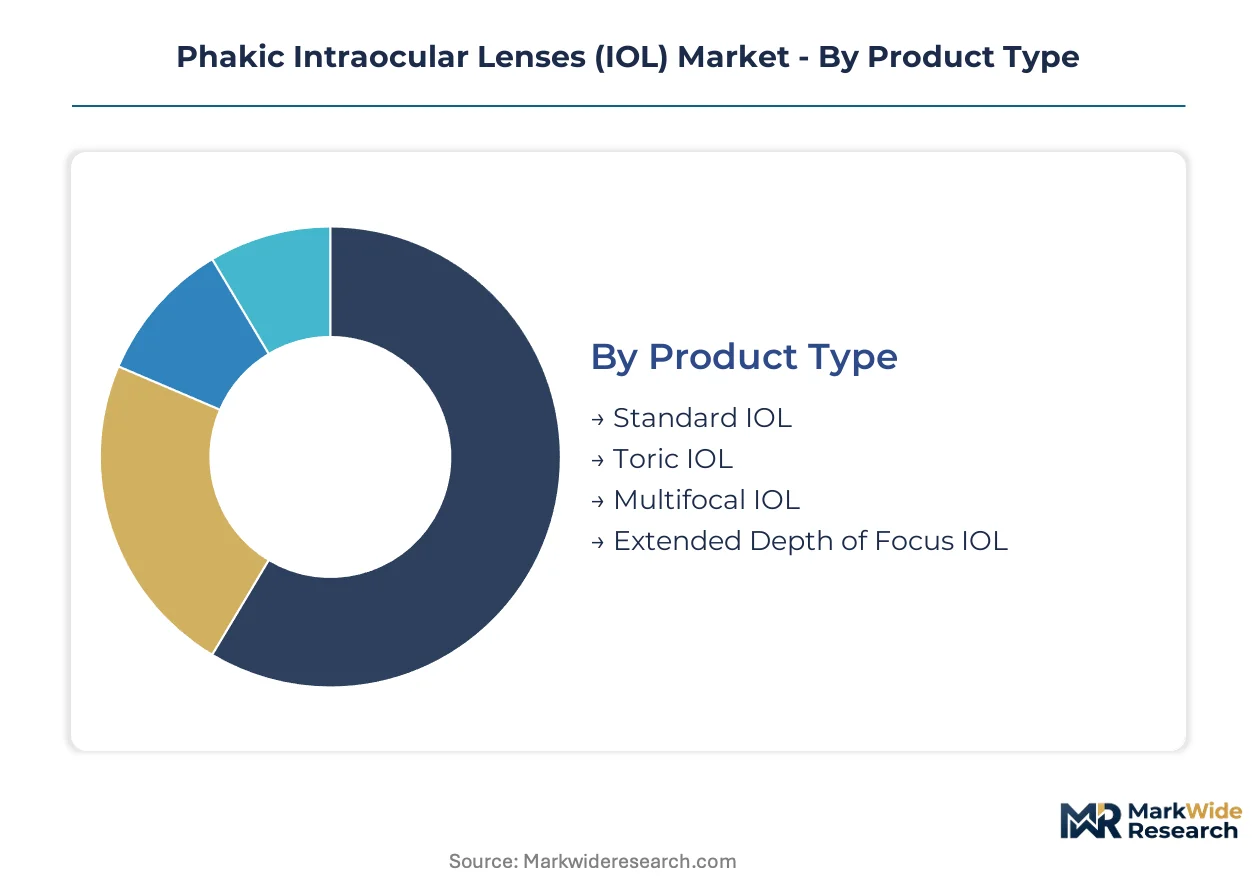
Phakic IOL segmentation reveals how implant selection drives surgical workflow design and postoperative monitoring intensity. Each category intersects with reimbursement pathways, surgeon training requirements, and regulatory submission strategies differently.
Product Type:
After-sales service intensity varies sharply across lens platforms, with premium designs demanding extended follow-up protocols and complication management resources.
- Standard IOL:Monofocal spherical designs correct single-distance vision without astigmatism compensation. Demand concentrates in cost-sensitive ambulatory surgical centers in Germany where reimbursement caps favor basic implant categories over premium alternatives.
- Toric IOL:Cylindrical optics integrate astigmatism correction into the lens platform. Japanese ophthalmology clinics drive adoption due to higher prevalence of corneal astigmatism in East Asian populations and stronger private-pay tolerance for premium pricing.
- Multifocal IOL:Diffractive or refractive zone designs enable simultaneous near and distance vision correction.
- Extended Depth of Focus IOL:Echelette optics stretch the focal range to reduce spectacle dependence across intermediate distances.
Toric IOL holds the largest share; momentum sits with Extended Depth of Focus IOL.
End User:
Procurement patterns diverge sharply between institutional settings, with volume commitments and surgeon autonomy shaping manufacturer contract terms.
- Ophthalmology Clinics:Specialized refractive practices maintain direct relationships with implant suppliers and control lens selection independently. United States metropolitan corridors exhibit the highest concentration of high-volume standalone clinics performing phakic procedures.
- Ambulatory Surgical Centers:Consolidated multi-site networks negotiate centralized purchasing agreements that compress per-unit pricing. These facilities are expanding fastest in Texas and Florida where certificate-of-need restrictions are minimal and surgeon ownership structures predominate.
- Hospitals:Academic medical centers and community hospital systems embed phakic procedures within broader ophthalmology service lines.
- Eye Care Centers:Optometry-ophthalmology integrated practices handle screening and referral but rarely perform implantation.
Ambulatory Surgical Centers command the highest volume throughput; Ophthalmology Clinics retain the strongest pricing power.
Material:
Biocompatibility certification requirements from FDA, EMA, and PMDA create divergent approval timelines and post-market surveillance obligations for each polymer class.
- Hydrophilic Acrylic:High water-content polymers enable foldable delivery through micro-incisions and exhibit strong uveal biocompatibility. Alcon controls substantial global supply of specialized hydrophilic acrylic feedstock, creating single-source dependency risks for competing manufacturers.
- Silicone:Elastomeric optics deliver excellent optical clarity and resistance to calcification in long-term implantation. Japanese PMDA registration pathways impose extended JIS-standard biocompatibility testing timelines that favor established silicone platforms with historical safety databases.
- Acrylic:Hydrophobic variants reduce posterior capsule opacification rates compared to earlier generations.
- Polypropylene:Rigid haptic materials persist in anterior chamber angle-fixated designs despite declining overall utilization.
Silicone maintains the broadest regulatory approval footprint; Hydrophilic Acrylic faces the steepest supply concentration risk.
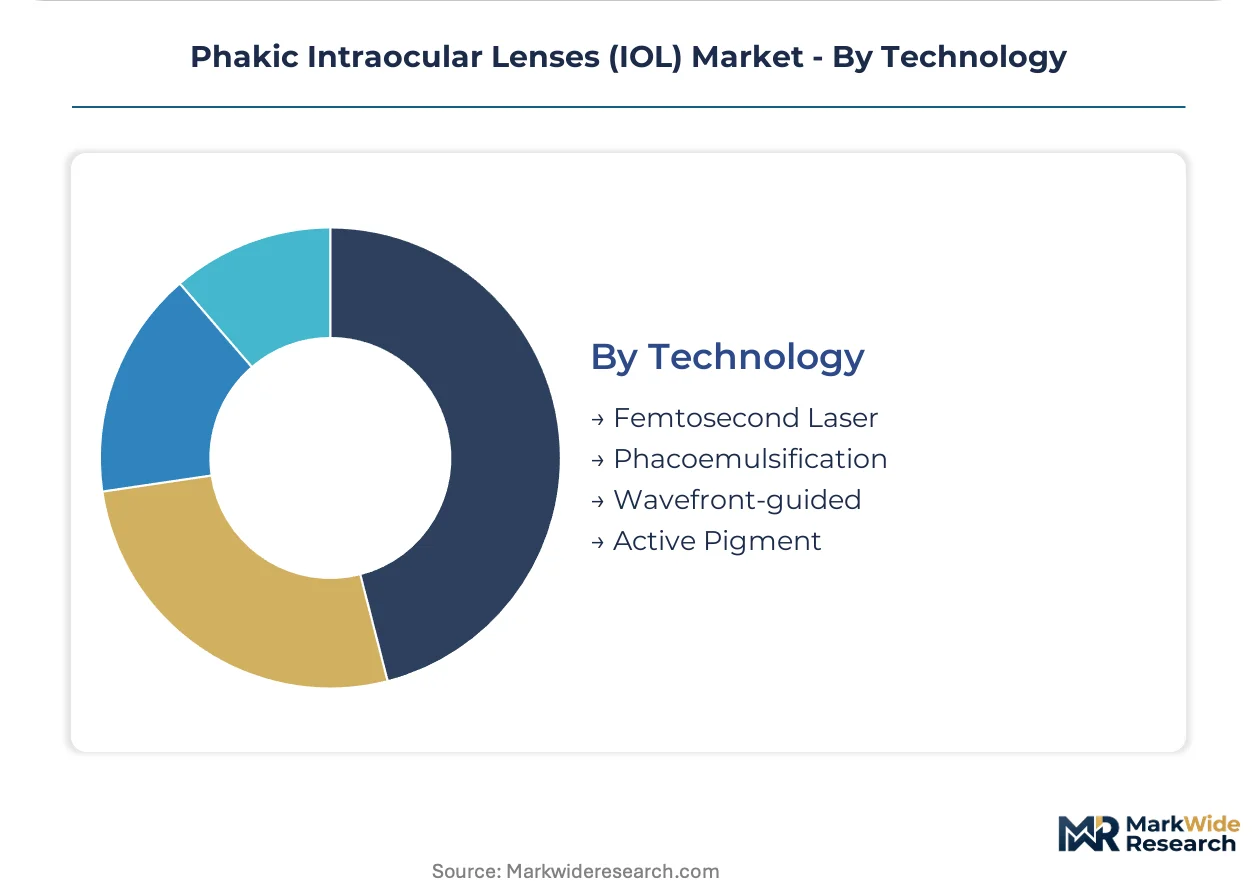
Technology:
Capital equipment integration determines which implant platforms surgeons can physically deploy, creating technology lock-in effects that span laser systems, phacoemulsification consoles, and diagnostic workstations.
- Femtosecond Laser:Corneal incision and lens fragmentation automation enables standardized capsulotomy dimensions and arcuate keratotomy precision. Johnson & Johnson Vision anchors market position through integrated femtosecond-to-implant workflows that reduce procedure variability.
- Phacoemulsification:Ultrasonic emulsification remains the standard technique for lens removal in combined procedures and maintains dominance in emerging markets where capital equipment costs constrain femtosecond adoption.
- Wavefront-guided:Aberrometry-linked implant selection optimizes optical outcomes for higher-order aberration profiles.
- Active Pigment:Photochromic or light-adjustable materials enable postoperative power modification.
Phacoemulsification retains the widest installed base; Femtosecond Laser is climbing the fastest as ambulatory surgical centers upgrade capital equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket approval pathways and EMA MDR compliance mandates are redirecting manufacturer investment toward established regulatory jurisdictions with predictable reimbursement frameworks.
United States
High-volume ambulatory surgical centers in Texas and Florida drive procedural volume as certificate-of-need restrictions remain minimal. The FDA Office of Ophthalmic Devices maintains stringent evidentiary standards for novel lens materials that extend development timelines. Metropolitan corridors including Dallas-Fort Worth and Miami host concentrated networks of standalone refractive practices with direct supplier relationships.
Germany
Reimbursement caps favor basic implant categories in cost-sensitive surgical settings while private-pay tolerance sustains premium toric adoption. EMA MDR-compliant clinical follow-up requirements filter marginal competitors and elevate product credibility. The Baden-Württemberg and Bavaria regions concentrate manufacturing infrastructure for hydrophilic acrylic feedstock processing.
Japan
Higher prevalence of corneal astigmatism in East Asian populations expands addressable demand for cylindrical optics platforms. PMDA JIS-standard biocompatibility testing extends registration timelines but strengthens long-term product positioning. The Kanto region surrounding Tokyo anchors specialized ophthalmology clinics with strong private-pay capacity for premium lens categories.
United Kingdom
NHS reimbursement thresholds constrain public-sector adoption of extended depth of focus platforms while private surgical chains capture presbyopia-correcting demand. MHRA post-Brexit regulatory alignment with EMA MDR frameworks maintains continuity in clinical evidence requirements. London and the Southeast corridor concentrate high-volume ambulatory networks negotiating centralized procurement contracts.
India
Rising myopia prevalence among younger demographics expands the patient pool beyond traditional laser ablation candidates. CDSCO medical device registration pathways are harmonizing with international standards to accelerate market access for established manufacturers. Maharashtra and Karnataka host emerging clusters of ophthalmology-focused ambulatory centers in Mumbai and Bangalore metropolitan zones.
Phakic Intraocular Lenses (IOL) Market Competitive Landscape
On the supply side, the industry is consolidating around manufacturers with captive raw material positions and direct surgeon training infrastructures. Three strategic archetypes dominate: integrated ophthalmic conglomerates controlling polymer feedstock supply, specialized refractive device companies with dedicated education platforms, and diversified medical technology firms leveraging femtosecond laser ecosystems. Competitive maneuvering concentrates on backward integration into hydrophilic acrylic production and exclusive ambulatory surgical center procurement contracts.
Among the established multinational tier, STAAR Surgical Company, Johnson & Johnson Vision, and Alcon occupy positions defined by distinct capability anchors. STAAR Surgical exemplifies the specialized refractive archetype through its surgeon training infrastructure. Johnson & Johnson Vision represents integration between capital equipment and implantable device workflows. Alcon sits within the raw material control archetype through hydrophilic acrylic supply positioning.
| Leading Market Players |
|---|
| STAAR Surgical Company |
| Johnson & Johnson Vision |
| Alcon |
| Carl Zeiss Meditec |
| Bausch + Lomb |
| Hoya Surgical Optics |
| Nidek Co., Ltd. |
| EyeYon Medical |
| Rayner Surgical Group |
| Others |
Value Network & Pricing Analysis
Baden-Württemberg and Bavaria anchor hydrophilic acrylic feedstock processing capacity for phakic IOL manufacturing, concentrating polymer supply leverage among incumbent producers who translate captive raw material positions into premium pricing power for toric and extended depth of focus platforms.
Pricing Analysis
Certification level (FDA PMA-grade versus CE-marked standard) creates the primary spread between implant price tiers. Three-tier pricing structure across premium toric, extended depth of focus, and standard monofocal levels segments buyer budgets. Cost compression in standard spherical categories is intensifying because ambulatory surgical centers negotiate centralized volume contracts. Ophthalmology clinics with direct supplier relationships show least price sensitivity for astigmatism-correcting variants.
Supply Chain Analysis
Export control regimes for precision optical manufacturing equipment limit technology transfer to emerging production hubs. Hydrophilic acrylic polymerization capacity concentrates in Germany, Japan, and the United States. Silicone elastomer feedstock draws from specialized chemical suppliers with long qualification timelines. Single-source vulnerability for hydrophilic acrylic raw stock creates supply disruption exposure. Distribution runs through consolidated procurement networks serving multi-site ambulatory surgical center chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phakic IOL penetration sits at early-cycle expansion with presbyopia-correcting extended depth of focus platforms capturing premium pricing as aging demographics seek spectacle independence beyond laser ablation limits.
For Market Incumbents: Pre-empt femtosecond laser workflow integration by locking exclusive ambulatory surgical center procurement contracts before competitors complete capital equipment upgrades. Backward integration into hydrophilic acrylic polymer production defends margin position against feedstock cost volatility. Accelerate JIS-standard biocompatibility dossier preparation to sustain PMDA registration advantages.
For New Entrants and Emerging Players: Build out virtual surgeon training platforms to bypass distributor relationships compressed by consolidated procurement networks. Underpenetrated refractive corridors in India and Southeast Asia offer white-space access with harmonizing CDSCO registration pathways. Target direct-to-clinic digital education as primary go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized refractive device companies with captive surgeon training infrastructures and premium toric portfolio depth. Long-term viability favors manufacturers with backward integration into polymer feedstock and established FDA PMA-grade certification databases. Watch extended depth of focus platform adoption curves in United States ambulatory surgical centers as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | PMA-grade certification unlocks premium pricing tiers and hospital system access. |
| Backward Integration into Hydrophilic Acrylic | Captive polymer supply insulates margins from single-source feedstock concentration. |
| Direct Surgeon Training Infrastructure | STAAR Surgical's education platform sustains implant loyalty across refractive corridors. |
| Extended Depth of Focus Portfolio Expansion | Presbyopia-correcting designs capture fastest-growing segment with premium reimbursement. |
| Ambulatory Surgical Center Procurement Contracts | Exclusive agreements with multi-site chains displace traditional distributor relationships. |
Research Methodology
A spread of perspectives from refractive surgeons, ambulatory surgical center procurement directors, biomedical engineers, and regulatory affairs specialists converged on the working assumptions. Primary interviews combined with secondary validation against FDA PMA filings, EMA MDR submission databases, PMDA registration records, and hospital GPO contract repositories. Bottom-up procedure volume estimates and top-down manufacturer revenue analysis triangulated market sizing.
Demand-supply balance modeling across the projection horizon integrated patient population demographics, laser vision correction substitution elasticities, and ambulatory surgical center capacity expansion. Segmentation dimensions included product type, end-user facility category, material polymer class, and technology platform. CAGRs derived from procedure volume trajectories and average selling price evolution. Forecast inputs incorporated myopia prevalence curves and premium lens reimbursement threshold shifts.
The forecast holds incumbent behavior within observed patterns; aggressive moves by femtosecond laser capital equipment manufacturers into implantable lens workflows would shift outcomes. Material shifts in FDA evidentiary requirements for novel lens materials or EMA MDR post-market surveillance mandates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Nerve Stimulators Market
Medical Devices
Sphincterotomes Market
Medical Devices
Medical Electronics Market
Medical Devices
Global Surgical Drills Market
Medical Devices
India Minimally Invasive Surgery Devices Market
Medical Devices
Global Cataract Surgery Devices Market
Medical Devices
Electronic Smart Mask Market
Medical Devices
Hearing Aid Dehumidifier Market
Medical Devices
South Africa Artificial Organs and Bionic Implants Market
Medical Devices
Fluorescence-Guided Surgery Systems Market
Medical Devices
Retinal Surgery Devices Market
Medical Devices
Disposable Medical Devices Sensors Market
Medical Devices
Global Surgical Tourniquets Market
Medical Devices
Prescription Lens Market
Medical Devices
Middle East and Africa Medical Device Reprocessing Market
Medical Devices
Thoracic Surgery Devices Market